
 Global Digital Light Processing Chipset Market | 2026-2036
Global Digital Light Processing Chipset Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Light Processing Chipset Market Intelligence
The European Union's Ecodesign for Sustainable Products Regulation (ESPR) is repositioning the cost-of-entry calculus for chipset manufacturers by mandating higher energy efficiency and repairability standards. Texas Instruments leverages its extensive patent portfolio and manufacturing scale to meet these new performance-per-watt targets. OSRAM specializes in high-efficiency light sources, a critical component for ESPR-compliant projection systems. Barco differentiates through its focus on high-brightness solutions for professional and medical imaging applications.
A digital light processing chipset is a micro-opto-electromechanical system (MOEMS) containing an array of individually addressable micromirrors. Each mirror rapidly reflects light to generate pixels, forming a high-fidelity digital image for projection systems and display devices. Single-chip solutions dominate the consumer electronics segment due to their cost-effectiveness, while 3-chip architectures serve high-performance applications like digital cinema. The automotive end-user category represents the fastest-growing application area, particularly for integrated head-up displays.
Compliance with standards from the US Federal Communications Commission (FCC) on electromagnetic interference and China's GB standards for product safety are essential for market access. These regulations, alongside ISO 9001 quality management systems, dictate design constraints and testing protocols for all new chipset releases. Navigating the trade-off between increasing pixel density for 4K/8K displays and meeting stricter power consumption limits remains the central engineering challenge.
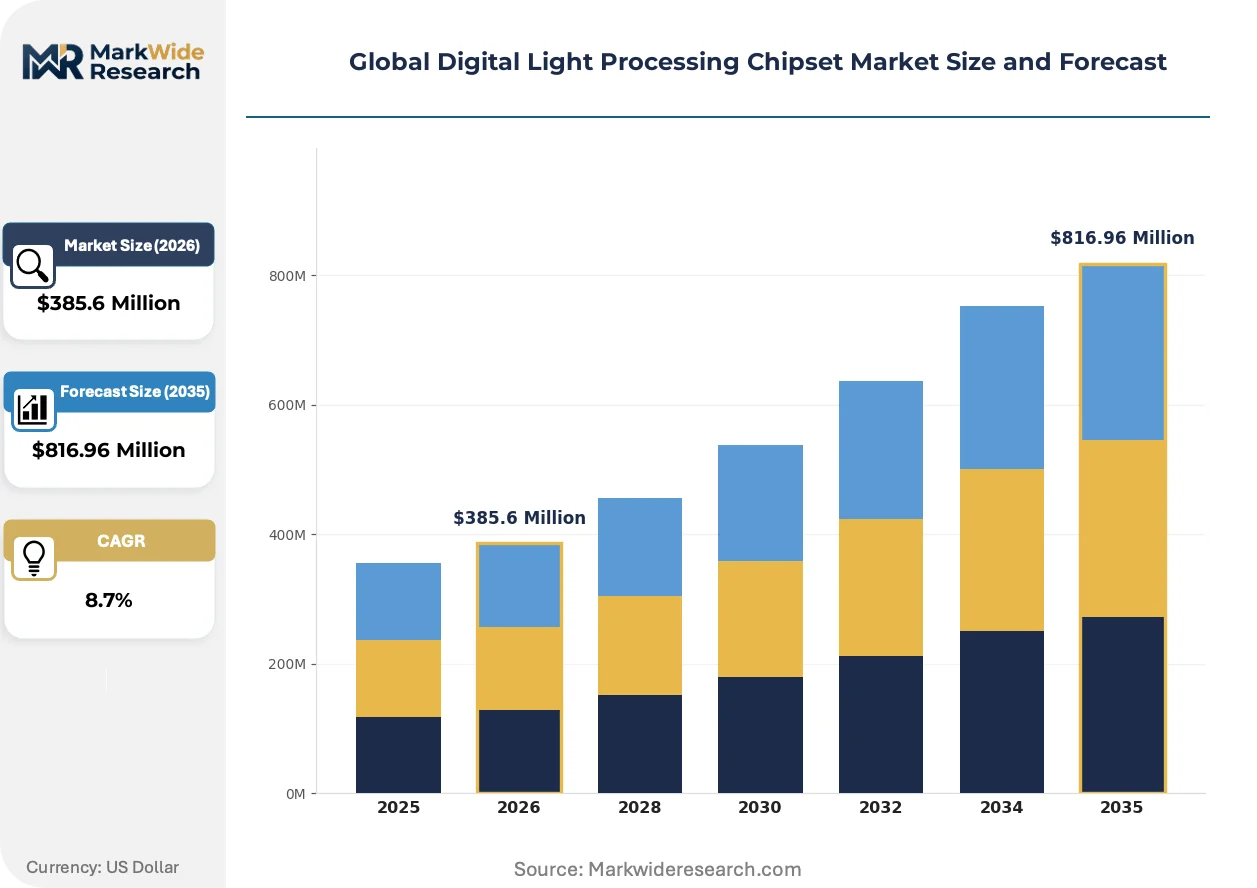
Market Dynamics
The central engineering challenge shaping the market is the trade-off between increasing pixel density for 4K/8K displays and meeting stricter power consumption limits imposed by regulations like the EU's Ecodesign for Sustainable Products Regulation (ESPR).
Growth Catalysts
- Automotive Integration:Demand for head-up displays in China's automotive ecosystem provides a high-growth application area for specialized, automotive-grade chipsets.
- Consumer Device Miniaturization:The trend toward smaller consumer electronics with embedded projection fuels demand for cost-effective, single-chip solutions.
- Professional Venue Upgrades:The upgrade cycle for digital cinema projectors to 4K/8K resolution creates demand for high-brightness, 3-chip systems.
Market Restraints
- Specialized Light Source Cost:The high price of efficient laser and LED light sources, necessary for brightness and ESPR compliance, inflates total system cost.
- MOEMS Manufacturing Barriers:Fabricating micro-mirror arrays is a capital-intensive process with high technical barriers, concentrating production among few suppliers.
- Flat-Panel Display Substitution:Falling prices for large OLED and MicroLED screens create a direct substitution threat in fixed home cinema and signage applications.
Strategic Opportunities
- Industrial 3D Metrology:Integrating chipsets into structured light systems for automated quality control in advanced manufacturing offers a new industrial vertical.
- Medical Imaging Systems:Developing chipsets for medical applications like surgical navigation and endoscopy addresses a need for high-fidelity, reliable projection.
- Augmented Reality Eyewear:Miniaturized mirror arrays are being adapted for near-eye displays in AR glasses, representing a potential high-volume market.
Industry Challenges
- Thermal Management in Compact Designs:Dissipating heat from high-density mirror arrays within small form-factor devices remains a primary engineering and cost challenge for designers.
- Multi-Jurisdictional Compliance Burden:Simultaneously meeting the divergent requirements of the EU's ESPR, China's GB standards, and US FCC rules complicates design and extends testing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Light Processing Chipset Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Chip, 3-Chip, DLP Pico, DLP UHD End User: Consumer Electronics, Automotive, Aerospace, Education Technology: LED, Laser, Lamp-based, Hybrid Application: Projection Systems, Display Devices, Smart Devices, Medical Imaging |
| Companies Covered | Texas Instruments, Koninklijke Philips, OSRAM, Barco, Optoma, BenQ, General Electric, Panasonic, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Light Processing Chipset Market Strategic Shifts & Innovations
The push for higher resolution and smaller form factors is reshaping the market's design priorities. This drive now intersects with new environmental regulations, forcing innovation in power efficiency and chipset architecture to balance performance with sustainability.
Advanced Pixel Control
Adaptive pixel control algorithms are a key software-level innovation. These systems analyze image content to selectively dim or deactivate micromirrors in darker sections. Consumer electronics manufacturers are adopting this technology to extend battery life in portable projectors. This software-driven efficiency is consolidating hardware gains, helping devices meet energy standards like ESPR without sacrificing perceived contrast.
Regulation-Driven Design
European Union's Ecodesign for Sustainable Products Regulation (ESPR) is a pivotal regulatory force. It mandates strict energy efficiency and repairability, making performance-per-watt a primary design constraint for European market access. Consumer-grade projector manufacturers are most affected, re-engineering power supplies and light source modules to ensure compliance.
Integrated System Procurement
A transition from buying standalone chipsets to acquiring integrated display systems defines a major demand-side shift. This model bypasses traditional component distributors in favor of system integrators who become the primary channel. The trend is most visible in the automotive sector, where chipsets are procured as part of a complete Tier 1 supplier's HUD module in China and Europe.
Global Digital Light Processing Chipset Market Segmentation
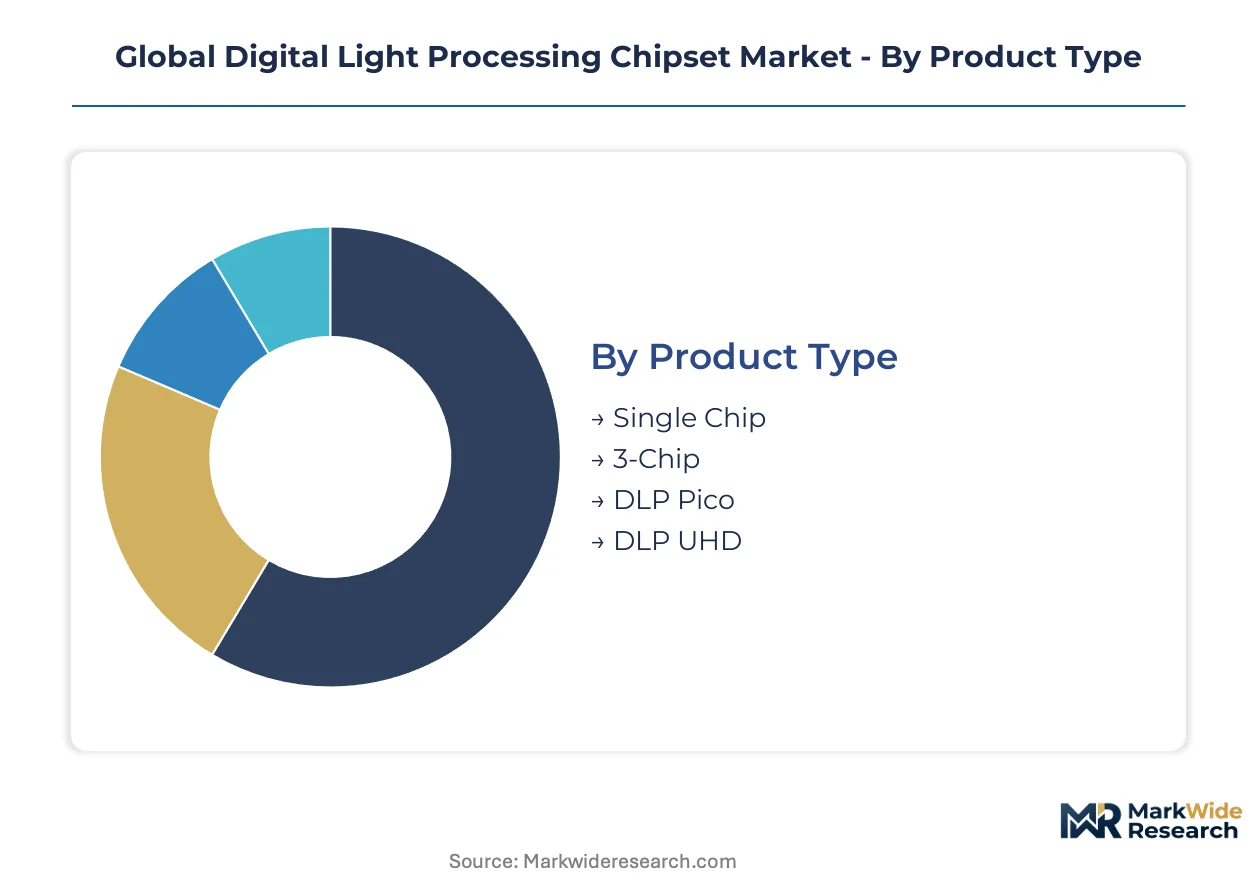
The Global Digital Light Processing Chipset Market exhibits diverse segmentation across product types, end-user applications, underlying technologies, and specific application areas. Understanding these distinctions is essential for manufacturers to tailor product development and market strategies. Each segment addresses unique performance requirements and cost considerations within the broader projection and display ecosystem.
Product Type:
Supply concentration in the Digital Light Processing chipset market often dictates the available product types, favoring established manufacturing processes for specific mirror array configurations.
- Single Chip:These chipsets utilize one micro-mirror device to project a full-color image sequentially, offering a cost-effective solution for compact devices. Consumer electronics manufacturers integrate single-chip solutions into portable projectors and smart home devices due to their efficiency.
- DLP UHD:This product type delivers ultra-high definition resolutions, typically 4K or 8K, by precisely controlling millions of micromirrors. Demand for DLP UHD chipsets is concentrating in professional cinema and high-end home theater systems, driven by the desire for superior image fidelity.
- 3-Chip:These systems employ three separate micro-mirror devices, one for each primary color (red, green, blue), allowing for simultaneous color projection. Digital cinema installations and large venue projection utilize 3-chip architectures for maximum brightness and color accuracy.
- DLP Pico:Miniaturized DLP chipsets enable ultra-portable projection capabilities for integration into smartphones, smart speakers, and other small form-factor consumer devices.
Today's leader: Single Chip. Tomorrow's challenger: DLP UHD.
End User:
Target application areas for Digital Light Processing chipsets vary significantly by end-user category, each demanding specific performance characteristics and reliability standards.
- Automotive:This segment requires robust chipsets for head-up displays (HUDs) and advanced driver-assistance systems, operating under extreme temperature and vibration conditions. Demand for automotive-grade chipsets is expanding most quickly in China's burgeoning electric vehicle market.
- Consumer Electronics:Chipsets for consumer electronics power a wide array of devices, including home theater projectors, smart TVs, and portable media players. This segment prioritizes cost-effectiveness and compact design for mass-market appeal.
- Aerospace:High-reliability chipsets serve specialized display needs in aircraft cockpits and flight simulators, where precision and durability are paramount.
- Education:Projection systems in educational institutions utilize DLP chipsets for interactive whiteboards and classroom presentations, balancing performance with budget constraints.
The Automotive sector exhibits the steepest expansion trajectory, while Consumer Electronics maintains significant volume.
Technology:
The underlying light source technology significantly impacts a Digital Light Processing chipset's performance, energy efficiency, and total system cost.
- Laser:Laser-based projection systems offer superior brightness, wider color gamut, and longer operational lifespans compared to traditional lamps. Professional venue upgrades and high-end home cinema installations increasingly adopt laser technology for its performance advantages.
- LED:Light Emitting Diode technology provides energy-efficient illumination with instant on/off capabilities and extended durability. Consumer device miniaturization drives the integration of LED light sources with DLP chipsets for portable projectors.
- Lamp-based:Traditional lamp-based projectors remain a cost-effective option for many applications, though they require periodic lamp replacement and offer lower energy efficiency.
- Hybrid:Hybrid light sources combine different technologies, such as LED and laser, to achieve a balance of brightness, color accuracy, and cost-effectiveness for various projection needs.
Laser technology is gaining share fastest, while LED technology offers substantial volume growth.
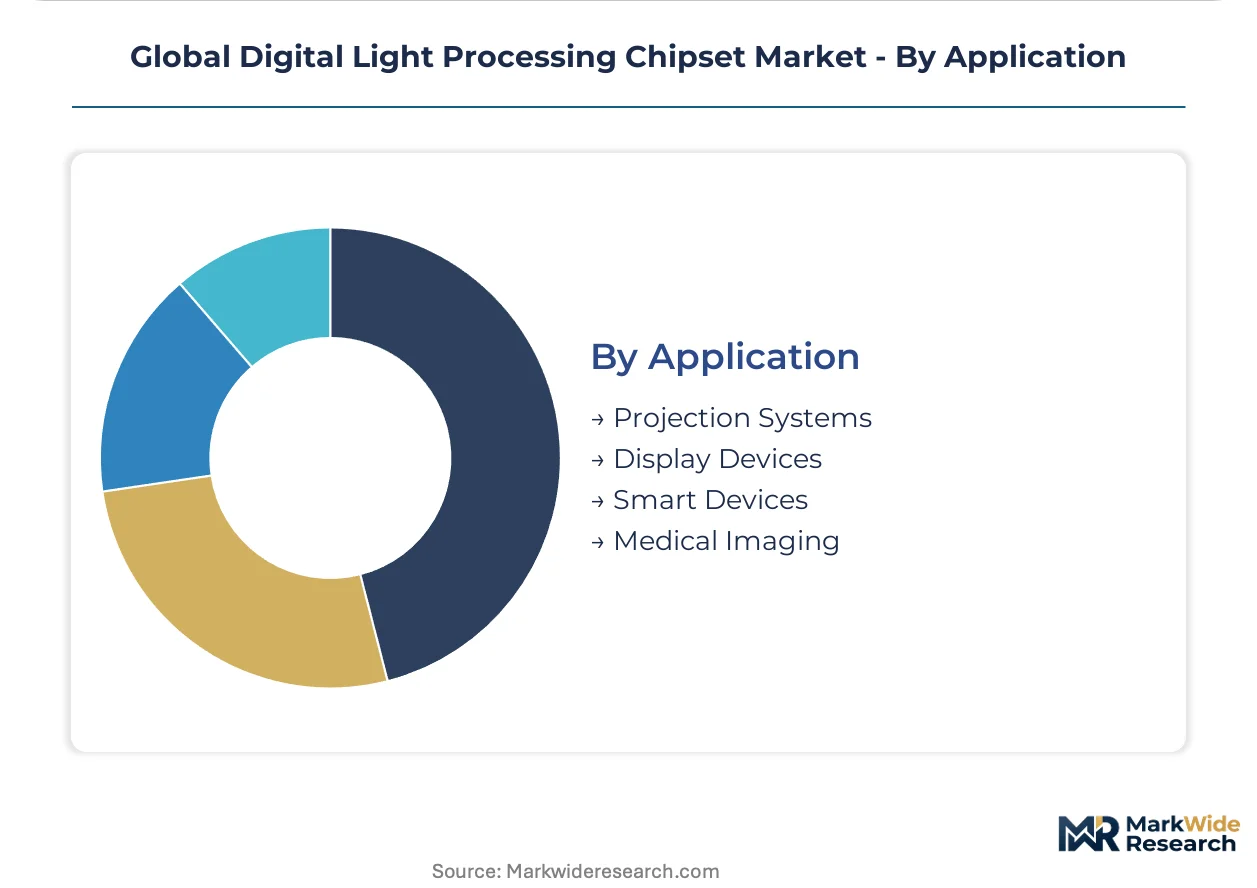
Application:
Digital Light Processing chipsets find utility across a broad spectrum of applications, from traditional image display to emerging industrial and medical uses.
- Smart Devices:This category includes chipsets integrated into augmented reality (AR) eyewear, smart speakers with projection capabilities, and other connected consumer gadgets. Miniaturized mirror arrays are crucial for enabling near-eye displays in AR glasses, representing a potential high-volume market.
- Medical Imaging:Chipsets designed for medical imaging systems require exceptionally high fidelity, reliability, and color accuracy for applications like surgical navigation and endoscopy. Developing chipsets tailored for precise medical visualization offers a new industrial vertical.
- Projection Systems:The traditional and largest application for DLP chipsets, encompassing home theater, digital cinema, business projectors, and large venue displays.
- Display Devices:This segment includes chipsets used in rear-projection TVs, video walls, and specialized industrial displays where DLP technology offers advantages.
Smart Devices are climbing the fastest, while Projection Systems maintain their foundational position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled engineering talent concentrations across several key geographies anchor the Digital Light Processing chipset market's innovation and production. These regions drive both demand and supply for advanced projection technologies. Regulatory frameworks significantly influence market access and product design across these areas.
China
Demand for advanced head-up displays in electric vehicles drives automotive-grade chipset integration. China's GB standards for product safety and electromagnetic compatibility dictate stringent design constraints for market access. The Yangtze River Delta region, with its extensive electronics manufacturing ecosystem, sees high production and adoption of DLP chipsets for consumer devices.
United States
Consumer electronics, particularly portable projectors, and aerospace applications generate substantial demand for high-fidelity chipsets. The US Federal Communications Commission (FCC) regulates electromagnetic interference for all electronic devices, influencing product design. Silicon Valley continues to innovate in micro-opto-electromechanical systems (MOEMS) design and advanced pixel control algorithms.
Germany
The automotive sector, particularly for advanced driver-assistance systems and integrated HUDs, requires robust DLP chipsets. The European Union's Ecodesign for Sustainable Products Regulation (ESPR) mandates strict energy efficiency for market entry across the bloc. Bavaria's automotive industry drives specialized chipset development and integration into premium vehicle models.
Japan
High-end home theater systems and professional venue upgrades sustain demand for 4K/8K DLP solutions, emphasizing image fidelity. Japan's METI promotes advanced manufacturing and digital transformation initiatives across its industrial base. The Kanto region, including Tokyo, remains a hub for consumer electronics and display technology research and development.
South Korea
Consumer device miniaturization and smart device integration create significant demand for compact DLP pico chipsets. South Korea's Ministry of Trade, Industry and Energy (MOTIE) supports semiconductor innovation and export-oriented manufacturing. The Seoul Capital Area hosts major electronics manufacturers integrating DLP pico chipsets into next-generation portable devices.
Global Digital Light Processing Chipset Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, shaping the Digital Light Processing chipset market structure. This market exhibits a tiered competitive landscape, with established semiconductor giants operating alongside niche optical component providers. Strategic archetypes include vertically integrated developers, specialized component suppliers, and system integrators. Technology licensing, capacity expansion, and strategic partnerships represent dominant competitive moves as companies pursue portfolio diversification to address various end-user segments.
Specialists in high-performance projection components, such as OSRAM, focus on advanced light sources critical for energy efficiency and brightness in projection systems. Texas Instruments, a semiconductor leader, anchors the market through its extensive patent portfolio and manufacturing scale in micro-mirror arrays, serving diverse applications. Barco occupies a position in high-brightness solutions, particularly for professional and medical imaging applications, differentiating through specialized system integration. These companies exemplify the blend of hardware innovation and application-specific tailoring required in this market.
| Leading Market Players |
|---|
| Texas Instruments |
| Koninklijke Philips |
| OSRAM |
| Barco |
| Optoma |
| BenQ |
| General Electric |
| Panasonic |
| STMicroelectronics |
| Others |
Cost & Logistics Intelligence
Micro-mirror array fabrication costs, driven by capital-intensive MOEMS processes, define upstream pricing, translating into tiered pricing for downstream system integrators. This cost structure impacts the final price of projection systems, especially for high-resolution 4K/8K solutions.
Pricing Analysis
Bundled solutions, often including the chipset as part of a complete projection module, define the dominant pricing structure for high-volume applications. Price differentiation stems from the quality grade, particularly for automotive-grade chipsets requiring AEC-Q100 certification, and the overall volume scale of procurement. Pricing pressure stems from the falling prices of large-format OLED and MicroLED screens, which offer a direct substitution threat in fixed display applications. Consumer electronics manufacturers exhibit the highest price sensitivity, while automotive and medical imaging sectors prioritize performance and reliability over cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized MOEMS fabrication facilities due to high technical barriers and capital investment. Geographic supply concentration centers on China for consumer electronics manufacturing, the United States for advanced MOEMS design, and Germany for automotive-grade chipset integration. The market relies on specialized silicon wafers and high-efficiency light sources, specifically laser diodes and LEDs, as critical component dependencies. Regulatory compliance complexity across multiple jurisdictions, including the EU's ESPR and China's GB standards, represents a structural supply chain risk. Distribution runs through system integrators for automotive and industrial applications, while traditional component distributors serve the broader consumer electronics segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Light Processing chipset market presents a margin-expansion story, driven by the shift towards higher-value, specialized applications like automotive HUDs and medical imaging.
For Market Incumbents:
Deepen vertical integration into specialized light source production to control costs and enhance performance-per-watt for ESPR compliance. Invest heavily in automotive-grade chipset research and development, securing design wins with Tier 1 suppliers in China and Germany. Leverage extensive patent portfolios to deter new entrants and maintain market share against flat-panel display substitution. Expand manufacturing capacity for 3-chip systems to address professional venue upgrade cycles.
For New Entrants and Emerging Players:
Launch via system integrators targeting the industrial 3D metrology vertical, focusing on structured light systems for automated quality control. Target niche medical imaging applications, such as surgical navigation, where high-fidelity and reliability command premium pricing. Focus on developing miniaturized mirror arrays specifically for augmented reality eyewear, aiming for high-volume component supply to device manufacturers. Penetrate markets with less stringent regulatory requirements initially to build expertise.
For Investors and Strategic Acquirers:
Roll-up economics work for specialized component providers because the market values niche expertise in MOEMS fabrication and advanced light sources. The long-term viability favors companies with strong intellectual property in micro-mirror array technology or high-efficiency projection components for specialized applications. Acquisition targets should include MOEMS fabrication specialists or high-efficiency light source providers. The signal to watch is the adoption rate of augmented reality eyewear, indicating a potential high-volume market for miniaturized DLP pico chipsets.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in MOEMS Fabrication | Addresses supply concentration and technical barriers, ensuring stable component availability. |
| Strategic Partnership in Automotive | Secures market share in the fastest-growing end-user segment, particularly for HUDs. |
| R&D Investment in Adaptive Pixel Control | Enhances energy efficiency for regulatory compliance and extends battery life in portable devices. |
| Product Diversification into Industrial Metrology | Opens new high-margin application verticals beyond traditional projection and display. |
| Licensing of Advanced Light Source Technology | Reduces total system cost for ESPR-compliant products and improves brightness. |
Research Approach
Coverage spans China, the United States, Germany, Japan, and South Korea, with primary inputs from each key region. The methodology combines in-depth primary interviews with industry stakeholders and rigorous secondary validation. Stakeholders included R&D directors, procurement managers at automotive Tier 1 suppliers, system integrators for digital cinema, and regulatory compliance officers. Secondary data sources comprised patent databases, industry association reports from SEMI and CEA, and government technology roadmaps from METI. Bottom-up and top-down triangulation ensured data accuracy and comprehensive market sizing.
Rate-of-change decomposition framed the analytical framework across the analysis window. The model segmented the market by product type (Single Chip, DLP UHD, 3-Chip, DLP Pico), end-user (Automotive, Consumer Electronics, Aerospace, Education), technology (Laser, LED, Lamp-based, Hybrid), application (Smart Devices, Medical Imaging, Projection Systems, Display Devices), and key geographic regions. Compound annual growth rates were derived from historical data analysis and projected market dynamics. Forecast inputs included automotive production forecasts, consumer electronics shipment volumes, and professional venue upgrade cycles.
Several conditions sit outside the modeled scope, including specific company-level financial performance and detailed material science breakthroughs. Forecasts reflect assumptions regarding regulatory stability and technological evolution. Key risk factors that could revise forecasts include unforeseen technological disruption from MicroLED advancements or significant shifts in global trade policies. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
G Fast Chipset Market
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
NFC Chips Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
Airbag Chip Market
Chipset and Processors
Processor Chip Market
Chipset and Processors
Thailand Data Center Processor Market
Chipset and Processors
Accelerated Processing Unit (APU) Market
Chipset and Processors
High Performance Computing (HPC) Chipset Market
Chipset and Processors
Europe MPU Market
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
Cockpit Soc Chip Market
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
Global Automotive Self-Driving Chip Market
Chipset and Processors
System on Chip (Soc) Market