
 PV Module Encapsulant Film Market | 2026-2036
PV Module Encapsulant Film Market Size, Share, and Industry Trends Forecast 2026-2036
PV Module Encapsulant Film Market Analytics
The PV module encapsulant film market is pivoting on a widening split between premium silicone and thermoplastic polyurethane grades for bifacial applications versus commodity ethylene vinyl acetate volumes serving conventional cell lines. DuPont de Nemours sustains technology leadership in high-durability ionomer alternatives that command price premiums in harsh-climate installations. Hangzhou First Applied Material dominates domestic supply chains through captive ethylene vinyl acetate resin processing and direct module-maker relationships. Mitsui Chemicals navigates the premium tier through specialized polyolefin elastomer films targeting floating solar and agricultural PV dual-use projects.
PV module encapsulant film is a polymeric interlayer laminated between the solar cell matrix and front glass or backsheet, typically 300μm to 500μm thick, that provides electrical insulation, moisture barrier protection, and mechanical adhesion across decades of UV and thermal cycling exposure. Ethylene vinyl acetate remains the structural volume leader due to decades of process optimization and established lamination equipment compatibility, though margin pools are migrating toward thermoplastic polyurethane and silicone segments where thermal stability and PID resistance justify higher unit economics. Bifacial cell technology is accelerating demand for transparent backsheet-compatible encapsulant formulations that eliminate traditional white reflective layers.
The EU F-Gas Regulation and REACH chemical restrictions are reshaping material qualification requirements for films sold into European module assembly, while China's GB standards and dual carbon goals enforce domestic recyclability targets that favor thermoplastic alternatives over crosslinked ethylene vinyl acetate. India's BIS certification mandates and PLI scheme localization rules are creating divergent compliance pathways for multinational suppliers versus domestic film producers. Stakeholders must monitor how evolving national carbon accounting frameworks treat encapsulant film embodied emissions in module-level lifecycle assessments.
Market Dynamics
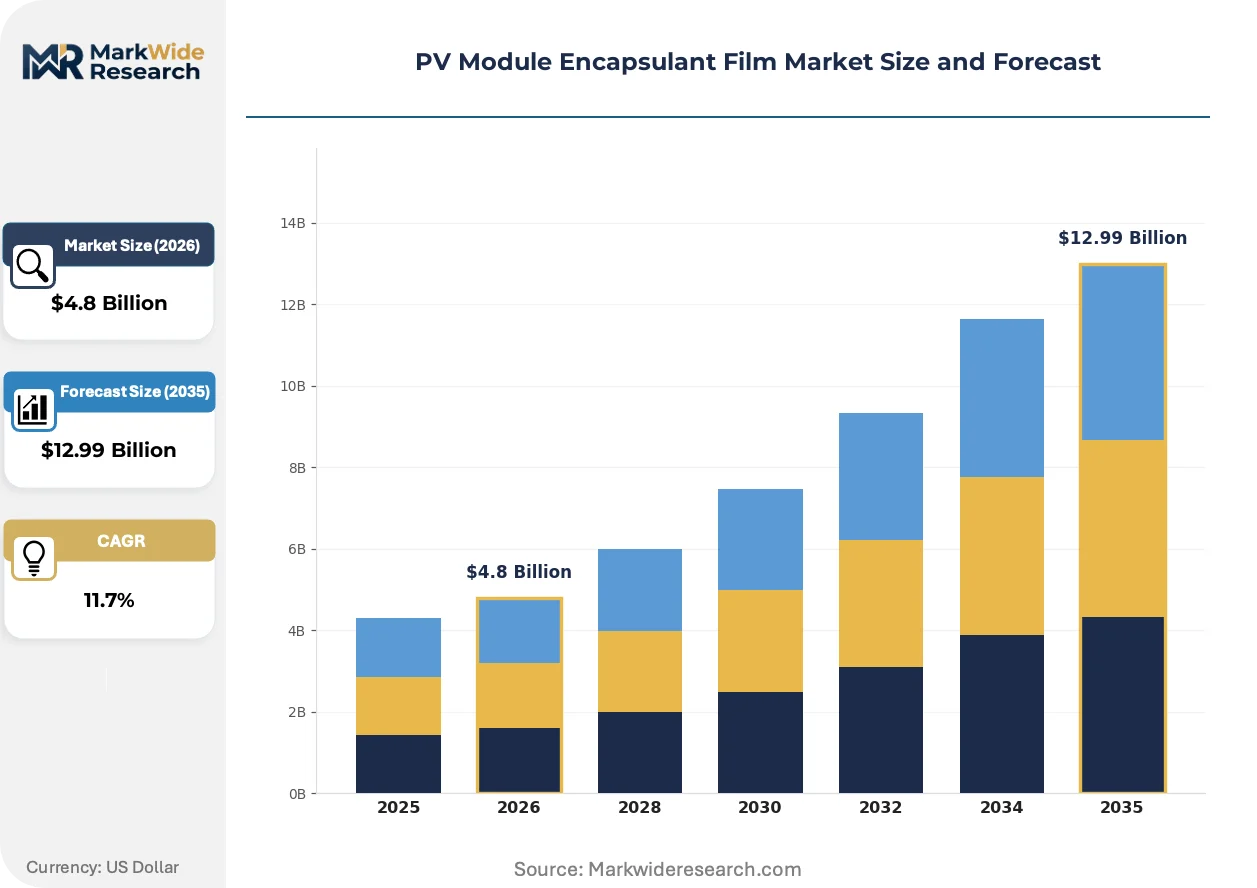
The PV module encapsulant film market is bifurcating around thermal stability requirements as bifacial and heterojunction cell architectures proliferate, forcing manufacturers to choose between reformulating ethylene vinyl acetate or migrating to premium silicone and polyolefin alternatives.
Growth Catalysts
- Heterojunction cell expansion:High-efficiency cell architectures demand encapsulant films with superior thermal conductivity and potential-induced degradation resistance, pulling material specifications upward across module assembly lines.
- EU Green Deal carbon border adjustments:The Carbon Border Adjustment Mechanism penalizes embodied emissions in imported modules, incentivizing European assemblers to source lower-carbon encapsulant formulations regardless of cost premiums.
- Floating solar deployment:Aquatic installations require encapsulant films with enhanced moisture barrier properties and salt-mist corrosion resistance, opening specification windows for specialized thermoplastic polyurethane grades.
Market Restraints
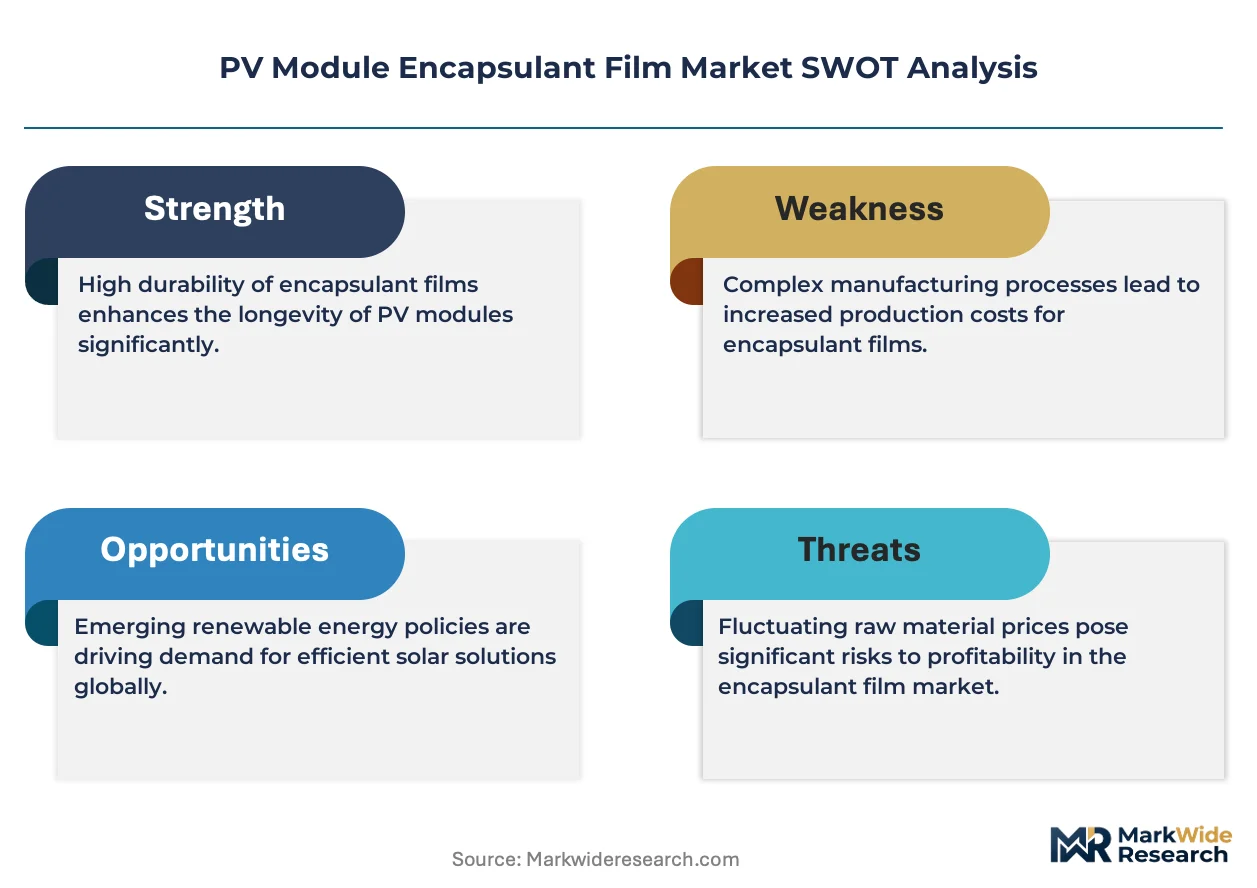
- Ethylene vinyl acetate resin price volatility:Feedstock costs for vinyl acetate monomer fluctuate with crude oil and natural gas pricing, compressing margins for commodity-grade film producers without long-term supply contracts.
- China supply concentration:Vertically integrated domestic producers control resin processing and film extrusion capacity, creating barriers for multinational suppliers seeking meaningful market access without local manufacturing presence.
- Crosslinked ethylene vinyl acetate recyclability limitations:Thermoset chemistry prevents mechanical recycling at end-of-life, conflicting with China's GB standards recyclability mandates and EU circular economy directives.
Strategic Opportunities
- India PLI scheme localization:Production-linked incentive rules require domestic content in module assembly, creating openings for local encapsulant film manufacturing partnerships with cell and module producers establishing Indian operations.
- Agrivoltaic dual-use projects:Agricultural photovoltaic installations require encapsulant films with spectral selectivity properties that optimize both crop photosynthesis and electricity generation, a specification niche served by specialized polyolefin elastomer formulations.
- US Inflation Reduction Act domestic content bonuses:Additional tax credits for modules with North American-made components are accelerating sourcing reviews among project developers, creating demand pull for US-based encapsulant film production.
Industry Challenges
- Polymer compounding expertise scarcity:Formulating encapsulant films with balanced optical clarity, adhesion strength, and long-term thermal stability requires specialized knowledge in photostabilizer packages and crosslinking chemistry that resides in a limited talent pool.
- Lamination equipment retrofit requirements:Transitioning from conventional ethylene vinyl acetate to thermoplastic alternatives demands capital expenditure on modified laminators with adjusted temperature and pressure profiles, slowing material substitution timelines.
- Multi-jurisdiction certification complexity:Module assemblers selling into both European and Chinese markets must qualify encapsulant films against divergent testing protocols, extending product development cycles and increasing qualification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PV Module Encapsulant Film Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Ethylene Vinyl Acetate, Polyvinyl Butyral, Thermoplastic Polyurethane, Silicone Thickness: 100μm, 200μm, 300μm, 500μm End User: Module Manufacturers, OEMs, Research Institutions, Solar Power Plants Technology: Conventional Cells, Bifacial Cells, Cadmium Telluride, Concentrated Photovoltaic |
| Companies Covered | 3M, Borealis, STR Holdings, Changzhou Betterial Film Technologies, Arkema, Mitsui Chemicals, H.B. Fuller, DuPont de Nemours, Hangzhou First Applied Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PV Module Encapsulant Film Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to accelerate formulation turnover, with thermal stability specifications and circular design requirements now driving R&D allocation more than incremental cost reduction.
Silicone encapsulant formulations are electrifying the premium segment of the market by delivering operating temperature stability beyond 150°C without yellowing or delamination. Heterojunction and tandem cell module producers in Japan and South Korea are specifying silicone interlayers for rooftop and building-integrated applications where thermal management is critical. This chemistry is compressing the addressable market for conventional ethylene vinyl acetate in high-performance installations while establishing new price anchoring points.
The EU F-Gas Regulation and REACH Annex XIV authorization requirements are systematically restricting perfluorinated compounds and certain plasticizers used in backsheet and encapsulant formulations. European module assemblers are reformulating supply specifications to exclude restricted substances ahead of sunset dates, forcing film producers to requalify additive packages. The thermoplastic polyurethane segment is responding fastest due to inherently simpler chemistry and broader formulation flexibility.
Utility-scale project developers are consolidating procurement decisions at the portfolio level rather than the individual project level, concentrating negotiating leverage with a smaller set of module suppliers. This buyer concentration is compressing the number of qualified encapsulant film vendors per module maker, favoring producers with scale and balance sheet capacity to offer extended payment terms. The pattern is most visible in the US and Middle Eastern markets where gigawatt-scale project pipelines dominate procurement calendars.
PV Module Encapsulant Film Market Segmentation
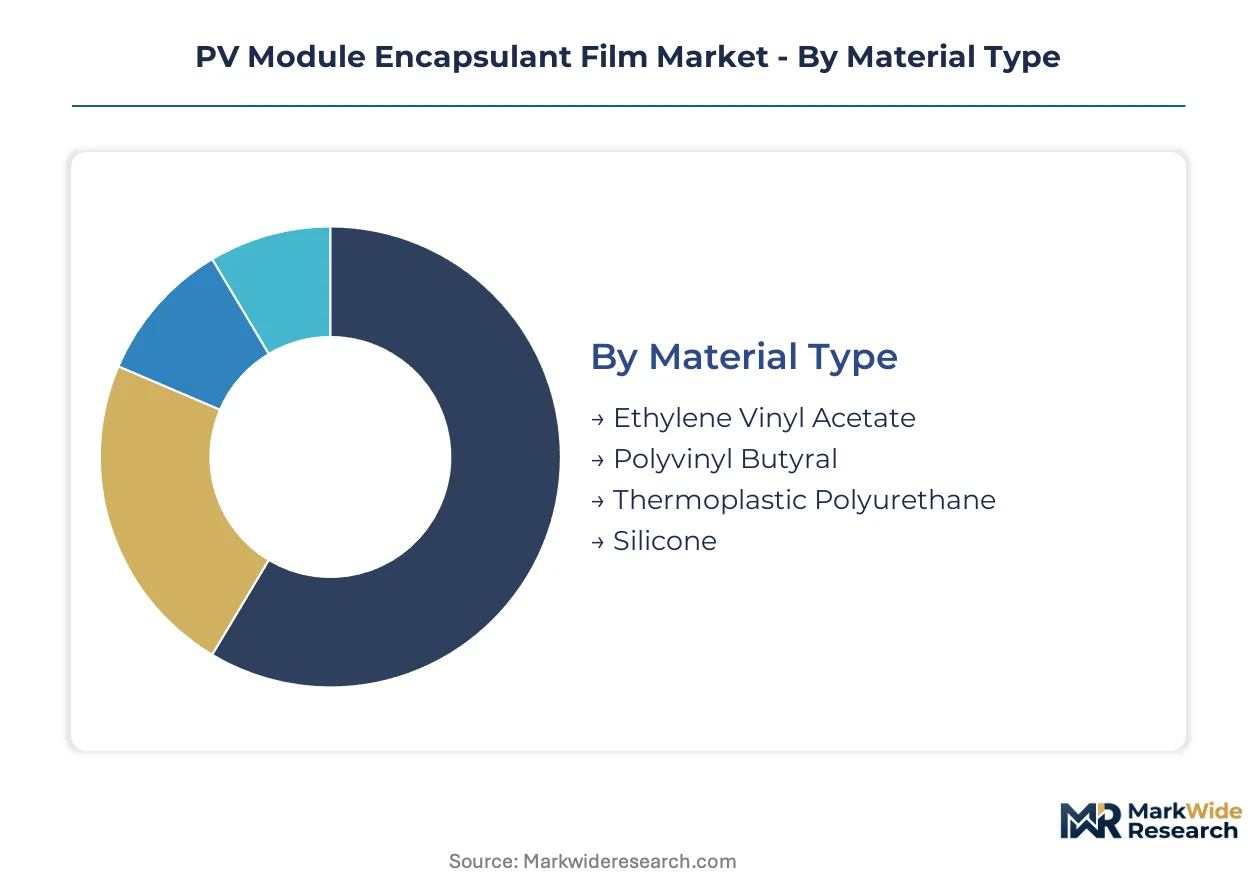
Segmentation in the PV module encapsulant film market reveals how material chemistry, dimensional specifications, and cell architecture requirements create distinct procurement pathways. Each segment carries unique certification burdens and supply chain configurations that determine vendor qualification timelines and margin structures.
Material Type:
Certification requirements diverge sharply across material chemistries, with ethylene vinyl acetate governed by decades-old IEC 61215 protocols while silicone and thermoplastic polyurethane face emerging bifacial-specific test standards.
- Ethylene Vinyl Acetate:Crosslinked copolymer formulation dominates installed base compatibility with standard lamination equipment. Demand concentrates among conventional module producers in China and Southeast Asia seeking lowest unit cost per watt-peak, though recyclability limitations under EU circular economy directives now constrain European procurement.
- Thermoplastic Polyurethane:Elastomer chemistry delivers superior moisture barrier performance and thermal stability for floating solar and coastal installations. Japanese and South Korean module producers specify this grade for heterojunction cell lines where potential-induced degradation resistance justifies cost premiums.
- Silicone:Inorganic backbone provides operating temperature stability exceeding 150°C without yellowing. Premium segment applications in building-integrated photovoltaics and concentrated solar systems drive specification.
- Polyvinyl Butyral:Laminated glass interlayer chemistry adapted from architectural glazing applications. Niche demand from crystalline silicon module producers seeking alternative lamination chemistries for specific climatic zones.
Ethylene vinyl acetate sits at the top of the volume ranking, with thermoplastic polyurethane climbing the fastest.
Thickness:
Dimensional specifications correlate directly with electrical insulation requirements and mechanical load-bearing capacity across module architectures.
- 300μm:Mid-range specification balances optical transmission efficiency with lamination throughput speeds. Standard for monocrystalline and polycrystalline cell lines in utility-scale procurement.
- 500μm:Heavy-gauge formulation provides enhanced edge-sealing and moisture ingress protection for framed modules in high-humidity climates. Concentrated demand from Southeast Asian and Middle Eastern project developers.
- 200μm:Reduced thickness enables material cost savings and improved light transmission for lightweight module designs. Thin-film and flexible substrate applications drive specification.
- 100μm:Ultra-thin gauge for specialized building-integrated and vehicle-integrated photovoltaic applications where weight reduction overrides durability margins.
300μm formulations command the largest production volumes, while 500μm specifications are expanding most quickly in coastal and floating solar deployments.
End User:
Customer type determines contract structures, with module manufacturers negotiating multi-year supply agreements while research institutions require small-batch qualification volumes.
- Module Manufacturers:Tier-1 and tier-2 cell-to-module producers account for structural volume demand, with procurement consolidated among vertically integrated Chinese producers and specialized Western suppliers.
- Solar Power Plants:Utility-scale developers increasingly specify encapsulant film chemistry at the engineering-procurement-construction contract level, bypassing module maker discretion.
- OEMs:Original equipment manufacturers for specialized applications including aerospace, marine, and portable power systems require customized formulation batches.
- Research Institutions:National laboratories and university programs drive next-generation material qualification for tandem cell and perovskite-silicon architectures.
Module manufacturers retain the dominant demand share, with solar power plants gaining procurement influence fastest through portfolio-level contracting.
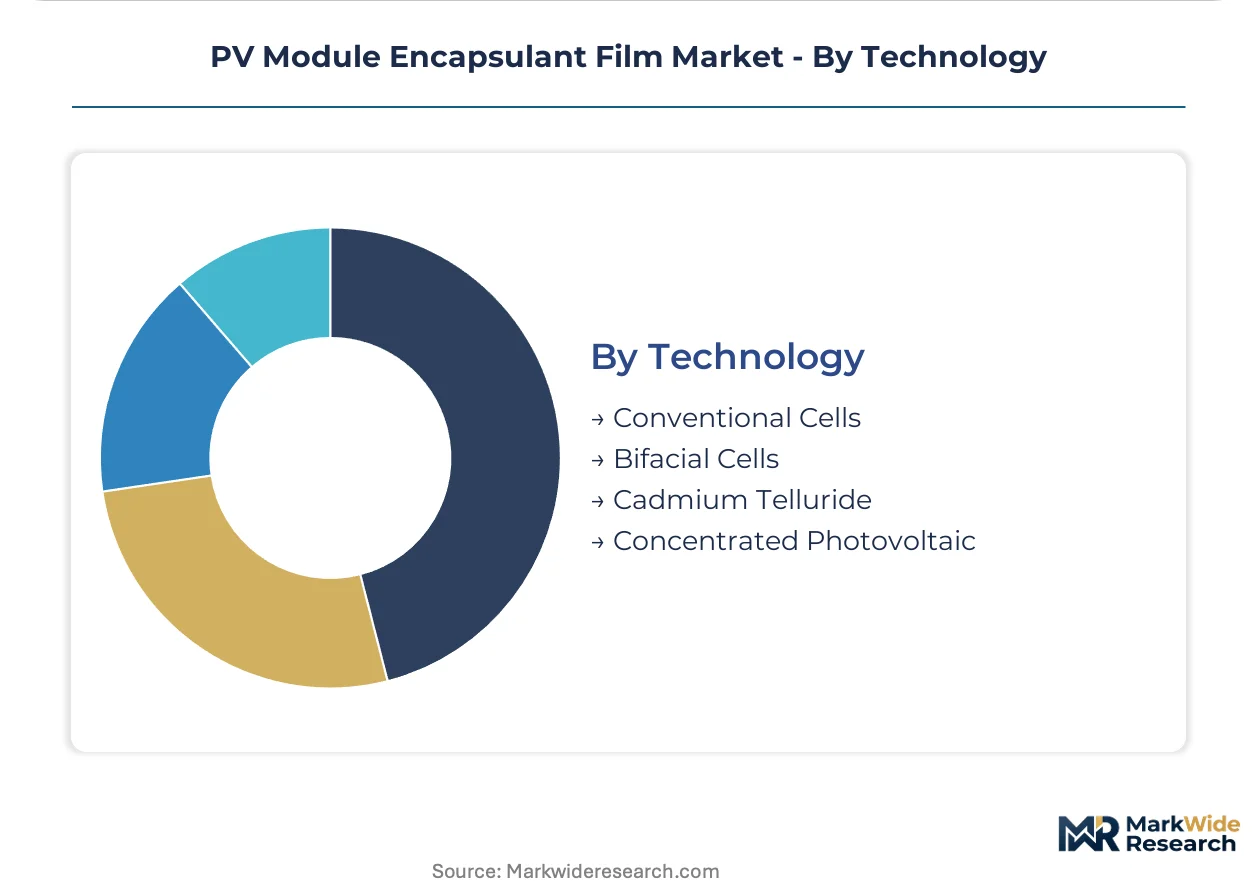
Technology:
Cell architecture specifications dictate encapsulant optical and thermal performance requirements, creating material substitution pressure as heterojunction and bifacial lines expand.
- Conventional Cells:Monofacial crystalline silicon architectures remain the volume anchor, with established ethylene vinyl acetate specifications and qualified supplier bases.
- Bifacial Cells:Dual-side light capture demands transparent encapsulant formulations without reflective back layers, driving silicone and thermoplastic polyurethane specification for rear-side transmission optimization.
- Cadmium Telluride:Thin-film technology requires encapsulant compatibility with vapor deposition processes and different thermal expansion coefficients than silicon.
- Concentrated Photovoltaic:High-flux optical concentration systems demand encapsulant films with extreme thermal stability and UV resistance under magnified irradiance conditions.
Conventional cells maintain the highest shipment volumes, with bifacial cell lines showing the steepest expansion trajectory in new capacity announcements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer compounding talent clusters in Germany, Japan, and the eastern United States anchor global encapsulant formulation capabilities. Regional regulatory divergence now shapes where film producers locate qualification laboratories and resin processing assets.
China
Vertically integrated cell-to-module producers in Jiangsu and Zhejiang provinces drive structural volume demand for ethylene vinyl acetate formulations. GB standards and dual carbon goals enforced by MEE mandate thermoplastic alternatives with end-of-life recyclability. Hangzhou-based resin processors control captive supply chains through direct module-maker relationships.
United States
Utility-scale project developers in Texas and California consolidate procurement at the portfolio level, compressing vendor qualification pools. IRA domestic content bonuses administered by Treasury accelerate sourcing reviews for North American-made components. Southeast manufacturing clusters attract film extrusion capacity to serve regional module assembly plants.
Germany
Heterojunction cell producers in Saxony and Bavaria specify silicone and thermoplastic polyurethane grades for building-integrated applications. EU F-Gas Regulation and REACH restrictions enforced by ECHA exclude perfluorinated compounds from encapsulant additive packages. Frankfurt-Rhine-Main chemical corridor hosts reformulation laboratories serving European module assemblers.
Japan
Floating solar deployments in Kansai and Kyushu regions demand thermoplastic polyurethane with salt-mist corrosion resistance. METI efficiency standards pull material specifications toward premium thermal stability grades. Osaka-based chemical groups specialize in polyolefin elastomer films for agricultural photovoltaic dual-use projects.
India
Module manufacturers in Gujarat and Tamil Nadu expand capacity under PLI scheme localization rules administered by MNRE. BIS certification mandates create compliance barriers for imported film formulations. Domestic resin processing partnerships in Maharashtra target captive supply to cell-to-module producers establishing Indian operations.
PV Module Encapsulant Film Market Competitive Landscape
Top-tier vendors anchor premium silicone and ionomer segments, while commodity ethylene vinyl acetate producers compete on scale and captive resin access. The vendor base stratifies across three archetypes: integrated chemical conglomerates with backward resin control, specialized film extruders with module-maker partnerships, and regional compounders serving niche climatic specifications. Dominant competitive moves include capacity expansion in India and Southeast Asia, plus strategic partnerships between resin suppliers and module assemblers to secure qualification slots.
Among integrated chemical conglomerates, DuPont de Nemours and Mitsui Chemicals occupy positions exemplifying premium-tier specialization through high-durability formulations. Hangzhou First Applied Material anchors the scale-driven commodity segment with captive ethylene vinyl acetate resin processing. Arkema and Borealis represent European chemical groups navigating regulatory chemistry restrictions through thermoplastic alternative development.
| Leading Market Players |
|---|
| 3M |
| Borealis |
| STR Holdings |
| Changzhou Betterial Film Technologies |
| Arkema |
| Mitsui Chemicals |
| H.B. Fuller |
| DuPont de Nemours |
| Hangzhou First Applied Material |
| Others |
Value Network & Pricing Analysis
Heterojunction cell migration toward premium silicone and thermoplastic polyurethane formulations is compressing commodity ethylene vinyl acetate margins while concentrating pricing power among resin processors with captive supply. This technology bifurcation simultaneously elevates input cost structures for high-performance grades and intensifies spot-market volatility for conventional formulations.
Pricing Analysis
Bundled long-term supply agreements dominate procurement between tier-1 module manufacturers and resin-integrated film producers, while unbundled spot transactions serve smaller assemblers without volume commitments. Price differentiation rests on certification tier—IEC 61215 baseline versus emerging bifacial-specific protocols—and captive resin access that insulates integrated producers from vinyl acetate monomer volatility. Cost compression in commodity ethylene vinyl acetate is intensifying because vertically integrated Chinese producers leverage backward resin control. Utility-scale developers exhibit lowest price sensitivity due to lifecycle cost framing, while distributed solar installers remain most sensitive to per-watt material costs.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and the US Inflation Reduction Act are fragmenting previously consolidated sourcing patterns toward regional manufacturing footprints. Geographic supply concentration centers on China for ethylene vinyl acetate resin processing, Germany for specialty silicone compounding, and Japan for thermoplastic polyurethane formulation. Raw material dependencies include vinyl acetate monomer, polyolefin elastomer feedstocks, and photostabilizer additive packages. Single-source vulnerability pervades vinyl acetate monomer supply given petrochemical co-location requirements. Distribution runs through direct module-maker contracts rather than distributor networks, with qualification timelines acting as de facto switching costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PV module encapsulant film market functions as a stable compounder anchored by irreplaceable polymer interlayer demand across multi-decade module lifespans. Solar capacity additions exceeding terawatt-scale annual deployment create persistent volume tailwinds regardless of cell technology transitions.
For Market Incumbents: Deploy certification pre-emption as the primary defensive lever. Accelerate IEC 61215 bis bifacial qualification ahead of regulatory sunset dates to lock out second-tier competitors. Anchor capacity addition in India under PLI localization rules to secure qualification slots with expanding domestic module producers. The threat of thermoplastic substitution for crosslinked ethylene vinyl acetate demands R&D allocation toward recyclable formulation chemistry that satisfies China's GB standards mandates. For New Entrants and Emerging Players: Premium-to-economy price-point gaps in the 40-60% range for heterojunction-compatible encapsulant grades create immediate white-space opportunity. Target India's BIS certification pathway as the most penetrable geography given PLI-driven module capacity expansion and nascent domestic film supply. Agrivoltaic dual-use specifications represent the least contested application niche, with spectral selectivity requirements favoring specialized polyolefin elastomer entrants over commodity producers. A joint-venture structure with established resin processors accelerates qualification timelines versus greenfield compounding investment. For Investors and Strategic Acquirers: Valuations sit cheapest among regional compounders with captive module-maker relationships but limited resin backward integration. The five-to-ten-year viability window favors acquisition targets with thermoplastic formulation portfolios aligned to circular economy directives rather than crosslinked ethylene vinyl acetate legacy assets. Watch for inflection in China's GB standards enforcement timeline as the decisive signal for thermoplastic substitution velocity versus incumbent reformulation defense.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vinyl Acetate Monomer | Captive resin supply insulates margin compression from petrochemical feedstock volatility. |
| Bifacial-Specific Certification Investment | IEC 61215 bis pre-emption secures supplier status for heterojunction module lines. |
| India PLI-Aligned Capacity Buildout | Domestic production satisfies MNRE localization rules for module assembly qualification. |
| Thermoplastic Formulation R&D Pivot | Recyclable chemistry alignment with EU circular economy directives and China's GB standards. |
| Long-Term Supply Agreement with Utility-Scale Developers | Portfolio-level procurement consolidation favors qualified vendors with balance sheet capacity. |
Research Methodology
Direct dialogue with module manufacturer procurement directors, resin processor plant managers, EPC contractor material specifiers, and regulatory affairs leads at chemical conglomerates grounded qualitative assessments. Secondary validation drew from IEC certification databases, customs trade flows for ethylene vinyl acetate resin, SEC filings of listed chemical producers, and MNRE PLI scheme beneficiary disclosures. Bottom-up module deployment forecasts triangulated against top-down polymer demand estimates from petrochemical industry associations.
Bottom-up volume modeling by material type, thickness specification, cell architecture, and end-user category fed into value projections across the analysis window. Segmentation dimensions included chemistry tier, dimensional gauge, and technology application with regional regulatory cluster overlays. CAGRs derived from fitted growth curves anchored to disclosed capacity expansion timelines and module efficiency improvement trajectories. Forecast inputs incorporated heterojunction cell migration rates and floating solar deployment pipelines.
The model assumes a particular technology adoption path; alternative pathways for perovskite-silicon tandem commercialization would alter the outlook through modified thermal stability requirements. Forecasts reflect assumptions regarding regulatory enforcement intensity for circular economy directives and carbon border adjustment implementation scope. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
Compound Semiconductor Materials Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
Encapsulant Market
Semiconductor Material
Tungsten Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Global Scintillator Market
Semiconductor Material
Silicon Germanium Material Market
Semiconductor Material
Platter Substrate Materials Market
Semiconductor Material
Semiconductor PI Film Market
Semiconductor Material
Gallium Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Electroceramics Market
Semiconductor Material
Methyl Phenyl Silicone Resin Market
Semiconductor Material
India Liquid Silicon Rubber Market