
 DCB and AMB Substrate Market | 2026-2036
DCB and AMB Substrate Market Size, Share, and Industry Trends Forecast 2026-2036
DCB and AMB Substrate Market Outlook
Aftermarket thermal management services is tilting margin pools away from raw substrate sales toward module-level integration support. Heraeus Electronics leverages its precious metals heritage to dominate metallization chemistry for AMB substrates. Kyocera Corporation anchors Japanese supply security through captive ceramic powder production. Rogers Corporation competes in North American defense and aerospace qualification channels with specialized thin-film DCB variants.
DCB and AMB substrates are ceramic-metal composite structures, typically aluminum oxide or silicon nitride bonded to copper through high-temperature direct bonding or active metal brazing, engineered to dissipate heat in power semiconductor modules operating above 150°C. AMB substrates using silicon nitride deliver superior thermal cycling resistance for traction inverter applications where DCB remains cost-preferred in lower-power LED and consumer drives. Power electronics applications command the deepest value pools due to EV inverter buildouts, while telecommunications infrastructure sustains steady DCB consumption in base station RF amplifiers.
REACH and RoHS frameworks in Europe restrict lead-based brazing alloys and mandate material traceability, pushing substrate makers toward silver-copper-tin active braze formulations. China's GB standards and MIIT efficiency regulations accelerate domestic silicon nitride AMB qualification for rail and grid converters. Japan's METI technology roadmaps coordinate supplier-OEM development consortia for next-generation wide-bandgap packaging. Stakeholders must monitor how substrate thermal conductivity specifications evolve under each jurisdiction's semiconductor self-sufficiency programs.
Market Dynamics
Silicon nitride AMB substrates are compressing qualification timelines for 800V traction inverters as OEMs abandon aluminum oxide DCB for thermal cycling reliability above 150°C junction temperatures.
Growth Catalysts
- China MIIT efficiency mandates:Domestic rail and grid converter specifications now require silicon nitride AMB qualification, accelerating local substrate capacity buildout.
- EV power module thermal loads:Traction inverter manufacturers specify AMB for 800V architectures where thermal cycling resistance exceeds DCB capability.
- European Union Green Deal:REACH and RoHS frameworks restrict lead-based brazing alloys, forcing silver-copper-tin active braze formulation adoption across substrate supply chains.
Market Restraints
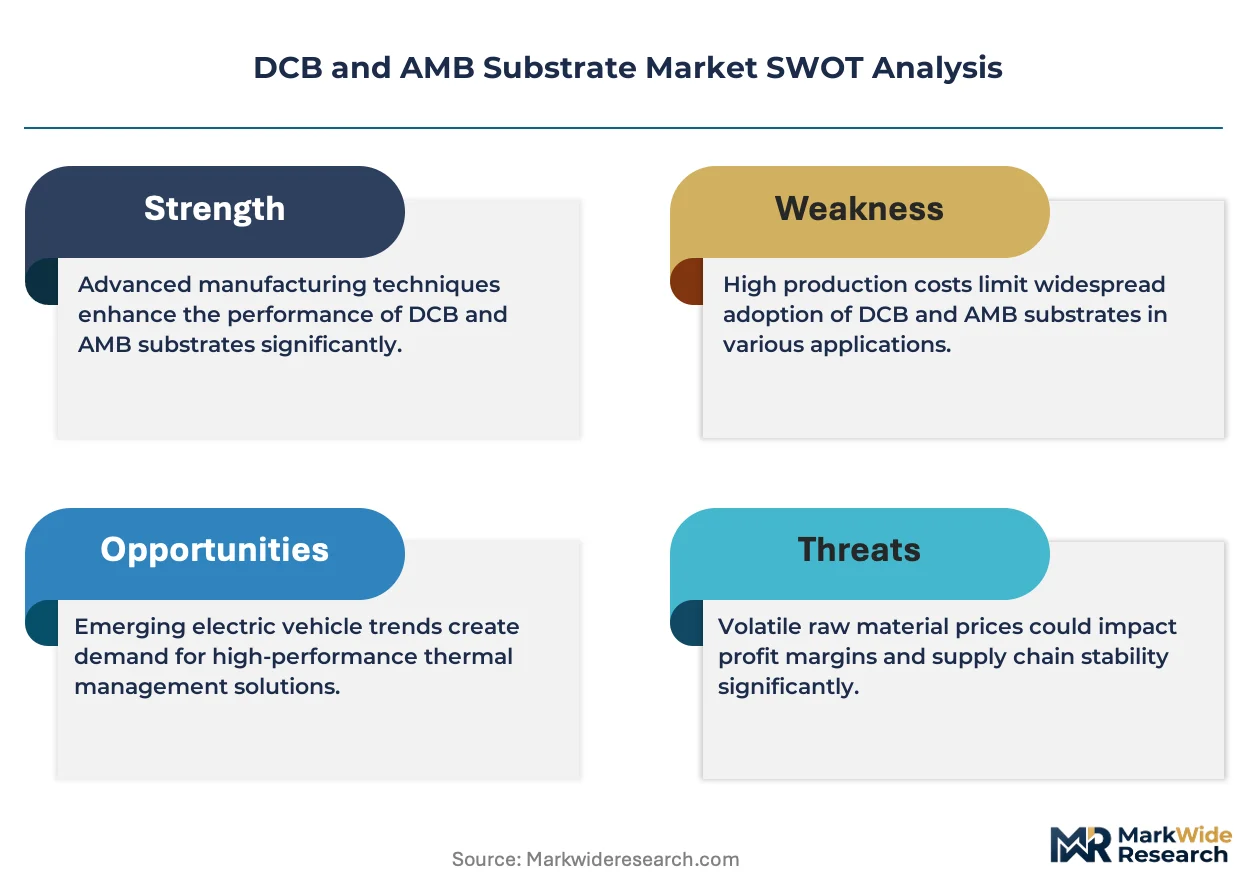
- Silver price volatility:Active braze formulations depend on silver-copper-tin chemistry, exposing metallization costs to precious metal commodity swings.
- Japanese ceramic powder concentration:Kyocera and NGK Insulators control silicon nitride powder supply, creating single-source risk for AMB substrate manufacturers outside Japan.
- Aluminum oxide DCB technical ceiling:Thermal conductivity limits near 24 W/mK prevent aluminum oxide substrates from serving 800V inverter applications regardless of cost advantage.
Strategic Opportunities
- India PLI scheme for semiconductors:Domestic packaging substrate incentives create first-mover advantage for AMB qualification in South Asian EV supply chains.
- Wide-bandgap convergence:Silicon carbide MOSFET packaging requirements for 175°C continuous operation favor silicon nitride AMB thermal expansion matching.
- Aftermarket thermal management services:Module-level integration support contracts capture margin pools beyond raw substrate sales in European EV service networks.
Industry Challenges
- Active metal brazing technician scarcity:Vacuum furnace operation and braze alloy formulation expertise concentrate in German and Japanese engineering clusters, constraining global AMB capacity expansion.
- Automotive AEC-Q100 certification timelines:18-24 month qualification cycles for traction inverter substrates delay revenue recognition despite design wins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DCB and AMB Substrate Market |
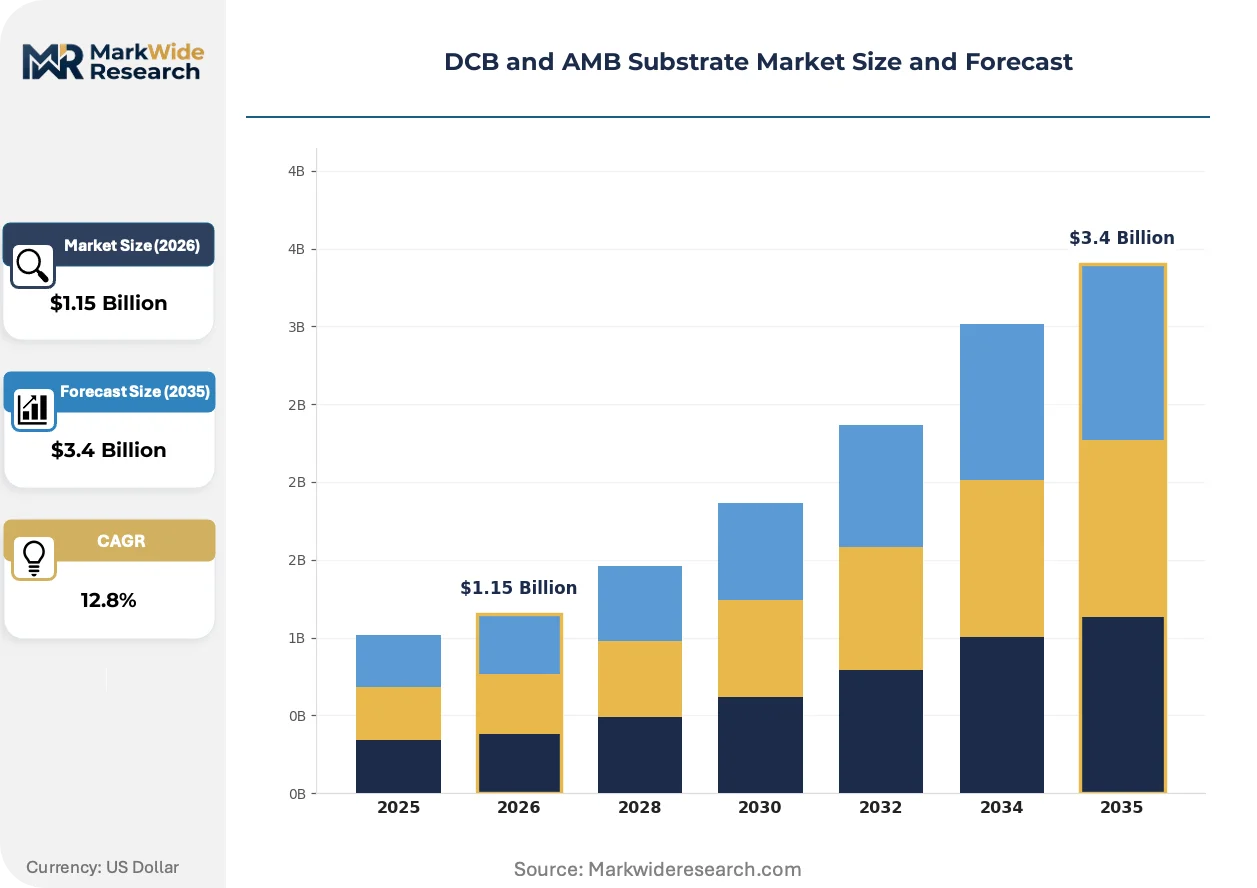
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $3.4 Billion |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DCB, AMB, Ceramic, Metal Technology: High-Temperature Superconductors, Thin Film, 3D Packaging, Power Modules End User: Telecommunications, Automotive, Renewable Energy, Industrial Automation Application: Power Electronics, LED Lighting, Aerospace, Medical Devices |
| Companies Covered | NGK Insulators, Heraeus Electronics, Rogers Corporation, Mitsubishi Materials Corporation, CeramTec GmbH, Kyocera Corporation, DENKA Company Limited, BYD Electronics, Ferrotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DCB and AMB Substrate Market Strategic Shifts
Substrate metallization chemistry and ceramic grade specifications are diverging as wide-bandgap semiconductor packaging demands exceed legacy DCB design margins established for silicon IGBT modules.
Silicon nitride ceramic substrates with thermal conductivity above 90 W/mK are rendering obsolete aluminum oxide DCB in 800V EV traction inverters. Tier-1 automotive suppliers specify AMB exclusively for new platform designs launching from 2026. The technology shift is compressing DCB market share to LED lighting and consumer appliance segments where thermal cycling loads remain modest.
REACH Annex XVII restrictions on lead compounds are forcing European substrate manufacturers to eliminate lead-containing brazing alloys from active metal brazing processes. Silver-copper-tin formulations now dominate AMB production, increasing material traceability documentation burdens across the supply chain. German automotive OEMs require full substance disclosure to meet EU battery passport regulations extending to power module substrates.
Power module assemblers are consolidating procurement around qualified substrate suppliers capable of co-designing direct-plated copper patterns. Direct technical collaboration replaces spot-market purchasing in European and Japanese EV supply chains. This behavior shift favors integrated metallization-ceramic manufacturers over pure-play substrate fabricators in high-volume inverter programs.
DCB and AMB Substrate Market Segmentation
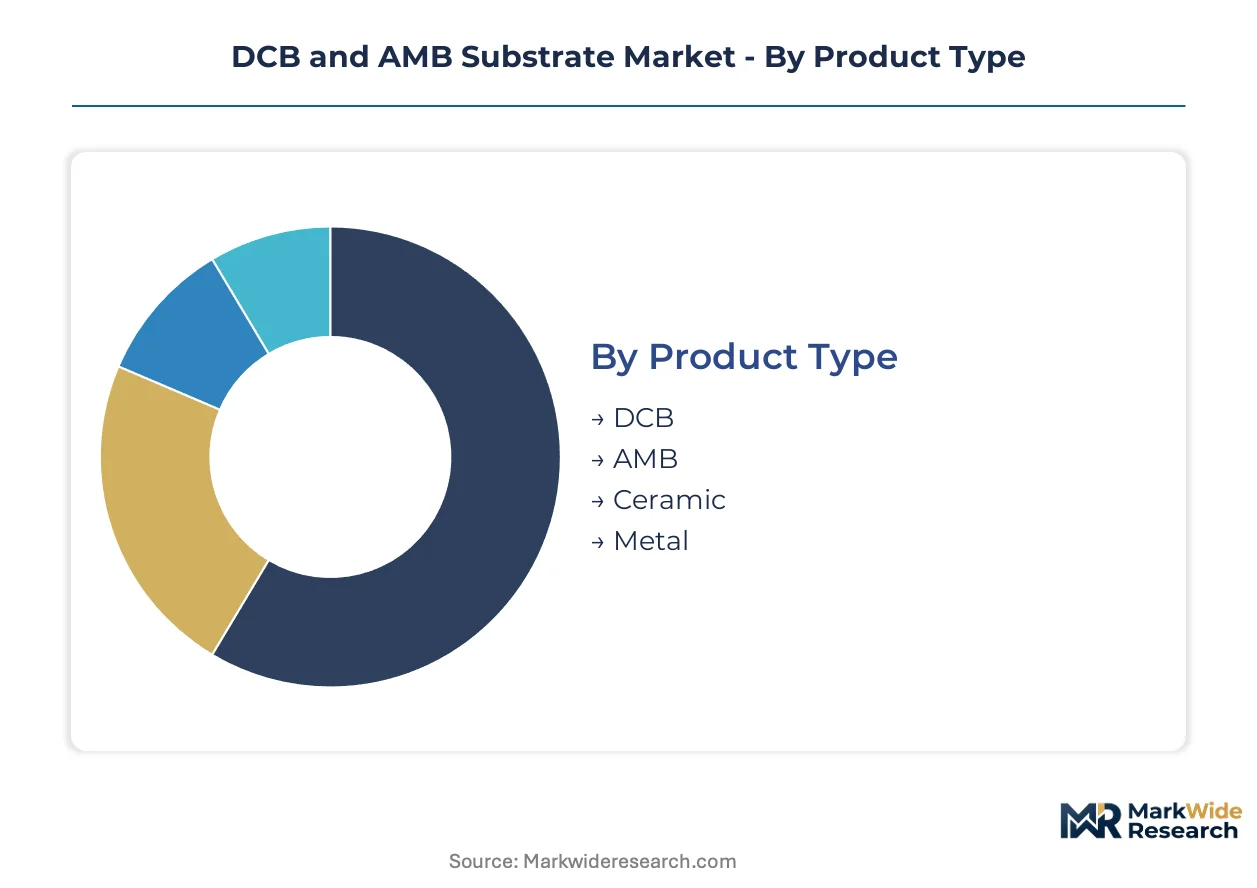
DCB and AMB substrate procurement patterns diverge sharply across product generations and end-use thermal loads. Substrate specification cascades from semiconductor junction temperature requirements through ceramic grade selection to metallization chemistry.
Product Type:
Cost tier separates legacy aluminum oxide systems from silicon nitride platforms commanding metallization premiums.
- DCB:Direct copper bonding onto aluminum oxide ceramic delivers thermal conductivity near 24 W/mK through high-temperature eutectic bonding. Consumer appliance motor drives in Germany and LED retrofit installations across India sustain volume despite technical ceiling constraints.
- AMB:Active metal brazing with silver-copper-tin chemistry bonds copper to silicon nitride substrates exceeding 90 W/mK thermal conductivity. 800V traction inverter programs at German and Japanese automotive OEMs specify AMB exclusively for junction temperatures above 150°C.
- Ceramic:Raw aluminum oxide and silicon nitride substrates without metallization serve captive integration at Japanese ceramic powder manufacturers.
- Metal:Copper and aluminum base plates for thermal interface layers in power module assembly.
DCB commands the established base. The steepest expansion runs through AMB.
Technology:
Application maturity ranges from volume production to qualification-stage architectures.
- Power Modules:Standardized DCB and AMB substrates for IGBT and silicon carbide MOSFET packaging dominate procurement volumes. EV inverter buildouts in China, Germany, and Japan concentrate demand for thermally matched substrate stacks.
- Thin Film:Sputtered copper patterns on ceramic achieve sub-100 micron trace resolution for RF amplifiers in 5G base station deployments.
- High-Temperature Superconductors:Specialized ceramic substrates for cryogenic power electronics in fusion energy research.
- 3D Packaging:Embedded substrate architectures for advanced wide-bandgap module integration remain pre-commercial.
Power modules anchor current procurement. Thin film gains share fastest in telecommunications infrastructure.
End User:
Customer type determines thermal cycling qualification rigor and contract duration.
- Automotive:Tier-1 inverter suppliers specify AMB substrates with AEC-Q100 certification and 18-24 month qualification timelines. Traction programs at OEMs in Germany, Japan, and China drive silicon nitride adoption.
- Renewable Energy:Grid-tied inverters and wind converter manufacturers balance thermal performance against 25-year reliability warranties.
- Industrial Automation:Motor drive OEMs in Germany and Japan specify DCB for cost-sensitive variable frequency drives below 100kW.
- Telecommunications:Base station RF amplifier manufacturers consume thin-film DCB variants for gallium nitride devices.
Automotive end-use concentrates value capture. Renewable energy presents the steepest expansion trajectory for AMB qualification.
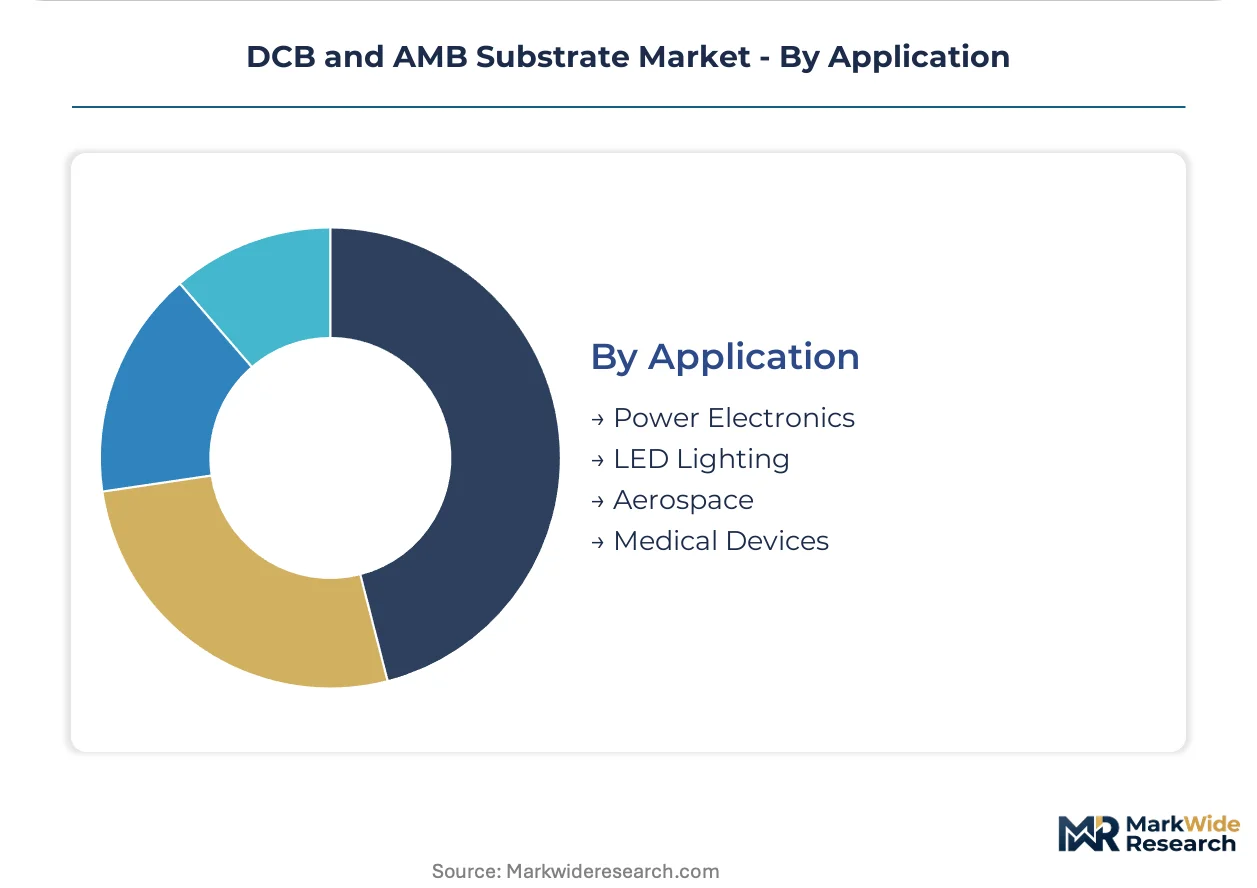
Application:
Functional thermal load dictates ceramic grade and metallization thickness specifications.
- Power Electronics:Traction inverters, grid converters, and motor drives generate substrate demand across all power classes. EV applications above 150kW specify silicon nitride AMB exclusively.
- LED Lighting:Mid-power commercial and residential retrofit luminaires specify aluminum oxide DCB for thermal management below 100W.
- Aerospace:Defense-qualified thin-film substrates for radar and electronic warfare systems operate through Rogers Corporation supply channels in North America.
- Medical Devices:Imaging equipment power supplies and surgical laser systems require medical-grade substrate traceability.
Power electronics commands the established base. Aerospace and medical segments climb fastest through qualification backlogs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian motor drive OEMs exhibit acute price sensitivity toward aluminum oxide DCB substrates, while German and Japanese automotive Tier-1s absorb metallization premiums for silicon nitride AMB without volume elasticity. This demand bifurcation concentrates high-value procurement in automotive clusters and commodity procurement in industrial automation corridors.
China
Domestic EV inverter buildouts at BYD and CATL power module subsidiaries are consuming silicon nitride AMB substrates at unprecedented scale. MIIT efficiency mandates for rail and grid converters now require AMB qualification, accelerating substrate capacity expansion in Jiangsu and Zhejiang provinces. Suzhou and Hangzhou manufacturing corridors host emerging domestic AMB fabrication lines serving BYD Electronics and local automotive OEM supply chains.
Germany
BMW and Volkswagen traction inverter programs specify AMB exclusively for 800V platform launches, eliminating aluminum oxide DCB from new designs. REACH Annex XVII restrictions on lead compounds force silver-copper-tin braze formulation adoption across substrate supply chains. Bavaria and Baden-Württemberg host concentrated metallization chemistry expertise, with Nuremberg-area vacuum furnace operations serving Continental and Bosch power module divisions.
Japan
Toyota and Honda electrification roadmaps coordinate silicon nitride AMB qualification through METI-sponsored supplier-OEM consortia. Kyocera and NGK Insulators maintain captive ceramic powder production, securing supply chain sovereignty for domestic substrate fabricators. Nagoya and Kyoto industrial clusters concentrate active metal brazing technician expertise, constraining global AMB capacity expansion outside these engineering centers.
United States
Defense and aerospace qualification channels sustain specialized thin-film DCB consumption for radar and electronic warfare systems. Rogers Corporation anchors North American supply for these applications, with Massachusetts and Connecticut hosting thin-film sputtering operations. Commercial EV substrate demand remains import-dependent, with no domestic silicon nitride AMB volume production qualified for automotive AEC-Q100 standards.
India
Variable frequency drive manufacturers in Gujarat and Maharashtra specify aluminum oxide DCB for cost-sensitive motor control below 100kW. The PLI scheme for semiconductors creates first-mover incentives for AMB substrate qualification, though no domestic silicon nitride powder production exists. Tamil Nadu and Karnataka EV manufacturing corridors represent emerging demand centers as Ola Electric and Tata Motors expand inverter sourcing.
DCB and AMB Substrate Market Competitive Environment
Integrated metallization-ceramic manufacturers and pure-play substrate fabricators split the market along value-chain depth lines. Three strategic archetypes dominate: Japanese ceramic powder suppliers with captive substrate integration, German metallization chemistry specialists with vacuum furnace expertise, and North American defense-qualified thin-film operators. Competitive moves concentrate on backward integration into ceramic powder production and co-design partnerships with automotive Tier-1 power module divisions.
Within the integrated ceramic-metallization tier, Kyocera Corporation and NGK Insulators exemplify supply security through in-house silicon nitride powder production. Heraeus Electronics occupies a distinct position as a metallization chemistry specialist leveraging precious metals heritage for active braze formulation. These three anchors demonstrate how substrate competitive positioning depends on controlling either upstream ceramic material or critical metallization chemistry, with rare overlap between both capabilities.
| Leading Market Players |
|---|
| NGK Insulators |
| Heraeus Electronics |
| Rogers Corporation |
| Mitsubishi Materials Corporation |
| CeramTec GmbH |
| Kyocera Corporation |
| DENKA Company Limited |
| BYD Electronics |
| Ferrotec |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's freight cost volatility transmits directly into substrate landed costs, amplifying price spreads between German vacuum-furnace metallization and Chinese active-braze fabrication while forcing automotive Tier-1s to consolidate procurement around qualified suppliers capable of absorbing logistics swings through long-term offtake structures.
Pricing Analysis
Aftermarket thermal management service contracts now capture margin pools exceeding raw substrate sales in European EV service networks. Pricing stratifies across AEC-Q100 certified silicon nitride AMB, industrial-grade aluminum oxide DCB, and unqualified ceramic substrates for captive integration. Cost compression in aluminum oxide DCB is intensifying because Indian motor drive OEMs exhibit acute price sensitivity below 100kW applications. Automotive Tier-1s show least price elasticity, absorbing silver-copper-tin metallization premiums without volume reduction.
Supply Chain Analysis
Export control restrictions on vacuum furnace technology and active braze alloy formulations limit AMB capacity expansion outside German and Japanese engineering clusters. Supply concentrates in Japan, Germany, and China for silicon nitride powder production, metallization chemistry, and substrate fabrication respectively. Raw material dependencies include silver for braze formulations, high-purity silicon nitride ceramic, and copper foil for direct bonding. Single-source vulnerability pervades Japanese silicon nitride powder supply controlled by Kyocera and NGK Insulators. Distribution runs through direct technical collaboration contracts replacing spot-market purchasing in automotive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Tier-1 automotive supplier consolidation around qualified substrate fabricators capable of co-designing direct-plated copper patterns, fragmenting procurement access for pure-play manufacturers lacking metallization integration.
For Market Incumbents: Pre-empt silicon carbide MOSFET packaging qualification cycles by securing AEC-Q100 certification for 175°C continuous operation substrates before wide-bandgap convergence accelerates. Backward integration into ceramic powder production mitigates single-source exposure to Japanese supply. Capacity addition in Jiangsu and Zhejiang provinces captures China MIIT efficiency mandate demand. Threat from emerging domestic Chinese fabricators with government subsidy backing intensifies margin pressure in commodity DCB tiers. For New Entrants and Emerging Players: Establish a beachhead in Indian PLI scheme semiconductor packaging incentives before domestic AMB qualification saturates. White-space targets include aftermarket thermal management services in European EV service networks and defense-qualified thin-film substrates for North American radar applications. Go-to-market angle: co-development partnerships with Ola Electric and Tata Motors in Tamil Nadu and Karnataka corridors where inverter sourcing is expanding. For Investors and Strategic Acquirers: Metallization chemistry specialists with precious metals heritage and vacuum furnace operational expertise represent the priority acquisition archetype for substrate supply chain consolidation. Long-term viability hinges on positioning for wide-bandgap semiconductor packaging transition over the next decade. Signal to watch: AEC-Q100 certification timeline compression for 800V traction inverter programs as OEMs abandon aluminum oxide DCB.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Production | Kyocera and NGK Insulators demonstrate supply security through captive silicon nitride manufacturing. |
| AEC-Q100 Certification Investment | German automotive OEMs require 18-24 month qualification cycles for traction inverter substrate approval. |
| Silver-Copper-Tin Braze Formulation Scale-Up | REACH Annex XVII restrictions force elimination of lead-containing alloys across European supply chains. |
| Co-Design Partnership with Tier-1 Power Module Divisions | Continental and Bosch procurement consolidation favors integrated metallization-ceramic manufacturers. |
| Geographic Manufacturing Footprint in Jiangsu Province | BYD Electronics and CATL power module subsidiaries consume AMB substrates at unprecedented scale. |
Study Parameters
Operator-level perspectives from vacuum furnace technicians, active metal brazing chemists, Tier-1 power module procurement directors, and automotive platform engineers anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from MIIT efficiency mandate filings, METI technology roadmaps, REACH Annex XVII substance restrictions, and SEC disclosures from substrate manufacturers. Bottom-up substrate fabrication capacity estimates triangulated against top-down EV inverter buildout projections across German, Japanese, and Chinese automotive OEM supply chains.
Scenario-bracketing around silver price volatility, silicon nitride powder supply disruption, and AEC-Q100 certification timeline compression shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include substrate product type, ceramic grade specification, metallization chemistry, end-user industry, and regional regulatory cluster. CAGRs derived from substrate procurement volume trajectories tied to EV inverter production schedules and renewable energy converter installations. Industry-specific forecast inputs encompass traction inverter thermal load specifications and wide-bandgap semiconductor packaging temperature requirements.
Sensitivities concentrate around silver commodity price swings, Japanese ceramic powder export restrictions, and 800V platform adoption rates. Forecasts reflect documented assumptions regarding MIIT mandate enforcement timelines and METI consortium coordination intensity. Material shifts in EU battery passport substance disclosure requirements or China dual carbon goal acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Global Semiconductor Microelectronics Materials Market
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Compound Semiconductor Materials Market
Semiconductor Material
Yttrium Market
Semiconductor Material
Polysilicon for Solar Semiconductor Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Electronic Assembly Materials Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Global Gallium Oxide Market
Semiconductor Material
Global Polybutylene Terephthalate (PBT) Market
Semiconductor Material
Solar Silicon Ingots Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
Electronic Thermal Management Materials Market
Semiconductor Material
Silicon Tetrachloride Market