
 Gallium Trichloride Market | 2026-2036
Gallium Trichloride Market Size, Share, and Industry Trends Forecast 2026-2036
Gallium Trichloride Market Insights
The EU Green Deal is pivoting chemical purity requirements for electronics precursors, forcing suppliers to certify lower halide contamination. Indium Corporation leverages its vertical integration from metal refining to specialty chemicals, sustaining captive feedstock advantages. Neo Performance Materials competes through rare earth and critical mineral diversification, while American Elements specializes in custom synthesis for research-scale buyers.
Gallium trichloride is an anhydrous Lewis acid with formula GaCl₃, typically synthesized via direct chlorination of metallic gallium or oxide reduction with chlorine at elevated temperatures; it serves as a precursor for gallium arsenide and gallium nitride epitaxy in optoelectronics. Semiconductor Grade material anchors margin pools due to sub-ppm trace metal specifications required by MOCVD tool operators. Electronics Grade demand accelerates fastest as mini-LED and micro-LED fabs multiply wafer starts, while Industrial Grade applications in bulk chemical synthesis occupy mature, price-sensitive territory with thinner returns.
REACH registration and RoHS substance restrictions in Europe, alongside China's SAMR oversight of electronic-grade chemical standards, shape product specifications and cross-border market access for non-compliant producers. The US EPA and OSHA jointly govern workplace exposure limits and waste handling for chlorinated gallium compounds in domestic manufacturing. Stakeholders must monitor evolving dual-use export controls on precursor chemicals and pre-position alternative supply arrangements before qualification timelines extend.
Market Dynamics
Semiconductor fabs are consolidating gallium trichloride procurement around single-source qualification programs, compressing supplier diversity as MOCVD tool operators demand batch-to-batch consistency for sub-10nm epitaxial layers.
Growth Catalysts
- Micro-LED fab construction:Display manufacturers in South Korea and Taiwan are commissioning dedicated epitaxy lines that specify semiconductor-grade GaCl₃ for wafer-scale uniformity.
- REACH registration deadlines:ECHA's phased substance evaluation is accelerating supplier consolidation toward pre-registered producers with dossier completeness.
- GaN-on-Si power electronics:Automotive inverter programs are qualifying GaN epitaxy for 800V architectures, pulling high-purity precursor volumes.
Market Restraints
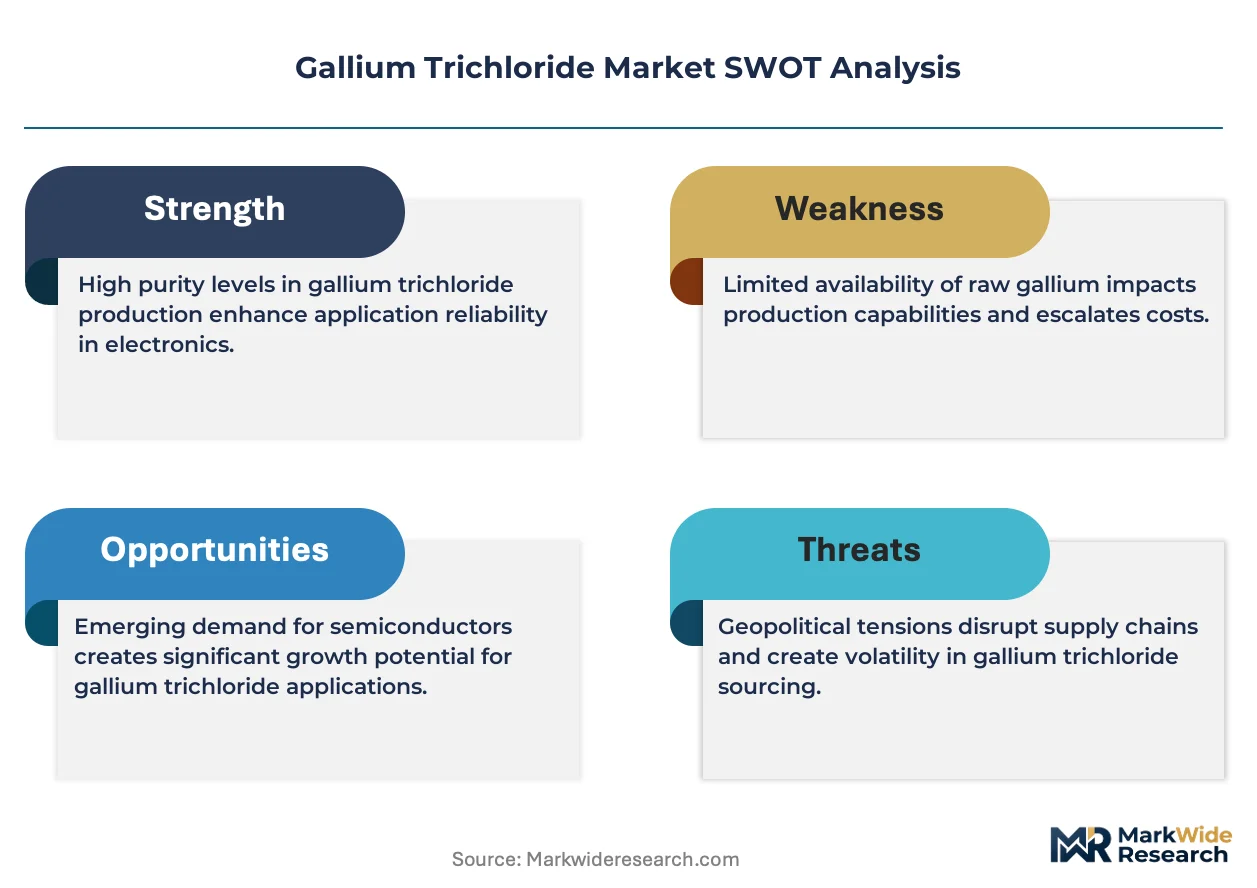
- Primary gallium supply concentration:Over 80% of feedstock refining occurs in Chinese state-controlled smelters, exposing non-domestic formulators to export quota volatility.
- Chlorine handling infrastructure:Anhydrous synthesis requires pressure-rated chlorination vessels and scrubber systems that carry seven-figure capital intensity.
- Perfluorinated precursor substitution:CVD tool operators are testing organometallic alternatives for select III-V deposition steps, threatening long-term volume assumptions.
Strategic Opportunities
- Indian PLI scheme for compound semiconductors:Ministry of Electronics and Information Technology incentives are attracting GaN fab investments that will localize precursor demand.
- On-site synthesis units:Integrated device manufacturers are piloting captive GaCl₃ generation adjacent to MOCVD bays, eliminating packaging and transport contamination risks.
- EU Critical Raw Materials Act:Strategic stockpiling mandates and domestic processing targets are creating offtake guarantees for European-qualified suppliers.
Industry Challenges
- Ultra-trace analysis capability:ICP-MS operators with sub-ppb detection limits for alkali and transition metals command salaries exceeding standard chemical QA roles by 40-60%.
- Dual-use export classification:Bureau of Industry and Security licensing for electronic-grade chlorides adds 90-120 day lead times to US-origin shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gallium Trichloride Market |
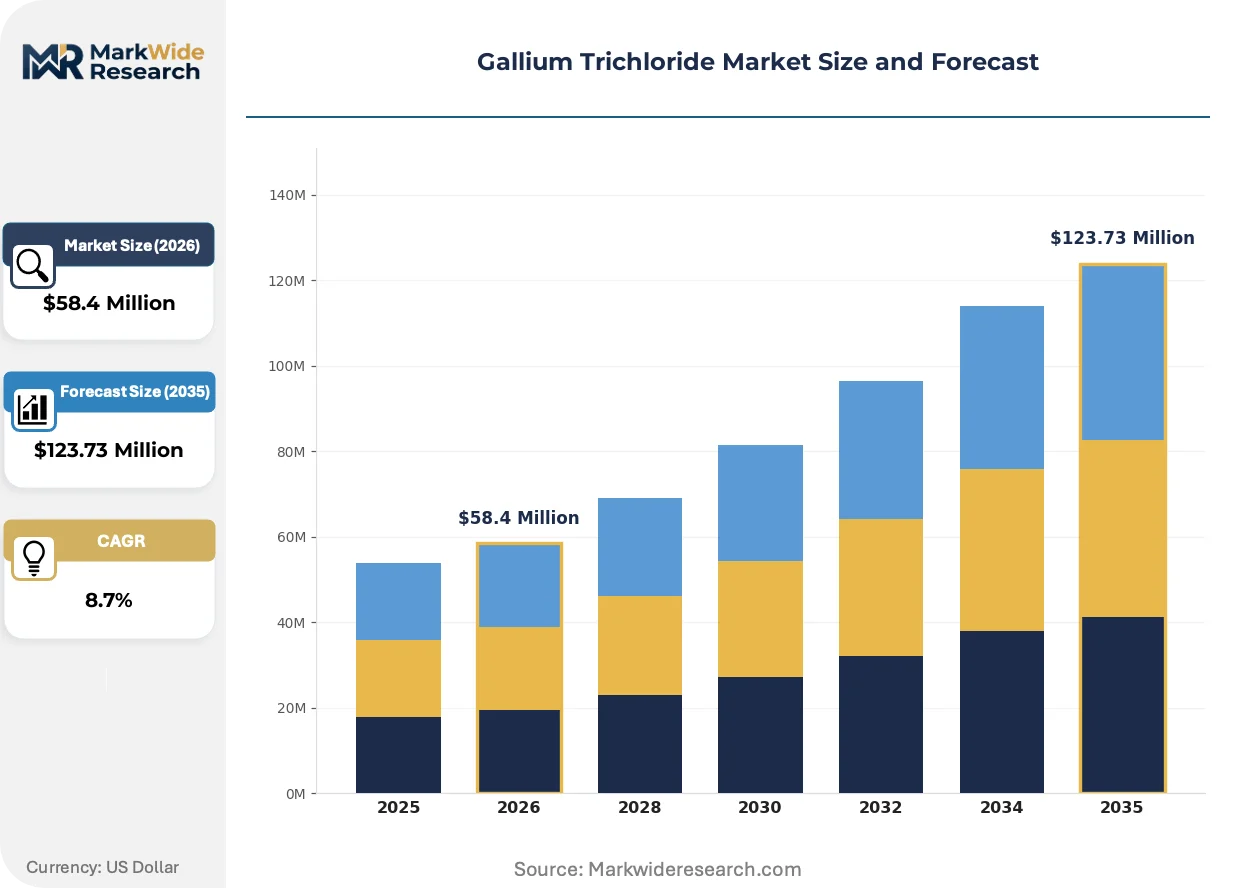
| Market Size in 2026 | $58.4 Million |
| Market Size in 2035 | $123.73 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics Grade, Semiconductor Grade, Industrial Grade, Reagent Grade Application: LED Manufacturing, Semiconductor Fabrication, Chemical Synthesis, Thin Film Deposition End User: Electronics Industry, Chemical Industry, Research Laboratories, Academic Institutions Packaging Type: Drum, Bottle, Bulk, Cylinder |
| Companies Covered | Indium Corporation, Ereztech, Actylis, Neo Performance Materials, American Elements, Merck KGaA, Strem Chemicals, Alfa Chemistry, Tokyo Chemical Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gallium Trichloride Market Trends and Innovations
Epitaxial precursor supply is fragmenting into performance-tiered service models where chemical specification, packaging format, and logistics integration are unbundled and repriced separately.
Containerized synthesis units are modularizing gallium trichloride production for co-location with semiconductor fabs. MOCVD operators in Hsinchu and Pyeongtaek are piloting skid-mounted chlorination systems that eliminate cross-border chemical transport. This distributed architecture is compressing qualification cycles from 18 months to 6 months for new epitaxy lines.
China's GB/T 31326-2014 electronic chemical standards are tightening moisture and particle specifications for imported precursors. SAMR enforcement actions against non-compliant suppliers have accelerated since 2023, forcing reformulation investments among traders. Korean chemical distributors are responding by establishing bonded warehousing with in-country repackaging capabilities.
Contract structures are migrating from spot purchasing to multi-year tolling agreements with volume commitments. Mini-LED fabs in Taoyuan and Gumi are locking in 36-month supply schedules that embed price collars and quality audit rights. This shift transfers inventory carrying costs upstream while securing allocation during feedstock constraints.
Gallium Trichloride Market Segmentation
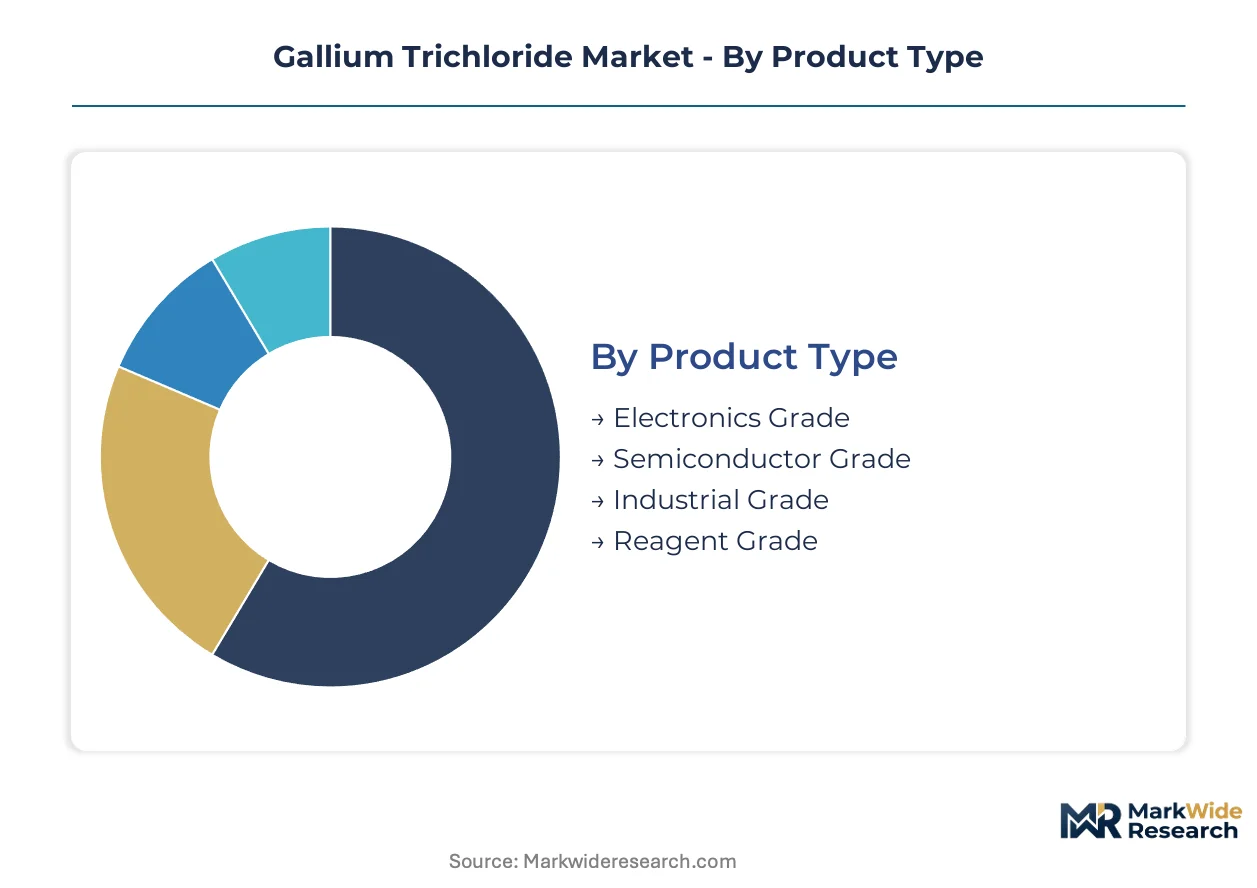
Segmentation in gallium trichloride procurement reflects divergent purity tolerances across epitaxy applications. Semiconductor fabs enforce sub-ppm specifications while industrial synthesis tolerates higher halide content, creating tiered supply chains with minimal supplier overlap.
Product Type:
Purity thresholds define the technology axis, with each grade calibrated to contamination limits that determine MOCVD compatibility.
- Semiconductor Grade:Specifications demand sub-ppm alkali and transition metal content for GaN and GaAs epitaxy in advanced node production. South Korean display fabs in Gumi and Paju anchor procurement volumes as micro-LED qualification accelerates.
- Electronics Grade:Moisture and particle specifications align with mini-LED and power electronics deposition requirements. Taiwan-based epitaxy houses in Hsinchu and Taoyuan are expanding wafer starts, pulling volumes from qualified distributors with bonded warehousing capabilities.
- Industrial Grade:Bulk chemical synthesis applications in catalyst production and organic gallium compound manufacturing tolerate elevated halide residuals.
- Reagent Grade:Research-scale volumes serve academic laboratories and materials science programs with flexible specification windows.
Mature deployment sits with Industrial Grade. Newer deployment is concentrated in Semiconductor Grade.
Application:
End-use concentration tracks the migration of compound semiconductor manufacturing toward dedicated LED and power electronics fabs.
- LED Manufacturing:Blue, green, and white LED epitaxy consumes the largest GaCl₃ volumes, with Taiwan's LED chipmakers in Tainan and Miaoli operating continuous MOCVD campaigns. Samsung Display and LG Innotek in South Korea are qualifying domestic precursor supplies for next-generation displays.
- Semiconductor Fabrication:GaN-on-Si power device programs for 800V automotive inverters are expanding qualification pipelines. European automotive suppliers are engaging directly with precursor formulators to secure REACH-registered volumes.
- Chemical Synthesis:Organogallium reagent production and gallium-based catalyst manufacturing occupy stable demand territory.
- Thin Film Deposition:CVD and ALD processes for specialty coatings and research applications require precise vapor pressure control.
Volume concentration favors LED Manufacturing. Technology migration is accelerating fastest in Semiconductor Fabrication.
End User:
Customer type determines packaging format, logistics integration, and quality audit protocols across the value chain.
- Electronics Industry:Integrated device manufacturers and pure-play foundries specify semiconductor-grade material with batch traceability and certificate of analysis documentation. Procurement teams in Hsinchu Science Park negotiate multi-year tolling agreements with embedded price collars.
- Chemical Industry:Specialty chemical formulators and catalyst producers purchase industrial-grade volumes on spot or quarterly contract terms.
- Research Laboratories:Corporate R&D facilities in optoelectronics and materials science require flexible order quantities with rapid qualification support.
- Academic Institutions:University chemistry and physics departments source reagent-grade material through distributor networks with educational pricing structures.
Contract sophistication peaks with Electronics Industry. Pricing flexibility is greatest with Academic Institutions.
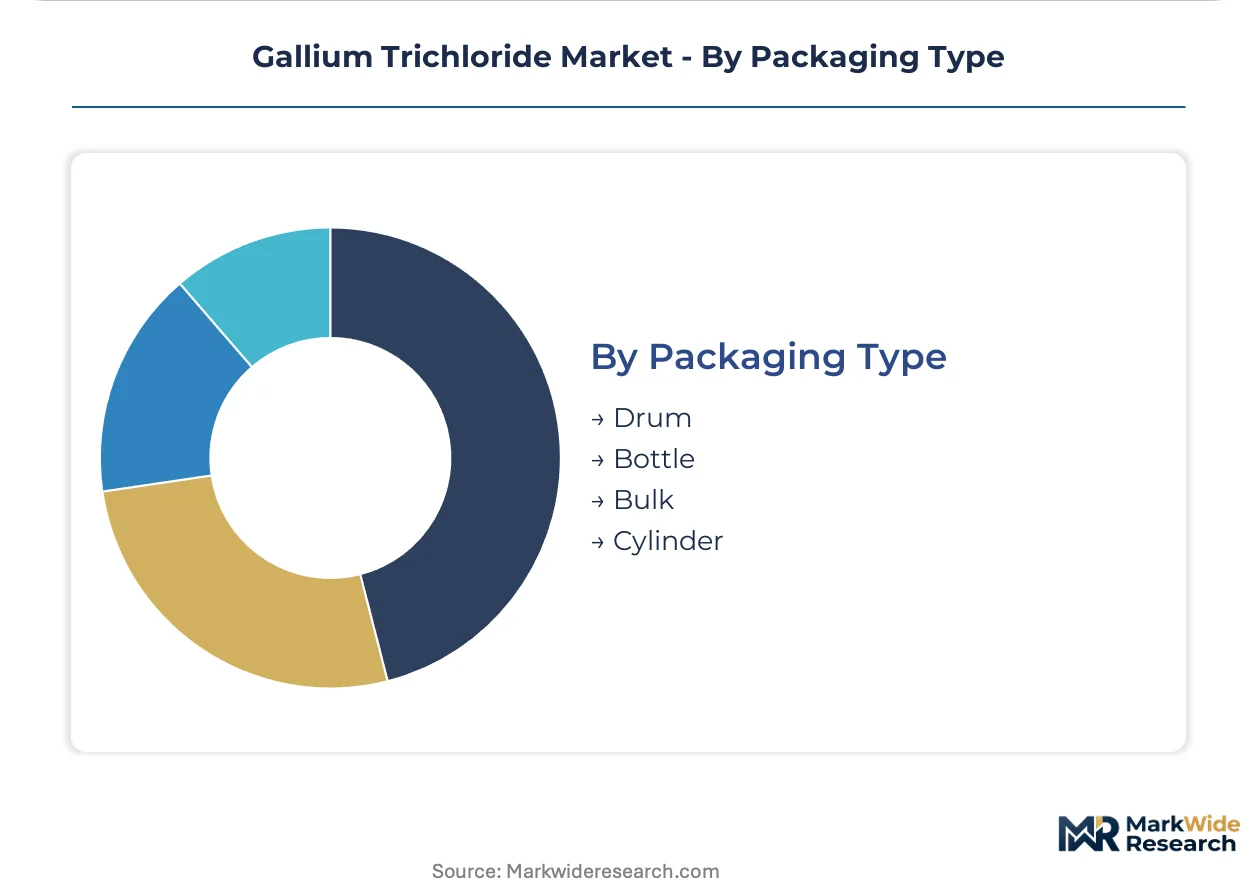
Packaging Type:
Container selection balances contamination risk, transport economics, and handling infrastructure at the point of use.
- Cylinder:High-pressure vessels with inert gas overlay preserve anhydrous integrity for semiconductor-grade material during long-haul transport. Korean distributors are investing in cylinder fleets with GPS tracking and temperature logging.
- Bulk:ISO tank containers and dedicated tanker deliveries serve high-volume LED fabs with on-site storage and repackaging capabilities.
- Drum:Stainless steel drums with nitrogen padding accommodate mid-scale electronics-grade shipments for fabs without bulk infrastructure.
- Bottle:Amber glass or fluoropolymer bottles protect reagent-grade material from photodegradation and moisture ingress for laboratory-scale consumption.
Capital intensity concentrates with Cylinder. Cost efficiency is expanding fastest with Bulk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park in Taiwan commands the densest concentration of gallium trichloride consumption, with epitaxy houses running continuous MOCVD campaigns for micro-LED qualification. Procurement teams there negotiate multi-year tolling agreements that embed price collars and batch traceability requirements.
China
State-controlled smelters in Guangxi and Guizhou provinces refine over 80% of global primary gallium feedstock, exposing downstream formulators to export quota volatility. SAMR enforcement of GB/T 31326-2014 standards since 2023 has accelerated compliance investments among traders serving the Yangtze River Delta semiconductor cluster.
South Korea
Samsung Display and LG Innotek in Gumi and Paju are commissioning dedicated micro-LED epitaxy lines that specify semiconductor-grade GaCl₃ for wafer-scale uniformity. The Ministry of Trade, Industry and Energy backs domestic precursor supply development through compound semiconductor initiatives.
United States
GaN-on-Si power device programs for 800V automotive inverters are expanding qualification pipelines in Michigan and Texas manufacturing corridors. Bureau of Industry and Security licensing for electronic-grade chlorides adds 90-120 day lead times to domestic-origin shipments.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg are engaging directly with precursor formulators to secure REACH-registered volumes for GaN epitaxy. The EU Critical Raw Materials Act is creating offtake guarantees for European-qualified suppliers through strategic stockpiling mandates.
India
The Ministry of Electronics and Information Technology's PLI scheme for compound semiconductors is attracting GaN fab investments to Karnataka and Telangana that will localize precursor demand. Domestic chemical distributors are establishing bonded warehousing with in-country repackaging capabilities.
Gallium Trichloride Market Competitive Landscape
The competitive structure tilts toward vertically integrated metal refiners with captive gallium feedstock. Supplier consolidation is compressing diversity as MOCVD tool operators demand batch-to-batch consistency for sub-10nm epitaxial layers. Two strategic archetypes dominate: integrated specialty chemical producers with backward control over rare earth and critical mineral supply chains, and research-scale custom synthesis specialists serving flexible specification windows. Capacity expansion and geographic diversification through bonded warehousing partnerships represent the dominant competitive moves.
Among North American-anchored suppliers, Indium Corporation exemplifies the integrated refiner-to-specialty-chemical archetype, while American Elements occupies a position within the custom synthesis tier for research-scale buyers. Neo Performance Materials represents the diversified critical minerals conglomerate model competing through rare earth and specialty material breadth. These three anchors illustrate how feedstock security, regulatory dossier completeness, and qualification timeline compression separate viable suppliers from marginal participants.
| Leading Market Players |
|---|
| Indium Corporation |
| Ereztech |
| Actylis |
| Neo Performance Materials |
| American Elements |
| Merck KGaA |
| Strem Chemicals |
| Alfa Chemistry |
| Tokyo Chemical Industry |
| Others |
Pricing and Supply Chain Analysis
Primary gallium metal price indices set the floor for gallium trichloride procurement contracts, cascading through semiconductor-grade and electronics-grade tiers as Chinese state-controlled smelters adjust export quotas. Buyers in Hsinchu and Gumi absorb feedstock volatility through tolling agreements with embedded price collars.
Pricing Analysis
Yield-guaranteed pricing anchors semiconductor-grade contracts, with MOCVD operators paying premiums for batch-to-batch consistency that minimizes epitaxial defect rates. Price differentiation separates REACH-registered European volumes from unregistered trader material, while Korean display fabs show lowest sensitivity due to captive qualification timelines. Cost compression in industrial-grade segments intensifies as bulk chemical buyers switch to spot purchasing.
Supply Chain Analysis
Gallium trichloride supply rests on Chinese primary metal refining, German chlorination equipment manufacturing, and Taiwanese MOCVD tool deployment. Feedstock draws from Guangxi and Guizhou smelters, chlorine from chlor-alkali producers, and specialty packaging from Japanese fluoropolymer fabricators. Single-source vulnerability concentrates in Chinese export quota administration. Distribution runs through bonded warehousing hubs in Seoul and Taoyuan before final-mile cylinder delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gallium trichloride market operates as a cost-of-compliance story where REACH dossier completeness erects barrier-to-entry moats that pre-registered suppliers exploit. ECHA substance evaluation timelines reward early registrants with locked customer relationships.
For Market Incumbents: Deploy captive feedstock contracting to secure primary gallium allocation before Chinese export quota adjustments. Indium Corporation and Neo Performance Materials should expand cylinder fleet GPS tracking capabilities to defend against Korean distributor encroachment. Backward integration into chlor-alkali chlorine sourcing mitigates pressure-rated vessel capital intensity risks from perfluorinated precursor substitution threats.
For New Entrants and Emerging Players: The EU Critical Raw Materials Act opens a window for European-qualified suppliers to capture automotive GaN epitaxy offtake guarantees. Target Indian PLI scheme beneficiaries in Karnataka and Telangana with bonded warehousing partnerships. Lead with mini-LED fab qualification support as the go-to-market wedge against entrenched tolling agreement structures.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated metal refiners with existing gallium circuits and ECHA dossier completeness. Watch for Chinese export quota tightening as the inflection signal triggering premium pricing for non-domestic feedstock security.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Gallium | Captive feedstock from Chinese state smelters insulates against export quota volatility. |
| REACH Dossier Expansion | ECHA registration completeness locks out unregistered traders from European automotive supply chains. |
| Containerized Synthesis Deployment | Skid-mounted chlorination units in Hsinchu and Pyeongtaek compress qualification cycles for new epitaxy lines. |
| Bonded Warehousing Partnerships | In-country repackaging capabilities in Seoul and Taoyuan bypass SAMR enforcement actions against non-compliant imports. |
| Multi-Year Tolling Agreements | Thirty-six month contracts with price collars transfer inventory carrying costs upstream while securing allocation. |
Research Methodology
Independent corroboration across MOCVD tool operators, specialty chemical procurement leads, and chlor-alkali plant managers underwrites the qualitative findings in this study. Primary interviews with epitaxy house technical directors, Korean chemical distributor logistics heads, and European automotive supplier quality engineers combined with secondary validation from ECHA registration databases, Chinese customs trade data, and SEC filings from critical mineral processors. Bottom-up volume estimates from individual fab consumption rates triangulate against top-down gallium metal flow analysis.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. The analytical framework models segmentation across purity grade tiers, end-use applications spanning LED and power electronics, packaging formats from cylinders to bulk ISO tanks, and regional production hub clusters. CAGRs derive from epitaxial wafer start projections and MOCVD tool shipment data, with mini-LED fab construction timelines and GaN-on-Si automotive inverter qualification pipelines serving as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for organometallic CVD precursors would alter the outlook for chloride-based epitaxy demand. Forecasts reflect assumptions regarding Chinese export quota stability, REACH enforcement continuity, and micro-LED yield improvement trajectories. A small set of triggers—primary gallium nationalization, perfluorinated precursor technical breakthroughs, and dual-use export control expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Chalcocite-Digenite Group Market
Semiconductor Material
DCB and AMB Substrate Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Monocrystalline Silicone Market
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
Global Polybutylene Terephthalate (PBT) Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
Semiconductor Silicon Wafer Market
Semiconductor Material
Platter Substrate Materials Market
Semiconductor Material
Niobium Hydride Market
Semiconductor Material
Indium Gallium Zinc Oxide Market
Semiconductor Material
Quartz Crucible Market
Semiconductor Material
Compound Semiconductor Materials Market
Semiconductor Material
Glass Wafer Market
Semiconductor Material
Zinc Oxide Nanoparticles Market