
 Compound Semiconductor Materials Market | 2026-2036
Compound Semiconductor Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Compound Semiconductor Materials Market Intelligence
China's dual carbon goals are repositioning material demand towards higher-efficiency substrates, creating new opportunities in the power electronics sector. Sumitomo Electric Industries leverages its extensive material science portfolio to supply critical substrates for these applications. Infineon Technologies AG specializes in developing power device solutions for automotive and industrial markets. Meanwhile, IQE Plc dominates the market for advanced epitaxial wafers, a critical upstream component for many device manufacturers.
Compound semiconductor materials are crystalline solids composed of elements from at least two different groups in the periodic table, such as gallium arsenide (GaAs) or silicon carbide (SiC). These materials exhibit superior electronic and optoelectronic properties, including higher electron mobility and wider bandgaps compared to elemental silicon. Their primary purpose is to enable the fabrication of devices that operate at higher frequencies, temperatures, and power levels. While Gallium Arsenide (GaAs) remains vital for RF amplifiers in telecommunications, Silicon Carbide (SiC) and Gallium Nitride (GaN) represent the fastest-growing product segments, driven by demand for advanced power devices.
Regulatory frameworks profoundly shape material selection and device design. The EU's RoHS directive restricts the use of certain hazardous materials, influencing substrate composition. In the United States, EPA standards for energy efficiency in electronics push manufacturers toward more efficient materials like GaN and SiC. Concurrently, Japan's METI actively promotes the development of next-generation power electronics. Navigating the distinct performance-cost tradeoffs between automotive and consumer electronics applications remains a central strategic challenge for material suppliers.
Market Dynamics
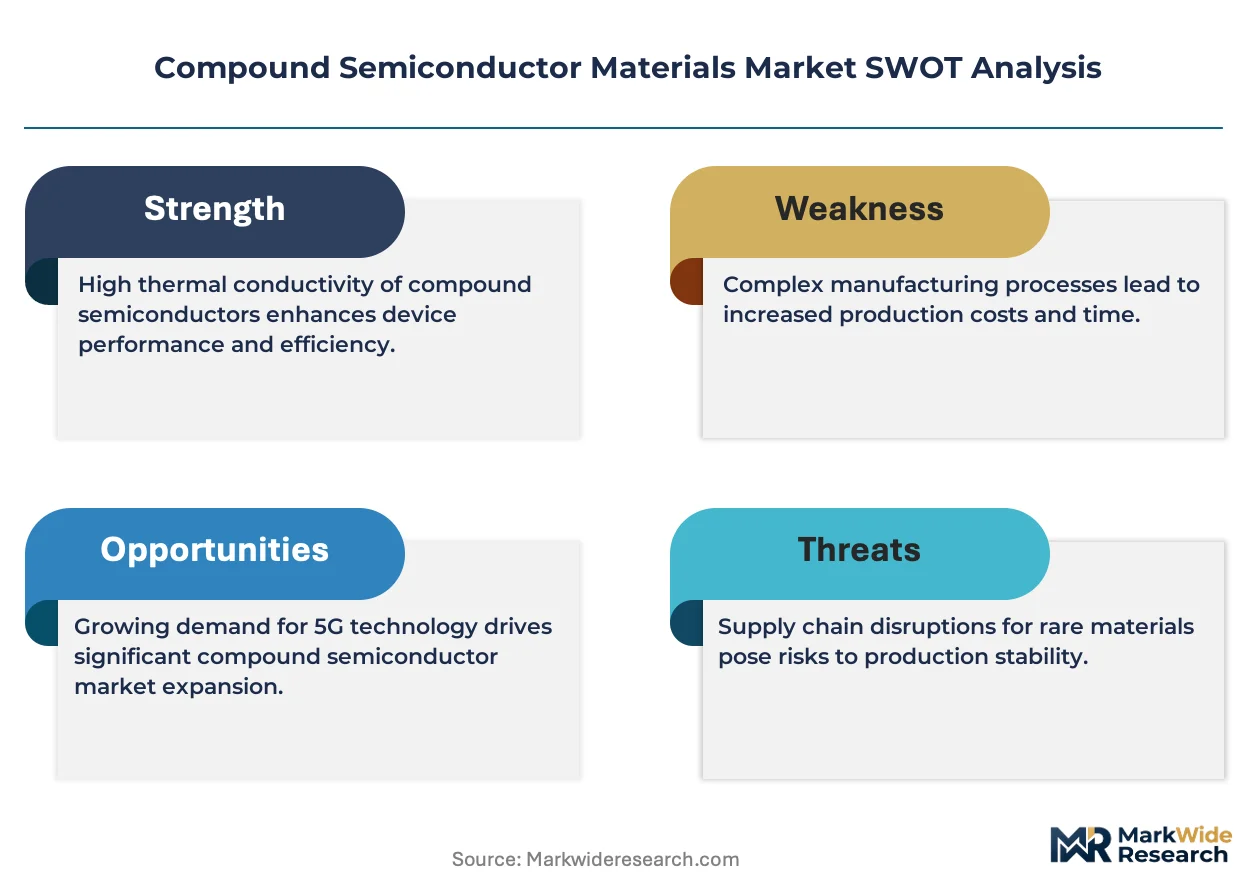
The market's primary tension lies between escalating performance demands from electric vehicle and 5G sectors and the inherent manufacturing complexities of wide-bandgap materials like SiC and GaN. This dynamic governs investment in substrate production and epitaxy.
Growth Catalysts
- Electric Vehicle Adoption:The global automotive industry's transition to electric vehicles creates immense demand for SiC-based power modules for inverters, on-board chargers, and DC-DC converters, prized for their efficiency and thermal management.
- 5G Infrastructure Rollout:Deployment of 5G networks requires a massive build-out of base stations and active antenna systems, which depend on the high-frequency performance of GaAs and GaN RF devices.
- Government Energy Mandates:The EU Green Deal and similar initiatives in other regions promote energy efficiency, accelerating the replacement of silicon with more efficient compound semiconductors in power supplies, solar inverters, and industrial motors.
Market Restraints
- High Substrate Cost:The high price of large-diameter, high-quality SiC and GaN-on-SiC wafers remains a significant barrier to wider adoption, particularly in cost-sensitive consumer electronics and lighting applications.
- Epitaxy Process Complexity:Achieving uniform, low-defect epitaxial layers on compound semiconductor substrates is technically challenging and requires significant process expertise, limiting the pool of high-quality epi-wafer suppliers.
- Supply Chain Concentration:The supply of critical raw materials, such as high-purity gallium and specialty gases, is concentrated in a few geographic regions, creating vulnerability to geopolitical tensions and logistical disruptions for manufacturers.
Strategic Opportunities
- Ultra-Wide Bandgap Materials:Research into next-generation materials like gallium oxide (Ga2O3) and aluminum nitride (AlN) presents opportunities for devices operating at even higher voltages and efficiencies, targeting grid-scale power electronics and deep-UV applications.
- Power Grid Modernization:National initiatives in countries like India and the United States to upgrade aging electrical grids offer a substantial long-term market for SiC-based solid-state transformers and high-voltage DC transmission systems.
- Advanced Photonic Devices:The expansion of data centers and optical communications creates opportunities for indium phosphide (InP) and other compound semiconductors in high-speed lasers, modulators, and detectors for photonic integrated circuits.
Industry Challenges
- Specialized Talent Scarcity:A shortage of engineers and technicians with expertise in compound semiconductor physics, crystal growth, and device fabrication processes limits the industry's ability to scale production and innovate rapidly.
- Device Reliability and Qualification:Establishing long-term reliability and standardized qualification testing for new SiC and GaN devices, especially for demanding automotive and industrial uses, is a time-consuming and costly process that can delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compound Semiconductor Materials Market |
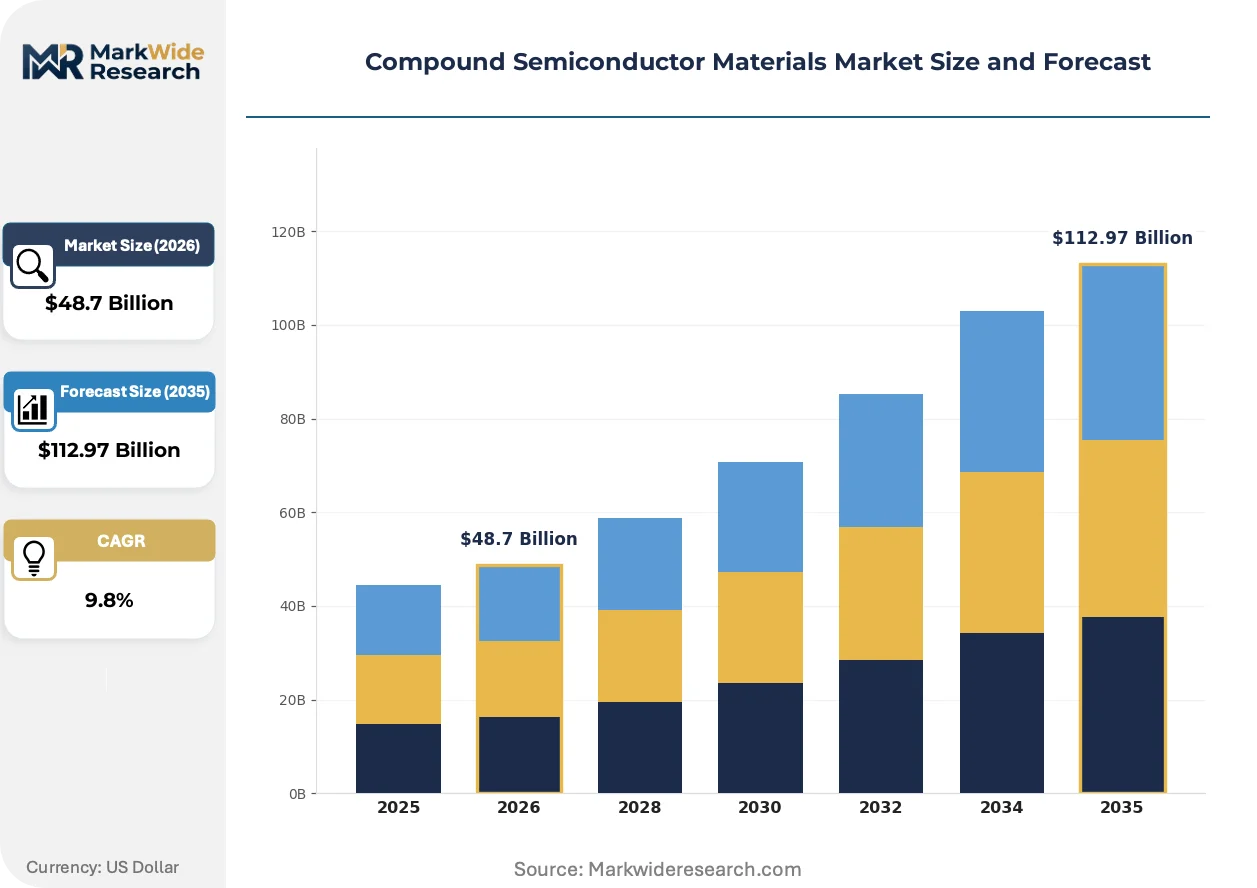
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $112.97 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GaN, InP, GaAs, SiC Application: Telecommunications, Consumer Electronics, Automotive, Defense End User: Electronics Manufacturers, Telecom Operators, Automotive OEMs, Research Institutions Technology: Laser Diodes, RF Amplifiers, Photonic Devices, Power Devices |
| Companies Covered | Sumitomo Electric Industries, Shin-Etsu Chemical, DowDuPont, Infineon Technologies AG, Texas Instruments Inc., Qorvo Inc., IQE Plc, AXT Inc., Freiberger Compound Materials GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compound Semiconductor Materials Market Strategic Shifts & Innovations
Material evolution is intersecting with new regulatory mandates and shifting OEM procurement strategies. This convergence is compelling substrate suppliers and device makers to re-evaluate process technologies and supply chain alignments to meet new performance and compliance benchmarks.
Advanced MOCVD (Metalorganic Chemical Vapor Deposition) systems are the core technology for growing the epitaxial layers that define compound semiconductor device performance. Leading fabs are rapidly adopting these systems to handle larger wafer sizes, from 150mm to 200mm, for SiC and GaN production. This transition towards larger wafers is automating the defect detection and process control feedback loop, which is critical for improving device yield and lowering per-chip costs.
China's "dual carbon" goals and MIIT directives are creating a powerful domestic pull for high-efficiency power semiconductors. This policy framework directly subsidizes and prioritizes the development of a local SiC and GaN supply chain, from substrate to device. The most affected segments are electric vehicle manufacturing and renewable energy infrastructure, where domestic champions are mandated to increase their use of locally sourced power electronics.
Automotive OEMs are moving away from purchasing discrete components and toward sourcing complete, pre-validated power module solutions. This shift disrupts the traditional component-level sales channel, favoring device manufacturers who can offer integrated systems combining the driver, power switch, and passive components. The trend is most visible in the electric vehicle sector, where speed-to-market and system-level reliability are paramount design considerations.
Compound Semiconductor Materials Market Segmentation
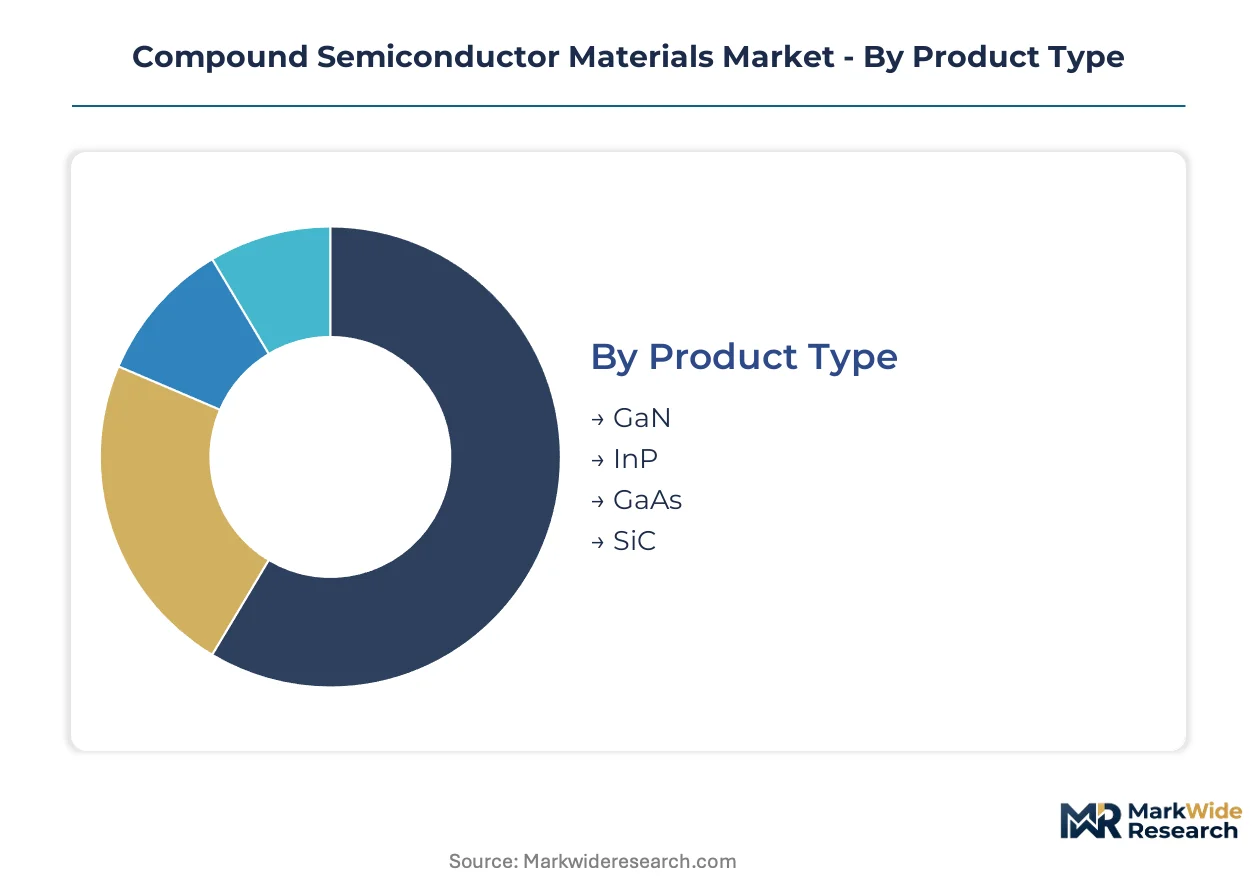
Segmentation within the compound semiconductor materials market clarifies how diverse material properties align with specific performance requirements across various industries. This market necessitates a precise material-to-application matching process due to the specialized nature of high-frequency, high-power, and optoelectronic device functionalities.
Product Type:
Product types in the compound semiconductor market often delineate between materials primarily used as standalone devices and those integrated into complex systems, reflecting varied manufacturing and application complexities.
- SiC:Silicon Carbide (SiC) is a wide-bandgap semiconductor offering superior thermal conductivity and breakdown voltage compared to elemental silicon. Demand concentrates in the automotive industry, driven by the need for efficient power modules in electric vehicle inverters and on-board chargers.
- GaN:Gallium Nitride (GaN) provides high electron mobility and power density, enabling compact, high-frequency device designs. The 5G infrastructure rollout fuels demand for GaN RF devices in base stations and active antenna systems.
- InP:Indium Phosphide (InP) materials are crucial for high-speed optical communications, enabling advanced photonic devices in data centers and fiber optic networks.
- GaAs:Gallium Arsenide (GaAs) remains essential for high-frequency RF applications in telecommunications and radar systems, prized for its high electron mobility.
GaAs leads volumes today; SiC is gaining share fastest.
Application:
Different applications impose distinct volume and performance requirements on compound semiconductor materials, influencing material selection and device design priorities.
- Automotive:The automotive sector utilizes compound semiconductors for power electronics in electric vehicles, including inverters, on-board chargers, and DC-DC converters. This demand is driven by the efficiency and thermal management advantages of SiC and GaN in harsh operating environments.
- Telecommunications:Telecommunications relies on these materials for high-frequency RF components in 5G infrastructure and optical transceivers for data transmission. GaAs and GaN devices are critical for signal amplification and high-speed data processing in these networks.
- Consumer Electronics:Consumer electronics applications leverage compound semiconductors for efficiency gains in power adapters, wireless charging, and compact RF modules in smartphones.
- Defense:The defense sector employs compound semiconductors for high-power radar systems, electronic warfare, and satellite communications due to their robust performance in extreme conditions.
Automotive applications demonstrate significant growth, while telecommunications maintains a mature but evolving demand profile.
End User:
End users in this market vary significantly in their direct procurement capabilities and their focus on either mass production integration or fundamental research and development.
- Automotive OEMs:Automotive Original Equipment Manufacturers directly integrate compound semiconductor-based power modules into their electric vehicles, driving demand for high-reliability and AEC-Q qualified components. Their procurement strategies prioritize system-level solutions and long-term supply agreements.
- Electronics Manufacturers:Electronics manufacturers incorporate compound semiconductors into a wide array of products, from consumer devices to industrial power supplies. They seek materials that offer performance advantages for miniaturization, energy efficiency, and high-frequency operation.
- Telecom Operators:Telecom operators deploy compound semiconductor-enabled equipment for network infrastructure, demanding robust and efficient RF devices for 5G base stations.
- Research Institutions:Research institutions explore novel compound semiconductor materials and device architectures, contributing to future technological advancements and new application development.
Automotive OEMs exert substantial influence on long-term supply chain planning due to their stringent qualification processes.
Technology:
Each technology segment highlights a specific functional capability, driving the selection of compound semiconductor materials best suited for those performance characteristics.
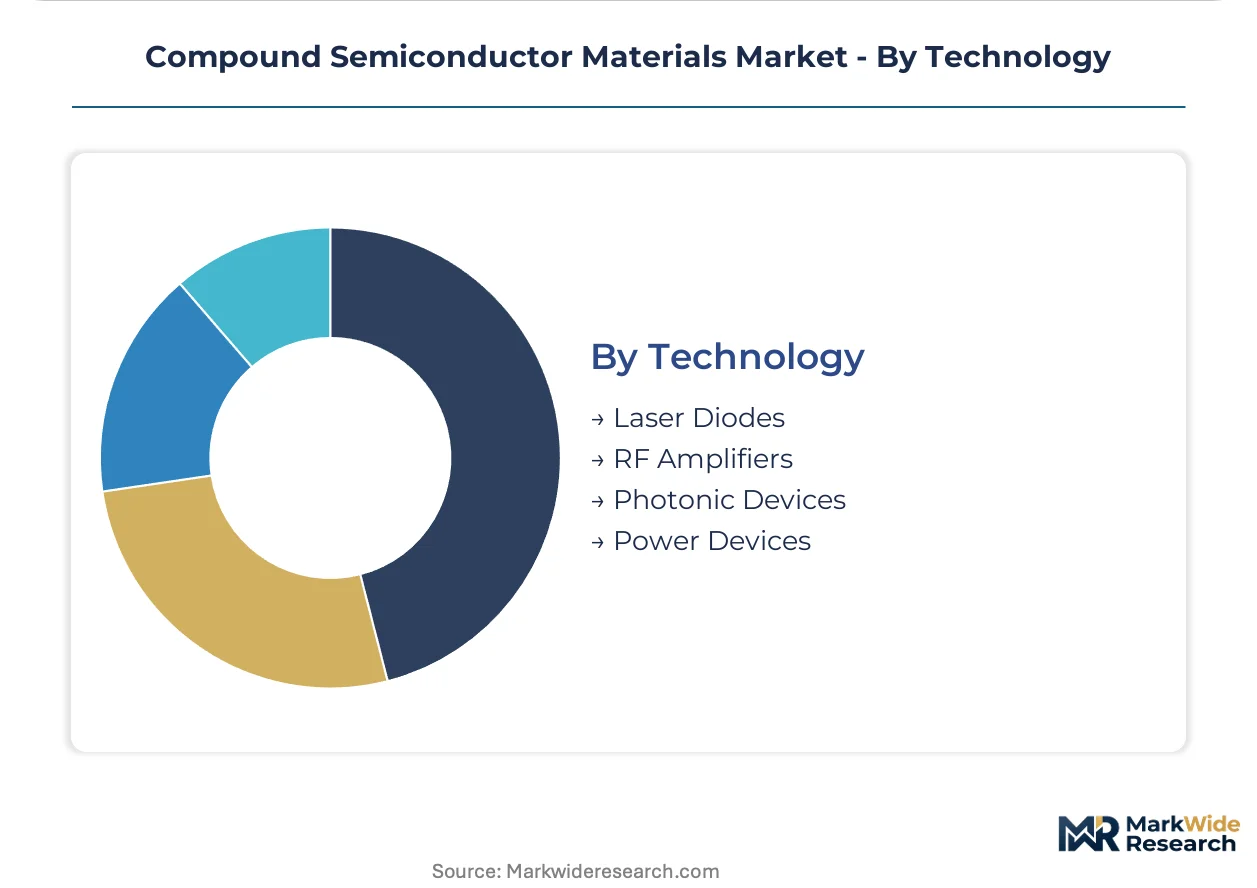
- Power Devices:Power devices, primarily built with SiC and GaN, manage and convert electrical energy with high efficiency and thermal stability. Their demand is escalating in electric vehicles and renewable energy systems due to superior voltage handling and switching speeds.
- RF Amplifiers:RF amplifiers, often using GaAs and GaN, boost radio frequency signals for wireless communication and radar systems. They are critical for 5G base stations and satellite communications, where high linearity and power output are essential.
- Laser Diodes:Laser diodes, frequently based on GaAs and InP, generate coherent light for optical communications, data storage, and sensing applications.
- Photonic Devices:Photonic devices, including modulators and detectors, leverage InP and other compound semiconductors for high-speed data transmission in fiber optic networks and data centers.
Innovation in power devices is rapidly commercializing, while photonic devices see continuous advancements for data infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The compound semiconductor industry initially scaled in regions with advanced electronics manufacturing capabilities, particularly in Asia and North America. These areas developed the foundational expertise for complex material synthesis and device fabrication. Today, diverse global policies and market demands shape regional growth trajectories for these high-performance materials.
United States
The United States drives demand for compound semiconductors in defense applications and high-performance computing, particularly for advanced radar systems. EPA standards for energy efficiency strongly influence material selection, favoring GaN and SiC in power electronics. Silicon Valley continues to foster significant innovation in advanced device design and integration, attracting substantial R&D investment.
China
China's rapid electric vehicle adoption and 5G infrastructure rollout create immense demand for SiC and GaN materials. The nation's dual carbon goals and MIIT directives actively promote a local supply chain for power semiconductors. The Yangtze River Delta region is a significant hub for SiC and GaN production, supported by government subsidies.
Japan
Japan maintains robust demand for compound semiconductors in automotive power electronics and high-speed optical communications. METI actively promotes the development of next-generation power electronics, fostering domestic innovation. Kyushu island maintains strong semiconductor manufacturing capabilities, contributing to global substrate supply.
Germany
Germany's automotive industry and industrial sector demand high-performance compound semiconductor modules. The EU Green Deal influences material selection, accelerating the shift away from traditional silicon. Dresden is a key center for semiconductor research and manufacturing, attracting significant investment in advanced fabs.
Taiwan
Taiwan's established semiconductor fabrication and packaging industry drives significant demand for compound materials. Local industrial policies consistently support the growth of its sophisticated semiconductor ecosystem. Hsinchu Science Park remains a global center for advanced chip production, specializing in foundry services.
Compound Semiconductor Materials Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the compound semiconductor value chain. The industry structure is characterized by a blend of highly specialized material suppliers and integrated device manufacturers. Strategic archetypes include foundational substrate providers, advanced epi-wafer specialists, and comprehensive power device solution providers. Dominant competitive moves involve significant investments in capacity expansion and strategic partnerships to secure critical supply chain nodes.
Within the specialized material segment, Japan-based Sumitomo Electric Industries exemplifies a diversified materials science provider, leveraging its extensive material science portfolio to supply critical substrates for high-efficiency applications. Germany-headquartered Infineon Technologies AG represents a leading power device solution provider, focusing on advanced solutions for automotive and industrial markets, particularly for electric vehicle power electronics. UK-based IQE Plc anchors the specialized epitaxial wafer segment, maintaining a dominant market position for these critical upstream components required by many device manufacturers globally for their high-frequency and power devices.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| Shin-Etsu Chemical |
| DowDuPont |
| Infineon Technologies AG |
| Texas Instruments Inc. |
| Qorvo Inc. |
| IQE Plc |
| AXT Inc. |
| Freiberger Compound Materials GmbH |
| Others |
Cost & Logistics Intelligence
The performance-cost tradeoff between wide-bandgap materials and mature compound semiconductors creates a distinct market bifurcation. This divergence shapes both pricing power for specialized substrates and the fragmented supply chain for upstream raw materials.
Pricing Analysis
Long-term contract pricing dominates for high-performance SiC and GaN materials, reflecting significant upfront investments in capacity. Price differentiation stems from substrate quality, AEC-Q certification for automotive applications, and volume scale. Pricing pressure originates from the high cost of large-diameter, low-defect wafers and specialized raw material sourcing. Consumer electronics manufacturers exhibit high price sensitivity, contrasting with the lower sensitivity seen in defense and automotive sectors.
Supply Chain Analysis
The absence of significant material recovery or remanufacturing flows for compound semiconductors underscores their linear supply chain. Geographic supply concentrates in Taiwan for fabrication, with China emerging as a SiC and GaN production hub, and Japan providing specialized substrates. Raw material dependencies include high-purity gallium and specialty gases. This concentration creates vulnerability to geopolitical tensions and logistical disruptions, with distribution typically running direct from material suppliers to device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with policy mandates accelerating demand for high-efficiency materials. The EU Green Deal, emphasizing energy efficiency, specifically drives the transition from silicon to compound semiconductors.
For Market Incumbents:Deepen vertical integration into advanced epi-wafer production to mitigate supply chain risks and control quality. Incumbents should strategically invest in larger wafer diameter manufacturing to lower per-chip costs, defending against emerging cost-competitive threats from new material technologies. Securing long-term supply agreements for critical raw materials like gallium is essential to buffer against geopolitical volatility.
For New Entrants and Emerging Players:Specialized design houses represent an entry point for new material solutions, offering integration expertise to device manufacturers. New entrants should target ultra-wide bandgap materials like gallium oxide for grid-scale power electronics, where performance gains justify development costs. Focusing on China's subsidized domestic supply chain for SiC and GaN offers a penetrable geographic segment. Partnerships with automotive OEMs for pre-validated power module solutions provide a direct go-to-market angle.
For Investors and Strategic Acquirers:Consolidation pressure builds where manufacturing complexity and capital intensity create high barriers to entry for advanced material production. The long-term viability of compound semiconductors is secured by their foundational role in global energy transition and digital infrastructure. Investors should seek specialized epi-wafer suppliers or next-generation material startups with proprietary growth technologies. Increased M&A activity in substrate manufacturing signals market maturation and strategic positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for SiC Wafers | Addresses growing automotive demand and lowers production costs. |
| R&D in Gallium Oxide Materials | Unlocks higher voltage and efficiency for grid-scale power. |
| Strategic Partnership with Automotive OEMs | Secures long-term demand and accelerates device qualification. |
| Acquisition of Epi-Wafer Specialist | Strengthens upstream supply control and technological edge. |
| Investment in Advanced MOCVD Systems | Enhances manufacturing precision and supports larger wafer sizes. |
Research Approach
Coverage spans the United States, China, Japan, Germany, and Taiwan, with primary inputs from each region. This involved interviews with material scientists, device fabrication engineers, and automotive OEM procurement leads. Secondary data sources included company annual reports, government energy policy documents, and patent databases. A rigorous bottom-up and top-down triangulation approach validated market sizing and growth projections.
Market granularity was modeled across product types, key applications, end-user segments, and technology specificities, including wafer diameter. The analytical framework used historical trends and projected growth drivers to derive Compound Annual Growth Rates throughout the forecast period. Key forecast inputs included electric vehicle production forecasts and 5G infrastructure deployment plans. This ensured a comprehensive view of market evolution over the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts and raw material price volatility. Projections reflect current assumptions about technological development and market adoption. Practitioners should monitor new regulatory mandates and major capacity announcements for early signals of market shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
Indium Market
Semiconductor Material
Indium Gallium Zinc Oxide Market
Semiconductor Material
Silicon Hydride Market
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Yttrium Market
Semiconductor Material
Barium Titanate Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Semiconductor Materials Market
Semiconductor Material
Electronic Thermal Management Materials Market
Semiconductor Material
Global Gallium Nitride Market
Semiconductor Material
Neodymium Sputtering Target Market