
 Photoresist Stripper Market | 2026-2036
Photoresist Stripper Market Size, Share, and Industry Trends Forecast 2026-2036
Photoresist Stripper Market Analytics
Specialty chemical distribution through integrated fab-supply partnerships is rewriting procurement patterns for photoresist strippers. Tokyo Ohka Kogyo leverages its captive position in Japanese semiconductor supply chains to sustain premium placement for solvent-based formulations. DuPont de Nemours anchors North American supply through its advanced materials division, while Entegris competes on contamination control expertise that extends into chemical delivery systems.
Photoresist stripper denotes a formulated chemical blend, typically comprising amines, glycol ethers, or polar solvents at controlled pH and temperature thresholds, engineered to dissolve and lift photoresist residues from patterned wafers and substrates without attacking underlying metal or dielectric films. Aqueous strippers now dominate volume shipments for backend packaging applications where environmental discharge rules have tightened, while plasma strippers occupy the highest-margin tier at sub-7nm logic nodes where liquid chemistries risk pattern collapse. Solvent strippers retain structural importance in legacy analog and power semiconductor fabs where capital retrofit costs deter technology migration.
EPA enforcement of effluent guidelines for semiconductor fabrication facilities shapes formulation choices in the United States, while REACH registration requirements and the EU F-Gas Regulation constrain halogenated and high-VOC stripper chemistries across European wafer fabs. Japan's METI chemical management framework and South Korea's K-REACH parallel restrictions are forcing reformulation investments by suppliers serving Samsung and SK Hynix. Stakeholders must monitor regulatory divergence between East Asian export hubs and European import standards, as compliance misalignment threatens to fragment product portfolios and inflate qualification timelines for next-generation stripping chemistries.
Market Dynamics
Advanced node migration below 5nm is fragmenting photoresist stripper demand into highly specialized chemistries, as plasma-based stripping displaces solvent formulations at leading-edge logic fabs while legacy analog facilities resist capital-intensive retooling.
Growth Catalysts
- Sub-7nm logic ramp:Taiwan Semiconductor Manufacturing and Samsung Foundry are qualifying next-generation stripping chemistries for 3nm and 2nm production lines, creating pull-through for ultra-low-residue formulations.
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is accelerating investment in aqueous and bio-based alternatives across German and French wafer fabrication facilities.
- Advanced packaging proliferation:Fan-out wafer-level packaging and 3D-IC stacking are expanding addressable volume for backend-compatible strippers that process multiple redistribution layers.
Market Restraints
- Raw material concentration:N-methyl-2-pyrrolidone supply chains concentrate in Chinese petrochemical complexes, exposing formulators to feedstock disruption and tariff volatility.
- Technical ceiling at atomic scale:Liquid chemistries face fundamental limitations in residue removal at sub-3nm feature sizes without attacking fragile porous low-k dielectrics.
- REACH registration burden:The European Chemicals Agency's data requirements for new substance registrations extend qualification timelines by 18-24 months for novel stripping formulations.
Strategic Opportunities
- India semiconductor manufacturing:The country's PLI scheme for fabs and ATMP facilities is creating first-mover advantage for suppliers establishing local formulation and blending capacity.
- Carbon border adjustment alignment:The EU's CBAM mechanism rewards low-carbon stripping chemistry production, favoring European and renewable-powered Asian manufacturing sites.
- Equipment-chemistry integration:Single-wafer processing tools and point-of-use chemical delivery systems are converging, opening bundled service contracts that lock in multi-year stripper supply.
Industry Challenges
- Process engineer scarcity:The specialized knowledge required to optimize stripping chemistries for heterogeneous integration processes is concentrating at a handful of equipment suppliers and IDM research centers.
- Fab qualification protocols:Samsung and TSMC each maintain proprietary 12-18 month chemical validation cycles that fragment supplier development roadmaps and inflate R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photoresist Stripper Market |
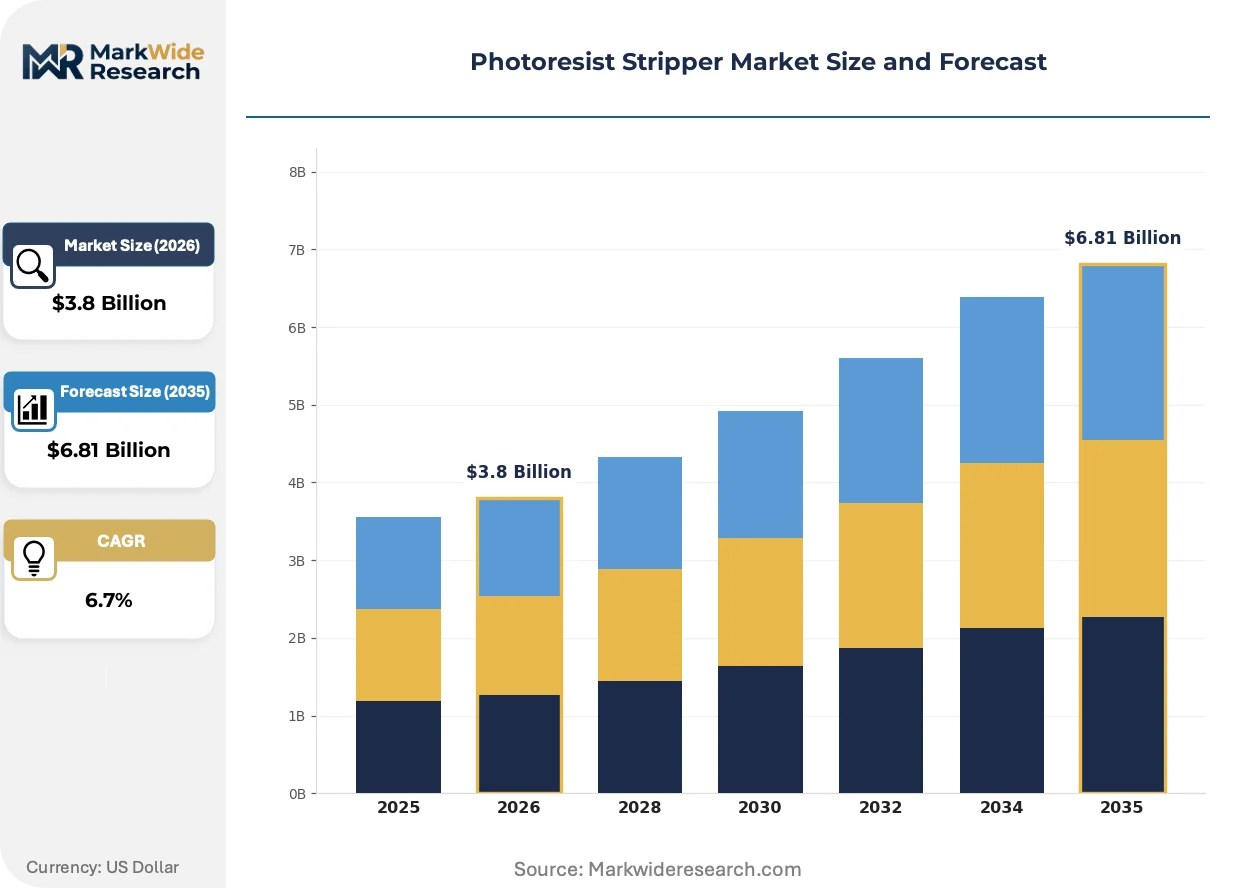
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Strippers, Solvent Strippers, Bio-based Strippers, Plasma Strippers Technology: Conventional, Eco-friendly, Advanced Chemical, Thermal End User: Semiconductor Manufacturers, Electronics Fabricators, Research Institutions, Aerospace Companies Application: PWB Manufacturing, Flat Panel Display, MEMS, Integrated Circuits |
| Companies Covered | Tokyo Ohka Kogyo Co., Ltd., Mitsubishi Gas Chemical, DuPont de Nemours Inc., Technic Inc., Avantor Inc., Entegris Inc., Fujifilm Corporation, Solexir, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photoresist Stripper Market Evolving Landscape
Formulation science is bifurcating between aqueous systems for environmental compliance and plasma-based methods for pattern fidelity, while equipment-chemistry bundling rewires procurement relationships.
Supercritical CO2-based stripping is virtualizing residue removal for photoresist and post-etch polymer cleaning in memory fabs, where SK Hynix and Micron are piloting systems that eliminate aqueous waste streams entirely. The technology compresses chemical consumption and water treatment infrastructure, redefining operating cost structures for high-volume NAND and DRAM production.
Japan's METI chemical management framework is tightening substance reporting thresholds for semiconductor process chemicals, forcing Tokyo Ohka Kogyo and domestic competitors to reformulate legacy amine-based strippers ahead of 2026 compliance deadlines. Memory manufacturers serving Japanese automotive chip customers are accelerating qualification of alternative chemistries to avoid supply interruption.
Integrated device manufacturers are consolidating chemical procurement through direct fab-supplier partnerships that displace traditional distributor networks, with contract terms now spanning five to seven years and incorporating joint development clauses for node-specific formulations. This concentration is most visible in South Korea, where Samsung's supplier reduction programs have halved qualified stripper vendors since 2020.
Photoresist Stripper Market Segmentation
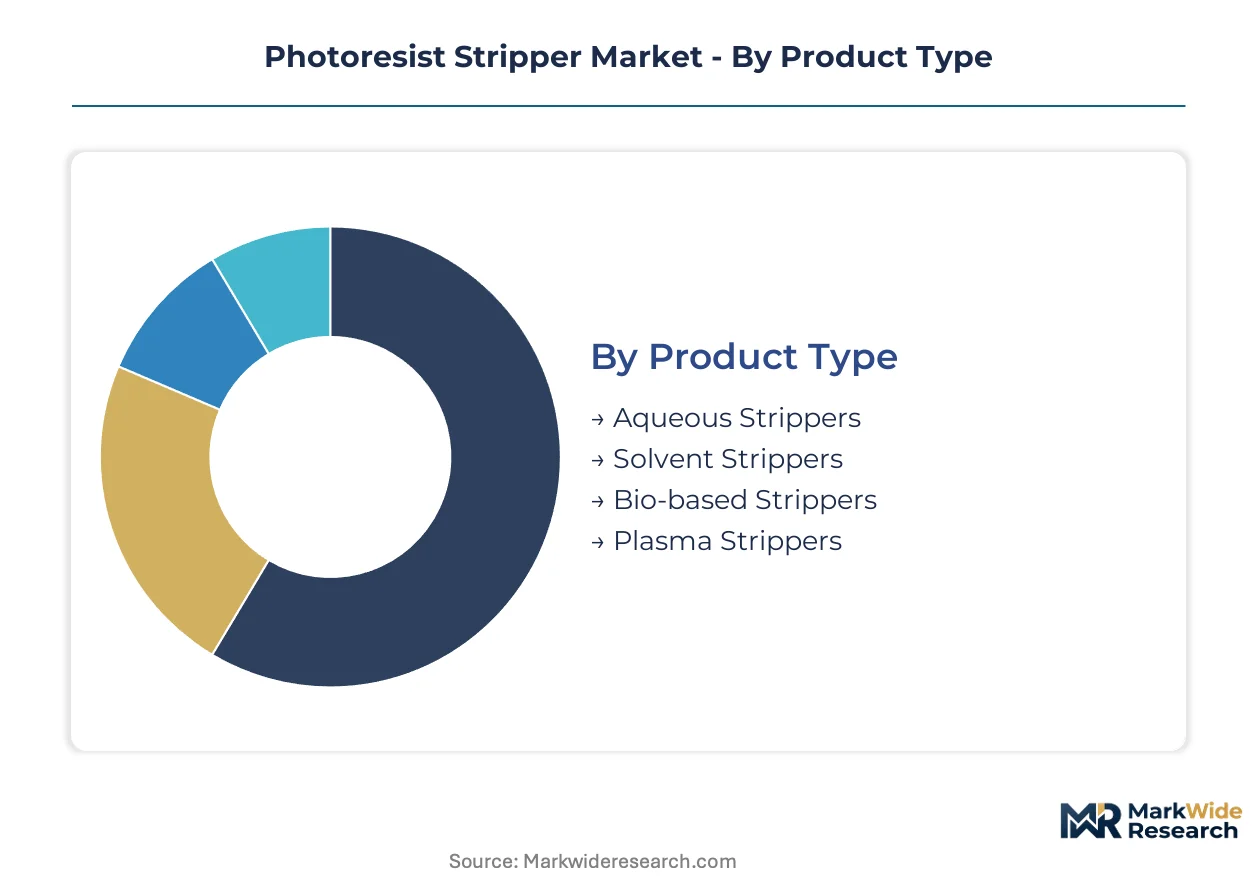
Photoresist stripper segmentation tracks how formulation chemistry, process technology, and end-use application intersect to determine qualification requirements, service intensity, and margin structures. Each dimension carries distinct procurement protocols and technical support demands that reshape supplier relationships across the value chain.
Product Type:
After-sales service intensity escalates with formulation complexity, as aqueous and bio-based systems demand continuous process optimization support while plasma strippers require equipment-chemistry integration expertise.
- Aqueous Strippers:Water-based formulations incorporating amines, glycol ethers, and corrosion inhibitors at controlled pH levels serve backend packaging and legacy node fabrication. Demand concentrates in European fabs where REACH and EU F-Gas Regulation enforcement has accelerated displacement of solvent alternatives; German wafer facilities now specify these systems for discharge compliance.
- Solvent Strippers:NMP-based and polar aprotic solvent blends retain dominance in analog and power semiconductor fabrication where capital retrofit costs deter migration. Taiwan and South Korean foundry clusters sustain volume for these formulations in mature node production, though supply chain exposure to Chinese NMP feedstock concentration creates procurement risk.
- Bio-based Strippers:Renewable-derived formulations using esters, terpenes, or bio-glycols target carbon footprint reduction mandates.
- Plasma Strippers:Gas-phase systems employing oxygen, fluorine, or hydrogen plasmas occupy the highest service tier at sub-7nm logic nodes.
Solvent strippers hold the largest share; momentum sits with aqueous alternatives.
Technology:
Technology tiers stratify by capital intensity and environmental compliance burden, with advanced chemical and thermal methods commanding premium positioning against conventional formulations.
- Conventional:Established solvent and aqueous chemistries deployed in high-volume manufacturing with minimal equipment modification. Electronics fabricators in mature industrial clusters rely on these systems for cost predictability.
- Eco-friendly:Low-VOC, biodegradable formulations engineered for regulatory alignment with Japan's METI chemical management framework and EU discharge standards. South Korean memory fabs are qualifying these systems ahead of K-REACH enforcement milestones.
- Advanced Chemical:Ultra-low-residue formulations with sub-ppm metal contamination specifications for leading-edge logic. Taiwan Semiconductor Manufacturing and Samsung Foundry mandate these chemistries for 3nm and 2nm production ramps.
- Thermal:Elevated-temperature stripping processes that reduce chemical consumption through kinetic acceleration.
Conventional technology dominates shipment volume; advanced chemical systems are climbing the fastest.
End User:
End-user segmentation reveals divergent procurement power, with semiconductor manufacturers consolidating suppliers through direct partnerships while research institutions fragment demand across small-batch orders.
- Semiconductor Manufacturers:Integrated device manufacturers and foundries operating captive fabs or contract manufacturing facilities. Samsung's supplier reduction programs have halved qualified stripper vendors since 2020, concentrating procurement through five-to-seven-year partnership contracts with joint development clauses.
- Electronics Fabricators:Printed circuit board and substrate manufacturers serving industrial, automotive, and consumer electronics. These customers prioritize formulation consistency and logistics reliability over technical co-development.
- Research Institutions:University cleanrooms and national laboratories evaluating next-generation chemistries for future node insertion.
- Aerospace Companies:Specialty semiconductor consumers with extreme reliability requirements and extended qualification cycles.
Semiconductor manufacturers command the greatest procurement leverage; research institutions are gaining share fastest as pilot line expansion accelerates.
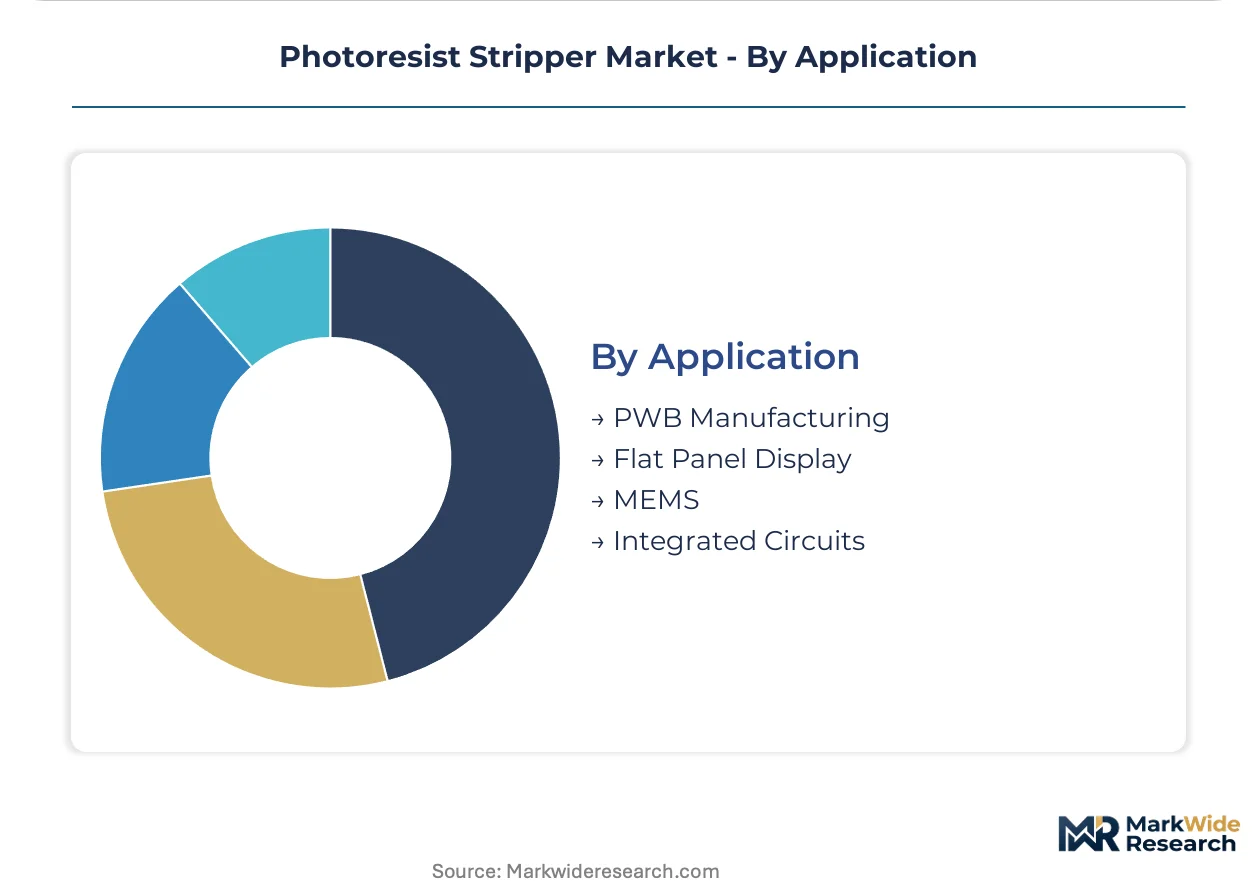
Application:
Application segmentation maps directly to device complexity and yield sensitivity, with integrated circuits and MEMS demanding the most specialized stripping protocols.
- PWB Manufacturing:Printed wiring board fabrication employs aqueous strippers for photoresist removal from copper laminates. Environmental discharge rules in German and French facilities have tightened specification requirements for these applications.
- Flat Panel Display:Large-area substrate processing for LCD and OLED manufacturing uses high-volume solvent systems. South Korean display clusters sustain demand despite gradual aqueous substitution in newer fabs.
- MEMS:Microelectromechanical systems require residue-free stripping that preserves fragile suspended structures and moving parts.
- Integrated Circuits:Logic and memory device fabrication spans the full technology spectrum from mature nodes to sub-3nm processes.
Integrated circuits represent the largest application segment; MEMS is expanding most quickly as heterogeneous integration proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in East Asian foundry clusters while European environmental compliance costs compress margins for formulators serving German and French wafer fabs.
Taiwan
TSMC's 3nm and 2nm ramp drives qualification of ultra-low-residue stripping chemistries at the Tainan Science Park. The island's Industrial Development Bureau enforces chemical substance reporting that tightens ahead of 2026 deadlines. Hsinchu Science Park facilities now specify advanced aqueous formulations for backend packaging lines.
South Korea
Samsung Foundry and SK Hynix expand DRAM and NAND capacity in Pyeongtaek and Icheon, pulling through specialized plasma stripping systems. K-REACH registration requirements extend qualification timelines for novel chemistries by 18-24 months. Yongin semiconductor clusters concentrate demand for equipment-integrated chemical delivery systems.
United States
Intel's Arizona and Ohio fab investments sustain volume for solvent-based strippers in mature node production. EPA effluent guidelines for semiconductor fabrication shape formulation choices in Arizona and Oregon facilities. Portland-area wafer fabs now prioritize aqueous alternatives to reduce water treatment infrastructure costs.
Germany
Infineon and Bosch semiconductor operations in Dresden and Reutlingen drive demand for REACH-compliant stripping chemistries. EU F-Gas Regulation phasedown accelerates investment in bio-based alternatives across Bavarian and Saxon wafer facilities. Dresden's Silicon Saxony cluster mandates low-VOC formulations for new fab construction.
Japan
Tokyo Electron and Shin-Etsu supply chain integration sustains captive demand for solvent strippers in analog and power semiconductor fabs. METI's chemical management framework forces reformulation of legacy amine-based systems ahead of 2026 compliance deadlines. Kyushu's Kumamoto semiconductor corridor accelerates qualification of alternative chemistries for automotive chip customers.
Photoresist Stripper Market Competitive Landscape
Integrated material suppliers and specialized chemical distributors split the market between captive fab partnerships and open distribution networks. Japanese and North American players anchor consolidated supply positions at leading-edge logic manufacturers. Three archetypes dominate: integrated material conglomerates with captive semiconductor chemical divisions, specialized electronic chemical formulators with deep fab relationships, and equipment-chemistry bundlers leveraging contamination control expertise. Competitive moves concentrate on multi-year partnership contracts with joint development clauses and geographic expansion into emerging fab clusters.
Within the integrated material tier, Tokyo Ohka Kogyo Co., Ltd. exemplifies the Japanese captive supply model, while DuPont de Nemours Inc. represents North American advanced materials positioning. Entegris Inc. occupies the equipment-chemistry integration archetype, bundling chemical delivery systems with formulation supply. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning across divergent procurement channels.
| Leading Market Players |
|---|
| Tokyo Ohka Kogyo Co., Ltd. |
| Mitsubishi Gas Chemical |
| DuPont de Nemours Inc. |
| Technic Inc. |
| Avantor Inc. |
| Entegris Inc. |
| Fujifilm Corporation |
| Solexir |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese NMP petrochemical complexes is compressing feedstock costs for solvent stripper formulators while simultaneously eroding pricing power for regional producers serving mature node fabs. This utilization asymmetry between raw material supply and finished formulation demand is forcing suppliers to absorb margin pressure or accelerate migration toward aqueous and plasma alternatives.
Pricing Analysis
Configured-to-order pricing for node-specific formulations commands a substantial premium over standard aqueous stripper catalogs. Three-tier pricing structure across premium, standard, and economy levels separates plasma-based systems for sub-7nm logic from advanced aqueous chemistries for packaging, with commodity solvent blends occupying the lowest rung. Price differentiation hinges on contamination specifications and joint development clauses. Cost compression in standard aqueous tiers is intensifying because Samsung and TSMC procurement consolidation has halved qualified vendor pools. Backend packaging fabricators exhibit the highest price sensitivity; leading-edge logic manufacturers prioritize residue performance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration among Taiwan Semiconductor Manufacturing, Samsung Foundry, and SK Hynix fabs anchors global formulation demand. Supply concentrates in Taiwan, South Korea, and Japan, with German and U.S. facilities serving regional captive demand. Raw material flows draw from Chinese NMP complexes, Japanese amine producers, and Korean glycol ether suppliers. Single-source vulnerability in Chinese petrochemical feedstock exposes formulators to tariff volatility and export licensing disruption. Distribution runs through direct fab-supplier partnerships that displace traditional distributor networks, with five-to-seven-year contracts now standard for qualified vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized process engineering talent for heterogeneous integration has concentrated at a handful of equipment suppliers and IDM research centers, creating a bottleneck that constrains formulation optimization velocity and extends qualification timelines for novel chemistries.
For Market Incumbents: Build captive equipment-chemistry integration moats by bundling single-wafer processing tools with point-of-use delivery systems. Deepen backward integration into amine and glycol ether supply to offset Chinese NMP concentration risk. Secure joint development clauses in Samsung and TSMC partnership contracts to lock out substitute plasma-based technologies. Prioritize certification investment for EU F-Gas Regulation and K-REACH compliance ahead of enforcement milestones. For New Entrants and Emerging Players: Pursue white-space positioning in India's PLI-driven fab and ATMP facility buildout, where first-mover formulation capacity yields multi-year procurement advantages. Target bio-based stripper segments serving European carbon border adjustment mechanisms, as incumbent reformulation lag creates penetration windows. Exploit equipment-chemistry bundling gaps among mid-tier memory fabs seeking to replicate Samsung's supplier reduction model. Lead with aqueous system qualifications for backend packaging lines where environmental discharge rules have tightened specification requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-chemistry bundlers with multi-year fab service contracts, positioning these archetypes for sustained cash flow quality across semiconductor capital cycles. Long-term viability favors suppliers with demonstrated qualification success at sub-7nm nodes and established joint development pipelines with Taiwan and South Korean foundries. Acquisition target archetype: specialized electronic chemical formulators with deep fab relationships and pending REACH or K-REACH approvals that unlock European and Korean addressable markets. Monitor TSMC and Samsung 2nm pilot line announcements as inflection indicators for next-generation stripping chemistry pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine Supply | Reduces exposure to Chinese NMP concentration and secures feedstock for aqueous formulation expansion. |
| Joint Development Partnership with Foundry | Locks in multi-year supply contracts at TSMC or Samsung for node-specific qualification pipelines. |
| Plasma Stripper Equipment Bundling | Captures highest-margin tier at sub-7nm logic nodes where liquid chemistries face technical ceilings. |
| India Local Formulation Capacity | Establishes first-mover position in PLI-driven fab clusters before incumbent supplier consolidation. |
| Bio-based Chemistry Certification | Aligns with EU F-Gas Regulation and carbon border adjustment rewards for low-carbon production. |
Research Methodology
A standing panel of fab process engineers, chemical procurement leads at IDMs, formulation R&D directors, and environmental compliance officers provided ongoing calibration across primary interview cycles. Semiconductor fabrication stakeholders contributed operational data on qualification timelines, residue specifications, and supplier consolidation patterns. Secondary validation drew from EPA effluent guideline filings, ECHA REACH registration databases, METI chemical management framework updates, and SEC disclosures from listed material suppliers. Bottom-up triangulation across wafer fab capacity expansion announcements and top-down cross-checks against foundry capital expenditure disclosures anchored volume estimates.
Scenario-bracketing around regulatory enforcement timing, node migration velocity, and feedstock tariff exposure bounded the projection range. Segmentation dimensions spanned formulation chemistry, process technology tier, end-use application, and regional fab cluster. CAGRs were derived from installed capacity growth rates, content-per-wafer assumptions for advanced nodes, and substitution elasticities between solvent, aqueous, and plasma systems. Industry-specific inputs included TSMC and Samsung disclosed node ramps, SK Hynix supercritical CO2 pilot expansion, and EU F-Gas Regulation phasedown schedules.
Sensitivities concentrate around K-REACH and REACH registration timeline slippage, Chinese NMP export restriction imposition, and plasma stripper technical feasibility at sub-3nm feature sizes. Forecasts reflect assumptions on fab utilization rates, joint development contract renewal rates, and environmental regulation enforcement intensity. Quarterly review of foundry equipment procurement announcements, chemical substance regulatory filings, and memory fab supercritical CO2 pilot results is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Stencil Lithography Market
Semiconductor Manufacturing
Chip Melting Furnace Market
Semiconductor Manufacturing
Semiconductor and Circuit Manufacturing Market
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
Photomask Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
United States Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market
Semiconductor Manufacturing
Surface Mount Technology (SMT) Market
Semiconductor Manufacturing
Global Wafer Cutting Fluids Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
Semiconductor Polishing Pads Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
Medical Component Manufacturing Market
Semiconductor Manufacturing
Silicon Wafer Reclaim Market