
 Global High-Performance Computing (HPC) Market | 2026-2036
Global High-Performance Computing (HPC) Market Size, Share, and Industry Trends Forecast 2026-2036
Global High-Performance Computing (HPC) Market Foresight
Buyer concentration among government agencies and hyperscale research institutes is recalibrating procurement dynamics across the HPC landscape. NVIDIA leverages its dominance in GPU-accelerated architectures to anchor premium supply relationships with national laboratories. Cray (HPE) sustains its position through deep vertical integration from interconnects to liquid cooling systems. IBM competes via specialized quantum-HPC hybrid platforms targeting financial services clients.
High-Performance Computing encompasses clustered and massively parallel systems operating at petaflop-scale throughput, typically deploying thousands of x86 or accelerator cores with high-bandwidth memory subsystems and low-latency InfiniBand or custom interconnect fabrics for complex simulation, modeling, and analytics workloads. The supercomputers segment occupies the highest capital allocation tier, while cloud HPC is expanding fastest as energy sector and financial services buyers shift capital expenditure to operational expenditure models. Accelerators command disproportionate margin pools due to silicon scarcity and foundry capacity constraints.
The EU AI Act, REACH substance restrictions on cooling fluids, and ISO 50001 energy management standards are collectively tightening compliance thresholds for system deployments across European research infrastructure. The EPA's ENERGY STAR specifications and emerging FERC grid-interconnection rules are shaping datacenter power planning for U.S. national laboratory expansions. Stakeholders must monitor evolving carbon accounting frameworks and export control classifications for advanced accelerators to anticipate procurement eligibility shifts.

Market Dynamics
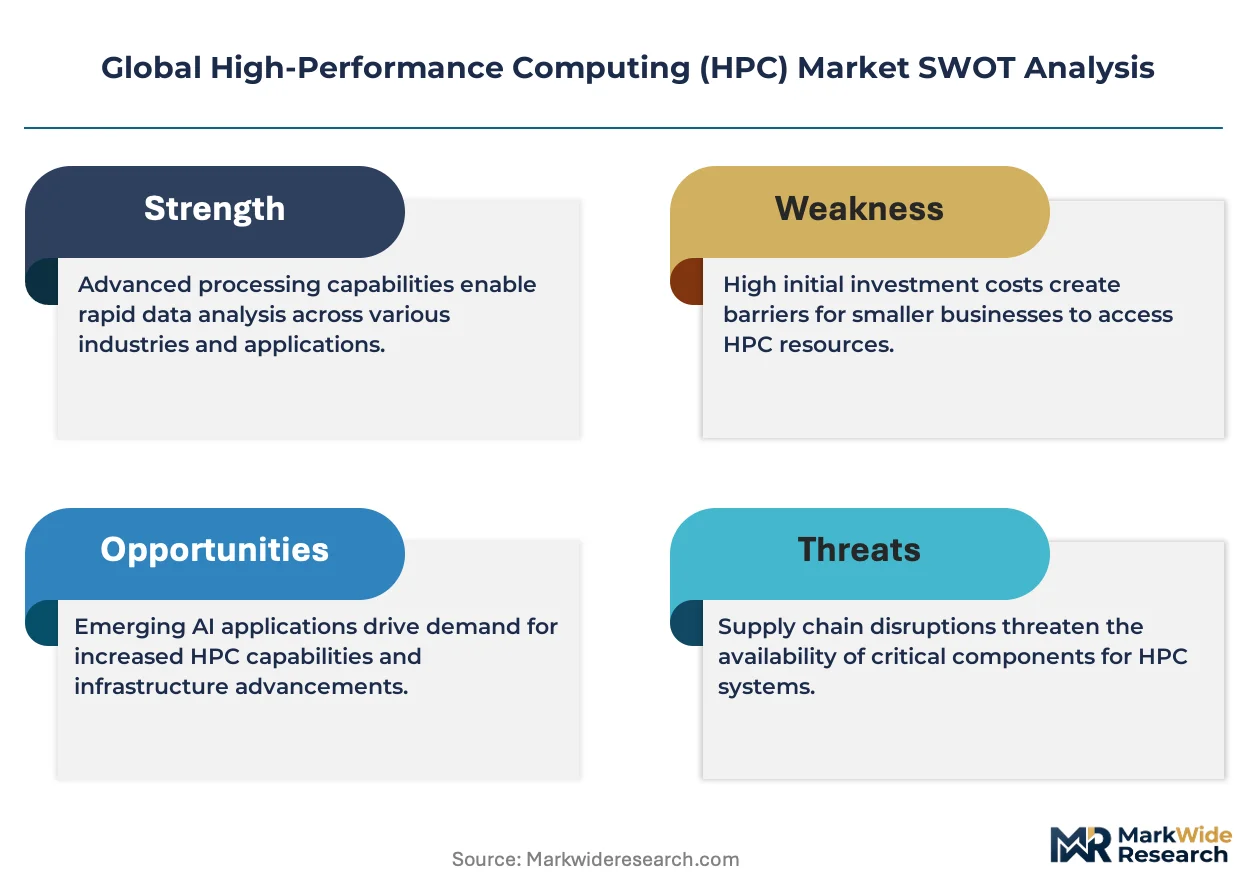
Accelerator silicon scarcity is concentrating procurement power among national laboratories and hyperscale research institutes, forcing system vendors into multi-year supply commitments and reshaping competitive positioning across the entire HPC value chain.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for high-stakes computational workloads are accelerating refresh cycles among European genomics institutes and automotive simulation centers.
- Cloud HPC adoption in energy sector:Oil and gas majors are shifting capital expenditure to operational expenditure models, expanding addressable market for hosted supercomputing services.
- Munich-Stuttgart industrial corridor concentration:Germany's automotive and aerospace research clusters are consolidating procurement budgets into fewer, larger system deployments.
Market Restraints
- TSMC foundry capacity allocation:Accelerator GPU wafer starts face 18-24 month queues, capping shipment volumes regardless of downstream demand.
- REACH substance restrictions on cooling fluids:Per- and polyfluoroalkyl substance limitations are disqualifying legacy liquid cooling chemistries from new European installations.
- Power density physics ceiling:Rack-level thermal design power exceeding 100 kilowatts is constraining air-cooled architectures without facility-level infrastructure rebuilds.
Strategic Opportunities
- India's semiconductor PLI scheme:Domestic assembly incentives are creating localized system integration capacity for South Asian research and defense buyers.
- Quantum-HPC hybrid convergence:Financial services risk modeling applications are opening premium pricing tiers for specialized accelerator-photonic interconnect platforms.
- ISO 50001 energy management certification:Mandatory efficiency auditing for publicly funded datacenters is creating retrofit service revenue streams.
Industry Challenges
- InfiniBand and CXL protocol integration complexity:Memory-coherent interconnect standardization gaps are extending system validation timelines by 6-9 months.
- Computational fluid dynamics and cryogenic engineering skill scarcity:Liquid cooling subsystem design expertise concentrates among aging specialist workforces in the United States and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High-Performance Computing (HPC) Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Supercomputers, Clusters, Workstations, Servers, Accelerators Technology: Distributed Computing, Parallel Processing, Quantum Computing, Cloud HPC, Grid Computing Application: Scientific Research, Weather Forecasting, Oil & Gas Exploration, Financial Modeling, Artificial Intelligence End User: Research Institutes, Energy Sector, Financial Services, Government Agencies, Academic Institutions |
| Companies Covered | NVIDIA, Cray (HPE), Hewlett Packard Enterprise, Supermicro, Fujitsu, IBM, Lenovo, Penguin Solutions, Dell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High-Performance Computing (HPC) Market Shifts & Advancements
Computational workloads are fragmenting across edge-to-core hierarchies, with artificial intelligence training pipelines and physics simulation codes demanding divergent hardware architectures from the same supplier base.
Disaggregated memory pooling via Compute Express Link is decentralizing traditional monolithic server architectures into composable resource fabrics. National laboratories in the United States and Japan are piloting chassis-less blade configurations that allocate DRAM and accelerator pools dynamically across workload queues. This topology is compressing hardware stranding ratios and extending usable system lifecycles beyond conventional five-year refresh windows.
REACH substance restrictions on fluorinated greenhouse gases are tightening deployment eligibility for two-phase immersion cooling systems across European research infrastructure. ECHA's 2024 amendment proposals are accelerating substitution toward single-phase dielectric fluids and direct-to-chip cold plate designs. German and French national computing centers are front-loading capital budgets to secure qualified cooling subsystem inventory ahead of anticipated 2026 phase-out deadlines.
Energy sector buyers are unbundling traditional hardware-plus-support contracts into separate infrastructure and managed service agreements. Independent software vendors and specialized HPC consultancies are capturing margin pools previously retained by original equipment manufacturers. This pattern is most visible in Norwegian and United Kingdom offshore wind simulation markets, where engineering firms now procure raw compute capacity through intermediaries rather than direct system ownership.
Global High-Performance Computing (HPC) Market Segmentation
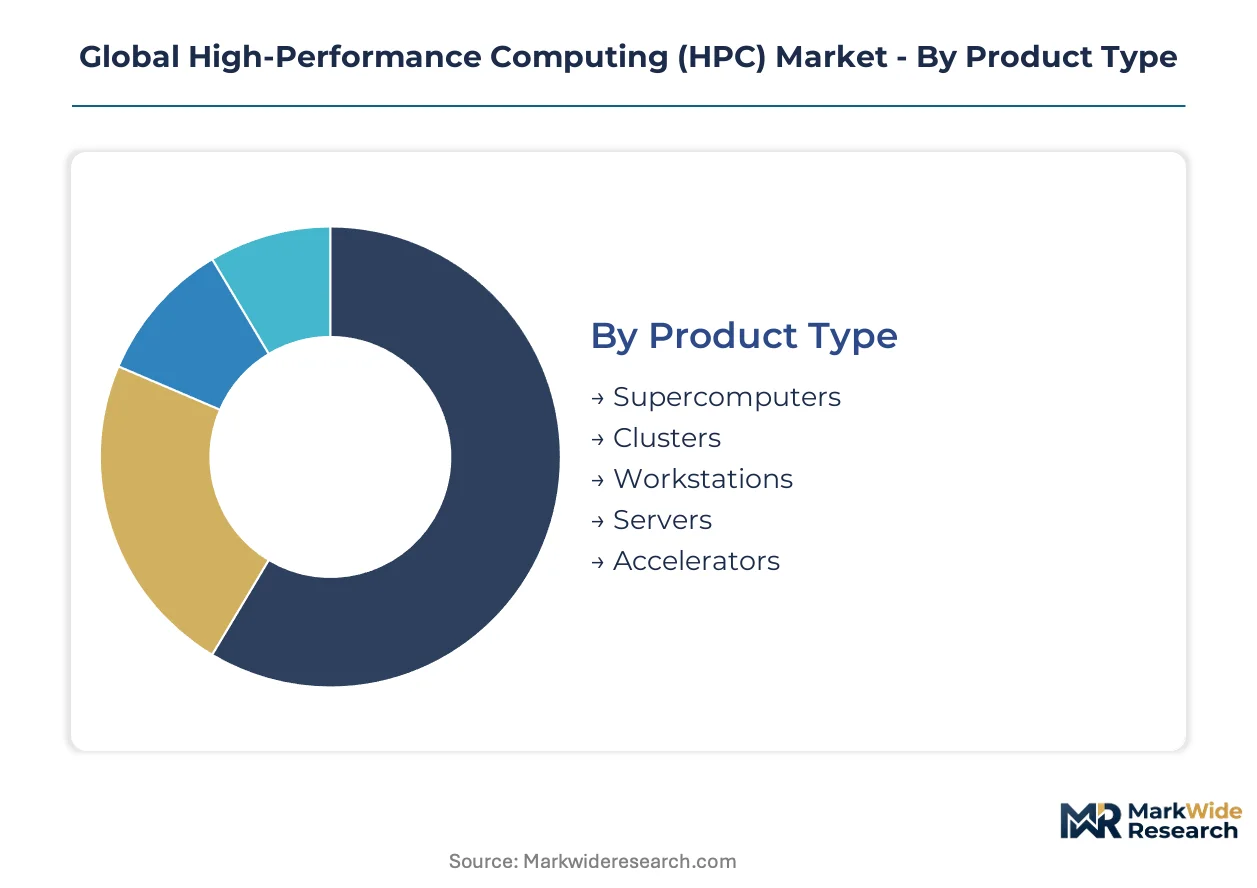
HPC procurement patterns diverge sharply across deployment scales, with national laboratories demanding integrated supercomputer systems while commercial buyers fragment into specialized accelerators and cloud-hosted clusters. Understanding these segment boundaries clarifies where silicon scarcity, cooling constraints, and regulatory compliance reshape vendor priorities.
Product Type:
Capital allocation intensity separates buyers into distinct procurement tiers, with rack-level thermal design power and interconnect bandwidth requirements driving vendor selection criteria.
- Supercomputers:Massively parallel architectures exceeding petaflop throughput integrate thousands of accelerator cores with custom interconnect fabrics. National laboratories in the United States and Japan anchor demand, constrained by TSMC foundry allocation queues and FERC grid-interconnection rules for power infrastructure.
- Accelerators:GPU and AI-optimized silicon modules command disproportionate margin pools due to wafer scarcity and memory-bandwidth engineering complexity. German automotive simulation centers and genomics institutes in the EU are expanding procurement budgets ahead of AI Act compliance deadlines.
- Clusters:Mid-scale distributed systems aggregate commodity servers for departmental research workloads.
- Workstations:Single-user compute nodes target engineering design and visualization applications.
- Servers:Rack-mounted general-purpose systems support mixed enterprise workloads without specialized acceleration.
Supercomputers lead on scale; accelerators lead on momentum.
Technology:
Workload characteristics determine architectural choices, with artificial intelligence training pipelines and physics simulation codes demanding divergent hardware-software integration approaches.
- Cloud HPC:Hosted supercomputing services convert capital expenditure to operational expenditure models for energy sector and financial services buyers. Norwegian offshore wind engineering firms and United Kingdom simulation consultancies are unbundling traditional hardware contracts into managed service agreements.
- Parallel Processing:Symmetric multiprocessing architectures dominate weather forecasting and computational fluid dynamics workloads. India's semiconductor PLI scheme is creating localized system integration capacity for defense and research buyers requiring sovereign compute infrastructure.
- Distributed Computing:Geographically dispersed resource aggregation supports collaborative scientific workflows.
- Grid Computing:Federated resource sharing protocols enable multi-institutional workload scheduling.
- Quantum Computing:Specialized quantum-HPC hybrid platforms target financial risk modeling with premium pricing tiers.
Cloud HPC expands most quickly; parallel processing retains the largest installed base.
Application:
End-use computational requirements vary by data intensity, algorithmic complexity, and regulatory sensitivity across vertical markets.
- Artificial Intelligence:Deep learning training and inference workloads drive accelerator procurement at genomics research institutes and automotive simulation centers. EU AI Act transparency mandates are accelerating refresh cycles among European buyers.
- Oil & Gas Exploration:Seismic processing and reservoir simulation demand high-memory-bandwidth architectures. Cloud HPC adoption is climbing fastest here as majors shift from owned infrastructure to hosted capacity.
- Scientific Research:Fundamental physics and materials modeling spans government-funded national laboratories.
- Weather Forecasting:Operational meteorological services require deterministic low-latency execution.
- Financial Modeling:Risk analytics and derivative pricing utilize quantum-HPC hybrid convergence for complex stochastic simulations.
Artificial intelligence leads on investment growth; scientific research maintains the deepest funding commitments.
End User:
Budget authority and compliance obligations concentrate procurement power among institutional buyers with multi-year capital planning horizons.
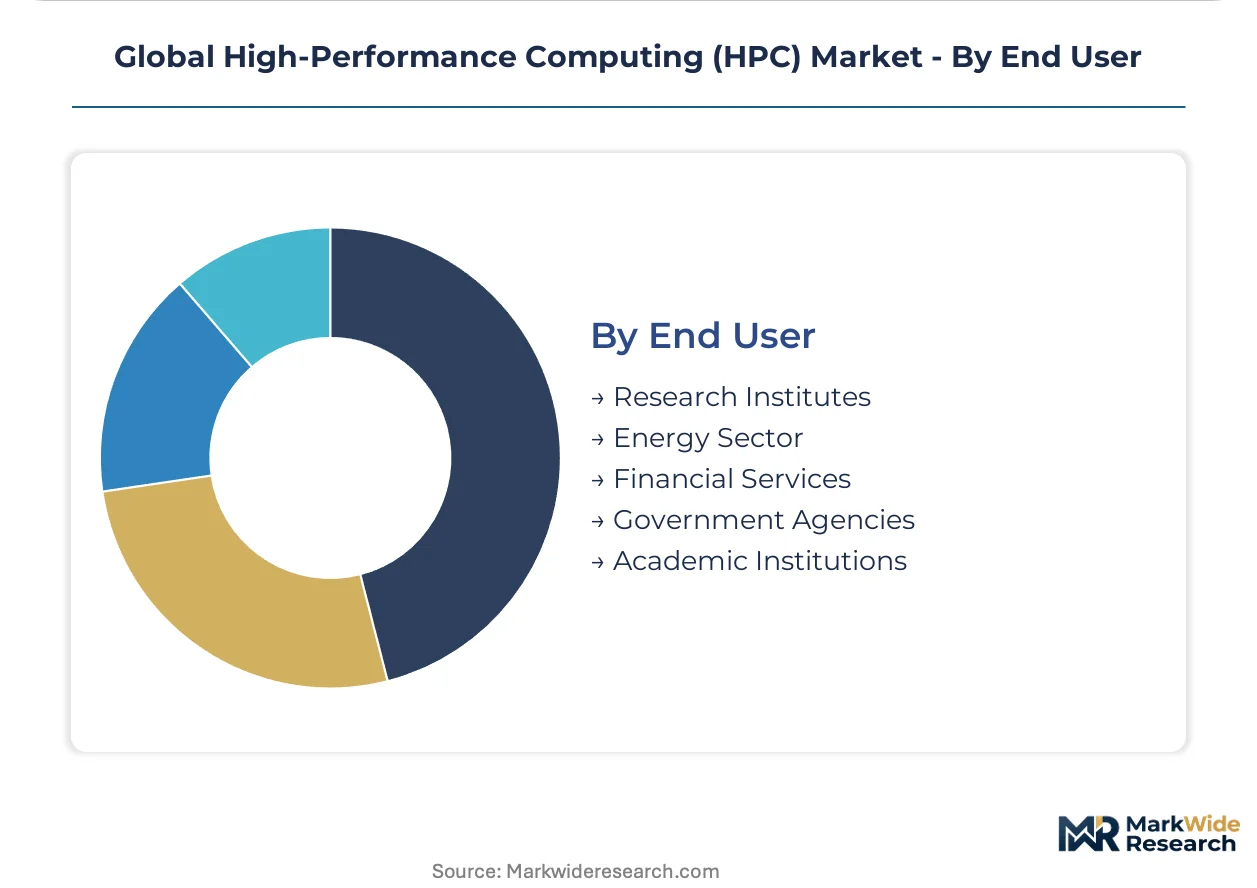
- Research Institutes:Genomics and materials science centers in Germany's Munich-Stuttgart corridor are consolidating budgets into fewer, larger system deployments. REACH substance restrictions on cooling fluids are disqualifying legacy liquid cooling chemistries from new European installations.
- Government Agencies:National laboratories in the United States face EPA ENERGY STAR specifications and emerging carbon accounting frameworks for datacenter expansions. Export control classifications for advanced accelerators constrain procurement eligibility.
- Energy Sector:Oil and gas majors and offshore wind developers are shifting toward operational expenditure models.
- Financial Services:Banks and insurance firms adopt quantum-HPC hybrid platforms for risk modeling.
- Academic Institutions:University research computing centers operate under tighter budget constraints than national facilities.
Research institutes lead on system scale; government agencies lead on procurement volume stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Computational fluid dynamics and cryogenic engineering expertise concentrates among aging specialist workforces in the United States and Germany, anchoring regional competitive advantages in liquid cooling subsystem design. Japan and China are cultivating domestic talent pipelines for advanced interconnect engineering. India's semiconductor assembly incentives are creating localized integration capacity for defense and research buyers.
United States
National laboratories in California and New Mexico are expanding petaflop-scale deployments for materials modeling and fusion energy research. The EPA's ENERGY STAR specifications and emerging FERC grid-interconnection rules are tightening datacenter power planning requirements for Department of Energy facilities. The Pacific Northwest National Laboratory and Oak Ridge National Laboratory anchor procurement concentration in the Pacific Northwest and Tennessee Valley corridors.
Germany
Automotive simulation centers and genomics institutes in the Munich-Stuttgart industrial corridor are consolidating procurement budgets into fewer, larger system deployments. ECHA's REACH substance restrictions on per- and polyfluoroalkyl substances are disqualifying legacy liquid cooling chemistries from new installations. The Leibniz Supercomputing Centre and HLRS Stuttgart are front-loading capital budgets to secure qualified cooling subsystem inventory ahead of anticipated phase-out deadlines.
Japan
METI-funded initiatives are accelerating domestic accelerator procurement for weather forecasting and materials science workloads. The RIKEN Center for Computational Science in Kobe anchors demand for custom interconnect fabrics and high-bandwidth memory subsystems. Japanese national laboratories are piloting chassis-less blade configurations that allocate DRAM and accelerator pools dynamically across workload queues.
China
Domestic foundry capacity expansion through SMIC and Hua Hong Semiconductor is reducing reliance on TSMC wafer allocation for mid-scale cluster deployments. MIIT standards for high-performance computing infrastructure are mandating local content ratios for government-funded research facilities. The Yangtze River Delta and Beijing-Tianjin-Hebei corridors concentrate system integration capacity for defense and aerospace simulation buyers.
India
The semiconductor PLI scheme is creating localized system integration capacity for South Asian research and defense buyers requiring sovereign compute infrastructure. CEA regulations for critical infrastructure datacenters are mandating ISO 50001 energy management certification for publicly funded facilities. The Delhi-NCR and Bengaluru corridors are emerging as assembly hubs for mid-scale parallel processing clusters serving university research centers.
Global High-Performance Computing (HPC) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented procurement tiers, with accelerator silicon scarcity forcing multi-year supply commitments that reshape vendor-client relationships. The vendor base stratifies into three archetypes: GPU-accelerated architecture suppliers, vertically integrated supercomputer integrators, and quantum-HPC hybrid platform developers. Dominant competitive moves include strategic partnerships with national laboratories for multi-year system deployments and backward integration into liquid cooling subsystem design to circumvent REACH substance restrictions.
Within the GPU-accelerated architecture tier, NVIDIA anchors premium supply relationships through accelerator dominance and memory-bandwidth engineering. Among vertically integrated supercomputer integrators, Cray (HPE) exemplifies deep upstream control over interconnects and cooling systems. IBM occupies a position in the quantum-HPC hybrid convergence space, targeting financial services risk modeling applications with specialized accelerator-photonic interconnect platforms.
| Leading Market Players |
|---|
| NVIDIA |
| Cray (HPE) |
| Hewlett Packard Enterprise |
| Supermicro |
| Fujitsu |
| IBM |
| Lenovo |
| Penguin Solutions |
| Dell Technologies |
| Others |
Supply & Pricing Matrix
Sovereign-backed national laboratories and hyperscale research institutes anchor procurement concentration, compressing vendor margins through multi-year supply commitments while elevating accelerator premiums through silicon scarcity discipline.
Pricing Analysis
The bundled-versus-unbundled service split distinguishes capital-intensive supercomputer deployments from operational-expenditure cloud HPC subscriptions. Pricing stratifies across premium accelerator tiers, standard cluster configurations, and economy workstation levels, with differentiation driven by memory-bandwidth engineering and ISO 50001 energy certification status. Cost compression in mid-scale cluster segments is intensifying because energy sector buyers are shifting toward managed service intermediaries. Academic institutions exhibit highest price sensitivity, while government agencies with multi-year capital planning horizons absorb premium pricing for custom interconnect fabrics.
Supply Chain Analysis
Domestic-content mandates through China's MIIT standards and India's semiconductor PLI scheme are reshaping sourcing patterns for government-funded research facilities. Accelerator silicon concentrates in Taiwan and South Korea foundries, while system integration capacity clusters in Germany, Japan, and the United States. The supply chain draws from high-bandwidth memory subsystems, custom interconnect fabrics, and specialized dielectric cooling fluids. Single-source vulnerability around TSMC wafer allocation creates structural risk. Distribution runs through direct vendor relationships with national laboratories and emerging managed service intermediaries in the energy sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in accelerator-photonic interconnect platforms and liquid cooling retrofit services, justified by REACH substance restrictions forcing premature refresh cycles.
For Market Incumbents: Acquire liquid cooling subsystem design expertise to circumvent ECHA phase-out deadlines. Cray and HPE exemplify backward integration into interconnect and cryogenic engineering. National laboratories are consolidating procurement into fewer vendors, threatening mid-scale cluster specialists. Defensive moves require securing TSMC foundry allocation through multi-year supply commitments and investing in ISO 50001 certification capabilities for European public datacenter eligibility.
For New Entrants and Emerging Players: The price-point gap between premium quantum-HPC hybrid platforms and economy cloud HPC subscriptions offers white-space entry. India's semiconductor PLI scheme creates localized assembly opportunity for South Asian defense and research buyers requiring sovereign infrastructure. Norwegian offshore wind engineering consultancies represent the most penetrable segment. A channel partnership strategy with independent software vendors captures margin pools previously retained by original equipment manufacturers.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale cluster integrators lacking accelerator supply relationships. Long-term viability centers on quantum-HPC hybrid convergence platforms serving financial services risk modeling. Acquisition targets should demonstrate CXL protocol integration capabilities and established relationships with German automotive simulation centers. The signal to monitor is ECHA's 2026 cooling fluid phase-out timeline accelerating consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Liquid Cooling | Circumvents REACH substance restrictions disqualifying legacy chemistries from European installations. |
| Quantum-HPC Hybrid Platform Development | Opens premium pricing tiers for financial services risk modeling applications at RIKEN and IBM. |
| Multi-Year Accelerator Supply Commitments | Secures TSMC foundry allocation priority for national laboratory deployments in California and Tennessee. |
| Managed Service Agreement Unbundling | Captures operational-expenditure shift among Norwegian offshore wind engineering consultancies. |
| ISO 50001 Certification Investment | Creates retrofit service revenue from India's CEA-mandated efficiency auditing for publicly funded datacenters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with supercomputer procurement officers at national laboratories, datacenter infrastructure planners, liquid cooling subsystem engineers, and cloud HPC service directors with secondary validation. Sources included SEC filings from accelerator suppliers, ECHA regulatory amendment proposals, FERC grid-interconnection filings, and hyperscaler capital expenditure disclosures. Bottom-up cluster deployment counts and top-down foundry capacity allocation estimates were triangulated for market sizing.
Across the analysis window, forecasts anchored to historical refresh cycle patterns and foundry utilization rates. Segmentation dimensions modeled included deployment scale, interconnect architecture, cooling technology, compliance certification tier, and regional procurement concentration. CAGRs derived from regression against semiconductor capital equipment spending and research infrastructure budget allocations. Industry-specific inputs encompassed TSMC wafer queue estimates and ECHA substance restriction implementation timelines.
Caveats apply where foundry capacity reallocation or export control classification revisions could materially shift the outlook. Forecasts reflect assumptions around sustained national laboratory funding and cooling fluid substitution timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Printed Electronics Market
Emerging and Next Generation Technologies
Roll to Roll Flexible Electronics Market
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
Nanopatterning Market
Emerging and Next Generation Technologies
Microfluidics Prototype Market
Emerging and Next Generation Technologies
Spintronics Market
Emerging and Next Generation Technologies
Multi-Touch Technology Market
Emerging and Next Generation Technologies
Switchable Smart Film Market
Emerging and Next Generation Technologies
Global Smart Window Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market
Emerging and Next Generation Technologies
Global Nano Batteries Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
Laser Technology Market
Emerging and Next Generation Technologies
Flexible Hybrid Electronics (FHE) Market
Emerging and Next Generation Technologies
North America Wigig Market
Emerging and Next Generation Technologies
Haptic Technology Market