
 LED Materials Market | 2026-2036
LED Materials Market Size, Share, and Industry Trends Forecast 2026-2036
LED Materials Market Intelligence
The performance gap between mid-tier sapphire substrates and premium silicon carbide wafers is collapsing as manufacturing yields improve. Wolfspeed, A Cree Company, specializes in silicon carbide wafers, providing a critical component for high-power LEDs. Nichia Corporation leverages its extensive patent portfolio and vertical integration to maintain a leading position in high-brightness blue and white LEDs. Intematix Corporation focuses on phosphor materials, which are essential for converting blue light into white light.
LED materials encompass a range of semiconductor compounds, substrates, and phosphors used to fabricate light-emitting diodes. Core materials like gallium nitride are grown via metal-organic chemical vapor deposition to create the active p-n junction that emits photons. Among material types, gallium nitride and its alloys command the high-brightness segment, while sapphire substrates remain a high-volume choice. Automotive lighting and large display panels represent high-margin applications compared to the more commoditized general lighting sector.
The European Union's RoHS directive restricts hazardous materials, influencing the composition of solders and encapsulants used in LED packages. Simultaneously, China's GB standards and dual carbon goals incentivize the production of higher-efficiency LEDs, driving demand for premium substrate and epitaxial materials. Material suppliers must now decide whether to invest in advanced GaN-on-Si technologies or optimize existing sapphire-based production to remain competitive.
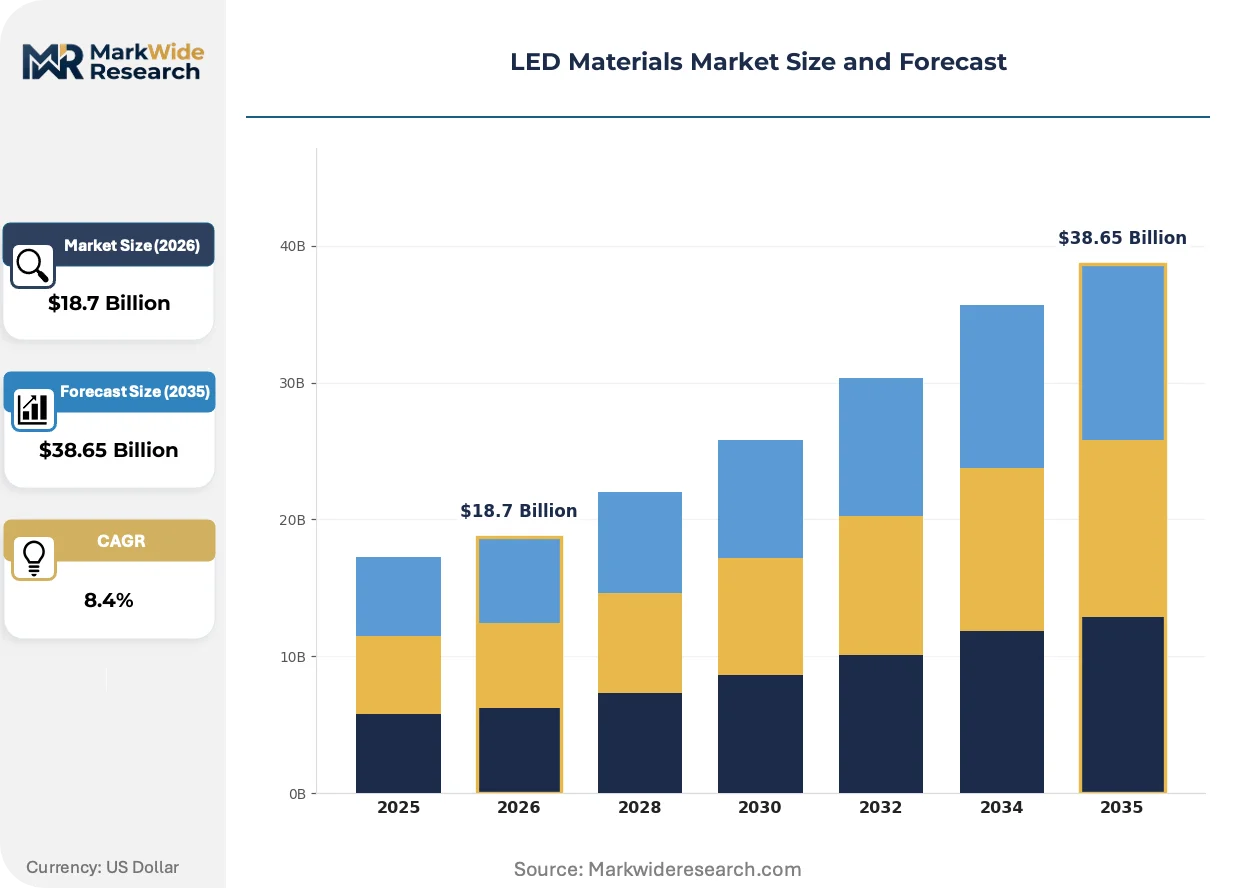
Market Dynamics
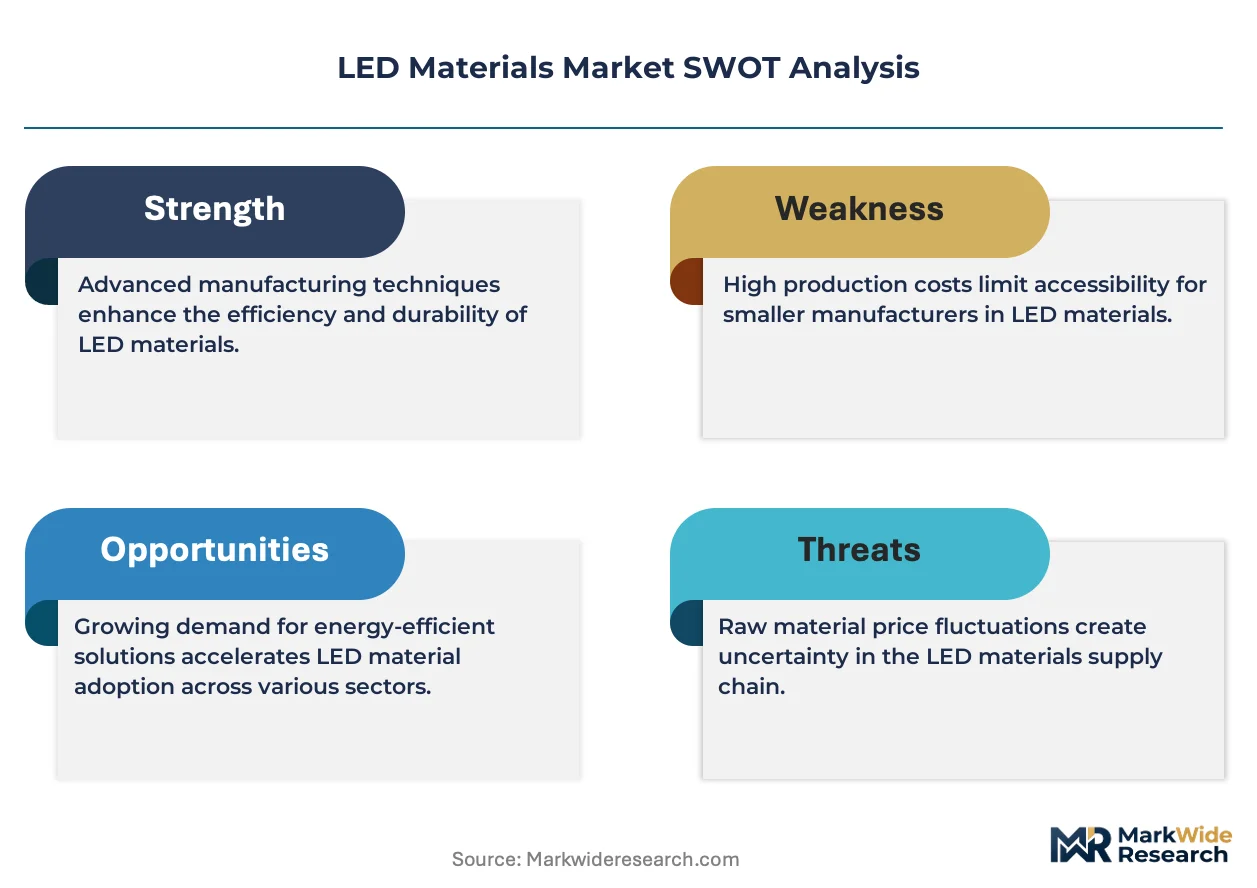
The push for higher efficiency and specialized performance, particularly from automotive and display sectors, is creating a rift between commoditized sapphire-based platforms and advanced, high-cost materials like silicon carbide and GaN-on-Si.
Growth Catalysts
- Automotive Lighting Demand:Advanced driver-assistance systems require high-reliability LEDs, driving consumption of premium substrates and phosphors for adaptive headlamps.
- EU RoHS Directive:Restrictions on hazardous substances favor compliant materials like lead-free solders and cadmium-free quantum dots in LED packages.
- GaN-on-Si Technology:Maturing GaN-on-Si processes offer a path to larger wafer diameters and potential cost reductions, creating new economies of scale.
Market Restraints
- High Input Costs:Manufacturing high-purity metal-organic precursors for MOCVD is a significant cost driver, limiting margin expansion in epitaxy.
- Supply Chain Concentration:Heavy reliance on clusters in China and South Korea for wafer fabrication creates geopolitical and logistical supply risks.
- Yield and Defectivity:Achieving low defect densities on large-diameter silicon carbide or GaN substrates remains technically challenging, impacting manufacturing costs.
Strategic Opportunities
- MicroLED Displays:The development of displays for wearables and automotive applications creates a market for new material sets and mass-transfer technologies.
- China's Dual Carbon Goals:National policies incentivizing energy efficiency accelerate demand for premium materials that enable higher-efficacy LEDs.
- Horticultural Lighting:Specialized lighting for indoor farming requires tailored phosphor and quantum dot solutions to optimize plant growth, a nascent market.
Industry Challenges
- Intellectual Property Complexity:A dense web of patents around core technologies like blue LEDs and certain phosphors creates high licensing costs and litigation risk.
- High Capital Expenditure:Establishing or upgrading MOCVD fabrication facilities requires substantial investment, creating high barriers to entry and expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Materials Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Gallium Nitride, Indium Gallium Nitride, Aluminium Gallium Indium Phosphide, Sapphire Substrate, Silicon Carbide, Zinc Selenide Application: Display Panels, Lighting Fixtures, Automotive Lighting, Traffic Signals, Signage, Backlighting End User Industry: Consumer Electronics, Automotive Manufacturers, Commercial Construction, Entertainment Production, Aerospace Engineering Product Form: Bulk Crystals, Thin Films, Powders, Wafers, Nano-Particles |
| Companies Covered | Nichia Corporation, Wolfspeed, A Cree Company, Intematix Corporation, OSRAM Opto Semiconductors GmbH, EPISTAR Corporation, AkzoNobel N.V., II-VI Incorporated, Hitachi Metals, Ltd., Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Materials Market Strategic Shifts & Innovations
The pursuit of performance beyond general illumination is driving material innovation. A shift toward application-specific material systems is displacing the one-size-fits-all substrate and phosphor model that characterized the market’s early growth phase.
MicroLED technology requires the precise placement of microscopic LED chips onto a backplane. High-end display manufacturers are adopting this for next-generation automotive dashboards and premium consumer electronics. This requirement for new mass transfer techniques and specialized substrates is fragmenting the traditional, monolithic wafer-scale fabrication supply chain into separate die-transfer and bonding steps.
The European Union's RoHS directive governs the use of specific hazardous materials in electronic equipment. This regulation forces the reformulation of certain solders and quantum dot materials to eliminate substances like lead and cadmium. The LED packaging and component sectors are most affected, accelerating R&D into compliant, high-performance alternatives for the European market.
Automotive lighting designers are increasingly specifying performance outcomes for lighting modules rather than procuring discrete LED components. This change disrupts the traditional sales channel by shifting material selection responsibility to Tier-1 suppliers who must integrate substrates, chips, and phosphors. The trend is most visible within advanced driver-assistance system development in Germany and Japan.
LED Materials Market Segmentation
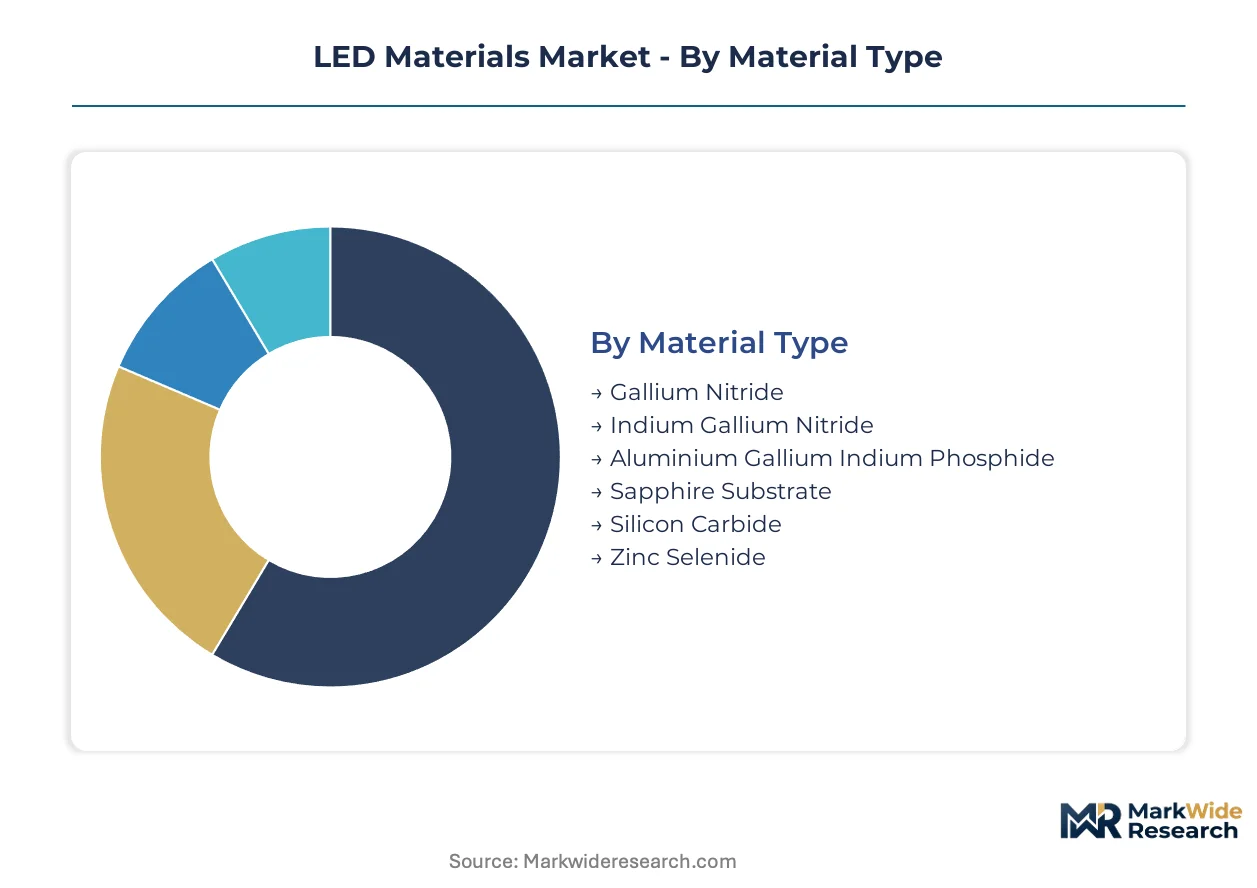
Segmentation provides a granular view of the LED materials market, illustrating how diverse material compositions, applications, end-user requirements, and product forms shape demand and supply dynamics. Understanding these distinctions allows stakeholders to identify specific growth pockets and material innovation priorities within the broader industry.
Material Type:
Material types dictate the initial upstream supply channels for LED component manufacturers, influencing both cost structures and performance capabilities.
- Gallium Nitride:This semiconductor compound forms the active p-n junction in blue and white LEDs, grown epitaxially on various substrates. Demand concentrates in high-brightness applications like automotive headlamps due to its superior efficiency and power handling.
- Sapphire Substrate:A widely used, cost-effective substrate for growing gallium nitride, offering good thermal and optical properties. High-volume general lighting and display backlighting applications in China drive its significant consumption.
- Indium Gallium Nitride:An alloy of gallium nitride, used to tune the emission wavelength for blue and green LEDs. It is critical for achieving specific color temperatures in full-color displays.
- Aluminium Gallium Indium Phosphide:This material is primarily utilized for red, orange, and yellow LEDs, often found in traffic signals and automotive taillights.
- Silicon Carbide:A premium substrate material offering excellent thermal conductivity and high power handling, particularly for high-power and high-frequency LED applications.
- Zinc Selenide:A less common material, historically used for blue-green LEDs, but largely superseded by gallium nitride in mainstream applications.
Sapphire Substrate dominates installed base. Silicon Carbide is where expansion concentrates.
Application:
Application segments reflect varying performance demands and price sensitivities across end markets for LED materials.
- Automotive Lighting:Requires highly reliable and durable LED materials for adaptive headlamps, interior lighting, and advanced driver-assistance systems. Germany and Japan lead in specifying premium materials for these demanding applications.
- Display Panels:This segment includes materials for high-resolution screens, including LCD backlights and emerging MicroLED displays for consumer electronics. Demand from South Korea and China for next-generation televisions and wearables is significant.
- Lighting Fixtures:Encompasses general illumination products for residential, commercial, and industrial settings, often prioritizing cost-effectiveness and lumen output. This segment represents a high-volume, commoditized market.
- Backlighting:Primarily for LCD screens in televisions, monitors, and mobile devices, requiring efficient and uniform light distribution. This application often uses blue LEDs with phosphor converters.
- Traffic Signals:Demands robust and long-lasting LED materials that can withstand outdoor conditions and provide high visibility. The materials must meet specific regulatory standards for color and intensity.
- Signage:Includes materials for digital billboards, advertising displays, and indicator lights, requiring bright and durable LED components.
Automotive Lighting and Display Panels exhibit the highest demand for specialized material formulations.
End User Industry:
End user industries define the regulatory landscape and performance specifications for LED material procurement.
- Automotive Manufacturers:These companies demand materials that meet stringent reliability, thermal management, and longevity standards for vehicle integration. The EU's RoHS directive impacts material choices for automotive electronics.
- Consumer Electronics:Drives innovation in compact, high-efficiency, and color-accurate LED materials for smartphones, wearables, and televisions. Manufacturers in China and South Korea are key consumers.
- Commercial Construction:Focuses on energy-efficient and long-lasting LED solutions for office buildings, retail spaces, and infrastructure projects. China's dual carbon goals incentivize high-efficiency LED adoption.
- Aerospace Engineering:Requires lightweight, extremely reliable, and radiation-tolerant LED materials for aircraft interior lighting and display systems.
- Entertainment Production:Utilizes high-brightness and color-tunable LED materials for stage lighting, studio backdrops, and architectural accent lighting.
Automotive Manufacturers and Consumer Electronics drive significant material innovation due to rigorous performance requirements.
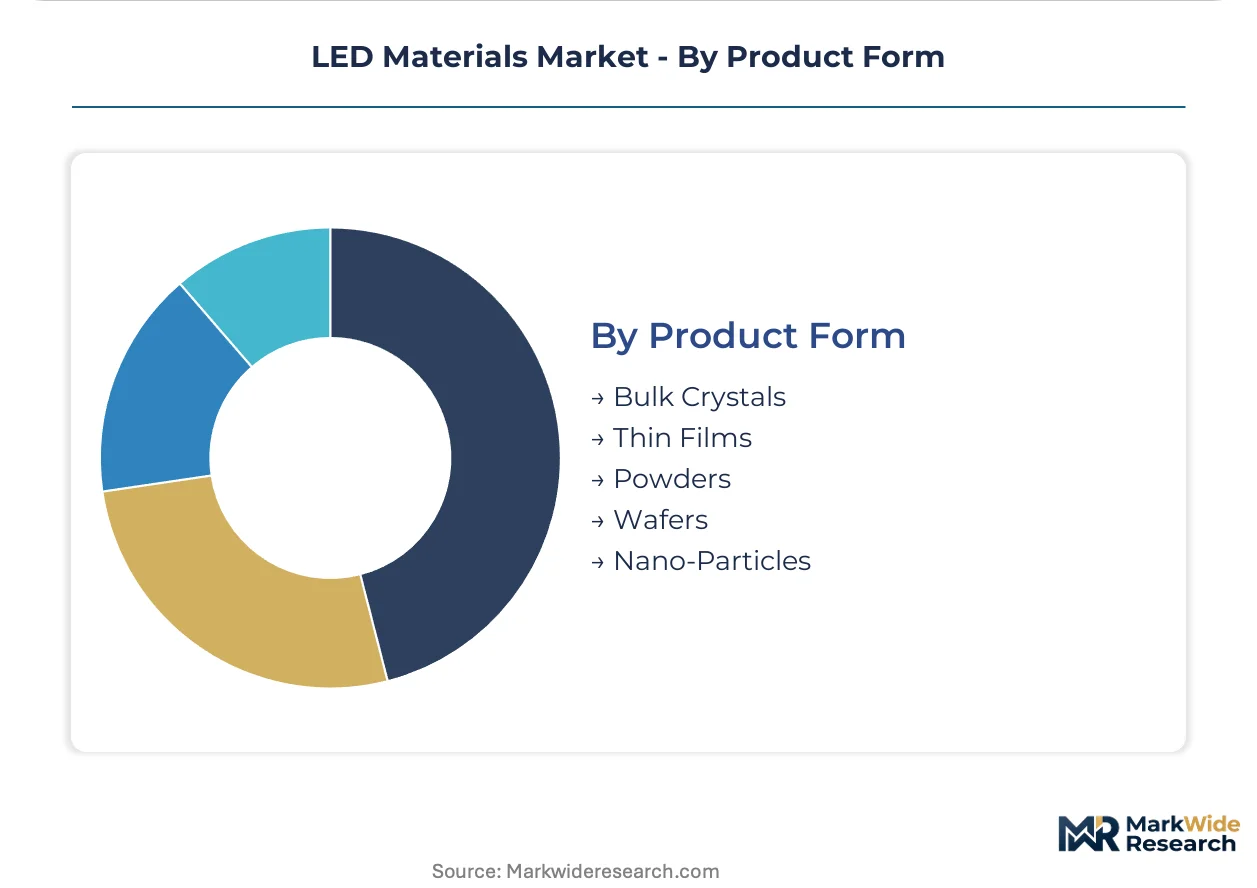
Product Form:
Product forms illustrate the manufacturing stages and supply chain nodes for LED material processing.
- Wafers:Substrate materials like sapphire, silicon, or silicon carbide, which serve as the foundation for epitaxial growth of LED active layers. Wafers are a critical intermediate product in LED chip manufacturing.
- Thin Films:Epitaxially grown layers of semiconductor materials, such as gallium nitride, deposited onto a substrate to form the light-emitting structure. These films are precisely controlled for thickness and composition.
- Powders:Primarily refers to phosphor materials, which are finely ground inorganic compounds used to convert blue LED light into white light. Intematix Corporation specializes in these materials.
- Bulk Crystals:Large single crystals of materials like sapphire or silicon carbide, which are then sliced into wafers for further processing. These are the raw material for wafer production.
- Nano-Particles:Includes quantum dots and other nanoscale materials used for color conversion and enhancement in advanced displays and specialized lighting.
Wafers remain central to chip fabrication, while Nano-Particles represent a rapidly developing material frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply chain activities for LED materials concentrate heavily in industrial clusters within China and South Korea. This geographical focus creates specific dynamics for material procurement and technological advancement. Demand for high-performance LED materials varies significantly across different global regions.
China
China's substantial manufacturing base drives immense demand for sapphire substrates and gallium nitride. The country's GB standards and dual carbon goals incentivize the production of higher-efficiency LEDs. Industrial clusters in the Yangtze River Delta and Pearl River Delta lead in high-volume LED component fabrication and material consumption.
South Korea
South Korea exhibits significant demand for advanced LED materials, particularly for display panels and consumer electronics. The government actively supports research into next-generation display technologies like MicroLEDs. Major technology hubs around Seoul and Gyeonggi Province house leading manufacturers pushing material innovation.
Germany
Germany's automotive sector demands premium LED materials for adaptive headlamps and advanced driver-assistance systems. The EU's RoHS directive influences material choices, favoring compliant substances in LED packages. Cities like Stuttgart and Munich, centers of automotive engineering, drive specifications for high-reliability components.
Japan
Japan's high-tech industries, including automotive and specialized lighting, require robust and high-performance LED materials. METI initiatives support advanced material science research for energy-efficient electronics. Manufacturers in regions like Kansai and Kanto focus on precision manufacturing and advanced epitaxial growth techniques.
United States
The United States drives innovation in high-power and specialized LED applications, especially in areas like horticultural lighting and microLED development. Federal investments in semiconductor research support the development of novel substrate materials. Silicon Valley and research institutions across the country are key centers for material science breakthroughs.
LED Materials Market Key Industry Players
Concentration sits with established semiconductor material suppliers and vertically integrated LED manufacturers. The market structure presents a tiered landscape, with premium material specialists alongside high-volume substrate providers. Strategic archetypes include advanced material innovators, integrated component producers, and specialized phosphor developers. Dominant competitive moves involve significant capital expenditure in MOCVD facilities and strategic partnerships for technology co-development and market access.
Within the specialized material and integrated component segments, Wolfspeed, A Cree Company, exemplifies a focus on advanced silicon carbide substrates for high-power applications. Nichia Corporation, a Japanese entity, represents a vertically integrated approach to high-brightness blue and white LED production, leveraging its intellectual property. Intematix Corporation, an American firm, occupies a position as a key supplier of phosphor materials essential for converting blue light into white light. These companies anchor critical points in the LED material supply chain, from foundational substrates to light-converting compounds.
| Leading Market Players |
|---|
| Nichia Corporation |
| Wolfspeed, A Cree Company |
| Intematix Corporation |
| OSRAM Opto Semiconductors GmbH |
| EPISTAR Corporation |
| AkzoNobel N.V. |
| II-VI Incorporated |
| Hitachi Metals, Ltd. |
| Sumitomo Electric Industries |
| Others |
Cost & Logistics Intelligence
GaN-on-Si technology, as a named substitution dynamic, simultaneously reshapes supply geography by reducing reliance on sapphire and alters pricing economics through potential cost reductions. This material shift influences where investments in advanced manufacturing facilities occur, particularly in China and South Korea, impacting the overall cost structure of LEDs.
Pricing Analysis
The EU's RoHS directive dictates the pricing tier structure by mandating compliant materials, creating a premium for certified lead-free solders and cadmium-free quantum dots. Pricing stratifies across premium, standard, and economy tiers, driven by material purity, automotive-grade certification levels, and customization requirements. Cost compression in the general lighting segment is intensifying due to improving manufacturing yields for sapphire substrates. Automotive and MicroLED display manufacturers exhibit the least price sensitivity, prioritizing performance and reliability over cost.
Supply Chain Analysis
Port congestion and container availability challenges in major trade lanes impact the inbound logistics costs for high-purity metal-organic precursors and large-diameter sapphire ingots. Geographic supply concentrates heavily in China and South Korea for wafer fabrication and epitaxy. The supply chain draws from specialized raw material dependencies such as gallium nitride precursors and phosphor elements. Geopolitical and logistical risks represent a significant structural risk. Distribution runs through a combination of direct sales to large LED manufacturers and specialized material distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LED materials market faces a capability scarcity, particularly in advanced substrate processing for large-diameter silicon carbide and GaN-on-Si technologies. This gap presents both challenges and opportunities across the value chain.
For Market Incumbents: Consolidate existing intellectual property portfolios and invest in next-generation MOCVD facilities to maintain a competitive edge. This defends against the threat of lower-cost GaN-on-Si solutions from emerging players. Leverage vertical integration into advanced substrate production to control material quality and cost, especially for high-power applications.
For New Entrants and Emerging Players: Automotive-grade certification fast-track offers a direct route into high-margin segments like adaptive headlamps. Target white-space opportunities in horticultural lighting and MicroLED mass transfer technologies, which require specialized material formulations. A go-to-market strategy focused on tailored phosphor solutions for specific spectral requirements can differentiate offerings.
For Investors and Strategic Acquirers: China's dual carbon goals reshape the acquisition landscape by incentivizing investments in energy-efficient LED material producers. Long-term viability for the sector spans a 5-10 year window, driven by sustained demand for higher-efficacy LEDs across diverse applications. Target advanced material innovators specializing in novel substrates or quantum dots. Increasing M&A activity in substrate technology serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in GaN-on-Si R&D | This initiative reduces manufacturing costs and enables larger wafer diameters for high-volume applications. |
| Secure long-term precursor supply | It mitigates geopolitical risks and price volatility for critical metal-organic compounds from China. |
| Expand automotive-grade certification | This unlocks access to high-margin automotive lighting applications in Germany and Japan. |
| Develop MicroLED mass transfer solutions | It addresses a critical bottleneck for next-generation display technologies in South Korea. |
| Form strategic phosphor partnerships | This optimizes color conversion efficiency for specialized lighting, including horticultural applications. |
Research Approach
A spread of perspectives from R&D directors, procurement leads, material scientists, and application engineers converged on the working assumptions for the LED materials market. This involved extensive primary interviews with industry stakeholders, validated through secondary research. Secondary data sources included SEC filings of publicly traded companies, industry association reports, patent databases, and technical journals. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy and consistency.
The forecast framework modeled segmentation dimensions including material type, application, end-user industry, product form, and regional demand across the analysis window. Compound Annual Growth Rates were derived from an assessment of historical trends, market drivers, and expert projections. Key industry-specific forecast inputs included projected MOCVD capacity expansions and anticipated substrate yield improvements.
The analysis sits within stated boundaries; outcomes outside significant geopolitical shifts or unforeseen technological breakthroughs would require recalibration. Forecasts reflect assumptions concerning regulatory stability and material cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Quartz Market
Semiconductor Material
Global Silicon Alloys Market
Semiconductor Material
Cadmium Market
Semiconductor Material
Semiconductor Grade PTFE Market
Semiconductor Material
Solar Silicon Ingots Market
Semiconductor Material
OLED Materials Market
Semiconductor Material
Electronic-Grade Polysilicon Market
Semiconductor Material
Ultra High Purity Silicon Carbide Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
5G Substrate Materials Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Asia Pacific Graphene Market