
 Big Size Synthetic Diamond Market | 2026-2036
Big Size Synthetic Diamond Market Size, Share, and Industry Trends Forecast 2026-2036
Big Size Synthetic Diamond Market Insights
Modular rough-diamond parcels is decoupling traditional bundled supply contracts, letting buyers select specific carat-weight brackets and quality tiers without committing to mixed lots. Element Six leverages its captive HPHT capacity in the UK and US to sustain supply security for industrial and gem clients. Henan Huanghe Whirlwind anchors Chinese production scale with integrated seed-crystal and pressing operations. Diamond Foundry differentiates through US-based CVD growth targeting premium jewelry channels.
Big size synthetic diamond denotes laboratory-created crystals exceeding one carat, produced through high-pressure high-temperature (HPHT) or chemical vapor deposition (CVD) methods that replicate natural diamond lattice structures with controlled nitrogen and boron doping levels. These stones serve precision cutting, thermal management substrates, and luxury jewelry applications where hardness, thermal conductivity, and optical clarity matter. Colorless product type leads current revenue pools due to bridal and fashion jewelry penetration, while Type IIa material commands premium positioning for electronics and scientific optics. Electronics application shows the fastest structural expansion as thermal interface materials in power semiconductors and 5G base stations multiply addressable demand. HPHT manufacturing technique still dominates volume output for industrial-grade material, though CVD growth rates accelerate for gem-quality larger stones.
US FTC guidelines on diamond disclosure and China's SAMR labeling enforcement both shape how producers communicate origin to downstream buyers, with non-compliance risking market access penalties. India's BIS certification pathway for synthetic gem imports adds a compliance layer that filters smaller traders from established supply chains. ISO grading standards for cut, color, clarity, and carat provide cross-border quality arbitration that reduces transaction friction. Stakeholders must monitor how regulatory divergence between consumer-protection and environmental-disclosure frameworks reshapes sourcing strategies and capital allocation priorities.
Market Dynamics
HPHT production capacity concentrates in China's Henan province, where integrated seed-crystal and pressing operations create supply bottlenecks that constrain downstream gem-quality availability. India's Surat cutting cluster processes the majority of large synthetic rough, creating a geographic chokepoint that amplifies price volatility during demand surges.
Growth Catalysts
- Dual carbon goals:China's GB standards and energy-use tightening for HPHT facilities are accelerating efficiency investments that reduce per-carat production costs for compliant operators.
- 5G base station deployment:Thermal interface material specifications for power semiconductors are pulling Type IIa diamond into electronics supply chains at volumes unseen in gem applications.
- Bridal jewelry normalization:Lab-grown stone acceptance in US and European bridal collections is expanding addressable demand beyond industrial buyers into premium consumer channels.
Market Restraints
- Energy input volatility:HPHT synthesis requires sustained 1,500°C temperatures and 5 GPa pressure, making electricity costs a structural margin pressure for Chinese producers.
- Supply concentration risk:Surat's cutting and polishing cluster processes over seventy percent of large synthetic rough, creating single-point vulnerability for global gem-quality availability.
- Natural diamond substitution persistence:De Beers' Lightbox pricing strategy and natural stone marketing continue to constrain lab-grown price ceilings in bridal segments.
Strategic Opportunities
- India BIS certification pathway:Synthetic gem import standards are filtering smaller traders from established supply chains, creating consolidation opportunities for compliant operators with testing infrastructure.
- Scientific optics expansion:Type IIa material for high-power laser windows and EUV lithography substrates commands premium positioning beyond jewelry applications.
- US FTC disclosure enforcement:Origin labeling clarity is enabling brand differentiation for CVD producers targeting transparency-conscious consumers in North American markets.
Industry Challenges
- ISO grading standard fragmentation:Cross-border quality arbitration for cut, color, clarity, and carat remains inconsistently applied, creating transaction friction between producer and retail buyers.
- CVD growth capex intensity:Plasma reactor systems for gem-quality larger stones require multi-year capital commitments with uncertain yield curves.
- Seed-crystal supply security:High-quality diamond substrate availability constrains CVD expansion plans for mid-scale entrants lacking backward integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Size Synthetic Diamond Market |
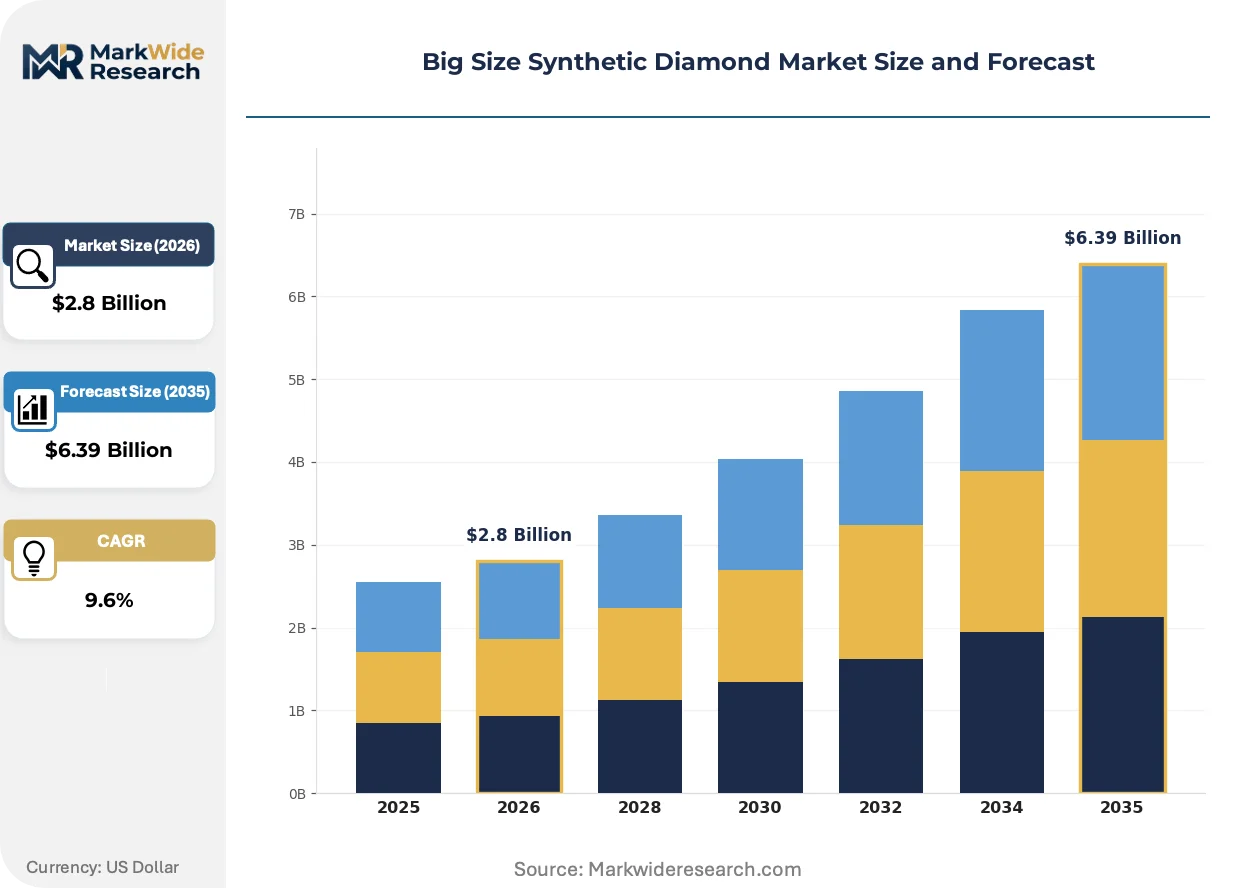
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.39 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colorless, Fancy Color, Industrial Grade, Type IIa Application: Jewelry, Electronics, Cutting Tools, Aerospace Manufacturing Technique: HPHT, CVD, Thermal Basem, Microwave Plasma End User: Retail Sector, Technology Firms, Automotive Components, Medical Devices |
| Companies Covered | Henan Huanghe Whirlwind, Zhengzhou Sino-Crystal Diamond, Element Six, North Industries Group Red Arrow, IIa Technologies, Diamond Foundry, Sumitomo Electric Industries, Henan Liliang Diamond, Adamas One Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Size Synthetic Diamond Market Trends and Innovations
CVD growth technology is advancing plasma reactor designs that compress production cycles for colorless stones above two carats. HPHT producers are responding with larger cubic press configurations that challenge CVD's gem-quality dominance.
Multi-layer CVD deposition is converging with microwave plasma control systems to enable single-crystal growth with nitrogen impurity levels below one part per billion. Electronics manufacturers in Japan and South Korea are qualifying these materials for thermal spreader applications in GaN power devices. The structural consequence is compressing natural diamond's residual share in high-value thermal management markets.
EU CSRD disclosure requirements are mandating supply-chain carbon footprint reporting for jewelry retailers operating in European markets. This regulatory pressure is forcing importers to document HPHT electricity sources and CVD methane feedstock origins. Bridal brands sourcing through Antwerp and Mumbai trading offices are restructuring supplier qualification protocols to meet these standards.
Modular rough-diamond parcels are displacing traditional bundled supply contracts across wholesale channels. Buyers now select specific carat-weight brackets and quality tiers without committing to mixed lots containing unusable material. This pattern is most visible in India's Surat cluster, where mid-size cutting houses are negotiating directly with Chinese HPHT producers for single-specification shipments.
Big Size Synthetic Diamond Market Segmentation
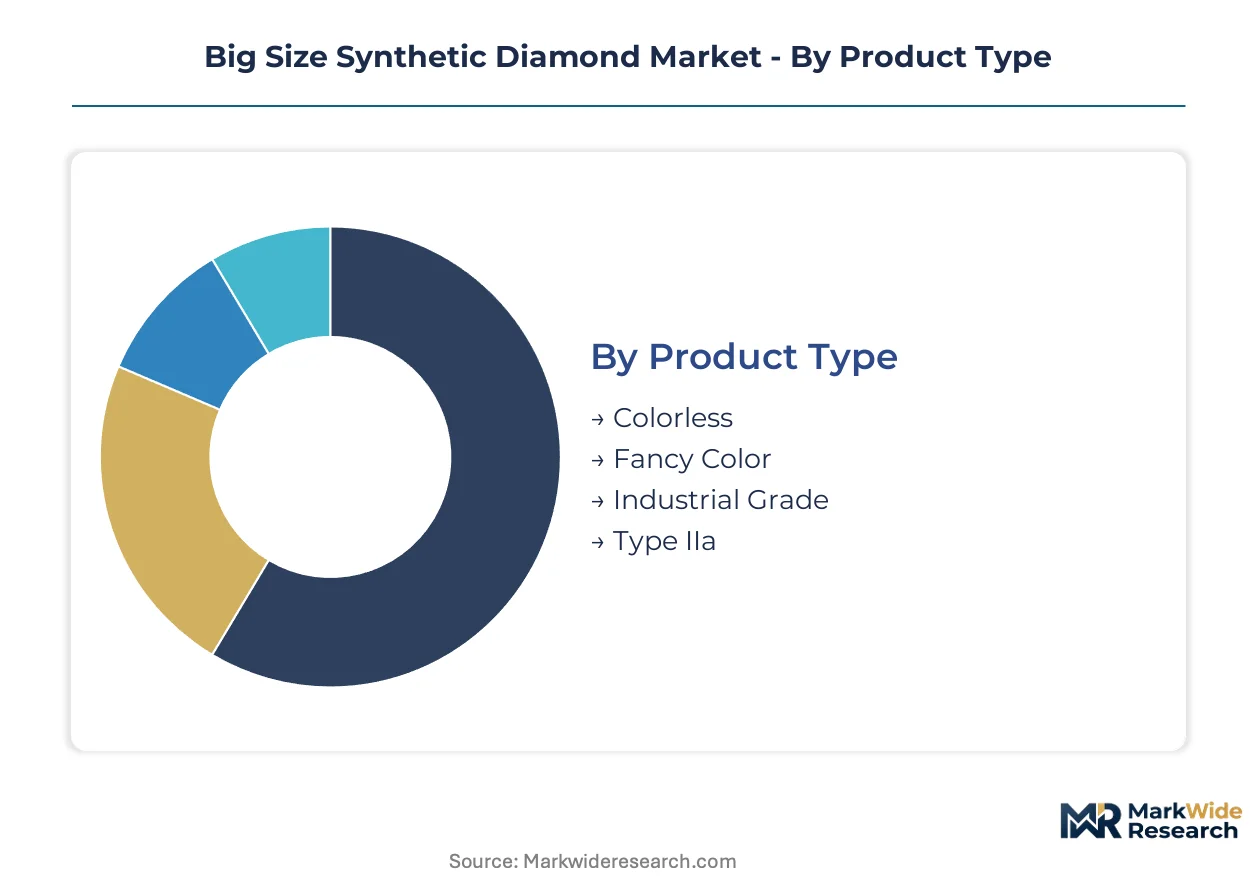
Segmentation in the big size synthetic diamond market determines which certification pathways and disclosure standards apply to each transaction. Buyers in premium channels face stricter provenance documentation than industrial purchasers, creating tiered compliance burdens across the value chain.
Product Type:
Colorless stones carry the heaviest certification load, requiring ISO grading documentation plus FTC or SAMR origin disclosure depending on destination market. Industrial-grade material faces lighter documentation, typically needing only batch-level composition certificates.
- Colorless:Near-zero nitrogen content produces optical clarity matching top-tier natural stones. Bridal jewelry manufacturers in the US and Europe concentrate procurement here, driven by consumer acceptance of lab-grown alternatives in engagement segments.
- Type IIa:Boron-free, nitrogen-free crystal structure delivers exceptional thermal conductivity and optical transmission. Electronics manufacturers in Japan and South Korea qualify these substrates for GaN power device thermal spreaders, where material purity specifications are stringent.
- Fancy Color:Intentional nitrogen or boron doping creates yellow, blue, and pink hues for fashion jewelry differentiation.
- Industrial Grade:Lower clarity tolerance acceptable for cutting, grinding, and drilling applications where hardness dominates over optical properties.
Leading the category by volume: Industrial Grade. Growing fastest: Type IIa.
Application:
Electronics applications command premium pricing tiers due to thermal performance specifications, while jewelry volumes dominate absolute throughput. Aerospace qualification cycles create the longest sales timelines, often spanning multi-year vendor approval processes.
- Jewelry:Bridal collections and fashion accessories absorb the majority of gem-quality output above one carat. India's Surat cluster processes most rough entering this channel, with cutting houses negotiating directly for single-specification parcels.
- Electronics:Thermal interface materials for 5G base stations and power semiconductors pull Type IIa material into supply chains at price points exceeding jewelry applications. Japanese and South Korean device manufacturers drive qualification protocols.
- Cutting Tools:Polycrystalline diamond compacts for machining hard metals and composites.
- Aerospace:Optical windows and thermal management components requiring traceable material pedigree.
Highest margin concentration sits with Electronics. Steepest expansion trajectory belongs to the same segment.
Manufacturing Technique:
HPHT producers in China's Henan province face tightening GB standards on energy consumption, while CVD operators document methane feedstock origins for EU CSRD compliance. Microwave plasma systems require the most specialized technical labor.
- HPHT:Cubic press technology dominates volume output for industrial-grade material. Chinese producers anchor global supply, though dual carbon goals are accelerating efficiency investments among compliant operators.
- CVD:Plasma reactor growth enables larger colorless stones with controlled impurity profiles. US-based producers leverage FTC disclosure clarity to target transparency-conscious North American consumers.
- Thermal Basem:Specialized substrate preparation for electronics-grade material deposition.
- Microwave Plasma:Advanced reactor design compressing production cycles for gem-quality stones above two carats.
Greatest output volume: HPHT. Fastest technology improvement curve: CVD.
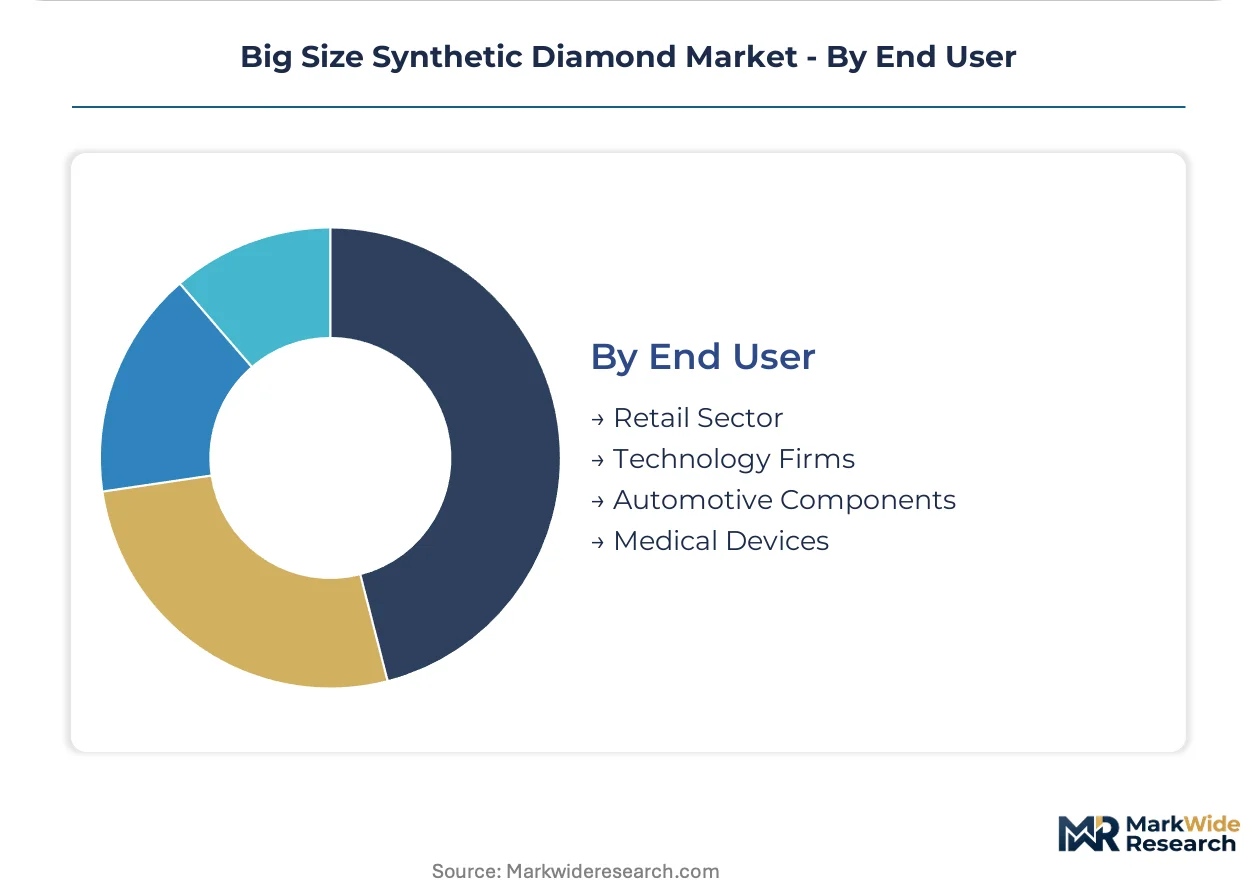
End User:
Retail sector buyers demand the most extensive documentation chains, from rough origin through cutting certification. Technology firms prioritize material specifications over provenance, streamlining procurement protocols.
- Retail Sector:Jewelry brands and bridal retailers require ISO grading plus origin disclosure for consumer-facing inventory. EU CSRD mandates are forcing documentation of electricity sources and feedstock origins.
- Technology Firms:Semiconductor and telecommunications equipment manufacturers qualify synthetic diamond for thermal management. Japanese and South Korean electronics companies set material purity benchmarks.
- Automotive Components:Precision cutting tools and thermal management parts for electric vehicle power electronics.
- Medical Devices:Surgical instruments and diagnostic equipment requiring biocompatible superhard materials.
Largest absolute demand: Retail Sector. Fastest qualification growth: Technology Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in China's Henan province while consumption spreads across jewelry cutting centers and electronics manufacturing hubs in India, the United States, and East Asia. This geographic split creates supply chain chokepoints that amplify price volatility during demand surges.
China
Henan province hosts the majority of global HPHT production capacity through integrated seed-crystal and pressing operations. GB standards and dual carbon goals from MEE are tightening energy-use regulations for synthesis facilities, accelerating efficiency investments among compliant operators. Zhengzhou anchors the upstream supply base where producers negotiate directly with Indian cutting houses for rough diamond parcels.
India
Surat processes over seventy percent of large synthetic rough entering global gem channels, creating a single-point vulnerability for availability. BIS certification requirements for synthetic gem imports are filtering smaller traders from established supply chains. Gujarat's cutting houses are restructuring procurement protocols to document electricity sources and feedstock origins for EU-bound exports.
United States
Bridal jewelry manufacturers in New York and Los Angeles are expanding lab-grown stone acceptance in engagement collections. FTC disclosure enforcement on diamond origin labeling enables brand differentiation for transparency-conscious consumers. CVD producers target North American retail channels where origin clarity commands premium positioning.
Japan
Electronics manufacturers in Tokyo-Osaka corridor are qualifying Type IIa synthetic diamond for thermal spreader applications in GaN power devices. METI-backed research programs support material purity benchmarking for semiconductor supply chains. Japanese device makers set specification standards that cascade through Asian electronics procurement networks.
South Korea
Telecommunications equipment producers in Seoul-Gyeonggi region are integrating synthetic diamond thermal interface materials into 5G base station designs. MFDS and national industrial policy frameworks encourage domestic qualification of high-purity substrates. Samsung and SK Hynix supply chain requirements are pulling material through Japanese and Chinese producer networks.
Big Size Synthetic Diamond Market Competitive Landscape
The competitive structure tilts toward integrated upstream operators with captive seed-crystal supply and geographic diversification. Two strategic archetypes dominate: Chinese HPHT specialists with backward-integrated pressing operations, and Western CVD producers targeting premium gem and electronics channels with transparency-focused branding. Capacity expansion and direct procurement relationships with cutting clusters represent the primary competitive moves, alongside certification infrastructure investments to meet BIS and EU CSRD requirements.
Within the integrated Chinese tier, Henan Huanghe Whirlwind and Zhengzhou Sino-Crystal Diamond exemplify scale-driven operators with upstream control over seed-crystal production. Element Six occupies a position bridging industrial and gem applications through UK and US-based facilities. Diamond Foundry represents the Western CVD archetype targeting North American premium channels. Among Japanese electronics-focused fabricators, Sumitomo Electric Industries and IIa Technologies sit within the high-purity material specialization segment serving thermal management applications.
| Leading Market Players |
|---|
| Henan Huanghe Whirlwind |
| Zhengzhou Sino-Crystal Diamond |
| Element Six |
| North Industries Group Red Arrow |
| IIa Technologies |
| Diamond Foundry |
| Sumitomo Electric Industries |
| Henan Liliang Diamond |
| Adamas One Corp |
| Others |
Pricing and Supply Chain Analysis
Skilled cutting labor in India's Surat cluster compresses cost differentials between premium gem-quality and standard industrial grades, widening pricing-tier spreads as Chinese HPHT producers pass through energy-efficiency gains to compliant operators.
Pricing Analysis
Margin tightening in colorless gem tiers reflects De Beers' Lightbox pricing discipline and natural diamond marketing persistence. Three-tier pricing structure across premium Type IIa, standard colorless, and economy industrial grades separates electronics buyers from bridal retailers from tool manufacturers. Cost-down pressure on HPHT material accelerates because Henan province's dual carbon goals force electricity cost absorption. Industrial-grade buyers exhibit highest price sensitivity; electronics manufacturers show least.
Supply Chain Analysis
Direct-to-cutting-house channels from Zhengzhou producers handle bulk rough procurement for Surat's gem-processing cluster. Supply concentrates in China for HPHT synthesis, India for cutting and polishing, and the United States for CVD gem finishing. Raw material flows draw from captive seed-crystal operations, methane feedstock for plasma reactors, and high-purity metal catalysts. Single-point vulnerability at Surat's seventy-percent processing share creates structural availability risk. Distribution runs through Antwerp and Mumbai trading offices for EU-bound certified material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where seed-crystal supply security and BIS certification infrastructure determine competitive endurance.
For Market Incumbents: Lock in captive seed-crystal supply through backward integration into substrate production, insulating against CVD expansion constraints. Defend gem-quality positioning by accelerating BIS certification investments ahead of India's import standard enforcement. Natural diamond substitution campaigns from De Beers threaten price ceilings; counter with transparency-focused FTC disclosure branding.
For New Entrants and Emerging Players: Launch via direct procurement relationships with mid-size Surat cutting houses bypassing established trading office markups. Target Type IIa electronics substrates where Japanese and South Korean device manufacturers set purity benchmarks with limited qualified supplier bases. White-space exists in EU CSRD-compliant documentation services for bridal brands restructuring supplier protocols.
For Investors and Strategic Acquirers: Re-rating potential sits with CVD operators possessing US-based plasma reactor capacity given FTC disclosure clarity enabling North American premium channel access. Long-term viability hinges on technology firms' thermal management material qualification cycles completing. Monitor 5G base station deployment volumes as inflection signal for Type IIa demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed-Crystal Production | Captive substrate supply secures CVD expansion capacity against supply bottlenecks constraining mid-scale entrants. |
| BIS Certification Infrastructure Investment | Testing capability filters smaller traders from Indian import channels, consolidating compliant operator market share. |
| Direct Procurement with Surat Cutting Houses | Single-specification parcel negotiations displace bundled supply contracts, improving yield and reducing unusable material. |
| EU CSRD Documentation Protocol Development | Carbon footprint reporting for electricity sources and methane feedstock origins meets retailer restructuring requirements. |
| Type IIa Electronics Qualification Programs | Material purity benchmarking with Japanese device manufacturers opens thermal spreader applications in GaN power devices. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary fieldwork incorporated structured interviews with HPHT plant managers in Henan province, procurement leads at Surat cutting houses, and regulatory affairs specialists navigating BIS certification pathways. Secondary sources included SAMR labeling enforcement documentation, EU CSRD disclosure requirement texts, and FTC guideline updates on diamond origin communication. Bottom-up capacity estimates from Chinese synthesis facilities reconciled with top-down jewelry channel demand assessments.
Data-stream reconciliation across production capacity surveys and end-use consumption patterns informed the analytical framework. Segmentation dimensions spanned product type, application, manufacturing technique, and end user across the projection horizon. CAGRs derived from fitted growth curves incorporating technology adoption rates, regulatory enforcement timelines, and substitution elasticity parameters. Electronics qualification cycle completion rates and bridal jewelry acceptance indices served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for CVD plasma reactor scaling would alter the outlook. Forecasts reflect base-case assumptions regarding GB standard compliance timelines and EU disclosure mandate enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Global Silicon Alloys Market
Semiconductor Material
Yttrium Market
Semiconductor Material
Methyl Phenyl Silicone Resin Market
Semiconductor Material
Gallium Market
Semiconductor Material
Silicon Nitride Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
Solar Silicon Ingots Market
Semiconductor Material
Sapphire Ingot Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Electronic Ceramics Market
Semiconductor Material
PV Module Encapsulant Film Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Quartz Crucible Market
Semiconductor Material
Rhenium Market
Semiconductor Material
Transparent Conductive Films Market