
 Gallium Oxide Transistor Market | 2026-2036
Gallium Oxide Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Gallium Oxide Transistor Market Foresight
The gap between silicon carbide performance and gallium oxide cost potential is narrowing as epitaxial growth techniques mature for 6-inch wafer processing. Novel Crystal Technology leverages vertical integration from single-crystal substrates to epitaxial wafers, controlling quality across the stack. Flosfia anchors device-level innovation through its proprietary corundum-structured gallium oxide technology. Wolfspeed competes by extending its SiC expertise into beta-Ga2O3 evaluation programs, while Sumitomo Electric Industries dominates industrial gas supply critical for crystal growth atmospheres.
Gallium oxide transistors are wide-bandgap semiconductor devices fabricated from beta-Ga2O3 or alpha-Ga2O3 crystals, typically grown by edge-defined film-fed growth or Czochralski methods, with bandgaps near 4.8 eV enabling breakdown fields above 8 MV/cm for high-voltage switching applications. Field-effect transistor architectures lead commercial development due to their compatibility with existing power electronics packaging, while Schottky barrier variants sustain niche positions in high-frequency rectification where forward voltage drop minimization matters. Metal-oxide-semiconductor structures occupy the fastest-growing trajectory as foundries adapt planar silicon processes to gallium oxide's anisotropic etch characteristics.
Japan's METI and the US NHTSA shape demand through efficiency mandates in automotive traction systems and charging infrastructure standards, while REACH compliance in Europe constrains precursor chemical sourcing for epitaxial processes. The FCC and FAA in the United States impose electromagnetic compatibility requirements that favor gallium oxide's switching speed in radar and communication amplifiers. Stakeholders must monitor how substrate diameter transitions from 2-inch to 6-inch formats alter equipment amortization and foundry economics.
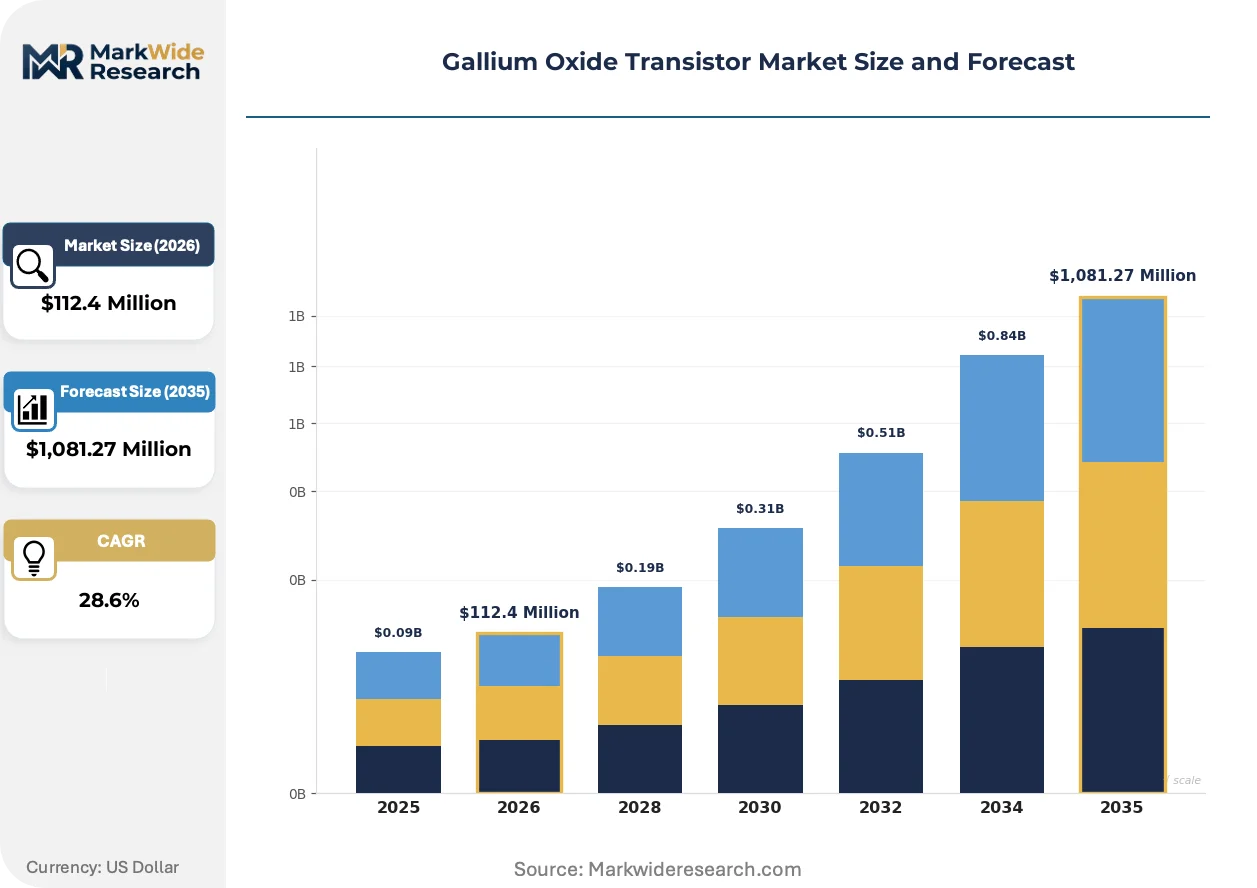
Market Dynamics
Wafer diameter transitions from 2-inch to 6-inch formats are compressing unit economics and forcing equipment recalibration across the gallium oxide transistor supply chain, with foundry amortization schedules now tied to substrate scaling milestones.
Growth Catalysts
- Automotive efficiency mandates:NHTSA fuel economy standards in the United States are accelerating traction inverter redesigns toward wide-bandgap semiconductors that cut switching losses.
- Japan's METI semiconductor revitalization:Directed funding streams are de-risking beta-Ga2O3 commercialization through substrate and epitaxial wafer development programs.
- Edge-defined film-fed growth maturation:Crystallization technique improvements are lifting boule quality and reducing defect densities for power device fabrication.
Market Restraints
- Precursor chemical supply concentration:High-purity gallium sourcing remains concentrated among limited specialty metal refiners, creating input cost volatility.
- Epitaxial equipment bottlenecks:MOCVD reactor availability for wide-bandgap materials lags silicon carbide demand, stretching lead times for gallium oxide qualification.
- Silicon carbide incumbent defense:Established SiC supply chains and proven reliability records slow substitution timelines in conservative automotive procurement.
Strategic Opportunities
- Grid-scale renewable integration:Utility-scale solar and wind inverters represent underpenetrated demand for ultra-high-voltage switching devices.
- Corundum-structured alpha-Ga2O3 devices:Heterostructure integration with existing nitride platforms opens RF amplifier applications.
- US CHIPS Act fabrication incentives:Domestic foundry construction subsidies could anchor non-Japanese gallium oxide manufacturing capacity.
Industry Challenges
- Compound semiconductor process engineering talent:Specialized expertise in anisotropic etch control and ohmic contact formation remains scarce.
- Automotive AEC-Q101 qualification timelines:Extended stress testing protocols delay revenue realization for power discrete suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gallium Oxide Transistor Market |
| Market Size in 2026 | $112.4 Million |
| Market Size in 2035 | $1,081.27 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Field-Effect Transistor, Schottky Barrier, Metal-Oxide-Semiconductor, Junction Gate, Planar Transistor Technology: Beta-Ga2O3, Alpha-Ga2O3, Epitaxial Growth, Pulsed Laser Deposition, Molecular Beam Epitaxy End User Industry: Power Electronics, Renewable Energy, Aerospace, Consumer Electronics, Telecommunication Equipment Application: Switch Mode Power Supply, Radio Frequency Amplifiers, Electric Vehicles, High Voltage Rectifiers, UV Photodetectors |
| Companies Covered | Flosfia Inc, Novel Crystal Technology, Saint-Gobain S.A, Aixtron SE, Kyma Technologies, Taiyo Nippon Sanso, Sumitomo Electric Industries, Gallox Semiconductors, Wolfspeed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gallium Oxide Transistor Market Shifts & Advancements
Process convergence between silicon planar fabrication and wide-bandgap epitaxy is rewriting equipment specifications, while regulatory efficiency mandates and procurement centralization are compressing supplier qualification cycles.
6-inch beta-Ga2O3 wafer processing is collapsing the cost gap against silicon carbide for 650V and above applications. Automotive tier-1 suppliers are accelerating device evaluation programs. This substrate scaling is collapsing foundry equipment amortization periods and enabling price parity in traction inverter procurement.
Japan's METI wide-bandgap commercialization roadmap is mandating domestic supply chain security for power semiconductors. Subsidy allocation now requires vertical substrate-to-device integration commitments. Japanese manufacturing clusters are responding by consolidating epitaxial growth and device fabrication within single corporate boundaries.
Centralized procurement by automotive OEMs is displacing tier-2 distributor networks for power discretes. Direct foundry relationships are replacing catalog purchasing for high-volume inverter programs. This concentration is most visible in German and Japanese automotive supply chains where platform standardization drives volume commitments.
Gallium Oxide Transistor Market Segmentation
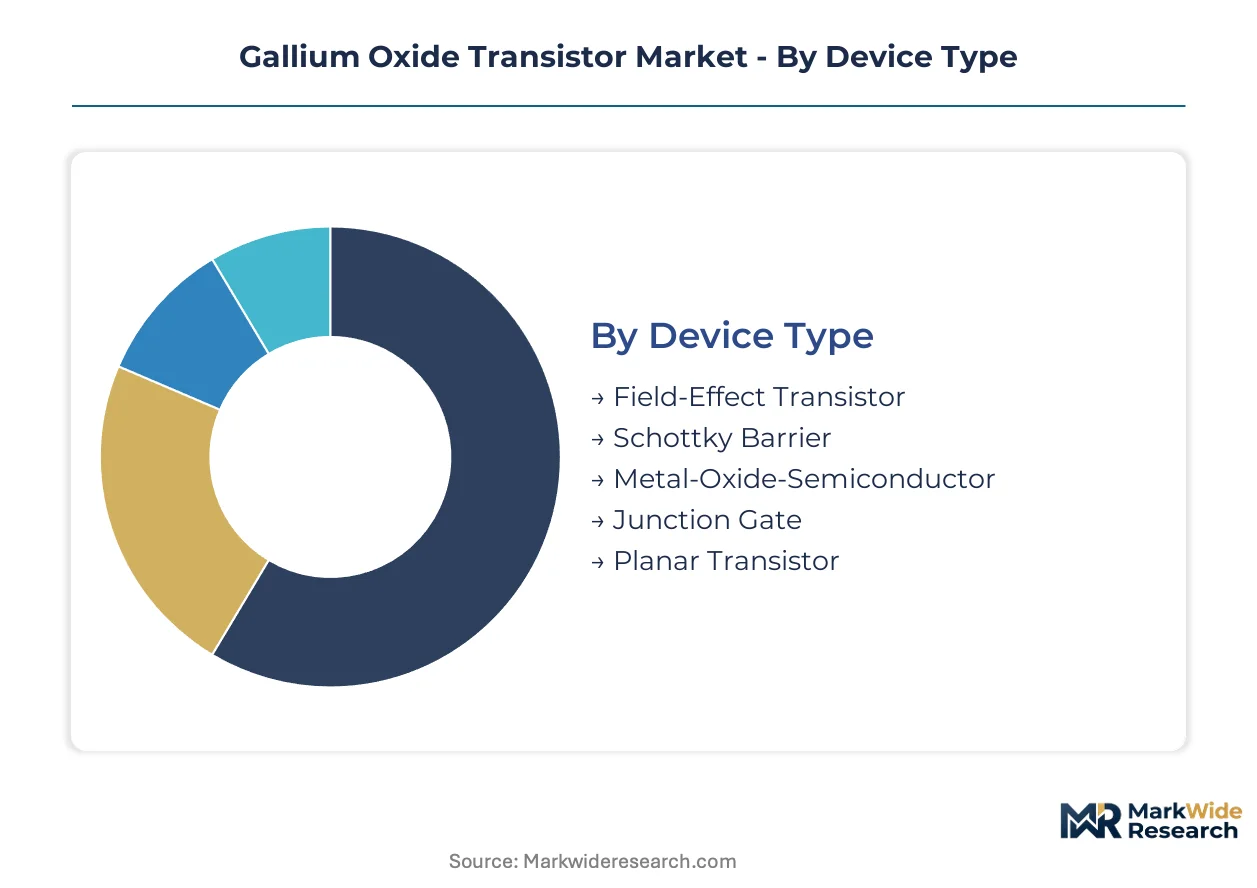
Gallium oxide transistor segmentation reveals how device architecture, crystal phase, and end-use voltage requirements fragment commercial pathways. Each dimension carries distinct qualification timelines and foundry tooling implications that shape supplier strategy.
Device Type:
Power switching applications span a voltage-handling spectrum from kilowatt-scale inverters to megawatt grid infrastructure.
- Field-Effect Transistor:Lateral and vertical FET architectures dominate 650V and above traction inverter designs. Automakers in Japan and Germany are qualifying these for electric vehicle powertrains where switching loss reduction justifies premium device costs.
- Metal-Oxide-Semiconductor:Planar MOS structures adapt existing silicon foundry equipment through modified gate stack processes. This segment is expanding most quickly as foundries in the United States and Japan repurpose depreciated 200mm lines for wide-bandgap production.
- Schottky Barrier:Rectifier applications in high-frequency power supplies leverage low forward voltage drops.
- Junction Gate:Vertical power devices for grid-scale switching benefit from high breakdown field tolerance.
- Planar Transistor:RF amplifier designs exploit surface-channel mobility in epitaxial films.
Established volume favors Field-Effect Transistor; emerging adoption favors Metal-Oxide-Semiconductor.
Technology:
Crystal growth method determines defect density, substrate diameter capability, and compatibility with existing epitaxial tooling.
- Beta-Ga2O3:Edge-defined film-fed growth produces boules with the lowest dislocation densities for power device substrates. Japanese manufacturers anchor substrate supply through this polymorph, with METI funding accelerating 6-inch wafer process development.
- Alpha-Ga2O3:Corundum-structured films grown by mist CVD enable heterostructure integration with gallium nitride HEMTs. Aerospace radar programs in the United States are evaluating these for X-band amplifier applications.
- Epitaxial Growth:Halide vapor phase epitaxy dominates thick drift layer deposition.
- Pulsed Laser Deposition:Research-scale film growth for UV sensor prototyping.
- Molecular Beam Epitaxy:Ultra-thin channel layers for RF device development.
Process maturity concentrates in Beta-Ga2O3; Alpha-Ga2O3 captures frontier applications.
End User Industry:
Customer procurement patterns split between long-qualification automotive programs and faster-cycle industrial equipment.
- Power Electronics:Industrial motor drives and server power supplies constitute the largest addressable base. German and Japanese industrial automation OEMs are piloting gallium oxide in 400V bus architectures.
- Electric Vehicles:Traction inverters and onboard chargers represent the highest-value qualification pipeline. NHTSA efficiency mandates are compressing supplier selection timelines for 800V platform designs.
- Renewable Energy:Utility-scale solar inverters above 1500V DC bus voltages.
- Aerospace:Satellite power conditioning and radar systems.
- Consumer Electronics:Compact adapter designs below 100W.
- Telecommunication Equipment:Base station power amplifiers.
Revenue concentration sits with Power Electronics; steepest expansion trajectory belongs to Electric Vehicles.
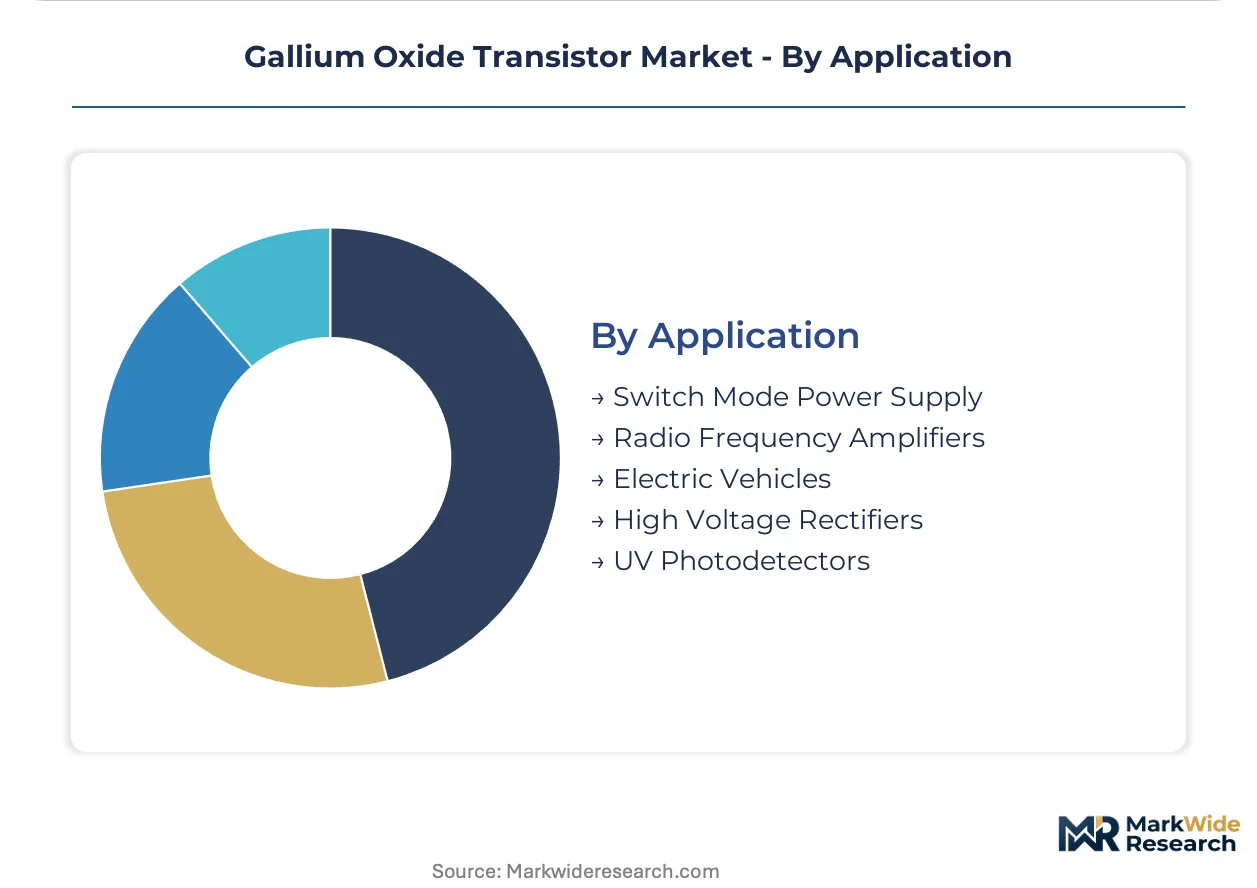
Application:
Voltage blocking requirements and switching frequency demands segment addressable markets by device performance tier.
- Electric Vehicles:Main inverters, DC-DC converters, and onboard chargers above 650V. Platform consolidation around 800V architectures by Korean and German automakers is creating volume commitments for qualified suppliers.
- Switch Mode Power Supply:Server and telecom rectification below 400V. Data center operators in the United States are specifying titanium efficiency standards that favor wide-bandgap switching.
- Radio Frequency Amplifiers:Radar and communication systems.
- High Voltage Rectifiers:Grid infrastructure and industrial drives.
- UV Photodetectors:Flame sensing and sterilization monitoring.
Design win activity concentrates in Electric Vehicles; qualification velocity peaks in Switch Mode Power Supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports gallium oxide substrates and epitaxial wafers to German and United States automotive manufacturers, while China imports crystal growth equipment from European suppliers to build domestic fabrication capacity.
Japan
Domestic automakers and power electronics OEMs drive substrate demand for next-generation traction inverters. METI's semiconductor revitalization policies channel public funding toward 6-inch wafer process development. The Chubu region around Nagoya anchors manufacturing clusters where Novel Crystal Technology and Flosfia control substrate-to-device vertical integration.
Germany
Industrial automation OEMs and automotive tier-1 suppliers pilot gallium oxide in 400V and 800V bus architectures for motor drives and EV platforms. KBA efficiency mandates and EU Green Deal industrial decarbonization targets compress supplier qualification timelines. Bavaria's semiconductor corridor around Munich hosts evaluation programs linking German automotive OEMs to Japanese substrate suppliers.
United States
Data center operators and aerospace radar programs generate dual demand for power switching and RF amplification devices. NHTSA fuel economy standards and FCC electromagnetic compatibility requirements favor wide-bandgap adoption in automotive and communication systems. The Research Triangle in North Carolina and Silicon Valley in California concentrate MOCVD equipment evaluation and foundry process development.
China
Domestic EV manufacturers and renewable energy inverter producers seek alternative wide-bandgap sources amid silicon carbide supply constraints. MIIT industrial policy targets wide-bandgap semiconductor self-sufficiency through domestic crystal growth capacity building. The Yangtze River Delta around Shanghai and the Pearl River Delta host equipment import hubs and pilot epitaxial wafer production lines.
South Korea
Battery and automotive conglomerates evaluate gallium oxide for 800V platform onboard chargers and DC-DC converters. MFDS and national industrial competitiveness programs support wide-bandgap material research through public-private consortia. The Seoul Capital Area anchors device qualification laboratories serving Hyundai-Kia and Samsung SDI supply chains.
Gallium Oxide Transistor Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the gallium oxide transistor value chain. The market structure consolidates around substrate suppliers with captive epitaxial capabilities and fragments among device foundries seeking process differentiation. Three archetypes dominate: vertically integrated Japanese material specialists, silicon carbide incumbents extending into beta-Ga2O3 evaluation, and European equipment vendors supplying MOCVD reactors. Capacity expansion and strategic technology licensing represent the primary competitive moves as foundries secure substrate supply commitments.
Among Japan-based material specialists, Novel Crystal Technology and Flosfia occupy positions exemplifying substrate-to-device vertical integration archetypes, while Wolfspeed represents the silicon carbide incumbent pivoting into complementary wide-bandgap evaluation programs. These three companies anchor competitive positioning across the supply chain without yet establishing dominant market share positions in the emerging device fabrication tier.
| Leading Market Players |
|---|
| Flosfia Inc |
| Novel Crystal Technology |
| Saint-Gobain S.A |
| Aixtron SE |
| Kyma Technologies |
| Taiyo Nippon Sanso |
| Sumitomo Electric Industries |
| Gallox Semiconductors |
| Wolfspeed |
| Others |
Supply & Pricing Matrix
Japanese substrate concentration around Novel Crystal Technology and Flosfia anchors upstream margin capture, with epitaxial wafer premiums flowing to vertically integrated suppliers while device foundries absorb yield-risk cost volatility.
Pricing Analysis
2-inch legacy wafer pricing sits at substantial discount to 6-inch next-generation formats, while transitional 4-inch formats occupy mid-market positioning. Contract-based long-term offtake dominates automotive procurement, with price differentiation driven by AEC-Q101 certification tier and volume scale commitments. Cost compression in consumer-grade Schottky devices is intensifying because silicon carbide incumbents defend share through aggressive bundling. Power electronics OEMs exhibit highest price sensitivity; aerospace radar programs show least.
Supply Chain Analysis
Extended payment terms from automotive tier-1 suppliers are forcing substrate vendors into supply-chain finance facilities to bridge working capital gaps. Geographic supply concentration centers on Japan, China, and Germany for crystal growth, epitaxial processing, and automotive integration respectively. Raw material dependencies draw from high-purity gallium metal, halide precursors, and specialized crucible ceramics. Single-source vulnerability in MOCVD reactor supply creates structural risk. Distribution runs through direct foundry relationships displacing traditional component distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in anisotropic etch control and ohmic contact formation remains scarcer than installed fabrication capacity, constraining output expansion regardless of capital deployment.
For Market Incumbents: Entrench substrate-to-device vertical integration by securing captive epitaxial capacity in Japan's Chubu region. Accelerate 6-inch wafer qualification timelines to outpace silicon carbide cost curves. Defend against Wolfspeed's beta-Ga2O3 evaluation programs by locking automotive OEMs into multi-year platform commitments.
For New Entrants and Emerging Players: Establish a beachhead in grid-scale renewable inverters above 1500V, where silicon carbide supply constraints create immediate substitution openings. Target US-based foundry construction under CHIPS Act incentives as the most penetrable geography. Pursue licensing partnerships with Japanese substrate specialists rather than greenfield crystal growth investment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed compound semiconductor equipment vendors holding MOCVD reactor portfolios. Five-to-ten year viability hinges on substrate diameter transition execution rather than device architecture selection. Watch for METI subsidy allocation shifts as the inflection signal for Japanese manufacturing cluster consolidation pace.
| Strategic Initiative | Industry Significance |
|---|---|
| 6-Inch Wafer Process Development | Enables cost parity with silicon carbide for 650V+ traction inverters at Japanese manufacturing clusters. |
| Backward Integration into Epitaxial Growth | Captures margin pools currently flowing to specialized wafer vendors serving automotive qualification pipelines. |
| AEC-Q101 Certification Investment | Unlocks tier-1 automotive procurement relationships compressed by NHTSA efficiency mandate timelines. |
| Corundum-Structured Alpha-Ga2O3 Licensing | Opens RF amplifier adjacencies for aerospace radar programs evaluating heterostructure integration. |
| CHIPS Act Foundry Construction | Anchors non-Japanese gallium oxide capacity for domestic EV supply chain security under US industrial policy. |
Research Methodology
Desk research of METI policy filings, NHTSA regulatory dockets, and SEC semiconductor equipment disclosures preceded structured interviews with substrate engineering directors, MOCVD equipment specialists, automotive tier-1 procurement leads, and epitaxial process technologists. Primary intelligence combined with secondary validation from patent landscapes, customs trade data, and foundry capacity announcements. Bottom-up wafer shipment estimates and top-down automotive inverter content projections were triangulated against disclosed pilot program volumes.
Assumptions held fixed across the modeling period include substrate diameter transition timelines and automotive platform voltage standardization at 800V architectures. Segmentation dimensions spanned device architecture, crystal polymorph, end-use voltage tier, and regional manufacturing cluster. CAGRs were derived from installed base replacement modeling and new vehicle content penetration curves. Forecast inputs incorporated MOCVD reactor delivery lead times and AEC-Q101 qualification cycle durations.
Stress conditions across gallium precursor price volatility, substrate yield ramp rates, and silicon carbide incumbent pricing response were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory efficiency mandate enforcement and foundry equipment availability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
High Speed Data Converters Market
Semiconductor Devices
Digital Transistor Market
Semiconductor Devices
Global Current Sense Amplifier Market
Semiconductor Devices
IT & Telecom Discrete Semiconductor Market
Semiconductor Devices
Plastic Transistors Market
Semiconductor Devices
Japan MLCC Market
Semiconductor Devices
Leadframes Market
Semiconductor Devices
Gan-On-Silicon Market
Semiconductor Devices
Global Switched Capacitor Filter Market
Semiconductor Devices
Global Semiconductor Lead Frame Market
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Transistor Arrays Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
Gaming GPU Market
Semiconductor Devices
South Korea MLCC Market