
 Global Inorganic Scintillators Market | 2026-2036
Global Inorganic Scintillators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inorganic Scintillators Market Intelligence
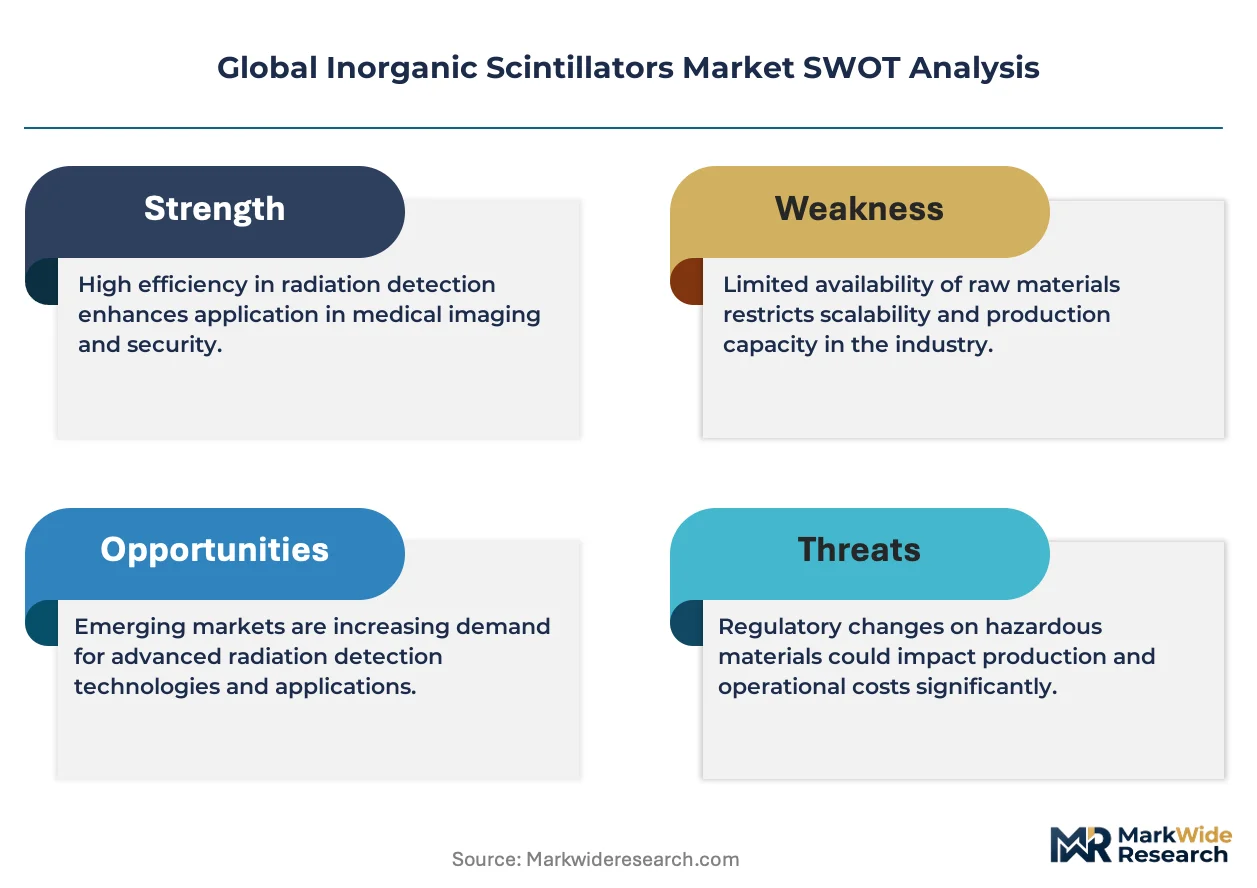
The EU Green Deal is broadening compliance obligations for scintillator manufacturers serving European medical and security markets. Saint-Gobain leverages its integrated crystal growth capabilities to sustain supply continuity for sodium iodide detectors deployed across nuclear medicine networks. Hamamatsu Photonics anchors premium positioning through proprietary photomultiplier tube integration with in-house scintillator arrays. Mirion Technologies competes on radiation monitoring system bundling, extending its reach beyond component sales into integrated detection platforms.
Inorganic scintillators are crystalline materials that convert ionizing radiation into visible photons through luminescence, with typical light yields ranging from thousands to tens of thousands of photons per MeV depending on host lattice and dopant selection; their primary commercial purpose lies in radiation detection and spectroscopy across medical imaging, security screening, and nuclear safeguards applications. Sodium iodide dominates installed base economics due to mature manufacturing and lower unit costs, while lutetium orthosilicate captures margin concentration in PET-CT detector modules where timing resolution requirements justify premium pricing. Security screening applications are accelerating procurement cycles as customs agencies modernize cargo and baggage inspection infrastructure at major transit hubs.
The FDA governs scintillator incorporation into diagnostic imaging devices through 510(k) and PMA pathways, while REACH restricts heavy element sourcing and doping agent chemistry for European manufacturers. Japan's METI enforces domestic content thresholds for radiation detection equipment deployed at nuclear facilities under post-Fukushima safety mandates. Stakeholders must monitor evolving dual-use export controls affecting cesium iodide and bismuth germanate shipments to emerging nuclear programs.
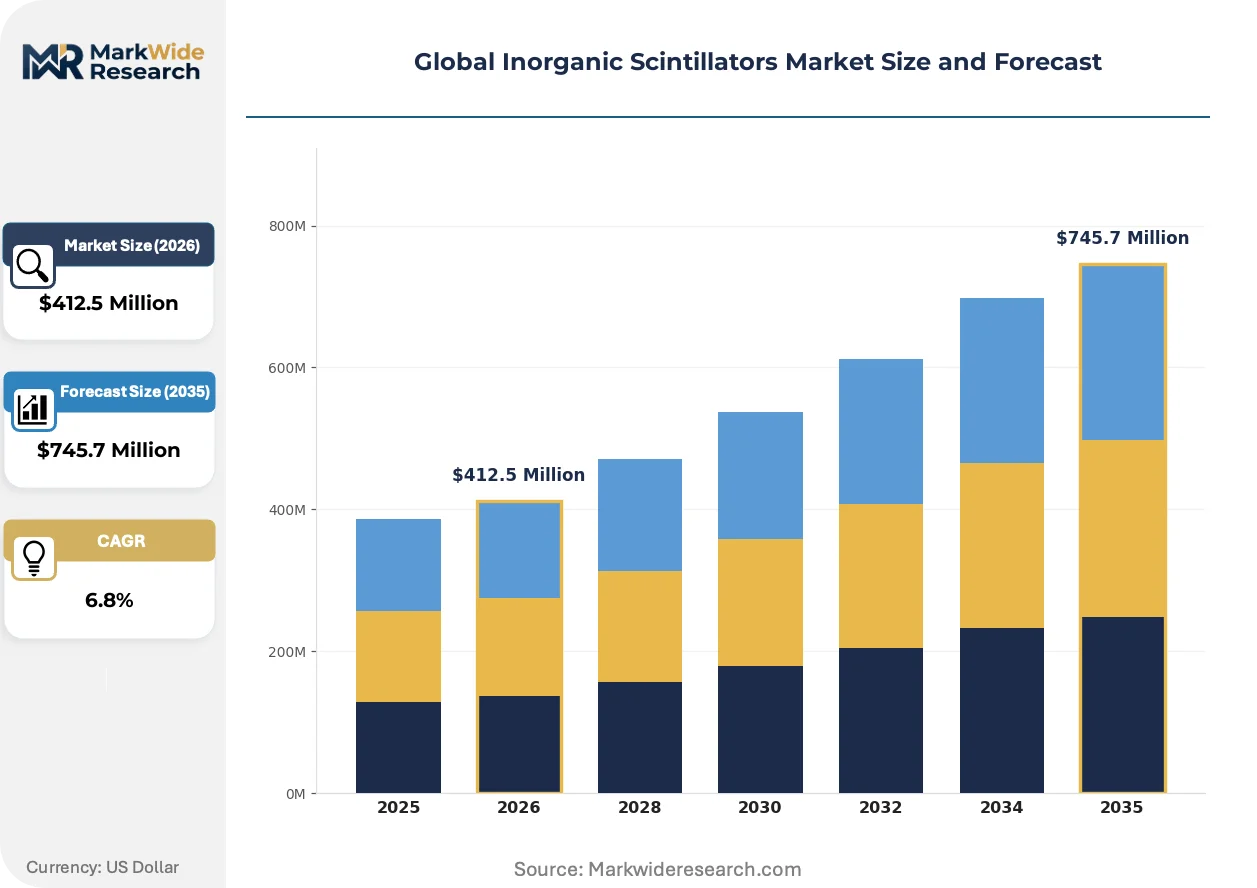
Market Dynamics
Supply concentration in lutetium and cerium feedstock is forcing detector manufacturers to negotiate long-term offtake agreements or pursue backward integration into rare-earth processing, reshaping competitive economics across medical imaging and security screening segments.
Growth Catalysts
- REACH compliance mandates:ECHA enforcement of heavy-element traceability requirements is accelerating replacement cycles for legacy sodium iodide installations in European nuclear medicine networks.
- PET-CT detector upgrades:Timing resolution specifications for lutetium orthosilicate arrays are tightening as oncology departments pursue sub-300 picosecond coincidence windows.
- Japan's METI safety protocols:Post-Fukushima domestic content thresholds for radiation monitoring equipment are sustaining procurement volumes for in-house scintillator production.
Market Restraints
- Rare-earth supply concentration:Lutetium oxide refining capacity concentrates in Chinese state-controlled enterprises, exposing detector manufacturers to export quota volatility.
- High-purity precursor costs:Cerium-doped lanthanide crystals require 5N+ purity metal-organic precursors whose spot pricing fluctuates with semiconductor materials demand.
- Cadmium zinc telluride substitution:Direct-conversion semiconductor detectors are capturing share in gamma spectroscopy applications where energy resolution trumps light yield.
Strategic Opportunities
- Indian nuclear medicine expansion:CDSCO streamlined approval pathways for diagnostic imaging devices are lowering market entry barriers for scintillator-integrated PET systems.
- EU Green Deal material passports:Circular economy disclosure requirements for critical raw materials create first-mover advantage for vertically integrated crystal growers with closed-loop doping agent recovery.
- Neutron-gamma discrimination hybrids:Convergence of lithium-6 loaded glass scintillators with pulse-shape analysis electronics opens safeguards and border inspection applications.
Industry Challenges
- Crystal growth technician scarcity:Czochralski and Bridgman furnace operation expertise concentrates in aging workforces at Saint-Gobain and Hitachi facilities, constraining capacity expansion.
- FDA 510(k) resubmission cycles:Scintillator specification changes trigger 12-18 month requalification timelines for PET-CT OEMs, freezing design iterations mid-development.
- Legacy PMT integration complexity:Photomultiplier tube voltage divider networks from 1990s-era nuclear medicine systems resist retrofit with silicon photomultiplier readouts without full detector head replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inorganic Scintillators Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Iodide, Cesium Iodide, Bismuth Germanate, Lutetium Orthosilicate, Gadolinium Oxyorthosilicate Application: Security Screening, Nuclear Instrumentation, Oil Exploration, High Energy Physics, Non-Destructive Testing End User: Research Laboratories, Military & Defense, Environmental Monitoring Agencies, Radiopharmaceutical Manufacturers, Space Agencies Manufacturing Stage: Crystal Growth, Doping Process, Cutting & Polishing, Assembly, Quality Inspection |
| Companies Covered | Saint-Gobain, Hamamatsu Photonics, Mirion Technologies, Hitachi Metals, Dynasil Corporation, Scintacor, Rexon Components, Toshiba Materials, Shanghai SICCAS High Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inorganic Scintillators Market Strategic Shifts & Innovations
Detector architecture is fragmenting from monolithic crystal blocks toward pixelated arrays with integrated readout electronics, compressing manufacturing batch sizes while multiplying SKU complexity for crystal growers.
Lutetium-yttrium orthosilicate solid solutions are modularizing detector design rules across PET-CT platforms. Siemens Healthineers and GE Healthcare are specifying exchangeable scintillator tiles with standardized mechanical interfaces. This modularity is compressing field service timelines from weeks to days while enabling incremental light-yield upgrades without full gantry replacement.
EU F-Gas Regulation phase-down schedules are forcing manufacturers to abandon perfluorinated cooling fluids in crystal growth furnaces. ECHA guidance documents issued under the Green Deal framework now classify certain fluoride flux chemistries as restricted substances. German and French crystal growers are retrofitting Czochralski pullers with argon recirculation systems, adding 15-20 percent to thermal management capex.
Hospital procurement committees are unbundling scintillator supply from OEM service contracts, directly negotiating multi-year crystal purchases with Saint-Gobain and Dynasil. This disintermediation is compressing distributor margins while exposing detector manufacturers to spot-price volatility in rare-earth feedstock. The pattern is most visible in United States academic medical centers with dedicated nuclear medicine physics staff capable of independent crystal specification.
Global Inorganic Scintillators Market Segmentation
Segmentation reveals how crystal composition, application physics, and end-user procurement authority fragment pricing power across the value chain. Manufacturers must align furnace capacity and doping chemistry with specific detector performance thresholds rather than pursuing horizontal scale.
Product Type:
Material selection pivots on light yield, decay time, and energy resolution trade-offs that determine suitability for timing-critical versus spectroscopy-dominant applications.
- Sodium Iodide:Thallium-doped NaI crystals deliver the highest light yield among commercial scintillators at moderate cost, sustaining dominance in gamma spectroscopy systems deployed across environmental monitoring networks in the United States and Germany. Legacy installed base and mature Czochralski growth economics resist displacement despite inferior timing resolution.
- Lutetium Orthosilicate:Cerium-doped LSO offers sub-40 nanosecond decay constants essential for PET-CT coincidence detection, capturing premium pricing in oncology imaging suites at academic medical centers in Japan and the United States. Timing resolution below 300 picoseconds commands 3-4x unit pricing over sodium iodide equivalents.
- Cesium Iodide:Sodium-doped CsI variants optimize X-ray absorption efficiency for security screening portals at major transit hubs.
- Bismuth Germanate:BGO's high density and photoelectric cross-section serve calorimetry applications in high-energy physics facilities.
- Gadolinium Oxyorthosilicate:GSO's intermediate properties fill niche spectroscopy roles where radiation hardness exceeds priority over timing.
Sodium iodide leads on scale; lutetium orthosilicate leads on momentum.
Application:
End-use physics dictate crystal geometry, readout integration depth, and regulatory qualification burden.
- Security Screening:Customs agencies in the United States, Germany, and Japan are modernizing cargo and baggage inspection infrastructure with high-throughput detector arrays. Procurement cycles compress as border security budgets elevate and dual-use export controls tighten on cesium iodide shipments.
- Nuclear Instrumentation:Post-Fukushima safety mandates from Japan's METI sustain domestic content thresholds for radiation monitoring equipment at nuclear facilities. Scintillator suppliers must demonstrate closed-loop traceability for lutetium and cerium feedstock to satisfy safeguard protocols.
- Oil Exploration:Downhole logging tools employ ruggedized sodium iodide detectors for formation evaluation in shale plays.
- High Energy Physics:CERN and Fermilab specifications drive electromagnetic calorimeter crystal volumes with extreme radiation hardness requirements.
- Non-Destructive Testing:Industrial radiography systems integrate compact cesium iodide arrays for pipeline and weld inspection.
Security screening leads on scale; nuclear instrumentation leads on momentum.
End User:
Procurement authority concentrates differently across institutional buyers with varying technical specification capabilities.
- Radiopharmaceutical Manufacturers:Isotope production facilities in Germany and the United States require high-purity scintillators for quality control of fluorodeoxyglucose and other PET tracers. CDSCO streamlined pathways in India are expanding addressable demand as domestic isotope production scales.
- Military & Defense:Homeland security budgets in the United States sustain radiation portal monitor deployments at ports of entry. Dual-use export controls from the Wassenaar Arrangement constrain supplier eligibility for neutron-gamma discrimination hybrids.
- Research Laboratories:National physics facilities in France, Switzerland, and the United States drive customized crystal development for detector R&D.
- Environmental Monitoring Agencies:EPA and BfS networks employ sodium iodide spectrometry for fallout and contamination surveillance.
- Space Agencies:NASA and ESA missions specify radiation-hardened scintillators for gamma-ray burst observatories with extreme thermal cycling tolerance.
Radiopharmaceutical manufacturing leads on scale; military and defense leads on momentum.
Manufacturing Stage:
Value capture concentrates at stages where technical expertise creates bottlenecks rather than commodity processing.
- Crystal Growth:Czochralski and Bridgman furnace operation expertise concentrates at Saint-Gobain and Hitachi facilities with aging workforces. Technician scarcity constrains capacity expansion despite elevated demand for lutetium-based crystals in PET-CT modules.
- Doping Process:Cerium and thallium activation requires 5N+ purity metal-organic precursors with spot pricing tied to semiconductor materials demand. ECHA REACH restrictions on heavy-element traceability are forcing European growers to qualify alternative dopant chemistries.
- Cutting & Polishing:Dimensional tolerance for pixelated arrays demands sub-micron surface finish control.
- Assembly:Scintillator tile integration with silicon photomultiplier readouts replaces legacy PMT architectures.
- Quality Inspection:Light yield uniformity mapping and radiation hardness validation extend qualification timelines.
Crystal growth leads on scale; doping process leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Inorganic scintillator manufacturing traces its commercial origins to sodium iodide crystal growth operations established in the United States and Germany during the 1950s, with subsequent lutetium-based material development concentrated in Japanese and French facilities serving nuclear medicine expansion.
United States
Academic medical centers in Boston and Houston drive PET-CT detector procurement for oncology imaging suites. FDA 510(k) pathways govern scintillator integration into diagnostic devices, with resubmission timelines extending 12-18 months for specification changes. Domestic crystal growth expertise concentrates at Dynasil facilities in Massachusetts, supplying sodium iodide arrays for environmental monitoring networks.
Germany
Radiopharmaceutical production facilities in Munich and Berlin require high-purity scintillators for fluorodeoxyglucose quality control. ECHA REACH enforcement mandates heavy-element traceability for European nuclear medicine networks, accelerating replacement cycles for legacy installations. Crystal growers in the Rhineland retrofit Czochralski furnaces with argon recirculation systems to comply with EU F-Gas Regulation phase-down schedules.
Japan
Post-Fukushima safety protocols from METI sustain domestic content thresholds for radiation monitoring equipment at nuclear facilities in Fukui and Niigata prefectures. Hitachi maintains in-house scintillator production capabilities to satisfy safeguard requirements. Hamamatsu Photonics anchors premium positioning through proprietary photomultiplier tube integration with detector arrays.
China
State-controlled enterprises dominate lutetium oxide refining capacity, exposing international detector manufacturers to export quota volatility. Shanghai SICCAS High Technology Corporation represents domestic crystal growth capabilities serving regional security screening and medical imaging demand. Customs modernization at Shanghai and Shenzhen ports drives procurement of high-throughput detector arrays.
India
CDSCO streamlined approval pathways for diagnostic imaging devices lower market entry barriers for PET system integrators. Domestic isotope production scaling in Mumbai and Hyderabad expands addressable demand for quality control scintillators. Hospital procurement committees increasingly unbundle crystal supply from OEM service contracts, negotiating directly with international growers.
Global Inorganic Scintillators Market Key Industry Players
Premium-margin players sit above commodity-margin players across timing resolution performance tiers, with sub-300 picosecond coincidence window specifications commanding 3-4x unit pricing over sodium iodide equivalents. The vendor base stratifies into integrated crystal growth specialists, detector system bundlers, and component distributors. Three archetypes dominate: vertically integrated furnace operators with rare-earth processing capabilities, photomultiplier tube manufacturers backward-integrated into scintillator arrays, and radiation monitoring system integrators extending beyond component sales. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with long-term offtake agreements for lutetium and cerium feedstock reshaping supply economics.
Among integrated specialists, Saint-Gobain represents the furnace-operation archetype with established sodium iodide and lutetium orthosilicate capabilities. Hamamatsu Photonics occupies a premium-tier position through photomultiplier tube integration expertise. Mirion Technologies exemplifies the system-bundling archetype, competing on radiation monitoring platform extension rather than component sales alone. These three anchors demonstrate how technical specialization and integration depth determine margin capture across medical imaging and security screening segments.
| Leading Market Players |
|---|
| Saint-Gobain |
| Hamamatsu Photonics |
| Mirion Technologies |
| Hitachi Metals |
| Dynasil Corporation |
| Scintacor |
| Rexon Components |
| Toshiba Materials |
| Shanghai SICCAS High Technology Corporation |
| Others |
Cost & Logistics Intelligence
Lutetium oxide feedstock costs cascade through three distinct pricing tiers as Chinese state-controlled refiners exert leverage over detector manufacturers negotiating long-term offtake agreements for PET-CT crystal production.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates cerium-doped lutetium orthosilicate arrays from thallium-activated sodium iodide blocks and undoped cesium iodide security panels. Timing resolution below 300 picoseconds commands substantial premiums at academic medical centers in Japan and the United States, while environmental monitoring agencies in Germany prioritize unit economics over performance margins. Cost compression in the sodium iodide tier is intensifying because hospital procurement committees are unbundling crystal supply from OEM service contracts and negotiating directly with growers.
Supply Chain Analysis
Single-source vulnerability sits with Chinese state-controlled enterprises dominating lutetium oxide refining capacity and cerium metal-organic precursor production. Crystal growth expertise concentrates in France, Japan, and the United States, with Saint-Gobain and Hitachi facilities housing aging technician workforces. Supply chain risk centers on export quota volatility from Beijing affecting rare-earth availability. Distribution runs through radiopharmaceutical manufacturers, PET-CT OEMs, and homeland security integrators with diverging specification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in lutetium-based crystal tiers as oncology departments upgrade coincidence detection specifications and security agencies modernize cargo inspection infrastructure.
For Market Incumbents: To counter cadmium zinc telluride substitution in gamma spectroscopy applications, Saint-Gobain and Hamamatsu Photonics should deepen backward integration into rare-earth processing and accelerate silicon photomultiplier readout integration to displace legacy PMT architectures in installed nuclear medicine systems. For New Entrants and Emerging Players: Launch via direct hospital procurement relationships in India where CDSCO streamlined pathways lower PET system integration barriers. White-space targets include quality control scintillators for domestic isotope production facilities in Mumbai and Hyderabad, plus neutron-gamma discrimination hybrids for safeguards applications underserved by incumbent system bundlers. For Investors and Strategic Acquirers: Roll-up economics work for specialized crystal growth boutiques because technician scarcity at established furnace operators constrains capacity expansion despite elevated demand. Acquisition targets include European Czochralski specialists with argon recirculation retrofit capabilities and Indian distributors with hospital procurement committee relationships. The signal to watch is ECHA enforcement intensity accelerating replacement cycles for legacy sodium iodide installations.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Lutetium Offtake Agreement | Secures feedstock continuity against Chinese export quota volatility for PET-CT crystal production. |
| Silicon Photomultiplier Integration | Replaces legacy PMT voltage divider networks to enable sub-300 picosecond timing resolution specifications. |
| Argon Recirculation Retrofit | Complies with EU F-Gas Regulation phase-down schedules for Czochralski furnace thermal management. |
| Direct Hospital Procurement Channel | Bypasses OEM service contract bundling to capture margin compression from unbundling trends in academic medical centers. |
| Neutron-Gamma Discrimination Hybrid Development | Opens safeguards and border inspection applications through lithium-6 loaded glass scintillator convergence with pulse-shape analysis electronics. |
Research Approach
Direct dialogue with crystal growth technicians, PET-CT biomedical engineers, hospital procurement managers, radiopharmaceutical quality control directors, and homeland security integrators combined with bottom-up and top-down triangulation against ECHA REACH guidance documents, FDA 510(k) filing databases, METI safety protocol announcements, CDSCO approval registries, and rare-earth trade flow customs records.
Bottom-up modeling of unit volumes by crystal composition, application physics, and end-user procurement authority converged with top-down macro validation across the projection horizon. Segmentation dimensions included material type, detector performance tier, geographic regulatory cluster, and manufacturing stage value capture. CAGRs were derived from installed base replacement cycles, nuclear medicine infrastructure expansion, and security screening modernization procurement patterns.
Several conditions sit outside the modeled scope, including sudden rare-earth export restrictions, breakthrough direct-conversion semiconductor cost reductions, and Fukushima-scale regulatory regime shifts. Forecasts reflect assumptions about technician workforce continuity, furnace capacity utilization, and dual-use export control stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Middle East Silicon Carbide (Sic) Market
Semiconductor Material
India Liquid Silicon Rubber Market
Semiconductor Material
Encapsulant Market
Semiconductor Material
Global Gallium Nitride Market
Semiconductor Material
Europe Silicone Market
Semiconductor Material
Indium Gallium Zinc Oxide Market
Semiconductor Material
Electronic Thermal Management Materials Market
Semiconductor Material
PV Module Encapsulant Film Market
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
Solar Silicon Ingots Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
Yttrium Oxide Market
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
Tungsten Market