
 Electronic Ceramics Market | 2026-2036
Electronic Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Ceramics Market Intelligence
Aftermarket service revenue for ceramic component testing and failure analysis is reconfiguring margin pools away from pure volume manufacturing. Murata Manufacturing Co., Ltd. leverages its captive MLCC production network to dominate high-frequency telecommunications substrates. Kyocera Corporation anchors industrial ceramic packages through backward integration into raw material synthesis. CeramTec GmbH specializes in medical-grade piezoelectric assemblies that command premium positioning over standard consumer grades.
Electronic ceramics denote inorganic, non-metallic materials processed through sintering at temperatures exceeding 1,200°C to achieve controlled dielectric, piezoelectric, or magnetic properties for signal management and power conversion. Ceramic capacitors constitute the largest product category by shipment volume, though dielectric ceramics for 5G base station filters capture disproportionate margin as frequency requirements intensify. Piezoelectric ceramics represent the fastest-expanding product segment, driven by ultrasonic sensor deployment in automotive electronics and industrial non-destructive testing equipment.
Japan's METI enforces JIS standards for electronic ceramic reliability, while REACH and RoHS in Europe restrict hazardous substances in dielectric formulations, compelling reformulation investments. The EU Green Deal's embodied carbon tracking requirements are reshaping supplier qualification criteria for automotive OEMs. Stakeholders must monitor how China's GB standards evolution and SAMR certification timelines affect cross-border component flows and localized production decisions.
Market Dynamics
Automotive electrification is compressing ceramic component qualification timelines as EV powertrains demand higher thermal tolerance and voltage stability from dielectric substrates.
Growth Catalysts
- EV Powertrain Proliferation:Battery management systems and onboard chargers require MLCC densities that legacy automotive electronics never demanded.
- REACH RoHS Reformulation Mandates:Europe's hazardous substance restrictions are accelerating lead-free piezoelectric ceramic adoption across consumer and industrial grades.
- 5G Infrastructure Deployment:Base station filter manufacturers in Japan's Kansai corridor are scaling dielectric ceramic capacity for millimeter-wave frequency bands.
Market Restraints
- Raw Material Concentration:High-purity barium titanate and rare-earth dopant supply chains cluster in China's Jiangxi and Hunan provinces.
- Sintering Energy Intensity:Kiln operations exceeding 1,200°C face escalating natural gas and electricity input costs.
- Technical Performance Ceiling:Lead-free piezoelectric formulations still exhibit lower electromechanical coupling coefficients than legacy PZT compositions.
Strategic Opportunities
- Medical Ultrasound Expansion:Piezoelectric ceramic arrays for high-frequency imaging transducers command pricing multiples over standard consumer grades.
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging are drawing ceramic substrate investments to Gujarat and Karnataka.
- EU Green Deal Embodied Carbon Tracking:Automotive OEM supplier qualification criteria now reward low-carbon ceramic sintering processes.
Industry Challenges
- Materials Science Talent Scarcity:Formulation chemists with expertise in grain boundary engineering and dopant optimization remain concentrated in Japan and Germany.
- Multi-Jurisdictional Certification Burden:Component suppliers must synchronize JIS reliability testing, REACH substance declarations, and SAMR GB standard compliance for cross-border shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Ceramics Market |
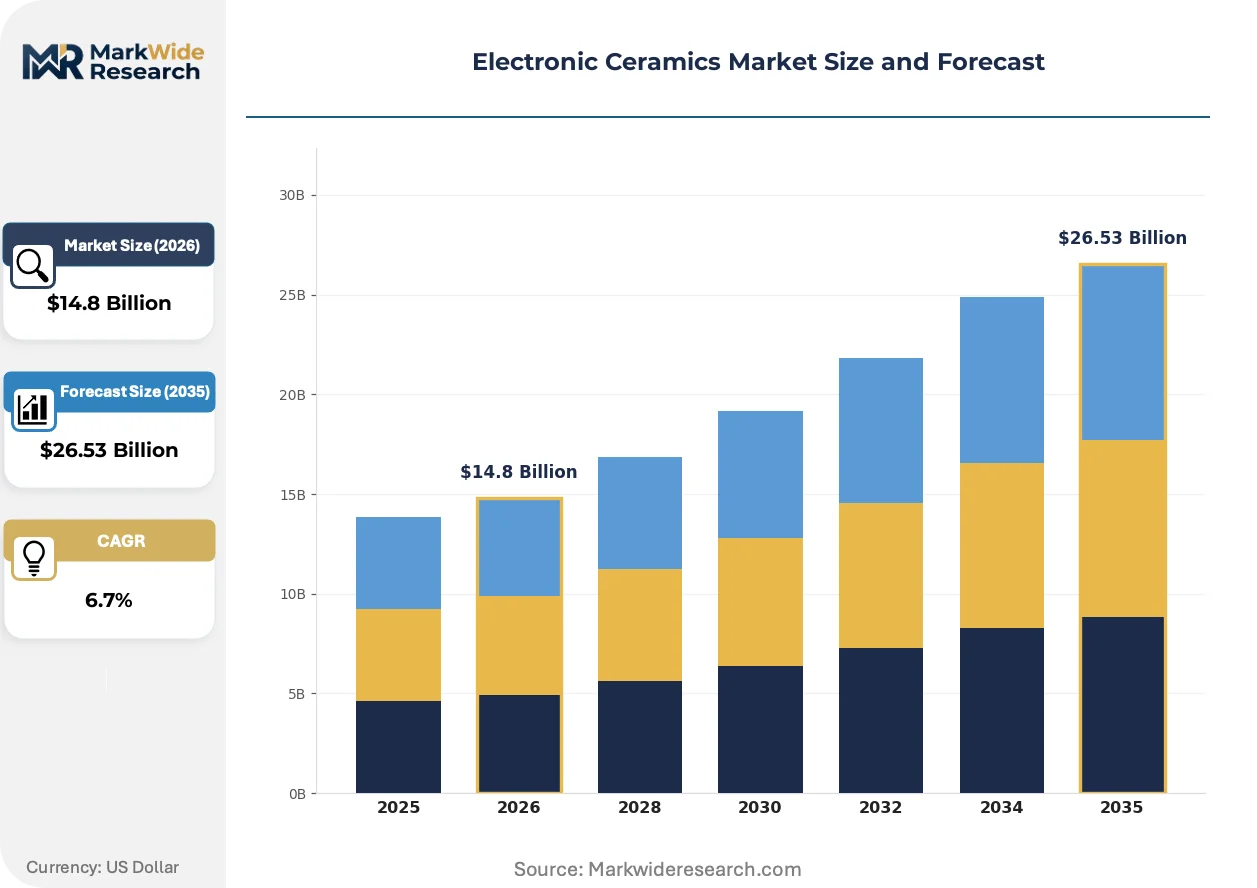
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Capacitors, Piezoelectric Ceramics, Magnetic Ceramics, Dielectric Ceramics Application: Consumer Electronics, Telecommunications, Automotive Electronics, Industrial Equipment End User: Manufacturers, OEMs, Distributors, Research Institutions Technology: Advanced Ceramics, Insulating Ceramics, Conductive Ceramics, Semi-conductive Ceramics |
| Companies Covered | Murata Manufacturing Co., Ltd., Kyocera Corporation, CeramTec GmbH, Morgan Advanced Materials, CoorsTek Inc., MARUWA Co., Ltd., APC International, TDK Corporation, NGK Insulators, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Ceramics Market Strategic Shifts & Innovations
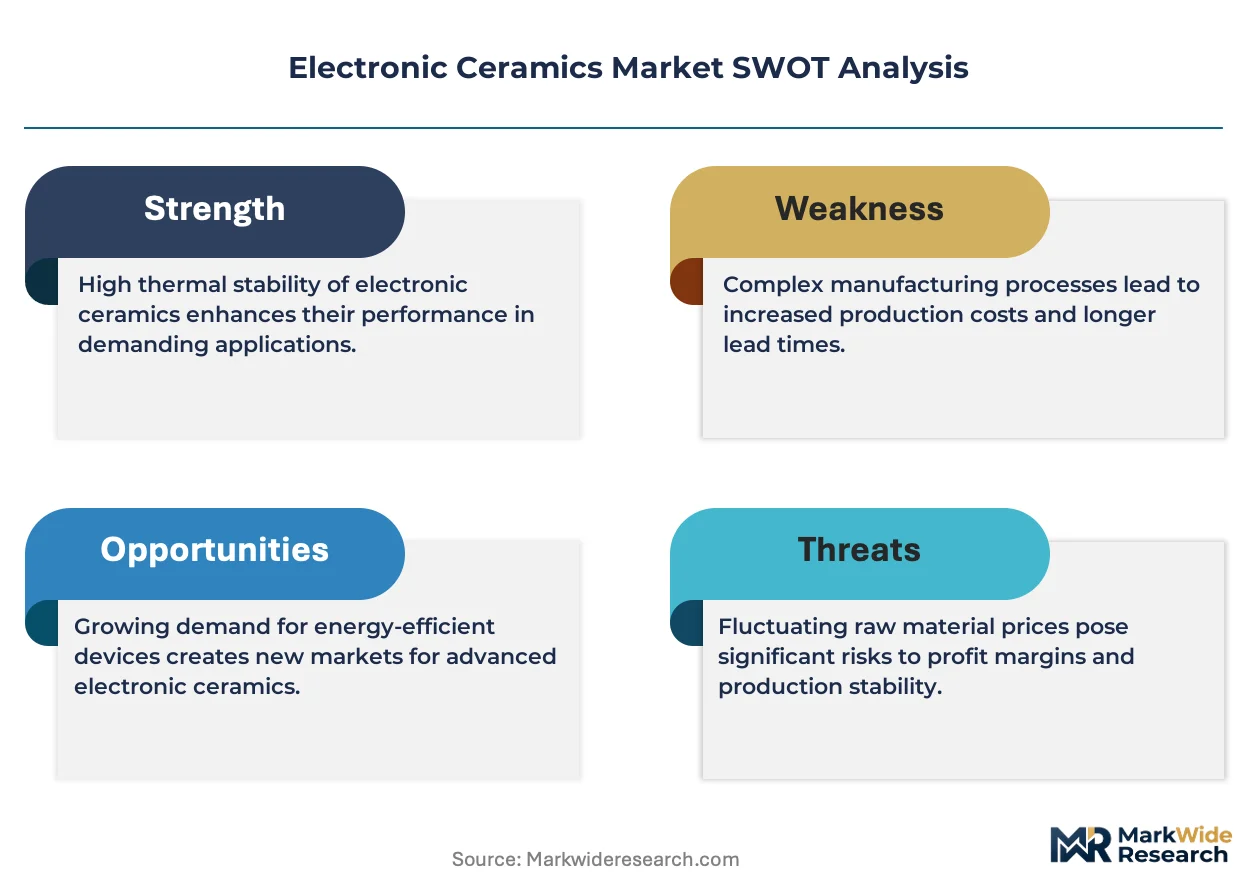
Material science breakthroughs and regulatory chemistry mandates are rewriting competitive boundaries between legacy ceramic families and next-generation formulations.
Lead-free piezoelectric compositions based on potassium sodium niobate (KNN) and bismuth sodium titanate (BNT) are achieving electromechanical performance parity with lead zirconate titanate (PZT) in ultrasonic sensor applications. Automotive Tier-1 suppliers in Germany and Japan are qualifying these formulations for parking assistance and cabin occupancy detection systems. The transition is rendering obsolete decades of PZT-dominant intellectual property and process equipment investments.
China's GB standards evolution under SAMR oversight is tightening allowable lead content thresholds in electronic ceramics for domestic consumption. Manufacturers serving both export and domestic markets face dual-track formulation strategies that fragment production runs and complicate inventory management. Dielectric ceramic producers with integrated raw material synthesis capabilities are absorbing compliance costs more efficiently than merchant compounders.
Aftermarket service unbundling is separating ceramic component testing and failure analysis from original equipment supply contracts. Independent laboratories in South Korea's Gyeonggi province and Taiwan's Hsinchu Science Park are capturing margin pools that manufacturers previously retained. This shift is most pronounced in telecommunications infrastructure, where base station operators demand localized diagnostic capabilities to minimize network downtime.
Electronic Ceramics Market Segmentation
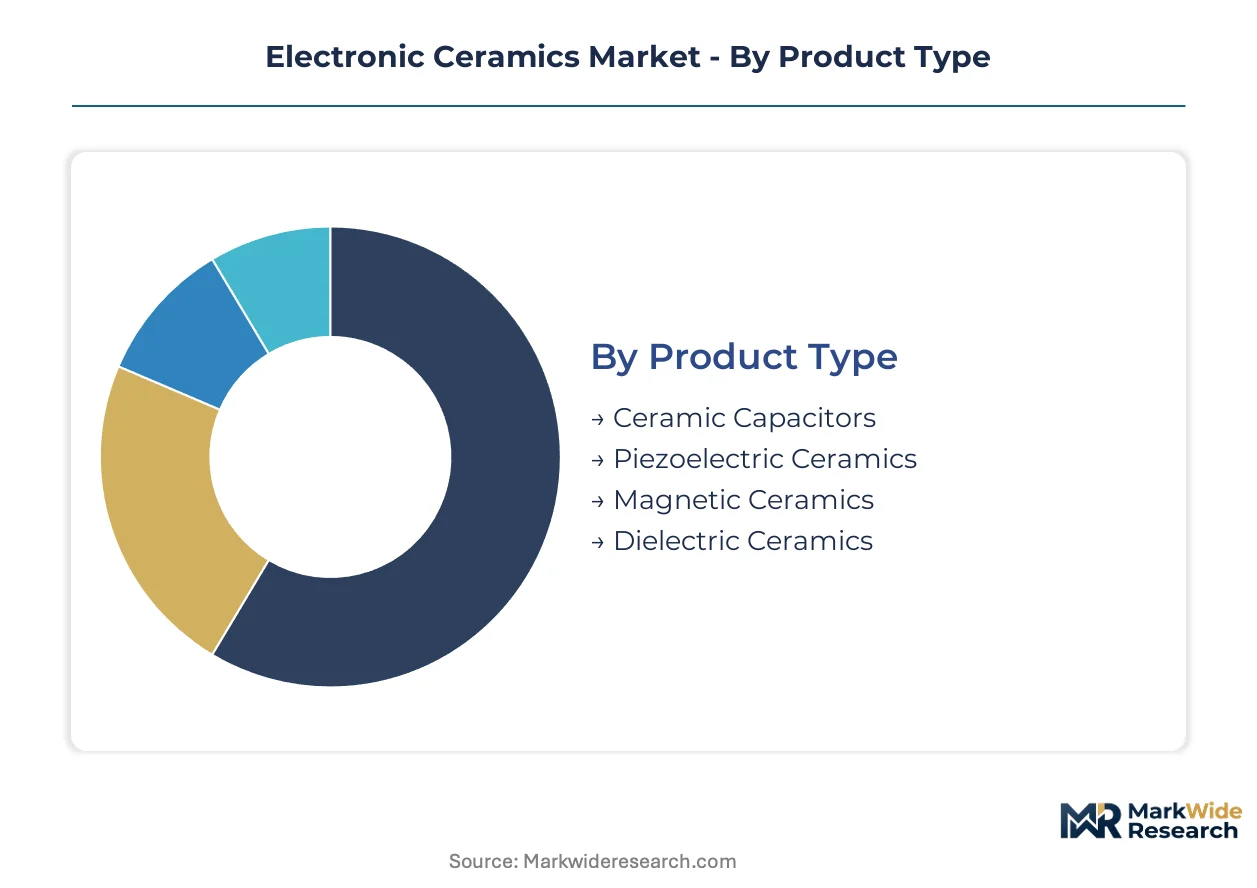
Electronic ceramics segmentation reveals divergent inventory velocities and margin profiles across product families. Dielectric and piezoelectric formulations turn over at markedly different rates due to qualification timelines and end-use volatility. Understanding these cycle-time differentials shapes capacity planning and working capital allocation for compounders and substrate fabricators.
Product Type:
Ceramic capacitors rotate inventory fastest due to standardized JIS reliability testing and high-volume consumer electronics offtake, while piezoelectric ceramics face extended automotive qualification cycles. Dielectric ceramics for telecommunications infrastructure occupy intermediate turnover positions tied to 5G base station deployment cadences.
- Ceramic Capacitors:Multi-layer ceramic chip devices dominate shipment volumes through sintered barium titanate dielectric layers with nickel internal electrodes. Consumer electronics manufacturers in Japan's Kansai corridor and South Korea's Gyeonggi province absorb the highest volumes for smartphone and tablet motherboards, though EV battery management systems are now demanding automotive-grade temperature-stable formulations that extend qualification timelines.
- Piezoelectric Ceramics:Lead zirconate titanate and emerging potassium sodium niobate compositions convert mechanical stress to electrical signals for ultrasonic transducers. Automotive Tier-1 suppliers in Germany and Japan are qualifying lead-free formulations for parking assistance sensors, stretching development cycles as electromechanical coupling coefficients approach parity with legacy PZT.
- Magnetic Ceramics:Ferrite cores for inductors and transformers serve power conversion applications with moderate inventory velocity tied to industrial equipment replacement schedules.
- Dielectric Ceramics:Low-loss formulations for 5G millimeter-wave filters command extended production lead times due to tight dimensional tolerances and substrate purity requirements.
Ceramic capacitors anchor the volume base while piezoelectric ceramics gain share at the steepest rate.
Application:
Automotive electronics commands the highest specification tier and longest qualification horizons, while consumer electronics drives volume throughput with compressed development cycles. Telecommunications infrastructure sits between these extremes with multi-year deployment timelines but standardized filter architectures.
- Consumer Electronics:Smartphones, tablets, and wearables consume MLCCs in densities exceeding 1,000 units per device. Assembly plants in Vietnam and Mexico are absorbing growing volumes as manufacturing diversifies beyond East Asian concentrations.
- Automotive Electronics:EV powertrains and advanced driver-assistance systems multiply ceramic component counts per vehicle. Onboard chargers and DC-DC converters require dielectric substrates with voltage ratings and thermal tolerance that consumer-grade formulations cannot satisfy.
- Telecommunications:Base station filters for 5G millimeter-wave bands utilize temperature-compensated dielectric ceramics. Japan's Kansai corridor manufacturers are scaling capacity for 28 GHz and 39 GHz frequency deployments.
- Industrial Equipment:Piezoelectric sensors for non-destructive testing and process automation generate steady replacement demand with moderate technical specification requirements.
Consumer electronics generates the highest unit volumes while automotive electronics expands most quickly.
End User:
OEMs impose the most stringent qualification protocols and captive sourcing requirements, while distributors buffer inventory volatility for smaller manufacturers. Research institutions drive experimental volume for next-generation formulations with irregular procurement patterns.
- Manufacturers:Merchant compounders and substrate fabricators purchase raw barium titanate and rare-earth dopants for in-house ceramic production.
- OEMs:Murata Manufacturing and Kyocera Corporation maintain captive ceramic production networks to secure supply continuity for telecommunications and automotive programs.
- Distributors:Arrow Electronics and Avnet buffer MLCC inventory for mid-tier electronics manufacturers lacking direct supplier relationships.
- Research Institutions:Universities and national laboratories prototype lead-free piezoelectric compositions under Japan's METI and Germany's BMBF funding programs.
OEMs dominate value capture while distributors handle the highest transaction frequency.
Technology:
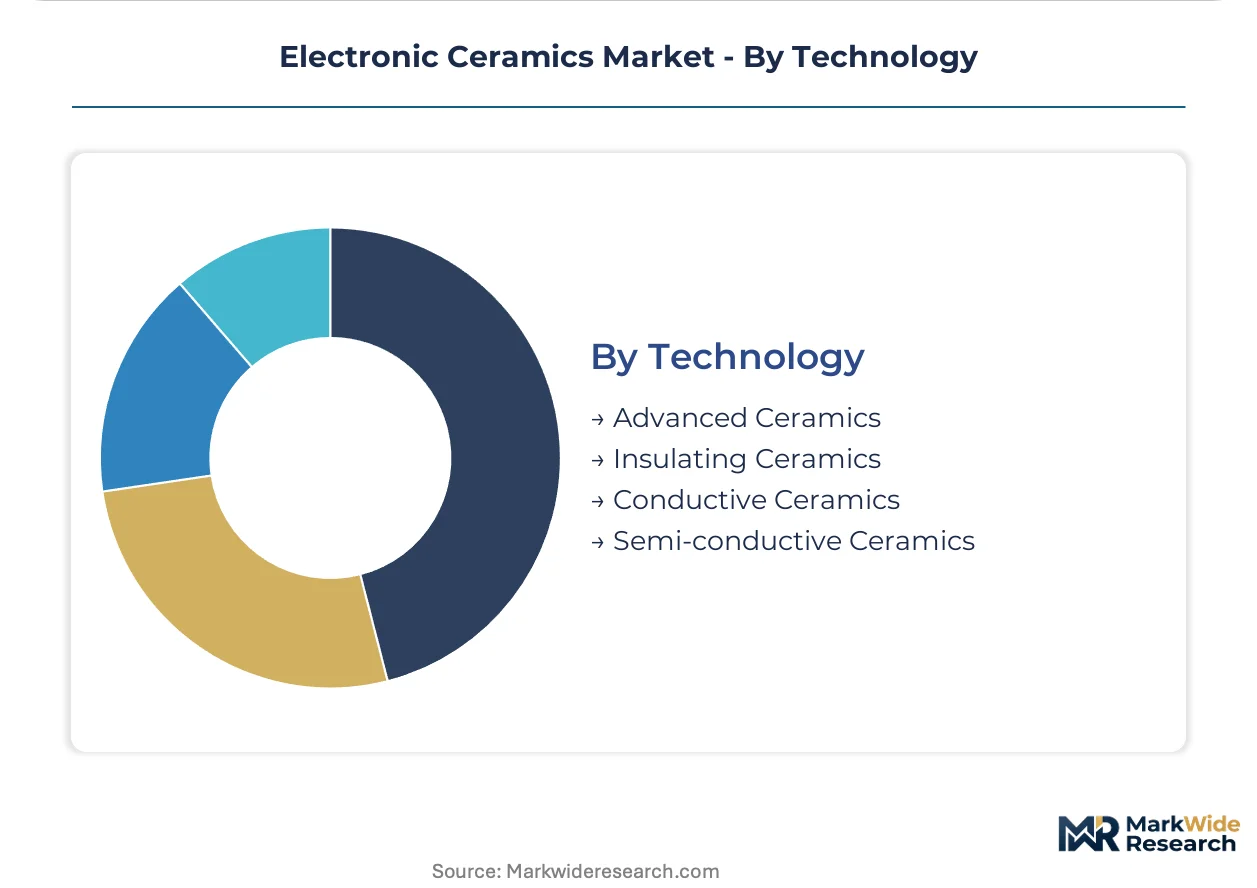
Advanced ceramics command premium positioning through proprietary grain boundary engineering, while insulating ceramics serve commoditized applications with price-sensitive procurement. Conductive and semi-conductive formulations occupy specialized niches with concentrated supplier bases.
- Advanced Ceramics:Engineered microstructures with controlled porosity and dopant distribution achieve superior dielectric or piezoelectric performance. Kyocera Corporation and CeramTec GmbH specialize in medical-grade and aerospace-qualified formulations.
- Insulating Ceramics:Alumina and aluminum nitride substrates provide thermal management and electrical isolation for power modules. Standardized specifications enable multi-source procurement.
- Conductive Ceramics:Lanthanum-doped barium titanate and similar formulations serve sensor and heating element applications.
- Semi-conductive Ceramics:Positive temperature coefficient thermistors and varistors protect circuits from overcurrent and overvoltage conditions.
Insulating ceramics anchor the volume base while advanced ceramics gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Japanese manufacturers prioritize high-reliability formulations for telecommunications infrastructure, while Chinese producers emphasize cost-optimized dielectric ceramics for consumer electronics volume. European demand concentrates on lead-free piezoelectric compositions driven by REACH compliance mandates.
Japan
Automotive electronics and 5G telecommunications infrastructure absorb the highest-specification ceramic substrates. METI enforces JIS reliability standards that extend qualification timelines for EV powertrain components. The Kansai corridor around Osaka anchors dielectric ceramic production for millimeter-wave base station filters.
China
Domestic EV production and consumer electronics assembly drive MLCC consumption at unprecedented scale. SAMR's GB standards evolution and MEE emissions enforcement are tightening lead-content thresholds for ceramics sold domestically. Jiangxi and Hunan provinces concentrate high-purity barium titanate and rare-earth dopant supply chains.
Germany
Automotive Tier-1 suppliers qualify lead-free piezoelectric formulations for ultrasonic sensors and battery management systems. The EU Green Deal's embodied carbon tracking requirements are reshaping supplier qualification criteria for OEMs. Bavaria-based ceramic fabricators specialize in medical-grade and industrial sensor applications.
South Korea
Semiconductor packaging and memory module substrates generate concentrated demand for advanced dielectric ceramics. MFDS oversight of medical device components intersects with industrial ceramic applications in diagnostic imaging equipment. The Gyeonggi province cluster houses captive MLCC production networks serving domestic electronics conglomerates.
United States
Defense electronics and aerospace applications sustain demand for high-reliability ceramic packages with extended temperature ranges. FCC spectrum allocations for 5G millimeter-wave bands are driving base station filter deployments. The Pacific Northwest and Southwest regions concentrate specialty ceramic research funded by national laboratory programs.
Electronic Ceramics Market Key Industry Players
Capability concentration sits with integrated compounders possessing captive raw material synthesis; scale advantage sits with high-volume MLCC manufacturers serving consumer electronics. The market structures around three tiers: vertically integrated Japanese conglomerates, European specialists in medical and industrial grades, and emerging Asian compounders. Dominant competitive moves include backward integration into rare-earth dopant supply and geographic diversification of sintering capacity to manage energy cost volatility.
Within the integrated Japanese tier, Murata Manufacturing Co., Ltd. and Kyocera Corporation exemplify archetypes of captive production network operators. CeramTec GmbH represents the European specialist model focused on premium-grade formulations. These three anchors illustrate how competitive positioning diverges between scale-driven consumer electronics supply and specification-driven automotive and medical segments.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| Kyocera Corporation |
| CeramTec GmbH |
| Morgan Advanced Materials |
| CoorsTek Inc. |
| MARUWA Co., Ltd. |
| APC International |
| TDK Corporation |
| NGK Insulators, Ltd. |
| Others |
Cost & Logistics Intelligence
Jiangxi province's high-purity barium titanate refineries feed captive synthesis operations at Murata Manufacturing and Kyocera Corporation, concentrating upstream pricing power among vertically integrated Japanese conglomerates while merchant compounders absorb raw material cost volatility through quarterly contract renegotiations.
Pricing Analysis
Long-term offtake agreements dominate procurement for automotive-grade dielectric ceramics, with EV battery management system suppliers locking in eighteen-month price commitments to secure thermal-stable MLCC volumes. Pricing stratifies across automotive-qualified, telecommunications-grade, and consumer electronics tiers, with JIS-certified formulations commanding substantial premiums over standard commercial grades. Cost compression in consumer-grade MLCCs is intensifying because Vietnamese and Mexican assembly plants are consolidating purchasing through distributor networks. Tier-1 automotive suppliers exhibit the lowest price sensitivity due to qualification lock-in effects, while mid-tier consumer electronics manufacturers remain highly responsive to spot-market fluctuations.
Supply Chain Analysis
Extended payment terms from automotive OEMs are forcing ceramic substrate fabricators to utilize supply-chain finance facilities, stretching working capital cycles for merchant producers without captive raw material synthesis. Production gravity centers on Japan, China, and South Korea, with Jiangxi and Hunan provinces anchoring rare-earth dopant refining and the Kansai corridor housing dielectric ceramic finishing. Sintering operations draw from high-purity barium titanate, nickel electrode pastes, and rare-earth oxide dopants. Single-source vulnerability concentrates in China's ion-adsorption clay deposits for heavy rare-earth elements. Distribution runs through Arrow Electronics and Avnet for mid-tier manufacturers, while OEMs maintain direct supplier relationships with integrated compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive OEMs and telecommunications infrastructure operators, as EV platform standardization and 5G base station deployment timelines concentrate procurement volumes among fewer purchasing decision-makers.
For Market Incumbents: Entrench formulation expertise in lead-free piezoelectric compositions as potassium sodium niobate patents expire and Chinese compounders challenge legacy PZT dominance. Backward integration into rare-earth dopant supply buffers against Jiangxi province export restriction risks. Prioritize JIS reliability certification investments to maintain automotive qualification barriers against emerging Asian producers. For New Entrants and Emerging Players: Establish a beachhead in medical-grade piezoelectric assemblies where CeramTec GmbH's premium positioning leaves mid-tier pricing gaps for imaging transducer arrays. India's PLI scheme incentives for semiconductor packaging in Gujarat and Karnataka offer the most penetrable geography for substrate fabrication entry. Pursue joint development agreements with German automotive Tier-1 suppliers seeking dual-source qualification for lead-free ultrasonic sensors. For Investors and Strategic Acquirers: Long-term, this sits as a materials science consolidation play because formulation chemistry talent scarcity in grain boundary engineering concentrates competitive moats among Japanese and German specialists. Acquisition targets should emphasize integrated compounders with captive raw material synthesis and existing automotive qualification pipelines. Monitor SAMR GB standards enforcement timelines as the critical signal for domestic Chinese market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Supply | Secures dopant access against China's Jiangxi export licensing volatility. |
| Lead-Free Formulation Certification | Qualifies KNN compositions for REACH-compliant European automotive programs. |
| Medical-Grade Production Capacity | Captures premium pricing multiples in diagnostic imaging transducer markets. |
| India Manufacturing Footprint | Accesses PLI scheme incentives for semiconductor substrate packaging. |
| Aftermarket Testing Service Expansion | Captures margin pools as base station operators unbundle diagnostic contracts. |
Research Approach
Desk research of customs trade databases, METI technical bulletins, and SAMR regulatory filings preceded structured interviews with ceramic formulation chemists, automotive Tier-1 procurement directors, telecommunications infrastructure operators, and medical device OEM quality managers. Primary fieldwork combined with secondary validation against SEC 10-K disclosures, Japan Ceramics Association production statistics, and EU ECHA substance restriction updates. Bottom-up capacity modeling triangulated against top-down consumption estimates across dielectric and piezoelectric product families.
Assumptions held fixed include current REACH and RoHS substance restriction frameworks, while variables encompassed China's GB standards evolution pace and automotive electrification penetration rates. The analytical framework segmented by product type, application, and end-user archetype across the projection horizon. CAGRs derived from regression analysis of historical shipment volumes against EV production forecasts and 5G base station deployment cadences. Key inputs included sintering energy cost trajectories and rare-earth oxide price indices.
Sensitivities concentrate around Chinese environmental enforcement intensity and automotive qualification timeline compression. Forecasts reflect documented assumptions regarding raw material supply continuity and regulatory chemistry mandates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Semiconductor Glass Market
Semiconductor Material
Gallium Market
Semiconductor Material
Indium Gallium Zinc Oxide Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
Ultra High Purity Silicon Carbide Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Chalcocite-Digenite Group Market
Semiconductor Material
Electronic Assembly Materials Market
Semiconductor Material
Rhenium Market
Semiconductor Material
Graphene Oxide (GO) Market
Semiconductor Material
Organic Silicon Coating Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Global Semiconductor Epoxy Mold Compound Market
Semiconductor Material
North America Silicone Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Indium Market