
 Global Semiconductor Epoxy Mold Compound Market | 2026-2036
Global Semiconductor Epoxy Mold Compound Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Epoxy Mold Compound Market Outlook
Market Context
REACH is decoupling legacy formulations from the European supply base by restricting bisphenol-A derivatives and halogenated hardeners. Sumitomo Bakelite Co., Ltd. leverages its captive phenolic resin technology to preempt compliance costs. Samsung SDI Co., Ltd. anchors its position through backward integration into high-purity epoxy monomers in South Korea. Eternal Materials Co., Ltd. specializes in low-alpha emission grades for memory packaging, navigating the tightening purity thresholds set by major foundry customers.
Technical Definition and Segment Structure
Semiconductor epoxy mold compound is a thermosetting formulation combining epoxy resin, phenol novolac hardener, silica filler, and curing accelerators, designed to encapsulate integrated circuits against moisture, thermal stress, and mechanical shock during operation. Transfer molding dominates volume throughput for legacy leadframe packages, while compression molding captures the fastest expansion as fan-out wafer-level packaging displaces traditional substrate-based assembly. In application terms, power devices command premium pricing due to ceramic-filled thermal conductivity requirements, whereas LED packaging remains a mature, cost-commoditized segment where formulators compete on granule flow consistency.
Regulatory Framework
EPA toxics rules, EU RoHS substance restrictions, and China's GB standards on electronic chemical emissions collectively elevate formulation disclosure burdens and restrict certain flame retardant chemistries. Japan's METI circular economy guidelines additionally press suppliers toward bio-based epoxy precursors and solvent recovery systems. Stakeholders must monitor how overlapping jurisdictional requirements on halogen content and carbon footprint disclosure reshape supplier qualification timelines and regional sourcing decisions.
Market Dynamics
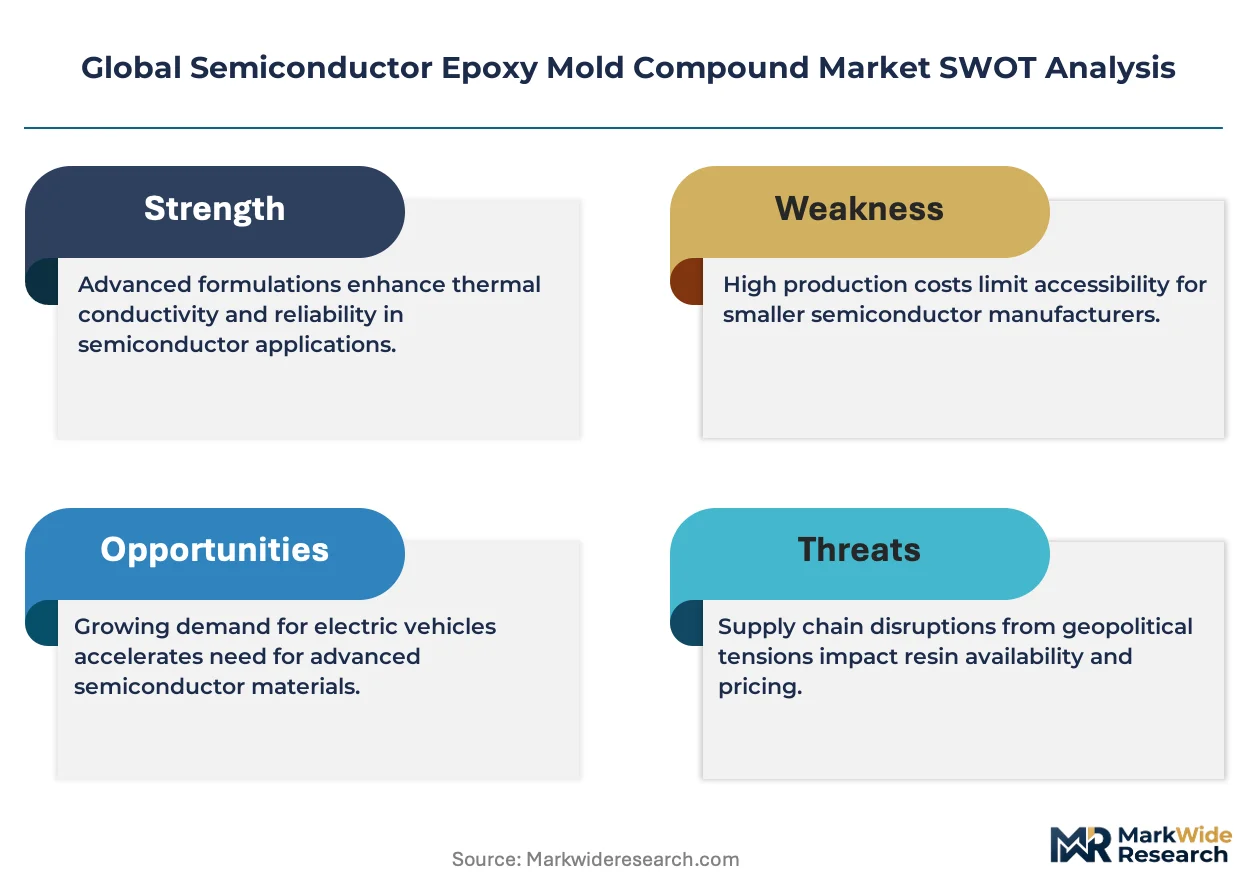
Automotive electrification is compressing qualification timelines for epoxy mold compounds as EV powertrain modules demand thermal cycling endurance beyond legacy consumer-grade specifications. Foundry customers now mandate 175°C continuous operation ratings that force formulators to redesign silica filler loadings and hardener chemistries.
Growth Catalysts
- EV Powertrain Thermal Requirements:Electric vehicle inverters and onboard chargers require ceramic-filled compounds with thermal conductivity above 3 W/mK, pulling formulation innovation away from standard memory packaging grades.
- REACH Substance Restrictions:ECHA's tightening controls on bisphenol-A derivatives and halogenated flame retardants are disqualifying incumbent suppliers and creating qualification slots for compliant alternatives.
- Advanced Packaging Migration:Fan-out wafer-level packaging adoption in South Korea and Taiwan is displacing transfer molding with compression molding processes that demand low-viscosity, ultra-fine filler compounds.
Market Restraints
- High-Purity Silica Concentration:Ultra-low alpha particle silica sources concentrate in Japanese and German mining operations, exposing compounders to geographic supply risk and price volatility.
- Epoxy Monomer Import Dependence:China's dual carbon goals from MEE are capping domestic epoxy resin capacity expansion, forcing compounders to source monomers from South Korean petrochemical complexes at premium freight costs.
- Ceramic Filler Loading Limits:Power device thermal conductivity targets above 5 W/mK hit mechanical reliability thresholds where filler agglomeration causes wire sweep defects during molding.
Strategic Opportunities
- India Semiconductor Subsidies:India's PLI scheme for electronics manufacturing is attracting OSAT investment in Gujarat and Tamil Nadu, creating virgin demand for mold compound qualification programs without incumbent supplier lock-in.
- Bio-Based Epoxy Precursors:Japan's METI circular economy guidelines are pressuring formulators to develop lignin-derived epoxy resins that qualify for carbon footprint disclosure advantages with automotive OEMs.
- Memory Packaging Purity Thresholds:Low-alpha emission grades for DRAM and NAND stacking are commanding 40-60% price premiums over standard compounds as foundry customers tighten particle contamination specifications.
Industry Challenges
- Formulation Chemist Scarcity:The intersection of polymer rheology, semiconductor reliability physics, and regulatory compliance requires specialists that compounders compete for against pharmaceutical and aerospace sectors.
- Qualification Timeline Compression:Automotive module customers are compressing JEDEC preconditioning and HAST test cycles from 18 months to 9 months, straining R&D throughput without compromising reliability validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Epoxy Mold Compound Market |
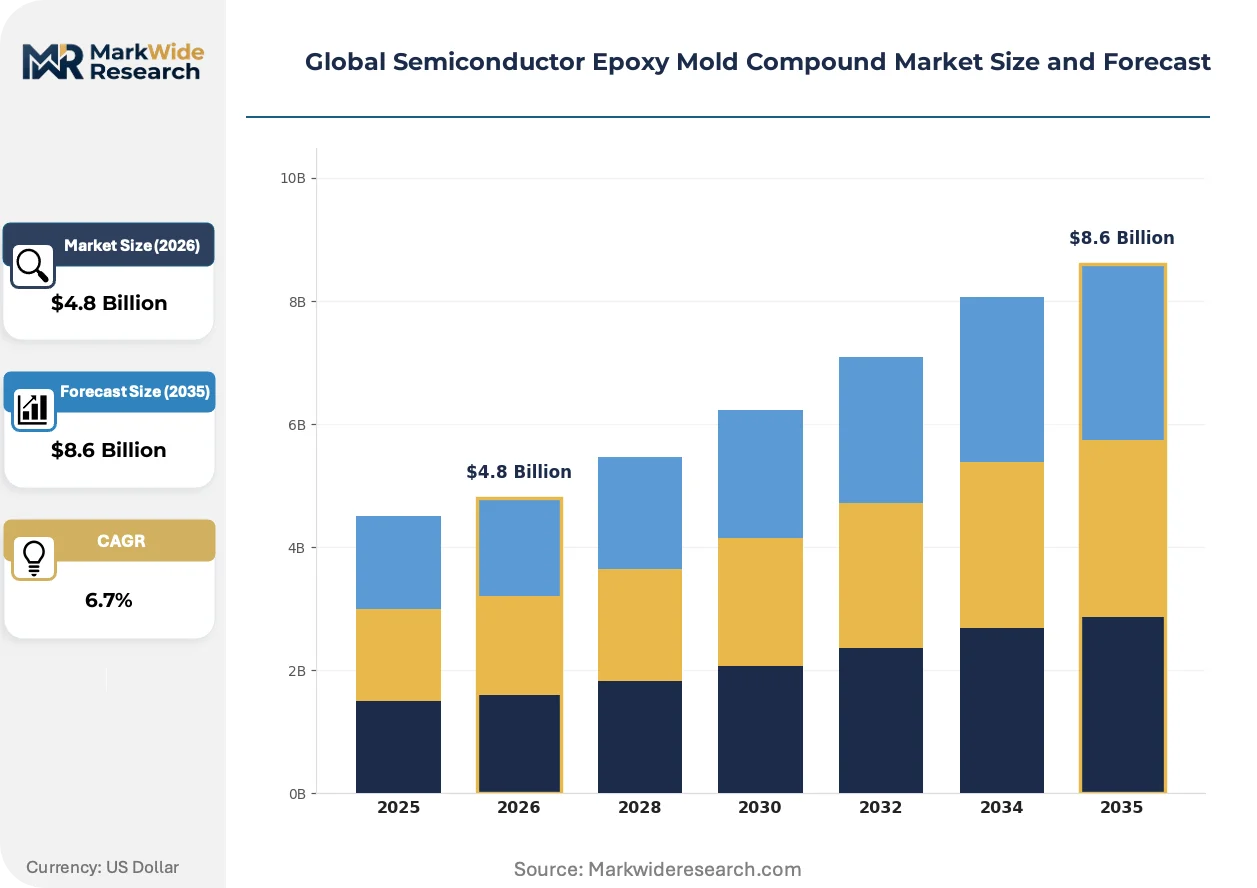
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transfer Molding, Injection Molding, Compression Molding, Encapsulation Molding End User: Consumer Electronics, Automotive, Telecommunication, Industrial Equipment Application: Integrated Circuits, LED Packaging, Power Devices, RF Components Form: Solid, Liquid, Paste, Granules |
| Companies Covered | Hitachi Chemical Co., Ltd., Kyocera Corporation, Sumitomo Bakelite Co., Ltd., Eternal Materials Co., Ltd., Samsung SDI Co., Ltd., Chang Chun Group, Panasonic Corporation, KCC Corporation, Shin-Etsu Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Epoxy Mold Compound Market Strategic Shifts
Epoxy mold compound innovation is pivoting from generic encapsulation toward application-specific thermal and electrical performance engineering. Formulators now compete on simulation-backed reliability prediction rather than commodity granule specifications.
Sintering silver die-attach materials are converging with high-thermal-conductivity mold compounds in power module packaging. Automotive inverter manufacturers in Germany and Japan are adopting this stack to eliminate solder fatigue failures under 150°C junction temperatures. The combination is converging with traditional epoxy molding processes, forcing compounders to develop low-stress formulations compatible with silver sintering cure profiles.
EU RoHS substance restrictions are expanding beyond finished electronics to cover chemical precursors in semiconductor packaging materials. Compounders must now document halogen content below 900 ppm across all raw material streams, not just final formulations. Power device suppliers serving European automotive OEMs are responding by dual-sourcing from Japanese and South Korean formulators with established RoHS compliance documentation systems.
Consolidated procurement by foundry customers is compressing supplier panels from six qualified sources to two preferred partners per packaging node. Memory packaging specialists in Taiwan and South Korea now mandate quarterly cost reduction targets alongside annual reliability audits. This concentration is most visible in HBM stacking applications where thermal interface material and mold compound sourcing decisions are merged under single supplier accountability contracts.
Global Semiconductor Epoxy Mold Compound Market Segmentation
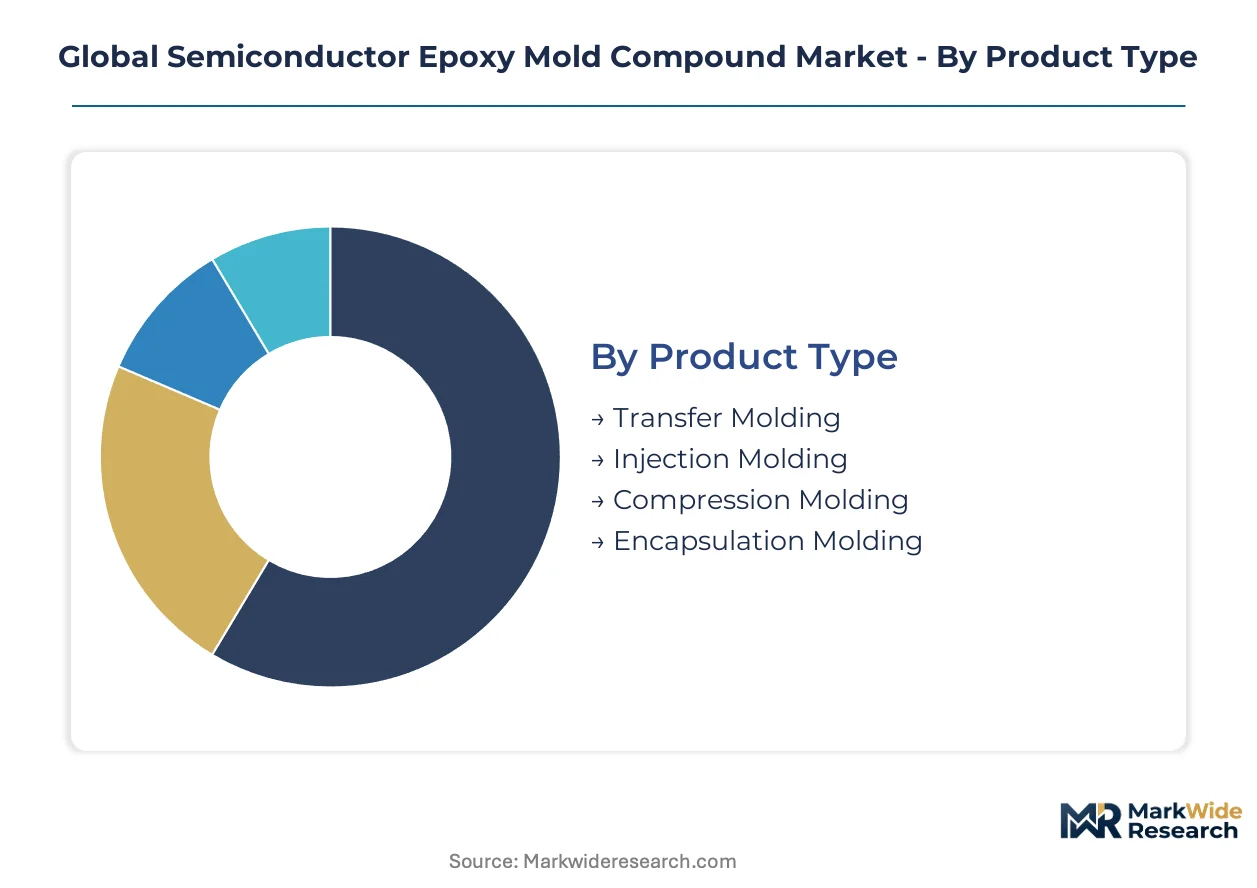
Semiconductor epoxy mold compound segmentation reflects divergent capital requirements across molding technologies and end-use reliability standards. Formulators must align product architecture with specific thermal cycling demands and purity thresholds rather than offering generic encapsulation solutions.
Product Type:
Capital intensity varies sharply across molding processes, with compression molding requiring precision platen systems and cleanroom infrastructure that transfer molding avoids.
- Transfer Molding:Legacy process using heated plungers to force compound through runners into leadframe cavities. Demand concentrates in Southeast Asian OSAT facilities serving consumer memory packaging where high-throughput throughput outweighs dimensional precision requirements.
- Compression Molding:Direct placement of compound onto wafer-level substrates before cavity closure. South Korean and Taiwanese foundries anchor demand as fan-out wafer-level packaging displaces substrate-based assembly for advanced logic devices.
- Injection Molding:Screw-based plastication systems adapted for high-viscosity thermosets. Automotive power module suppliers in Germany and Japan specify injection-molded compounds for complex geometries in inverter housings.
- Encapsulation Molding:Potting-style processes for discrete component protection. Industrial equipment manufacturers in Japan favor encapsulation for ruggedized sensor modules exposed to vibration and moisture.
Transfer molding absorbs the bulk of installed capacity; compression molding is expanding most quickly.
End User:
Customer reliability specifications create tiered pricing structures, with automotive modules commanding premiums against commoditized consumer grades.
- Automotive:EV powertrain inverters and onboard chargers require ceramic-filled formulations rated for 175°C continuous operation. German and Japanese Tier-1 suppliers mandate AEC-Q100 preconditioning protocols that extend qualification timelines.
- Consumer Electronics:Smartphones, tablets, and wearables drive volume for standard memory packaging grades. Taiwanese and South Korean foundries concentrate procurement for DRAM and NAND stacking applications.
- Telecommunication:Base station amplifiers and optical transceivers demand low-dielectric-loss compounds for high-frequency signal integrity. 5G infrastructure deployment in India and Southeast Asia pulls demand for RF-optimized formulations.
- Industrial Equipment:Factory automation controllers and motor drives specify extended temperature range encapsulation. Japanese machine tool manufacturers prioritize moisture resistance under JIS humidity cycling standards.
Consumer electronics commands the largest volume share; automotive is climbing the fastest on EV electrification.
Application:
Thermal conductivity requirements stratify the application landscape, with power devices demanding ceramic loadings that memory packaging avoids.
- Power Devices:IGBT and SiC module packaging requires fused silica and aluminum nitride filler loadings above 70% by weight to achieve thermal conductivity targets above 3 W/mK. European automotive OEMs are tightening specifications to match silicon carbide junction temperatures.
- Integrated Circuits:Logic and memory die encapsulation prioritizes low-alpha particle emission over thermal performance. South Korean foundries enforce purity thresholds that disqualify standard-grade compounds from HBM stacking applications.
- LED Packaging:Mid-power and high-power emitters require phosphor-dispersed compounds with refractive index matching. Chinese LED封装 manufacturers compete on granule flow consistency for automated dispensing systems.
- RF Components:Millimeter-wave radar and 5G antenna modules specify ultra-low-loss dielectric properties. Japanese automotive radar suppliers drive formulation innovation in 77-81 GHz frequency stability.
Integrated circuits absorb the bulk of installed capacity; power devices are gaining share fastest on electrification.
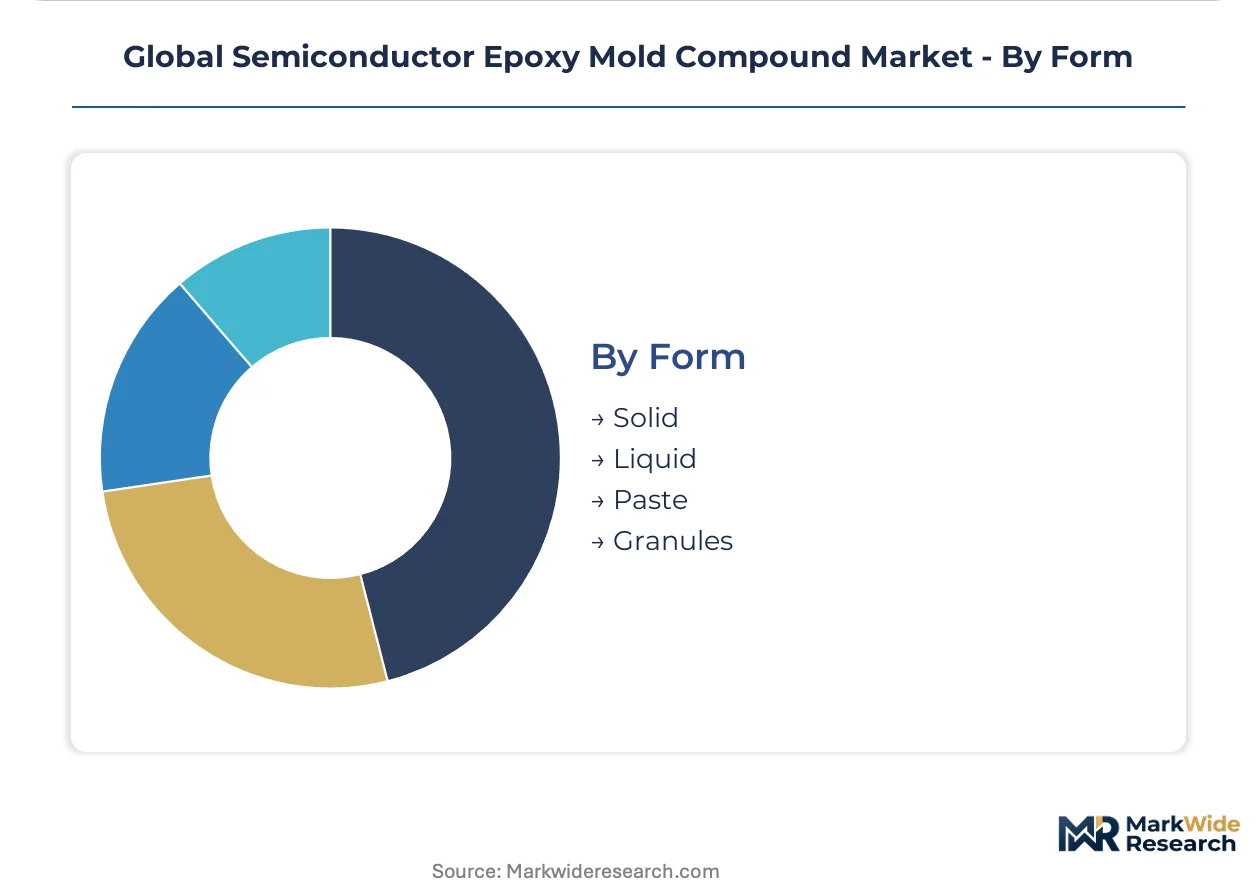
Form:
Physical state determines handling infrastructure and automation compatibility across customer facilities.
- Solid:Pelletized compound for automated transfer molding presses. Southeast Asian OSATs favor solid form for high-volume memory packaging lines with robotic loading systems.
- Liquid:Low-viscosity formulations for potting and underfill applications. Industrial sensor manufacturers in Germany specify liquid compounds for conformal coating of complex PCB assemblies.
- Paste:Thixotropic formulations for stencil printing and dot dispensing. Taiwanese fan-out packaging specialists use paste form for selective encapsulation of known-good die.
- Granules:Free-flowing solid particles optimized for compression molding platen feeding. South Korean advanced packaging foundries require granule size distributions below 100 microns for thin-profile wafer molding.
Solid form holds the majority of production volume; granules are expanding most quickly with compression molding adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in South Korea, Taiwan, and eastern China concentrate epoxy mold compound demand near advanced packaging foundries. Tax incentives in Gujarat and Tamil Nadu are attracting OSAT investment to India. Regulatory divergence across REACH, EPA toxics rules, and China's GB standards is fragmenting supplier qualification pathways.
South Korea
EV powertrain module packaging and HBM memory stacking drive formulation demand toward low-alpha emission grades. Samsung SDI Co., Ltd. anchors backward integration into high-purity epoxy monomers under domestic petrochemical complexes. The Pyeongtaek-Dongtan corridor hosts compression molding capacity expansion for fan-out wafer-level packaging.
China
Domestic epoxy resin capacity faces caps under MEE dual carbon goals, forcing compounders toward South Korean monomer imports. LED packaging manufacturers in Guangdong compete on granule flow consistency for automated dispensing. GB standards on electronic chemical emissions tighten formulation disclosure burdens for power device suppliers.
Taiwan
Dram and NAND stacking applications concentrate procurement for ultra-pure compounds with tightened particle contamination specifications. Foundry customers mandate quarterly cost reduction targets alongside annual reliability audits. The Hsinchu-Taichung corridor anchors advanced packaging foundry clusters driving compression molding adoption.
Japan
METI circular economy guidelines press suppliers toward bio-based epoxy precursors and solvent recovery systems. Automotive radar suppliers in the Chubu region drive formulation innovation for 77-81 GHz frequency stability. Aichi and Shizuoka prefectures host industrial equipment manufacturers prioritizing JIS humidity cycling standards.
United States
EPA toxics rules restrict flame retardant chemistries in semiconductor packaging materials serving domestic automotive OEMs. Onshore inverter manufacturing for EV powertrains pulls demand for ceramic-filled thermal conductivity grades. Texas and Arizona foundry investments are creating new qualification programs for mold compound suppliers.
Global Semiconductor Epoxy Mold Compound Market Competitive Environment
Japanese and South Korean producers anchor the premium reliability tier; Taiwanese and Chinese specialists hold volume positions in consumer packaging. The vendor base splits between integrated petrochemical conglomerates with captive resin supply and independent compounders sourcing monomers at market prices. Three archetypes dominate: backward-integrated resin producers, purity-focused memory packaging specialists, and automotive-grade thermal compound developers. Competitive moves center on dual-sourcing qualification slots opened by REACH substance restrictions and capacity expansion near India PLI scheme beneficiaries.
Among Japanese chemical conglomerates, Hitachi Chemical Co., Ltd. and Shin-Etsu Chemical Co., Ltd. occupy positions exemplifying integrated material science capabilities spanning resin synthesis to final formulation. Sumitomo Bakelite Co., Ltd. represents the captive phenolic resin technology archetype that preempts compliance cost escalation under tightening halogen restrictions. South Korean energy-materials conglomerates sit within a separate tier where Samsung SDI Co., Ltd. anchors upstream control over high-purity epoxy monomers.
| Leading Market Players |
|---|
| Hitachi Chemical Co., Ltd. |
| Kyocera Corporation |
| Sumitomo Bakelite Co., Ltd. |
| Eternal Materials Co., Ltd. |
| Samsung SDI Co., Ltd. |
| Chang Chun Group |
| Panasonic Corporation |
| KCC Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Family-owned Japanese chemical conglomerates with multi-decade formulation legacies anchor supply discipline through captive phenolic resin production, insulating their pricing power from volatile spot monomer markets while compressing margins for independent compounders sourcing at market rates.
Pricing Analysis
Lead-time-driven pricing separates urgent automotive qualification programs from standard memory packaging procurement, with EV powertrain suppliers paying premiums for 9-month compressed JEDEC cycles versus 18-month standard timelines. Three-tier pricing structure across AEC-Q100 certified automotive, JEDEC-qualified memory, and industrial-grade economy levels reflects reliability audit intensity. Cost compression in consumer electronics tiers stems from Taiwanese foundry mandates for quarterly cost reduction targets. LED packaging manufacturers in Guangdong exhibit highest price sensitivity due to commoditized granule flow competition.
Supply Chain Analysis
Regional distribution centers in Yokkaichi, Pyeongtaek, and Kaohsiung stage finished compounds near advanced packaging foundry clusters, with hub-and-spoke patterns radiating to Southeast Asian OSAT facilities. Ultra-low alpha particle silica concentrates in Japanese and German mining operations, while high-purity epoxy monomers flow from South Korean petrochemical complexes. Single-source vulnerability concentrates in ceramic filler supply for power device thermal conductivity grades above 5 W/mK. Distribution runs through qualified supplier panels consolidated from six sources to two preferred partners per packaging node.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance restrictions on bisphenol-A derivatives and halogenated hardeners erect a cost-of-compliance moat that advantages incumbent Japanese and South Korean formulators with established ECHA documentation systems, disqualifying legacy suppliers and consolidating qualification slots.
For Market Incumbents: Anticipate compressed automotive qualification timelines by pre-positioning AEC-Q100 preconditioning capacity ahead of EV powertrain module procurement waves. Deepen backward integration into high-purity epoxy monomers to preempt South Korean petrochemical freight premiums. Defend against emerging bio-based epoxy specialists by accelerating lignin-derived resin R&D under Japan's METI circular economy guidelines. For New Entrants and Emerging Players: Begin with India's PLI scheme beneficiaries in Gujarat and Tamil Nadu, where virgin OSAT investment creates qualification programs without incumbent supplier lock-in. Target fan-out wafer-level packaging compression molding demand as the most penetrable technology node. Lead with low-alpha emission grade specialization for HBM stacking applications commanding 40-60% price premiums over standard compounds. For Investors and Strategic Acquirers: Distressed-cycle entries favor purity-focused memory packaging specialists in Taiwan with established foundry customer audits and low-alpha emission grade production capability. Long-term viability centers on compounders qualifying for single-supplier accountability contracts in HBM thermal interface material sourcing. Watch for inflection when automotive OEMs mandate carbon footprint disclosure advantages for bio-based epoxy precursors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Monomers | Samsung SDI's captive supply from South Korean petrochemical complexes insulates margin from MEE dual carbon capacity caps. |
| Low-Alpha Emission Grade Capacity Expansion | Eternal Materials commands HBM stacking premiums through tightened particle contamination specifications at South Korean foundries. |
| Bio-Based Epoxy Precursor Development | Sumitomo Bakelite's lignin-derived resin investment qualifies for carbon footprint advantages with European automotive OEMs. |
| Compression Molding Process Qualification | Advanced packaging foundries in the Hsinchu-Taichung corridor displace transfer molding with low-viscosity ultra-fine filler compounds. |
| India PLI Scheme OSAT Partnership | Chang Chun Group's Gujarat qualification programs bypass incumbent supplier lock-in at emerging Tamil Nadu packaging facilities. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving epoxy mold compound formulators, foundry procurement leads at Samsung and TSMC, automotive Tier 1 packaging engineers, and silica mining operation managers. SEC 10-K disclosures from Hitachi Chemical and Shin-Etsu Chemical, ECHA REACH substance restriction updates, and Japan's METI circular economy guideline releases provided demand-side validation. Bottom-up capacity utilization estimates from South Korean and Taiwanese petrochemical complexes reconciled with top-down automotive electrification forecasts.
Data-stream reconciliation across molding technology adoption curves, end-use reliability tier migrations, and regional regulatory divergence produced volume and value outputs over the projection horizon. Segmentation dimensions modeled include transfer versus compression versus injection molding processes, automotive AEC-Q100 versus consumer JEDEC versus industrial grade tiers, and power device versus memory versus LED application thermal conductivity requirements. CAGRs derived from foundry capital expenditure cycles and EV powertrain inverter production ramps. Silica filler loading limits and ceramic particle agglomeration thresholds informed power device segment constraints.
Underlying measurement precision varies by segment; automotive electrification and HBM stacking applications carry tighter precision than mature LED packaging due to disclosed foundry capacity expansion timelines. Forecasts reflect assumptions around REACH enforcement intensity, MEE dual carbon goal implementation pace, and automotive OEM supplier consolidation preferences. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Electronic Assembly Materials Market
Semiconductor Material
Global Strontium Market
Semiconductor Material
Terbium Oxide Market
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
Monocrystalline Silicone Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Asia-Pacific Transparent Conductive Films Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Silicon Nitride Balls Market
Semiconductor Material
Middle East Silicon Carbide (Sic) Market
Semiconductor Material
Zinc Oxide Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
Silicon Carbide Ceramics Market
Semiconductor Material
Global Gallium Nitride Market
Semiconductor Material
Methyl Phenyl Silicone Resin Market