
 OLED Materials Market | 2026-2036
OLED Materials Market Size, Share, and Industry Trends Forecast 2026-2036
OLED Materials Market Intelligence
Fluorescent emitter chemistry is pivoting toward phosphorescent and thermally activated delayed fluorescence systems to extend device lifetimes and cut power consumption. Universal Display Corporation dominates intellectual property around phosphorescent OLED architectures. Idemitsu Kosan leverages vertically integrated synthesis from precursor chemicals to finished emitter materials. Samsung SDI anchors supply security through captive production serving its parent display division.
OLED materials encompass organic small molecules and polymers engineered for electroluminescence, typically deposited via vacuum thermal evaporation or inkjet printing at layer thicknesses below 100 nanometers to achieve efficient charge transport and light emission. These materials enable self-emissive displays and solid-state lighting with superior contrast ratios and form factor flexibility compared to liquid-crystal alternatives. Emitters command the largest value share within product types due to stringent color purity requirements and patent-protected dopant formulations. SMOLED technology leads commercial volume while PHOLED variants capture premium applications demanding maximum efficiency. The automotive end-user segment shows accelerating qualification activity for transparent and flexible interior displays.
The EPA governs volatile organic compound emissions from solvent-based OLED material synthesis in the United States. REACH and RoHS frameworks in Europe restrict cadmium and other heavy metals in consumer electronics applications, directly influencing emitter material selection and supplier qualification protocols. Japan's METI promotes domestic OLED supply chain resilience through coordinated industry standards under JIS certification schemes. Stakeholders must monitor evolving substance restrictions and display efficiency mandates across multiple jurisdictions to anticipate material specification shifts.
Market Dynamics
Phosphorescent emitter architectures are compressing fluorescent market share as smartphone and automotive display makers demand higher efficiency and extended operational lifetimes. This technology transition concentrates procurement power among patent holders while forcing second-tier suppliers into costly licensing negotiations or alternative TADF development paths.
Growth Catalysts
- Flexible Display Proliferation:Samsung Display and LG Display are expanding foldable panel capacity, driving demand for bendable substrate-compatible emitter formulations and thin-film encapsulation materials.
- Automotive Interior Digitization:Transparent OLED qualification for dashboard and pillar-to-pillar applications is opening new specification tiers requiring automotive-grade reliability testing protocols.
- REACH Heavy-Metal Restrictions:European RoHS and REACH frameworks are accelerating cadmium-free quantum dot and heavy-metal-free phosphorescent emitter substitution programs.
Market Restraints
- Patent Thicket Density:Universal Display Corporation's phosphorescent IP portfolio creates licensing barriers for new emitter entrants, compressing gross margins for unlicensed manufacturers.
- Precursor Chemical Volatility:Iridium and platinum organometallic precursor costs fluctuate with mining output, destabilizing emitter material pricing for SMOLED and PHOLED production lines.
- South Korean Supply Concentration:Samsung SDI and LG Chem captive production networks limit third-party material access, creating single-source vulnerabilities for non-integrated display makers.
Strategic Opportunities
- India Display Manufacturing:PLI scheme subsidies for semiconductor and display fabrication are attracting emitter material suppliers to establish local synthesis capabilities near Vedanta-Foxconn and ISMC Digital projects.
- Thermally Activated Delayed Fluorescence:TADF systems without iridium dopants offer patent-expired pathways for cost-competitive high-efficiency emitters in mid-tier television applications.
- Solid-State Lighting Convergence:OLED panel efficiency gains are positioning the technology for architectural and automotive ambient lighting where color tunability commands specification premiums.
Industry Challenges
- Thin-Film Deposition Expertise Gap:Vacuum thermal evaporation process engineers with sub-nanometer thickness control experience are scarce, constraining capacity expansion timelines for new fabrication facilities.
- Automotive Qualification Cycles:AEC-Q100 and OEM-specific validation protocols demand 10,000+ hour operational testing, extending time-to-revenue for interior display material qualifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OLED Materials Market |
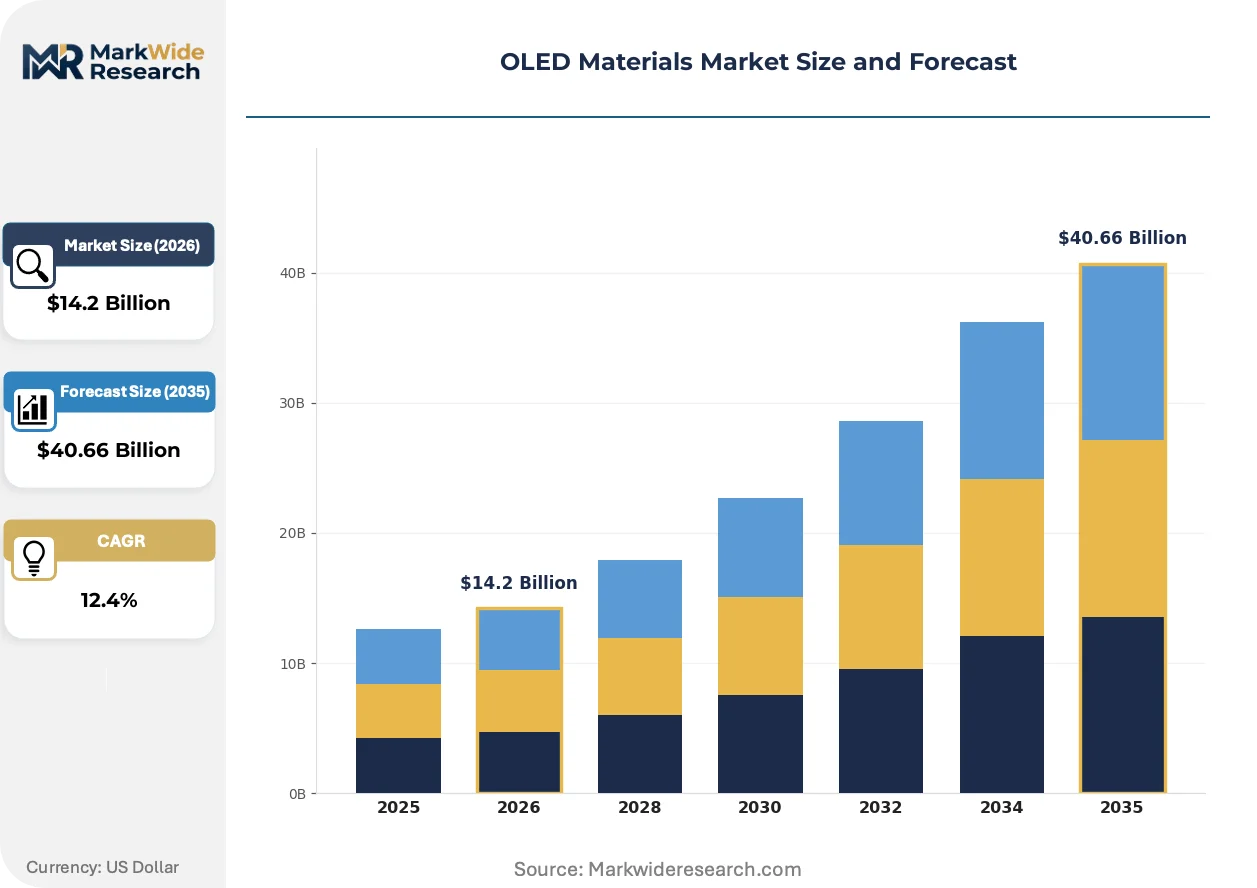
| Market Size in 2026 | $14.2 Billion |
| Market Size in 2035 | $40.66 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emitters, Substrates, Conductive Polymers, Encapsulation Materials Application: Televisions, Smartphones, Wearables, Lighting End User: Consumer Electronics, Automotive, Industrial, Healthcare Technology: PHOLED, SMOLED, TOLED, FOLED |
| Companies Covered | DuPont, Idemitsu Kosan, Universal Display Corporation, Dow Chemical Company, Samsung SDI, Merck KGaA, Sumitomo Chemical, Hodogaya Chemical, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OLED Materials Market Strategic Shifts & Innovations
Materials innovation is compressing the efficiency gap between laboratory demonstrations and mass-manufactured panels. Three concurrent developments are restructuring competitive positioning across the value chain.
TADF emitter systems are electrifying the mid-tier display segment by delivering phosphorescent-equivalent external quantum efficiencies without iridium content. Chinese panel makers BOE and TCL CSOT are integrating these materials into television and monitor lines to circumvent licensing costs. This chemistry transition is compressing royalty-dependent business models while expanding addressable market volume for patent-expired dopant suppliers.
Japan's METI is coordinating domestic OLED supply chain resilience through updated JIS standards and coordinated R&D consortia linking precursor chemical synthesis to finished emitter formulation. The framework mandates traceability protocols for rare metal content and establishes efficiency benchmarking for next-generation emitters. Domestic material suppliers are responding by consolidating synthesis capabilities under unified quality certification schemes to reduce qualification friction with display manufacturers.
Automotive procurement teams are unbundling material specifications from panel vendor contracts, creating direct sourcing relationships with emitter and transport layer suppliers. Tier-1 integrators like Continental and Bosch are establishing approved vendor lists for display stack materials to secure supply continuity and cost transparency. This pattern is most pronounced in Germany and South Korea where automotive-electronics convergence is deepest and OEMs demand end-to-end material traceability for safety-critical cabin displays.
OLED Materials Market Segmentation
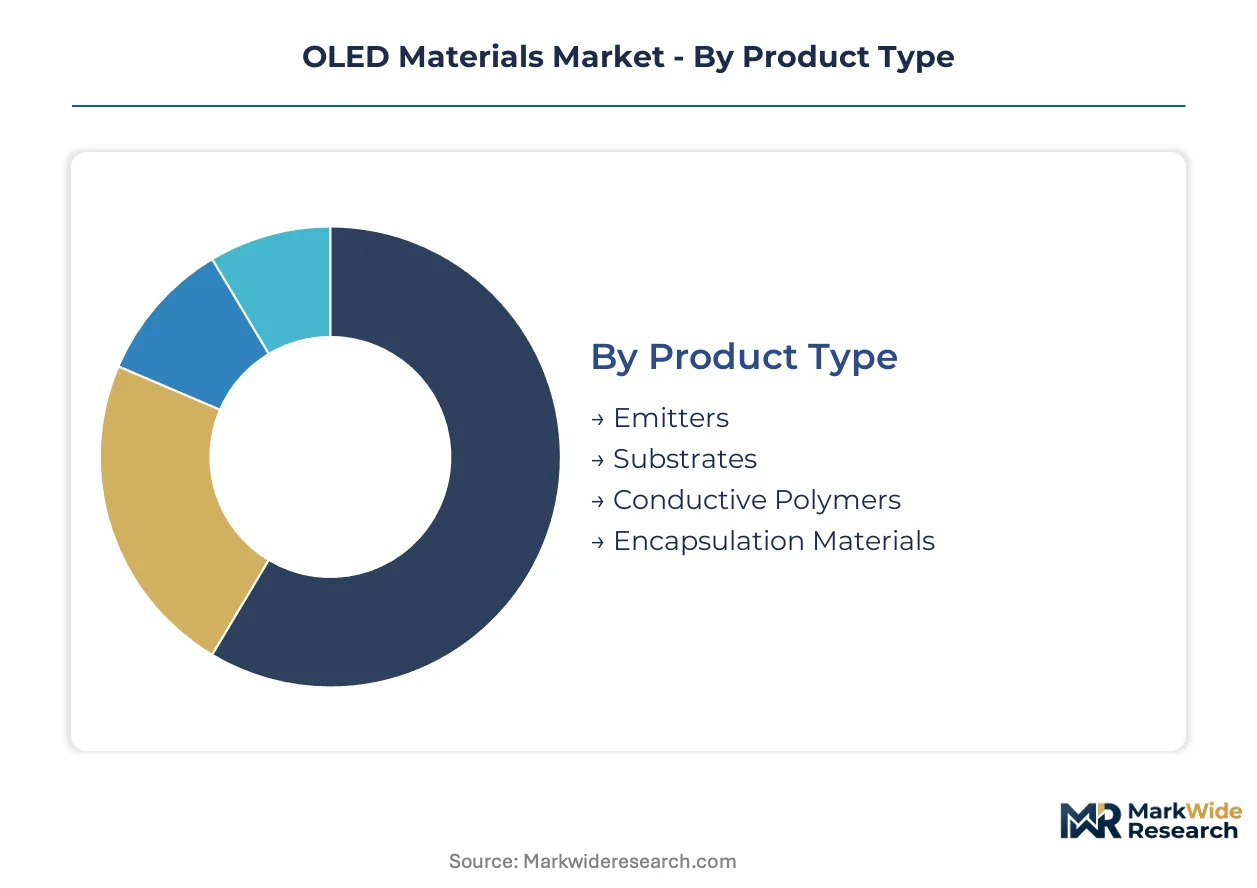
OLED materials command divergent pricing and specification tiers depending on deposition method, device architecture, and end-use reliability requirements. Segmentation reveals where patent-protected formulations concentrate value versus where commodity substitution pressures operate.
Product Type:
Buyers differentiate primarily by layer function in the device stack and the purity thresholds each layer demands.
- Emitters:Organometallic complexes and thermally activated delayed fluorescence dopants generate electroluminescence through precise energy transfer mechanisms. Smartphone and automotive display procurement teams prioritize emitters for color purity and operational lifetime, driving specification premiums for iridium-based phosphorescent systems. Samsung Display and LG Display captive sourcing concentrates demand in South Korea.
- Encapsulation Materials:Thin-film barrier stacks prevent moisture and oxygen ingress that degrades organic layers. Flexible panel adoption is accelerating multi-layer encapsulation demand as foldable devices require bendable barrier architectures with water vapor transmission rates below 10⁻⁶ g/m²/day.
- Substrates:Glass and polyimide carrier materials provide mechanical support during fabrication. BOE and TCL CSOT expansion in China is diversifying substrate sourcing beyond traditional Japanese and South Korean suppliers.
- Conductive Polymers:Poly(3,4-ethylenedioxythiophene) derivatives and related hole transport polymers enable solution-processed deposition. Printed OLED development at JOLED and subsequent technology transfers are expanding addressable applications.
Emitters lead volumes today; encapsulation materials are gaining share fastest.
Application:
Volume scale and specification stringency separate consumer display segments from emerging industrial uses.
- Smartphones:Foldable and rollable form factors demand emitter formulations compatible with polyimide substrates and repeated mechanical stress. Apple and Samsung procurement specifications for peak brightness and power efficiency are tightening material qualification protocols.
- Televisions:Large-area deposition requires uniform evaporation across Gen 8.5+ substrate sizes. WOLED architectures from LG Display dominate this segment with blue common layers and color filters.
- Wearables:Small active areas prioritize power efficiency over brightness. Apple Watch and Samsung Galaxy Watch adoption of LTPO backplanes is extending emitter lifetime requirements.
- Lighting:Panel efficiency gains are positioning OLED for architectural ambient applications where color tunability commands specification premiums. Lumen maintenance targets of 70% at 10,000 hours exceed display requirements.
Television panels generate the largest absolute material consumption; automotive-derivative transparent displays are climbing the fastest.
End User:
Reliability certification depth and supply continuity requirements fragment procurement behavior across customer types.
- Consumer Electronics:Annual refresh cycles prioritize cost reduction and supply security over extreme reliability. Brand consolidation among Apple, Samsung, and Xiaomi is concentrating procurement power.
- Automotive:AEC-Q100 validation and OEM-specific 10,000+ hour operational testing extend qualification timelines. Continental and Bosch tier-1 integrators are establishing direct emitter supplier relationships for cabin display transparency.
- Industrial:Harsh environment operation demands encapsulation robustness beyond consumer specifications. Military and aerospace applications require ITAR-compliant supply chains.
- Healthcare:Diagnostic imaging and surgical visualization prioritize color accuracy and flicker-free operation. FDA device classification influences material biocompatibility documentation requirements.
Consumer electronics commands current volume leadership; automotive interior digitization is expanding most quickly.
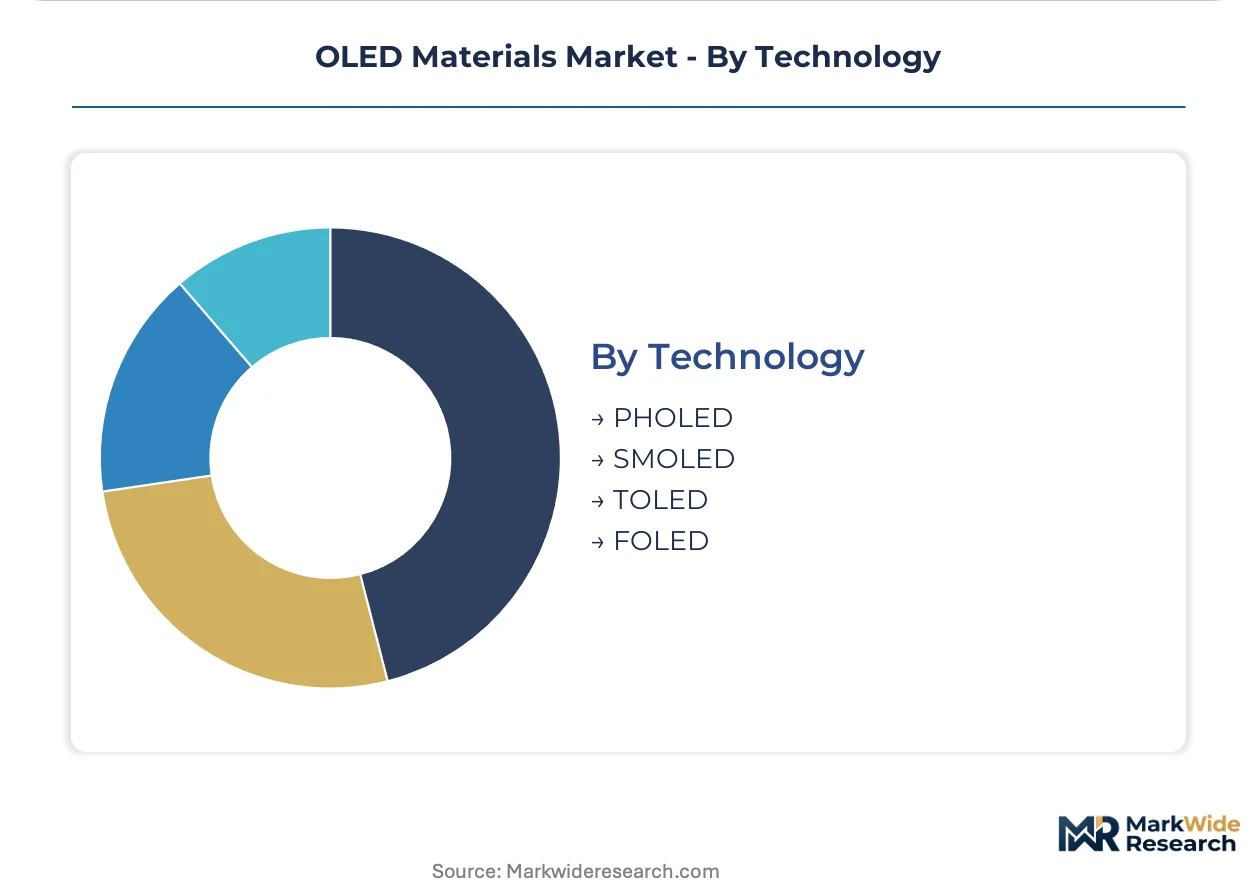
Technology:
Efficiency mechanism and manufacturing equipment compatibility determine technology selection and material chemistry.
- SMOLED:Fluorescent small-molecule systems rely on established vacuum thermal evaporation infrastructure. Mature manufacturing economics preserve market presence in cost-sensitive applications.
- PHOLED:Phosphorescent architectures achieve near-unity internal quantum efficiency through triplet harvesting. Universal Display Corporation patent licensing governs commercial deployment.
- TOLED:Transparent OLED stacks omit reflective cathodes for see-through display applications. Automotive HUD and smart window integration is validating this architecture.
- FOLED:Flexible substrate compatibility enables foldable and rollable device form factors. Polyimide substrate handling and laser lift-off processes define material requirements.
SMOLED retains installed base dominance; PHOLED is capturing premium application share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's display manufacturing belt around Seoul anchors global OLED material procurement, with Samsung Display and LG Display driving specification standards for emitter formulations and thin-film encapsulation systems.
South Korea
Samsung Display and LG Display expansion of foldable panel capacity is accelerating demand for bendable substrate-compatible materials. The country's Ministry of Trade, Industry and Energy coordinates domestic supply chain resilience programs under national strategic technology designations. Suwon and Paju industrial clusters concentrate captive production networks where Samsung SDI and LG Chem maintain integrated synthesis operations.
China
BOE and TCL CSOT capacity expansion for Gen 8.5+ deposition lines is diversifying substrate sourcing beyond traditional suppliers. The Ministry of Industry and Information Technology promotes domestic OLED supply chain development through GB standards alignment and dual carbon efficiency targets. The Yangtze River Delta around Shanghai and Hefei hosts emerging emitter material synthesis facilities serving panel makers' localization mandates.
Japan
Idemitsu Kosan and Sumitomo Chemical vertical integration from precursor chemicals to finished emitters preserves domestic supply chain control. METI coordinates industry standards under updated JIS certification schemes with traceability protocols for rare metal content. Chiba and Osaka prefectures concentrate synthesis capabilities where unified quality certification schemes reduce qualification friction with display manufacturers.
United States
Universal Display Corporation's phosphorescent IP licensing governs commercial deployment for premium efficiency applications. EPA volatile organic compound regulations constrain solvent-based synthesis operations, influencing material specification shifts. New Jersey and Delaware research corridors concentrate intellectual property development and strategic R&D partnerships with Asian panel makers.
Germany
Continental and Bosch tier-1 integrators are establishing direct emitter supplier relationships for automotive cabin display transparency. ECHA REACH and RoHS frameworks restrict cadmium and heavy metals, accelerating heavy-metal-free phosphorescent substitution programs. Bavaria and Baden-Württemberg automotive-electronics clusters drive qualification activity for transparent and flexible interior display specifications.
OLED Materials Market Key Industry Players
Global majors compete with regional champions across intellectual property control and captive supply integration. The market exhibits tiered concentration where patent holders extract licensing premiums while integrated chemical conglomerates defend volume positions through backward synthesis control. Two strategic archetypes dominate: IP-centric technology licensors with phosphorescent emitter portfolios, and vertically integrated material suppliers with precursor-to-finished-dopant capabilities. Competitive dynamics center on patent litigation defense and capacity expansion near emerging panel fabrication hubs.
Within the technology licensor tier, Universal Display Corporation occupies a position defined by phosphorescent OLED architecture patents. Among integrated chemical suppliers, Idemitsu Kosan exemplifies backward synthesis control from raw precursors through finished formulations. Samsung SDI anchors the captive production archetype, serving parent display division requirements through in-house material supply. These three company types represent the structural fault lines where pricing power and supply security negotiate.
| Leading Market Players |
|---|
| DuPont |
| Idemitsu Kosan |
| Universal Display Corporation |
| Dow Chemical Company |
| Samsung SDI |
| Merck KGaA |
| Sumitomo Chemical |
| Hodogaya Chemical |
| LG Chem |
| Others |
Cost & Logistics Intelligence
Iridium spot price volatility cascades through organometallic precursor costs into emitter material pricing tiers, compressing margins for unlicensed manufacturers while concentrating value capture among patent holders with captive supply security.
Pricing Analysis
Input-cost pass-through from iridium and platinum organometallic precursors governs emitter material pricing, with heavy-metal-free TADF formulations commanding premium-mid-economy pricing differentiation against iridium-based phosphorescent systems. Price differentiation rests on patent licensing status and automotive-grade reliability certification, with AEC-Q100 validation adding substantial specification premiums. Cost compression in mid-tier television emitters is intensifying because Chinese panel makers BOE and TCL CSOT are circumventing royalty burdens through TADF adoption. Consumer electronics procurement teams exhibit highest price sensitivity, while automotive tier-1 integrators prioritize supply continuity over unit cost.
Supply Chain Analysis
Workforce availability constraints for vacuum thermal evaporation process engineers with sub-nanometer thickness control experience are tightening in South Korea and Japan, extending capacity expansion timelines for new fabrication facilities. Geographic supply concentration centers on South Korea, Japan, and China, with Samsung SDI and LG Chem maintaining captive production networks while Idemitsu Kosan preserves backward integration from precursor chemicals. Raw material dependencies draw from iridium mining output, platinum group metals, and high-purity organic precursors. Single-source vulnerability pervades the South Korean industrial cluster around Suwon and Paju. Distribution runs through direct panel maker procurement with emerging unbundling toward tier-1 automotive integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OLED materials function as a stable compounder anchored by irreversible display technology substitution in smartphones and automotive interiors, with specification tightening driving recurring material refresh cycles.
For Market Incumbents: Cement patent litigation defense capabilities and expand captive precursor synthesis capacity near emerging panel fabrication hubs in India and China. Licensing revenue streams from Universal Display Corporation's phosphorescent IP portfolio face erosion threat from TADF chemistry advances, requiring accelerated heavy-metal-free emitter R&D investment and strategic patent acquisition in delayed fluorescence architectures.
For New Entrants and Emerging Players: Begin with India PLI scheme-aligned local synthesis capabilities serving Vedanta-Foxconn and ISMC Digital display projects, where import substitution mandates create procurement preference. Automotive interior digitization presents the most penetrable segment, with direct supplier relationships to Continental and Bosch tier-1 integrators offering bypass around entrenched South Korean supply networks. Pursue qualification-first go-to-market positioning emphasizing AEC-Q100 protocol compliance.
For Investors and Strategic Acquirers: Consolidation pressure builds where patent licensing dependence intersects with raw material cost volatility, favoring acquisition of vertically integrated material suppliers with precursor-to-emitter synthesis control. Long-term viability frames around 5-10 year technology transition windows as TADF systems displace iridium-dependent architectures. Target acquisition archetype: mid-scale Japanese or Korean material suppliers with JIS certification infrastructure and established panel maker relationships. Watch TADF external quantum efficiency parity announcements as inflection signal for phosphorescent licensing value erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Heavy-Metal-Free Emitter Development | REACH and RoHS compliance accelerates cadmium-free substitution programs across European automotive procurement. |
| Captive Precursor Synthesis Expansion | Samsung SDI and LG Chem vertical integration models reduce iridium price exposure and secure supply continuity. |
| Automotive Direct Supplier Qualification | Continental and Bosch approved vendor list establishment creates procurement bypass around panel maker intermediation. |
| India Localized Production Buildout | PLI scheme subsidies attract emitter material synthesis near Vedanta-Foxconn and ISMC Digital fabrication projects. |
| TADF Patent Portfolio Acquisition | Chinese panel maker adoption of iridium-free systems compresses royalty-dependent business model viability. |
Research Approach
Multiple input streams — primary interviews with emitter material R&D directors, display panel procurement leads, and automotive tier-1 integrator sourcing managers; secondary validation through SEC filings, customs and trade data, and JIS certification registries; plus patent landscape analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured specification evolution, qualification timeline, and procurement unbundling trends. Secondary sources included EPA volatile organic compound emission records, ECHA REACH substance restriction databases, and METI-coordinated industry standard documentation. Cross-referencing supply chain mapping against intellectual property licensing records enabled structural segmentation of competitive positioning.
Data-stream reconciliation across the projection horizon applied multi-dimensional segmentation modeling by deposition technology, layer function, end-use reliability tier, and geographic production cluster. Analytical framework incorporated iridium price elasticity, patent expiration sequencing, and automotive qualification cycle duration as industry-specific forecast inputs. CAGRs were derived from volume-weighted segment growth trajectories calibrated against panel capacity expansion announcements and emitter material intensity per display area.
Several conditions sit outside the modeled scope, including unannounced regulatory substance restrictions, breakthrough laboratory efficiency demonstrations without manufacturing scalability validation, and geopolitical trade measure implementations affecting rare metal precursor flows. Forecasts reflect assumptions around technology transition pacing and licensing negotiation outcomes. Material deviation in iridium supply disruption, patent litigation rulings, or automotive qualification acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Silicon Nitride Market
Semiconductor Material
Global Electronic Materials Market
Semiconductor Material
Niobium Hydride Market
Semiconductor Material
Global Scintillator Market
Semiconductor Material
Silicon Nitride Balls Market
Semiconductor Material
Terbium Oxide Market
Semiconductor Material
Silicon Base Paper Market
Semiconductor Material
Indium Market
Semiconductor Material
ITO Nanoparticles Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Middle East Silicon Carbide (Sic) Market
Semiconductor Material
Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Global Gallium Nitride Market
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Compound Semiconductor Materials Market
Semiconductor Material
Thermoelectric Materials Market