
 Zinc Oxide Nanoparticles Market | 2026-2036
Zinc Oxide Nanoparticles Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Oxide Nanoparticles Market Outlook
Personal care is consolidating its position as the dominant demand vertical for zinc oxide nanoparticles, displacing traditional coatings applications in volume terms. BASF leverages its integrated pigment-nanomaterial platform to supply cosmetic-grade dispersions across European and Asian markets. EverZinc anchors its competitive position through captive production of high-purity powders for pharmaceutical and electronics customers. Sakai Chemical Industry Co. Ltd specializes in surface-modified nanoparticles that meet stringent dermatological testing protocols in Japan and export markets.
Zinc oxide nanoparticles are crystalline or amorphous particles of ZnO with at least one dimension between 1 and 100 nanometers, typically synthesized via sol-gel, precipitation, or vapor-phase methods and valued for their UV absorption, antimicrobial activity, and piezoelectric properties. Powder formulations dominate current manufacturing output due to established handling infrastructure and lower logistics costs, though dispersion formats are capturing margin pools in premium cosmetic applications where aggregation control determines performance. The pharmaceuticals segment is maturing around standardized USP-grade material specifications, while electronics end-use is expanding fastest as nano-ZnO finds roles in transparent conductive films and varistor manufacturing.
REACH in Europe and the EU Cosmetics Regulation mandate pre-market notification and safety dossiers for nanomaterial-containing products, elevating compliance costs for entrants while rewarding incumbent suppliers with established toxicological data packages. The FDA in the United States maintains a separate GRAS evaluation pathway for nano-scale zinc oxide in sunscreens, creating a bifurcated regulatory landscape that shapes regional product development priorities. Stakeholders must monitor evolving definitions of nanomaterial thresholds across jurisdictions, as classification changes would trigger additional testing requirements and reshape market access conditions for existing formulations.
Market Dynamics
REACH pre-market notification requirements are compressing formulation timelines for cosmetic-grade nano-ZnO, forcing suppliers to front-load toxicological data generation and pushing smaller compounders toward contract manufacturing partnerships.
Growth Catalysts
- EU Cosmetics Regulation nanomaterial labeling:Mandatory ingredient disclosure protocols are pulling reformulation demand toward certified nano-ZnO suppliers with existing safety dossiers.
- Transparent conductive film manufacturing:Electronics fabricators in East Asia are scaling nano-ZnO deposition for flexible display substrates and touch-panel electrodes.
- Antimicrobial textile finishing:Post-pandemic hygiene standards in healthcare apparel are accelerating surface-modified nanoparticle integration into fiber treatments.
Market Restraints
- Zinc metal price volatility:Smelter output fluctuations and energy cost spikes transmit directly into nano-ZnO feedstock economics, compressing margin visibility for dispersion producers.
- High-purity powder supply concentration:Electronic-grade material synthesis requires specialized vapor-phase reactors concentrated among a limited supplier base in China and Japan.
- Photocatalytic degradation limits:Unmodified nano-ZnO particles exhibit UV-induced reactivity that restricts loading levels in certain polymer matrices without surface passivation.
Strategic Opportunities
- Indian pharmaceutical excipient market:CDSCO pathway harmonization with USP standards is opening formulation opportunities for dermatological and nutraceutical applications.
- Photocatalytic water treatment:Converging nano-ZnO with advanced oxidation process engineering is enabling municipal and industrial effluent remediation deployments.
- Direct-to-brand cosmetic ingredient platforms:Specialty chemical distributors are building digital procurement channels that bypass traditional multi-tier distribution for mid-size skincare formulators.
Industry Challenges
- Colloidal stability engineering:Maintaining particle dispersion integrity through freeze-thaw cycles and ionic strength variation demands specialized formulation chemistry expertise that outpaces current talent pipelines.
- Multi-jurisdiction dossier maintenance:Divergent nanomaterial definitions between ECHA, FDA, and NMPA require parallel toxicological study designs that extend registration timelines and inflate compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Oxide Nanoparticles Market |
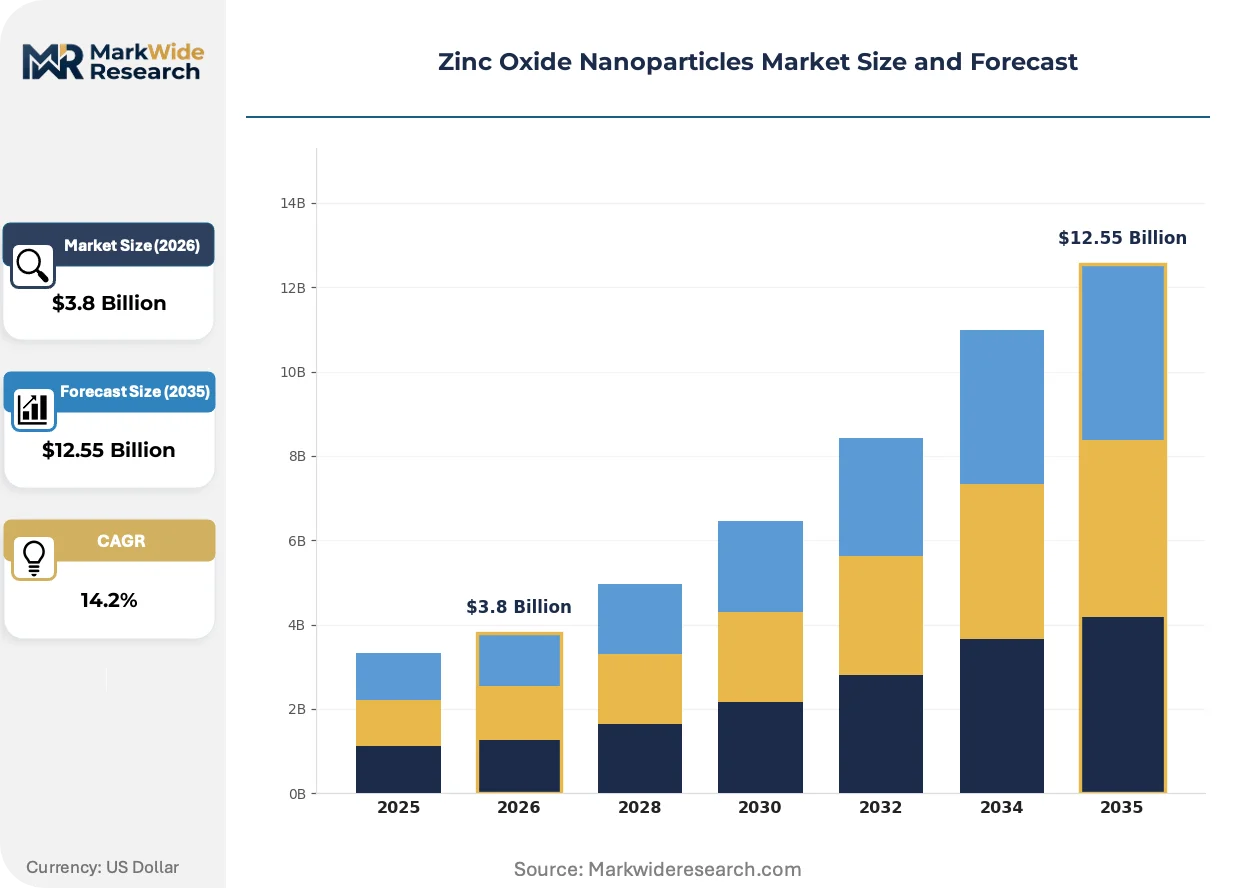
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dispersion, Powder, Paste, Gel Application: Cosmetics, Coatings, Pharmaceuticals, Textiles End User: Personal Care, Electronics, Agriculture, Healthcare Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | American Elements, BASF, EverZinc, Nanophase Technologies Corporation, SkySpring Nanomaterials Inc., Merck KGaA, Sakai Chemical Industry Co. Ltd, Croda, ALTANA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Oxide Nanoparticles Market Strategic Shifts
Surface functionalization chemistry is unifying previously separate performance attributes, enabling single-particle platforms to deliver UV attenuation, antimicrobial action, and controlled release in unified cosmetic and therapeutic formulations.
Core-shell architectures with silica or alumina surface layers are unifying photostability and skin compatibility in a single particle design. Premium sunscreen formulators in South Korea and France are adopting these structures at pilot scale. The technology is unifying what were previously separate supply chains for organic and inorganic UV filters into integrated nano-ZnO sourcing relationships.
REACH Annex VI amendments are tightening occupational exposure limits for nanomaterial manufacturing facilities across EU member states. Downstream cosmetic contract manufacturers are requalifying supplier networks to pre-screen for compliance documentation. German and French formulators are consolidating purchase orders toward incumbent suppliers with established worker-safety monitoring protocols.
Ingredient procurement through specialty chemical marketplaces is displacing traditional distributor relationships for mid-volume cosmetic compounders. These platforms aggregate certified nano-ZnO inventories from multiple qualified suppliers with transparent COA documentation. The shift is most visible among independent skincare brands in California and New York seeking rapid formulation iteration cycles without minimum order quantity constraints.
Zinc Oxide Nanoparticles Market Segmentation
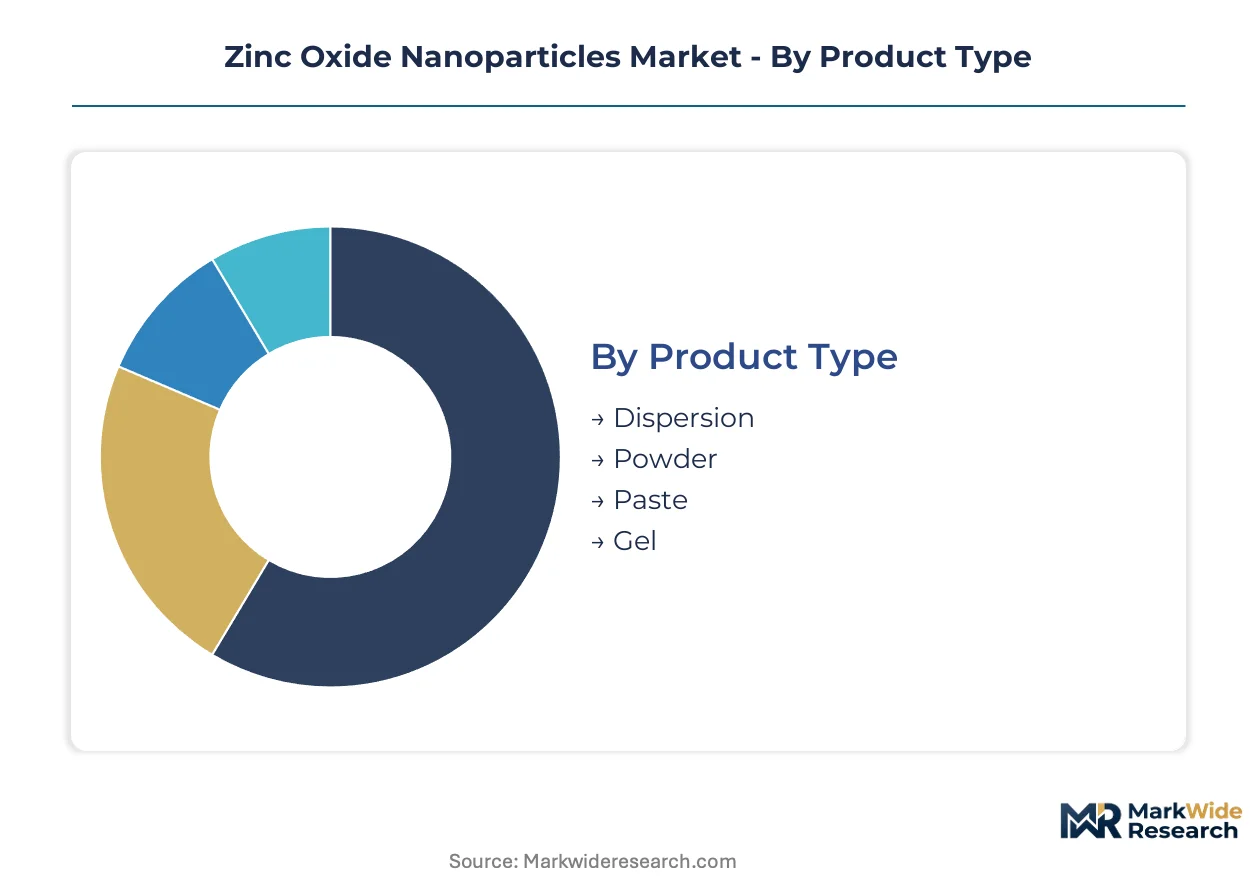
Zinc oxide nanoparticles serve divergent performance requirements across cosmetic, electronic, and therapeutic applications, demanding precise morphological control. Segmentation by physical form, end-use, and procurement channel reveals distinct margin structures and capital deployment patterns shaping supplier strategy.
Product Type:
Powder and dispersion formats demand fundamentally different manufacturing footprints, with dispersion production requiring continuous colloidal processing equipment and sterile handling infrastructure that multiplies upfront capital requirements.
- Powder:Crystalline or amorphous ZnO particles produced via vapor-phase or precipitation methods, typically specified at 99.9% purity for electronic and pharmaceutical applications. BASF and EverZinc concentrate capacity in Germany and Belgium to serve REACH-compliant cosmetic and industrial customers with established toxicological dossiers.
- Dispersion:Stabilized colloidal suspensions in aqueous or solvent carriers, requiring surface functionalization chemistry and real-time particle size monitoring during manufacture. Premium sunscreen formulators in South Korea and France source these formats to eliminate in-house dispersion processing and accelerate formulation timelines.
- Paste:High-solids concentrates for industrial coating and rubber compounding applications, valued for simplified handling in continuous manufacturing environments.
- Gel:Thixotropic formulations targeting topical pharmaceutical and veterinary dermatology applications, where controlled release kinetics and skin adhesion properties command formulation premiums.
Powder absorbs the bulk of installed capacity; dispersion is expanding most quickly.
Application:
Cosmetics and pharmaceuticals operate under stringent regulatory dossier requirements that elevate barrier-to-entry costs, while coatings and textiles permit broader supplier participation with lower compliance overhead.
- Cosmetics:Nano-ZnO serves as the primary inorganic UV filter in broad-spectrum sunscreens, with surface-modified grades achieving transparency at high loadings. EU Cosmetics Regulation mandates nanomaterial labeling and safety assessment, consolidating procurement toward incumbent suppliers with pre-submitted REACH dossiers.
- Pharmaceuticals:USP-grade material for dermatological creams, wound dressings, and nutritional supplements requires validated manufacturing under GMP conditions. CDSCO harmonization with USP standards in India is opening formulation opportunities for excipient-grade nano-ZnO in generic topical drug production.
- Coatings:Antimicrobial and UV-protective finishes for architectural and industrial substrates, where cost sensitivity favors larger particle sizes and lower purity grades.
- Textiles:Fiber surface treatments imparting antimicrobial and odor-control properties, with post-pandemic healthcare apparel standards accelerating adoption in Japan and Germany.
Cosmetics commands the dominant revenue share; pharmaceuticals climbs the fastest as therapeutic applications mature.
End User:
Personal care and electronics represent opposite ends of the specification spectrum, with cosmetic customers prioritizing dermatological safety documentation and electronics fabricators demanding tight particle size distributions for thin-film deposition.
- Personal Care:Sunscreen and skincare formulators drive volume demand for cosmetic-grade dispersions, with procurement consolidating toward suppliers offering transparent COA documentation and rapid batch certification.
- Electronics:Transparent conductive film and varistor manufacturers in China and Japan require electronic-grade powders with sub-50nm particle sizes and minimal agglomeration, produced via specialized vapor-phase reactors with limited global capacity.
- Agriculture:Nano-fertilizer and crop protection applications emerging from research-stage to pilot deployment, with regulatory pathways still evolving under EPA and national agricultural chemical frameworks.
- Healthcare:Antimicrobial coatings for medical devices and wound management products, where FDA device master file requirements parallel pharmaceutical-grade documentation burdens.
Personal care dominates current offtake; electronics gains share fastest on display substrate demand.
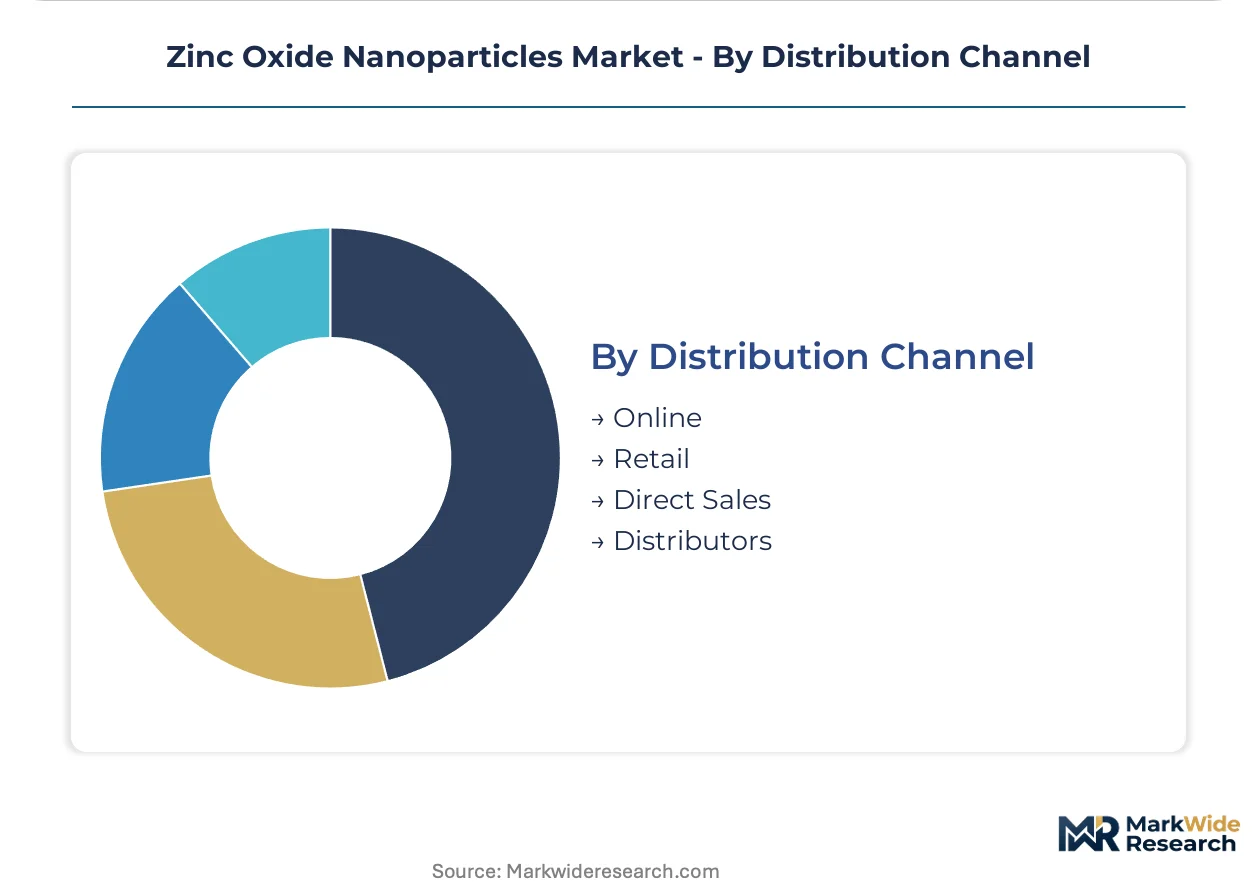
Distribution Channel:
Channel selection correlates with customer scale and formulation sophistication, with large compounders bypassing intermediaries while independent brands rely on digital platforms for rapid iteration.
- Direct Sales:Long-term supply agreements between nano-ZnO producers and multinational cosmetic and electronics manufacturers, locking in volume commitments and joint development programs for next-generation surface chemistries.
- Distributors:Specialty chemical intermediaries maintaining regional inventory positions and technical service capabilities for mid-tier formulators lacking in-house nanomaterial handling expertise.
- Online:Digital procurement platforms aggregating certified inventories from multiple qualified suppliers, displacing traditional relationships for independent skincare brands in California and New York seeking small-batch flexibility.
- Retail:Limited to consumer-facing finished products rather than industrial nano-ZnO quantities, with minimal relevance for bulk ingredient procurement.
Direct sales captures the majority of value; online channels expand most rapidly among emerging independent formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhangjiagang Free Trade Zone in Jiangsu Province anchors China's concentration of electronic-grade nano-ZnO synthesis capacity, with vapor-phase reactor clusters serving display substrate fabricators across the Yangtze River Delta.
China
Domestic production of electronic-grade nanoparticles is accelerating around Suzhou and Hangzhou industrial parks. NMPA oversight of nanomaterial classifications is tightening documentation requirements for cosmetic-grade exports. Zhangjiagang Free Trade Zone hosts specialized vapor-phase reactor capacity supplying transparent conductive film manufacturers in Kunshan and Wuxi.
Germany
REACH Annex VI amendments are compressing formulation timelines for cosmetic compounders in North Rhine-Westphalia. ECHA occupational exposure protocols are forcing requalification of supplier networks among Cologne-area contract manufacturers. Leverkusen and Ludwigshafen chemical clusters concentrate integrated pigment-nanomaterial platforms serving EU sunscreen formulators.
United States
FDA GRAS evaluation pathways for nano-scale zinc oxide in sunscreens are shaping regional product development priorities among New Jersey and California formulators. EPA oversight of antimicrobial textile treatments is expanding registration requirements for fiber-finishing applications. Greater Boston and Research Triangle Park host dermatological testing facilities certifying nano-ZnO for pharmaceutical-grade specifications.
Japan
METI industrial standards for nanomaterial manufacturing are elevating documentation burdens for Kansai-region chemical producers. PMDA alignment with international dermatological testing protocols is streamlining export certification for surface-modified nanoparticles. Osaka and Sakai industrial zones concentrate specialized surface-modification chemistry serving premium cosmetic brands in Tokyo and Yokohama.
South Korea
MFDS cosmetic ingredient notification requirements are consolidating procurement toward incumbent suppliers with pre-submitted safety dossiers. Seoul Capital Area formulators are piloting core-shell nano-ZnO architectures for premium sunscreen applications. Gyeonggi Province chemical clusters are scaling dispersion processing capacity for K-beauty export brands.
Zinc Oxide Nanoparticles Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates dominating powder supply while independent dispersion formulators capture premium cosmetic margins. The vendor base arranges into three tiers: multinational pigment platforms with REACH dossiers, regional electronic-grade specialists with captive vapor-phase capacity, and niche surface-modification boutiques serving dermatological testing protocols. Capacity expansion and strategic partnerships represent the dominant competitive moves, as suppliers seek to lock in long-term supply agreements with multinational cosmetic and electronics manufacturers.
Among Germany-based chemical platforms, BASF anchors the integrated pigment-nanomaterial tier with established toxicological documentation for EU cosmetic customers. EverZinc occupies a position within the high-purity powder segment, supplying pharmaceutical and electronics specifications from Belgian production assets. Sakai Chemical Industry Co. Ltd exemplifies the surface-modification specialist archetype, with Japanese manufacturing heritage supporting dermatological protocol compliance in export markets. These three entities represent distinct strategic postures: conglomerate scale, purity-focused vertical integration, and application-specific technical service.
| Leading Market Players |
|---|
| American Elements |
| BASF |
| EverZinc |
| Nanophase Technologies Corporation |
| SkySpring Nanomaterials Inc. |
| Merck KGaA |
| Sakai Chemical Industry Co. Ltd |
| Croda |
| ALTANA |
| Others |
Value Chain & Pricing Dynamics
Vapor-phase reactor technology upgrades in Jiangsu Province simultaneously compress production costs for electronic-grade nano-ZnO and concentrate supply leverage among operators with capital access, tightening margin structures for dispersion-dependent cosmetic formulators in Europe and North America.
Pricing Analysis
Lead-time compression commands premium positioning, with cosmetic-grade dispersions carrying 15-25% markups for sub-48-hour certification turnaround versus standard 2-week batch validation. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity grade and REACH dossier completeness, with pharmaceutical and electronics buyers exhibiting lowest price sensitivity due to substitution constraints. Cost compression in standard-grade powder is intensifying because Chinese vapor-phase capacity additions outpace European demand growth. Spot buyers in textile coatings demonstrate highest price elasticity, frequently switching to larger-particle zinc oxide when nano-grade premiums exceed formulation budget thresholds.
Supply Chain Analysis
Reverse-logistics infrastructure for nano-ZnO remains embryonic, with spent cosmetic dispersions and manufacturing slurry largely treated as industrial waste rather than feedstock for reclamation. Supply concentrates in China, Belgium, and Japan, with Zhangjiagang and Leverkusen anchoring divergent grade specializations. Feedstock economics draw from zinc metal smelter output, specialized vapor-phase reactor components, and surface-modification chemistry precursors. Single-source vulnerability permeates electronic-grade production, where sub-50nm particle synthesis rests on reactor designs controlled by three Japanese and Chinese equipment suppliers. Distribution runs through direct long-term agreements for multinational compounders, specialty chemical distributors for mid-tier formulators, and emerging digital platforms for independent skincare brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH dossier maintenance costs erect a formidable barrier-to-entry moat, consolidating procurement power among incumbent suppliers with pre-submitted toxicological data packages and forcing smaller compounders toward contract manufacturing partnerships.
For Market Incumbents: Cement market position by deepening backward integration into zinc metal refining to buffer feedstock volatility, and by acquiring surface-modification boutiques in South Korea to capture core-shell architecture demand from premium sunscreen formulators. Threat of REACH Annex VI occupational exposure tightening demands preemptive worker-safety protocol investment to avoid supplier disqualification. For New Entrants and Emerging Players: The mid-tier price-point gap between pharmaceutical-grade USP material and industrial coatings powder offers white-space targeting for CDSCO-aligned excipient suppliers in India. Agricultural nano-fertilizer applications present the most penetrable segment, with regulatory pathways still evolving under EPA frameworks. Go-to-market leverage rests on digital procurement platform partnerships that bypass traditional distributor minimum-order constraints. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking REACH-compliant cosmetic-grade capacity, with IPO viability tethered to demonstration of sustained electronics-grade margin expansion. Acquisition targets center on German and Belgian dispersion specialists with validated GMP infrastructure. Signal to watch is NMPA harmonization with REACH nanomaterial definitions, which would trigger consolidation demand among China-exporting suppliers lacking parallel dossier capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Metal Refining | Captive feedstock supply buffers margin compression from smelter output fluctuations and energy cost spikes. |
| Core-Shell Surface Modification R&D Partnership | Silica-alumina architectures unify photostability and skin compatibility for premium K-beauty and French formulator demand. |
| CDSCO-Aligned USP-Grade Capacity Expansion | Indian pharmaceutical excipient market opening accelerates generic topical drug formulation opportunities. |
| Digital Procurement Platform Integration | Direct-to-brand channels capture independent California and New York skincare formulators seeking rapid iteration cycles. |
| Vapor-Phase Reactor Technology Licensing | Equipment design control in China and Japan limits electronic-grade supply elasticity; licensing agreements unlock capacity scaling. |
Study Parameters
Multi-period observation of REACH registration timelines, NMPA classification amendments, and zinc metal smelter output patterns anchored the trend analysis, supplemented by interviews with plant managers at vapor-phase reactor facilities, procurement leads at multinational cosmetic compounders, distribution channel partners in specialty chemicals, and technical R&D directors in surface-modification chemistry. Secondary validation drew from ECHA registration databases, CDSCO harmonization notices, SEC 10-K filings of listed chemical producers, and customs trade data for nano-ZnO import-export flows. Bottom-up capacity estimates triangulated against top-down demand projections from end-use industry consumption models.
Segment-weighting across physical form, application, and procurement channel dimensions structured the analytical framework, with product-grade tiers, end-use industry verticals, and regional regulatory clusters serving as core stratification variables. CAGRs derived from fitted growth curves against historical capacity utilization and announced expansion projects, incorporating nano-fertilizer pilot deployment trajectories and transparent conductive film substrate demand from East Asian display fabricators as industry-specific forecast inputs.
Underlying measurement precision varies by segment; cosmetics and pharmaceuticals applications carry tighter precision than emerging agricultural deployments due to established regulatory reporting requirements. Forecasts reflect assumptions about REACH enforcement consistency, zinc metal price band stability, and vapor-phase reactor capacity commissioning schedules. Material deviation in NMPA-ECHA regulatory alignment or sudden feedstock cost shocks warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Dicing Die Attach Film Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Silicon Dioxide Market
Semiconductor Material
Electronic Ceramics Market
Semiconductor Material
Fullerene Market
Semiconductor Material
Glass Substrate in Semiconductor Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
Global Silicon Carbide (SIC) Market
Semiconductor Material
Semiconductor Glass Market
Semiconductor Material
Organic Silicon Coating Market
Semiconductor Material
Semiconductor PI Film Market
Semiconductor Material
Europe Silicone Market
Semiconductor Material
Sapphire Substrate Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Global Magnesium Oxide Nanopowder Market
Semiconductor Material
Germanium Market