
 Synthetic Single Crystal Diamond Market | 2026-2036
Synthetic Single Crystal Diamond Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Single Crystal Diamond Market Analysis
Chemical vapor deposition scaling is reshaping wafer-grade diamond production economics. Element Six leverages captive synthesis capacity to anchor European supply chains for quantum sensing substrates. Sumitomo Electric Industries Ltd. dominates high-purity boule growth for thermal spreader applications. ILJIN Diamond Co., Ltd. differentiates through HPHT gem-quality crystal control for optical windows.
Synthetic single crystal diamond consists of an isotropic carbon lattice engineered to defect densities below 10 parts per billion, manufactured by high-pressure high-temperature or microwave plasma CVD methods to deliver extreme thermal conductivity and optical transparency. Semiconductor diamond leads structural growth as gallium nitride power electronics drive substrate demand for heat dissipation beyond silicon carbide capabilities. Industrial diamond occupies mature margin pools in precision cutting tool inserts, while optical diamond segments command premium positioning in high-energy laser systems. CVD technology segments capture R&D investment flows as deposition area scaling reduces unit costs for electronic-grade material.
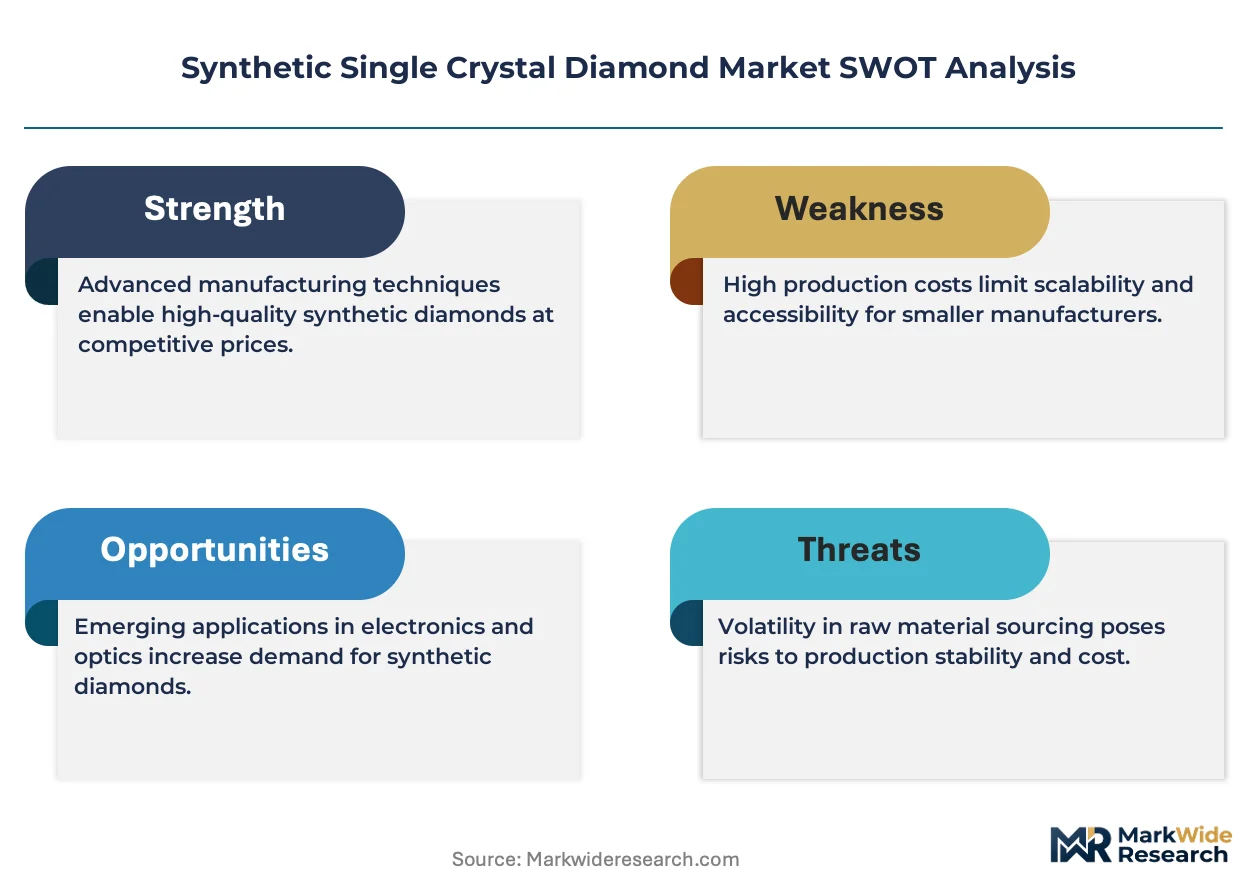
EPA emission rules for abrasive manufacturing and EU REACH substance restrictions on conflict-sourced natural diamonds shape product certification requirements and market access conditions for synthetic suppliers. Japan's METI funds diamond semiconductor commercialization through national technology roadmaps. Stakeholders must monitor HPHT energy cost trajectories against CVD yield improvements to determine optimal capacity allocation across thermal and optical product lines.
Market Dynamics
Wafer-grade diamond production economics hinge on microwave plasma CVD reactor scaling, where deposition area expansion and defect density reduction now outpace HPHT energy efficiency gains in unit cost trajectories for electronic-grade material.
Growth Catalysts
- Gallium nitride power electronics:Thermal management requirements for RF amplifiers and electric vehicle inverters exceed silicon carbide substrate capabilities, pulling diamond heat spreaders into qualification pipelines.
- EU REACH substance restrictions:Conflict-mineral traceability mandates redirect procurement toward certified lab-grown diamond sources with documented supply chain provenance.
- Quantum sensing substrate demand:Nitrogen-vacancy center engineering for magnetometry and quantum computing drives ultra-high-purity CVD boule specifications.
Market Restraints
- Plasma reactor capex intensity:Multi-million dollar microwave plasma CVD systems require 24-36 month depreciation cycles before yield optimization.
- HPHT electricity input volatility:Energy costs for high-pressure press operations fluctuate with regional grid pricing, compressing margin predictability.
- Natural diamond price arbitrage:Polished gem-quality synthetics face residual competition from recycled natural stones in optical window applications.
Strategic Opportunities
- Japan METI national roadmap funding:Diamond semiconductor commercialization programs subsidize pilot line establishment for power device substrates.
- High-energy laser optical windows:Fusion energy research facilities and directed-energy defense programs specify synthetic single crystal diamond for beam path components.
- South Korea fabrication cluster proximity:Thermal spreader integration with Samsung and SK Hynix memory packaging lines enables just-in-time substrate supply.
Industry Challenges
- Crystal growth technician scarcity:Microwave plasma CVD reactor operation requires specialized plasma physics and materials science cross-training unavailable in standard semiconductor process engineering programs.
- Electronic-grade certification timelines:SEMI standards compliance for semiconductor substrate qualification extends 18-24 months beyond initial crystal growth optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Single Crystal Diamond Market |
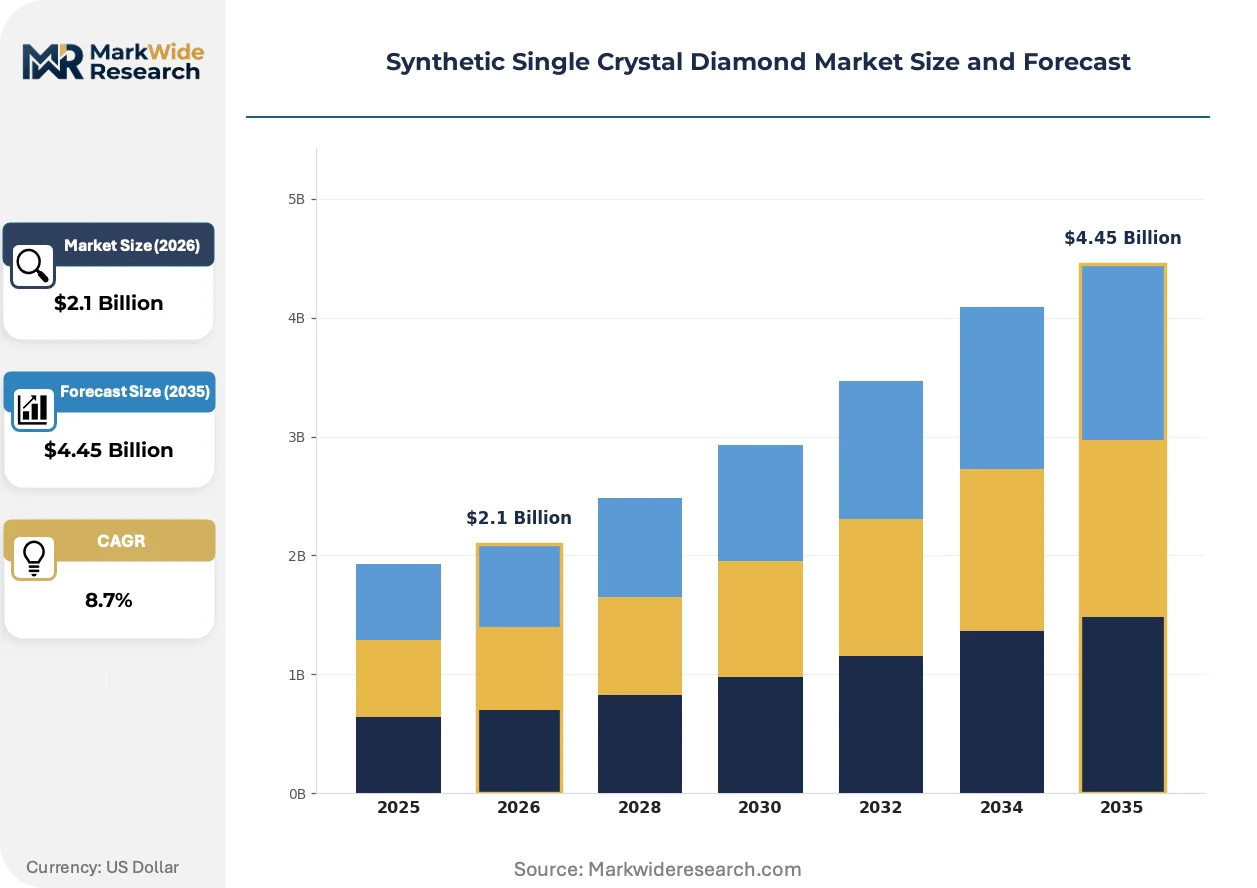
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gemstone, Industrial Diamond, Optical Diamond, Semiconductor Diamond Application: Electronics, Cutting Tools, Thermal Conductors, Medical Devices End User: Aerospace, Healthcare, Manufacturing, Telecommunications Technology: CVD, HPHT, Laser Technology, Chemical Vapor Deposition |
| Companies Covered | Orbray Co., Ltd., Henan Huanghe Whirlwind Co., Ltd., Element Six (De Beers Group), ILJIN Diamond Co., Ltd., Zhengzhou Sino-Crystal Diamond Co., Ltd., Sumitomo Electric Industries Ltd., Zhongnan Diamond Co., Ltd., Heyaru Group, Hyperion Materials & Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Single Crystal Diamond Market Emerging Trajectories
Process virtualization and substrate specification convergence are compressing traditional equipment qualification cycles while expanding addressable application spaces beyond legacy industrial cutting tools.
Multi-wafer microwave plasma CVD reactors are virtualizing single-crystal diamond growth economics by enabling simultaneous deposition across 150mm-equivalent areas. Semiconductor foundries in South Korea and Japan are qualifying these platforms for thermal management substrate supply. The technology is virtualizing batch processing economics previously confined to silicon carbide and gallium nitride epitaxy tools.
EPA emission rules for abrasive manufacturing impose particulate capture requirements on diamond synthesis facilities operating in the United States. Industrial diamond producers are retrofitting scrubber systems and migrating CVD operations to regions with renewable electricity sourcing. The regulations are accelerating facility relocation toward jurisdictions with cleaner grid profiles and streamlined environmental permitting.
Direct long-term agreements between diamond substrate suppliers and gallium nitride device manufacturers are displacing spot-market procurement for thermal spreader volumes. RF power amplifier and electric vehicle inverter producers in Japan and Germany are locking multi-year supply commitments with fixed pricing bands. This contract structure concentrates procurement authority within semiconductor device engineering teams rather than commodity purchasing functions.
Synthetic Single Crystal Diamond Market Segmentation
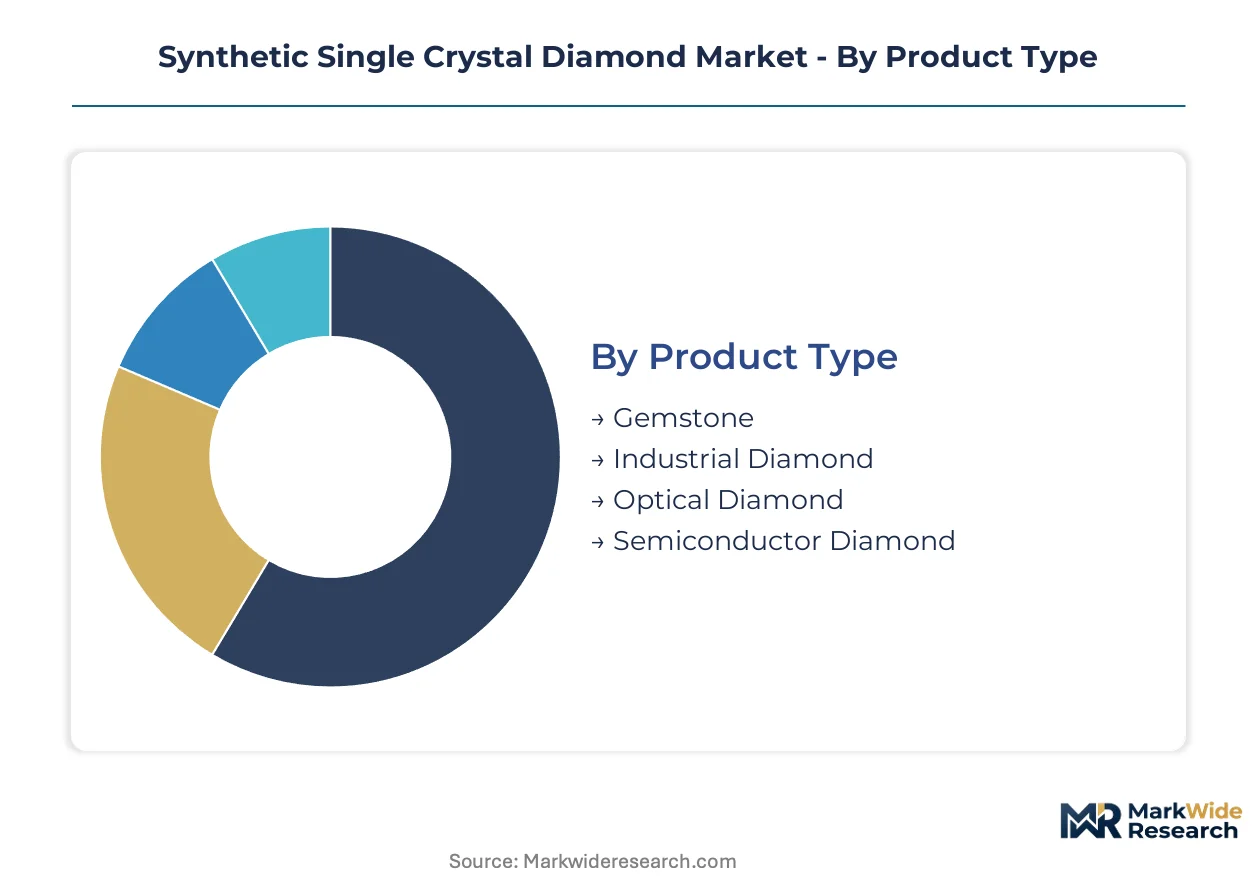
Segmentation in the synthetic single crystal diamond market reveals divergent maturity curves across product types and manufacturing technologies. Application-specific thermal and optical specifications drive fundamentally different procurement criteria and supplier qualification timelines.
Product Type:
Mature margin pools coexist with emerging high-growth categories as manufacturing methods specialize toward either volume commodity production or precision electronic-grade material.
- Semiconductor Diamond:Electronic-grade material engineered to defect densities below 10 parts per billion for thermal management substrates. Gallium nitride power electronics manufacturers in Japan and South Korea are qualifying these wafers for RF amplifier and electric vehicle inverter heat spreaders where thermal conductivity requirements exceed silicon carbide capabilities.
- Optical Diamond:Ultra-high-purity synthetic crystals specified for beam path components in high-energy laser systems. Fusion energy research facilities and directed-energy defense programs in Germany and the United States drive demand for chemical vapor deposition boules with exceptional optical transparency across infrared and ultraviolet spectra.
- Industrial Diamond:Precision cutting tool inserts and abrasive applications where hardness and wear resistance dominate performance criteria. EPA emission rules for abrasive manufacturing are accelerating facility relocation toward jurisdictions with renewable electricity sourcing and streamlined environmental permitting.
- Gemstone:Lab-grown diamond crystals for jewelry applications where EU REACH conflict-mineral traceability mandates redirect procurement toward certified synthetic sources with documented supply chain provenance.
Industrial Diamond retains volume leadership; Semiconductor Diamond holds the steepest expansion curve.
Application:
End-use concentration patterns reveal how thermal management requirements are restructuring procurement relationships across device manufacturing ecosystems.
- Thermal Conductors:Heat spreader substrates for power semiconductor packaging where microwave plasma CVD scaling reduces unit costs for electronic-grade material. Direct long-term agreements between diamond substrate suppliers and gallium nitride device manufacturers are displacing spot-market procurement in Japan and Germany.
- Electronics:Quantum sensing substrates leveraging nitrogen-vacancy center engineering for magnetometry applications. Japan's METI national technology roadmap subsidizes pilot line establishment for diamond semiconductor commercialization programs.
- Cutting Tools:Precision machining inserts for aerospace and automotive manufacturing where mature supply chains favor established HPHT production economics.
- Medical Devices:Surgical instruments and diagnostic probe components where biocompatibility and hardness specifications intersect.
Thermal Conductors command the highest value-per-kilogram; Electronics is climbing the fastest as quantum applications mature.
End User:
Customer-type segmentation exposes how fabrication cluster proximity determines logistics efficiency and just-in-time substrate supply feasibility.
- Manufacturing:Broad industrial base spanning cutting tools, precision machining, and thermal management components across German automotive and Japanese electronics supply chains.
- Telecommunications:RF power amplifier producers specifying diamond heat spreaders for base station infrastructure where thermal dissipation limits device performance.
- Aerospace:Directed-energy systems and satellite thermal management applications requiring radiation-hardened optical windows.
- Healthcare:Surgical instrument manufacturers and emerging quantum sensing diagnostic platforms with specialized purity requirements.
Manufacturing absorbs the largest absolute volumes; Telecommunications shows the most rapid demand acceleration as 5G infrastructure expands.
Technology:
Process economics hinge on deposition area scaling versus energy input efficiency trade-offs that vary dramatically by regional electricity pricing.
- CVD:Microwave plasma chemical vapor deposition enabling simultaneous deposition across 150mm-equivalent areas for wafer-grade production. Multi-million dollar reactor systems require 24-36 month depreciation cycles before yield optimization, concentrating investment among semiconductor foundry suppliers in South Korea.
- HPHT:High-pressure high-temperature synthesis using large-volume presses for gem-quality crystal growth. Electricity input volatility for press operations fluctuates with regional grid pricing, compressing margin predictability for European and Chinese producers.
- Laser Technology:Emerging precision processing methods for post-growth shaping and surface preparation of optical-grade components.
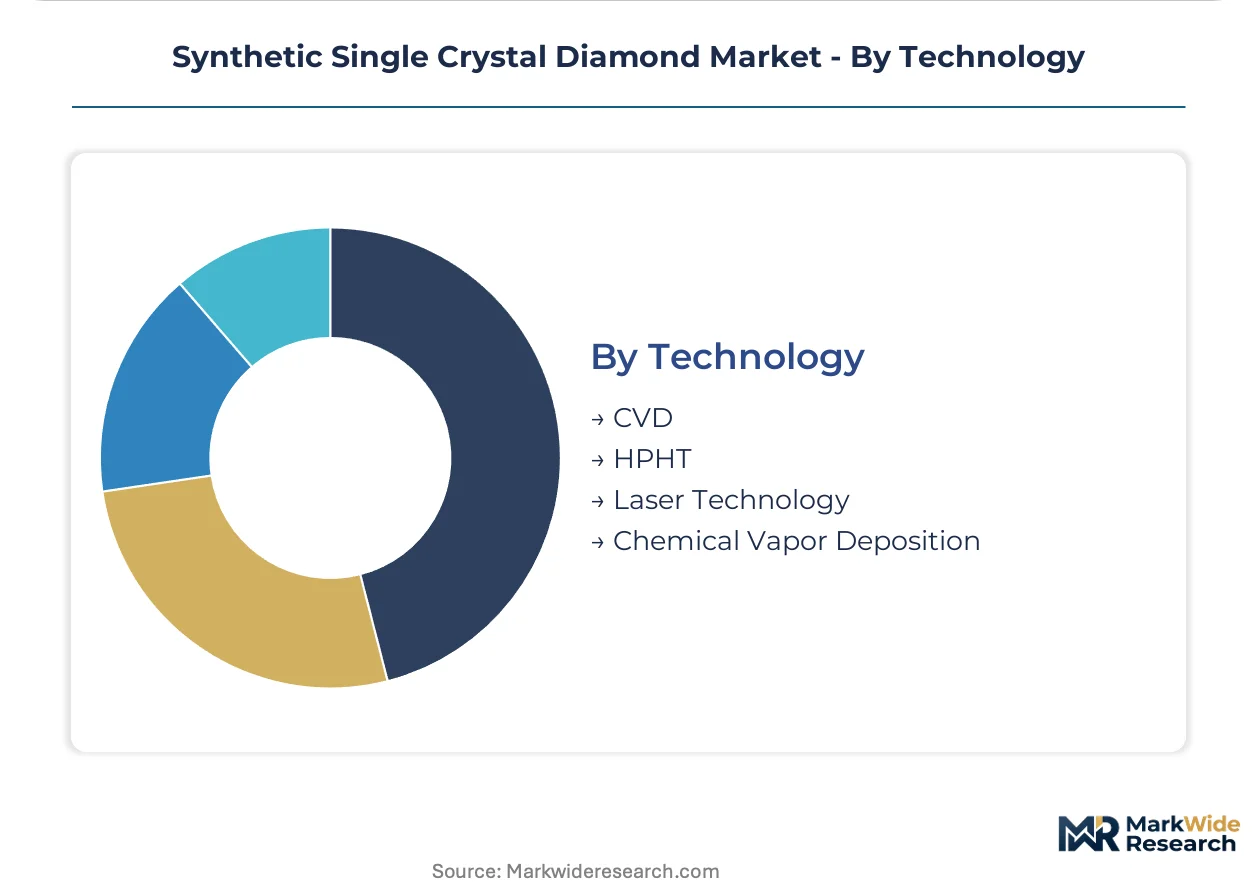
HPHT retains installed capacity leadership; CVD is gaining share fastest as electronic-grade specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor foundries and quantum research institutes concentrate procurement authority across East Asian fabrication clusters and European precision optics centers. Japan's METI national roadmap and South Korea's memory packaging ecosystem anchor thermal substrate demand. Germany's fusion energy programs and United States defense research facilities drive optical-grade specifications.
Japan
RF power amplifier manufacturers and electric vehicle inverter producers qualify diamond heat spreaders for gallium nitride packaging. METI subsidizes pilot line establishment through national technology roadmaps for diamond semiconductor commercialization. Tokyo-Osaka corridor hosts Sumitomo Electric Industries Ltd. boule growth operations for thermal spreader supply.
South Korea
Samsung and SK Hynix memory packaging lines integrate diamond substrates for thermal management in high-bandwidth modules. The country's national industrial policy prioritizes advanced materials for semiconductor self-sufficiency. Seoul-Incheon fabrication clusters enable just-in-time substrate supply from qualified CVD reactor operators.
Germany
Fusion energy research facilities specify synthetic single crystal diamond for high-energy laser beam path components. EU REACH substance restrictions redirect procurement toward certified lab-grown sources with documented provenance. Bavarian and North Rhine-Westphalian precision optics centers concentrate CVD boule qualification programs.
United States
Directed-energy defense programs and quantum sensing research platforms drive ultra-high-purity specifications for magnetometry substrates. EPA emission rules for abrasive manufacturing impose particulate capture requirements on domestic synthesis facilities. Greater Boston and Pacific Northwest research corridors anchor nitrogen-vacancy center engineering programs.
China
HPHT press operators serve precision cutting tool insert demand across automotive and aerospace supply chains. The country's dual carbon goals accelerate renewable electricity sourcing for energy-intensive synthesis operations. Henan Province concentrates large-volume press capacity for industrial diamond production.
Synthetic Single Crystal Diamond Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent technology vectors. CVD reactor operators and HPHT press fabricators occupy distinct margin pools with limited customer overlap. Three archetypes dominate: captive synthesis subsidiaries of diversified materials groups, independent HPHT specialists serving industrial cutting markets, and semiconductor-focused CVD platform operators. Capacity expansion and strategic partnerships constitute the primary competitive moves as electronic-grade qualification timelines extend procurement relationships.
Among Japanese fabricators, Sumitomo Electric Industries Ltd. and Orbray Co., Ltd. occupy positions within the precision electronics supply chain. Element Six represents the captive synthesis model anchored to European quantum sensing substrate demand. Henan Huanghe Whirlwind Co., Ltd. and Zhengzhou Sino-Crystal Diamond Co., Ltd. exemplify scale-driven HPHT operators serving industrial applications from Chinese manufacturing bases. ILJIN Diamond Co., Ltd. sits within the Korean specialist tier addressing optical window specifications.
| Leading Market Players |
|---|
| Orbray Co., Ltd. |
| Henan Huanghe Whirlwind Co., Ltd. |
| Element Six (De Beers Group) |
| ILJIN Diamond Co., Ltd. |
| Zhengzhou Sino-Crystal Diamond Co., Ltd. |
| Sumitomo Electric Industries Ltd. |
| Zhongnan Diamond Co., Ltd. |
| Heyaru Group |
| Hyperion Materials & Technologies |
| Others |
Supply Flow & Price Mechanics
Henan Province's HPHT press concentration anchors raw boule supply for industrial-grade material, concentrating margin capture with CVD reactor operators in South Korea and Japan who command premiums for electronic-grade specifications. Long-term offtake agreements between gallium nitride device manufacturers and diamond substrate suppliers are displacing spot-market procurement, locking pricing bands and transferring negotiation leverage to semiconductor engineering teams.
Pricing Analysis
Cost-plus contracts with electricity indexation dominate HPHT operations, while CVD platforms employ fixed-price multi-year agreements with yield-guarantee clauses. Price differentiation rests on SEMI certification tier and defect density grade, with unqualified material facing steep discounts. Cost compression in industrial diamond runs through Chinese electricity grid pricing volatility. RF power amplifier manufacturers show least price sensitivity; precision cutting tool distributors face margin squeeze from recycled natural stone competition.
Supply Chain Analysis
Export-control restrictions on microwave plasma CVD reactor technology limit equipment flows to Chinese operators, constraining their electronic-grade capacity expansion. Raw material supply draws from high-purity methane gas, tungsten carbide anvil components, and specialized steel press frames. Single-source vulnerability concentrates in Japanese microwave generator subsystems. Distribution runs through qualified semiconductor foundry channels rather than commodity distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among gallium nitride power device manufacturers has shifted buyer power toward volume-commitment leverage, fragmenting supplier pricing autonomy across thermal substrate tiers.
For Market Incumbents: Pre-empt CVD reactor operator encroachment by locking multi-year gallium nitride foundry partnerships before yield optimization completes. Secure captive methane supply through backward integration into high-purity gas production. METI subsidy qualification timelines present a regulatory lever to exclude late entrants from Japanese pilot line funding. For New Entrants and Emerging Players: German fusion energy research facilities represent underpenetrated demand for optical-grade boules with less stringent qualification timelines than semiconductor substrates. Target directed-energy defense procurement channels in the United States through ITAR-compliant partnership structures. White-space exists in laser post-processing services for CVD-grown rough crystals. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed HPHT operators in Henan Province facing electricity cost compression and environmental compliance retrofit requirements. Five-to-ten year viability hinges on CVD technology transfer feasibility. Watch for Japan METI roadmap funding announcements as inflection signals for electronic-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Wafer CVD Reactor Deployment | South Korean foundries qualify 150mm-equivalent platforms for thermal substrate supply. |
| SEMI Standards Certification Investment | Electronic-grade qualification timelines extend procurement relationships beyond spot markets. |
| Long-Term Supply Agreement Structuring | Gallium nitride device manufacturers lock fixed pricing bands through direct contracts. |
| Renewable Electricity Sourcing Migration | EPA emission rules accelerate facility relocation toward cleaner grid jurisdictions. |
| Quantum Sensing Substrate Partnership | Nitrogen-vacancy center engineering programs anchor ultra-high-purity CVD demand. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across microwave plasma CVD reactor manufacturers, HPHT press operators, gallium nitride device engineering teams, and semiconductor foundry procurement managers. Secondary validation drew from SEMI standards documentation, EPA emission rule filings, Japan METI technology roadmap publications, and EU REACH substance restriction updates. Bottom-up capacity estimates and top-down demand modeling were triangulated against customs trade data and national industrial statistics.
Calibration against historical CVD reactor installation rates and HPHT press electricity consumption patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, manufacturing technology, application, and end-user industry. CAGRs were derived from slope-intercept fitting against qualified substrate volume pipelines. Industry-specific forecast inputs incorporated gallium nitride power electronics thermal dissipation specifications and quantum sensing research funding trajectories.
Practitioners should monitor Japan METI subsidy allocation announcements and EU REACH enforcement actions on conflict-mineral traceability for early signals of demand inflection. Forecasts reflect documented assumptions regarding CVD yield improvement curves and regional electricity pricing stability. Material shifts in export-control regimes for plasma reactor technology or breakthroughs in laser-assisted post-growth processing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Zinc Oxide Nanoparticles Market
Semiconductor Material
Indium Gallium Zinc Oxide Market
Semiconductor Material
Encapsulant Market
Semiconductor Material
Asia-Pacific Transparent Conductive Films Market
Semiconductor Material
Global Silicon Carbide (SIC) Market
Semiconductor Material
Niobium Hydride Market
Semiconductor Material
Electronic Assembly Materials Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
Silicon Nitride Market
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
Glass Substrate in Semiconductor Market
Semiconductor Material
Glass Wafer Market
Semiconductor Material
5G Substrate Materials Market
Semiconductor Material
Tungsten Market
Semiconductor Material
Gallium Market
Semiconductor Material
Terbium Oxide Market