
 LED Lighting Controllers Market | 2026-2036
LED Lighting Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
LED Lighting Controllers Market Outlook
Multi-source procurement for semiconductor components is pivoting toward captive sourcing as supply volatility reshapes LED controller manufacturing. Acuity Brands Lighting Inc. leverages vertical integration across luminaire and control design to buffer input cost swings. Lutron Electronics Co., Inc. sustains technology leadership in precision dimming architectures for premium commercial installations. Signify Holding anchors global volume through manufacturing scale and direct channel control in European and Asian markets.
LED lighting controllers are electronic devices that regulate luminous output, color temperature, and operational scheduling through protocols such as DALI, Zigbee, or Bluetooth Low Energy, typically incorporating microcontrollers, power management ICs, and RF transceivers to enable networked or standalone command of solid-state lighting systems. Their primary purpose is to optimize energy consumption, extend luminaire lifespan, and enable human-centric or circadian lighting schemes in built environments. Smart controllers and wireless controllers are capturing the fastest expansion as facility managers prioritize retrofit compatibility and IoT interoperability over wired infrastructure. DALI retains structural importance in new commercial construction where centralized building management systems mandate hardwired reliability and standardized addressing.
The EU Green Deal and Ecodesign Directive shape product standards by mandating minimum controllability requirements for luminaires sold in member states, while the FCC in the United States governs RF emissions for Zigbee and Wi-Fi enabled devices entering the North American market. REACH compliance in Europe further constrains material selection for PCB assemblies and housing components. Stakeholders must monitor evolving interoperability certifications and energy-labeling thresholds as procurement specifications harden across public and private building portfolios.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing retrofit timelines across commercial real estate, forcing facility managers to accelerate DALI and wireless controller deployments ahead of statutory deadlines.
Growth Catalysts
- Municipal streetlight modernization:German cities are mandating networked LED retrofits with centralized dimming protocols, driving bulk procurement of DALI-compliant controllers for urban infrastructure.
- REACH material compliance:ECHA restrictions on hazardous substances in PCB assemblies are pushing manufacturers toward lead-free soldering and recycled housing polymers, opening premium positioning for certified suppliers.
- Bluetooth Low Energy mesh:This protocol stack is displacing proprietary RF in retail and hospitality retrofits where rewiring costs would exceed hardware budgets by factors of three or more.
Market Restraints
- MCU foundry concentration:Taiwan-based semiconductor fabrication accounts for the majority of microcontroller supply for LED controllers, exposing procurement to geopolitical shipment volatility.
- Copper and rare earth magnet pricing:Inductor and transformer windings face input cost swings that compress margin on economy-tier controller SKUs below sustainable thresholds.
- DALI-2 certification backlog:IEC 62386 compliance testing queues at accredited laboratories extend product launch timelines by four to six months for new market entrants.
Strategic Opportunities
- Circadian lighting in healthcare:German hospital networks are piloting tunable-white controllers for patient recovery protocols, creating a reference market for human-centric specification.
- Zigbee-to-Matter bridge architectures:Convergence of legacy Zigbee installations with Matter protocol ecosystems enables retrofit hardware sales without full infrastructure replacement.
- EU Recovery and Resilience Facility:Member state disbursements for building energy efficiency are channeling public procurement toward smart controller bundles with guaranteed connectivity interoperability.
Industry Challenges
- Firmware security certification:IEC 62443 industrial cybersecurity standards for networked lighting controllers require specialized engineering talent scarce outside established automation hubs.
- Legacy fluorescent ballast interoperability:Retrofit projects demand hybrid controllers capable of staged migration from magnetic ballast circuits, complicating SKU proliferation and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Lighting Controllers Market |
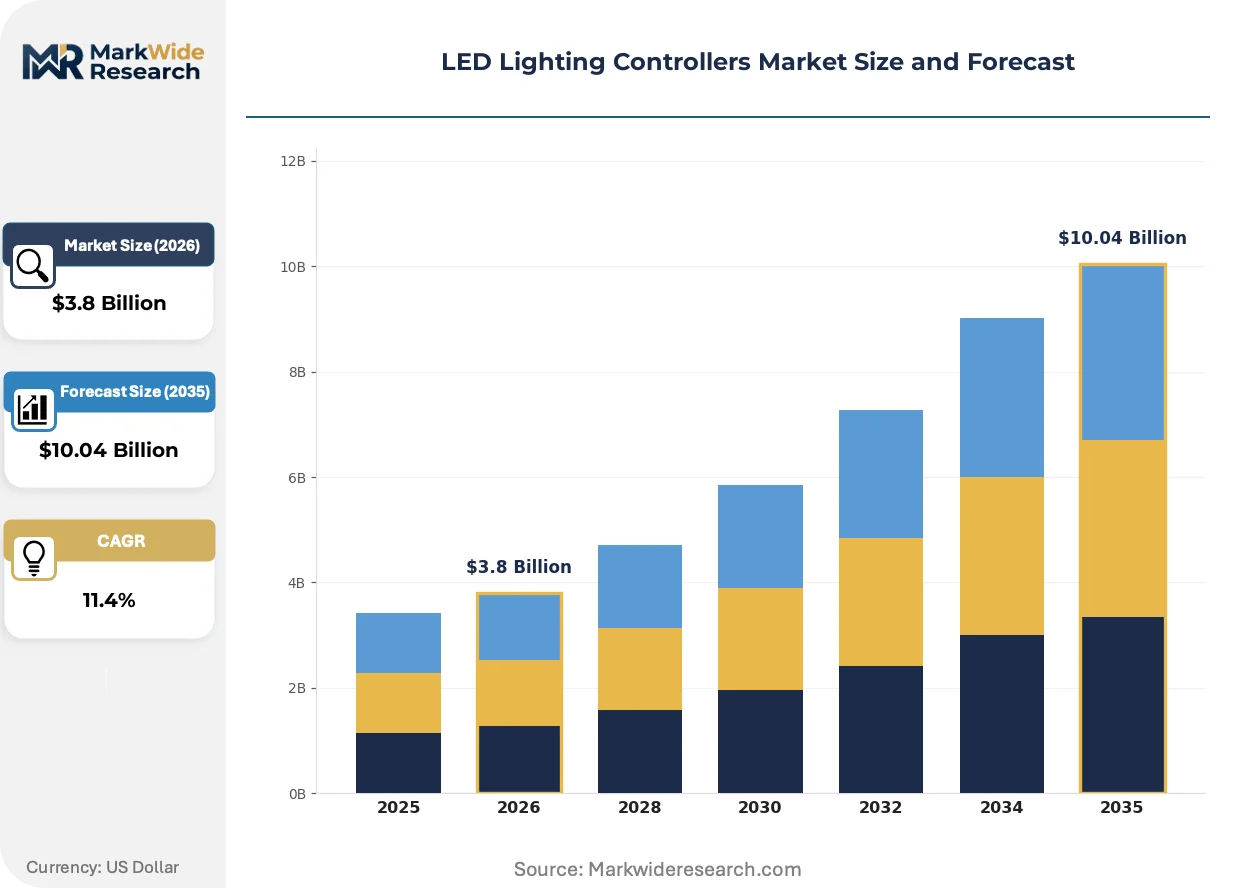
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dimmer Switches, Smart Controllers, Wireless Controllers, Lighting Management Systems Technology: Wi-Fi, Zigbee, Bluetooth, DALI Application: Residential Lighting, Commercial Lighting, Outdoor Lighting, Industrial Lighting End User: Contractors, Electricians, Facility Managers, Homeowners |
| Companies Covered | Acuity Brands Lighting Inc., Lutron Electronics Co., Inc., Leviton Manufacturing Co., Inc., ABB Group, Signify Holding, Cree, Inc., Douglas Lighting Controls, Inc., Hubbell Control Solutions, Echelon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Lighting Controllers Market Strategic Shifts
Wireless protocol maturation and regulatory energy-performance mandates are converging to restructure how controllers are specified, procured, and integrated into building automation hierarchies.
Power-over-Ethernet (PoE) controller architectures are absorbing data and electrical distribution into single-cable infrastructure for commercial office fit-outs. Corporate real estate teams in the Netherlands and Denmark are specifying PoE-native luminaires for new construction, eliminating separate low-voltage wiring trades. This convergence is compressing total installed cost premiums versus conventional DALI wired systems to under fifteen percent at scale.
CSRD corporate sustainability reporting requirements are mandating granular energy disclosure for commercial building portfolios. The directive forces asset managers to deploy sub-circuit metering and networked lighting controls capable of automated kWh attribution by tenant zone. German REITs and French office landlords are responding fastest, embedding controller specifications into green lease clauses ahead of 2025 reporting deadlines.
Facility management procurement is consolidating vendor relationships around full-stack lighting-control providers capable of warranty-backed performance contracting. German municipal utilities and Swedish housing cooperatives are displacing fragmented component sourcing with ten-year service agreements bundling hardware, commissioning, and cloud-based energy analytics. This bundling is visible most acutely in public-sector tenders where total-cost-of-ownership scoring outweighs capital expenditure minimization.
LED Lighting Controllers Market Segmentation
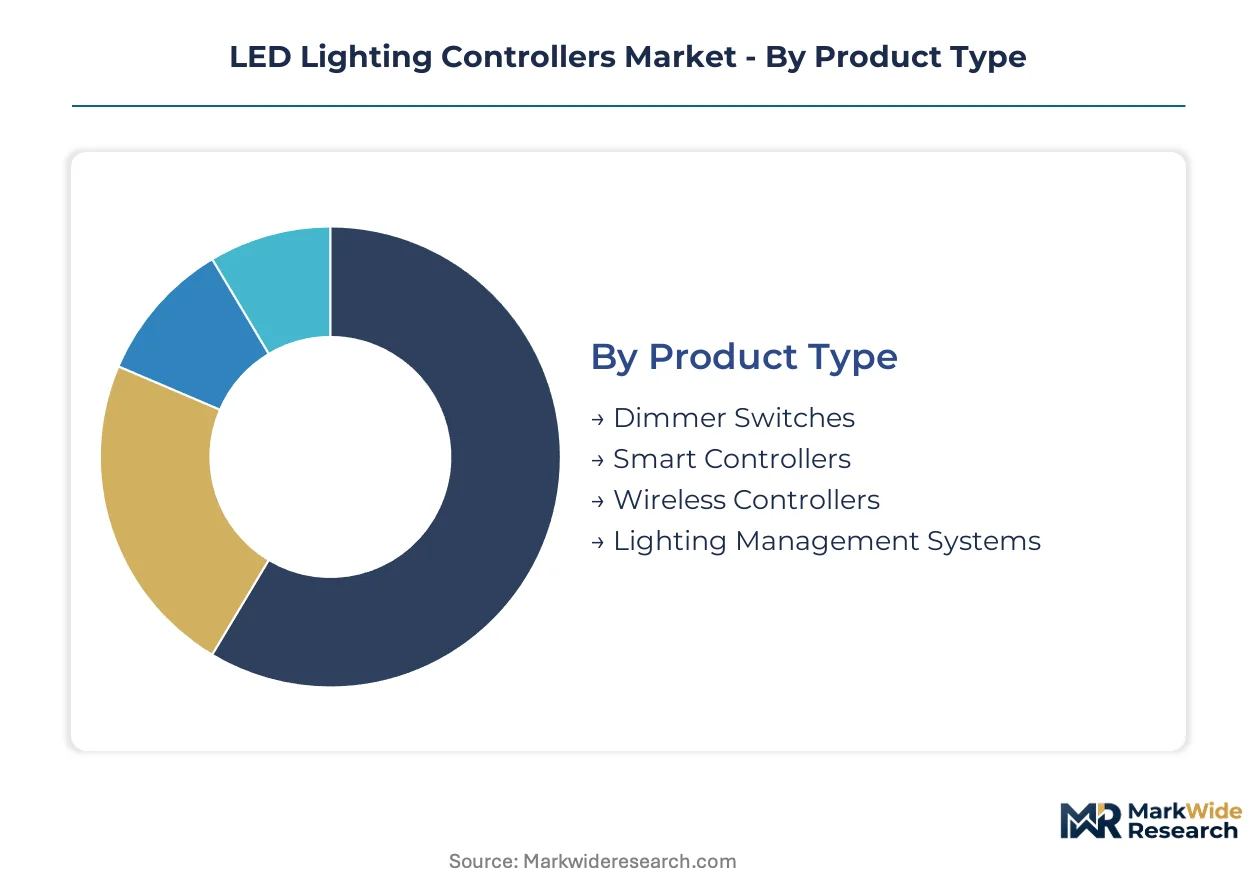
LED lighting controllers fragment across four distinct category axes, each reflecting divergent buyer priorities around installation cost, protocol interoperability, and energy accountability. Procurement specifications differ sharply between new construction and retrofit contexts, with technology choices locking in long-term building automation compatibility.
Product Type:
Volume concentrates in entry-level hardware, while premium capture flows toward integrated systems with cloud connectivity and predictive maintenance capabilities.
- Dimmer Switches:Analog and digital phase-cut circuits dominate residential replacement cycles, with TRIAC-based designs retaining cost advantage in single-room retrofits. Demand clusters in German and French residential renovation markets where homeowners prioritize fixture compatibility over protocol sophistication.
- Smart Controllers:Microprocessor-based units with embedded sensors and API-accessible telemetry are climbing the fastest as CSRD disclosure requirements force granular energy attribution by tenant zone. Corporate real estate teams in the Netherlands specify these for office fit-outs with automated daylight harvesting.
- Wireless Controllers:Battery-powered or mains-fed units using mesh networking eliminate rewiring costs in heritage building retrofits. Hospitality operators in Italy and Spain deploy these where structural preservation rules prohibit cable runs.
- Lighting Management Systems:Centralized software-hardware bundles with BMS integration serve municipal streetlight networks and airport campuses. German municipal utilities bundle ten-year service agreements with these platforms.
Today's leader: Dimmer Switches. Tomorrow's challenger: Smart Controllers.
Technology:
Protocol selection locks in supply chain sourcing, RF certification pathways, and long-term interoperability with adjacent building systems.
- Wi-Fi:IP-native controllers leverage existing enterprise WLAN infrastructure, reducing gateway hardware requirements. Facility managers in Danish commercial offices favor these where IT departments control network security policies.
- Zigbee:Mesh topology with sub-GHz penetration dominates industrial warehouses and multi-floor hospitality installations. Swedish housing cooperatives specify Zigbee for its proven interoperability with legacy BMS protocols.
- Bluetooth:Low-energy mesh stacks displace proprietary RF in retail and museum retrofits where smartphone commissioning accelerates installation timelines. French luxury retailers deploy these for beacon-enabled customer analytics integration.
- DALI:Hardwired digital addressing remains mandatory in German healthcare construction and airport terminals where electromagnetic resilience and centralized fault monitoring outweigh installation cost premiums.
Installed base dominance: DALI. Expansion trajectory steepest: Bluetooth.
Application:
End-use context dictates controller durability ratings, enclosure IP specifications, and scheduling complexity requirements.
- Residential Lighting:Consumer-grade dimmers and app-controlled color-tuning units serve renovation and new-build housing. German single-family homebuilders specify these with KNX home automation pre-wiring.
- Commercial Lighting:Networked controllers with occupancy sensing and circadian programming dominate office and retail fit-outs. French REITs embed specifications into green lease clauses ahead of CSRD deadlines.
- Outdoor Lighting:Weather-hardened controllers with astronomical clocks and remote monitoring serve municipal streetlight and highway tunnel networks. German cities mandate networked LED retrofits with centralized dimming protocols.
- Industrial Lighting:High-bay controllers with high-temperature ratings and instant-on capabilities serve manufacturing and logistics facilities. Automotive plants in the Czech Republic specify these with DALI-2 emergency lighting integration.
Current revenue concentration: Commercial Lighting. Fastest application gain: Outdoor Lighting.
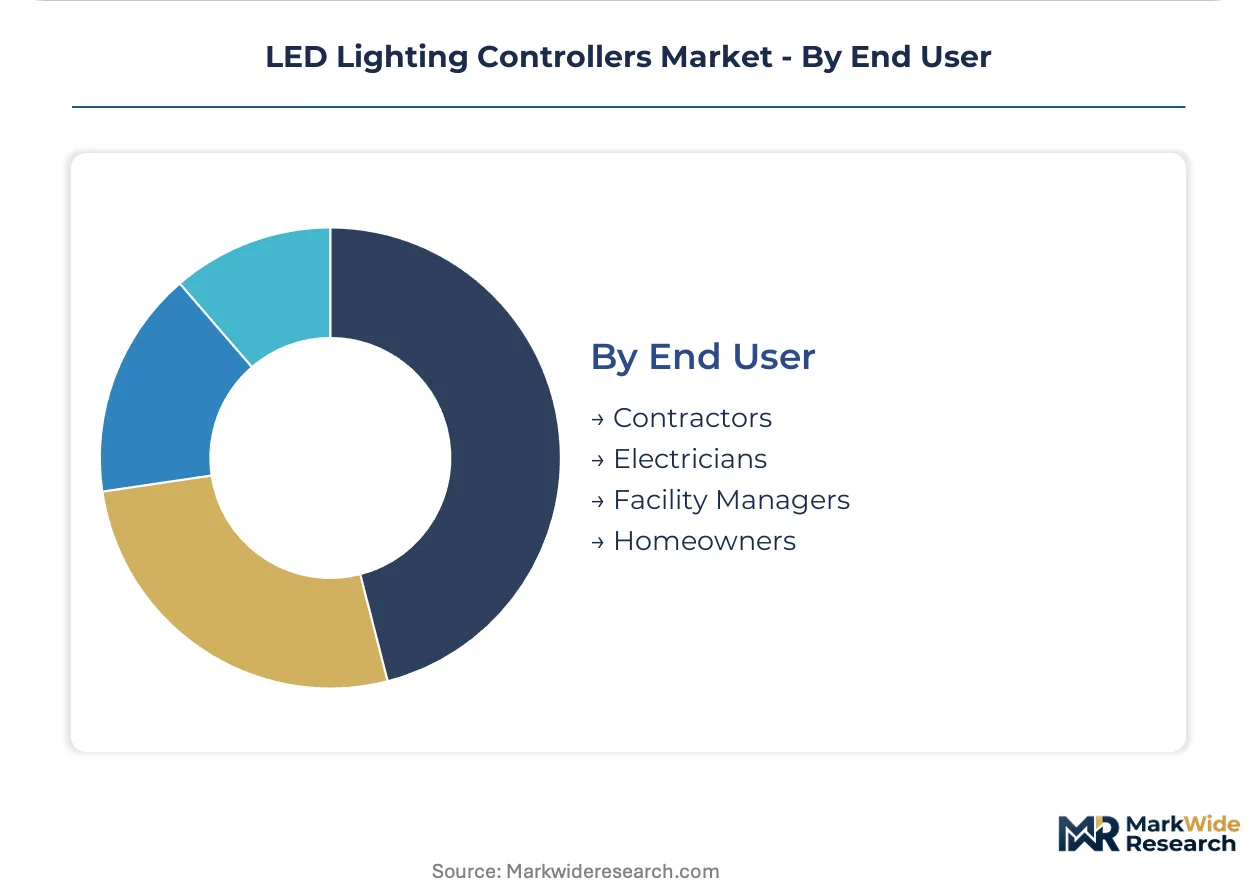
End User:
Buyer technical sophistication and procurement authority shape controller specification complexity and channel economics.
- Contractors:Generalist electrical contractors prioritize plug-and-play commissioning and multi-brand compatibility to minimize callback risk. German mid-size contractors favor DALI-2 certified units with guaranteed interoperability.
- Electricians:Independent installers serving residential and small commercial accounts stock economy-tier dimmers and basic wireless kits. Italian electricians drive Bluetooth controller volume through smartphone-app commissioning preferences.
- Facility Managers:Corporate and institutional asset managers specify networked systems with energy analytics dashboards and predictive maintenance alerts. Dutch facility management firms consolidate vendor relationships around full-stack providers.
- Homeowners:DIY purchasers prioritize retail availability, app store ratings, and voice assistant compatibility. French and German consumers increasingly demand Matter protocol support for cross-ecosystem interoperability.
Specification authority today: Facility Managers. Purchasing volume growth: Homeowners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's municipal streetlight modernization programs anchor LED controller demand across Europe. Smart building retrofits in commercial real estate accelerate deployments. Regulatory tightening under the EU Green Deal compresses retrofit timelines.
Germany
Municipal streetlight networks and healthcare construction drive bulk procurement of DALI-compliant controllers. The EU Green Deal mandates minimum controllability requirements for luminaires sold in member states. Bavarian hospital networks pilot tunable-white controllers for patient recovery protocols.
United States
Corporate real estate teams prioritize PoE-native luminaires for new commercial office fit-outs. The FCC governs RF emissions for Zigbee and Wi-Fi enabled devices entering the North American market. Facility managers in Greater Boston specify networked systems with energy analytics dashboards.
Netherlands
Corporate real estate teams specify smart controllers for automated daylight harvesting in office fit-outs. CSRD corporate sustainability reporting requirements mandate granular energy disclosure for commercial building portfolios. Randstad municipal utilities bundle ten-year service agreements with full-stack lighting-control providers.
France
REITs embed controller specifications into green lease clauses ahead of CSRD reporting deadlines. REACH compliance constrains material selection for PCB assemblies and housing components. Luxury retailers in Paris deploy Bluetooth mesh controllers for beacon-enabled customer analytics integration.
Sweden
Housing cooperatives specify Zigbee controllers for proven interoperability with legacy BMS protocols. The EU F-Gas Regulation tightens energy-efficiency mandates across member states. Stockholm facility management firms consolidate vendor relationships around warranty-backed performance contracting.
LED Lighting Controllers Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue wireless protocol specialization and cloud-native architectures. The vendor base spans multinational electrical conglomerates with captive luminaire divisions, precision dimming specialists, and component-scale manufacturers. Three archetypes dominate: full-stack providers bundling hardware with long-term service agreements, protocol-agnostic platform builders, and captive suppliers integrated into lighting fixture production. Competitive moves concentrate on backward integration into semiconductor sourcing and strategic partnerships with building automation system vendors.
Among North American incumbents, Acuity Brands Lighting Inc. and Lutron Electronics Co., Inc. exemplify contrasting positioning within the premium tier. Acuity Brands occupies a position anchored in vertical integration across luminaire and control design, buffering input cost volatility through captive sourcing. Lutron Electronics sits within the precision dimming specialist archetype, sustaining technology leadership in premium commercial installations. Signify Holding represents the scale-driven multinational model, anchoring global volume through manufacturing scale and direct channel control.
| Leading Market Players |
|---|
| Acuity Brands Lighting Inc. |
| Lutron Electronics Co., Inc. |
| Leviton Manufacturing Co., Inc. |
| ABB Group |
| Signify Holding |
| Cree, Inc. |
| Douglas Lighting Controls, Inc. |
| Hubbell Control Solutions |
| Echelon Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in German and Italian controller manufacturing anchor supply discipline through generational ownership horizons that resist margin erosion during semiconductor cost spikes. Their patient capital buffers pricing power against quarterly earnings pressure, while captive relationships with municipal procurement offices lock in multi-year service contracts that stabilize revenue visibility.
Pricing Analysis
Input-cost pass-through from microcontroller foundries and copper magnet wire suppliers compresses margins on economy-tier dimmer switches while premium smart controllers retain pricing power through firmware differentiation. Three-tier pricing structure across premium, standard, and economy levels separates DALI-2 certified hospital-grade units from basic TRIAC residential hardware. Pricing pressure stems from Taiwanese foundry concentration exposing procurement to shipment volatility. Facility managers in commercial retrofits exhibit lowest price sensitivity where ten-year service agreements bundle hardware with energy analytics.
Supply Chain Analysis
Dual-sourcing requirements mandated by German municipal utilities and Dutch corporate real estate teams force qualification of secondary microcontroller suppliers in South Korea and the United States alongside dominant Taiwanese sources. Controller manufacturing draws from copper inductor windings, rare earth magnets, and FR-4 PCB substrates. Single-source vulnerability in advanced node semiconductor fabrication threatens production continuity. Distribution runs through electrical wholesale distributors serving contractor channels and direct OEM supply agreements with luminaire manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
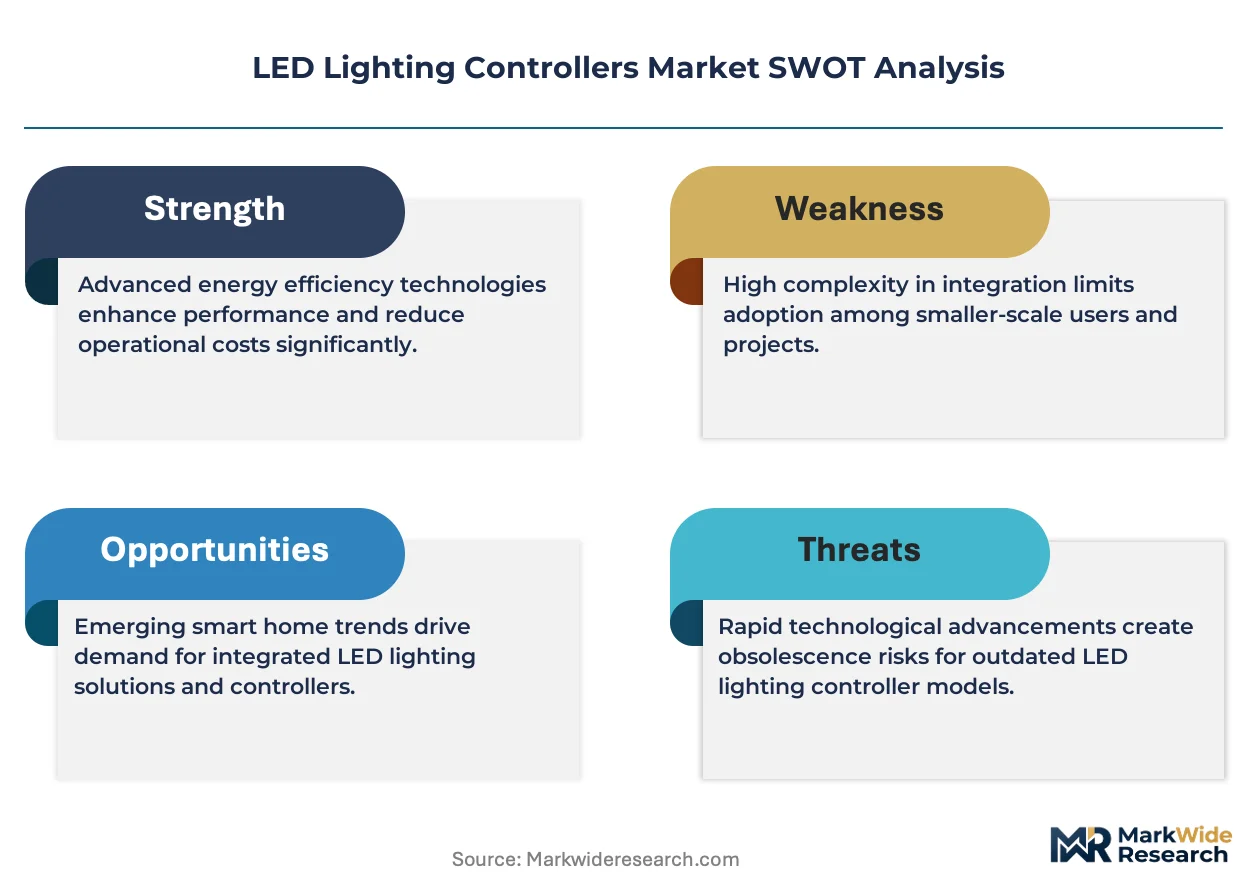
LED lighting controllers represent a late-cycle quality story as CSRD disclosure mandates shift procurement authority toward facility managers demanding predictive maintenance capabilities and sub-circuit metering precision.
For Market Incumbents: To counter Bluetooth Low Energy mesh entrants displacing proprietary RF in retail retrofits, Acuity Brands and Signify should deepen backward integration into power management IC sourcing while accelerating DALI-2 certification investment to defend specification authority in German healthcare construction. For New Entrants and Emerging Players: Enter via circadian lighting pilots in Bavarian hospital networks where tunable-white controller specifications remain unsettled, leveraging smartphone commissioning workflows to bypass entrenched contractor relationships in Italian hospitality retrofits. For Investors and Strategic Acquirers: Valuations sit cheapest among protocol-agnostic platform builders with Matter bridge architectures capable of converging legacy Zigbee installations. Long-term viability hinges on cybersecurity certification depth under IEC 62443 standards. Watch German REIT green lease clause adoption rates as the inflection signal for premium controller specification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| DALI-2 Certification Acceleration | Compresses four-to-six month laboratory testing queues that delay new entrant product launches. |
| PoE-Native Luminaire Integration | Eliminates separate low-voltage wiring trades in Dutch and Danish corporate office fit-outs. |
| Bluetooth Mesh Protocol Specialization | Displaces proprietary RF in Italian and Spanish heritage building retrofits where rewiring is prohibited. |
| Circadian Lighting Pilot Expansion | Creates reference specifications for human-centric lighting in German hospital recovery protocols. |
| Cybersecurity Talent Acquisition | Addresses IEC 62443 certification scarcity that constrains networked controller development timelines. |
Study Parameters
Multiple input streams — facility manager interviews, luminaire OEM procurement discussions, municipal tender document analysis, and semiconductor distributor channel checks — were reconciled against secondary validation from SEC filings, EU public procurement databases, and ECHA REACH restriction updates. Bottom-up unit demand modeling triangulated with top-down addressable market sizing from building stock databases and retrofit penetration assumptions.
Data-stream reconciliation anchored volume projections across technology, application, and end-user segmentation dimensions with protocol adoption curves and regulatory deadline impacts modeled explicitly. CAGRs derived from logistic diffusion curves fitted to historical technology substitution patterns in building automation, with PoE infrastructure deployment rates and CSRD compliance timelines treated as exogenous demand shapers.
Inputs from primary stakeholder interviews were available through the study window; gaps in real-time foundry utilization data introduce uncertainty bands around microcontroller cost pass-through assumptions. Deviation in German municipal streetlight modernization appropriations or Taiwan semiconductor export licensing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Lighting Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
Microled Market
LED
UK Indoor LED Lighting Market
LED
Programmable LED Drivers Market
LED
LED Display Control Card Market
LED
Global Chip on Board (COB) Light Emitting Diode Market
LED
Infrared (IR) LED Market
LED
Europe Indoor LED Lighting Market
LED
Middle East and Africa Outdoor LED Lighting Market
LED
LED Phosphor Materials Market
LED
Organic Light Emitting Diode (OLED) Market
LED
Saudi Arabia LED Lights Market
LED
Japan LED Market
LED
Europe LED Packaging Market
LED
US LED Downlight Market