
 Neurosurgical Drills Market | 2026-2036
Neurosurgical Drills Market Size, Share, and Industry Trends Forecast 2026-2036
Neurosurgical Drills Market Foresight
Aftermarket service revenue is rewriting profit dynamics across the neurosurgical drills landscape. Medtronic plc leverages its broad installed base to sustain recurring service contracts. Stryker Corporation anchors its position through direct hospital channel control. Johnson & Johnson (DePuy Synthes) differentiates via integrated power system ecosystems that lock in replacement part demand.
Neurosurgical drills are precision motor-driven instruments engineered to cut, shape, or remove cranial and spinal bone with rotational speeds typically ranging from 10,000 to 80,000 RPM and integrated irrigation to prevent thermal necrosis. Electric drills dominate capital procurement budgets due to torque consistency and programmable speed profiles, while pneumatic drills retain share in cost-sensitive settings where sterilization durability matters. Wireless and battery-powered configurations are capturing fastest-growing demand as operating room mobility requirements intensify and cord management constraints drive preference for untethered platforms.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for powered surgical instruments. ISO 13485 quality management compliance and IEC 60601 electrical safety standards further constrain vendor participation. Stakeholders must monitor reimbursement coding evolution for computer-navigated drilling procedures and assess whether smart drilling technology investments align with emerging pay-for-performance frameworks.
Market Dynamics
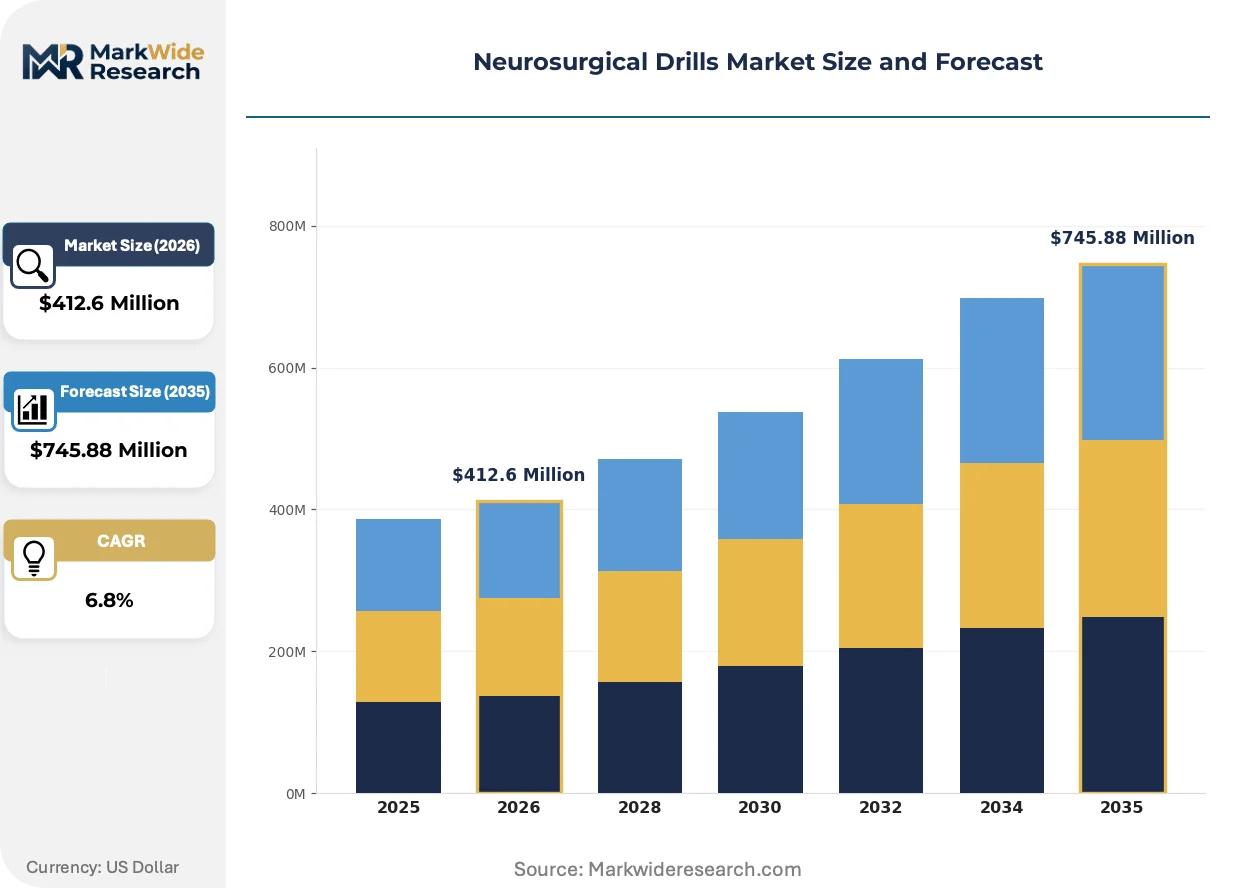
The transition from pneumatic to electric and battery-powered neurosurgical drill platforms is restructuring capital procurement cycles and aftermarket revenue streams across hospital systems and ambulatory surgical centers.
Growth Catalysts
- Battery-powered mobility:Wireless drill configurations eliminate cord management constraints in crowded operating theaters. Surgical teams at high-volume cranial centers in the United States prioritize untethered platforms for complex microsurgical approaches.
- FDA 510(k) pathway efficiency:Streamlined clearance mechanisms for powered surgical instruments accelerate product iterations. Manufacturers leverage predicate device strategies to reduce time-to-market for next-generation handpieces.
- EU MDR harmonization:Unified technical documentation requirements across European member states reduce regulatory fragmentation. Vendors consolidate quality management systems under ISO 13485 to serve multiple jurisdictions with single audits.
Market Restraints
- High-precision motor supply concentration:Brushless DC motor production for surgical applications clusters in Germany and Japan. Disruptions to these supplier bases propagate delays across OEM assembly lines.
- EU MDR clinical evidence burdens:Enhanced technical documentation requirements for Class IIa powered instruments extend certification timelines. Smaller manufacturers face capital constraints for clinical evaluation reports.
- Reusable sterilization durability limits:Pneumatic drill handpieces degrade under repeated autoclave cycles. Thermal stress fractures in aluminum housings accelerate replacement frequency beyond capital budget cycles.
Strategic Opportunities
- Computer-navigated drilling integration:Convergence of optical tracking systems with power drill handpieces enables real-time trajectory guidance. Academic medical centers in Germany pilot neuronavigation-compatible platforms for skull base approaches.
- India neurosurgical infrastructure expansion:Government hospital modernization programs create first-time electric drill procurement demand. State-level health missions prioritize cranial trauma capacity in tier-2 cities.
- Service contract unbundling:Third-party independent service organizations capture maintenance revenue from legacy installed bases. Specialized repair shops in Japan develop proprietary torque calibration capabilities.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies for new polymer housings extend development timelines. Contract research organization capacity constraints delay regulatory submissions.
- Legacy system integration friction:Electric drill platforms require updated OR electrical infrastructure. Hospitals with aging power distribution systems face retrofit costs that stall procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurosurgical Drills Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Drills, Pneumatic Drills, Manual Drills, Ultrasonic Drills End User: Hospitals, Specialty Clinics, Research Facilities, Rehabilitation Centers Technology: Battery-Powered, Corded, Wireless, Smart Drilling Application: Skull Surgery, Tumor Resection, Trauma Surgery, Neuroscience Research |
| Companies Covered | Johnson & Johnson (DePuy Synthes), Smith & Nephew plc, Medtronic plc, De Soutter Medical Ltd., Integra LifeSciences Holdings Corporation, Stryker Corporation, B. Braun SE, Conmed Corporation, Zimmer Biomet Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurosurgical Drills Market Shifts & Advancements
Smart drilling technology is compressing the boundary between mechanical bone removal and real-time surgical guidance, forcing vendors to rearchitect product roadmaps around sensor integration rather than motor performance alone.
Brushless motor controllers with embedded torque feedback algorithms are collapsing the distinction between high-speed cutting and delicate finishing operations within single handpiece units. Neurosurgical teams at quaternary referral centers in the United States adopt these platforms to reduce instrument changes during complex spinal decompressions. The consolidation of multiple surgical steps into unified devices is compressing per-procedure instrument costs and reshaping sterilization workflow economics.
EU MDR technical documentation requirements for powered surgical instruments are elevating clinical evidence standards for drill system biocompatibility and electrical safety. Manufacturers must now submit comprehensive risk management files spanning entire product families rather than individual SKUs. The spinal fusion segment faces the steepest compliance burden as reusable drill attachments undergo enhanced sterilization validation protocols.
Hospital procurement committees are unbundling capital equipment acquisition from long-term service agreements. IDNs in Germany and Japan now negotiate drill system purchases through centralized frameworks while sourcing maintenance through competitive third-party tenders. This bifurcation is compressing OEM service margins and accelerating independent calibration laboratory certification across European markets.
Neurosurgical Drills Market Segmentation
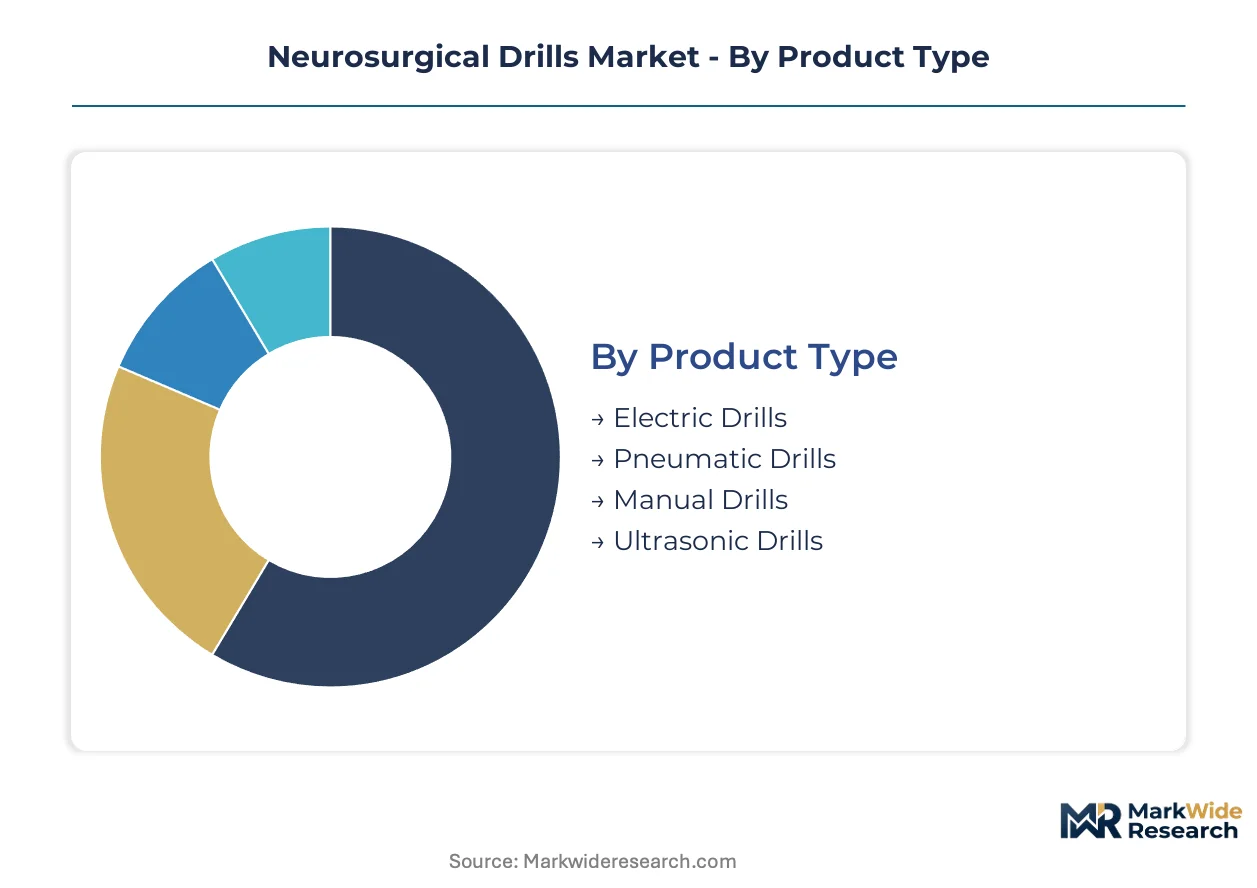
Neurosurgical drill segmentation reveals how procurement priorities diverge across clinical settings and technological maturity. Hospital capital committees weight torque precision against sterilization durability differently than ambulatory operators or academic researchers.
Product Type:
Mature electric platforms anchor hospital procurement budgets while emerging battery architectures reshape mobility requirements in crowded operating theaters.
- Electric Drills:Brushless DC motor systems deliver consistent torque across programmable speed profiles from 10,000 to 80,000 RPM. Academic medical centers in the United States prioritize these platforms for complex cranial approaches requiring sustained cutting power without pneumatic compressor dependency.
- Pneumatic Drills:Compressed-air-driven handpieces withstand aggressive autoclave cycles but suffer from torque variability at low speeds. Cost-sensitive facilities in India retain these systems where sterilization durability outweighs precision demands.
- Manual Drills:Hand-cranked instruments persist in resource-constrained settings and emergency backup scenarios.
- Ultrasonic Drills:Piezoelectric bone removal systems minimize thermal necrosis risk in delicate skull base approaches.
Electric drills handle the majority of throughput; ultrasonic systems are expanding most quickly in specialized skull base units.
End User:
Volume concentration follows procedure reimbursement tiers while customer type determines service contract structures and replacement part demand.
- Hospitals:Quaternary referral centers in Germany and Japan deploy integrated power system ecosystems with neuronavigation compatibility. These institutions generate recurring aftermarket revenue through centralized procurement frameworks and mandatory calibration protocols.
- Specialty Clinics:Ambulatory surgical centers in the United States favor compact battery-powered platforms for outpatient spinal decompressions. Medicare reimbursement coding for same-day procedures drives capital efficiency priorities over feature depth.
- Research Facilities:Academic laboratories source modified drill systems for ex vivo biomechanical studies and device prototyping.
- Rehabilitation Centers:Post-surgical care settings require minimal drilling capacity for hardware adjustment procedures.
Hospitals command the dominant share of installed base; specialty clinics are gaining share fastest as outpatient spine migration accelerates.
Technology:
Power delivery architecture determines cord management constraints, OR mobility, and integration complexity with surgical navigation systems.
- Battery-Powered:Lithium-ion cell configurations eliminate tethering requirements and reduce trip hazards in crowded surgical fields. High-volume cranial centers in Japan prioritize these platforms for microsurgical approaches demanding unrestricted handpiece positioning.
- Wireless:Inductive charging dock systems enable continuous operation without battery swap interruptions. German hospital networks pilot these configurations to streamline sterilization workflow economics.
- Corded:Mains-powered electric drills retain share in fixed-OR installations with established electrical infrastructure.
- Smart Drilling:Embedded torque feedback algorithms and optical tracking integration enable real-time trajectory guidance.
Corded technology maintains the largest installed footprint; smart drilling platforms show the steepest adoption trajectory among academic medical centers.
Application:
Procedure type dictates speed-torque requirements, irrigation integration needs, and compatibility with neuronavigation workflows.
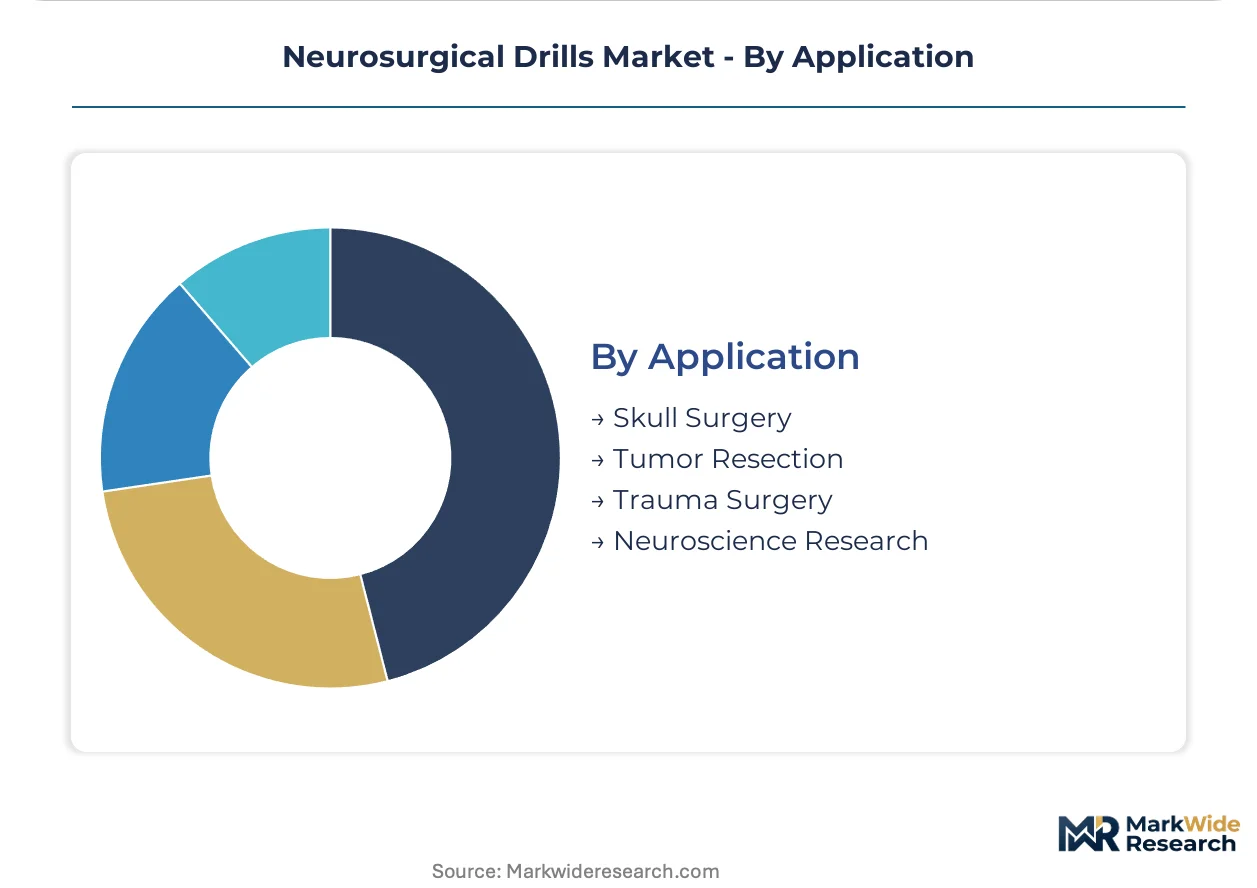
- Skull Surgery:High-speed cutting with integrated saline irrigation prevents thermal bone necrosis during craniotomy. Centers in the United States demand programmable speed profiles transitioning between aggressive cutting and delicate finishing without instrument changes.
- Tumor Resection:Extended operative durations require thermal management systems and ergonomic handpiece designs. German neuro-oncology units prioritize brushless motor efficiency for lengthy skull base approaches.
- Trauma Surgery:Rapid deployment requirements favor durable pneumatic systems in emergency settings.
- Neuroscience Research:Modified drill platforms serve animal model studies and cadaveric training applications.
Skull surgery absorbs the greatest equipment throughput; tumor resection applications are climbing fastest as oncologic procedure volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement patterns diverge sharply across major neurosurgical markets. German facilities prioritize integrated power ecosystems with neuronavigation compatibility. United States centers favor battery-powered mobility for outpatient migration. Japanese institutions emphasize precision torque calibration protocols.
United States
Academic medical centers in Boston and Baltimore drive demand for smart drilling platforms with embedded torque feedback. FDA 510(k) clearance pathways accelerate product iterations for powered surgical instruments. The Cleveland Clinic and Mayo Clinic anchor high-volume cranial procedure networks that standardize capital procurement frameworks.
Germany
University hospitals in Munich and Heidelberg pilot computer-navigated drilling integration for skull base approaches. EU MDR technical documentation requirements elevate clinical evidence standards for Class IIa powered instruments. The Baden-Württemberg medical technology cluster concentrates precision motor manufacturing for surgical applications.
Japan
Quaternary referral centers in Tokyo and Osaka prioritize brushless DC motor efficiency for extended tumor resection procedures. PMDA regulatory harmonization with ISO 13485 quality management standards streamlines market access. The Nagoya medical device corridor hosts specialized torque calibration laboratories serving aftermarket service demand.
India
Government hospital modernization programs in Maharashtra and Karnataka create first-time electric drill procurement for cranial trauma capacity. CDSCO medical device regulations align with international standards for powered surgical instruments. Tier-2 cities in Gujarat and Tamil Nadu expand neurosurgical infrastructure through state-level health missions.
United Kingdom
NHS trusts in London and Manchester consolidate procurement through centralized frameworks for capital equipment. MHRA post-Brexit regulatory autonomy maintains EU MDR-equivalent standards for powered instruments. The Cambridge medical technology cluster develops modified drill platforms for neuroscience research applications.
Neurosurgical Drills Market Competitive Landscape
Capability concentration sits with specialized precision motor fabricators; scale advantage sits with diversified surgical instrument conglomerates. The market structure reflects tiered competition between integrated power system providers and standalone handpiece specialists. Two strategic archetypes dominate: full-ecosystem vendors capturing recurring service revenue, and component specialists supplying OEM motor assemblies. Consolidation through strategic partnerships and geographic licensing agreements reshapes vendor positioning.
Among diversified surgical technology conglomerates, Johnson & Johnson (DePuy Synthes), Medtronic plc, and Stryker Corporation exemplify the full-ecosystem archetype. These entities anchor competitive positioning through broad installed bases and recurring aftermarket revenue streams. De Soutter Medical Ltd. occupies a specialist position within the precision fabrication tier. The competitive dynamic pits ecosystem lock-in strategies against component supplier flexibility across hospital procurement committees.
| Leading Market Players |
|---|
| Johnson & Johnson (DePuy Synthes) |
| Smith & Nephew plc |
| Medtronic plc |
| De Soutter Medical Ltd. |
| Integra LifeSciences Holdings Corporation |
| Stryker Corporation |
| B. Braun SE |
| Conmed Corporation |
| Zimmer Biomet Holdings Inc. |
| Others |
Supply & Pricing Matrix
German brushless DC motor fabricators and Japanese precision bearing suppliers anchor upstream concentration, channeling margin capture toward OEMs with captive torque calibration capabilities and hospital service contract control.
Pricing Analysis
Long-term service contracts dominate hospital procurement, with capital equipment acquisition increasingly unbundled from maintenance agreements. Pricing stratifies across premium smart-drilling platforms with embedded torque feedback, standard electric systems for fixed-OR installations, and economy pneumatic handpieces for cost-sensitive trauma settings. Cost compression in the economy tier is intensifying as Indian state health missions drive volume procurement of first-time electric drill systems. Ambulatory surgical centers exhibit the highest price sensitivity, prioritizing compact battery-powered configurations over feature depth.
Supply Chain Analysis
Brushless DC motor cores and high-precision surgical-grade bearings feed from concentrated manufacturing bases in Germany, Japan, and Switzerland. Aluminum housings, polymer biocompatible casings, and lithium-ion cell assemblies constitute critical component dependencies. Single-source vulnerability in German motor winding capacity propagates delays across OEM assembly lines during demand surges. Distribution runs through direct hospital channel control by diversified surgical instrument conglomerates, with third-party independent service organizations capturing legacy installed base maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital capital budget cycles are recovering from pandemic-induced deferrals, with cranial and spinal procedure volume rebounds driving replacement demand for aging pneumatic installed bases.
For Market Incumbents: Harden service contract retention through proprietary torque calibration infrastructure and embedded smart-drilling ecosystem lock-in. Counter third-party independent service organization encroachment by unbundling maintenance offerings only at premium tier price points. Deepen backward integration into brushless motor controller firmware development to sustain replacement part demand capture. For New Entrants and Emerging Players: Tier-2 Indian cities present the most penetrable geography for first-time electric drill procurement through state health mission frameworks. Battery-powered mobility configurations for ambulatory surgical centers offer the fastest white-space expansion path. Pursue GPO contract qualification in United States IDN networks as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward precision motor fabrication specialists with ISO 13485 certification and established hospital service laboratory footprints. The five-to-ten year viability window favors vendors with neuronavigation integration capabilities and software-defined drilling platform roadmaps. Monitor FDA 510(k) clearance velocity for smart-drilling predicate devices as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation for Class IIa powered instruments accelerates European hospital access. |
| Hospital System Partnership | Direct channel control with quaternary referral centers secures recurring aftermarket service revenue streams. |
| Software Companion Development | Torque feedback algorithm integration enables real-time surgical guidance and premium pricing capture. |
| Reimbursement Strategy | Medicare coding alignment for computer-navigated drilling procedures unlocks pay-for-performance adoption. |
| Backward Integration | In-house brushless motor controller production reduces supplier concentration risk and sustains margins. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract registries preceded structured interviews with neurosurgeons, biomedical engineers, hospital purchasing committee chairs, and GPO contracts managers. Primary fieldwork across United States academic medical centers, German university hospitals, and Japanese quaternary referral centers was validated against secondary sources including PMDA regulatory submissions, CDSCO medical device registrations, and ISO 13485 audit records. Bottom-up procedure volume modeling and top-down capital equipment spend analysis were triangulated to derive market sizing.
Assumptions held fixed include regulatory pathway efficiency for powered surgical instruments and hospital infrastructure modernization cadence in target geographies; variables tested include outpatient spine migration velocity and third-party service organization market share capture. Segmentation dimensions spanned product type, power delivery architecture, end-user facility tier, and application procedure category. CAGRs were computed from year-over-year capital procurement trajectories and replacement cycle compression factors, with cranial procedure volume elasticity and reimbursement coding evolution as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive ecosystem bundling by diversified surgical instrument conglomerates or rapid battery technology disruption would shift outcomes. Quarterly review of FDA 510(k) predicate device filings, EU MDR certification timeline extensions, and Indian state health mission electric drill tender awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Surgical Instrument Tracking System Market
Surgical Instruments
Ultrasound Needle Guides Market
Surgical Instruments
Asia Pacific Surgical Equipment Market
Surgical Instruments
Global Hysteroscopy Instruments Market
Surgical Instruments
Hemostatic Instruments Market
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
Disposable Spinal Instruments Market
Surgical Instruments
Global Bone Wax Market
Surgical Instruments
US Surgical Sutures Market
Surgical Instruments
Surgical Blades Market
Surgical Instruments
Biosurgery Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Heavy Power Surgical Tools Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Huber Needles Market