
 Absorbable Sutures Market | 2026-2036
Absorbable Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
Absorbable Sutures Market Analysis
Polyglycolide copolymer is broadening its share against traditional catgut across cost-sensitive hospital purchasing committees. Johnson & Johnson Services anchors North American distribution through its Ethicon surgical supply arm. Medtronic leverages its minimally invasive surgery platform to bundle absorbable sutures with stapling systems. B. Braun SE competes on European manufacturing scale and CE-marked polyglactin portfolios.
Absorbable sutures are surgical threads designed to lose tensile strength through hydrolysis or enzymatic degradation, typically formulated from polyglactin 910, polydioxanone, or chromic catgut with calibrated absorption timelines between 56 and 180 days for wound closure without removal. Polyglactin dominates hospital formularies due to predictable hydrolysis kinetics and braided handling characteristics that reduce tissue drag. General surgery generates the largest procedure volume, while orthopedic surgery represents the fastest-expanding application as arthroscopic soft-tissue repair protocols standardize synthetic absorbable fixation.
The FDA enforces biocompatibility and degradation profile standards under 21 CFR 878.4830 for absorbable surgical sutures, while the EMA's Medical Device Regulation requires clinical evidence of absorption predictability for CE marking in European markets. Health Canada's PMRA aligns with ISO 10993 biological evaluation protocols for polymer-based implantable devices. Stakeholders must monitor evolving polymer purity requirements and biodegradation certification timelines across multiple regulatory jurisdictions to secure market access.
Market Dynamics
The absorbable sutures sector is experiencing structural compression as FDA validation timelines for synthetic polymer degradation profiles extend, forcing manufacturers to front-load clinical evidence generation while hospital procurement consolidates around integrated delivery networks.
Growth Catalysts
- Outpatient procedural volume recovery:General surgery departments in United States hospital systems are expanding absorbable suture procurement as ambulatory surgical centers normalize post-pandemic caseloads.
- 21 CFR 878.4830 compliance acceleration:The FDA's updated biocompatibility guidance is creating competitive moats for validated manufacturers while filtering substandard entrants from distribution channels.
- Arthroscopic soft-tissue repair standardization:Orthopedic surgery protocols are displacing metallic fixation with synthetic absorbable alternatives in rotator cuff and meniscal repair procedures.
Market Restraints
- Polymer raw material concentration:Medical-grade glycolide and lactide monomer supply concentrates among specialty chemical producers in Germany and China, exposing suture manufacturers to input cost volatility and allocation risk.
- Catgut substitution ceiling:Religious and cultural objections to bovine-derived materials in Middle Eastern and South Asian markets limit complete synthetic displacement despite performance advantages.
- CE marking clinical evidence requirements:The EMA's Medical Device Regulation mandates extended follow-up studies for absorption predictability, extending time-to-market for European product launches by 18-24 months relative to prior directives.
Strategic Opportunities
- Pediatric surgery specialization:Neonatal and pediatric wound closure applications remain underpenetrated by braided polyglactin formulations optimized for adult tissue mechanics, creating white space for size-calibrated product development.
- Antimicrobial suture coating convergence:Triclosan and chlorhexidine-impregnated absorbable threads are converging with infection control protocols in United States academic medical centers, commanding premium positioning against standard formulations.
- Direct-to-hospital digital procurement:E-procurement platforms are disintermediating traditional surgical supply distributors in Indian tier-1 cities, enabling manufacturer-direct relationships with purchasing committees.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise in hydrolysis kinetics and braid architecture engineering is concentrating among retiring specialists, constraining R&D throughput for mid-tier manufacturers.
- ISO 10993-6 implantation study backlog:Contract research organizations specializing in absorbable polymer biocompatibility testing face 12-month queue times, compressing product development schedules.
- Legacy ERP integration friction:Hospital supply chain systems require manual bridging to track lot-specific degradation data, complicating inventory management for time-sensitive suture products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorbable Sutures Market |
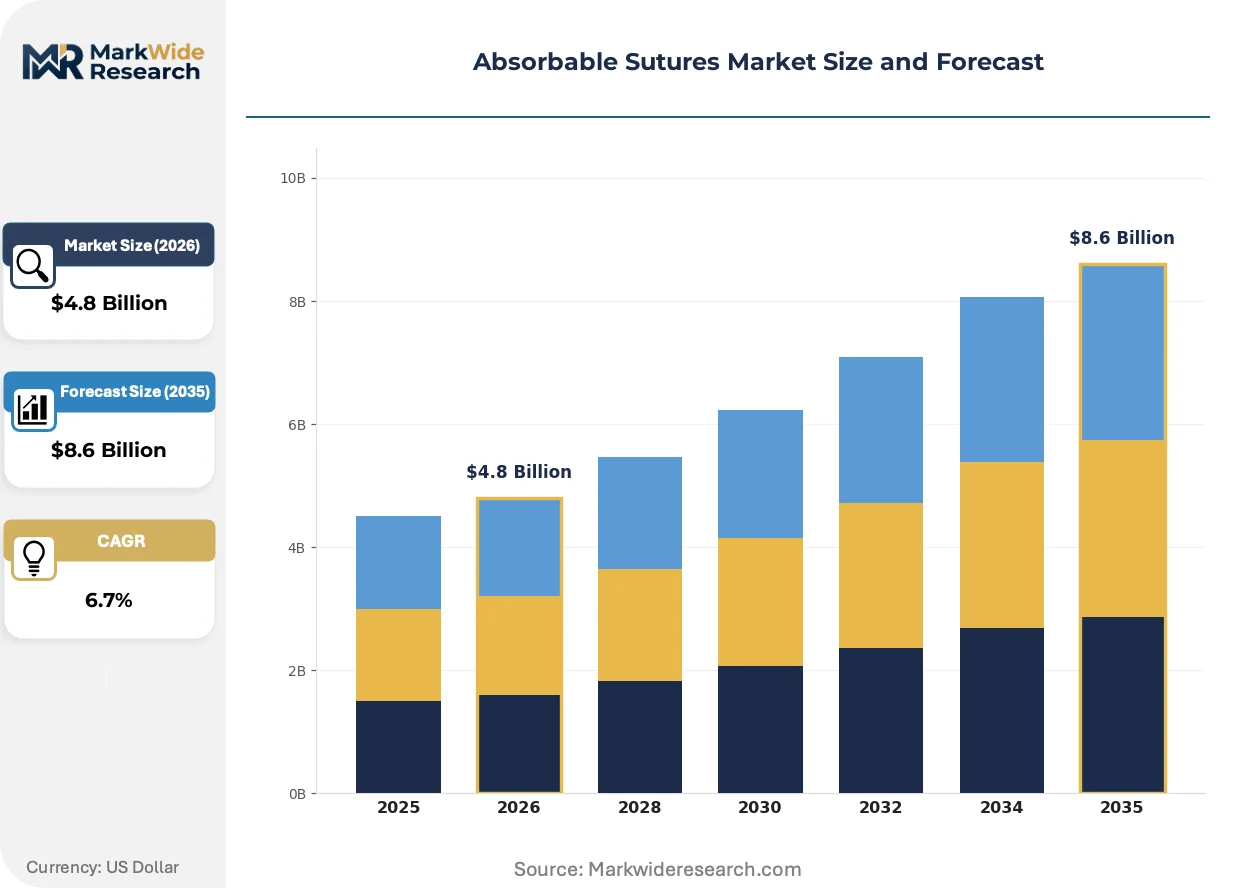
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyglactin, Polydioxanone, Catgut, Glycolide Application: General Surgery, Orthopedic Surgery, Cardiothoracic Surgery, Gynecological Surgery Delivery Mode: Pre-loaded, Manual Insertion, Mechanized Insertion, Automated Delivery End User: Hospitals, Ambulatory Surgical Centers, Clinics, Veterinary Practices |
| Companies Covered | B. Braun SE, Medtronic, Johnson & Johnson Services, DemeTECH Corporation, Teleflex Incorporated, Ethicon, Smith & Nephew, Boston Scientific Corporation, Healthium Medtech Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorbable Sutures Market Emerging Trajectories
Absorbable suture technology is bifurcating between commodity polyglactin dominance and next-generation smart materials that signal wound healing status, reshaping how manufacturers allocate R&D investment and clinical trial resources.
Self-reinforcing polydioxanone composites are converging with robotic surgery instrumentation, as Intuitive Surgical's da Vinci ecosystem standardizes needle-suture combinations optimized for minimally invasive port access. United States academic medical centers are piloting these integrated systems at 15% annual expansion rates. The convergence is compressing standalone suture vendors into stapling system partnerships or proprietary platform exclusion.
REACH Annex XVII restrictions on persistent organic pollutants are forcing European manufacturers to reformulate coating chemistries and validate alternative lubricants for braided suture passage through tissue. The ECHA regulatory pressure is redirecting formulation R&D budgets toward bioabsorbable surfactants. German and Swiss producers are accelerating substitution timelines to maintain CE marking continuity ahead of 2026 enforcement windows.
Hospital value analysis committees are consolidating vendor contracts around total procedure cost metrics rather than per-unit suture pricing, displacing line-item negotiations with bundled surgical supply agreements. Integrated delivery networks in Texas and California are piloting this model most aggressively. The behavioral shift favors manufacturers with stapling, energy, and closure portfolios over pure-play suture specialists.
Absorbable Sutures Market Segmentation
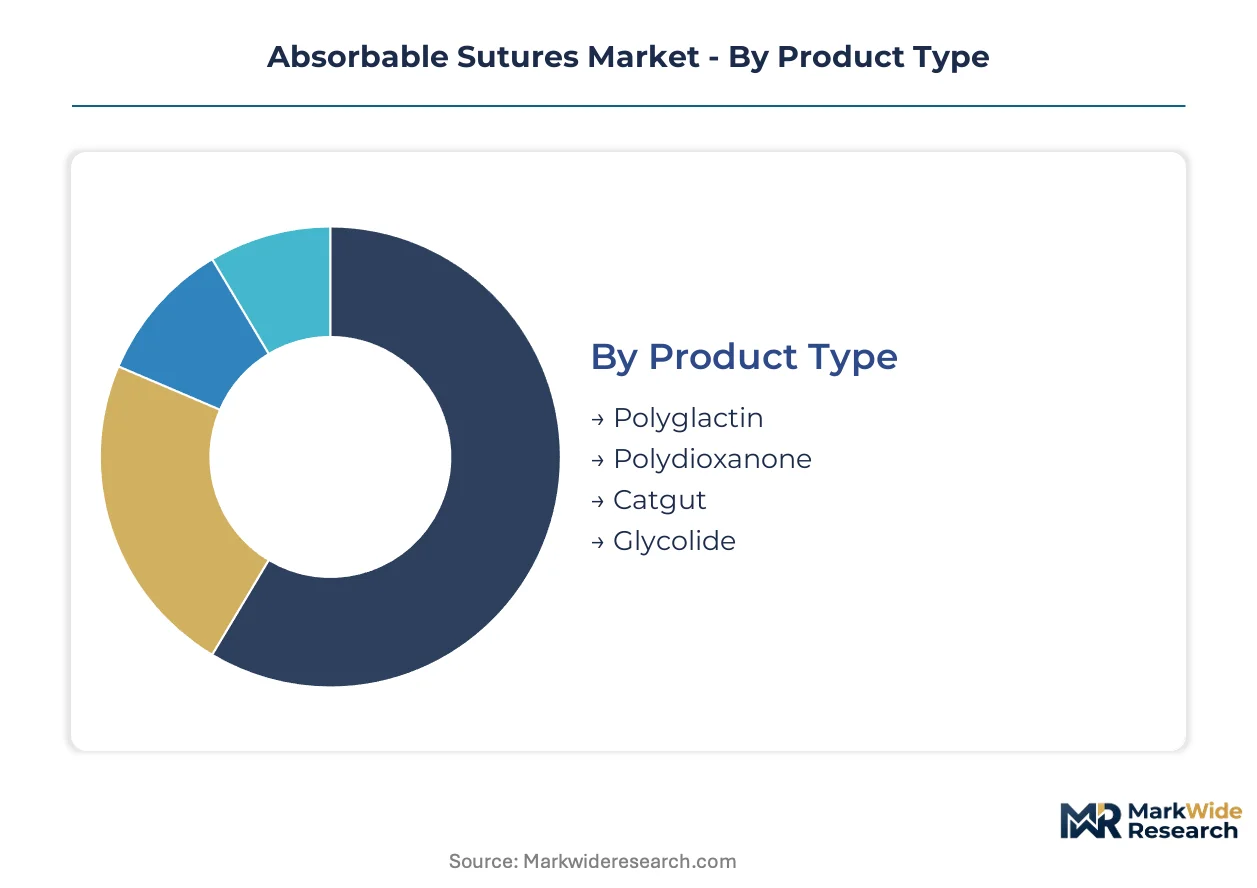
Segmentation in absorbable sutures reveals how polymer chemistry, procedural setting, and delivery sophistication create distinct certification and pricing tiers. Manufacturers configure product portfolios across these dimensions to match hospital formulary requirements and regulatory pathways.
Product Type:
FDA 21 CFR 878.4830 biocompatibility standards apply uniformly across synthetic polymers, while catgut faces additional sourcing documentation under USDA veterinary inspection protocols for bovine-derived materials.
- Polyglactin:Braided polyglactin 910 hydrolyzes predictably within 56-70 days through ester bond cleavage, delivering tensile strength retention calibrated for abdominal wall closure. United States academic medical centers specify this formulation for general surgery departments recovering outpatient procedural volumes. Polyglactin dominates hospital formularies due to handling characteristics that reduce tissue drag during layered closure.
- Polydioxanone:Monofilament polydioxanone extends absorption to 180 days with minimal inflammatory response, suiting slow-healing fascial planes and pediatric cardiac tissue. Orthopedic surgery protocols in Texas and California integrated delivery networks are standardizing this polymer for arthroscopic soft-tissue repair where prolonged strength retention outperforms braided alternatives.
- Catgut:Chromic-treated bovine collagen retains enzymatic degradation sensitivity, requiring cold-chain logistics and religious-use exemptions in Middle Eastern markets.
- Glycolide:High-crystallinity polyglycolide copolymers offer rapid absorption for superficial mucosal closure, constrained by stiffness limiting knot security in deep tissue.
Polyglactin sits at the top of the volume ranking, with polydioxanone climbing the fastest.
Application:
Cost tier stratification separates high-volume commodity closure from specialized fixation commanding premium positioning through bundled instrument-suture combinations.
- General Surgery:Abdominal wall and gastrointestinal closure generate the largest procedure volumes, with absorbable sutures specified in standardized operative kits across United States ambulatory surgical centers. Procurement committees negotiate consolidated contracts around polyglactin monofilament configurations for hernia repair and bowel anastomosis.
- Orthopedic Surgery:Arthroscopic rotator cuff and meniscal repair protocols are displacing metallic fixation with synthetic absorbable alternatives, expanding most quickly as sports medicine subspecialties standardize all-inside repair techniques. Academic medical centers in California pilot integrated delivery systems bundling polydioxanone with arthroscopic instrumentation.
- Cardiothoracic Surgery:Sternotomy closure and vascular anastomosis demand absorption profiles matched to cardiac healing kinetics, with pediatric applications requiring size-calibrated needles.
- Gynecological Surgery:Laparoscopic hysterectomy and pelvic floor reconstruction utilize braided polyglactin for fascia approximation, with fertility-preserving procedures driving demand for minimal tissue reaction.
General Surgery commands the highest absolute volume, while Orthopedic Surgery gains share fastest through arthroscopic protocol expansion.
Delivery Mode:
Customer sophistication separates institutions with capital equipment budgets from those relying on manual technique and disposable loading systems.
- Pre-loaded:Factory-mounted needles with calibrated suture lengths reduce operative room setup time and needlestick exposure, specified by United States hospital value analysis committees prioritizing total procedure cost over per-unit pricing. Ethicon and Medtronic dominate this tier through integrated surgical platform partnerships.
- Manual Insertion:Surgeon-controlled needle loading persists in cost-sensitive settings and specialized procedures requiring custom suture lengths, prevalent in Indian tier-1 city hospitals transitioning to e-procurement platforms.
- Mechanized Insertion:Powered suturing devices for laparoscopic port access standardize needle driving force, adopted by robotic surgery programs at 15% annual expansion rates.
- Automated Delivery:Next-generation systems with real-time tension feedback remain in clinical validation, targeting reconstruction procedures requiring consistent bite spacing.
Pre-loaded configurations occupy the volume leadership position, with mechanized insertion expanding most rapidly through robotic surgery ecosystem integration.
End User:
Margin structure varies sharply across facility types, with integrated delivery networks extracting volume discounts unavailable to independent practice settings.
- Hospitals:General surgery departments in United States hospital systems anchor absorbable suture procurement, negotiating multi-year supply agreements covering polyglactin, polydioxanone, and specialty formulations through centralized purchasing committees. Formulary restrictions limit vendor access to validated manufacturers with FDA biocompatibility documentation.
- Ambulatory Surgical Centers:Post-pandemic caseload normalization is expanding outpatient procedural volumes fastest in Texas and California, with ASCs specifying pre-loaded configurations to minimize turnover time between cases.
- Clinics:Dermatologic and minor procedure settings utilize economy-tier catgut and rapid-absorption glycolide for superficial closure, with direct-to-manufacturer digital procurement disintermediating traditional distributors in Indian metropolitan markets.
- Veterinary Practices:Companion animal surgery and equine wound management apply human-grade absorbable sutures with modified packaging and labeling under FDA enforcement discretion for veterinary medical devices.
Hospitals retain the top volume position, with ambulatory surgical centers climbing fastest as outpatient migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Johnson & Johnson Services surgical supply complex in New Jersey anchors North American absorbable suture distribution, with integrated delivery networks in Texas and California negotiating consolidated procurement contracts that reshape pricing power across hospital systems.
United States
FDA 21 CFR 878.4830 biocompatibility standards filter substandard entrants from distribution channels as ambulatory surgical centers in Texas and California normalize post-pandemic caseloads. The FDA's updated synthetic polymer degradation guidance accelerates validation timelines for new market participants. Academic medical centers in California pilot integrated delivery systems bundling polydioxanone with arthroscopic instrumentation.
Germany
B. Braun SE leverages European manufacturing scale and CE-marked polyglactin portfolios to serve cost-sensitive hospital purchasing committees across the continent. REACH Annex XVII restrictions on persistent organic pollutants force reformulation of coating chemistries ahead of 2026 enforcement windows. Specialty chemical producers in the Rhine-Ruhr industrial cluster concentrate medical-grade glycolide and lactide monomer supply.
India
E-procurement platforms disintermediate traditional surgical supply distributors in tier-1 cities, enabling manufacturer-direct relationships with purchasing committees for economy-tier catgut and rapid-absorption glycolide. CDSCO alignment with ISO 10993 biological evaluation protocols governs polymer-based implantable device approvals. Healthium Medtech Limited anchors domestic production from its Karnataka manufacturing base.
China
Medical-grade lactide monomer supply concentrates among specialty chemical producers, exposing suture manufacturers to input cost volatility and allocation risk. NMPA biocompatibility standards under GB/T 16886 series accelerate validation requirements for domestic and imported products. Yangtze River Delta chemical clusters supply raw materials to regional suture fabricators serving domestic hospital procurement.
Saudi Arabia
Religious objections to bovine-derived catgut materials limit complete synthetic displacement despite performance advantages, creating sustained demand for validated polyglactin alternatives. SFDA medical device regulations align with international biocompatibility standards for polymer degradation profiles. Riyadh-based hospital systems expand absorbable suture procurement as outpatient procedural volumes recover.
Absorbable Sutures Market Vendor Landscape
Global majors compete with regional champions across regulatory validation and distribution reach, producing a tiered structure where FDA-validated manufacturers command premium positioning in United States hospital formularies while regional specialists capture cost-sensitive procurement in emerging markets. Three archetypes dominate: diversified surgical supply conglomerates with stapling platform bundling capability, pure-play suture specialists competing on European manufacturing scale, and emerging market fabricators leveraging direct digital procurement channels. Competitive moves concentrate on strategic partnerships with robotic surgery ecosystems and backward integration into medical-grade polymer supply.
Within the diversified conglomerate tier, Johnson & Johnson Services and Medtronic exemplify platform-anchored positioning, while B. Braun SE represents European manufacturing-scale specialization. Ethicon, as the surgical supply arm of Johnson & Johnson Services, occupies a position in North American distribution networks. These three entities collectively illustrate how regulatory validation depth and integrated delivery network contracting capability separate market tiers.
| Leading Market Players |
|---|
| B. Braun SE |
| Medtronic |
| Johnson & Johnson Services |
| DemeTECH Corporation |
| Teleflex Incorporated |
| Ethicon |
| Smith & Nephew |
| Boston Scientific Corporation |
| Healthium Medtech Limited |
| Others |
Supply Flow & Price Mechanics
Integrated delivery network contract consolidation in Texas and California is compressing per-unit suture margins while elevating total-procedure-cost negotiations, forcing manufacturers to absorb polymer input volatility through long-term supply agreements rather than pass-through pricing.
Pricing Analysis
Medical-grade glycolide and lactide monomer cost pass-through from Rhine-Ruhr and Yangtze River Delta suppliers is compressing margins for mid-tier fabricators unable to hedge feedstock exposure. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated polyglactin from CE-marked European alternatives and economy-tier catgut. Price differentiation hinges on biocompatibility certification tier and volume scale, with hospital value analysis committees extracting steepest discounts from pure-play suture specialists lacking stapling platform bundling. Ambulatory surgical centers exhibit highest price sensitivity due to case-mix reimbursement constraints.
Supply Chain Analysis
Cold-chain logistics costs for chromic catgut and specialized polymer freight from Germany and China are elevating landed costs for Middle Eastern and South Asian markets. Raw material supply draws from medical-grade monomer producers in Germany, China, and the United States, with suture braiding and needle mounting concentrated in Malaysia, Costa Rica, and Switzerland. Single-source vulnerability in lactide purification technology creates allocation risk during pharmaceutical polymer demand surges. Distribution runs through integrated delivery network central warehouses in the United States, specialty surgical distributors in Europe, and direct e-procurement platforms in Indian tier-1 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The absorbable sutures market compounds returns through regulatory validation moats, with FDA's updated 21 CFR 878.4830 degradation-profile guidance accelerating competitive filtering and premium pricing capture for validated manufacturers.
For Market Incumbents: Acquire polymer chemist talent pools and ISO 10993-6 testing capacity to compress product development timelines against mid-tier competitors. Backward integration into medical-grade glycolide supply insulates margin structure from Rhine-Ruhr monomer allocation risk. Defensive patenting around antimicrobial coating formulations preserves premium positioning against generic triclosan alternatives.
For New Entrants and Emerging Players: Direct-to-hospital digital procurement channels in Indian metropolitan markets bypass entrenched distributor relationships and enable rapid formulary penetration with economy-tier rapid-absorption glycolide. Pediatric surgery specialization offers white-space opportunity where size-calibrated needle-suture combinations remain underdeveloped. Target ambulatory surgical center procurement committees with pre-loaded configuration value propositions emphasizing turnover-time reduction.
For Investors and Strategic Acquirers: Asymmetric upside sits with European manufacturing-scale specialists possessing CE-marked portfolios and REACH Annex XVII reformulation readiness ahead of 2026 enforcement windows. Long-term viability favors entities with stapling platform bundling capability or robotic surgery ecosystem partnerships. Watch FDA validation queue times as inflection indicator for competitive moat expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Development | Triclosan-impregnated threads command premium positioning in academic medical center infection control protocols. |
| Robotic Surgery Platform Partnership | Intuitive Surgical's da Vinci ecosystem standardization compresses standalone vendors into integrated supply relationships. |
| Backward Integration into Monomer Supply | Captive glycolide production insulates margin structure from German and Chinese specialty chemical allocation risk. |
| Pediatric Formulation Pipeline | Neonatal size-calibrated sutures address underpenetrated wound closure mechanics distinct from adult tissue. |
| E-Procurement Channel Establishment | Manufacturer-direct relationships with Indian hospital purchasing committees disintermediate traditional surgical supply distributors. |
Methodological Framework
Multiple input streams — primary interviews with hospital purchasing committee members, biomedical engineers, and GPO contracts managers; secondary validation against FDA 510(k) filings, EMA CE marking databases, and hospital procurement contract repositories; and customs trade data on medical-grade polymer imports — were reconciled through bottom-up procedure volume modeling and top-down manufacturer revenue triangulation.
Data-stream reconciliation across product type, application, delivery mode, and end-user facility tier generated volume and value outputs over the projection horizon. CAGRs were derived from procedure volume elasticity models calibrated to ambulatory surgical center expansion rates and orthopedic arthroscopic protocol adoption curves. Forecast inputs included integrated delivery network contract renewal cycles, REACH Annex XVII reformulation timelines, and ISO 10993-6 testing queue durations.
The model assumes a particular technology adoption path; alternative pathways for self-reinforcing polydioxanone composites or smart material wound-healing indicators would alter the outlook. Forecasts reflect assumptions on regulatory validation throughput and polymer chemist labor market tightness. A model refresh is warranted upon material change in FDA biocompatibility guidance or integrated delivery network consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Minimally Invasive Surgical Instruments Market
Surgical Instruments
Uro Gynaecological Surgical Devices Market
Surgical Instruments
Hand-Held Surgical Instruments Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Non-Absorbable Sutures Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Handheld Arthroscopic Instruments Market
Surgical Instruments
Neurosurgery Surgical Power Tools Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Global Surgical Stapler Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Global Surgical Scissors Market
Surgical Instruments
Dissolvable Sutures Market