
 Colorectal Procedure Market | 2026-2036
Colorectal Procedure Market Size, Share, and Industry Trends Forecast 2026-2036
Colorectal Procedure Market Insights
Hospital procurement channels for colorectal devices is tilting toward bundled service contracts that pair capital equipment with disposable consumables. Medtronic leverages its integrated gastrointestinal portfolio to anchor long-term supply agreements across integrated delivery networks. Intuitive Surgical competes by extending its robotic surgery ecosystem into colorectal resection protocols. Ethicon sustains brand strength in advanced energy devices for laparoscopic colectomy through sustained clinician training investments.
Colorectal procedures encompass diagnostic and therapeutic interventions targeting the colon, rectum, and anal canal, typically employing flexible endoscopes with working channels of 2.8–3.7 mm diameter for tissue manipulation, polyp removal, and biopsy sampling, with the primary purpose of detecting malignancy, managing inflammatory bowel disease, and preventing cancer progression through adenoma resection. Robotic technology commands premium positioning due to instrument articulation precision and recovery time reduction, while laparoscopic approaches retain volume leadership in cost-sensitive settings. Ambulatory surgery centers represent the fastest-growing end user segment as reimbursement shifts reward same-day discharge protocols.
FDA premarket notification requirements govern endoscopic device commercialization in the United States, while the EU Medical Device Regulation mandates clinical evidence thresholds for robotic surgical platforms entering European markets. The FDA's Breakthrough Devices Program accelerates review for AI-enhanced polyp detection systems, reshaping competitive timelines for technology developers. Stakeholders must monitor evolving CMS reimbursement decisions for outpatient colorectal surgery, as coverage determinations will dictate capital deployment priorities across health systems.
Market Dynamics
Robotic-assisted surgical platforms are compressing recovery timelines and redrawing capital allocation across ambulatory surgery centers, forcing traditional laparoscopic equipment suppliers to defend installed bases through service bundling rather than hardware differentiation alone.
Growth Catalysts
- CMS reimbursement expansion:Medicare coverage determinations for outpatient colorectal resections accelerate same-day discharge protocols across United States ambulatory facilities.
- AI-enhanced polyp detection:FDA Breakthrough Devices Program review pathways compress commercialization timelines for computer-assisted diagnostic systems.
- Germany's statutory screening mandates:Biennial colonoscopy coverage for insured populations sustains procedural volume growth independent of private payment trends.
Market Restraints
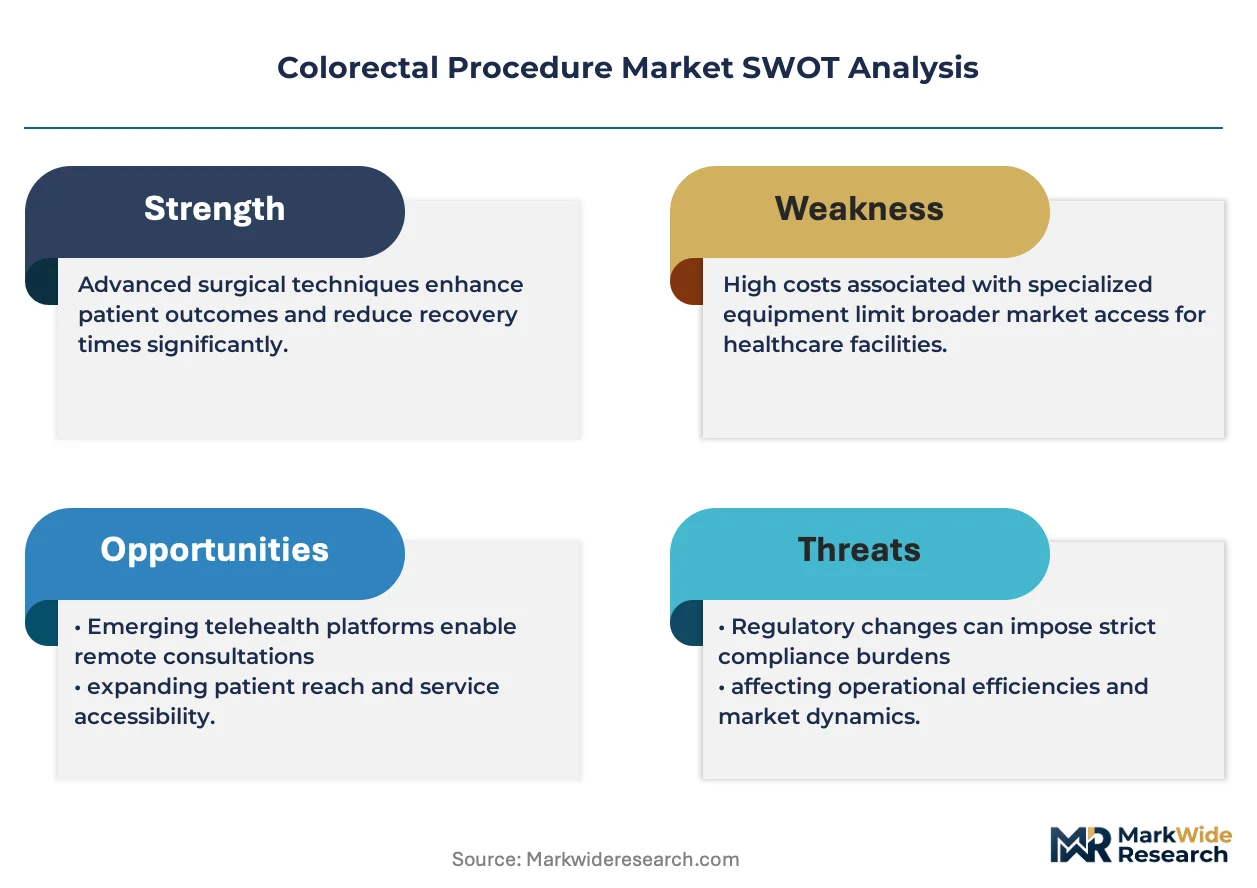
- Capital intensity concentration:Robotic platform acquisition costs exceed $2 million per unit, restricting deployment to well-capitalized health systems and limiting penetration in community hospital settings.
- Disposable consumable lock-in:Proprietary instrument ecosystems from dominant suppliers create switching costs that suppress price competition across integrated delivery networks.
- EU MDR clinical evidence thresholds:Expanded documentation requirements for robotic surgical platforms delay market entry and elevate regulatory compliance expenditures for European commercialization.
Strategic Opportunities
- Underpenetrated ambulatory migration:United States outpatient surgery centers currently perform under 15% of elective colectomies, leaving substantial volume for same-day protocol expansion.
- Convergence of navigation and energy:Integration of electromagnetic tracking with advanced bipolar sealing technology enables single-platform solutions for complex resections.
- India's Ayushman Bharat coverage expansion:Government-sponsored health insurance growth creates addressable demand for cost-optimized endoscopic screening infrastructure.
Industry Challenges
- Robotic surgery credentialing pipelines:Proctology fellowship programs produce insufficient trained operators to match deployed platform capacity, creating utilization bottlenecks.
- Legacy electronic health record integration:Surgical workflow data from robotic systems requires custom API development to interface with predominant hospital information systems.
- Reprocessing validation complexity:Flexible endoscope high-level disinfection protocols face heightened scrutiny from Joint Commission surveys, elevating compliance labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colorectal Procedure Market |
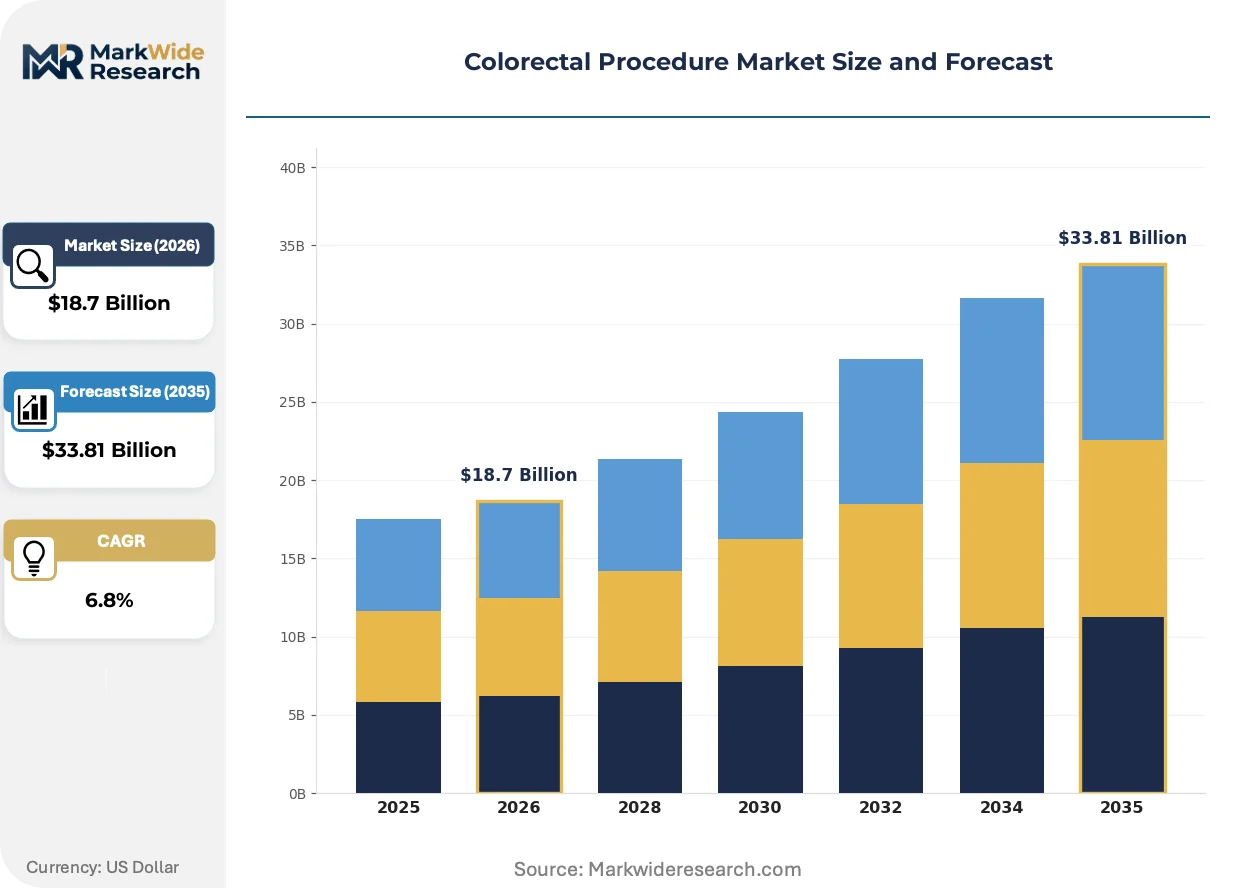
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Colonoscopy, Sigmoidoscopy, Biopsy, Polypectomy Technology: Endoscopic, Robotic, Laparoscopic, Imaging End User: Hospitals, Ambulatory Surgery Centers, Clinics, Research Institutions Delivery Mode: Inpatient, Outpatient, Telehealth, Home Care |
| Companies Covered | Medtronic, Intuitive Surgical, Ethicon (Johnson & Johnson Services, Inc.), Stryker, Colospan Ltd, SAFEHEAL, B. Braun Melsungen, Cardinal Health Inc, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colorectal Procedure Market Trends and Innovations
Digital pathology and remote surgical assistance are collapsing geographic constraints on specialist availability, while reimbursement policy accelerates site-of-care migration toward lower-acuity settings.
Cloud-based surgical planning software is virtualizing preoperative case review by enabling three-dimensional colon reconstruction from standard CT datasets. Community hospitals without on-site colorectal specialists adopt these platforms to reduce transfer rates for complex polypectomies. The technology is virtualizing traditional referral networks by allowing remote surgeons to annotate operative plans and guide local teams through high-risk resections.
EU Medical Device Regulation Article 61 clinical evaluation requirements are elevating evidence standards for robotic surgical platforms seeking CE marking. Manufacturers must now generate prospective clinical data rather than relying on predicate equivalence, extending development timelines by 18-24 months. German notified bodies are experiencing backlog concentrations that delay market entry for second-tier robotic competitors.
Hospital purchasing cooperatives are consolidating device procurement across multi-hospital systems, displacing individual facility contracting autonomy. GPOs extract standardized pricing across robotic instruments, advanced energy devices, and endoscopic consumables through multi-year sole-source agreements. This concentration is most visible in United States integrated delivery networks exceeding ten hospitals, where supply chain officers centralize vendor selection decisions.
Colorectal Procedure Market Segmentation
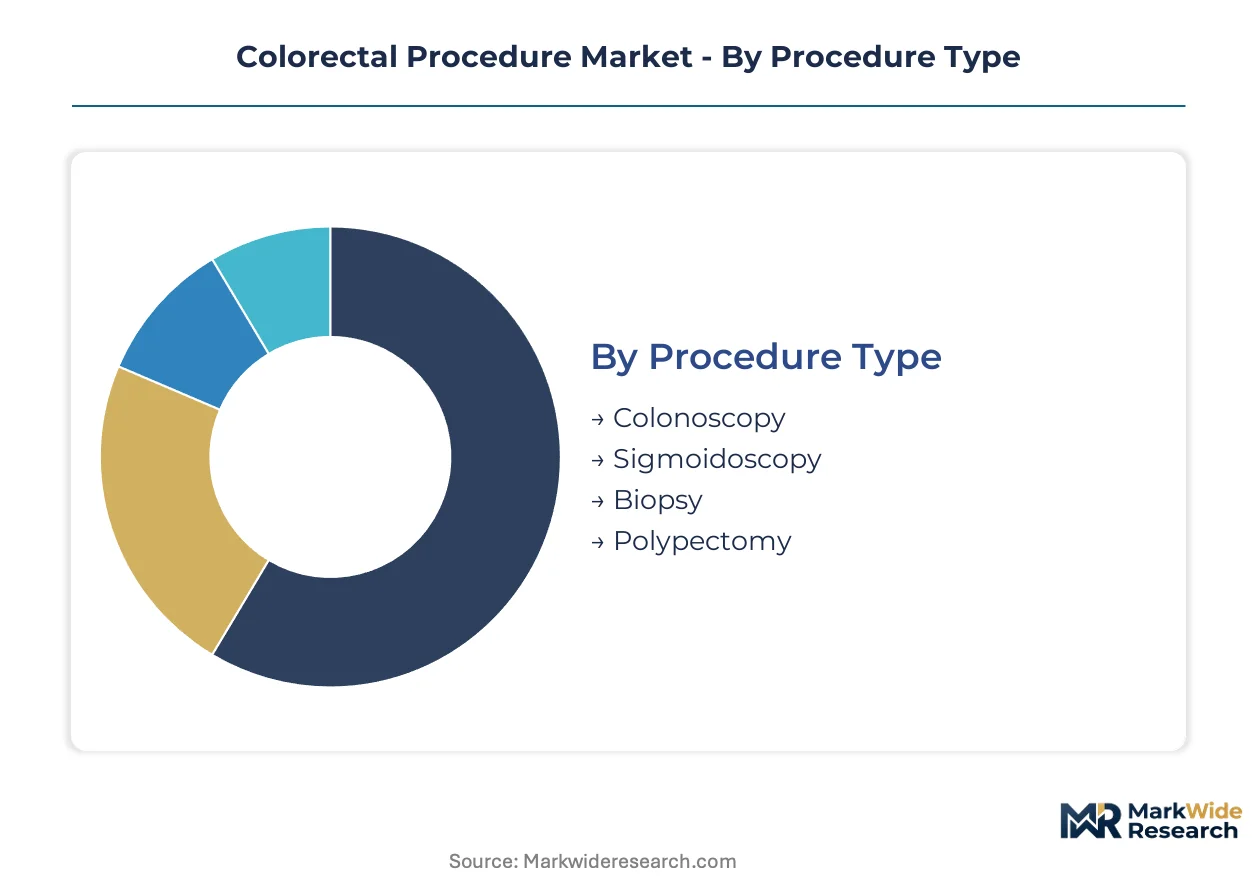
Procedure type and technology choices dictate capital deployment cycles, reimbursement pathways, and clinician training requirements across colorectal service lines. Segmentation clarity enables vendors to align product portfolios with the diverging economics of screening programs versus therapeutic interventions.
Procedure Type:
Cycle times vary dramatically across this category, with diagnostic screening procedures turning over in under 30 minutes while complex therapeutic resections extend to 3-4 hours and command entirely different staffing models.
- Colonoscopy:Comprehensive examination of the entire large intestine using flexible endoscopes with 3.2 mm instrument channels enables simultaneous biopsy and polypectomy. Demand concentrates in United States integrated delivery networks where CMS reimbursement incentives favor complete screening protocols over segmented diagnostics.
- Polypectomy:Therapeutic removal of adenomatous tissue during index procedures eliminates separate intervention scheduling and reduces patient compliance drop-off. German statutory health insurance frameworks specifically reward same-session polypectomy completion, anchoring procedural volume in European screening programs.
- Sigmoidoscopy:Distal colon examination limited to 60 cm insertion depth serves resource-constrained settings and fecal immunochemical test follow-up protocols.
- Biopsy:Tissue sampling for histopathological analysis represents the foundational diagnostic step across all procedural workflows.
Colonoscopy anchors the volume base while polypectomy gains share at the steepest rate as same-session therapeutic completion becomes standard of care.
Technology:
Cost tier stratification separates capital-intensive robotic platforms from disposable-dominated endoscopic systems, with laparoscopic equipment occupying the mid-tier replacement cycle.
- Endoscopic:Flexible fiberoptic or video systems with integrated irrigation, suction, and cautery capabilities dominate screening volumes through lower capital barriers and established clinician familiarity. Ambulatory surgery centers in the United States prioritize endoscopic platforms for same-day discharge eligibility under CMS outpatient reimbursement codes.
- Robotic:Articulated instrument arms with seven degrees of freedom and tremor filtration enable precise mesorectal dissection in confined pelvic anatomy. Well-capitalized academic medical centers in Germany deploy these systems for complex rectal cancer protocols despite per-procedure disposable costs exceeding standard laparoscopy.
- Laparoscopic:Rigid scope systems with carbon dioxide insufflation maintain cost leadership in colectomy volumes outside specialized cancer centers.
- Imaging:Advanced visualization modalities including narrow-band imaging and fluorescence angiography enhance tissue characterization capabilities.
Endoscopic technology anchors the volume base while robotic systems expand most quickly in high-acuity resection segments.
End User:
Customer type determines procurement authority structure, with hospital systems centralizing capital decisions while ambulatory facilities negotiate disposable-heavy supply agreements.
- Hospitals:Inpatient surgical departments maintain comprehensive service lines spanning emergency obstruction management to elective cancer resection, requiring full technology portfolios.
- Ambulatory Surgery Centers:United States outpatient facilities focused on elective polypectomy and low-risk colectomy drive fastest volume expansion under shifting CMS site-of-care incentives.
- Clinics:Office-based gastroenterology practices concentrate on diagnostic colonoscopy and surveillance protocols for inflammatory bowel disease.
- Research Institutions:Academic medical centers with NIH funding support generate clinical evidence for novel device platforms and AI-enhanced detection systems.
Hospitals anchor the volume base while ambulatory surgery centers climb the fastest as reimbursement migration accelerates.
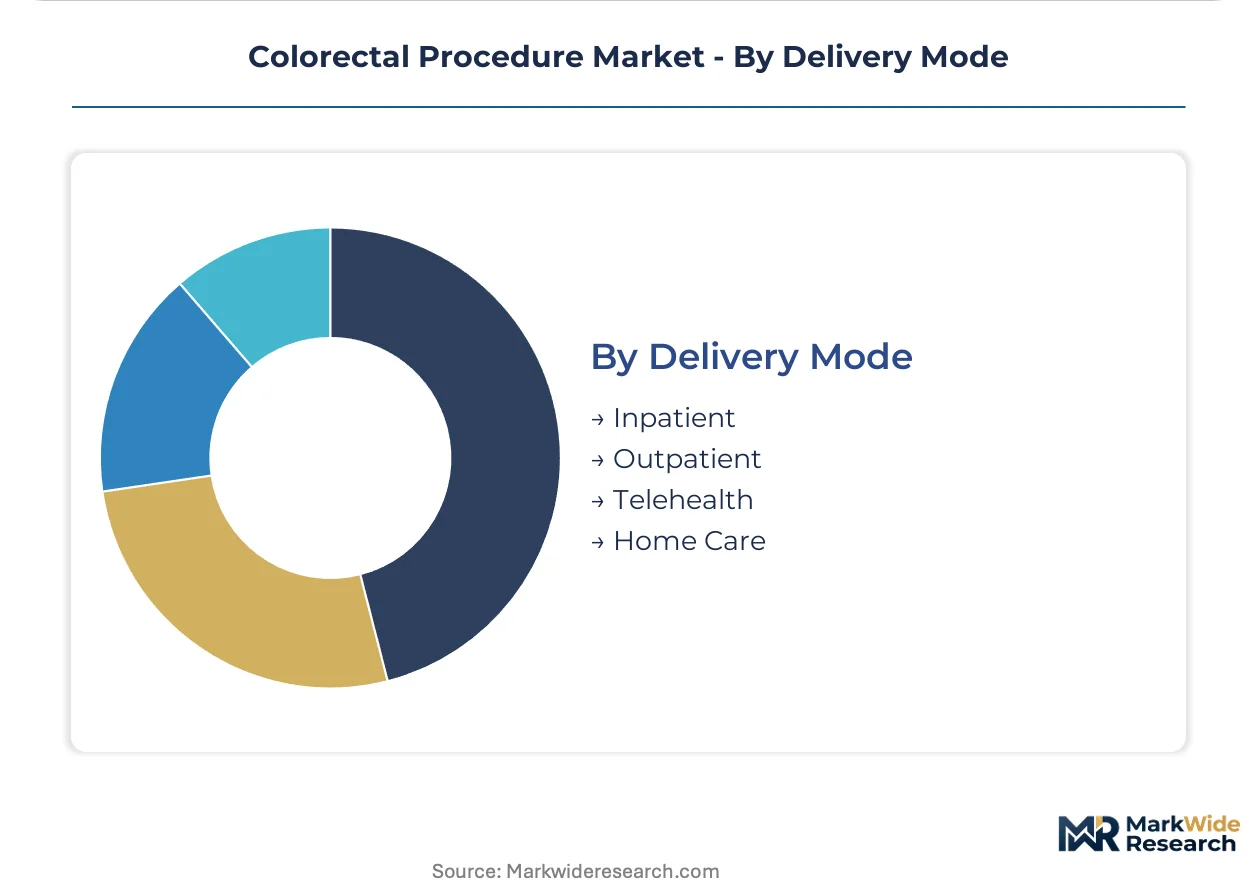
Delivery Mode:
Site-of-care economics separate high-overhead inpatient admissions from streamlined outpatient protocols, with telehealth emerging as a preoperative planning and postoperative surveillance channel.
- Inpatient:Admission requirements persist for emergency presentations, extensive resections with ostomy formation, and patients with significant comorbidity burdens.
- Outpatient:Same-day discharge protocols for elective polypectomy and uncomplicated colectomy concentrate in United States ambulatory surgery centers with dedicated recovery units.
- Telehealth:Virtual consultation platforms enable preoperative risk stratification and postoperative complication monitoring without facility-based encounters.
- Home Care:Bowel preparation kit distribution and remote patient monitoring extend procedural access to geographically dispersed populations.
Inpatient delivery anchors the volume base while outpatient protocols gain share at the steepest rate as same-day surgery infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German statutory reimbursement frameworks while cost-optimized protocols dominate Indian procurement channels, creating a two-tier procurement landscape across the colorectal procedure market.
United States
CMS reimbursement expansion for outpatient colorectal resections drives ambulatory surgery center volume migration. FDA 510(k) clearance pathways streamline robotic platform introductions for same-day discharge protocols. Major integrated delivery networks in Texas and California centralize capital procurement through group purchasing organizations.
Germany
Statutory health insurance biennial colonoscopy mandates sustain screening program volumes independent of private payment trends. EU MDR Article 61 clinical evaluation requirements elevate evidence standards for robotic surgical platforms seeking CE marking. Notified bodies in Berlin and Munich experience review backlogs that delay market entry for second-tier competitors.
China
Government-sponsored cancer screening initiatives expand endoscopic infrastructure into tier-two and tier-three cities. NMPA regulatory harmonization with international standards accelerates approval timelines for imported robotic surgical systems. Shanghai and Beijing academic medical centers deploy premium platforms for complex rectal cancer protocols.
India
Ayushman Bharat coverage expansion creates addressable demand for cost-optimized endoscopic screening infrastructure. CDSCO medical device regulations govern import licensing for flexible endoscope systems. Maharashtra and Karnataka hospital clusters prioritize disposable-heavy supply agreements over capital-intensive robotic acquisitions.
Japan
PMDA regulatory frameworks maintain stringent clinical evidence requirements for AI-enhanced polyp detection systems. METI industrial policy supports domestic manufacturing of advanced endoscopic imaging modalities. Tokyo and Osaka metropolitan areas concentrate specialist training capacity for complex therapeutic resections.
Colorectal Procedure Market Competitive Landscape
Integrated device conglomerates and robotic platform specialists split the market along capital intensity lines. The vendor base concentrates around three strategic archetypes: diversified medtech conglomerates with gastrointestinal portfolios, pure-play robotic surgery developers, and regional endoscopic equipment fabricators. Dominant competitive moves include long-term supply agreement anchoring across integrated delivery networks and service bundling that pairs capital equipment with disposable consumables.
Among diversified medtech conglomerates, Medtronic and Ethicon occupy positions that exemplify portfolio breadth strategies, while Intuitive Surgical represents the pure-play robotic archetype with ecosystem extension into colorectal resection protocols. These three companies anchor the competitive structure through divergent approaches to clinician training investments and installed base defense.
| Leading Market Players |
|---|
| Medtronic |
| Intuitive Surgical |
| Ethicon (Johnson & Johnson Services, Inc.) |
| Stryker |
| Colospan Ltd |
| SAFEHEAL |
| B. Braun Melsungen |
| Cardinal Health Inc |
| Boston Scientific Corporation |
| Others |
Pricing and Supply Chain Analysis
EU MDR clinical evidence thresholds for robotic surgical platforms concentrate regulatory risk in European commercialization pathways, compressing pricing spreads between CE-marked premium systems and standard laparoscopic equipment while forcing manufacturers to absorb extended development timelines into cost structures or surrender market position.
Pricing Analysis
Configured-to-order pricing for robotic surgical platforms commands substantial premiums over standard laparoscopic system pricing, with customization depth around instrument articulation range and imaging modality integration driving tier separation. Price differentiation rests on FDA breakthrough designation status and proprietary disposable ecosystem lock-in rather than hardware specifications alone. Pricing pressure stems from GPO consolidation across United States integrated delivery networks extracting standardized multi-year contracts. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraint structures, while academic medical centers in Germany absorb premium positioning for complex rectal cancer protocols.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk profiles for flexible endoscope component sourcing, with imaging sensor arrays and fiberoptic bundles drawing from concentrated East Asian manufacturing clusters. Raw material dependencies center on rare earth elements for electromagnetic navigation systems, specialized polymers for disposable instrument sheaths, and high-purity optical glass for lens assemblies. Single-source vulnerability concentrates in robotic instrument arm servo motor supply from Japanese precision manufacturers. Distribution runs through hospital purchasing cooperatives and GPO-negotiated sole-source agreements that displace direct manufacturer-to-facility contracting across multi-hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable consumable attach rates and service contract renewals expand faster than capital equipment sales across colorectal procedure platforms, making recurring revenue depth the decisive valuation driver for market participants.
For Market Incumbents: Entrench installed base position by extending proprietary instrument ecosystems into ambulatory surgery center partnerships, while accelerating clinician training pipeline investments to match deployed robotic platform capacity against emerging pure-play competitors. Vertical integration into flexible endoscope reprocessing services captures compliance labor cost pools elevating across Joint Commission-surveyed facilities. For New Entrants and Emerging Players: Pursue cost-optimized endoscopic screening infrastructure opportunities in India's Ayushman Bharat expansion corridors, where government-sponsored coverage creates addressable demand without capital-intensive robotic platform competition. Cloud-based surgical planning software for community hospitals without on-site colorectal specialists offers the most penetrable white-space target, with remote annotation capabilities as the differentiated go-to-market angle. For Investors and Strategic Acquirers: The market sits at a technology-convergence phase that favors platform-integrated device conglomerates over standalone component suppliers, with service revenue mix and disposable attach rates as the primary valuation differentiators. Acquisition target archetypes include AI-enhanced polyp detection developers holding FDA Breakthrough Devices Program designations, with CMS reimbursement determinations for outpatient colorectal surgery as the critical inflection signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 61 compliance accelerates market access for robotic platforms across German statutory insurance frameworks. |
| Hospital System Partnership | Long-term supply agreements with integrated delivery networks anchor disposable consumable volumes against GPO price compression. |
| Software Companion Development | AI-enhanced polyp detection modules qualify for FDA Breakthrough Devices Program review acceleration. |
| Reimbursement Strategy | CMS outpatient surgery code expansion directly determines ambulatory surgery center capital deployment priorities. |
| Clinician Training Investment | Proctology fellowship pipeline expansion addresses robotic surgery credentialing bottlenecks constraining platform utilization. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with colorectal surgeons, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineering directors, validated against secondary sources including FDA 510(k) clearance databases, CMS Medicare reimbursement determinations, EU MDR notified body guidance documents, and hospital procurement contract disclosures. Bottom-up procedure volume estimates triangulated with top-down capital equipment shipment data.
Calibration against historical regulatory approval timelines and reimbursement policy shifts anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass procedure type, technology tier, end-user facility category, and delivery mode site-of-care economics. CAGRs derived from installed base expansion rates, procedure volume trajectories, and per-procedure disposable consumption patterns, with robotic platform penetration curves and ambulatory surgery center migration rates as industry-specific forecast inputs.
Sensitivities concentrate around CMS reimbursement determinations for outpatient colorectal surgery, EU MDR notified body review backlogs, and robotic surgery credentialing pipeline expansion rates. Forecasts reflect documented assumptions regarding statutory screening mandate continuity and capital equipment replacement cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Ultrasonic Scalpel Market
Surgical Instruments
Global Dental Surgical Instruments Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Electrocautery Enhanced Delivery System Market
Surgical Instruments
Hand-Held Surgical Instruments Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
Harmonic Scalpel Market
Surgical Instruments
Uro Gynaecological Surgical Devices Market
Surgical Instruments
Global Surgical Scissors Market
Surgical Instruments
Surgical Headband Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Europe General Surgical Devices Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Surgical Drainage Devices Market
Surgical Instruments
Lumpectomy Market
Surgical Instruments
Knotless Tissue Control Devices Market