
 France General Surgical Devices Market | 2026-2036
France General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
France General Surgical Devices Market Foresight
Polymer composites are broadening design options for reusable forceps and retractors as stainless steel faces cost pressures. B. Braun Melsungen AG leverages its German manufacturing base to supply French distributors with sterilization-compatible polymer portfolios. Johnson & Johnson sustains competitive tension through its Ethicon division's suture kit specialization across Paris and Lyon hospital systems. Stryker Corporation anchors its position via dedicated sales teams serving ambulatory surgery centers in Marseille and Bordeaux.
General surgical devices encompass handheld and powered instruments employed to cut, coagulate, grasp, or retract tissue during operative procedures, typically manufactured from medical-grade stainless steel, titanium, or polymer composites with tolerances below 50 microns for blade edges. These instruments serve the fundamental purpose of enabling precise tissue manipulation while minimizing iatrogenic trauma across open and minimally invasive procedures. Electrosurgical technology leads revenue contribution given its integration into laparoscopic platforms, while ultrasonic devices represent the fastest-expanding segment due to reduced thermal spread in delicate dissection. Suture kits command durable margin pools through recurring consumable demand tied to procedure volume rather than capital replacement cycles.
ANSM enforces CE marking conformity under the EU Medical Device Regulation for all commercially distributed surgical instruments, creating compliance barriers for non-European manufacturers seeking French market entry. The French national health insurance system, CNAM, sets reimbursement tariffs that directly shape hospital purchasing committees' technology adoption timelines. Hospital procurement centralization through regional health agencies concentrates vendor qualification requirements. Stakeholders must monitor evolving MDR transition deadlines and CNAM's procedure-based budgeting methodology to anticipate purchasing cycle shifts.
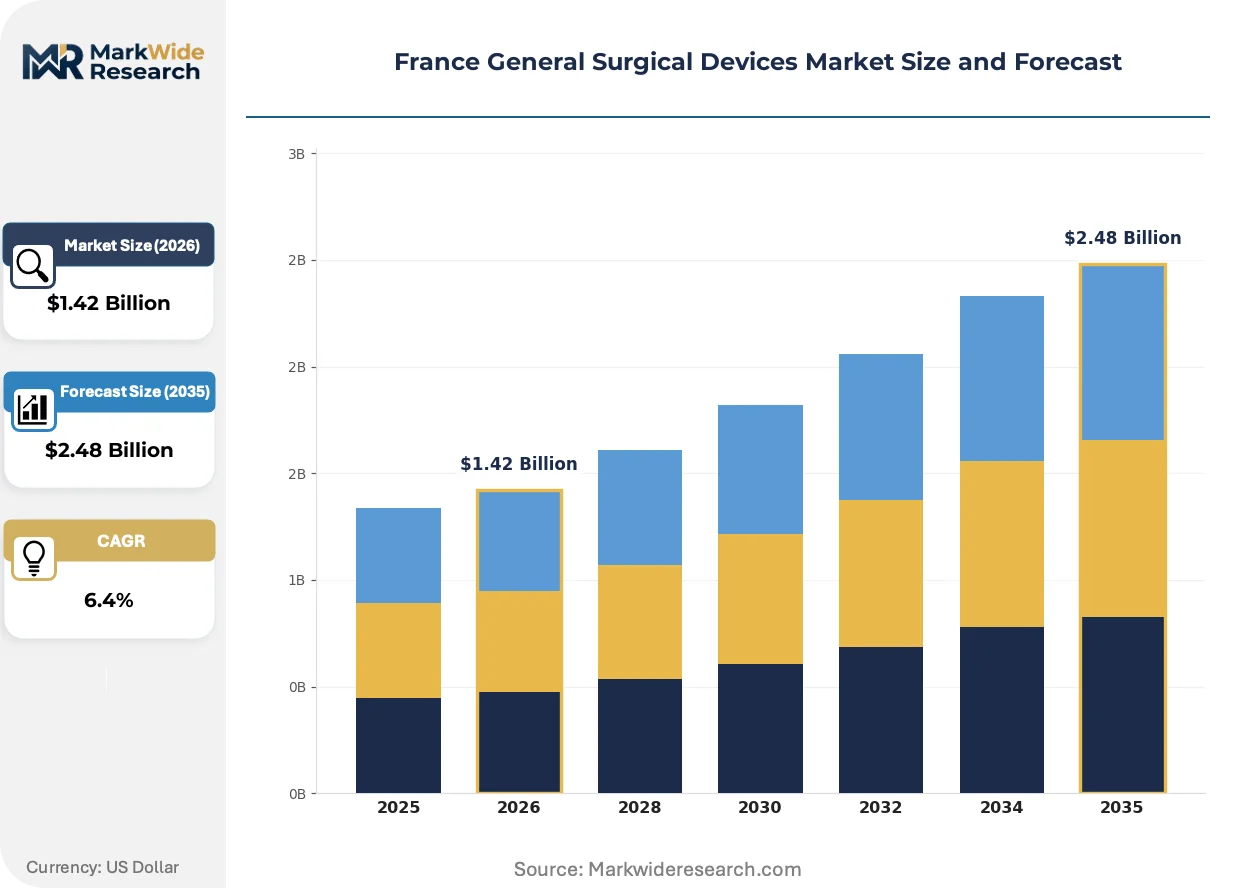
Market Dynamics
France's general surgical devices sector is compressing around the EU Medical Device Regulation transition timeline, with ANSM enforcement accelerating qualification barriers for non-European suppliers while public hospital procurement centralization through regional health agencies concentrates purchasing power into fewer vendor relationships.
Growth Catalysts
- ANSM Reimbursement Framework:France's national health insurance system CNAM sets procedure-based tariffs that accelerate adoption of electrosurgical platforms in Parisian teaching hospitals.
- Polymer Composite Materials:Medical-grade polymer portfolios enable sterilization-compatible instrument designs that reduce per-procedure costs for reusable forceps and retractors.
- Île-de-France Surgical Volume:The Paris metropolitan cluster anchors procedure concentration, driving sustained demand for suture kits and laparoscopic instruments through its hospital network density.
Market Restraints
- CE Marking Compliance Costs:The EU MDR technical documentation requirements impose capital-intensive conformity assessment barriers on small-scale manufacturers seeking French market entry.
- German Supply Concentration:Sterilization equipment and polymer raw material supply chains concentrate through Rhineland manufacturing hubs, creating single-source vulnerability for French distributors.
- Stainless Steel Input Volatility:Medical-grade steel pricing fluctuation compresses margin pools for traditional instrument portfolios against polymer alternatives.
Strategic Opportunities
- Auvergne-Rhône-Alpes Expansion:Lyon hospital system procurement decentralization creates vendor qualification openings outside the Paris-dominated supply base.
- Ambulatory Surgery Center Channel:Marseille and Bordeaux outpatient facilities represent underpenetrated demand for disposable instrument kits with compressed sterilization requirements.
- Ultrasonic-Electrosurgical Convergence:Hybrid energy platforms combining ultrasonic dissection with electrocautery functionality address reduced thermal spread requirements in delicate tissue procedures.
Industry Challenges
- MDR Transition Timeline Compression:Legacy instrument certificates expire under staggered EU deadlines, forcing simultaneous recertification campaigns across diversified product portfolios.
- Sterilization Validation Expertise Gap:Polymer composite compatibility testing requires specialized microbiology and materials science talent scarce in French contract manufacturing organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France General Surgical Devices Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scalpels, Forceps, Hemostats, Needle Holders, Retractors, Suture Kits Technology: Electrosurgical, Ultrasonic, Laser, Radiofrequency, Cryosurgical, Endoscopic Application: Cardiovascular, Neurosurgery, Orthopedic, Plastic Surgery, Gynecological, Gastrointestinal End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Teaching Institutions, Private Practices |
| Companies Covered | B. Braun Melsungen AG, Boston Scientific Corporation, CONMED Corporation, Johnson & Johnson, Olympus Corporation, Medtronic, Stryker Corporation, Abbott Laboratories, BD, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France General Surgical Devices Market Shifts & Advancements
Energy delivery modalities are fragmenting competitive positioning in French surgical suites, with thermal spread reduction becoming the decisive performance metric and procurement committees restructuring evaluation criteria around procedure-specific outcomes rather than capital cost alone.
Ultrasonic surgical systems is electrifying tissue dissection protocols in French oncology and gynecology departments. Lyon university hospitals have adopted these platforms for lymph node harvesting at accelerating replacement cycles. The technology is electrifying competitive dynamics by compressing electrosurgical incumbents into defensive bundling strategies.
The EU Medical Device Regulation's Unique Device Identification mandate is restructuring traceability infrastructure across French hospital supply chains. Manufacturers must embed machine-readable identifiers on instrument packaging, forcing serialization investments that reshape cost structures for low-margin reusable portfolios. Suture kit suppliers face the steepest compliance compression given high SKU complexity and distributed sterilization cycles.
Regional health agency procurement centralization is consolidating vendor relationships in France's hospital sector. The shift from individual facility purchasing to aggregated regional tenders reduces qualified supplier lists from dozens to single-digit panels. This concentration is most visible in Provence-Alpes-Côte d'Azur, where Marseille-based purchasing cooperatives now dominate ambulatory surgery center supply contracts.
France General Surgical Devices Market Segmentation
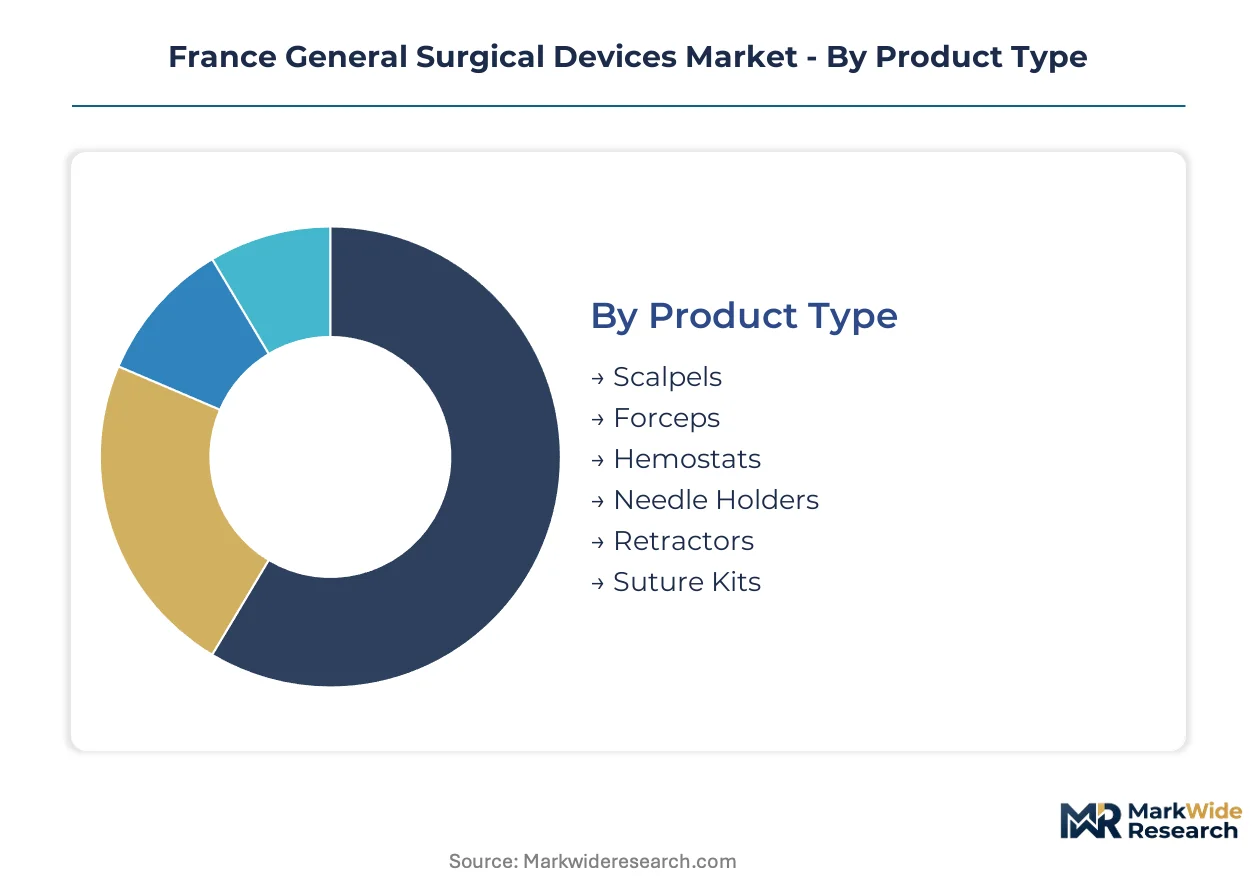
Segmentation in the France General Surgical Devices Market reveals how procurement committees prioritize capital equipment against consumable flows. Understanding these divisions exposes where ANSM compliance costs concentrate and where regional hospital networks direct their aggregated purchasing power.
Product Type:
Capital requirements vary sharply across instrument categories, with powered platforms demanding multimillion-euro sterilization infrastructure while handheld tools require minimal fixed asset deployment.
- Suture Kits:These consumable bundles combine needles, threads, and fixation devices in sterile packaging designed for single-procedure use. Demand concentrates in Parisian teaching hospitals where high-volume surgical throughput drives recurring procurement through regional health agency tenders. CNAM's procedure-based reimbursement directly scales kit consumption to operative volume.
- Retractors:Tissue exposure instruments span self-retaining mechanical designs and powered table-mounted systems requiring substantial OR integration investment. Lyon hospital systems are expanding retractor procurement as their cardiac surgery volumes climb, with polymer composite variants gaining preference over stainless steel for sterilization compatibility.
- Scalpels:Disposable blade-and-handle combinations dominate outpatient settings for cost efficiency.
- Forceps:Grasping instruments split between reusable titanium designs and single-use polymer variants.
- Hemostats:Vessel occlusion tools maintain steady demand across cardiovascular and trauma procedures.
- Needle Holders:Suturing assistance instruments require precision machining tolerances below 50 microns.
Suture kits absorb the bulk of installed procurement capacity; retractors are expanding most quickly as Lyon and Marseille hospital networks upgrade OR infrastructure.
Technology:
Technology selection in French surgical suites increasingly hinges on thermal spread metrics rather than capital cost alone, reshaping vendor qualification criteria.
- Electrosurgical:Radiofrequency current platforms for cutting and coagulation integrate into laparoscopic towers as the dominant energy modality. Île-de-France teaching hospitals anchor installed base concentration, though procurement committees are bundling these systems with ultrasonic attachments to address thermal damage concerns in delicate dissection.
- Ultrasonic:High-frequency mechanical vibration devices reduce lateral thermal spread compared to electrocautery, commanding premium positioning in oncology and gynecology departments. Lyon university hospitals have adopted these platforms for lymph node harvesting at accelerating replacement cycles.
- Laser:Focused light energy systems serve specialized ophthalmic and dermatological applications with limited general surgery penetration.
- Radiofrequency:Ablation-focused energy delivery targets cardiac and pain management procedures.
- Cryosurgical:Extreme cold tissue destruction remains niche for dermatological and prostatic interventions.
- Endoscopic:Visualization-coupled instrument platforms require dedicated tower infrastructure and specialized training pathways.
Electrosurgical platforms command the largest installed base; ultrasonic systems are climbing the fastest as thermal spread reduction becomes the decisive performance metric.
Application:
Procedure volume distribution across surgical specialties determines where device manufacturers concentrate their French sales and clinical support resources.
- Cardiovascular:Open-heart and interventional cardiac procedures demand high-precision instruments with specialized clamp and needle holder designs. The Auvergne-Rhône-Alpes region around Lyon anchors this segment through its cardiac surgery center density, with procurement decentralization creating vendor qualification openings outside Paris.
- Gastrointestinal:Laparoscopic and open abdominal procedures drive sustained demand for stapling devices and energy platforms. Marseille and Bordeaux ambulatory surgery centers are expanding GI procedure volumes, creating underpenetrated demand for disposable instrument kits with compressed sterilization requirements.
- Neurosurgery:Cranial and spinal interventions require sub-millimeter precision instruments with specialized ergonomic designs.
- Orthopedic:Joint replacement and trauma procedures consume high volumes of power tools and fixation devices.
- Plastic Surgery:Aesthetic and reconstructive procedures favor delicate tissue handling instruments with minimal thermal footprint.
- Gynecological:Minimally invasive hysterectomy and fertility procedures are adopting ultrasonic platforms for reduced adhesion formation.
Cardiovascular applications command the deepest installed base; gastrointestinal procedures are gaining share fastest as ambulatory surgery centers expand in Provence-Alpes-Côte d'Azur.
End User:
Customer type segmentation exposes divergent procurement authority structures, from centralized regional health agency tenders to individual physician purchasing decisions.
- Hospitals:Public and private acute care facilities dominate volume through aggregated regional procurement mechanisms. ANSM oversight and CNAM reimbursement frameworks shape technology adoption timelines, with Parisian teaching hospital networks setting standards that cascade to provincial facilities.
- Ambulatory Surgery Centers:Outpatient facilities in Marseille and Bordeaux represent underpenetrated demand for disposable instrument kits with compressed sterilization requirements. Regional purchasing cooperatives in Provence-Alpes-Côte d'Azur now dominate ASC supply contracts, consolidating vendor relationships into single-digit panels.
- Specialty Clinics:Focused ophthalmic, dental, and dermatological practices maintain independent procurement for procedure-specific instruments.
- Teaching Institutions:University-affiliated hospitals combine patient care with training missions, requiring instrument durability under intensive resident use.
- Private Practices:Individual surgeon offices maintain limited device procurement for minor procedural services.
Hospitals absorb the bulk of procurement volume; ambulatory surgery centers are expanding most quickly as France shifts procedures to outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's ZRR tax-incentive zones concentrate surgical device demand in designated regional clusters. Public hospital procurement centralization through regional health agencies channels investment into specific metropolitan corridors.
Île-de-France
Parisian teaching hospital networks drive the deepest installed base of electrosurgical platforms and suture kit consumption. ANSM oversight under the EU MDR framework accelerates technology qualification timelines for vendors serving this cluster. The Assistance Publique-Hôpitaux de Paris network anchors procurement volume, with aggregated tenders consolidating supplier relationships into single-digit panels.
Auvergne-Rhône-Alpes
Lyon's cardiac surgery centers generate expanding demand for precision retractors and needle holders with polymer composite sterilization compatibility. CNAM's procedure-based reimbursement tariffs directly scale device consumption to operative volume growth. The Hospices Civils de Lyon network is decentralizing procurement authority, creating vendor qualification openings outside Paris-dominated supply chains.
Provence-Alpes-Côte d'Azur
Marseille ambulatory surgery centers represent underpenetrated demand for disposable instrument kits with compressed sterilization requirements. Regional purchasing cooperatives now dominate ASC supply contracts, consolidating vendor relationships and reducing qualified supplier lists. The Aix-Marseille-Provence metropolitan cluster is expanding outpatient GI procedure volumes fastest.
Nouvelle-Aquitaine
Bordeaux hospital networks are upgrading OR infrastructure to capture shifting procedure volumes from inpatient to ambulatory settings. The EU MDR Unique Device Identification mandate is restructuring traceability infrastructure across regional supply chains. University hospital procurement committees are bundling electrosurgical systems with ultrasonic attachments to address thermal damage concerns.
France General Surgical Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational instrument portfolios dominating capital equipment while regional fabricators capture consumable flows. The vendor base concentrates around German supply chain proximity and Parisian distribution infrastructure. Three archetypes define positioning: diversified medtech conglomerates with full-stack surgical portfolios, mid-scale specialists in energy delivery platforms, and polymer-focused instrument fabricators serving sterilization-compatible niches. M&A activity targets ultrasonic-electrosurgical convergence capabilities, while strategic partnerships secure MDR compliance infrastructure for legacy certificate transitions.
Among diversified conglomerates, Johnson & Johnson and Stryker Corporation exemplify scale-driven positioning across French hospital systems. B. Braun Melsungen AG anchors the German manufacturing archetype with Rhineland-based supply chain integration into French distributor networks. These three occupy distinct competitive vectors: Johnson & Johnson through suture kit specialization, Stryker through ambulatory surgery center channel focus, and B. Braun through sterilization-compatible polymer portfolios.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Boston Scientific Corporation |
| CONMED Corporation |
| Johnson & Johnson |
| Olympus Corporation |
| Medtronic |
| Stryker Corporation |
| Abbott Laboratories |
| BD |
| Others |
Supply & Pricing Matrix
Regional health agency procurement centralization concentrates purchasing power into single-digit vendor panels, forcing suppliers toward contract-based pricing with volume-scaled discounts rather than spot-market transactions.
Pricing Analysis
Short lead-time premiums apply to polymer composite instruments facing sterilization validation bottlenecks, while spot inventory of stainless steel alternatives trades at modest discounts. The dominant structure is contract-based long-term offtake tied to regional tender awards, with price differentiation driven by CE marking tier and after-sales service bundling. Cost compression in traditional metal portfolios intensifies as German supply chain proximity erodes margin buffers. Ambulatory surgery centers exhibit highest price sensitivity due to compressed capital budgets; Parisian teaching hospitals show lowest sensitivity given procedure-based CNAM reimbursement.
Supply Chain Analysis
Freight costs from Rhineland manufacturing hubs to French distribution centers represent a persistent cost layer for polymer raw materials and sterilization equipment. Supply concentrates in Germany, Switzerland, and Ireland for precision-machined components and sterilization systems. Raw material dependencies span medical-grade stainless steel, titanium alloys, and polymer resins. Single-source vulnerability in German sterilization equipment creates structural risk. Distribution runs through Paris-based logistics nodes serving regional health agency consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
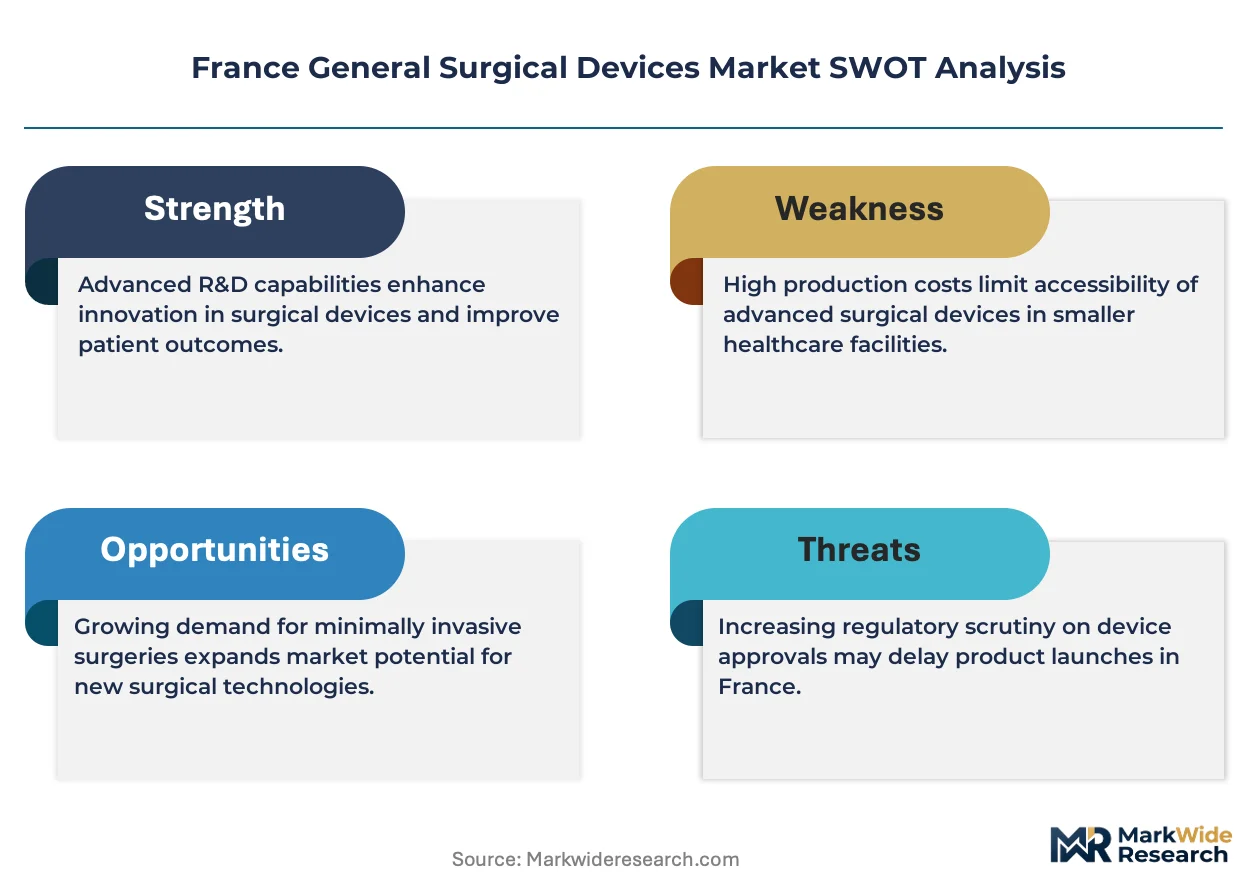
The France general surgical devices market operates as a cost-of-compliance story where EU MDR technical documentation requirements erect formidable barriers-to-entry moats for players with established Notified Body relationships.
For Market Incumbents: Lock in MDR certificate renewal cycles ahead of staggered legacy expiration deadlines to freeze out resource-constrained challengers. Secure backward integration into polymer resin supply through Rhineland partnerships to defend margin position against stainless steel price volatility. Channel control through dedicated sales teams serving ambulatory surgery centers in Marseille and Bordeaux remains essential as regional purchasing cooperatives consolidate vendor panels.
For New Entrants and Emerging Players: Ambulatory surgery centers in Provence-Alpes-Côte d'Azur represent the most penetrable buyer archetype given procurement decentralization and compressed sterilization requirements. Lyon hospital system procurement autonomy creates secondary entry opportunity outside Paris-dominated supply chains. A go-to-market angle bundling disposable instrument kits with UDI-compliant serialization services addresses immediate compliance pain points.
For Investors and Strategic Acquirers: The window for entry favors ultrasonic-electrosurgical convergence capabilities as thermal spread reduction becomes the decisive performance metric. Mid-scale energy platform specialists with MDR transition runway offer strongest long-term viability. Monitor ANSM enforcement intensity and CNAM reimbursement tariff adjustments as inflection indicators for purchasing cycle shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certificate Renewal Campaign | Accelerated timeline secures Notified Body relationships ahead of legacy expiration deadlines. |
| Polymer Composite Portfolio Expansion | Sterilization-compatible designs reduce per-procedure costs for reusable forceps and retractors. |
| Ambulatory Surgery Center Channel Buildout | Marseille and Bordeaux outpatient facilities represent underpenetrated demand for disposable kits. |
| Ultrasonic-Electrosurgical Platform Convergence | Hybrid energy systems address thermal spread requirements in oncology and gynecology departments. |
| UDI Serialization Infrastructure Investment | Machine-readable traceability compliance reshapes cost structures for high-SKU suture kit portfolios. |
Research Methodology
Document review covered hospital procurement databases, GPO contracts, ANSM regulatory filings, and CNAM reimbursement tariffs, complemented by interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and sterilization validation specialists. Secondary sources included EU MDR transition guidance, regional health agency tender documentation, and customs trade data for medical device imports. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Historical shipment data cross-referenced against panel input from procurement executives anchored volume projections across the analysis window. Segmentation dimensions modeled include product type, energy delivery technology, surgical application specialty, and end-user facility tier. CAGRs derived from procedure volume growth trajectories, reimbursement tariff evolution, and technology replacement cycle dynamics. Forecast inputs incorporated ANSM enforcement intensity scenarios and polymer raw material price trend assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MDR transition timeline slippage, CNAM reimbursement restructuring, and German supply chain disruption events. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Laparoscopic Power Morcellators Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Laparoscopic Gynecological Procedures Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
Global Laparoscopic Instruments Market
Surgical Instruments
Global Urology Surgical Instruments Market
Surgical Instruments
US Veterinary Surgical Instruments Market
Surgical Instruments
Surgical Drainage Devices Market
Surgical Instruments
United Arab Emirates General Surgical Devices Market
Surgical Instruments
Uro Gynaecological Surgical Devices Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Electrocautery Enhanced Delivery System Market
Surgical Instruments
Retractable Needles Market
Surgical Instruments
Articulating Paper Forceps Market
Surgical Instruments
Robotic Surgery Market
Surgical Instruments
Breast Retractors Market