
 Global Laparoscopic Instruments Market | 2026-2036
Global Laparoscopic Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laparoscopic Instruments Market Foresight
ISO 13485 certification cycles is reorganizing competitive standing in laparoscopic instrument manufacturing, elevating quality management barriers for new entrants. Medtronic leverages its broad surgical portfolio to sustain hospital system contracts across multiple instrument categories. Karl Storz SE & Co. KG anchors its position through rigid endoscope specialization and integrated visualization workflows. Olympus Corporation competes by dominating electrosurgical energy platforms that pair with laparoscopic access devices.
Laparoscopic instruments comprise elongated shafted tools with insulated handles and specialized tip geometries designed for triangulation through small abdominal ports, typically manufactured from surgical-grade stainless steel or titanium alloys with ceramic insulation layers to enable electrosurgical compatibility. These devices enable minimally invasive tissue manipulation, dissection, and hemostasis while reducing patient recovery trauma compared to open surgical approaches. Graspers and trocar cannulas constitute the mature volume base where pricing pressure intensifies, while robotic-assisted systems capture the fastest expansion trajectory as hospitals amortize platform investments across higher procedure volumes. Powered devices concentrate margin pools where battery technology and motor miniaturization differentiate performance.
FDA 510(k) clearance pathways govern US market entry timelines for novel laparoscopic devices, while the EU MDR requires strengthened clinical evidence for reusable instrument biocompatibility claims. The EPA regulates sterilization byproduct emissions from ethylene oxide processing facilities that clean reusable laparoscopic tool sets. Japan's PMDA maintains distinct quality system requirements that shape design documentation for Asian market access. Stakeholders must monitor regulatory divergence between major jurisdictions to avoid redundant conformity testing that strains product development budgets.
Market Dynamics
The EU Medical Device Regulation is compressing sterilization validation timelines for reusable instrument portfolios, forcing manufacturers to restructure quality management systems ahead of conformity assessment deadlines.
Growth Catalysts
- EU MDR sterilization mandates:Reusable instrument manufacturers face heightened biocompatibility documentation requirements that favor established producers with dedicated regulatory affairs infrastructure.
- Ambulatory surgical center expansion:United States outpatient facility networks are building dedicated laparoscopic service lines, creating concentrated procurement demand for instrument sets optimized for high-turnover environments.
- Robotic-assisted surgery platforms:Hospital capital investment in da Vinci and competing systems is generating pull-through demand for compatible instrument attachments and disposable accessories.
Market Restraints
- Titanium alloy supply concentration:Surgical-grade metal feedstock sourcing clusters in a limited geography, exposing instrument fabricators to input cost volatility and long-lead procurement cycles.
- Ethylene oxide sterilization capacity constraints:EPA emissions regulations are constraining facility throughput for reusable instrument reprocessing, creating bottlenecks in hospital supply chains.
- Single-use instrument substitution:Disposable laparoscopic tools are capturing procedure volume in infection-sensitive settings, pressuring reusable instrument pricing power.
Strategic Opportunities
- Japan PMDA pathway optimization:Dedicated quality system documentation for Asian market access remains underdeveloped among Western manufacturers, creating first-mover advantages for compliant entrants.
- Battery-powered device convergence:Motor miniaturization and wireless energy transfer are opening white space in powered dissectors and ultrasonic scalpels previously dominated by tethered systems.
- Direct-to-ambulatory distribution:Bypassing traditional hospital purchasing consortia to serve United States outpatient surgery centers with streamlined instrument sets and rapid replenishment logistics.
Industry Challenges
- ISO 13485 certification timeline compression:Quality management system audits are extending lead times for new product introductions, straining development budgets and launch sequencing.
- Electrosurgical compatibility testing:Ceramic insulation layer validation for bipolar energy devices requires specialized metrology infrastructure that mid-scale manufacturers lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laparoscopic Instruments Market |
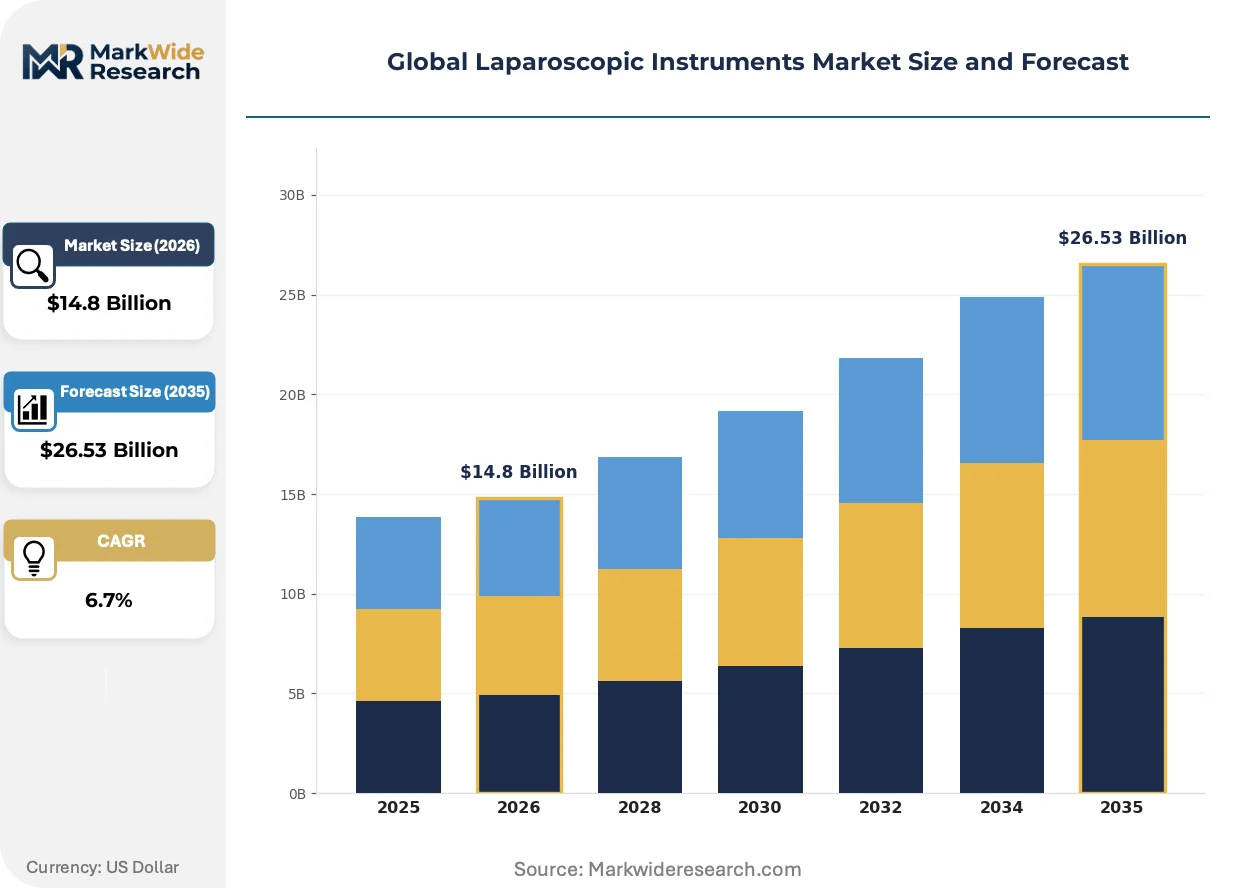
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graspers, Scissors, Trocar Cannulas, Needle Holders, Suction Irrigators Application: General Surgery, Gynecologic Procedures, Urologic Surgeries, Thoracic Interventions, Pediatric Operations End User: Specialty Clinics, Ambulatory Surgical Centers, Teaching Institutions, Diagnostic Centers Technology: Manual Instruments, Powered Devices, Robotic-Assisted Systems, Visualization Systems |
| Companies Covered | Johnson & Johnson Services, Inc., Medtronic, Olympus Corporation, Karl Storz SE & Co. KG, Stryker Corporation, CONMED Corporation, B. Braun Melsungen AG, Intuitive Surgical, Smith & Nephew plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laparoscopic Instruments Market Shifts & Advancements
Instrumentation design is converging with advanced materials science and wireless power systems, compressing device footprints while expanding functional integration within constrained abdominal access ports.
Motor and battery assemblies for powered laparoscopic instruments are miniaturizing through solid-state energy storage advances and brushless DC motor architectures. Ambulatory surgical centers in the United States are adopting these compact devices to reduce sterilization burden and accelerate room turnover. The technology is miniaturizing instrument shaft diameters below five millimeters while maintaining torque output, enabling reduced port trauma and expanded pediatric application.
REACH substance restrictions are phasing out specific nickel alloys in instrument compositions, compelling metallurgical reformulation toward cobalt-chrome alternatives. European manufacturers face requalification costs for existing product lines while Asian exporters confront border testing protocols for legacy material compositions. Electrosurgical instrument categories with prolonged tissue contact face the most stringent migration timeline and substitution cost exposure.
Hospital procurement consortia are consolidating vendor panels around multi-category surgical suppliers, displacing standalone instrument specialists from preferred supplier status. United States health system purchasing organizations are bundling laparoscopic tools with capital equipment and service contracts, compressing standalone instrument margins. General surgery departments within integrated delivery networks are standardizing on single-source portfolios to reduce sterilization protocol complexity and training variation.
Global Laparoscopic Instruments Market Segmentation
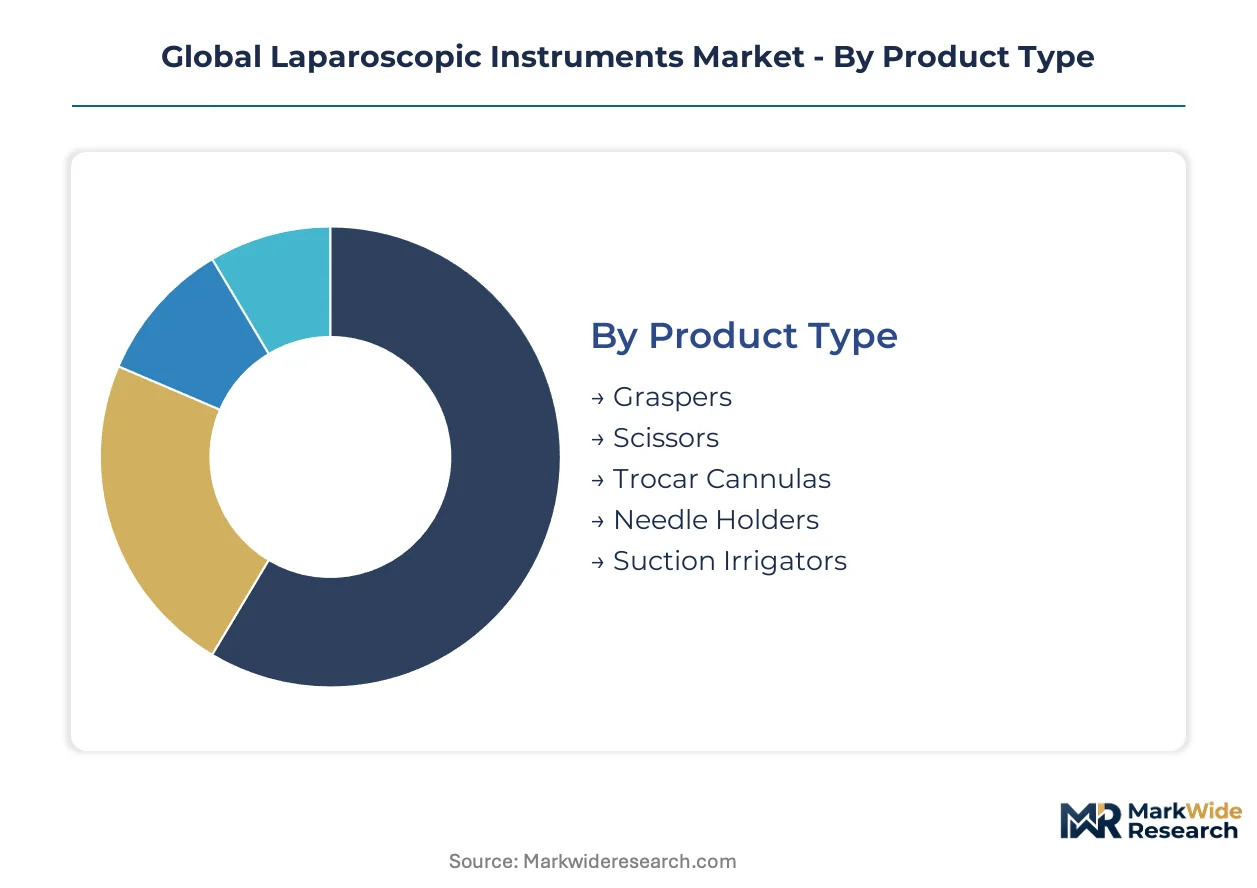
Laparoscopic instrument segmentation reveals how regulatory frameworks, procedural economics, and facility infrastructure shape procurement patterns across distinct product categories and clinical settings. Understanding these divides exposes where margin pools concentrate versus where volume commoditization pressures dominate.
Product Type:
FDA 510(k) clearance pathways and EU MDR biocompatibility mandates create divergent compliance burdens across mechanical versus electrosurgical instrument classes.
- Trocar Cannulas:These access ports combine polymer sleeves with stainless steel obturators, serving as the procedural entry point for all laparoscopic interventions. United States ambulatory surgical centers are standardizing on low-profile designs with integrated insufflation valves to accelerate room turnover. Established volume favors trocar cannulas; emerging adoption favors powered devices.
- Powered Devices:Battery-driven dissectors and ultrasonic scalpels incorporate brushless DC motors and solid-state energy storage within five-millimeter shaft diameters. Japanese teaching institutions are piloting these instruments to reduce sterilization burden and enable expanded pediatric applications. These instruments represent the fastest-growing trajectory as motor miniaturization advances.
- Graspers:Shafted tissue manipulation tools with insulated handles and specialized tip geometries for triangulation through abdominal ports.
- Scissors:Electrosurgical-compatible cutting instruments with ceramic insulation layers enabling bipolar energy delivery.
- Needle Holders:Precision suturing tools with ratcheted locking mechanisms for intracorporeal knot-tying in confined spaces.
- Suction Irrigators:Dual-lumen instruments combining fluid delivery and smoke evacuation during electrosurgical dissection.
Procurement economics favor high-volume consumables; clinical differentiation favors electrosurgical integration.
Application:
Procedural reimbursement rates and operative complexity determine instrument set composition and replacement cadence across surgical specialties.
- General Surgery:Cholecystectomy, appendectomy, and hernia repair procedures constitute the foundational volume base for laparoscopic instrument deployment. United States hospital systems are consolidating vendor contracts around multi-category suppliers to reduce sterilization protocol complexity. Established volume favors general surgery; emerging adoption favors thoracic interventions.
- Gynecologic Procedures:Hysterectomy, myomectomy, and endometriosis excision demand specialized curved instruments and uterine manipulation devices. German university hospitals are driving adoption of advanced bipolar vessel sealers in these procedures. Gynecologic applications are expanding most quickly as minimally invasive techniques replace open approaches.
- Urologic Surgeries:Prostatectomy and nephrectomy procedures require extended instrument lengths and articulating tip designs for deep pelvic access.
- Thoracic Interventions:Video-assisted thoracoscopic surgery employs angled instruments and specialized trocar configurations for rib-sparing access.
- Pediatric Operations:Reduced-port and single-incision procedures drive demand for three-millimeter instrument sets with scaled-down ergonomics.
Adult procedural volume anchors manufacturer revenue; pediatric specialization commands premium positioning.
End User:
Capital availability and case-mix density shape whether facilities invest in reusable instrument sterilization infrastructure or migrate toward single-use alternatives.
- Ambulatory Surgical Centers:United States outpatient networks are building dedicated laparoscopic service lines with instrument sets optimized for high-turnover environments. These facilities prioritize rapid sterilization turnaround and standardized tray configurations to maximize throughput. Established volume favors ambulatory surgical centers; emerging adoption favors specialty clinics.
- Teaching Institutions:Academic medical centers in Japan require dedicated quality system documentation for PMDA compliance, creating procurement complexity for Western manufacturers. These institutions drive demand for training-compatible instrument sets with enhanced tactile feedback. Teaching hospitals are gaining share fastest as residency programs expand minimally invasive curricula.
- Specialty Clinics:Focused gynecologic and urologic practices concentrate procedure volume in narrow instrument categories.
- Diagnostic Centers:Biopsy and exploratory laparoscopy facilities require basic instrument sets for low-complexity interventions.
High-throughput outpatient facilities dominate procurement scale; academic centers drive technology validation.
Technology:
Integration depth with visualization and energy platforms determines competitive positioning and customer switching costs.
- Manual Instruments:Stainless steel and titanium alloy tools with ceramic insulation layers constitute the mature volume base where pricing pressure intensifies. REACH substance restrictions are phasing out specific nickel alloys, compelling metallurgical reformulation toward cobalt-chrome alternatives in European markets. Established volume favors manual instruments; emerging adoption favors robotic-assisted systems.
- Robotic-Assisted Systems:da Vinci-compatible instrument attachments and disposable accessories generate pull-through demand from hospital capital investments. United States health systems are amortizing platform costs across higher procedure volumes through bundled service contracts. Robotic-assisted configurations are climbing the fastest as hospitals expand dedicated surgical programs.
- Powered Devices:Battery technology and motor miniaturization differentiate performance in ultrasonic and radiofrequency instruments.
- Visualization Systems:Integrated camera and light source platforms pair with rigid endoscopes for enhanced operative field clarity.
Tethered systems anchor current installed base; wireless and autonomous capabilities define replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement incentives for minimally invasive procedures are accelerating laparoscopic instrument procurement across hospital systems. Regulatory divergence between FDA 510(k) pathways and EU MDR conformity assessments is fragmenting market access strategies. Industrial clusters in Germany, the United States, Japan, and China concentrate manufacturing capacity and R&D investment.
United States
Ambulatory surgical center networks are expanding dedicated laparoscopic service lines, creating concentrated demand for high-turnover instrument sets. The FDA maintains 510(k) clearance pathways that govern market entry timelines for novel devices. The Minneapolis-St. Paul corridor hosts sterilization validation facilities serving reusable instrument reprocessing chains.
Germany
University hospitals in Baden-Württemberg and Bavaria drive adoption of advanced bipolar vessel sealers across gynecologic and general surgery procedures. The EU Medical Device Regulation mandates strengthened clinical evidence for reusable instrument biocompatibility claims. The Tuttlingen surgical instrument cluster anchors rigid endoscope specialization and integrated visualization workflows.
Japan
Teaching institutions in Tokyo and Osaka require dedicated quality system documentation for PMDA compliance, creating procurement complexity for Western manufacturers. METI oversees distinct design documentation standards that shape Asian market access. The Nagoya medical device corridor concentrates electrosurgical energy platform development.
China
Domestic hospital procurement is shifting toward locally manufactured instrument sets as NMPA streamlines registration pathways for Class II devices. The national pharmaceutical regulator enforces GB standards for surgical-grade stainless steel compositions. The Yangtze River Delta industrial zone hosts expanding fabrication capacity for trocar cannulas and graspers.
Global Laparoscopic Instruments Market Competitive Landscape
Player mix skews toward diversified surgical conglomerates with multi-category portfolios. The vendor base concentrates around three to five integrated suppliers capable of bundling instruments with capital equipment and service contracts. Two strategic archetypes dominate: broad-line hospital system contractors and rigid endoscope specialists with visualization integration. Competitive moves center on sterilization validation infrastructure investment and ambulatory surgical center direct distribution channels.
Within the diversified conglomerate tier, Johnson & Johnson Services, Inc. and Medtronic occupy positions as hospital system contractors across multiple instrument categories. Olympus Corporation exemplifies the electrosurgical energy platform archetype, while Karl Storz SE & Co. KG anchors rigid endoscope specialization. Stryker Corporation represents the orthopedic-to-surgical diversification model, and B. Braun Melsungen AG sits within the European manufacturing cluster with sterilization system integration.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Medtronic |
| Olympus Corporation |
| Karl Storz SE & Co. KG |
| Stryker Corporation |
| CONMED Corporation |
| B. Braun Melsungen AG |
| Intuitive Surgical |
| Smith & Nephew plc |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day sterilization validation cycles compress inventory turns for reusable instrument portfolios, concentrating pricing power with manufacturers possessing dedicated regulatory affairs infrastructure while forcing smaller fabricators toward single-use alternatives or contract sterilization dependencies.
Pricing Analysis
Certification level (ISO 13485/CE/FDA-grade) creates the primary spread between premium and commodity tiers in laparoscopic instruments. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with FDA-cleared electrosurgical devices commanding substantial premiums over basic mechanical graspers. Cost compression in standard-grade reusable sets is intensifying because hospital purchasing consortia are consolidating vendor panels around bundled multi-category contracts. Ambulatory surgical centers exhibit the highest price sensitivity due to constrained capital budgets and rapid room-turnover economics, while academic medical centers prioritize certification grade over unit cost.
Supply Chain Analysis
Strategic stockpiling of surgical-grade titanium and cobalt-chrome alloys has replaced just-in-time preferences as REACH substance restrictions and EPA emissions constraints disrupt feedstock availability. Manufacturing concentrates in Germany, the United States, and China, with the Tuttlingen cluster anchoring European rigid endoscope production and the Yangtze River Delta expanding trocar and grasper fabrication capacity. Supply chains rest on concentrated sourcing of nickel-free alloys, ceramic insulation substrates, and precision-machined polymer components. Single-source vulnerability in ethylene oxide sterilization capacity creates bottlenecks for reusable instrument reprocessing. Distribution runs through hospital purchasing consortia and GPO contracts in the United States, with direct-to-ambulatory channels gaining traction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense as single-use disposable instruments capture procedure volume in infection-sensitive clinical settings, eroding the reusable instrument installed base that has anchored manufacturer revenue.
For Market Incumbents: Consolidate sterilization validation infrastructure investments ahead of EU MDR conformity deadlines to defend hospital system contracts against emerging competitors lacking dedicated quality management resources. Deepen backward integration into surgical-grade alloy supply through captive sourcing agreements with German and Chinese metallurgical suppliers. Prioritize ambulatory surgical center direct distribution channels to offset pricing pressure from consolidated hospital purchasing consortia.
For New Entrants and Emerging Players: Anchor in Japan's PMDA pathway optimization opportunity where Western manufacturers remain underdeveloped in quality system documentation, creating first-mover positioning for compliant entrants. Target battery-powered device convergence in ultrasonic scalpels and powered dissectors, where motor miniaturization and wireless energy transfer have opened white space previously dominated by tethered systems. Pursue teaching institution partnerships to establish clinical validation credentials before scaling to broader hospital procurement.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified surgical conglomerates seeking to divest standalone instrument portfolios that lack capital equipment bundling leverage. Long-term viability hinges on exposure to robotic-assisted surgery platform compatibility and powered device technology trajectories rather than commoditized mechanical instrument categories. Monitor FDA 510(k) clearance velocity and EU MDR notified body capacity as inflection indicators for new product introduction timelines and competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Pathway Acceleration | Notified body capacity constraints compress sterilization validation timelines for reusable portfolios. |
| Ambulatory Surgical Center Direct Distribution | Bypassing hospital purchasing consortia captures high-turnover outpatient procedure volume. |
| Battery-Powered Device Miniaturization | Solid-state energy storage advances enable reduced-port pediatric applications. |
| Robotic Platform Compatibility Investment | da Vinci-compatible attachments generate pull-through demand from hospital capital commitments. |
| REACH Alloy Reformulation Program | Cobalt-chrome substitution for phased nickel alloys requires metallurgical requalification investment. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and ambulatory surgical center administrators and refined through secondary validation against FDA 510(k) clearance databases, EU MDR notified body registers, hospital procurement contract disclosures, and surgical instrument trade flow records. Bottom-up demand modeling across procedure volume and instrument replacement cadence was triangulated with top-down manufacturer revenue analysis.
Variance decomposition across product type, application specialty, end-user facility class, and technology platform shaped the analytical framework over the projection horizon. CAGRs were derived from procedure volume growth trajectories and instrument penetration rates by surgical specialty, with cross-referencing to capital equipment installation bases and reimbursement incentive structures. Electrosurgical energy platform integration depth and sterilization infrastructure compliance status served as critical forecast sensitivity inputs.
Material uncertainties — regulatory divergence between FDA and EU MDR pathways, ethylene oxide sterilization capacity constraints, and titanium alloy supply volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding procedure volume migration to ambulatory settings and robotic platform adoption curves. Practitioners should keep alternative scenarios live as REACH substance restriction timelines and EPA emissions enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
Global Surgical Scalpel Market
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
Global Surgical Suction Instruments Market
Surgical Instruments
Global Surgical Stapler Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
US Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Cryosurgery Market
Surgical Instruments
Global Surgical Instrument Tracking System Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
US Surgical Sutures Market
Surgical Instruments
Global Myomectomy Market
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
Endometrial Ablation Market