
 Minimally Invasive Gastrointestinal Surgical System Market | 2026-2036
Minimally Invasive Gastrointestinal Surgical System Market Size, Share, and Industry Trends Forecast 2026-2036
Minimally Invasive Gastrointestinal Surgical System Market Insights
4K visualization capability is rotating through the installed base of minimally invasive gastrointestinal surgical systems as hospitals replace aging standard-definition towers. Medtronic leverages its end-to-end surgical ecosystem to sustain service revenue across upgrade cycles. Intuitive Surgical anchors the robotic-assisted segment with proprietary instrument architectures that lock in recurring consumables revenue.
A minimally invasive gastrointestinal surgical system comprises instruments, visualization platforms, and energy devices designed to access and manipulate abdominal organs through ports smaller than twelve millimeters, typically employing carbon dioxide insufflation to create operative workspace. These systems enable tissue dissection, hemostasis, and reconstruction while minimizing incision trauma, which reduces postoperative recovery intervals and complication rates relative to open approaches. Robotic platforms command premium positioning due to their wristed instrumentation and tremor filtration, while laparoscopic systems retain volume leadership across cost-sensitive procurement environments. Visualization systems capture disproportionate margin pools as hospitals prioritize image clarity for complex bariatric and colorectal procedures.
The FDA governs 510(k) clearance and premarket approval pathways for these devices in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements and post-market surveillance obligations on manufacturers seeking CE marking. These frameworks shape product development timelines, predicate device selection strategies, and market access sequencing for new entrants. Stakeholders must monitor evolving reimbursement thresholds for robotic-assisted procedures as payors recalibrate coverage policies against outcome evidence.
Market Dynamics
The installed base replacement cycle for visualization towers is compressing as 4K and fluorescence-capable systems displace aging standard-definition infrastructure across integrated delivery networks.
Growth Catalysts
- 510(k) Pre-market Notification:The FDA's streamlined clearance pathway accelerates technology transfer from bench to bedside, reducing time-to-revenue for novel instrument architectures.
- Ambulatory Surgical Centers:Freestanding ASCs are expanding procedural volume for cholecystectomy and hernia repair, creating pull-through demand for compact laparoscopic platforms.
- Fluorescence-Guided Surgery:Near-infrared imaging integration with standard laparoscopes enables real-time perfusion assessment during colorectal anastomosis.
Market Restraints
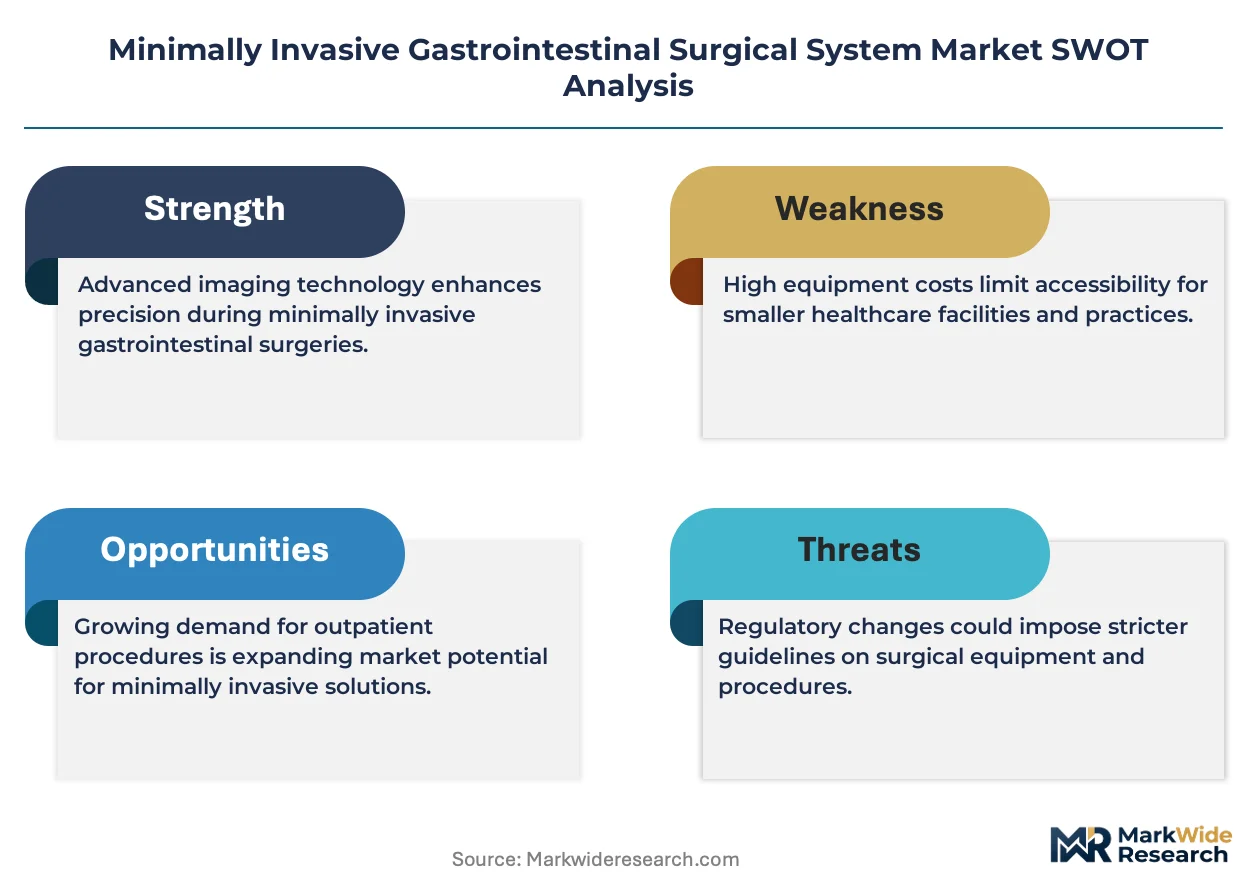
- Capital Equipment Intensity:Robotic platform acquisition requires $1.5–2.5 million upfront commitment plus multi-year service contracts, constraining community hospital participation.
- Instrument Supply Concentration:Proprietary robotic trocar and end-effector architectures lock purchasers into single-source consumable streams with limited pricing leverage.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation's stricter post-market surveillance and predicate device limitations extend recertification timelines for legacy laparoscopic portfolios.
Strategic Opportunities
- India Tier-2 Hospital Expansion:Government-funded medical college hospitals and district surgical centers present untapped demand for cost-optimized laparoscopic towers.
- Single-Port Platform Convergence:Integration of articulating instruments with miniaturized camera systems enables reduced-incision cholecystectomy and appendectomy.
- Japan PMDA Sakigake Pathway:The regenerative medicine and innovative device fast-track designation accelerates market entry for AI-integrated surgical navigation systems.
Industry Challenges
- Robotic Console Surgeon Training:Proctored case volume requirements and credentialing bottlenecks limit deployment speed for newly installed da Vinci systems.
- Interoperability with PACS Infrastructure:DICOM conformance gaps between proprietary visualization platforms and hospital archive systems create workflow friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minimally Invasive Gastrointestinal Surgical System Market |
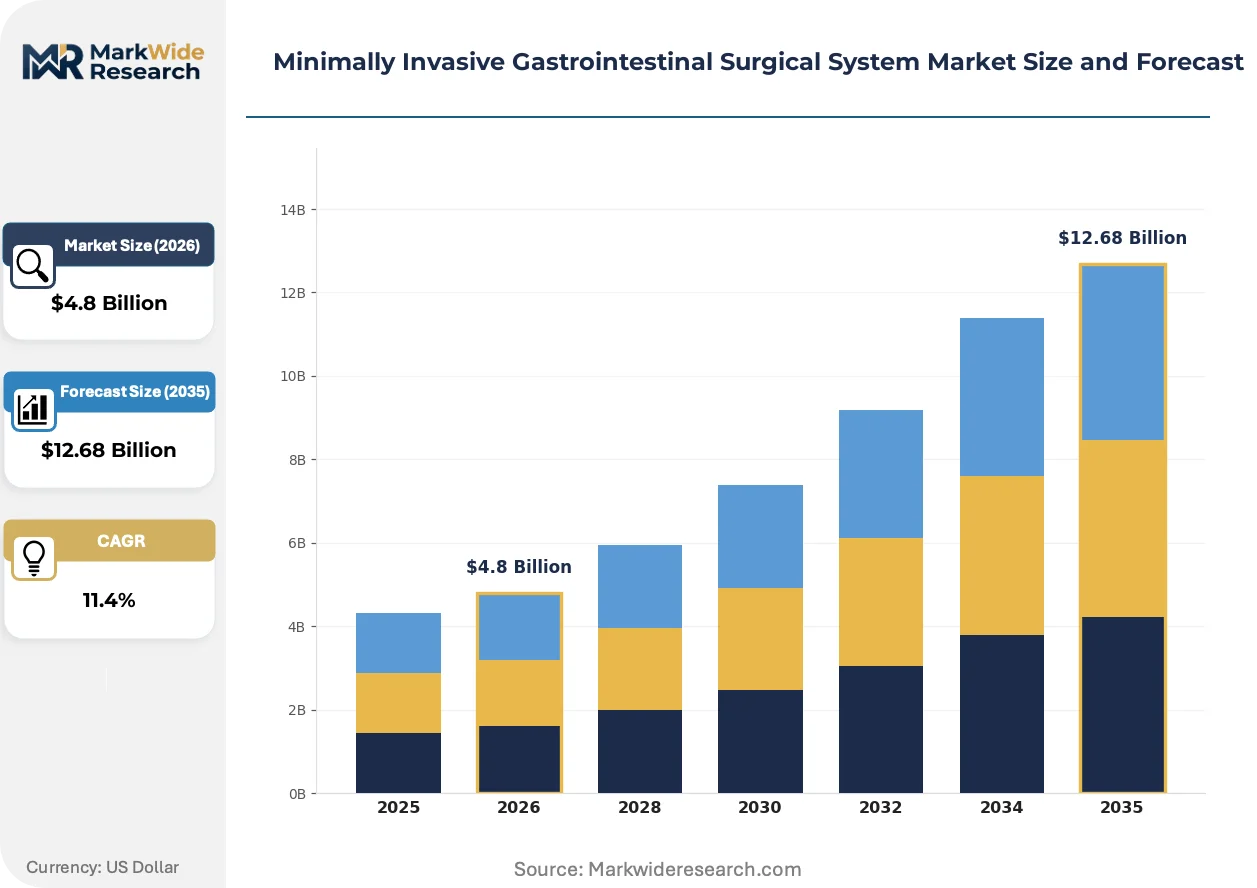
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopic, Laparoscopic, Electrosurgical, Robotic Technology: Visualization Systems, Energy Devices, Access Devices, Suturing Devices End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialized Surgical Centers Application: Colorectal Surgery, Bariatric Surgery, General Surgery, Cholecystectomy |
| Companies Covered | Medtronic, Intuitive Surgical, Johnson & Johnson, Boston Scientific Corporation, Stryker Corporation, Olympus Corporation, Karl Storz SE & Co. KG, Fujifilm Holdings Corporation, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minimally Invasive Gastrointestinal Surgical System Market Trends and Innovations
Digital surgery ecosystems are fragmenting competitive architecture as standalone instrument vendors, visualization specialists, and robotics platforms contest overlapping value pools.
Fluorescence-guided imaging is bifurcating the visualization market into premium-tier integrated systems and modular upgrade paths for installed standard-definition towers. Academic medical centers in the United States are adopting ICG-perfusion protocols for low anterior resection at accelerating pace. This technology is compressing revision surgery rates and shifting purchasing criteria toward image-processing chipset specifications.
The EU Medical Device Regulation's Unique Device Identification mandate is restructuring supplier documentation obligations and post-market clinical follow-up requirements. Manufacturers must now maintain active implantable device-level traceability for reusable laparoscopic instruments. The colorectal surgery segment faces the steepest compliance cost escalation as procedure-specific outcome registries become mandatory for CE marking renewal.
Hospital capital committees are unbundling service contracts from equipment procurement, forcing vendors to price maintenance and software updates as discrete line items. Integrated delivery networks in Texas and Florida are piloting utilization-based service agreements where vendor compensation ties to console uptime metrics. This shift is most visible among IDNs managing robotic fleet deployments exceeding six systems.
Minimally Invasive Gastrointestinal Surgical System Market Segmentation
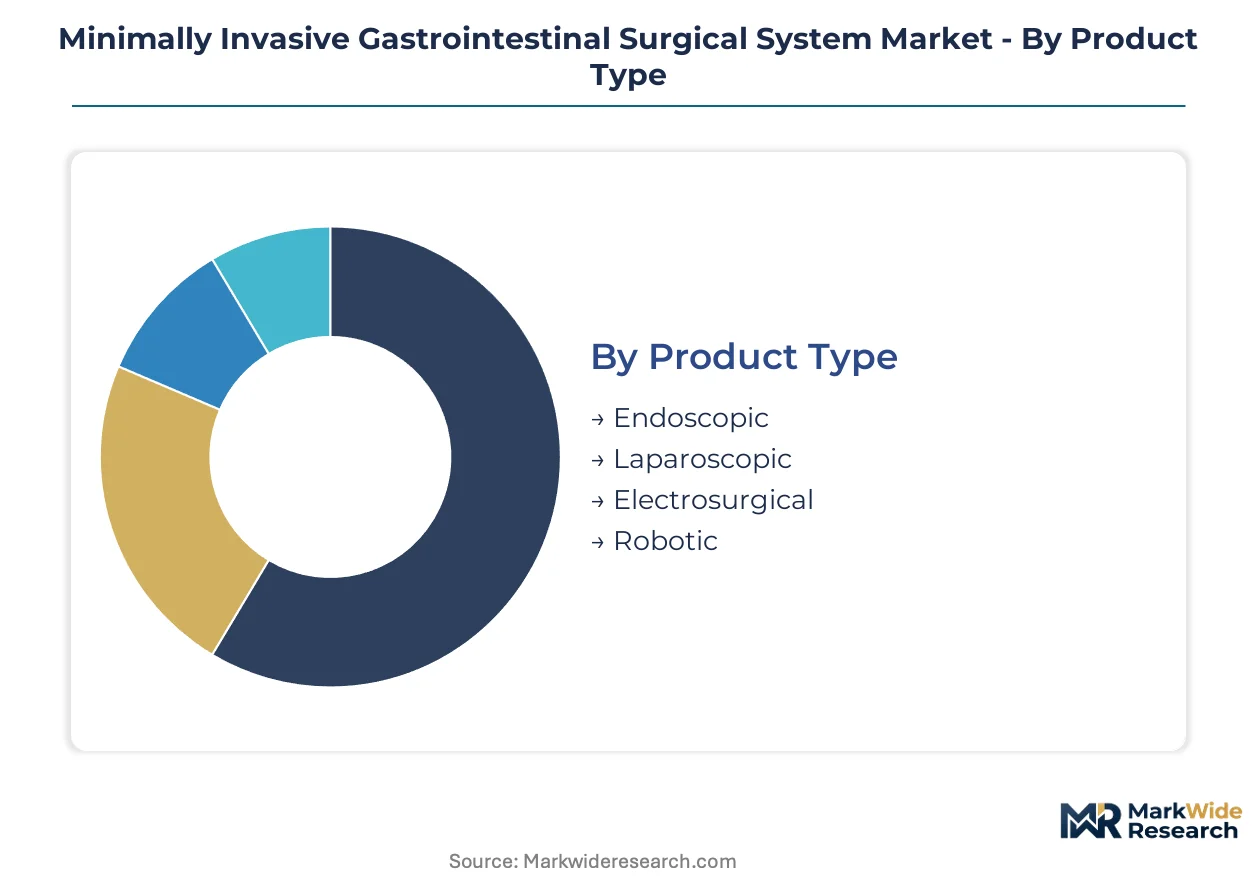
Product configuration determines capital deployment patterns across minimally invasive gastrointestinal surgical systems. Technology integration levels and end-user facility type shape procurement workflows and service contract structures.
Product Type:
Domestic procurement concentrates in robotic and electrosurgical platforms, while laparoscopic systems drive export volume to cost-sensitive markets.
- Endoscopic:Flexible scopes with integrated biopsy channels enable mucosal visualization and tissue sampling through natural orifices. Demand clusters in Japan and Germany where screening colonoscopy programs generate high procedural volume.
- Laparoscopic:Rigid telescopic instruments with trocar-based abdominal access form the installed base backbone. Community hospitals across India and Brazil prioritize these systems for cholecystectomy and hernia repair volume.
- Electrosurgical:Monopolar and bipolar energy platforms deliver tissue cutting and coagulation through instrument-integrated generators.
- Robotic:Wristed instrumentation with tremor filtration commands premium positioning in academic medical centers.
Laparoscopic systems hold the largest share; momentum sits with robotic platforms.
Technology:
Cost tier differentiation separates visualization systems at premium price points from access devices competing on volume scale.
- Visualization Systems:4K and fluorescence-capable camera towers with image processing chipsets capture disproportionate margin pools. Integrated delivery networks in the United States prioritize ICG-perfusion protocols for colorectal anastomosis assessment.
- Energy Devices:Ultrasonic and advanced bipolar platforms enable vessel sealing and tissue transection with minimal thermal spread. Adoption concentrates in bariatric surgery suites where leak prevention drives instrument selection.
- Access Devices:Trocars and insufflation systems create operative workspace through abdominal wall entry points.
- Suturing Devices:Automated and manual laparoscopic needle drivers facilitate intracorporeal knot tying and anastomosis construction.
Visualization systems command premium positioning; energy devices are expanding most quickly across procedural categories.
End User:
Customer type determines equipment footprint and service intensity, with hospitals managing complex fleets and ambulatory centers optimizing for throughput.
- Hospitals:Academic and community facilities with hybrid operating rooms integrate multi-platform surgical ecosystems. Capital committees in Texas and Florida unbundle service contracts from procurement to negotiate utilization-based vendor agreements.
- Ambulatory Surgical Centers:Freestanding facilities prioritize compact laparoscopic towers for high-volume cholecystectomy and hernia repair. Medicare reimbursement shifts for outpatient procedures accelerate ASC equipment refresh cycles.
- Clinics:Office-based settings deploy basic endoscopic systems for diagnostic procedures.
- Specialized Surgical Centers:Bariatric-focused facilities concentrate robotic platform deployment for complex metabolic procedures.
Hospitals retain volume leadership; ASCs are gaining share fastest as procedural migration accelerates.
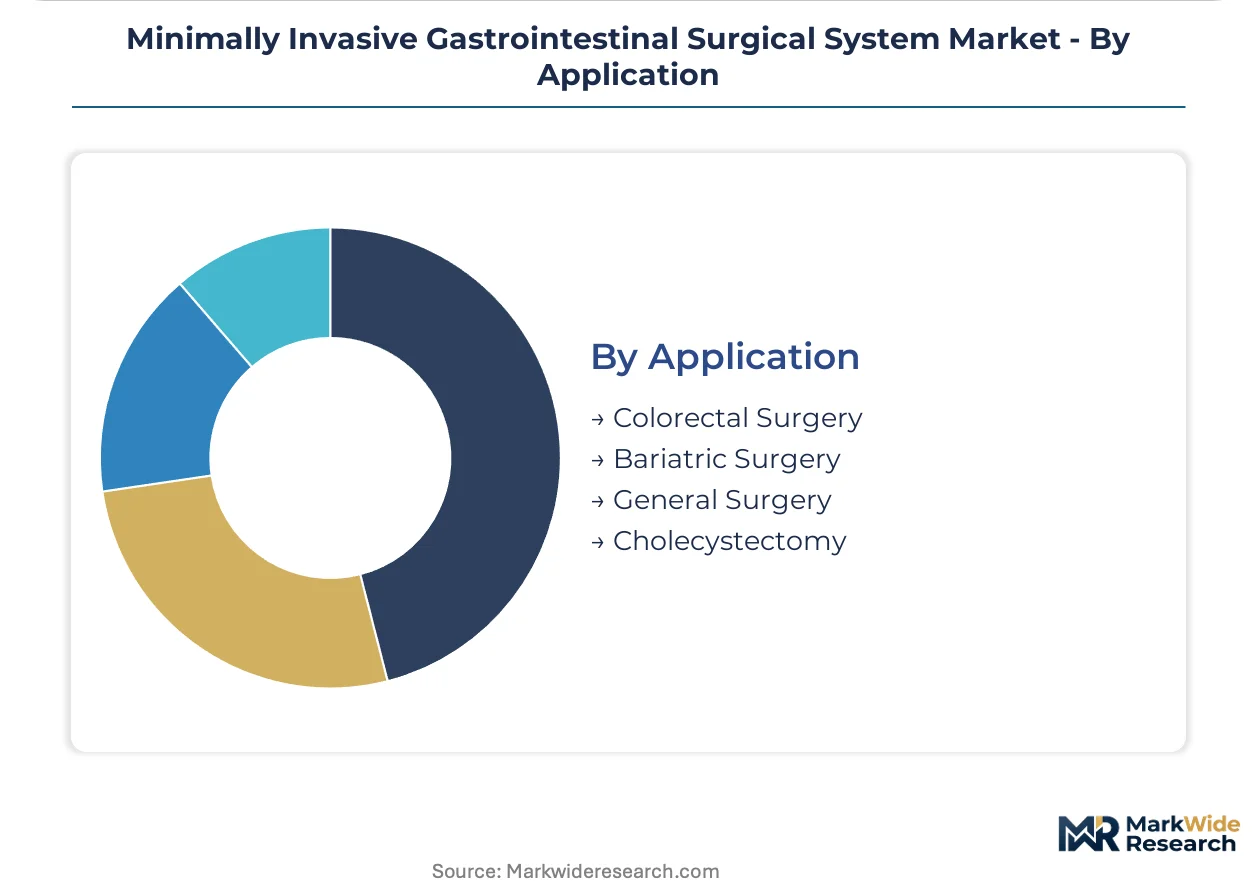
Application:
Procedure complexity and reimbursement levels stratify demand across surgical specialties, with bariatric and colorectal segments driving technology upgrade cycles.
- Colorectal Surgery:Low anterior resection and rectal cancer procedures demand fluorescence-guided perfusion assessment and precise mesenteric dissection. EU MDR compliance costs escalate for this segment as procedure-specific outcome registries become mandatory for CE marking renewal.
- Bariatric Surgery:Sleeve gastrectomy and gastric bypass require stapling systems with tissue thickness sensing and leak testing protocols. Academic medical centers anchor demand for integrated energy and stapling platforms.
- General Surgery:Appendectomy and diagnostic laparoscopy represent high-volume entry points for minimally invasive technique adoption.
- Cholecystectomy:Gallbladder removal serves as the foundational procedure for laparoscopic training and community hospital system deployment.
General surgery holds the largest share; colorectal applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters concentrate in Germany, the United States, and Japan, with assembly operations extending into China and India for cost-sensitive product tiers. Integrated delivery networks in Texas and Florida drive North American procurement volume, while government-funded hospital expansion in India accelerates laparoscopic tower deployment.
United States
Academic medical centers in Houston and Boston anchor demand for robotic-assisted platforms with wristed instrumentation. The FDA's 510(k) premarket notification pathway accelerates clearance timelines for novel visualization systems. IDNs across Texas unbundle service contracts from capital procurement, negotiating utilization-based vendor agreements tied to console uptime metrics.
Germany
Precision engineering clusters in Baden-Württemberg and Bavaria manufacture rigid endoscopes and camera towers for export markets. The EU Medical Device Regulation imposes stricter clinical evidence requirements and post-market surveillance obligations on manufacturers seeking CE marking. Tübingen and Erlangen host specialized surgical device development centers serving European hospital networks.
Japan
Screening colonoscopy programs generate high procedural volume for flexible endoscopic systems in Tokyo and Osaka metropolitan areas. The PMDA Sakigake fast-track designation accelerates market entry for AI-integrated surgical navigation platforms. Nagoya's medical device manufacturing corridor supplies fluorescence-capable imaging systems to domestic and Asian markets.
India
Government-funded medical college hospitals and district surgical centers in Maharashtra and Karnataka present demand for cost-optimized laparoscopic towers. The Central Drugs Standard Control Organization governs import licensing and clinical trial approvals for surgical devices. Chennai and Hyderabad host contract manufacturing facilities producing access devices and energy platforms for regional distribution.
China
Tier-2 hospital expansion in Sichuan and Shandong provinces drives procurement of domestic-brand laparoscopic systems. The National Medical Products Administration regulates 510(k)-style approval pathways for innovative surgical instruments. Suzhou's medical device industrial park houses visualization system assembly operations serving Asia-Pacific markets.
Minimally Invasive Gastrointestinal Surgical System Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates controlling end-to-end surgical ecosystems. The vendor base stratifies across three tiers: integrated platform providers with proprietary instrument architectures, standalone visualization specialists capturing margin pools through image-processing chipsets, and regional fabricators competing on cost-optimized access devices. Dominant competitive moves include M&A to consolidate service revenue streams and strategic partnerships to embed energy devices within robotic console workflows.
Within the integrated platform tier, Medtronic and Intuitive Surgical exemplify contrasting approaches to recurring revenue capture. Medtronic leverages its end-to-end surgical ecosystem to sustain service revenue across visualization tower upgrade cycles. Intuitive Surgical anchors the robotic-assisted segment with proprietary instrument architectures that lock in consumables revenue. Among diversified conglomerates, Johnson & Johnson occupies a position spanning sutures, staplers, and energy platforms that interface with third-party visualization systems.
| Leading Market Players |
|---|
| Medtronic |
| Intuitive Surgical |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Stryker Corporation |
| Olympus Corporation |
| Karl Storz SE & Co. KG |
| Fujifilm Holdings Corporation |
| Cook Medical |
| Others |
Pricing and Supply Chain Analysis
Production scale at German precision-engineering clusters in Baden-Württemberg and Bavaria shapes both supply concentration and price floors for visualization systems, as capital-intensive camera tower manufacturing creates barriers that sustain premium-tier margins while compressing mid-market alternatives.
Pricing Analysis
The FDA's 510(k) premarket notification dictates the pricing tier structure across minimally invasive gastrointestinal surgical systems, with clearance pathways separating premium robotic platforms from standard laparoscopic towers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because community hospitals in India and Brazil negotiate unbundled service contracts. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with GPO contracts show least.
Supply Chain Analysis
Strait of Malacca transit underwrites component flows for image-processing chipsets sourced from Taiwan and South Korea, with final assembly concentrating in China and India for cost-optimized access devices. Supply rests on germanium substrates for fluorescence-capable sensors, precision glass for rigid endoscopes, and medical-grade polymers for trocar housings. Single-source vulnerability concentrates in specialized CMOS sensor fabrication. Distribution runs through integrated delivery networks in Texas and Florida, with regional distributors serving tier-2 hospital expansion in Maharashtra and Karnataka.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorescence-guided surgery integration represents a high-growth disruption, with the FDA's streamlined 510(k) pathway accelerating technology transfer from bench to bedside and compressing incumbent upgrade cycles.
For Market Incumbents: Shield recurring revenue streams by embedding proprietary instrument architectures within robotic console workflows, mirroring Intuitive Surgical's consumables-lock strategy. Deepen backward integration into fluorescence-capable image-processing chipsets to defend margin position against standalone visualization specialists. Prioritize certification investment for EU MDR compliance as predicate device limitations threaten legacy portfolio recertification timelines. For New Entrants and Emerging Players: Japan's PMDA Sakigake fast-track designation offers the most penetrable regulatory pathway for AI-integrated surgical navigation systems. Target cost-optimized laparoscopic towers for India's government-funded medical college hospitals and district surgical centers, where procurement prioritizes throughput over premium features. Pursue hospital system partnership as the primary go-to-market angle, leveraging utilization-based service agreements piloted by Texas and Florida IDNs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated platform providers with proprietary instrument architectures and locked consumables streams. Long-term viability favors vendors controlling end-to-end surgical ecosystems rather than standalone component specialists. Watch for reimbursement threshold recalibration by CMS and commercial payors as the inflection indicator for robotic-assisted procedure volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates clearance timelines for novel visualization systems targeting academic medical centers. |
| CE Marking Pathway | EU MDR compliance secures access to German precision-engineering clusters and hospital networks. |
| Hospital System Partnership | Texas and Florida IDNs pilot utilization-based agreements tied to console uptime metrics. |
| Software Companion Development | AI-integrated surgical navigation qualifies for Japan's PMDA Sakigake fast-track designation. |
| Reimbursement Strategy | CMS coverage policy alignment determines robotic-assisted procedure volume in community settings. |
Research Methodology
A spread of perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads converged on the working assumptions for this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and CMS reimbursement data. Bottom-up equipment shipment analysis and top-down healthcare expenditure triangulation anchored market sizing.
Segmentation dimensions modeled include product type, technology tier, end-user facility category, and application specialty across the projection horizon. CAGRs derived from installed base replacement cycle analysis, procedural volume migration patterns, and capital equipment procurement timelines. Fluorescence-guided surgery adoption curves and ASC equipment refresh cycles served as procedure-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable FDA clearance pathways and continued Medicare outpatient reimbursement shifts; material deviation in payor coverage policy would warrant model refresh. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and PMDA Sakigake qualification criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Europe General Surgical Devices Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Ultrasonic Tissue Ablation System Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Cystoscopy Needles Market
Surgical Instruments
Surgical Visualization Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
Handheld Arthroscopic Instruments Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Retractable Needles Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Laparotomy Sponges Market
Surgical Instruments
Gynecology Surgical Instruments Market