
 US Ophthalmic Handheld Surgical Instruments Market | 2026-2036
US Ophthalmic Handheld Surgical Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
US Ophthalmic Handheld Surgical Instruments Market Intelligence
Premium-grade titanium instrumentation is bifurcating the US ophthalmic handheld surgical instruments market into high-durability and value-tier supply channels. Alcon Inc. leverages its cataract surgery ecosystem to bundle instrument sets with consumable platforms. Katena Products Inc. specializes in premium forceps and scissors for retinal subspecialists. BVI anchors its position through broad catalog breadth across manual and disposable categories.
Ophthalmic handheld surgical instruments comprise manually operated, precision-engineered tools—typically manufactured from medical-grade stainless steel or titanium alloys with tungsten carbide inserts—designed for tissue manipulation, incision, and extraction during microsurgical ocular procedures. These instruments require sub-millimeter tip tolerances and ergonomic handle geometries to enable surgeon dexterity during procedures lasting one to three hours. Cataract forceps dominate procedure volume given the sheer scale of cataract surgery in the United States, while vitrectomy instruments command premium pricing due to complexity in pars plana instrumentation. Retinal scissors represent the fastest-growing product type as diabetic retinopathy and macular surgery volumes expand in ASC settings.
FDA 510(k) premarket notification requirements govern instrument safety and performance claims, while OSHA bloodborne pathogen standards mandate reprocessing protocols that influence reusable versus disposable purchasing decisions. The National Eye Institute's clinical trial priorities indirectly steer instrument innovation toward minimally invasive glaucoma surgery platforms. Stakeholders must monitor CMS reimbursement shifts for ASC-based cataract and retinal procedures, as site-of-service payment differentials reshape capital allocation between hospital and outpatient instrument procurement.
Market Dynamics
ASC volume migration is compressing hospital purchasing power while concentrating procurement decisions into multi-site ophthalmology networks across California, Florida, and Texas. This structural shift forces instrument suppliers to reconfigure pricing and service models around consolidated buyers rather than individual surgical facilities.
Growth Catalysts
- FDA 510(k) pathway efficiency:Streamlined premarket notification for reusable surgical instruments accelerates product iteration cycles. Manufacturers leverage predicate device claims to reduce regulatory burden for incremental design improvements.
- Diabetic retinopathy surge:Rising prevalence of diabetes-related ocular complications expands retinal surgery volumes. Pars plana vitrectomy procedures require specialized forceps, scissors, and membrane peelers.
- Titanium alloy adoption:Premium-grade titanium instrumentation offers superior corrosion resistance and reduced fatigue failure. ASCs prioritize instrument longevity to maximize capital utilization rates.
Market Restraints
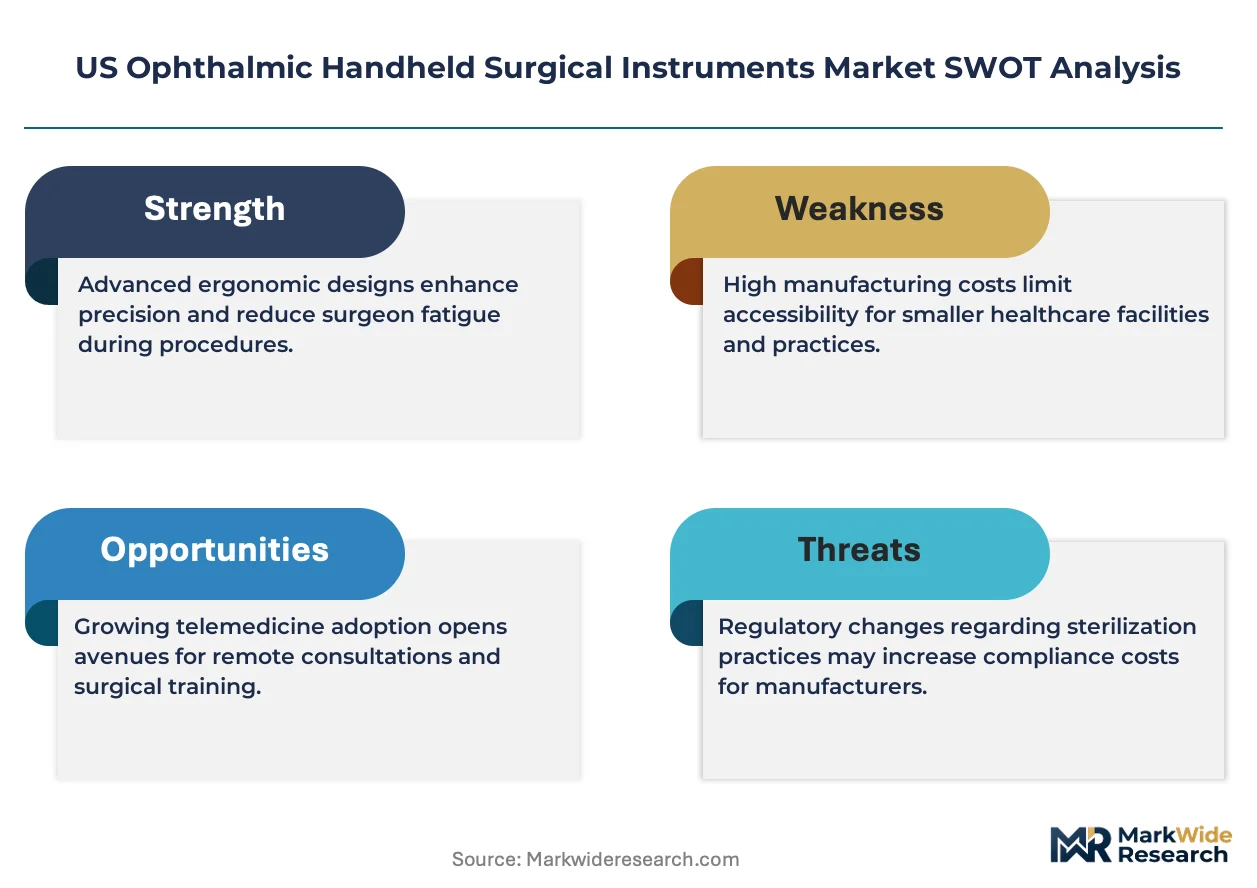
- Medical-grade titanium supply concentration:Specialty alloy mills in Pennsylvania and Ohio control domestic feedstock for surgical-grade titanium. Price volatility in sponge titanium imports from Kazakhstan and Ukraine creates input cost pressure.
- OSHA bloodborne pathogen compliance burden:Reusable instrument reprocessing mandates require validated sterilization protocols. Smaller ASCs face capital constraints for automated washer-disinfector installations.
- Single-use disposable substitution:Pre-sterilized disposable instruments eliminate reprocessing liability. Premium-priced disposables capture cases where sterilization infrastructure is inadequate.
Strategic Opportunities
- Minimally invasive glaucoma surgery expansion:MIGS procedures require micro-scale instrumentation with specialized angle access. FDA breakthrough device designation pathways incentivize innovation in this category.
- Texas and Arizona ASC buildouts:Retiree migration patterns concentrate demand in Sun Belt metropolitan areas. New facility construction creates greenfield instrument procurement opportunities.
- AI-assisted surgical planning integration:Pre-operative imaging analytics platforms guide instrument selection. Convergence of optical coherence tomography data with instrument specifications enables procedure-specific kit customization.
Industry Challenges
- Microsurgical instrument sharpening specialization:Sub-millimeter tip restoration requires artisan-level craftsmanship. Workforce aging in this trade threatens service network capacity.
- FDA quality system regulation audit intensity:21 CFR Part 820 compliance demands extensive design history file documentation. Smaller manufacturers struggle with inspection readiness costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Ophthalmic Handheld Surgical Instruments Market |
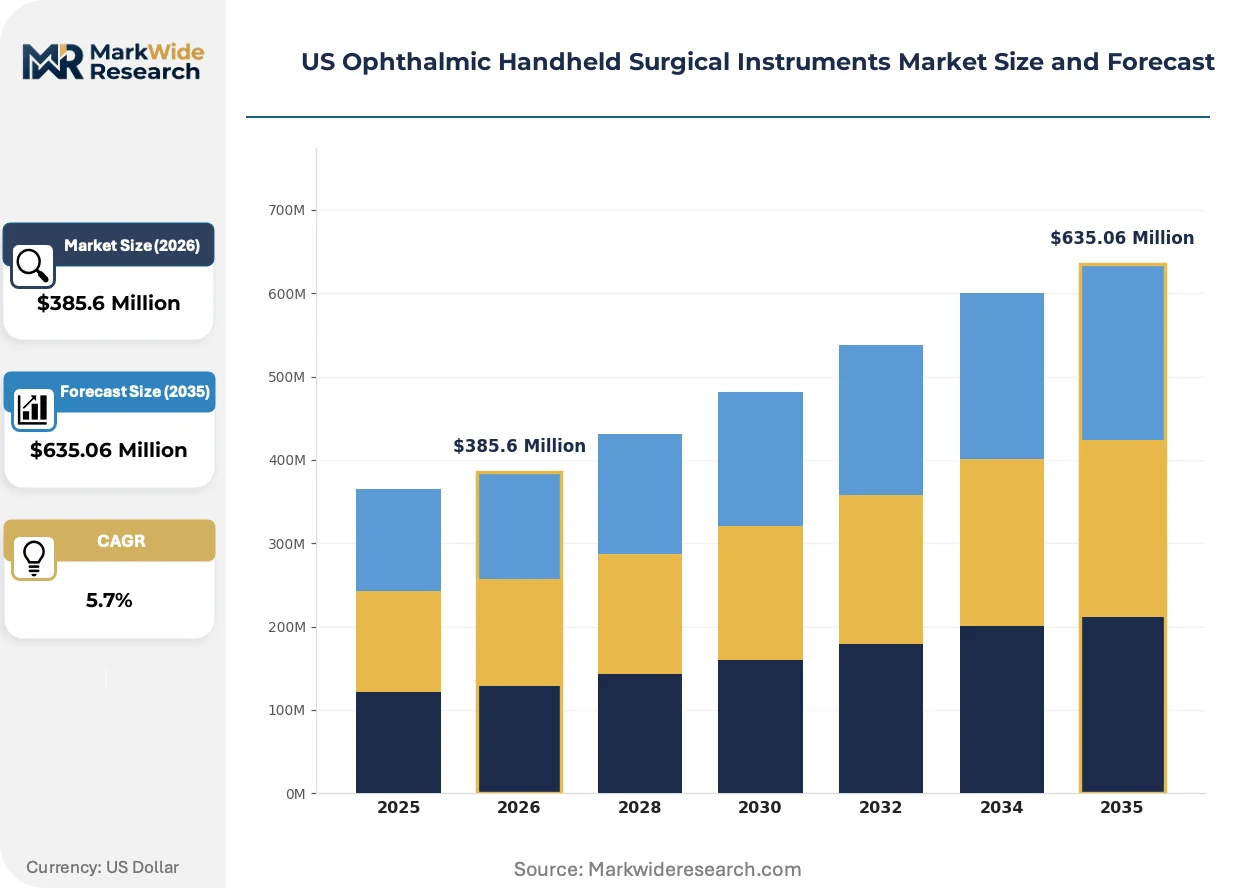
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $635.06 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cataract Forceps, Vitrectomy Instruments, Retinal Scissors, Tissues Graspers End User: Hospitals, Eye Clinics, Ambulatory Surgical Centers, Research Laboratories Technology: Electrosurgical, Laser-guided, Manual, Disposable Application: Cataract Surgery, Retinal Surgery, Glaucoma Treatment, Corneal Procedures |
| Companies Covered | BVI, Accutome Inc., Haag-Streit Group, Alcon Inc., Medline Industries Inc., Katena Products Inc., ASICO LLC, Appasamy Associates, Katalyst Surgical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Ophthalmic Handheld Surgical Instruments Market Strategic Shifts & Innovations
Digital thread integration across instrument design, manufacturing, and field service is compressing product lifecycle timelines. Suppliers now embed traceability markers and usage analytics into premium instrument lines.
Titanium-niobium alloy instrumentation is displacing conventional 400-series stainless steel in high-cycle cataract applications. Leading ASC networks in Southern California have standardized on these alloys for forceps and needle holders. The material shift enables extended reprocessing cycles while reducing surgeon hand fatigue during lengthy procedure days.
OSHA's updated bloodborne pathogens standard enforcement is tightening reprocessing documentation requirements. Inspectors now demand validated cleaning efficacy data for each instrument family. Facilities in Florida and New York have invested in automated tracking systems to demonstrate compliance during unannounced audits.
Consolidated procurement through multi-site ophthalmology platforms is compressing distributor margins. Independent ASCs in Texas increasingly join group purchasing organizations to access hospital-equivalent pricing tiers. This behavioral shift forces manufacturers to negotiate master agreements with network administrators rather than individual facility materials managers.
US Ophthalmic Handheld Surgical Instruments Market Segmentation
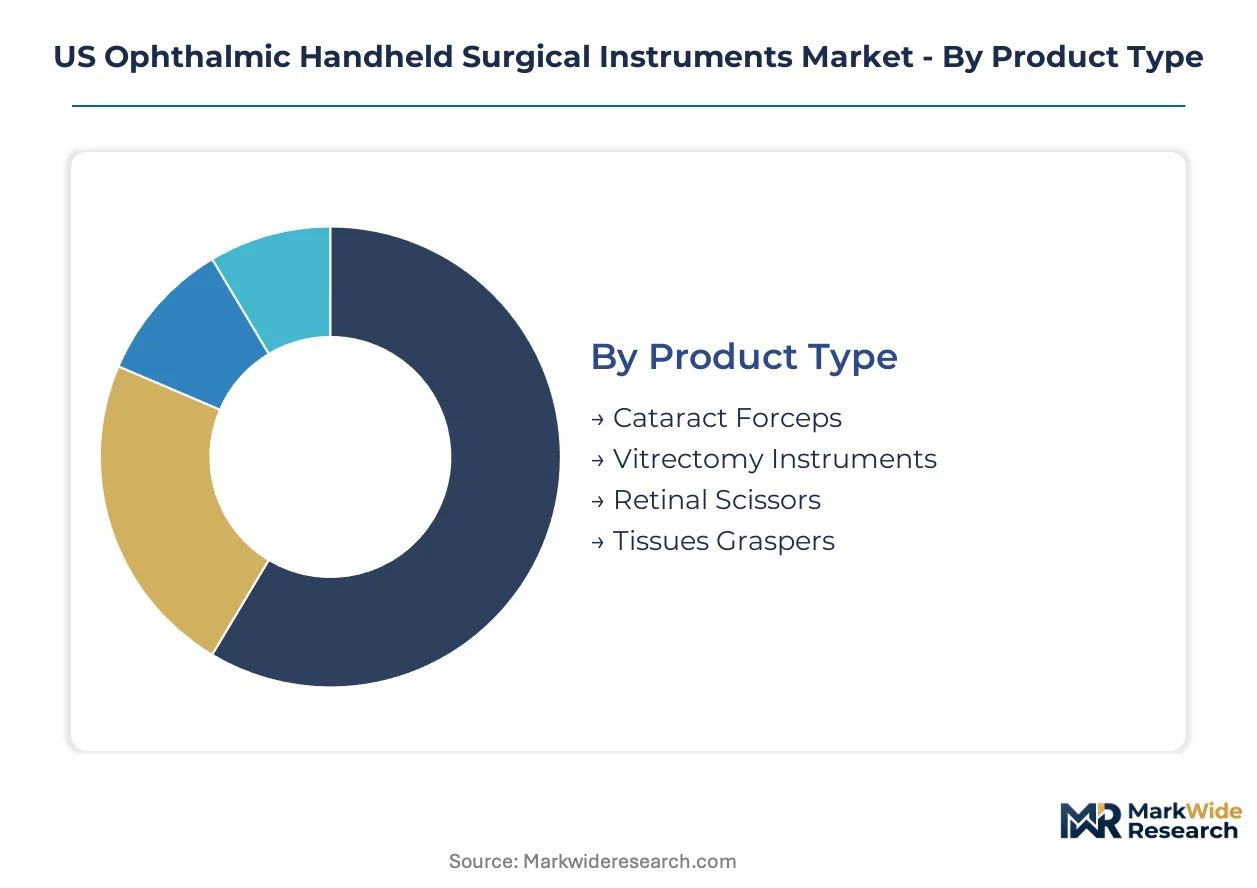
US ophthalmic handheld surgical instruments segment along four critical dimensions that determine procurement patterns, regulatory pathways, and competitive positioning. Product type differentiation reflects procedure volume concentration, while end-user segmentation tracks the ASC migration reshaping capital allocation. Technology tiers separate premium titanium platforms from disposable alternatives, and application splits align with subspecialty reimbursement dynamics.
Product Type:
Substitution pressure from single-use disposables concentrates most intensely on high-volume cataract instruments, where reprocessing economics face the stiffest challenge from pre-sterilized alternatives.
- Cataract Forceps:Manufactured from medical-grade stainless steel or titanium alloys with tungsten carbide jaw inserts, these instruments require sub-millimeter tip alignment for nucleus manipulation. California and Florida ASC networks standardize on premium-grade titanium variants to maximize reprocessing cycles amid high procedure throughput.
- Retinal Scissors:Micro-engineered with curved or angled blade geometries for membrane dissection in pars plana vitrectomy, these command the highest unit economics in the portfolio. Demand concentrates in Texas and Arizona metropolitan clusters where diabetic retinopathy surgical volumes are climbing fastest.
- Vitrectomy Instruments:Specialized forceps, picks, and membrane peelers designed for trans-pars plana access. These instruments face limited disposable substitution due to precision requirements.
- Tissue Graspers:General-purpose manipulation tools with atraumatic tip designs for conjunctival and extraocular tissue handling. Standardization across procedure types limits premium pricing power.
Cataract forceps retain volume leadership; retinal scissors hold the steepest expansion curve.
End User:
Procurement authority is consolidating into multi-site network administrators, compressing distributor margins and forcing manufacturers toward master service agreements.
- Ambulatory Surgical Centers:Freestanding outpatient facilities now drive the majority of US cataract and retinal procedure volume. California-based networks leverage scale to negotiate titanium instrument standardization across dozens of sites.
- Hospitals:Academic medical centers and community hospitals retain complex case referrals and training program procurement. These facilities maintain broader instrument catalogs to support resident education and multi-subspecialty coverage.
- Eye Clinics:Office-based settings concentrate on diagnostic and minor procedural instrumentation. Capital constraints limit penetration of premium titanium platforms in this channel.
- Research Laboratories:Institutional and commercial R&D facilities procure specialized instruments for preclinical testing and device development. NIH-funded centers in Maryland and Massachusetts anchor demand.
Ambulatory surgical centers now capture the majority procurement volume; eye clinics present the most price-sensitive demand profile.
Technology:
Margin structures diverge sharply between capital-intensive reusable platforms and consumable-disposable alternatives, with reimbursement site-of-service differentials determining optimal technology deployment.
- Manual:Traditional hand-actuated instruments requiring surgeon tactile feedback and dexterity. Florida ASCs favor manual titanium platforms for cost amortization across high procedure volumes.
- Disposable:Pre-sterilized single-use instruments eliminating reprocessing infrastructure requirements. These gain traction in smaller Texas facilities lacking automated washer-disinfector capital.
- Electrosurgical:Energy-integrated instruments for cauterization and tissue ablation during ocular surface and glaucoma procedures. Limited penetration due to ophthalmic microsurgical precision requirements.
- Laser-guided:Instrumentation with integrated aiming beams or femtosecond coupling for corneal and capsular applications. Premium positioning restricts adoption to academic and high-volume referral centers.
Manual instrumentation dominates installed base; disposable platforms are expanding most quickly in undercapitalized settings.
Application:
Reimbursement rate compression in cataract surgery is redirecting manufacturer R&D investment toward higher-margin subspecialty applications with less pricing pressure.
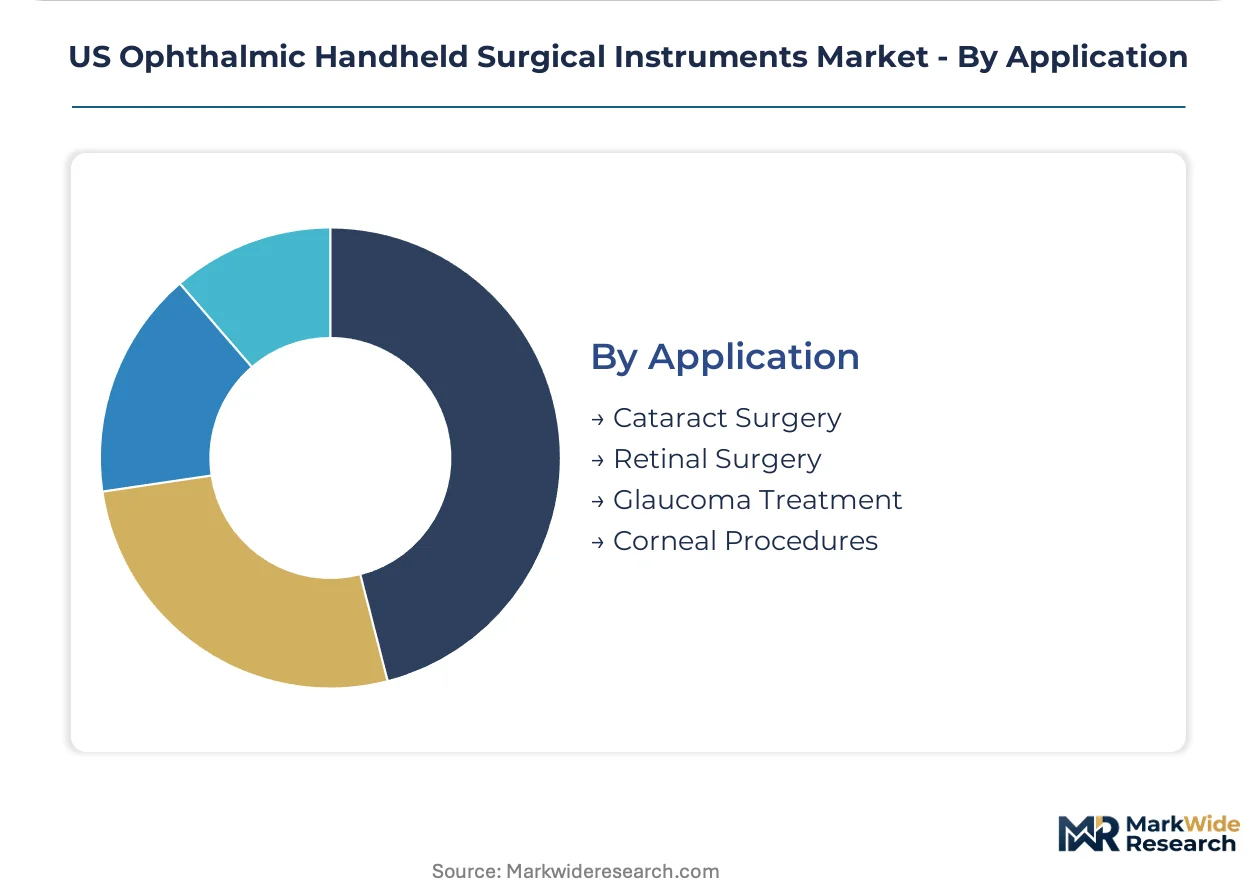
- Cataract Surgery:Phacoemulsification and manual small-incision procedures requiring nucleus fragmentation, cortical cleanup, and IOL insertion tools. Volume concentration in California and Florida drives instrument standardization.
- Retinal Surgery:Pars plana vitrectomy, membrane peeling, and retinal detachment repair demanding specialized micro-instrumentation. Diabetic retinopathy prevalence expansion is accelerating procedural growth in Sun Belt markets.
- Glaucoma Treatment:Trabeculectomy, tube shunt placement, and minimally invasive angle procedures. FDA breakthrough device pathways are stimulating instrument innovation in this category.
- Corneal Procedures:Transplantation, lamellar dissection, and refractive surface ablation requiring specialized trephines and dissectors. Lower procedure volume limits dedicated instrument development.
Cataract surgery anchors absolute demand; retinal surgery commands the highest instrument revenue per procedure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty alloy mills in Pennsylvania and Ohio control domestic feedstock for surgical-grade titanium, concentrating instrument manufacturing capacity in the Great Lakes industrial corridor. California and Florida ASC networks drive procurement volume through multi-site standardization. Texas and Arizona metropolitan clusters represent the fastest-expanding demand geography.
California
Retiree population concentration and large integrated eye surgery networks generate the highest ASC procedure density nationally. Kaiser Permanente and VSP Vision Care networks standardize titanium instrument procurement across dozens of Southern California sites. Los Angeles and San Diego metropolitan clusters anchor premium-grade forceps and scissor demand.
Florida
Snowbird migration patterns and Medicare Advantage penetration concentrate cataract volume in Tampa, Orlando, and Miami-Dade corridors. OSHA bloodborne pathogen audit intensity has driven automated tracking system adoption across ASC networks. Jacksonville and Fort Lauderdale surgical clusters prioritize instrument longevity to maximize capital utilization.
Texas
Dallas-Fort Worth and Houston metropolitan buildouts represent the fastest-growing greenfield ASC construction nationally. Independent facilities increasingly join group purchasing organizations to access hospital-equivalent pricing tiers. Austin and San Antonio retina specialist clusters drive retinal scissors procurement for diabetic retinopathy cases.
Arizona
Phoenix and Tucson retiree migration sustains high-volume cataract surgery demand. Smaller ASCs face capital constraints for automated washer-disinfector installations, creating substitution pressure toward disposable instruments. Scottsdale surgical corridors attract retinal subspecialists serving snowbird populations.
Ohio
Cleveland and Cincinnati academic medical centers retain complex case referrals and resident training program procurement. Specialty titanium alloy mills in the Youngstown-Warren corridor supply domestic feedstock to instrument manufacturers. Columbus ASC networks standardize on premium-grade platforms for cost amortization.
US Ophthalmic Handheld Surgical Instruments Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the US ophthalmic handheld surgical instruments market. Premium-grade titanium specialists command pricing power through material science differentiation, while broad-catalog suppliers compete on procurement efficiency and service breadth. Three archetypes dominate: integrated ophthalmic platform vendors, dedicated surgical instrument specialists, and diversified medical device conglomerates. Competitive moves concentrate on ASC network master agreements and titanium alloy supply security.
Within the integrated platform tier, Alcon Inc. leverages its cataract surgery ecosystem to bundle instrument sets with consumable platforms. Katena Products Inc. and BVI occupy distinct positions—Katena exemplifies the premium forceps and scissors specialist serving retinal subspecialists, while BVI anchors the broad-catalog breadth strategy spanning manual and disposable categories. These three represent the dominant competitive anchors shaping procurement negotiations with multi-site ophthalmology networks.
| Leading Market Players |
|---|
| BVI |
| Accutome Inc. |
| Haag-Streit Group |
| Alcon Inc. |
| Medline Industries Inc. |
| Katena Products Inc. |
| ASICO LLC |
| Appasamy Associates |
| Katalyst Surgical |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between specialty alloy mills and instrument manufacturers lock in titanium feedstock access while stabilizing input cost visibility for ASC procurement planning. These contract structures concentrate pricing power with Pennsylvania and Ohio-based suppliers who control domestic surgical-grade titanium sponge conversion.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across premium titanium, standard stainless steel, and economy-grade instrument lines. Certification grade and volume scale separate pricing bands, with multi-site ASC networks extracting steepest discounts through master service agreements. Pricing pressure intensifies as single-use disposable alternatives capture cases from undercapitalized facilities. Eye clinics exhibit highest price sensitivity; academic medical centers show least.
Supply Chain Analysis
Kazakhstan and Ukraine anchor sponge titanium exports feeding domestic alloy production in Pennsylvania and Ohio. Surgical-grade titanium billets, tungsten carbide inserts, and precision grinding equipment constitute critical input dependencies. Single-source vulnerability concentrates in specialty alloy mill capacity for medical-grade titanium. Distribution runs through GPOs and direct manufacturer agreements with multi-site ophthalmology networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern tied to ASC construction cycles and retiree migration demographics, with instrument replacement demand accelerating as facility buildouts mature.
For Market Incumbents: Secure titanium alloy supply through backward integration or captive offtake agreements with Youngstown-Warren corridor mills. Expand sharpening service networks to address artisan workforce aging. Defend against disposable substitution by embedding usage analytics and traceability into premium instrument lines.
For New Entrants and Emerging Players: Lead with AI-assisted surgical planning integration as a differentiated entry wedge. Target Arizona and Texas ASC greenfield construction where procurement decisions remain uncommitted. Pursue group purchasing organization membership to bypass incumbent distributor relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward premium titanium specialists with established FDA 510(k) predicate libraries and ASC network contracts. Long-term viability hinges on material science differentiation and reprocessing service infrastructure. Monitor CMS reimbursement shifts for ASC-based retinal procedures as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Expansion | Accelerates product iteration cycles by leveraging established device claims for incremental improvements. |
| Titanium-Niobium Alloy Standardization | Enables extended reprocessing cycles while reducing surgeon fatigue during high-volume procedure days. |
| ASC Network Master Agreements | Concentrates procurement authority into multi-site administrators, compressing distributor margins. |
| Automated Reprocessing Tracking Systems | Demonstrates OSHA bloodborne pathogen compliance during unannounced facility audits. |
| MIGS Instrument Innovation Pipeline | Captures FDA breakthrough device designation incentives for minimally invasive glaucoma surgery platforms. |
Research Approach
The analysis maps cataract forceps, retinal scissors, vitrectomy instruments, and tissue graspers, each validated through ASC materials managers, ophthalmic surgeons, GPO contract administrators, and biomedical engineering directors. Primary interview findings triangulate against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and specialty alloy trade data. Bottom-up facility-level instrumentation estimates reconcile with top-down manufacturer revenue segmentation.
Consistency checks validate volume and value outputs against ASC procedure registries and multi-site network capital expenditure disclosures. Segmentation models incorporate product type, end-user channel, technology tier, and application subspecialty across the projection horizon. CAGRs derive from instrument replacement cycles, facility expansion pipelines, and procedure volume elasticity to demographic shifts. Forecast inputs include diabetic retinopathy prevalence trajectories and titanium sponge import volatility.
The analysis sits within stated boundaries; outcomes outside current FDA regulatory pathways, OSHA enforcement intensity, or CMS reimbursement stability would require recalibration. Forecasts reflect documented assumptions regarding ASC migration pace and alloy supply continuity. Recalibration cycles align with material shifts in Medicare site-of-service payment differentials and specialty alloy mill capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Medical Tuning Fork Market
Surgical Instruments
South Korea General Surgical Devices Market
Surgical Instruments
Handheld Arthroscopic Instruments Market
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Surgical Tubing Market
Surgical Instruments
Surgical Stents Market
Surgical Instruments
Surgical Visualization Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Global Surgical Case Carts Market
Surgical Instruments
Lumpectomy Market
Surgical Instruments
Global Surgical Scalpel Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Surgical Blades Market