
 Argentina General Surgical Devices Market | 2026-2036
Argentina General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina General Surgical Devices Market Outlook
Multi-source procurement is decoupling from historical single-source dependencies across Argentina's public hospital networks. B. Braun leverages its sterilization infrastructure to anchor service contracts in provincial health systems. Medtronic competes through localized distribution partnerships that bypass import bottlenecks. Johnson & Johnson sustains brand preference among private surgical centers in Córdoba and Rosario corridors.
General surgical devices encompass manually operated instruments—typically stainless steel or titanium alloy constructions with Rockwell hardness ratings exceeding 45 HRC—designed for tissue manipulation, dissection, and hemostasis during operative procedures. Scalpels and forceps dominate volume throughput in Argentine public procurement, while titanium instruments command premium positioning in private cardiovascular and neurosurgery suites. Stainless steel retains cost-driven preference across general surgery applications, though carbon fiber composites gain traction in research labs seeking radiolucent instrument sets.
ANMAT enforces medical device registration under Resolution 2319-2002, mandating local quality system audits for Class III surgical instruments that delays foreign entry by twelve to eighteen months. BIS-equivalent material certifications and INMETRO traceability requirements for imported titanium feedstock compound compliance burdens. Stakeholders must monitor pending Mercosur harmonization protocols that could unify technical documentation standards across Argentine, Brazilian, and Uruguayan markets.
Market Dynamics
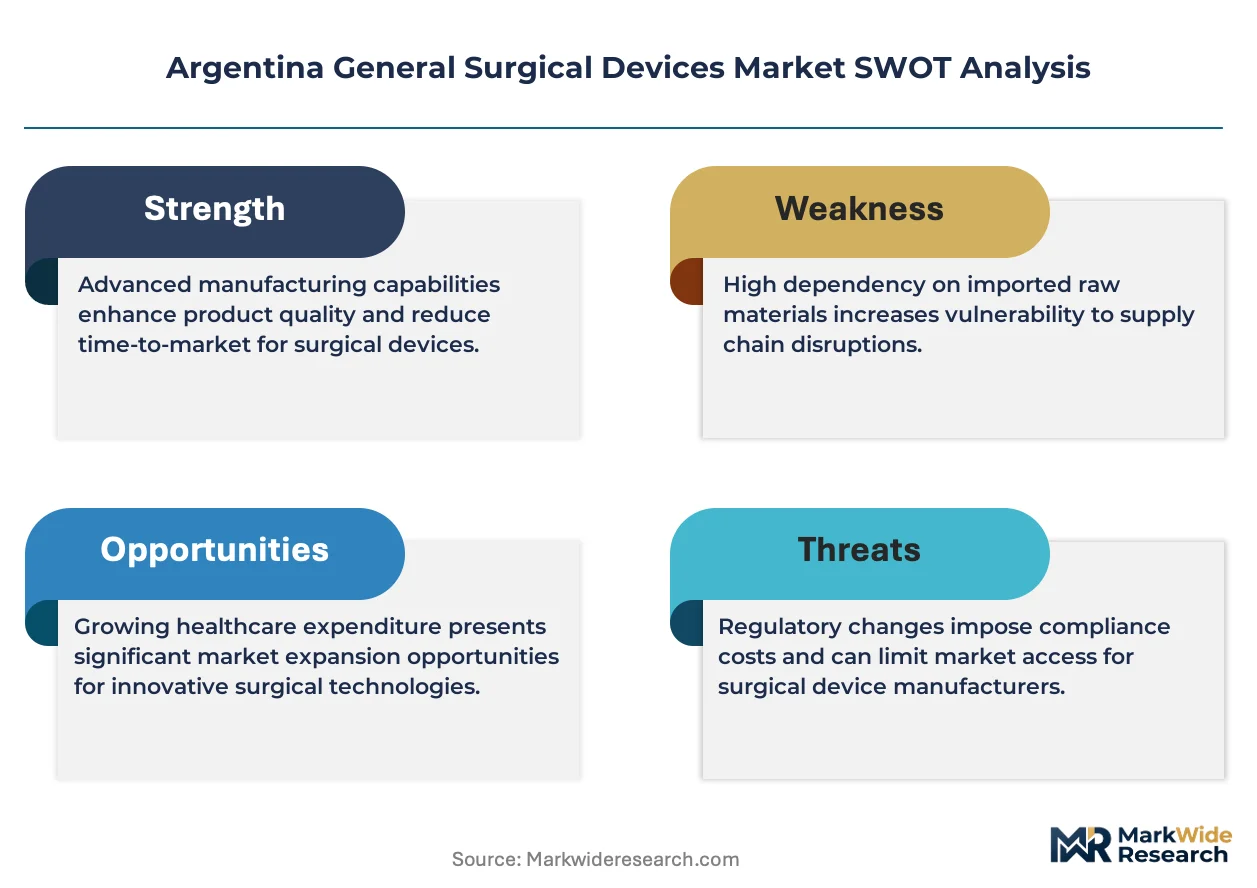
ANMAT's Resolution 2319-2002 registration pathway is compressing foreign entry timelines and forcing import substitution strategies across Argentina's provincial health systems. This regulatory friction is reshaping supply relationships between Buenos Aires public hospitals and domestic sterilization infrastructure operators.
Growth Catalysts
- Aging Demographics:Argentina's expanding elderly population is elevating trauma and orthopedic caseloads across public surgical wards. Buenos Aires Province hospitals report sustained volume pressure in joint replacement queues.
- Resolution 2319-2002 Localization Incentives:ANMAT's mandatory local quality audits for Class III instruments are accelerating domestic production partnerships. Foreign manufacturers are establishing captive sterilization facilities to bypass eighteen-month entry delays.
- Titanium Alloy Adoption:Cardiovascular and neurosurgery suites in Córdoba and Rosario corridors are specifying Rockwell 45+ HRC titanium instruments. Premium positioning in private centers is displacing stainless steel in complex procedures.
Market Restraints
- Import Feedstock Concentration:INMETRO traceability requirements for titanium billet create dependency on Brazilian and Asian suppliers. Argentine manufacturers face twelve-week certification lag for each raw material batch.
- ANMAT Registration Bottleneck:Class III surgical instrument approvals require redundant documentation across Mercosur member states. Resolution 2319-2002 lacks mutual recognition with Brazilian ANVISA pathways.
- Disposable Cost Premium:Single-use instrument sets cost three to four times reusable equivalents. Public hospital procurement budgets in Mendoza and Santa Fe provinces cannot absorb per-procedure pricing differentials.
Strategic Opportunities
- Mercosur Harmonization:Pending technical documentation unification across Argentine, Brazilian, and Uruguayan regulators would eliminate redundant certification costs. ANMAT-ANVISA alignment represents the most significant regulatory tailwind.
- Carbon Fiber Composite Instrument Sets:Research hospitals in La Plata and Mar del Plata are piloting radiolucent instruments for intraoperative imaging. Orthopedic trauma applications are emerging as the first commercial beachhead.
- Provincial Service Contracting:B. Braun's sterilization infrastructure model is replicable across Tucumán and Salta health systems. Equipment-leasing arrangements bypass upfront capital constraints in underfunded regions.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Argentine universities produce insufficient ANMAT-qualified regulatory affairs specialists. Device manufacturers compete with pharmaceutical firms for quality system auditors.
- Legacy Instrument Integration:Public hospitals maintain mixed inventories of stainless steel and titanium sets. Surgical staff face training friction when rotating between incompatible instrument standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina General Surgical Devices Market |
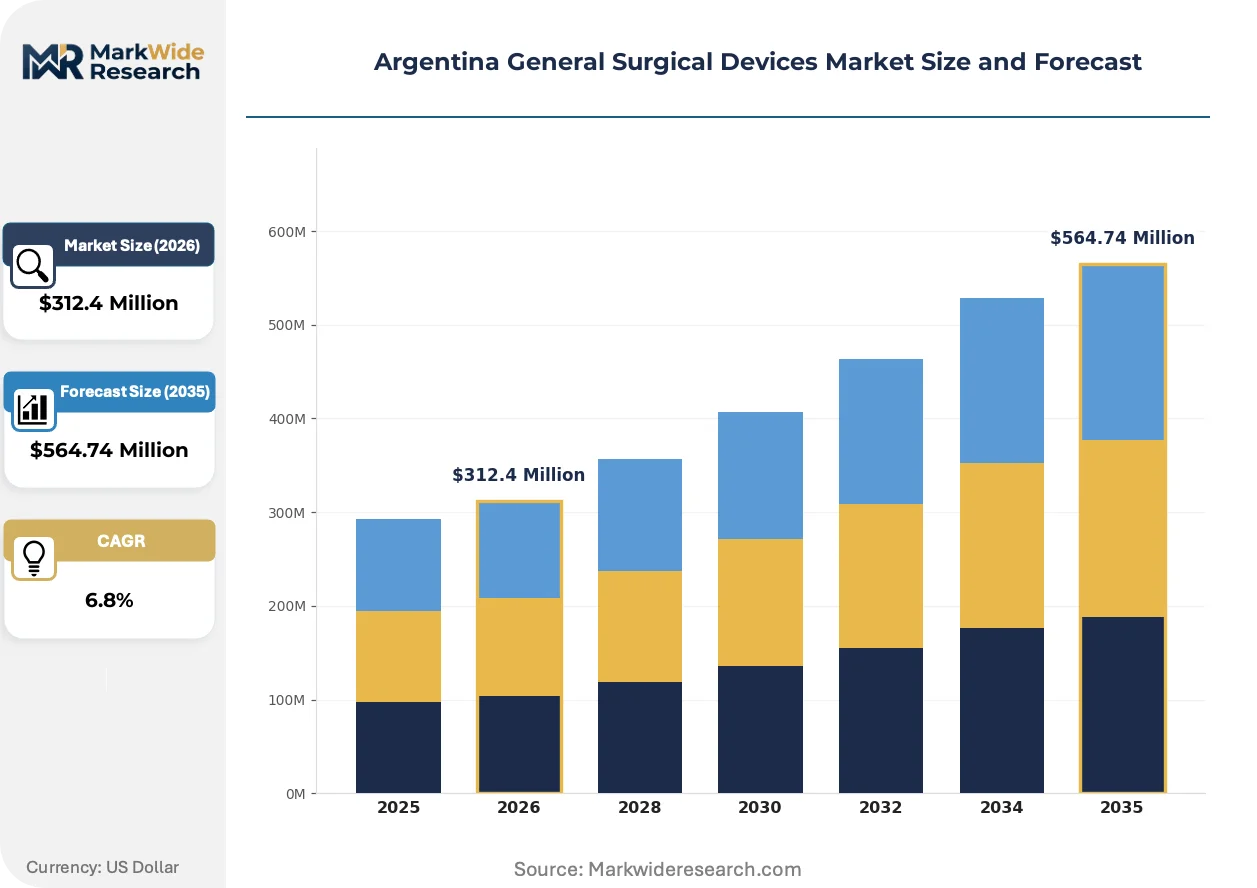
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scalpels, Forceps, Scissors, Hemostats End User: Hospitals, Surgical Centers, Clinics, Research Labs Material: Stainless Steel, Plastic, Titanium, Carbon Fiber Application: General Surgery, Orthopedic Surgery, Cardiovascular Surgery, Neurosurgery |
| Companies Covered | B. Braun, Olympus Corporation, Johnson & Johnson, Karl Storz, Conmed Corporation, Medtronic, Boston Scientific Corporation, Getinge, Stryker, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina General Surgical Devices Market Strategic Shifts
Disposable instrument technology is compressing sterilization infrastructure requirements while regulatory harmonization discussions are redrawing cross-border supply relationships. These forces are converging to reshape procurement patterns across Argentina's fragmented hospital network.
Titanium-nitride coated scalpels are rewriting performance expectations in Argentine cardiovascular suites. The coating reduces tissue adhesion during dissection, enabling faster closure times. Private surgical centers in Rosario are specifying these instruments in bundled procedure contracts, compressing reimbursement cycles for high-volume operators.
ANMAT's pending alignment with Brazilian ANVISA technical documentation standards is forcing manufacturers to restructure quality management systems. The industrial consequence is accelerated consolidation of Mercosur regulatory affairs functions in São Paulo. Argentine device importers are responding by hiring dual-qualified compliance officers capable of navigating both pathways simultaneously.
Multi-source procurement is displacing historical single-source dependencies across Buenos Aires Province public hospitals. Provincial purchasing cooperatives are aggregating demand to extract volume discounts from sterilization service providers. This behavioral shift is most visible in general surgery instrument categories where standardization across hospital networks reduces supplier switching costs.
Argentina General Surgical Devices Market Segmentation
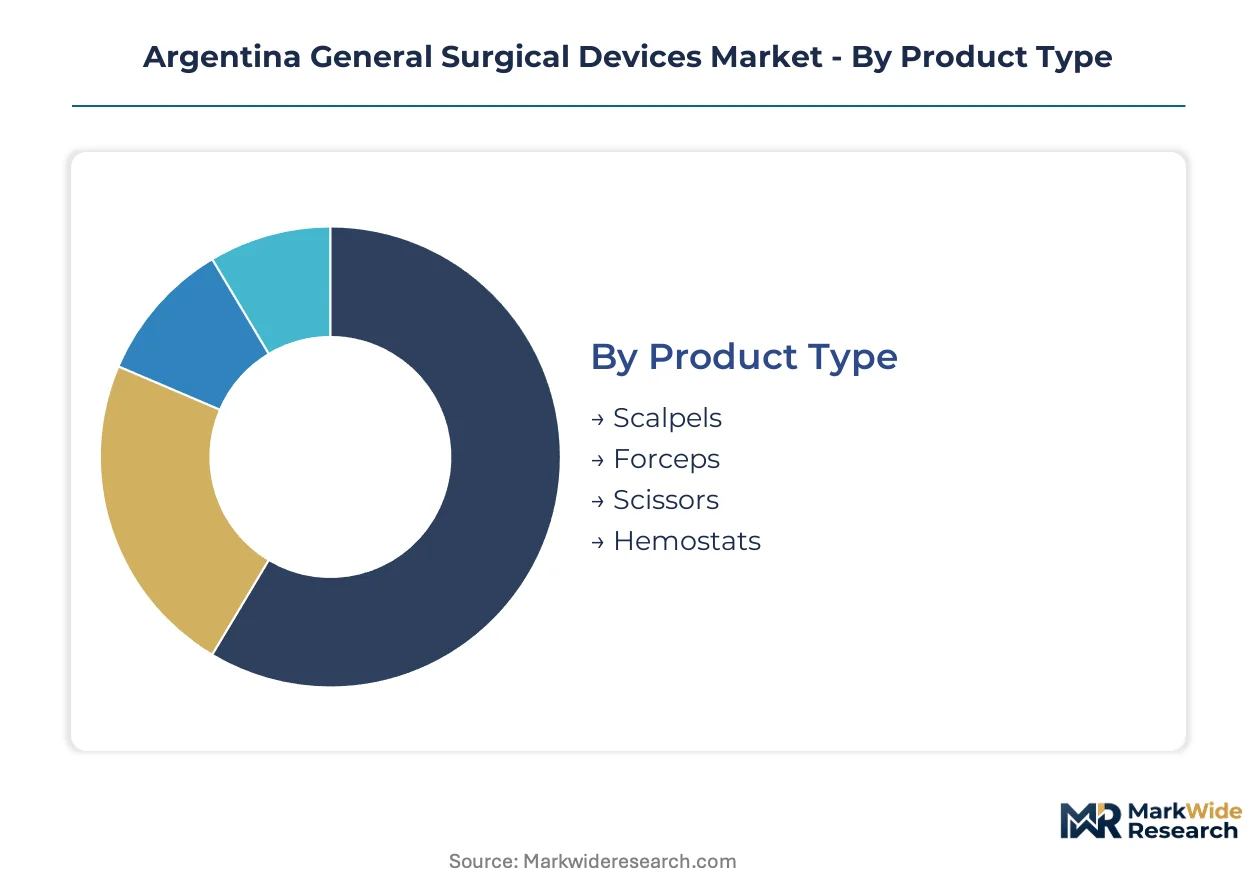
Segmentation in Argentina's surgical device market reveals how regulatory pressure and procurement economics fragment demand across material grades and institutional tiers. ANMAT registration timelines and provincial budget constraints create divergent purchasing patterns that reward localized supply strategies.
Product Type:
Instrument design specifications determine sterilization protocols and replacement cycles across Argentine hospital networks.
- Scalpels:Disposable variants with stainless steel or carbon steel blades dominate high-volume general surgery wards in Buenos Aires Province public hospitals. Procurement cooperatives aggregate demand for safety-engineered designs that reduce sharps injuries and liability exposure.
- Forceps:Titanium and stainless steel constructions with serrated jaw patterns serve tissue grasping across orthopedic and cardiovascular applications. Córdoba private surgical centers specify non-stick coated variants for electrosurgery compatibility.
- Scissors:Curved and straight blade configurations address dissection requirements in general surgery suites. Mendoza provincial hospitals prioritize reusable designs with standardized handle patterns to reduce training friction.
- Hemostats:Ratchet-locking instruments with carbide inserts control bleeding in trauma procedures. Santa Fe public procurement favors multi-pack disposable sets for emergency department throughput.
Mature deployment sits with forceps across Argentina's established surgical wards. Newer deployment is concentrated in disposable scalpel variants as sterilization infrastructure constraints intensify.
End User:
Institutional scale and reimbursement structure shape instrument specification intensity and brand loyalty patterns.
- Hospitals:Public institutions in Buenos Aires, Córdoba, and Santa Fe provinces drive volume demand for standard-grade stainless steel sets. ANMAT registration requirements favor established suppliers with captive sterilization infrastructure.
- Surgical Centers:Private ambulatory facilities in Rosario and La Plata corridors specify premium titanium instruments for orthopedic and ophthalmic procedures. Bundled payment models reward faster turnover instrument sets.
- Clinics:Smaller general surgery practices in Tucumán and Salta prioritize cost-optimized reusable instruments with extended warranty coverage. Limited capital budgets constrain disposable adoption.
- Research Labs:University-affiliated facilities in Mar del Plata pilot carbon fiber composite instruments for intraoperative imaging compatibility. Grant-funded procurement tolerates premium pricing for novel materials.
Volume concentration rests with public hospitals. Margin expansion is climbing fastest in private surgical centers.
Material:
Substrate selection balances mechanical performance against regulatory traceability burdens and import feedstock dependencies.
- Stainless Steel:AISI 420 and 440 grade alloys with Rockwell hardness exceeding 45 HRC serve cost-driven general surgery applications. Argentine manufacturers source billet from Brazilian suppliers under INMETRO traceability protocols.
- Plastic:Single-use instrument handles and retractors reduce sterilization infrastructure requirements in underfunded provincial hospitals. Polypropylene and polycarbonate formulations dominate disposable scalpel assemblies.
- Titanium:Grade 5 Ti-6Al-4V alloy instruments command premium positioning in cardiovascular and neurosurgery suites. Private centers in Córdoba specify these for reduced tissue adhesion and magnetic resonance compatibility.
- Carbon Fiber:Radiolucent composites enable intraoperative fluoroscopy without instrument shadowing. Research hospitals in La Plata evaluate these for orthopedic trauma applications requiring real-time imaging guidance.
Established penetration belongs to stainless steel across Argentina's public procurement networks. Carbon fiber composites are gaining share fastest in research and academic medical centers.
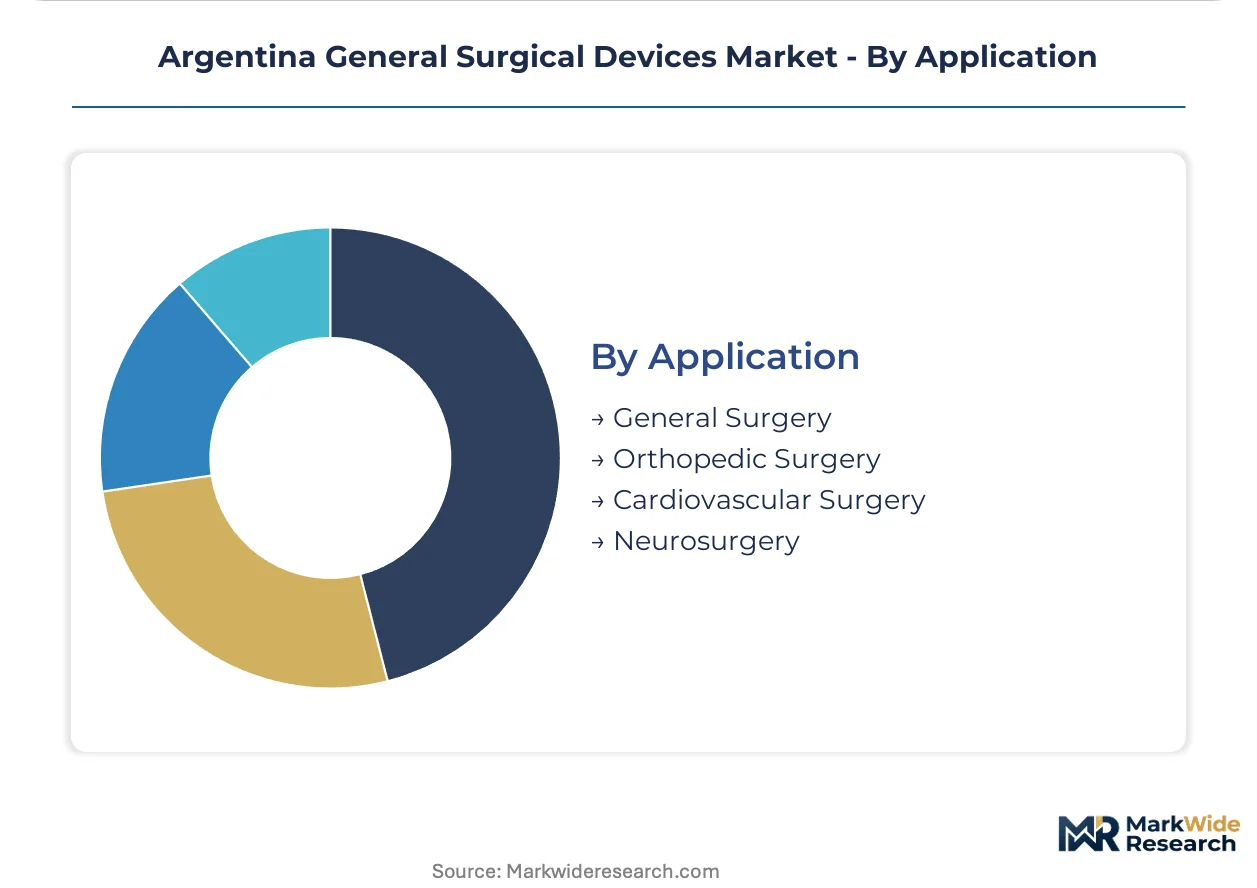
Application:
Procedure complexity and reimbursement intensity determine instrument specification grade and supplier relationship depth.
- General Surgery:Appendectomy, cholecystectomy, and hernia repair procedures consume high volumes of standard-grade scalpels, forceps, and hemostats. Buenos Aires Province public hospitals report sustained demand pressure from aging demographics.
- Orthopedic Surgery:Joint replacement and trauma fixation procedures require robust instrument sets with power tool compatibility. Titanium and stainless steel constructs face competing specifications across public and private procurement channels.
- Cardiovascular Surgery:Sternotomy and bypass procedures demand precision-engineered instruments with non-stick surface treatments. Rosario private centers specify titanium-nitride coated designs for reduced tissue adhesion.
- Neurosurgery:Microsurgical instruments with bayonet handles and diamond dusted tips serve cranial and spinal procedures. Limited case volumes concentrate demand in specialized tertiary centers.
Procedure volume concentrates in general surgery. Specification intensity is climbing fastest in cardiovascular applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian titanium billet suppliers under INMETRO traceability protocols anchor Argentina's surgical device feedstock chain. Provincial sterilization infrastructure concentrates in Buenos Aires, Córdoba, and Santa Fe corridors.
Buenos Aires Province
Public hospital networks drive disposable instrument procurement through aggregated purchasing cooperatives. ANMAT Resolution 2319-2002 mandates local quality audits that delay foreign entry timelines. La Plata and Mar del Plata research hospitals pilot carbon fiber composite instruments for intraoperative imaging.
Córdoba
Private surgical centers specify premium titanium instruments for orthopedic and cardiovascular procedures. Bundled payment models reward faster turnover instrument sets in ambulatory facilities. The Córdoba-Rosario corridor sustains brand preference among high-volume operators.
Santa Fe
Public procurement favors multi-pack disposable hemostat sets for emergency department throughput. Provincial budget constraints limit adoption of reusable titanium equivalents. Rosario private centers specify titanium-nitride coated scalpels for reduced tissue adhesion.
Mendoza
Cost-optimized reusable instruments dominate general surgery wards with extended warranty coverage. Disposable cost premiums three to four times above reusable equivalents constrain per-procedure budgets. Provincial health systems prioritize standardized handle patterns to reduce surgical staff training friction.
Tucumán and Salta
Underfunded regional health systems face capital constraints that favor equipment-leasing arrangements over upfront purchases. Service contracting models bypass sterilization infrastructure gaps in peripheral provinces. B. Braun's sterilization infrastructure model is replicable across these northern corridors.
Argentina General Surgical Devices Market Competitive Environment
Global majors compete with regional champions across distribution infrastructure and regulatory compliance capabilities. The vendor base clusters around three tiers: multinational conglomerates with captive sterilization facilities, mid-scale regional distributors with ANMAT-qualified quality systems, and domestic assemblers serving cost-driven provincial procurement. Three archetypes dominate: infrastructure-anchored service contractors, regulatory-fast-track importers with localized partnerships, and research-focused material innovators. Consolidation pressure is accelerating through sterilization facility acquisitions and dual-qualified regulatory affairs hiring.
Among infrastructure-anchored service contractors, B. Braun exemplifies the sterilization-leasing model penetrating provincial health systems. Medtronic occupies a position among regulatory-fast-track importers establishing localized distribution partnerships. Johnson & Johnson represents brand-preference sustainment in private surgical corridors. These three anchors illustrate divergent responses to ANMAT registration bottlenecks and import substitution pressures.
| Leading Market Players |
|---|
| B. Braun |
| Olympus Corporation |
| Johnson & Johnson |
| Karl Storz |
| Conmed Corporation |
| Medtronic |
| Boston Scientific Corporation |
| Getinge |
| Stryker |
| Others |
Value Chain & Pricing Dynamics
INMETRO-certified titanium billet pricing from Brazilian suppliers cascades through Argentine surgical device manufacturing into three distinct procurement tiers: premium titanium sets for private cardiovascular suites, standard stainless steel for public general surgery wards, and economy disposable plastics for underfunded provincial emergency departments.
Pricing Analysis
Warranty and sterilization-service bundling separates premium supplier contracts from unbundled transactional procurement in Argentina's public hospital networks. Three-tier pricing structure across premium, standard, and economy levels reflects ANMAT registration status, with Class III certified instruments commanding substantial premiums over uncertified imports. Cost compression in the economy tier is intensifying because provincial purchasing cooperatives aggregate volume to extract discounts from disposable instrument suppliers. Public hospitals in Mendoza and Santa Fe exhibit the highest price sensitivity, while private surgical centers in Córdoba and Rosario prioritize performance specifications over unit cost.
Supply Chain Analysis
Freight costs from São Paulo sterilization facilities to Buenos Aires distribution hubs add meaningful landed cost premiums for foreign manufacturers lacking Argentine captive infrastructure. Brazilian and Chinese suppliers anchor titanium and stainless steel feedstock chains, with Argentine manufacturers drawing from INMETRO-traceable billet and AISI-certified alloy shipments. Single-source vulnerability concentrates in Brazilian titanium feedstock, where certification lags create twelve-week procurement gaps. Distribution runs through provincial purchasing cooperatives in Buenos Aires, Córdoba, and Santa Fe, with direct-to-hospital contracts reserved for premium private surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's surgical device sector sits in a material-transition phase, with carbon fiber composite instruments displacing legacy stainless steel in research hospitals seeking intraoperative imaging compatibility.
For Market Incumbents: Extend sterilization infrastructure coverage into Tucumán and Salta through equipment-leasing arrangements that bypass provincial capital constraints. Deepen backward integration into Brazilian titanium feedstock sourcing to compress INMETRO certification timelines. ANMAT's pending Mercosur harmonization with ANVISA represents both threat and lever—dual-qualified quality systems will separate survivors from displaced single-pathway operators.
For New Entrants and Emerging Players: Launch via disposable instrument distribution partnerships with Buenos Aires Province purchasing cooperatives, where aggregated demand creates volume footholds without sterilization capital requirements. Carbon fiber composite research contracts at La Plata and Mar del Plata universities offer the most penetrable white space, with grant-funded procurement tolerating premium pricing for novel materials. Target provincial service contracting models that replicate B. Braun's infrastructure-anchored approach in northern corridors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale regional distributors with ANMAT-qualified quality systems and established provincial hospital relationships in Argentina's northern provinces. Long-term viability hinges on Mercosur regulatory consolidation, with dual ANMAT-ANVISA compliance capability as the critical five-to-ten year differentiator. Monitor ANMAT-ANVISA technical documentation alignment announcements as the decisive inflection signal for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| ANMAT-ANVISA Dual Certification | Eliminates redundant documentation costs across Argentine-Brazilian supply corridors. |
| Provincial Sterilization Infrastructure Leasing | Bypasses upfront capital constraints in Tucumán and Salta health systems. |
| Carbon Fiber Composite R&D Partnerships | Secures grant-funded beachheads at La Plata and Mar del Plata research hospitals. |
| INMETRO Traceability Integration | Compresses Brazilian titanium billet certification lags from twelve weeks. |
| Purchasing Cooperative Volume Contracts | Aggregates Buenos Aires Province demand to extract supplier switching discounts. |
Study Parameters
Document review covered ANMAT registration filings, provincial hospital procurement databases, and INMETRO certification records, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at device manufacturers. Secondary validation drew from Mercosur technical documentation standards, Brazilian ANVISA pathway comparisons, and titanium alloy trade flow data. Bottom-up instrument shipment estimates from provincial health system aggregators were cross-referenced against top-down market sizing from import registry analysis.
Historical procurement volume trajectories were cross-referenced against panel input from sterilization infrastructure operators and distribution channel partners across the analysis window. Segmentation modeling incorporated product type, end-user institution tier, material substrate, and application complexity dimensions. CAGRs were derived from regression analysis of provincial health budget allocations and surgical procedure volume trends, with ANMAT registration timeline assumptions and Mercosur harmonization probability weights as key forecast inputs.
Regulatory delay extensions, provincial budget austerity measures, and feedstock certification bottlenecks are the dominant revision risks that could compress or extend growth trajectories. Stakeholders should weight assumptions against their own operating context and sterilization infrastructure access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
Tonsil and Adenoid Removal Products Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market
Surgical Instruments
Huber Needles Market
Surgical Instruments
US Veterinary Surgical Instruments Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Surgical Pliers Market
Surgical Instruments
Global Surgical Retractor Market
Surgical Instruments
Global Hysteroscopy Instruments Market
Surgical Instruments
Medical Penlights Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Global Surgical Stapler Market
Surgical Instruments
Surgical Rasps Market