
 Pneumoperitoneum Market | 2026-2036
Pneumoperitoneum Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumoperitoneum Market Analytics
Minimally invasive surgical suites are restructuring the pneumoperitoneum landscape as laparoscopy displaces open procedures across general surgery and gynecology. Medtronic leverages its integrated surgical ecosystem to control gas delivery system placements in North American hospital networks. Olympus Corporation anchors its position through specialized insufflation hardware bundled with endoscopic visualization platforms. Stryker Corporation competes via robotic surgery compatibility and connected device architectures that embed pneumoperitoneum management into broader digital OR workflows.
Pneumoperitoneum denotes the deliberate introduction of gas into the peritoneal cavity to create operative workspace during abdominal procedures, with carbon dioxide serving as the standard insufflant due to its non-combustible properties, rapid absorption, and minimal physiological perturbation at flow rates typically maintained between one and fifteen liters per minute. The product type dimension shows carbon dioxide sustaining dominant share while helium gains traction in specific electrosurgery contexts where gas embolism risk demands alternative chemistry. Application segmentation reveals laparoscopic surgery as the established volume anchor, though diagnostic imaging applications are expanding as interventional radiology adopts controlled insufflation techniques for percutaneous access guidance.
FDA medical device regulations and CE marking requirements under the EU MDR shape gas purity specifications, insufflator safety thresholds, and electromagnetic compatibility standards that manufacturers must satisfy for market access. ISO 13485 quality management frameworks and IEC 60601 electrical safety standards further constrain design choices and testing protocols for automated delivery systems. Stakeholders must monitor evolving MDR transition timelines and FDA digital health guidance to anticipate compliance burdens that will favor scaled manufacturers with dedicated regulatory affairs infrastructure over smaller component suppliers.
Market Dynamics
Laparoscopic surgery volumes are restructuring the pneumoperitoneum landscape as minimally invasive procedures displace open abdominal operations across hospital systems worldwide. Gas delivery system specifications are tightening under evolving medical device frameworks, compressing margins for component suppliers while rewarding integrated platform manufacturers with dedicated regulatory infrastructure.
Growth Catalysts
- EU MDR compliance deadlines:The Medical Device Regulation's phased implementation is accelerating replacement cycles for legacy insufflators in European surgical suites. Hospitals must upgrade to certified systems before certificate expiration dates.
- Robotic surgery integration:Da Vinci and competing surgical robotic platforms require precise pneumoperitoneum management as a core workflow component. Compatible gas delivery systems are becoming standard procurement specifications.
- Carbon dioxide:The standard insufflant's non-combustible properties and rapid peritoneal absorption characteristics sustain its dominance across electrosurgery contexts where patient safety demands reliable chemistry.
Market Restraints
- Medical-grade CO2 supply concentration:Purified gas production clusters among industrial gas majors with regional bottlenecks in supply chain resilience. Surgical gas availability depends on non-medical priority allocations during shortage events.
- Insufflator hardware commoditization:Basic pressure-flow control mechanisms face price erosion as Asian contract manufacturers replicate core functionality. Differentiation requires software-layer investment many component suppliers cannot fund.
- Helium insufflation:Alternative gas chemistry for specific electrosurgery applications limits addressable procedure volumes. Carbon dioxide's cost and infrastructure advantages constrain helium penetration to niche safety-critical cases.
Strategic Opportunities
- Interventional radiology expansion:Controlled peritoneal insufflation for percutaneous access guidance represents an emerging application beyond traditional laparoscopy. Diagnostic imaging suites are adopting modified gas delivery protocols.
- India surgical infrastructure buildout:Government hospital modernization programs and private healthcare investment are expanding minimally invasive surgical capacity. First-time insufflator placements exceed replacement demand in this geography.
- Connected device architectures:Integration of pneumoperitoneum data streams with digital operating room platforms creates service revenue potential. Real-time pressure monitoring feeds into broader surgical workflow analytics.
Industry Challenges
- IEC 60601-1 electrical safety certification:Third-edition amendments for electromagnetic compatibility extend testing timelines and engineering redesign cycles for automated delivery systems.
- ISO 13485 quality management implementation:Smaller component suppliers struggle to maintain audit-ready documentation systems as notified body scrutiny intensifies under MDR transition.
- Legacy OR integration complexity:New insufflator generations must interface with heterogeneous installed bases of endoscopic towers and surgical robots without proprietary lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumoperitoneum Market |
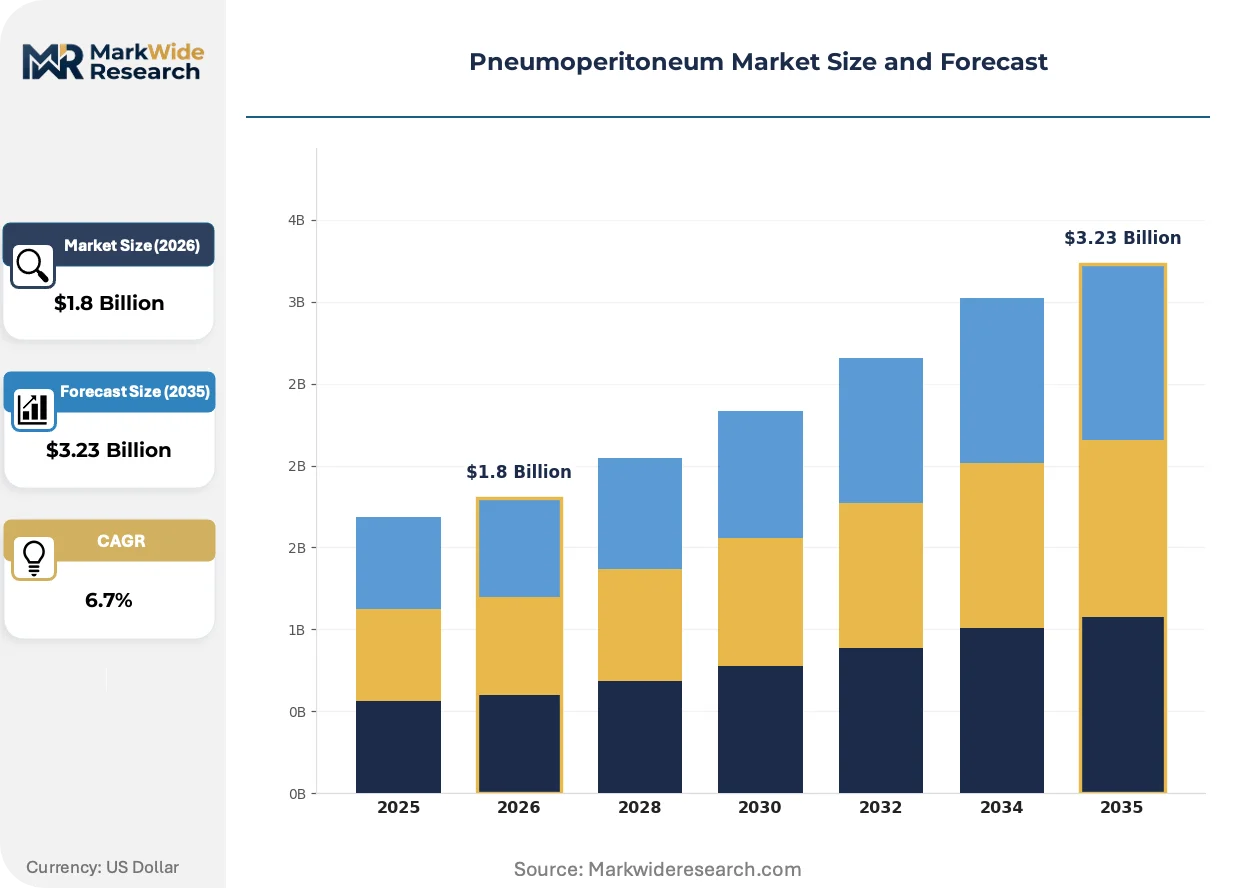
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Dioxide, Nitrous Oxide, Helium, Others Application: Laparoscopic Surgery, Diagnostic Imaging, Surgical Intervention, Others End User: Hospitals, Outpatient Clinics, Surgical Centers, Research Institutions Delivery Mode: Continuous Flow, Intermittent Flow, Manual Delivery, Automated Delivery |
| Companies Covered | Medtronic, Olympus Corporation, Ethicon US, LLC (Johnson & Johnson), STERIS, Karl Storz SE & Co. KG, Stryker Corporation, CONMED Corporation, B. Braun SE, Fujifilm Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumoperitoneum Market Evolving Landscape
Gas delivery automation and sensing sophistication are redefining competitive differentiation in pneumoperitoneum management. Three converging developments are compressing the technology lifecycle and reshaping procurement criteria across surgical specialties.
Smart insufflation systems with real-time pressure sensing and adaptive flow algorithms are electrifying the competitive landscape for integrated surgical platforms. Academic medical centers in Germany and Japan are adopting these systems at accelerated replacement cycles. The technology is compressing margins for standalone insufflator manufacturers unable to embed their hardware within broader visualization ecosystems.
EU MDR Article 10 technical documentation requirements are mandating clinical evidence portfolios for legacy device recertifications. Manufacturers must generate or acquire performance data previously unnecessary under the Medical Devices Directive. Class IIa insufflators face the steepest compliance burden as notified bodies apply heightened scrutiny to software-controlled pressure delivery systems.
Hospital procurement departments are consolidating vendor relationships through single-source framework agreements for entire surgical ecosystems. Independent insufflator suppliers face exclusion from integrated platform RFPs. This concentration is most visible in United States health system purchasing cooperatives where standardization incentives override best-of-breed component selection.
Pneumoperitoneum Market Segmentation
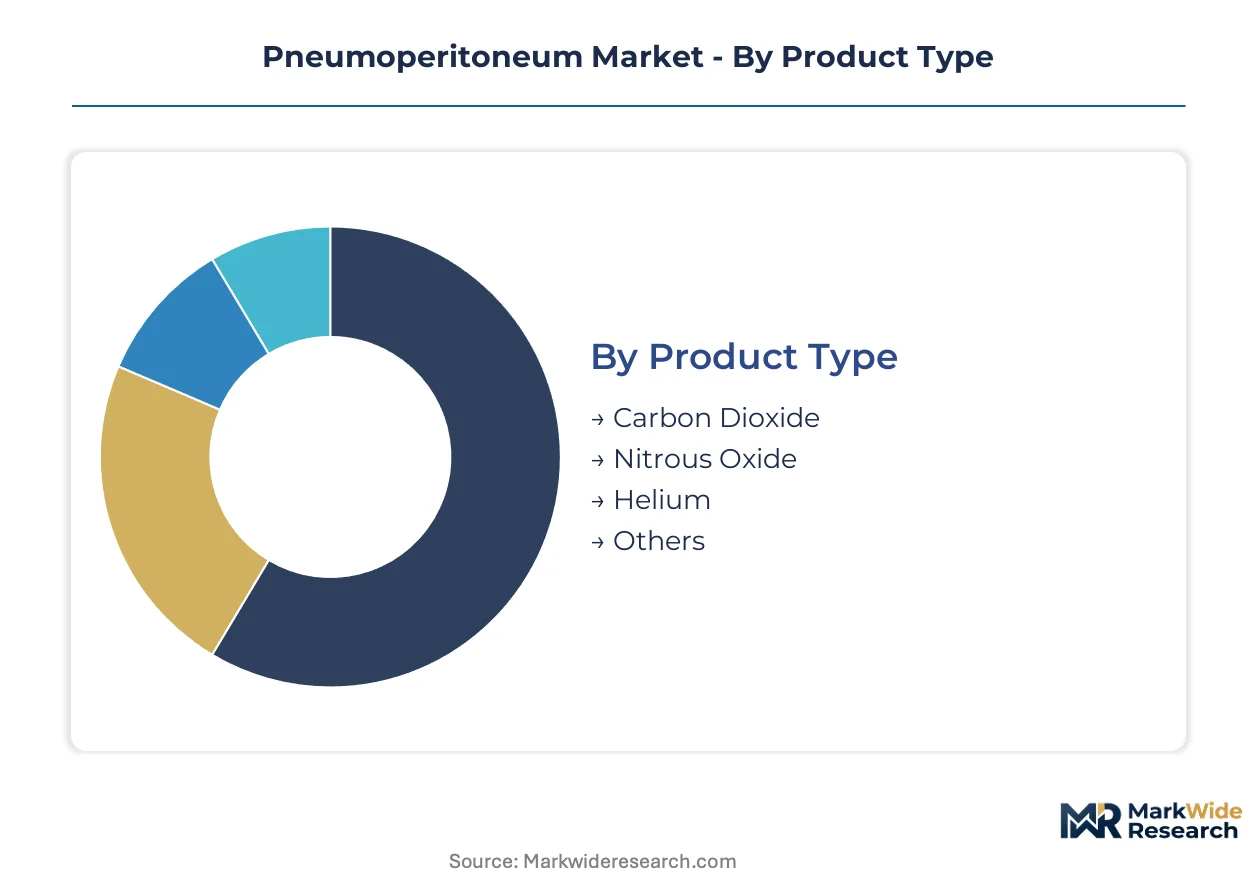
Pneumoperitoneum market segmentation reveals how gas chemistry, procedural application, and delivery automation intersect to determine procurement patterns. Manufacturers configure product portfolios around these dimensions to capture replacement cycles and first-time placements in expanding surgical infrastructure.
Product Type:
Medical gas supply chains concentrate purification capacity among industrial gas specialists, with certification requirements filtering available chemistry options for surgical use.
- Carbon Dioxide:The standard insufflant delivers non-combustible properties and rapid peritoneal absorption at flow rates between one and fifteen liters per minute. United States hospital systems specify medical-grade CO2 for electrosurgery suites where patient safety protocols demand reliable chemistry. FDA gas purity standards constrain sourcing to certified suppliers with dedicated medical production lines.
- Helium:Alternative gas chemistry addresses specific electrosurgery contexts where gas embolism risk demands non-absorbable insufflation. German academic medical centers specify helium for high-risk cardiac proximity procedures where CO2 absorption kinetics create physiological concerns. Supply bottlenecks limit penetration to safety-critical niche applications.
- Nitrous Oxide:Historical insufflant with limited contemporary surgical adoption due to combustion risk and slower absorption profiles.
- Others:Experimental and region-specific gas mixtures under evaluation for specialized interventional radiology protocols.
Carbon Dioxide absorbs the bulk of installed capacity; Helium is expanding most quickly among alternative chemistry options.
Application:
Procedure volume distribution across surgical specialties determines insufflator feature requirements and replacement timing.
- Laparoscopic Surgery:Minimally invasive abdominal procedures generate the core demand anchor for controlled peritoneal insufflation. General surgery and gynecology departments in Japan drive specification tightening for pressure-flow precision. Robotic surgery integration is elevating gas delivery system requirements in academic medical centers.
- Diagnostic Imaging:Controlled peritoneal insufflation for percutaneous access guidance represents an emerging application beyond traditional operative contexts. Interventional radiology suites in Germany are adopting modified gas delivery protocols for CT-guided procedures. Equipment manufacturers are adapting insufflator hardware for non-surgical workflow integration.
- Surgical Intervention:Hybrid operating rooms combine open and minimally invasive techniques requiring flexible insufflation management.
- Others:Veterinary applications and cadaveric training facilities represent peripheral demand segments with distinct procurement channels.
Laparoscopic Surgery commands the dominant share of procedure volumes; Diagnostic Imaging is climbing the fastest as interventional radiology expands gas delivery adoption.
End User:
Facility scale and case complexity shape purchasing authority and equipment specification hierarchies.
- Hospitals:Integrated health systems in the United States consolidate pneumoperitoneum procurement through centralized supply chain agreements. Multi-specialty surgical volumes justify premium insufflator platforms with robotic compatibility and digital OR integration. Replacement cycles accelerate where EU MDR compliance deadlines approach.
- Surgical Centers:Ambulatory facilities prioritize cost-efficient standalone insufflators for high-volume elective procedures. Asian markets show particular concentration of surgical center buildouts where government investment expands minimally invasive capacity. Basic pressure-flow control suffices for standardized laparoscopy protocols.
- Outpatient Clinics:Limited procedure volumes restrict equipment investment to portable or shared device models.
- Research Institutions:Preclinical and clinical trial applications drive demand for precision instrumentation with data logging capabilities.
Hospitals absorb the bulk of installed capacity; Surgical Centers are gaining share fastest amid ambulatory surgery expansion.
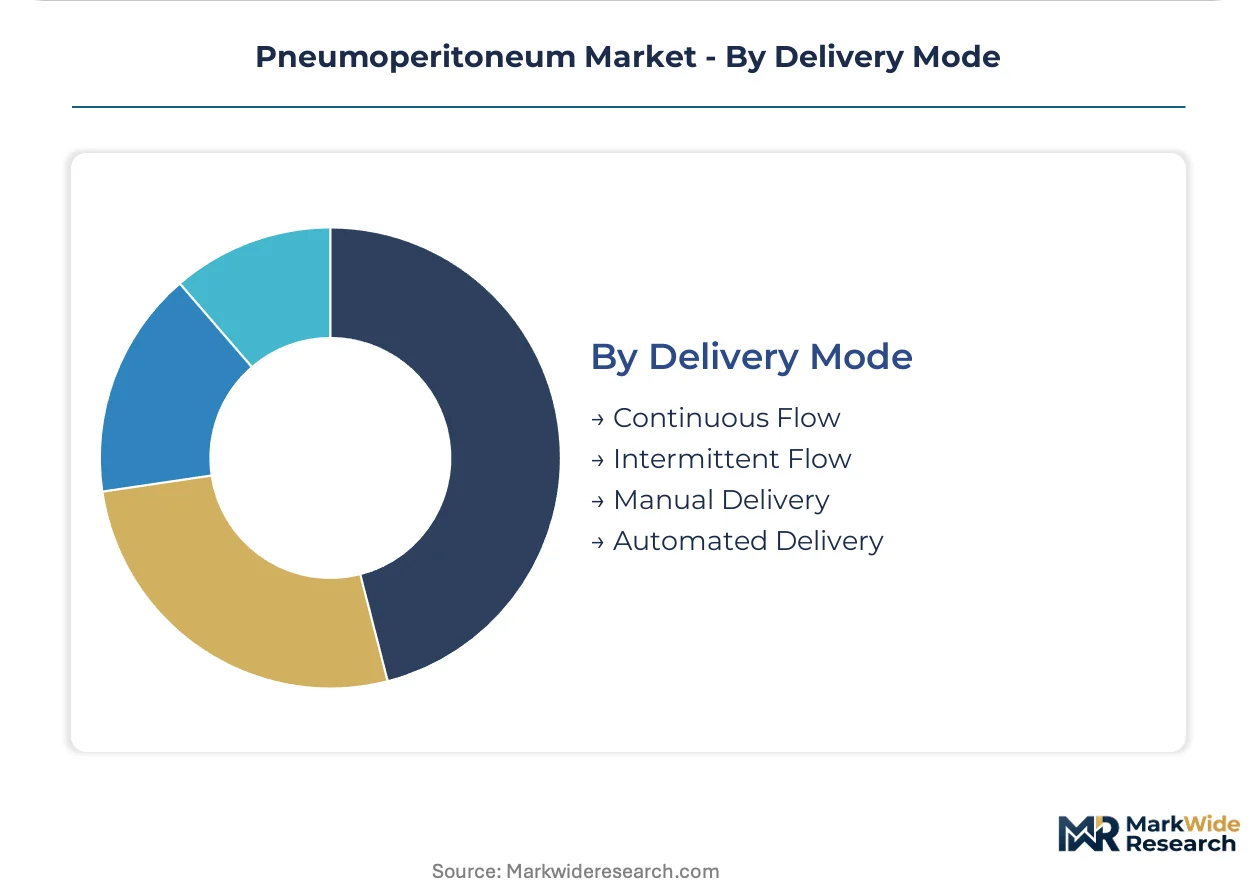
Delivery Mode:
Automation sophistication separates premium platform tiers from commodity hardware in procurement evaluations.
- Automated Delivery:Smart insufflation systems with real-time pressure sensing and adaptive flow algorithms command premium positioning in integrated surgical ecosystems. Academic medical centers in Japan and Germany lead adoption of these systems at accelerated replacement cycles. Software-layer investment requirements exclude smaller component suppliers from this tier.
- Continuous Flow:Standard pressure-maintained delivery dominates installed base volumes where basic laparoscopy suffices. United States community hospitals specify these systems for cost-conscious general surgery departments. Price erosion from Asian contract manufacturers compresses margins for standalone hardware.
- Intermittent Flow:Pulsed delivery protocols for specific pediatric or compromised patient applications.
- Manual Delivery:Legacy systems remaining in limited-resource settings and training environments.
Continuous Flow retains the dominant installed base; Automated Delivery is expanding most quickly as digital OR integration becomes standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade carbon dioxide production concentrates among industrial gas specialists in Germany and the United States, while surgical consumption clusters in hospital systems across Japan, Germany, and the United States where laparoscopic procedure volumes drive insufflator placement decisions.
United States
Integrated health systems consolidate pneumoperitoneum procurement through centralized supply chain agreements covering multi-specialty surgical volumes. FDA medical device regulations enforce gas purity specifications and electromagnetic compatibility standards for automated delivery systems. The Greater Boston and Houston medical corridors anchor demand for robotic-compatible insufflation platforms.
Germany
Academic medical centers in Bavaria and Baden-Württemberg specify precision insufflators for high-complexity procedures including cardiac-proximity electrosurgery. EU MDR compliance deadlines accelerate replacement cycles for legacy systems ahead of certificate expiration. The Rhine-Main cluster around Frankfurt hosts concentrated surgical robotics adoption requiring integrated gas delivery workflows.
Japan
Metropolitan hospital networks in Tokyo and Osaka drive specification tightening for pressure-flow precision in general surgery and gynecology departments. PMDA device approvals align with IEC 60601 electrical safety standards for software-controlled pressure delivery. The Kansai region leads accelerated replacement cycles for smart insufflation systems with adaptive flow algorithms.
India
Government hospital modernization programs and private healthcare investment expand minimally invasive surgical capacity in Maharashtra and Karnataka. CDSCO medical device regulations shape import requirements for insufflator hardware entering the market. First-time insufflator placements in Delhi-NCR and Chennai exceed replacement demand as surgical infrastructure buildout continues.
United Kingdom
NHS procurement frameworks standardize pneumoperitoneum equipment across trust networks with emphasis on cost efficiency and digital OR integration. MHRA regulations implement EU MDR-equivalent standards for gas delivery system safety and clinical evidence requirements. The London-Southeast corridor concentrates demand for connected device architectures feeding surgical workflow analytics.
Pneumoperitoneum Market Competitive Landscape
Top-tier vendors anchor integrated surgical ecosystems, while mid-tier component suppliers face margin compression from hardware commoditization and regulatory compliance burdens. The market structure rewards scaled manufacturers with dedicated regulatory affairs infrastructure over smaller standalone insufflator producers. Three archetypes dominate: diversified medical technology conglomerates with visualization platforms, specialized endoscopic equipment manufacturers, and industrial gas suppliers controlling purification capacity. Competitive dynamics center on strategic partnerships for robotic surgery compatibility and portfolio diversification into interventional radiology applications.
Among diversified medical technology conglomerates, Medtronic, Olympus Corporation, and Stryker Corporation exemplify the integrated platform approach. Medtronic represents the surgical ecosystem archetype with gas delivery system placements embedded within broader hospital network agreements. Olympus Corporation occupies a position exemplifying specialized endoscopic hardware bundled with visualization platforms. Stryker Corporation sits within the digital OR integration tier, where connected device architectures embed pneumoperitoneum management into broader workflow analytics. These three anchors demonstrate how scale and regulatory infrastructure separate premium-tier competitors from component suppliers facing exclusion from single-source framework agreements.
| Leading Market Players |
|---|
| Medtronic |
| Olympus Corporation |
| Ethicon US, LLC (Johnson & Johnson) |
| STERIS |
| Karl Storz SE & Co. KG |
| Stryker Corporation |
| CONMED Corporation |
| B. Braun SE |
| Fujifilm Holdings Corporation |
| Others |
Value Network & Pricing Analysis
EU MDR Article 10 technical documentation requirements gate qualified supply for premium-tier insufflator platforms, as manufacturers must absorb recertification costs that smaller component suppliers cannot fund. This regulatory filter concentrates pricing power among scaled platform vendors with dedicated regulatory affairs infrastructure while compressing margins for standalone hardware producers.
Pricing Analysis
Cost-down pressure on automated delivery tiers accelerates because software-layer investment requirements exclude smaller component suppliers from premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates robotic-compatible smart systems from basic pressure-flow hardware and legacy manual units. Certification grade under EU MDR and FDA gas purity standards drives price differentiation, with United States hospital systems least price-sensitive due to bundled procurement agreements while Asian surgical centers exhibit highest sensitivity to per-unit hardware costs.
Supply Chain Analysis
Direct-to-hospital channels handle integrated platform placements for multi-specialty health systems in the United States and Germany. Medical-grade carbon dioxide purification concentrates in Germany and the United States among industrial gas specialists, while insufflator hardware manufacturing draws from precision engineering clusters in Japan and Germany. Supply chain risk centers on single-source vulnerability for specialized pressure sensors and electromagnetic compatibility components. Distribution runs through GPO contracts in North America and tender-based hospital procurement in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pneumoperitoneum market is consolidating around platform vendors with regulatory infrastructure, as EU MDR compliance deadlines force weaker component suppliers toward exit or acquisition.
For Market Incumbents: Extend ecosystem lock-in through robotic surgery compatibility certifications and backward integration into medical-grade gas supply partnerships. Defensive positioning requires embedding insufflation data streams within broader digital OR workflow analytics to prevent disintermediation by standalone hardware competitors.
For New Entrants and Emerging Players: Capture first-time placement demand in India's government hospital modernization programs where replacement cycles exceed installed base competition. Interventional radiology applications for percutaneous access guidance represent the most penetrable white-space segment beyond traditional laparoscopy. Go-to-market positioning should emphasize portable, cost-efficient systems for ambulatory surgical centers in Maharashtra and Karnataka.
For Investors and Strategic Acquirers: Accelerated replacement cycles in Japanese academic medical centers for smart insufflation systems is the leading indicator that software-controlled pressure delivery will dominate premium-tier procurement. Long-term viability favors scaled manufacturers with ISO 13485 quality management infrastructure and notified body relationships. Acquisition targets should display CE marking pathway progress under MDR transition timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks European hospital procurement before certificate expiration deadlines. |
| Hospital System Partnership | Single-source framework agreements with United States GPOs secure multi-year insufflator placements. |
| Software Companion Development | Real-time pressure monitoring integration feeds digital OR workflow analytics platforms. |
| Backward Integration | In-house medical-grade CO2 supply partnerships reduce dependency on industrial gas majors. |
| Robotic Compatibility Certification | Da Vinci and competing surgical robot integration becomes standard procurement specification. |
Research Methodology
Multi-period observation of insufflator placement volumes, replacement cycle timing, and regulatory certification status anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body certificates, hospital procurement databases, and CMS Medicare claims data. Bottom-up installation base modeling triangulated against top-down surgical procedure volume estimates.
Segment-weighting across product type, application, end user, and delivery mode dimensions structured the analytical framework. CAGRs were derived from procedure volume trajectories, replacement timing assumptions, and pricing tier evolution across the projection horizon. Industry-specific forecast inputs included laparoscopic surgery adoption curves and EU MDR transition timeline impacts on replacement demand.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to medical-grade CO2 supply disruptions, MDR implementation delays, and robotic surgery platform market share shifts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market
Surgical Instruments
Lumpectomy Market
Surgical Instruments
Medical Tuning Fork Market
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Global Surgical Scalpel Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Electrocautery Enhanced Delivery System Market
Surgical Instruments
Electrosurgery Market
Surgical Instruments
Global Surgical Instrument Tracking System Market
Surgical Instruments
Surgical Blades Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Corneal Transplantation Surgical Instrument Package Market
Surgical Instruments
Disposable Surgical Devices Market