
 Surgical Pliers Market | 2026-2036
Surgical Pliers Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Pliers Market Analytics
Aftermarket service revenue for instrument refurbishment is reshaping how surgical pliers vendors capture lifetime value from hospital accounts. Integra LifeSciences Corporation leverages its direct-service infrastructure to lock in multi-year hospital contracts. Sklar Surgical Instruments anchors its position through deep specialization in hemostatic clamp refurbishment protocols.
Surgical pliers are hand-actuated grasping instruments manufactured from medical-grade stainless steel or titanium alloys, typically featuring serrated jaws, box-lock joints, and carbide inserts to deliver controlled mechanical advantage during tissue manipulation and needle driving. Needle holders dominate product-type revenue due to universal deployment across general surgery, while minimally invasive surgery applications expand fastest as laparoscopic and robotic platforms require longer, narrower instrument profiles. Stainless steel retains material share leadership though titanium variants command premium positioning in neurosurgical and microsurgical settings.
FDA 510(k) clearance pathways and EU MDR Class I/IIa conformity requirements govern market access and compel documented biocompatibility testing for all metallic surfaces. ISO 13485 quality management systems and ASTM F899 surgical alloy standards further constrain supplier qualification, filtering smaller forging operations from hospital vendor lists. Stakeholders must monitor how FDA's evolving reprocessing guidance and EU F-Gas Regulation impacts sterilization infrastructure investments.
Market Dynamics
Minimally invasive surgery platforms are compressing instrument lifecycles and forcing stainless steel suppliers to recalibrate forging capacity toward longer, narrower plier profiles demanded by laparoscopic and robotic systems.
Growth Catalysts
- EU MDR Class I/IIa conformity expansion:The Medical Device Regulation is compelling European hospitals to refresh instrument inventories, accelerating replacement procurement for aging hemostatic clamps and needle holders.
- Titanium alloy adoption in neurosurgery:Magnetic resonance imaging compatibility requirements are elevating titanium surgical pliers in cranial and spinal procedures where ferromagnetic interference risks patient safety.
- Outpatient surgery center proliferation:Ambulatory facilities in the United States are expanding dedicated instrument sets, creating parallel demand streams independent of traditional hospital procurement cycles.
Market Restraints
- Nickel price volatility in medical-grade stainless:ASTM F899-certified 440A and 17-4PH alloys face input cost swings that compress forging margins and destabilize multi-year hospital contracting.
- German forging concentration:Tuttlingen and Solingen clusters control premium surgical steel supply, creating geographic single-point-of-failure exposure for instrument OEMs.
- Carbide insert sourcing bottleneck:Tungsten carbide jaw reinforcement depends on limited sintering capacity, constraining production scale-up for high-wear applications.
Strategic Opportunities
- India's CDSCO manufacturing incentive pathway:Production-linked incentive schemes for medical devices are attracting forging investment to serve domestic surgery volume and export markets.
- Refurbishment-as-a-service models:Third-party instrument reprocessing is creating recurring revenue streams that extend customer lifetime value beyond initial hardware sales.
- Robotic surgery platform integration:Dedicated needle holder designs for da Vinci and Versius systems represent uncontracted white space in instrument portfolios.
Industry Challenges
- FDA 510(k) predicate device drift:Evolving substantial equivalence standards are extending clearance timelines for novel jaw geometries and locking mechanisms.
- Passivation chemistry workforce scarcity:Citric acid and nitric acid surface treatment expertise is concentrated among aging technicians, constraining quality-controlled production expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Pliers Market |
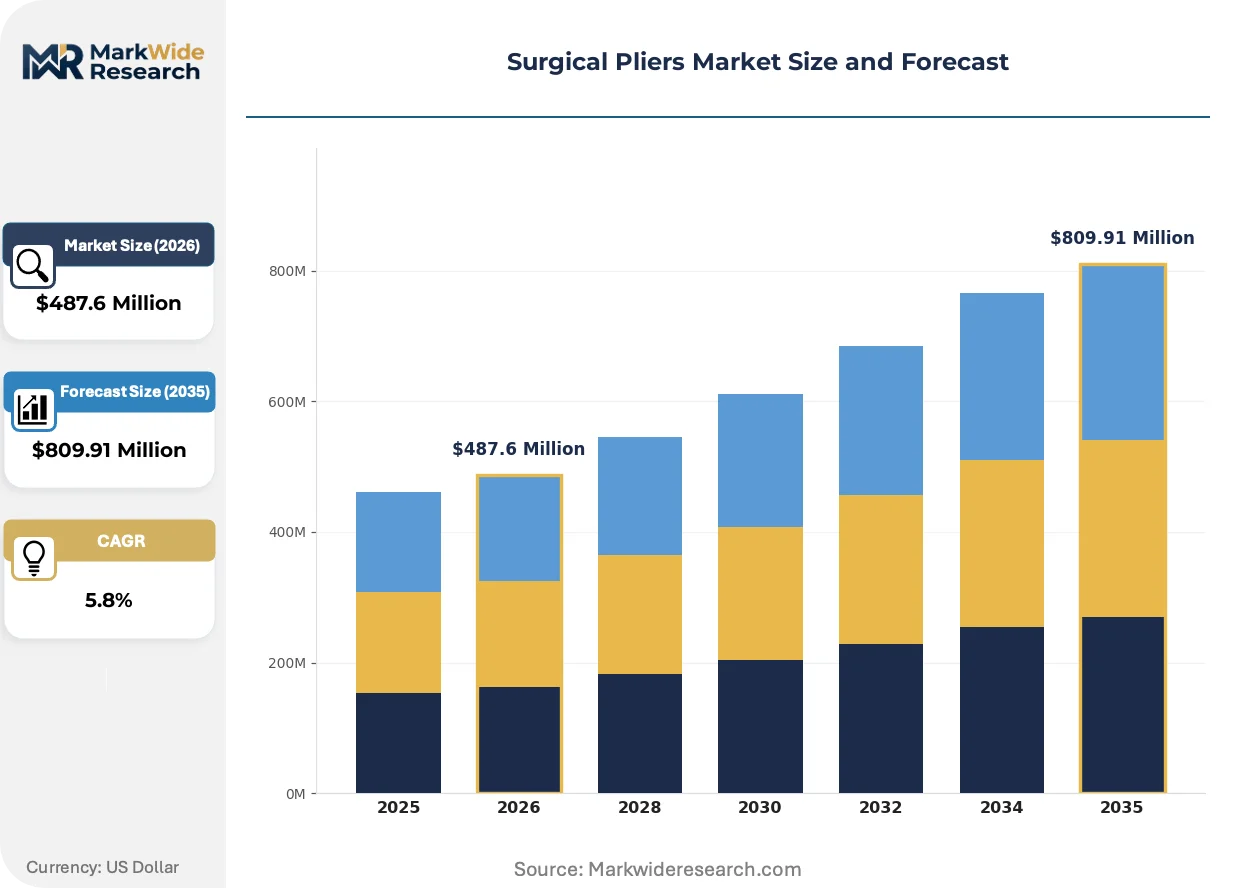
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Locking Pliers, Needle Holders, Tissue Graspers, Hemostatic Clamps Application: Open Surgery, Minimally Invasive Surgery, Orthopedic Procedures, Cardiovascular Procedures Material: Stainless Steel, Titanium, Plastic, Carbon Fiber End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions |
| Companies Covered | Novo Surgical, Eurotek Surgical, BlackSmith Surgical, GerMedUSA, Vital Surgical Technologies, Integra LifeSciences Corporation, Key Surgical, HYGITECH, Sklar Surgical Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Pliers Market Evolving Landscape
Digital thread integration across forging, finishing, and sterilization workflows is compressing quality assurance cycles and enabling lot-level traceability demanded by institutional procurement.
Carbide-serrated jaw surfaces are hybridizing with laser-etched depth markers to deliver tactile feedback and visual measurement in a single instrument profile. Academic medical centers in the United States are piloting these hybrid configurations for microvascular anastomosis. The convergence is compressing instrument count in specialized trays while elevating per-unit pricing power for manufacturers with precision laser capabilities.
EU F-Gas Regulation phase-down schedules are forcing sterilization infrastructure reinvestment across German and French hospital networks. Ethylene oxide alternative validation requirements are extending equipment procurement cycles. Central sterilization departments are prioritizing instrument designs compatible with hydrogen peroxide vapor and peracetic acid modalities, reshaping material selection criteria for box-lock joint lubricants and polymer inserts.
Hospital group purchasing organizations are consolidating vendor panels and unbundling after-sales service from capital equipment contracts. Integrated delivery networks in the United States are negotiating direct refurbishment agreements with specialized third parties, bypassing traditional manufacturer service hierarchies. This disintermediation is most visible in multi-hospital systems across Texas and Florida where procurement autonomy has shifted to centralized supply chain functions.
Surgical Pliers Market Segmentation
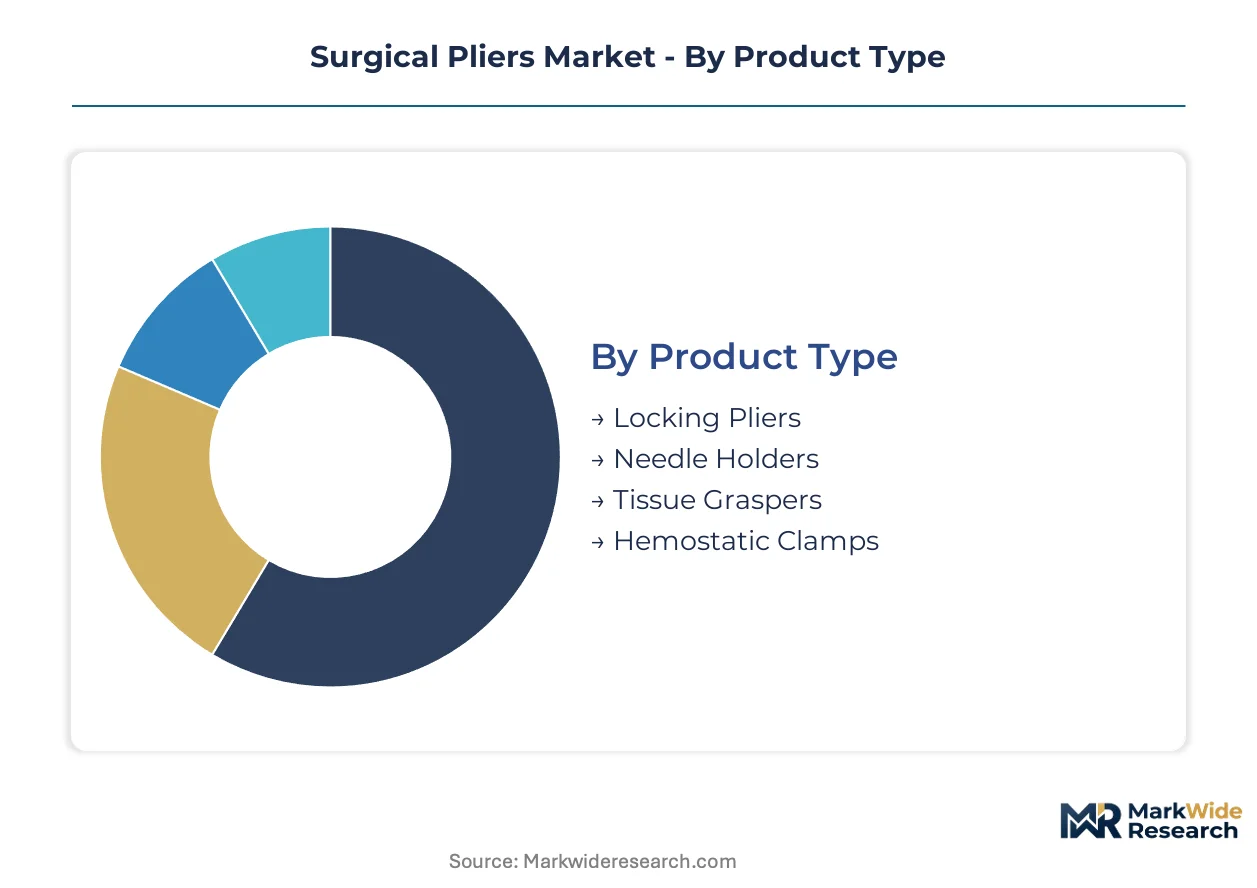
Surgical pliers segmentation reveals how instrument specifications align with procedural economics and regulatory requirements across care settings. Product type and material choices directly determine sterilization compatibility, lifecycle durability, and reimbursement capture rates.
Product Type:
Mature configurations dominate hospital procurement cycles while emerging designs address minimally invasive platform requirements.
- Needle Holders:Box-lock joint mechanisms with tungsten carbide jaw inserts deliver needle driving torque across general surgery suites. United States academic medical centers are standardizing on longer shaft profiles to accommodate bariatric patient anatomy. Demand concentrates in multi-hospital systems where tray standardization reduces sterilization turnaround.
- Hemostatic Clamps:Ratcheted locking mechanisms with longitudinal serrations enable vessel occlusion across cardiovascular and general surgery applications. German hospital networks are refreshing aging inventories to meet EU MDR traceability requirements. Procurement is accelerating as Tuttlingen forging clusters expand passivation capacity.
- Locking Pliers:Self-retaining jaw configurations reduce surgical assistant demand in resource-constrained settings.
- Tissue Graspers:Atraumatic tip geometries prioritize organ manipulation in laparoscopic cholecystectomy and appendectomy procedures.
Needle holders retain volume leadership; tissue graspers hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive platform-dependent procedures from instrument-agnostic open surgery.
- Minimally Invasive Surgery:Laparoscopic and robotic platforms demand elongated, narrow-diameter plier profiles with insulated handles to prevent thermal injury. Japanese tertiary hospitals are expanding dedicated instrument sets for da Vinci system integration. Reimbursement density in Tokyo and Osaka metropolitan areas supports premium pricing for titanium variants.
- Open Surgery:Traditional instrument specifications persist where robotic infrastructure investment remains uneconomical. Rural United States hospitals and emerging market facilities prioritize reusable stainless steel configurations with established sterilization protocols. Procurement cycles extend to seven-to-ten years in budget-constrained environments.
- Orthopedic Procedures:High-torque jaw designs accommodate wire manipulation and fragment reduction in trauma settings.
- Cardiovascular Procedures:Microsurgical precision requirements elevate demand for titanium needle holders with diamond-dust jaw surfaces.
Open surgery retains volume leadership; minimally invasive surgery gains share fastest.
Material:
Margin structure varies dramatically across metallurgical grades and composite alternatives.
- Stainless Steel:ASTM F899-certified 440A and 17-4PH alloys deliver cost-effective durability for high-turnover general surgery instruments. German and Japanese forging operations control premium supply chains. Price volatility in nickel inputs is compressing multi-year contracting margins.
- Titanium:Magnetic resonance imaging compatibility and superior strength-to-weight ratios command premium positioning in neurosurgical and microsurgical settings. United States cranial procedure volume is elevating demand for non-ferromagnetic instrument sets. PMDA clearance pathways in Japan are accelerating adoption for spinal fusion applications.
- Plastic:Single-use configurations address contamination risk in outbreak response and resource-limited settings.
- Carbon Fiber:Emerging lightweight alternatives target robotic surgery platforms where instrument mass affects manipulator payload limits.
Stainless steel retains volume leadership; titanium holds the steepest expansion curve.
End User:
Customer type determines procurement autonomy, service contract structure, and instrument lifecycle management.
- Hospitals:Central sterilization departments and group purchasing organization contracts dominate volume procurement. United States integrated delivery networks are unbundling refurbishment services from manufacturer agreements. Texas and Florida multi-hospital systems are piloting direct third-party reprocessing contracts.
- Ambulatory Surgical Centers:Dedicated instrument sets and rapid sterilization turnaround requirements favor streamlined tray configurations. United States outpatient facility proliferation is creating parallel demand streams independent of hospital procurement cycles. Medicare reimbursement shifts are accelerating site-of-service migration.
- Specialty Clinics:Ophthalmology and dermatology settings prioritize precision micro-instruments with specialized jaw geometries.
- Research Institutions:Preclinical and cadaveric training applications demand instrument durability under repeated sterilization cycles.
Hospitals retain volume leadership; ambulatory surgical centers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German hospitals prioritize instrument longevity and refurbishment cycles, while United States facilities emphasize rapid tray turnover and GPO contract compliance. Japanese procurement concentrates on titanium compatibility for advanced imaging suites.
United States
Academic medical centers in Boston and Houston are standardizing elongated needle holder profiles for bariatric procedures. FDA 510(k) clearance pathways govern all new instrument submissions. The Texas Medical Center cluster anchors multi-hospital system procurement where centralized supply chain functions now negotiate direct refurbishment contracts.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia are refreshing aging hemostatic clamp inventories to meet EU MDR traceability mandates. The Tuttlingen forging cluster controls premium surgical steel supply chains and is expanding passivation capacity to serve accelerated replacement demand.
Japan
Tertiary hospitals in Tokyo and Osaka metropolitan areas are expanding dedicated instrument sets for da Vinci robotic system integration. PMDA clearance pathways are accelerating titanium surgical pliers adoption for spinal fusion applications where magnetic resonance imaging compatibility is mandatory.
India
Government hospitals in Maharashtra and Karnataka are scaling surgical volume under Ayushman Bharat coverage expansion. CDSCO manufacturing incentive schemes are attracting forging investment to serve domestic demand and export markets. The Pune industrial corridor is emerging as a stainless steel instrument fabrication hub.
United Kingdom
NHS trusts in London and the Midlands are consolidating vendor panels under national procurement frameworks. MHRA post-Brexit regulatory alignment with EU MDR is extending conformity assessment timelines. The Sheffield surgical steel tradition is adapting to serve refurbished instrument demand from centralized sterilization departments.
Surgical Pliers Market Competitive Landscape
Capability concentration sits with specialized forging operations; scale advantage sits with diversified medical device conglomerates. The market structures around three tiers: premium instrument specialists with direct hospital service infrastructure, mid-scale fabricators serving group purchasing organization contracts, and regional suppliers competing on price for emerging market tenders. Dominant competitive moves include backward integration into carbide insert sourcing and geographic expansion through distribution partnerships.
Among United States-based diversified manufacturers, Integra LifeSciences Corporation exemplifies the service-integrated archetype through its direct infrastructure model. Sklar Surgical Instruments occupies a position within the specialized refurbishment tier. Eurotek Surgical and Novo Surgical represent the mid-scale fabricator segment serving standardized hospital procurement cycles.
| Leading Market Players |
|---|
| Novo Surgical |
| Eurotek Surgical |
| BlackSmith Surgical |
| GerMedUSA |
| Vital Surgical Technologies |
| Integra LifeSciences Corporation |
| Key Surgical |
| HYGITECH |
| Sklar Surgical Instruments |
| Others |
Value Network & Pricing Analysis
Tuttlingen's forging cluster capacity dynamics directly shape downstream pricing power for ASTM F899-certified surgical pliers, with passivation bottleneck constraints enabling premium capture for qualified suppliers while nickel volatility compresses margins among second-tier fabricators.
Pricing Analysis
Long-term offtake contracts dominate hospital procurement, with multi-year GPO agreements locking in stainless steel instrument pricing while spot purchasing persists for emergency titanium specialty orders. Price differentiation rests on ISO 13485 certification tier and carbide insert sourcing reliability, with FDA 510(k) predicate clearance commanding measurable premiums. Cost compression in standard hemostatic clamps is intensifying because German forging concentration limits competitive sourcing alternatives. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement constraints, while academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculus for tungsten carbide jaw reinforcement components. Raw material dependencies draw from Indonesian nickel ore, German 440A alloy stock, and Chinese sintered carbide inserts. Geographic supply concentration centers on Tuttlingen and Solingen in Germany, Pune in India, and Sialkot in Pakistan for finished instrument fabrication. Single-source vulnerability in citric acid passivation chemistry expertise constrains quality-controlled production expansion. Distribution runs through hospital GPO contracts, specialty surgical instrument distributors, and direct manufacturer service infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refurbishment-as-a-service revenue layers are expanding faster than hardware sales, making instrument lifecycle management contracts the priority attach opportunity for sustainable margin capture.
For Market Incumbents: Harden direct-service infrastructure against third-party reprocessing disintermediation by locking multi-year hospital contracts with guaranteed turnaround SLAs. Deepen backward integration into carbide insert sourcing to defend against tungsten supply bottlenecks. Prioritize EU MDR traceability system investments to capture inventory refresh cycles in German hospital networks. For New Entrants and Emerging Players: Establish a beachhead in India's CDSCO-certified manufacturing pathway by leveraging production-linked incentive schemes to serve domestic Ayushman Bharat volume and export markets. Target ambulatory surgical center instrument sets in Texas and Florida where procurement autonomy has shifted to centralized supply chain functions. Pursue robotic surgery platform integration partnerships with dedicated needle holder designs for da Vinci and Versius systems. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized forging operations with captive passivation capabilities and established hospital service infrastructure. Long-term viability over a five-to-ten year window hinges on refurbishment revenue attach rates exceeding thirty percent of total account value. The signal to watch is FDA reprocessing guidance evolution that could validate or invalidate third-party reprocessing business models.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year GPO contracts with Integra LifeSciences lock in recurring refurbishment revenue streams. |
| CE Marking Pathway | EU MDR Class I/IIa conformity accelerates inventory replacement cycles across German hospital networks. |
| Backward Integration | In-house carbide insert production insulates margins from tungsten sintering capacity constraints. |
| Software Companion Development | Digital thread integration enables lot-level traceability demanded by institutional procurement. |
| Reimbursement Strategy | Medicare site-of-service migration favors ambulatory surgical center dedicated instrument sets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR conformity databases, hospital procurement contracts, and ASTM F899 alloy specifications. Primary interviews engaged instrument forging operators, hospital biomedical engineers, GPO contracts managers, and central sterilization department heads. Secondary validation drew from customs trade data, SEC 10-K medical device segment disclosures, and German Tuttlingen cluster production statistics. Bottom-up demand modeling triangulated against top-down market sizing across product type, material grade, and end-user segments.
Forecast inputs include surgical procedure volume trajectories, minimally invasive surgery platform adoption curves, and regulatory compliance cost burdens across the analysis window. Segmentation dimensions modeled encompass product type, material metallurgy, application setting, and end-user facility tier. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity constraints. Industry-specific forecast inputs incorporate nickel price volatility assumptions and EU F-Gas Regulation sterilization infrastructure reinvestment cycles.
Macroeconomic conditions sit as an overlay; deviation in surgical reimbursement rates, nickel commodity pricing, or FDA reprocessing guidance would shift the trajectory. Forecasts reflect documented assumptions regarding procedure volume growth and regulatory implementation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Laparoscopic Gynecological Procedures Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Lumpectomy Market
Surgical Instruments
Neovaginal Surgery Market
Surgical Instruments
Hand-Held Surgical Instruments Market
Surgical Instruments
High Flow Needle Sets Market
Surgical Instruments
Global Surgical Scalpel Market
Surgical Instruments
Heavy Power Surgical Tools Market
Surgical Instruments
Global Surgical Scissors Market
Surgical Instruments
Biosurgery Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Global Hysteroscopy Instruments Market
Surgical Instruments
Surgical Drains Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Surgical Clips Market