
 Cancer IVD Market | 2026-2036
Cancer IVD Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer IVD Market Analysis
CLIA-high-complexity certification is rotating toward the center of competitive strategy in oncology diagnostics. Danaher Corporation leverages its Beckman Coulter and Cepheid divisions to sustain integrated workflow automation from sample prep to result reporting. Abbott Laboratories anchors its position through Alinity platform placements in health system core laboratories across North America and Europe. Roche Diagnostics dominates immunohistochemistry antibody-menu depth, competing on breadth rather than price in anatomic pathology.
Cancer in vitro diagnostics comprise reagent-based analytical systems and instruments that detect tumor-associated biomarkers in patient-derived specimens through nucleic acid amplification, protein detection, or cytogenetic analysis, with sensitivity thresholds typically reaching picogram-per-milliliter analyte concentrations. These technologies enable oncologists to classify malignancy subtypes, select targeted therapies, and monitor minimal residual disease during treatment courses. PCR-based assays currently occupy the largest revenue share among technology segments due to entrenched reimbursement and established clinical utility in EGFR and KRAS mutation testing. Next-generation sequencing platforms are capturing the fastest expansion as panel sizes broaden from hotspot analyses to comprehensive genomic profiling in solid tumors. Diagnostic laboratories represent the highest-margin end-user channel because of consolidated purchasing power and direct payer contracts for molecular pathology services.
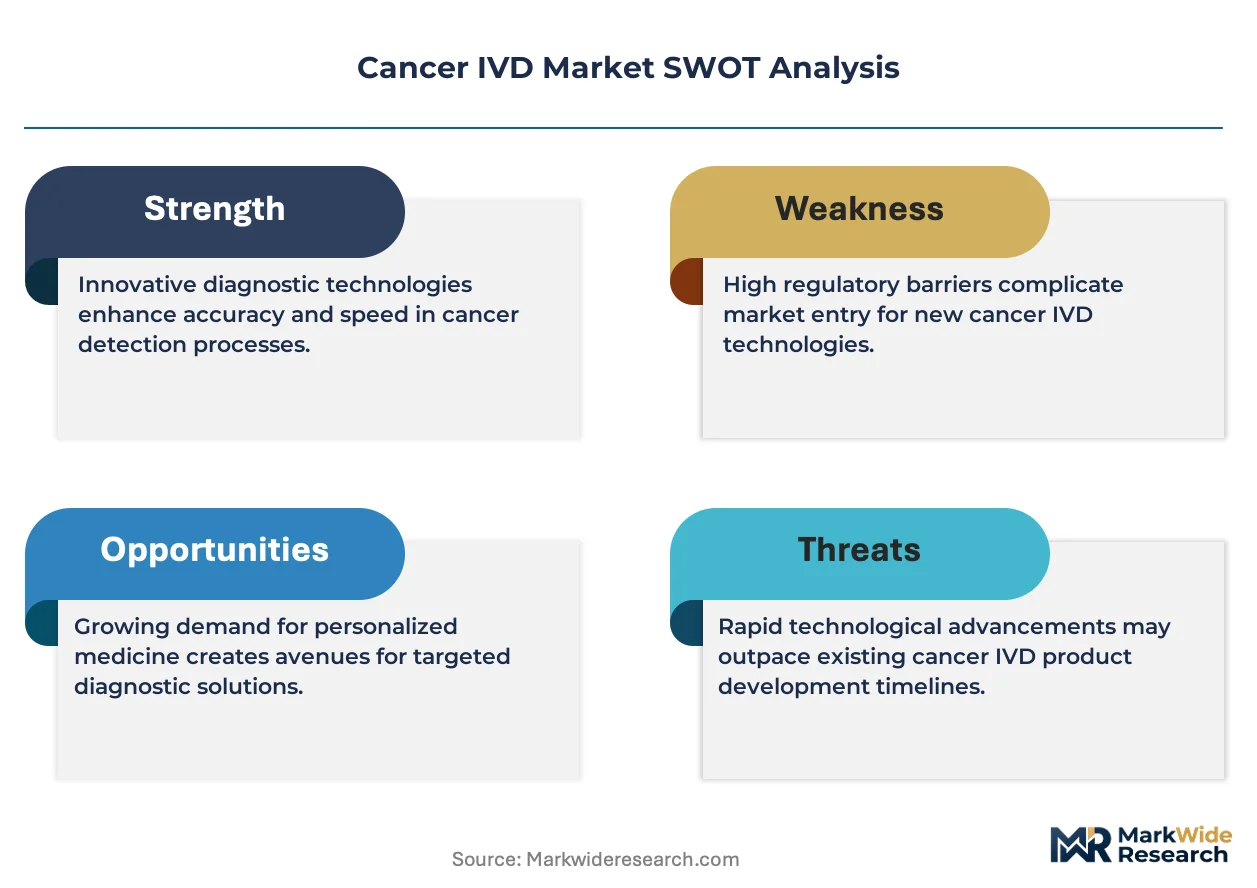
FDA premarket approval and CLIA laboratory certification shape product commercialization pathways and analytical performance standards for cancer IVD manufacturers seeking U.S. market access. EMA In Vitro Diagnostic Regulation transition timelines are forcing European notified body capacity constraints that delay CE-marking for novel oncology assays. Stakeholders must monitor how FDA breakthrough device designation criteria and EMDR technical documentation requirements diverge on clinical evidence standards for companion diagnostic co-development programs.
Market Dynamics
Companion diagnostic co-development requirements are compressing product lifecycles as pharmaceutical sponsors demand parallel regulatory submissions for targeted therapies and their paired assays.
Growth Catalysts
- Liquid biopsy reimbursement expansion:Statutory health insurance frameworks in Germany now cover circulating tumor DNA testing for solid tumor profiling, driving volume in molecular pathology laboratories.
- FDA breakthrough device designation:Expedited premarket review pathways for oncology companion diagnostics shorten time-to-market for novel biomarker assays.
- Minimal residual disease monitoring:Hematology-oncology practices are adopting next-generation sequencing-based MRD panels for post-treatment surveillance in leukemia and lymphoma.
Market Restraints
- Notified body capacity constraints:EMA In Vitro Diagnostic Regulation transition timelines are creating CE-marking backlogs that delay European commercialization for novel oncology assays.
- Reagent supply concentration:Polymerase and nucleotide raw material production clusters in East Asian contract manufacturers create single-source vulnerability for PCR-based test kits.
- Analytical validation complexity:Comprehensive genomic profiling panels require reference standard libraries that exceed current FDA guidance on variant classification evidence thresholds.
Strategic Opportunities
- Home-based specimen collection:Dried blood spot and saliva collection devices enable decentralized oncology screening in rural and underserved U.S. regions.
- Artificial intelligence-assisted pathology:Deep learning algorithms for immunohistochemistry quantification are converging with digital slide scanners to automate biomarker scoring.
- Japan's regenerative medicine framework:PMDA accelerated approval pathways for CAR-T companion diagnostics create early-mover advantages for CD19 and BCMA assay developers.
Industry Challenges
- Bioinformatics pipeline standardization:Variant interpretation workflows lack cross-platform harmonization, forcing laboratories to maintain redundant validation protocols for each NGS instrument.
- CLIA-high-complexity personnel recruitment:Molecular genetics technologist certification requirements outpace U.S. educational program output, constraining laboratory expansion.
- LIMS integration with EMR systems:Electronic health record interoperability gaps delay result reporting and complicate longitudinal patient data tracking across health system networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer IVD Market |
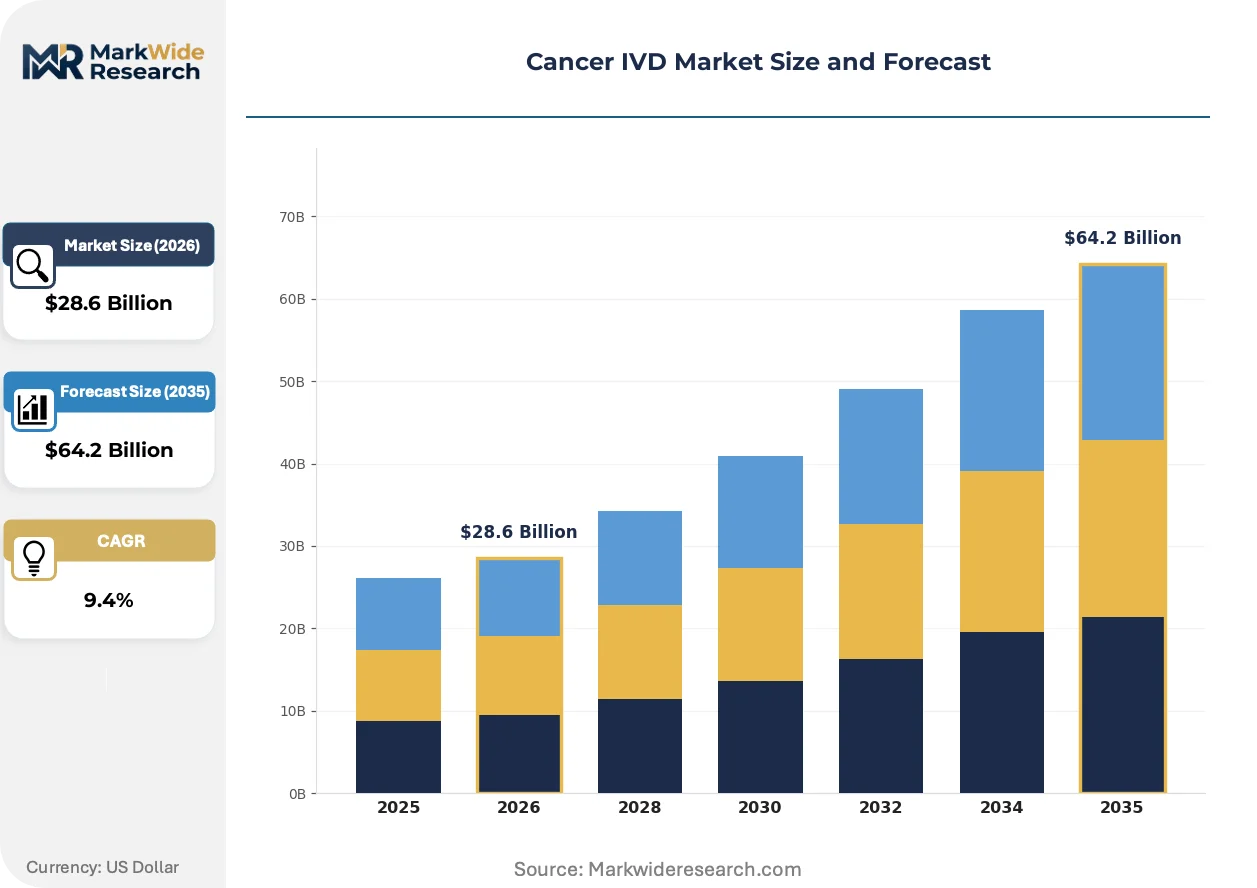
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assays, Devices, Reagents, Kits Technology: PCR, Next-Generation Sequencing, Immunohistochemistry, Microarrays End User: Hospitals, Diagnostic Laboratories, Academic Institutions, Research Centers Application: Early Detection, Disease Monitoring, Treatment Selection, Personalized Medicine |
| Companies Covered | Danaher Corporation, Bio-Rad Laboratories Inc., Abbott Laboratories, Myriad Genetics Inc., Hologic Inc., Roche Diagnostics, Siemens Healthineers AG, Biocartis Group NV, Agilent Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer IVD Market Emerging Trajectories
Multi-omics assay architectures are displacing single-analyte testing as pharmaceutical sponsors demand integrated biomarker strategies for clinical trial stratification and companion diagnostic labeling.
Methylation-based early detection assays are fragmenting the oncology screening landscape. Guardant Health and Exact Sciences are commercializing blood-based tests for colorectal and multi-cancer screening in asymptomatic populations. This fragmentation is compressing the addressable market for established fecal immunochemical testing and creating new channel conflicts between reference laboratories and health system outreach programs.
EMA In Vitro Diagnostic Regulation performance study requirements are reshaping European commercialization strategies. Manufacturers must now generate clinical evidence from within the EU rather than relying on U.S. FDA submissions for CE-marking. German and French notified bodies are prioritizing oncology assays in their review queues, while smaller member state authorities face eighteen-month backlogs for novel biomarker submissions.
Health system laboratory insourcing is altering distribution economics for molecular diagnostics. Academic medical centers in the United States are bringing comprehensive genomic profiling in-house to capture technical component revenue and reduce send-out costs. This shift favors instrument-agnostic reagent suppliers over integrated platform vendors and compresses margins for reference laboratory service providers dependent on specimen volume from hospital affiliates.
Cancer IVD Market Segmentation
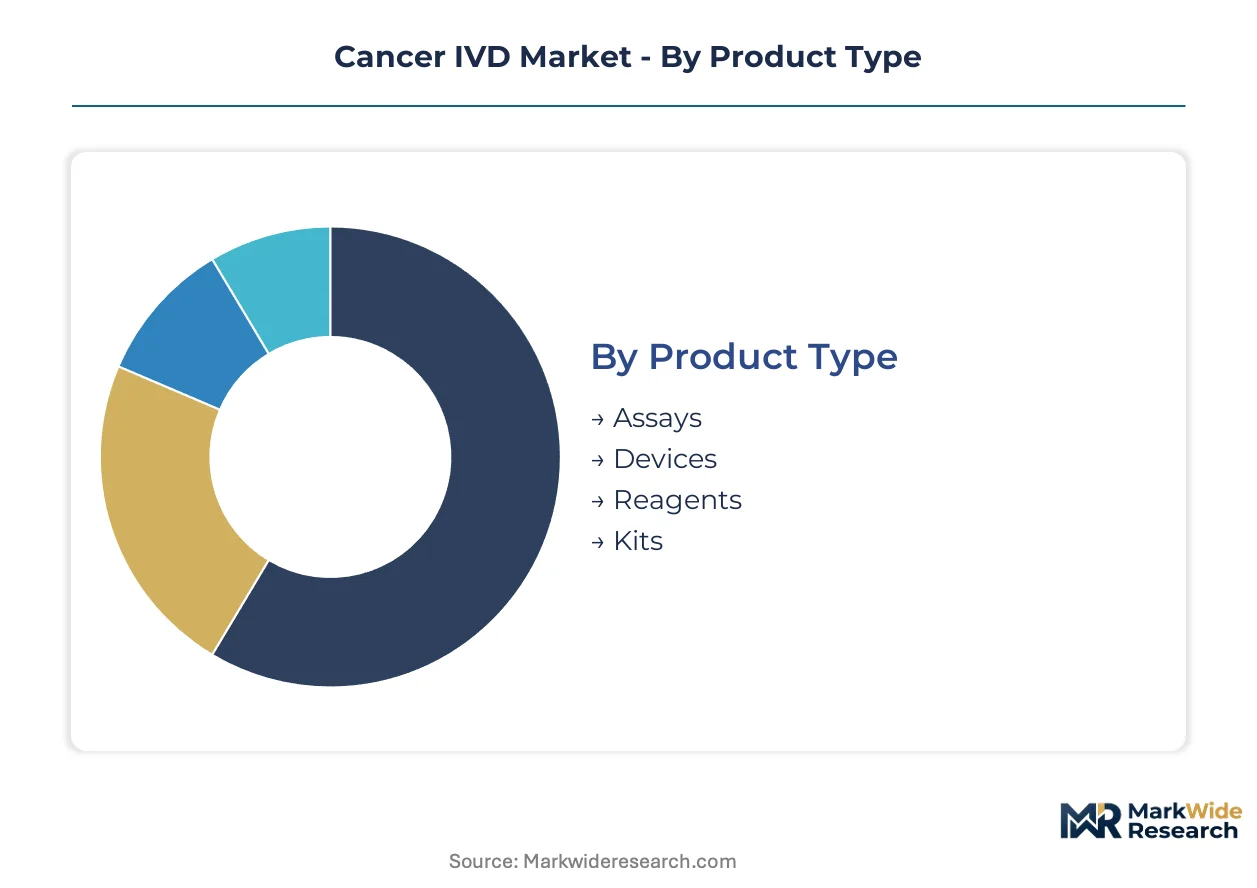
Segmentation in cancer IVDs determines channel economics and margin capture. Reagent suppliers, platform vendors, and service laboratories each optimize around distinct product-technology combinations. Understanding these flows exposes where pricing power concentrates and where commoditization threatens.
Product Type:
Assays and reagents flow through consolidated laboratory purchasing coalitions. Devices and kits distribute through instrument-lease arrangements that lock in multi-year consumable commitments.
- Assays:Pre-validated test systems for specific biomarker targets, typically bundled with analytical software and interpretation algorithms. Demand concentrates in health system core laboratories across Germany and the United States, where CLIA-high-complexity certification requirements favor validated assay menus over laboratory-developed tests.
- Reagents:Enzyme, buffer, and nucleotide formulations that constitute the variable cost in PCR and NGS workflows. Academic medical centers in the United States are insourcing reagent preparation to capture technical component revenue, compressing margins for reference laboratory service providers.
- Devices:Automated sample processors, thermal cyclers, and slide staining instruments. Placement volumes track capital expenditure cycles at diagnostic laboratories in France and Italy.
- Kits:Complete testing systems including consumables, controls, and documentation for specific cancer markers. Procurement patterns favor CE-IVD marked products in European hospital settings facing EMA In Vitro Diagnostic Regulation compliance deadlines.
Reagents dominate installed base. Assays are where expansion concentrates.
Technology:
Cost tier differentiation separates premium NGS platforms from standard PCR workflows. Immunohistochemistry occupies a mid-tier position with entrenched reimbursement but slower growth.
- PCR:Polymerase chain reaction systems for targeted mutation detection with established clinical utility in EGFR and KRAS testing. Reimbursement codes in the United States and statutory health insurance coverage in Germany sustain volume despite panel breadth limitations.
- Next-Generation Sequencing:Massively parallel sequencing platforms enabling comprehensive genomic profiling. Hematology-oncology practices in the United States are adopting NGS-based minimal residual disease panels, driving the steepest expansion trajectory among technology segments.
- Immunohistochemistry:Antibody-based protein detection on tissue sections with standardized scoring protocols. Anatomic pathology laboratories in France and Germany rely on IHC for PD-L1 and HER2 testing with established companion diagnostic labeling.
- Microarrays:Solid-phase nucleic acid hybridization systems for copy number and methylation analysis. Research centers in Japan utilize microarrays for biomarker discovery under PMDA exploratory study frameworks.
PCR anchors current revenue. Next-Generation Sequencing is climbing the fastest.
End User:
Customer type determines margin structure. Diagnostic laboratories command volume discounts while academic institutions prioritize research flexibility over standardization.
- Diagnostic Laboratories:Commercial and hospital-affiliated testing facilities with consolidated purchasing power. Direct payer contracts for molecular pathology services in the United States generate the highest-margin channel.
- Hospitals:Inpatient and outpatient clinical departments with integrated laboratory services. Health system insourcing trends in the United States favor instrument-agnostic reagent suppliers.
- Academic Institutions:University medical centers with research and clinical missions. Exploratory biomarker studies in Germany and France drive demand for customizable assay configurations.
- Research Centers:Dedicated oncology research facilities without clinical diagnostic accreditation. Early-stage assay development in Japan aligns with PMDA regenerative medicine framework timelines.
Diagnostic Laboratories capture the greatest revenue concentration. Hospitals are gaining share fastest through insourcing.
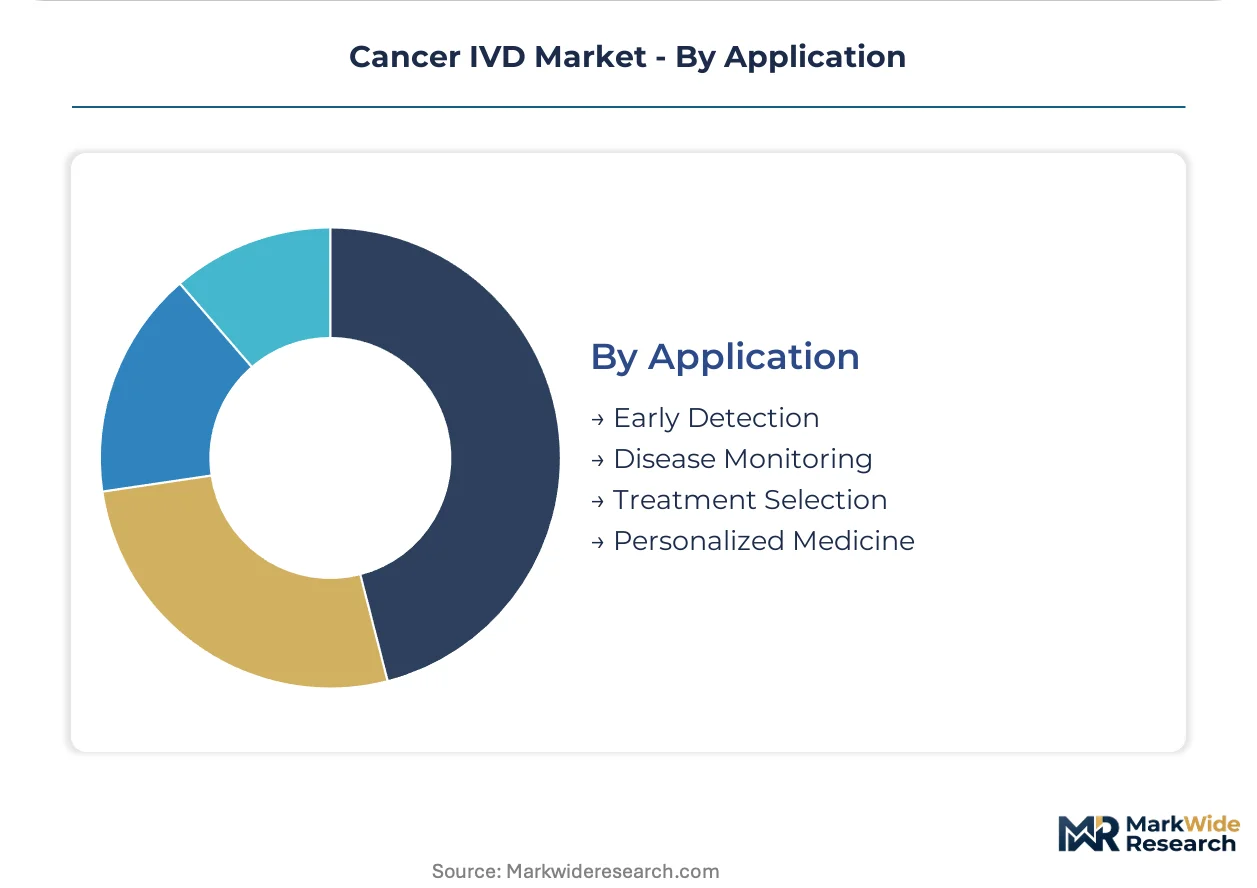
Application:
Maturity gradient runs from established treatment selection toward emerging early detection. Disease monitoring occupies a mid-position with growing clinical evidence.
- Treatment Selection:Companion diagnostic testing to match patients with targeted therapies. FDA breakthrough device designation pathways compress development timelines for novel biomarker assays paired with oncology drugs.
- Early Detection:Screening asymptomatic populations for cancer signals. Blood-based methylation assays from Guardant Health and Exact Sciences are fragmenting the colorectal cancer screening landscape in the United States.
- Disease Monitoring:Serial testing to assess treatment response and recurrence. Circulating tumor DNA testing for solid tumor profiling now receives statutory health insurance reimbursement in Germany.
- Personalized Medicine:Comprehensive biomarker integration for individualized therapeutic strategies. Comprehensive genomic profiling panels require reference standard libraries that exceed current FDA guidance on variant classification.
Treatment Selection dominates current test volume. Early Detection is where venture financing and regulatory attention concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate the lowest price elasticity due to statutory reimbursement guarantees, while academic medical centers in the United States negotiate aggressively on reagent contracts. Emerging markets in Asia-Pacific show intermediate sensitivity, prioritizing instrument-agnostic platforms over integrated systems.
United States
Health system laboratory insourcing concentrates demand in academic medical centers across Massachusetts and California. FDA breakthrough device designation pathways compress premarket review timelines for companion diagnostics. The Greater Boston cluster anchors comprehensive genomic profiling adoption, with Danaher Corporation and Abbott Laboratories maintaining platform placements in core laboratories.
Germany
Statutory health insurance reimbursement for molecular diagnostics eliminates out-of-pocket price sensitivity among diagnostic laboratories. EMA In Vitro Diagnostic Regulation transition timelines create CE-marking bottlenecks that favor established assay menus. The Rhine-Ruhr metropolitan region hosts the highest density of CLIA-equivalent certified laboratories in Europe.
Japan
PMDA accelerated approval pathways for CAR-T companion diagnostics attract early-mover assay developers. METI funding for regenerative medicine infrastructure expands biobank networks in Kanto and Kansai regions. Osaka-based research centers drive adoption of methylation-based early detection assays under exploratory study frameworks.
China
NMPA innovation device designation streams priority review for oncology IVDs with domestic clinical evidence. Dual carbon goals accelerate energy-efficient platform procurement in Yangtze River Delta hospital systems. Shanghai's Zhangjiang Hi-Tech Park clusters NGS instrument manufacturing and reagent production for Asia-Pacific distribution.
United Kingdom
NHS England genomic medicine service contracts consolidate purchasing power for comprehensive profiling panels. MHRA recognition of FDA approvals streamlines market entry for U.S.-validated companion diagnostics. The Cambridge-Oxford-London golden triangle concentrates early-stage assay development and clinical validation studies.
Cancer IVD Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated platform vendors commanding premium pricing in high-complexity laboratories and reagent suppliers capturing volume in insourced hospital settings. The market structure tilts toward consolidation at the platform tier and fragmentation among specialty assay developers. Three archetypes dominate: diversified conglomerates with diagnostic divisions, pure-play molecular diagnostics specialists, and pharmaceutical-aligned companion diagnostic partners. Competitive moves concentrate on workflow automation integration and geographic expansion through distributor networks rather than direct sales forces.
Among diversified conglomerates with diagnostic divisions, Danaher Corporation and Abbott Laboratories exemplify platform-centric strategies, while Roche Diagnostics anchors the immunohistochemistry antibody-menu depth segment. These three entities occupy positions that span instrument placement, reagent supply, and companion diagnostic co-development, representing the consolidation endpoint toward which mid-cap specialists are gravitating through partnership structures.
| Leading Market Players |
|---|
| Danaher Corporation |
| Bio-Rad Laboratories Inc. |
| Abbott Laboratories |
| Myriad Genetics Inc. |
| Hologic Inc. |
| Roche Diagnostics |
| Siemens Healthineers AG |
| Biocartis Group NV |
| Agilent Technologies Inc. |
| Others |
Supply Flow & Price Mechanics
NGS platform displacement of PCR workflows simultaneously redraws supply geography toward East Asian instrument manufacturing clusters and compresses reagent pricing power in mature markets. This substitution dynamic concentrates margin capture in after-sales consumable streams while fragmenting bargaining leverage among diagnostic laboratory buyers.
Pricing Analysis
After-sales reagent and service contracts generate lifetime value multiples exceeding instrument placement economics. Three-tier pricing structure across premium, standard, and economy levels separates FDA-breakthrough-designated companion diagnostics from CE-IVD marked assays and research-use-only panels. Pricing pressure stems from health system insourcing trends in the United States as academic medical centers negotiate direct reagent contracts. Diagnostic laboratories in Germany demonstrate lowest price sensitivity due to statutory reimbursement guarantees, while hospital procurement committees in France drive hardest bargain.
Supply Chain Analysis
China and South Korea anchor polymerase and nucleotide raw material production for PCR-based test kits. East Asian contract manufacturers supply Taq polymerase, dNTP formulations, and magnetic bead chemistries that feed global reagent kit assembly. Single-source vulnerability concentrates in Wuhan and Seoul metropolitan production zones exposed to geopolitical friction and export licensing restrictions. Distribution runs through regional distribution hubs in Rotterdam and Singapore before final-mile delivery to CLIA-certified laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where CLIA-high-complexity certification and FDA companion diagnostic labeling create switching costs that entrench incumbent positions.
For Market Incumbents: Shield installed base positions through captive reagent supply contracts and exclusive health system partnerships that lock out instrument-agnostic competitors. Deepen backward integration into nucleotide raw material production to offset East Asian supply concentration risk. Prioritize FDA breakthrough device designation pursuit for novel biomarker assays before EMA IVDR transition deadlines compress European approval timelines. For New Entrants and Emerging Players: Differentiate on AI-assisted pathology algorithms that automate immunohistochemistry quantification for PD-L1 and HER2 scoring. White-space opportunity concentrates in Japan's PMDA accelerated approval pathway for CAR-T companion diagnostics and in rural United States home-based specimen collection devices. Go-to-market through distributor networks rather than direct sales forces to bypass incumbent hospital system relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed comprehensive genomic profiling service laboratories facing margin compression from health system insourcing. Long-term viability hinges on regulatory entrenchment and test menu breadth rather than technology novelty alone. Watch FDA guidance evolution on variant classification evidence thresholds as inflection signal for NGS panel reimbursement durability.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | Aligns assay validation timelines with FDA oncology drug approval pathways. |
| CLIA-High-Complexity Laboratory Acquisition | Captures technical component revenue and insources comprehensive genomic profiling. |
| AI-Assisted Pathology Software Launch | Automates biomarker scoring for PD-L1 expression on digital slide platforms. |
| East Asian Reagent Manufacturing Footprint | Reduces polymerase supply vulnerability through captive production in Shanghai. |
| EMA IVDR Performance Study Investment | Generates EU-sourced clinical evidence required for CE-marking novel oncology assays. |
Methodological Framework
A standing panel of molecular pathology laboratory directors, FDA regulatory affairs specialists, hospital GPO contract managers, and companion diagnostic co-development executives provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) and PMA filings, EMA IVDR technical documentation, CMS Medicare reimbursement databases, and German statutory health insurance coverage decisions. Bottom-up test volume modeling triangulated against top-down market sizing from instrument placement tracking and reagent consumption estimates.
Consistency checks validated volume and value outputs against external benchmarks including hospital capital expenditure disclosures and pharmaceutical sponsor R&D pipeline announcements. Segmentation dimensions spanned technology platform, product type, end-user channel, application purpose, and regional regulatory cluster across the analysis window. CAGRs derived from logistic diffusion curves fitted to biomarker adoption patterns and reimbursement expansion timelines. Forecast inputs incorporated liquid biopsy coverage expansion in Germany and minimal residual disease panel adoption in United States hematology-oncology practices.
Material uncertainties — EMA notified body capacity constraints, FDA guidance revisions on variant classification, polymerase supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement stability and regulatory pathway continuity that external shocks could revise. Recalibration cycles align with material shifts in companion diagnostic co-development requirements and statutory coverage decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Glucose Tolerance Test Market
Diagnostics
Global Chromoendoscopy Agents Market
Diagnostics
Global Urinalysis Market
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
Global Renal Biomarkers Market
Diagnostics
Autoimmunity Immunoassay Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Preeclampsia Diagnostics Market
Diagnostics
Global Immunoassay Market
Diagnostics
Helicobacter Pylori (H. Pylori) Diagnostics Market
Diagnostics
Sperm Count Test Market
Diagnostics
Influenza Diagnostics Market
Diagnostics
Asia-Pacific Thyroid Cancer Diagnostics Market
Diagnostics
Livestock Diagnostics Market