
 Snare Devices Market | 2026-2036
Snare Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Snare Devices Market Outlook
The EU Green Deal's biodiversity restoration targets is recalibrating procurement standards across European conservation agencies. Medtronic leverages its polymer science expertise to develop composite snare alternatives with reduced tissue impact. Boston Scientific Corporation anchors its position through R&D partnerships with veterinary research centers in Germany and France. Cook Medical differentiates via specialized single-snare configurations designed for endangered species protocols.
Snare devices are mechanical restraint instruments engineered with calibrated loop mechanisms, typically constructed from aircraft-grade steel cable or high-tensile polymer filaments rated for specific breaking strengths, designed to capture or hold target animals without lethal force. The primary commercial purpose centers on wildlife population management, scientific specimen collection, and relocation operations across terrestrial and aquatic ecosystems. Disposable snare configurations command expanding share among government agencies prioritizing biosecurity and cross-contamination prevention. Multi-snare systems lead in research institution procurement where simultaneous sample collection improves field efficiency. Steel material grades retain dominance in heavy-duty pest control applications despite composite alternatives gaining traction in rehabilitation settings.
FDA device classification frameworks influence North American manufacturers seeking crossover applications in veterinary surgical retrieval. ECHA REACH compliance requirements govern polymer and coating substance approvals for European distribution. ISO 10993 biocompatibility testing standards shape material selection for snare devices contacting mammalian tissue. Stakeholders must monitor evolving national wildlife agency mandates on humane capture certification as procurement gatekeepers tighten qualification requirements.
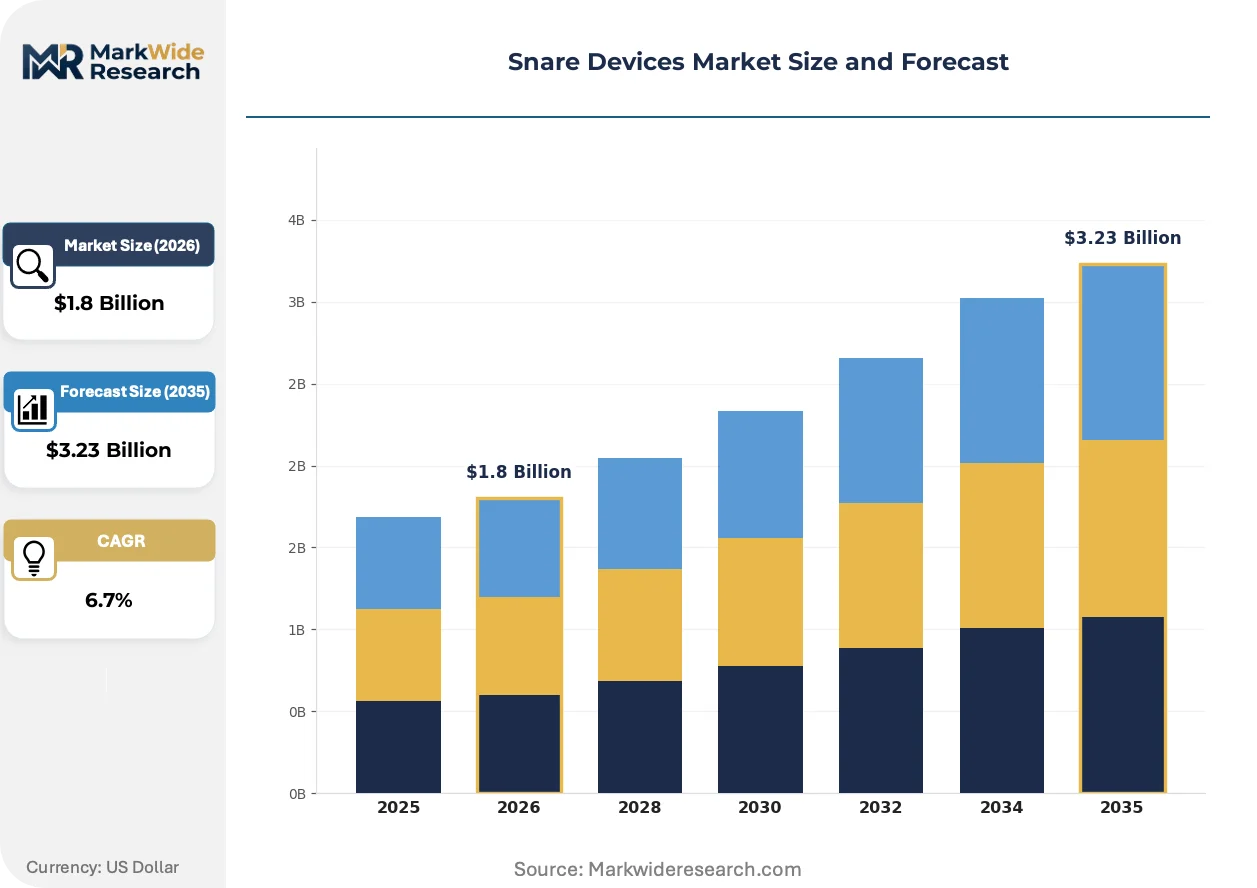
Market Dynamics
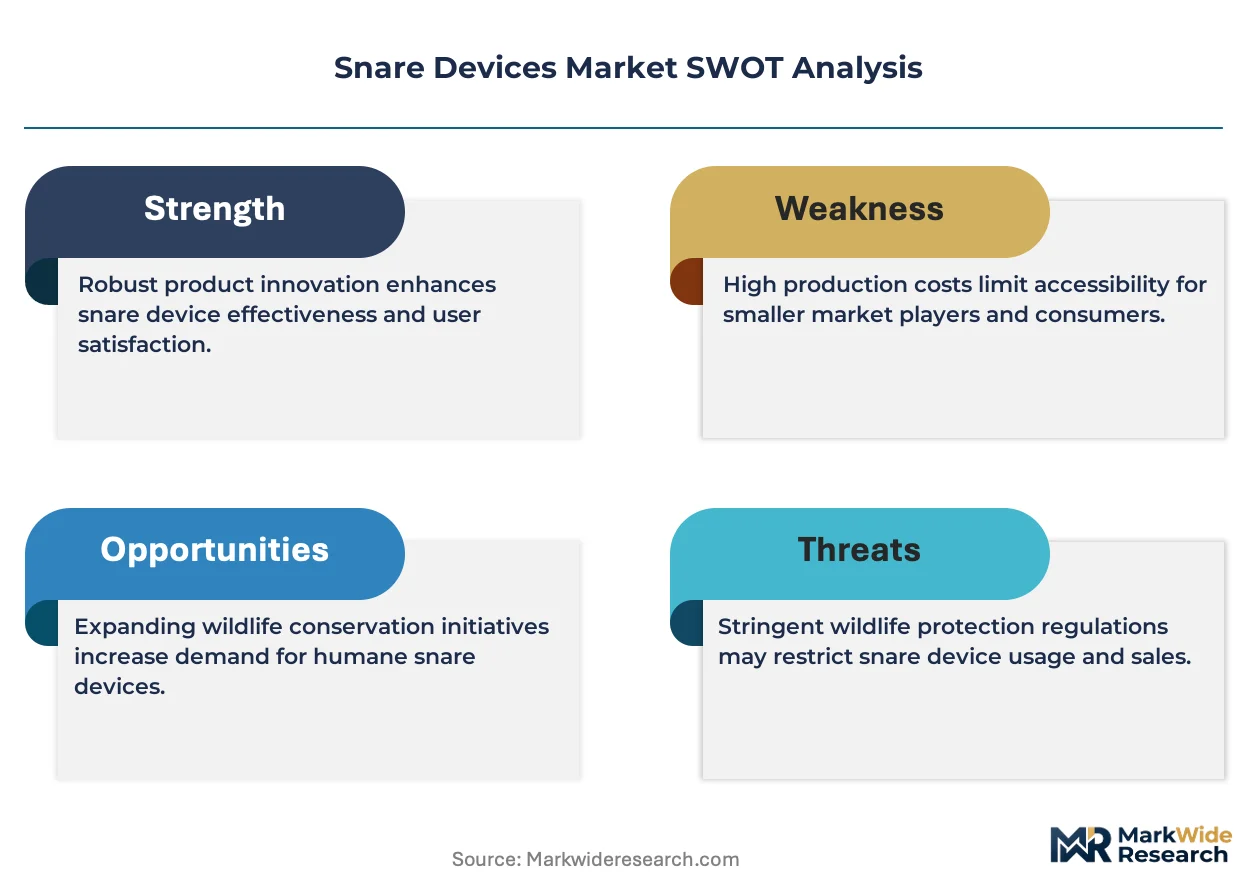
EPA guidelines on wildlife interaction protocols are tightening material compliance standards across North American procurement channels, forcing manufacturers to requalify polymer formulations and steel grades under compressed timelines.
Growth Catalysts
- EU Green Deal biodiversity targets:European conservation agencies are recalibrating procurement standards toward humane capture systems, creating certified supplier preference windows for compliant device manufacturers.
- Disposable configurations:Government agencies prioritizing biosecurity and cross-contamination prevention are expanding single-use snare procurement across federal land management contracts.
- Multi-snare field efficiency:Research institutions are consolidating vendor relationships around simultaneous sample collection systems that reduce per-capture labor hours and transport logistics.
Market Restraints
- Aircraft-grade steel cable volatility:Specialty steel supply concentrates among a limited producer base, exposing manufacturers to input cost swings and qualification delays for alternative metallurgy.
- ECHA REACH compliance friction:Polymer and coating substance approvals for European distribution require extensive substance registration timelines that extend market entry cycles by multiple quarters.
- Composite material performance gaps:High-tensile polymer filaments rated for specific breaking strengths still underperform steel grades in heavy-duty pest control load scenarios, limiting substitution elasticity.
Strategic Opportunities
- State-level conservation program expansion:United States wildlife management agencies are unbundling equipment procurement from service contracts, opening direct vendor relationships for specialized single-snare configurations.
- ISO 10993 biocompatibility convergence:Veterinary surgical retrieval applications are creating crossover demand for snare devices contacting mammalian tissue, with FDA device classification frameworks enabling dual-market qualification.
- Rehabilitation setting penetration:Endangered species protocols are absorbing composite snare alternatives with reduced tissue impact, displacing steel in capture-and-release operations where trauma minimization commands premium positioning.
Industry Challenges
- Humane capture certification timelines:National wildlife agency mandates on capture certification are tightening qualification requirements, extending product validation cycles and straining smaller manufacturer compliance resources.
- Polymer science talent scarcity:Composite snare development requires specialized material engineering expertise that concentrates among veterinary research center partnerships, limiting independent R&D velocity for mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snare Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Snare, Multi-Snare, Integrated Snare, Disposable Snare Application: Wildlife Management, Research, Pest Control, Rehabilitation Material: Steel, Nylon, Composite, Aluminum End User: Government Agencies, Conservation Groups, Research Institutions, Private Companies |
| Companies Covered | Medtronic, Boston Scientific Corporation, Olympus Corporation, Cook Medical, CONMED Corporation, Medline Industries, Inc., Steris, Merit Medical Systems, Fujifilm Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snare Devices Market Strategic Shifts
Material science advances and regulatory harmonization pressures are compressing traditional equipment procurement cycles while elevating performance certification requirements across conservation agency vendor pools.
High-tensile polymer filaments rated for specific breaking strengths are absorbing market share in rehabilitation settings where tissue impact reduction outweighs absolute load capacity. Wildlife rehabilitation centers and endangered species recovery programs are adopting these composites at accelerating pace despite per-unit cost premiums. The technology is absorbing functionality previously reserved for steel grades, compressing the addressable market for traditional cable configurations in sensitive capture protocols.
REACH substance registration requirements are forcing reformulation of polymer coatings and cable lubricants across European distribution channels. Manufacturers serving ECHA jurisdictions are consolidating supplier relationships around pre-registered substance portfolios to avoid registration cost duplication. Veterinary research centers in Germany and France are most affected, responding by anchoring R&D partnerships with polymer science specialists who maintain compliant substance libraries.
Federal land management contracts are unbundling equipment supply from integrated capture services, enabling direct manufacturer relationships with agency procurement offices. This channel disintermediation is compressing distributor margins while rewarding vendors with in-house certification documentation and rapid fulfillment infrastructure. The United States market exhibits this pattern most visibly, with state-level conservation programs following federal precedent in vendor qualification procedures.
Snare Devices Market Segmentation
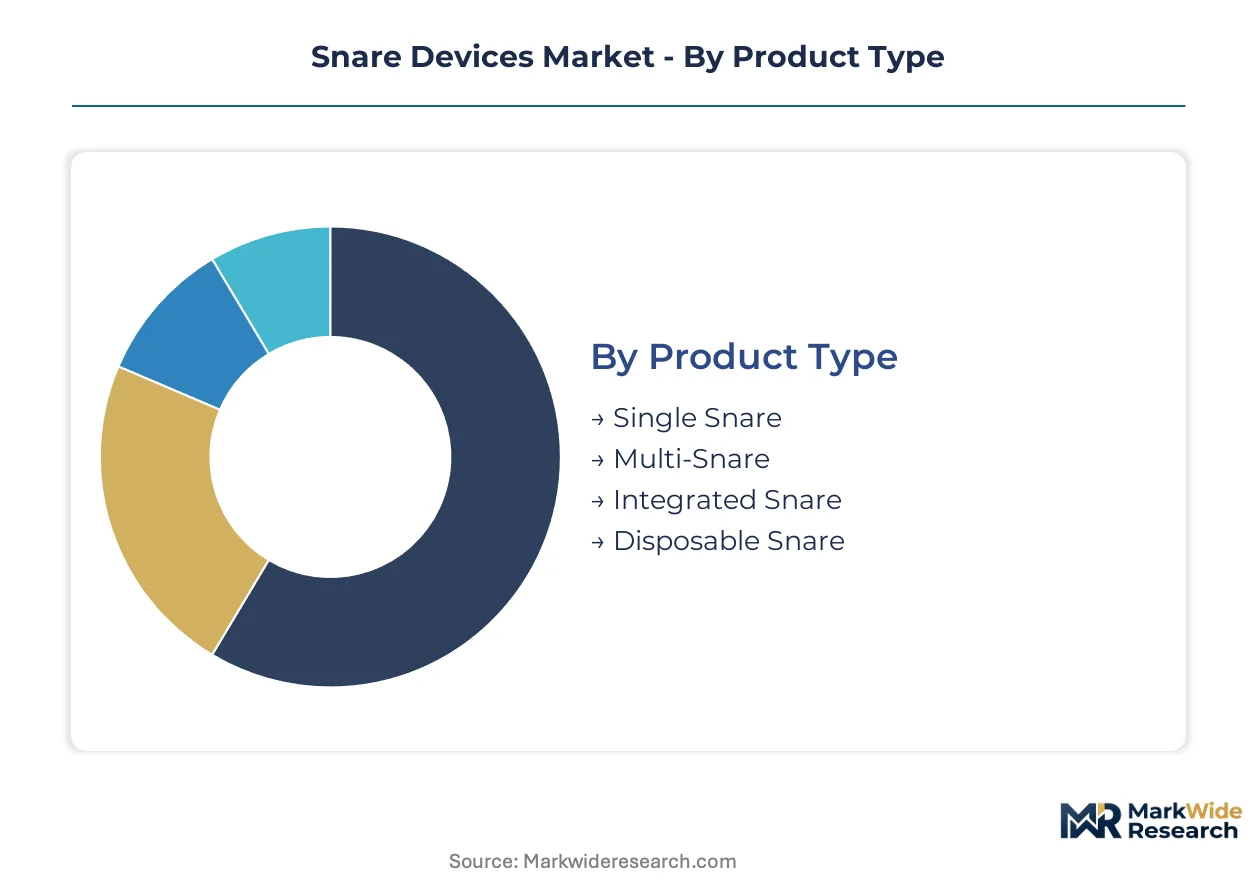
Snare device procurement splits sharply between disposable biosecurity protocols and reusable heavy-duty applications. Understanding where upgrade cycles accelerate versus where replacement stretches across years clarifies vendor resource allocation and R&D prioritization.
Product Type:
Upgrade cycles vary dramatically across product configurations, with disposable formats driving annual procurement volume while integrated systems command extended replacement timelines and premium positioning.
- Single Snare:Individual loop mechanisms constructed from aircraft-grade steel cable or polymer filaments rated for calibrated breaking strengths. United States federal land management contracts absorb the majority of volume, prioritizing rapid deployment simplicity and minimal field maintenance requirements over multi-capture efficiency.
- Multi-Snare:Simultaneous capture arrays engineered for research specimen collection efficiency. Research institutions in Germany and France are consolidating vendor relationships around these systems, reducing per-capture labor hours and transport logistics through coordinated sample protocols.
- Integrated Snare:Sensor-equipped configurations with remote monitoring capabilities for real-time capture alerts.
- Disposable Snare:Single-use polymer configurations eliminating cross-contamination risks in disease surveillance operations.
Volume placements concentrate in Single Snare configurations; the faster expansion belongs to Disposable Snare formats.
Application:
Application segmentation reveals divergent cost tiers, with pest control absorbing commodity-grade steel products while rehabilitation commands premium composite alternatives at substantially higher unit economics.
- Wildlife Management:Population control and relocation operations across terrestrial ecosystems. Government agencies in the United States are unbundling equipment procurement from service contracts, opening direct vendor relationships for specialized configurations.
- Research:Scientific specimen collection requiring precise tissue preservation and minimal capture trauma. Research institutions prioritize ISO 10993 biocompatibility compliance, creating crossover demand from veterinary surgical retrieval applications.
- Pest Control:Heavy-duty elimination protocols favoring absolute load capacity over tissue impact considerations.
- Rehabilitation:Endangered species recovery programs absorbing composite alternatives with reduced tissue impact.
Cost tiers stratify sharply: Pest Control anchors volume at commodity pricing; Rehabilitation generates the steepest expansion trajectory through premium positioning.
Material:
Material selection reflects supply concentration dynamics, with steel grades dependent on limited specialty producer bases while polymer formulations require ECHA REACH compliance investments.
- Steel:Aircraft-grade cable retaining dominance in heavy-duty load scenarios despite weight and corrosion penalties. EPA guidelines on wildlife interaction protocols are tightening material compliance standards, forcing requalification of metallurgy under compressed timelines.
- Nylon:High-tensile synthetic filaments offering intermediate strength-to-weight ratios for general-purpose deployment.
- Composite:Engineered polymer filaments with calibrated breaking strengths and reduced tissue impact. Wildlife rehabilitation centers are adopting these at accelerating pace despite per-unit cost premiums, displacing steel in capture-and-release trauma-sensitive protocols.
- Aluminum:Lightweight structural components for portable field deployment frames.
Supply concentrates in Steel grades; share gains are climbing the fastest in Composite formulations.
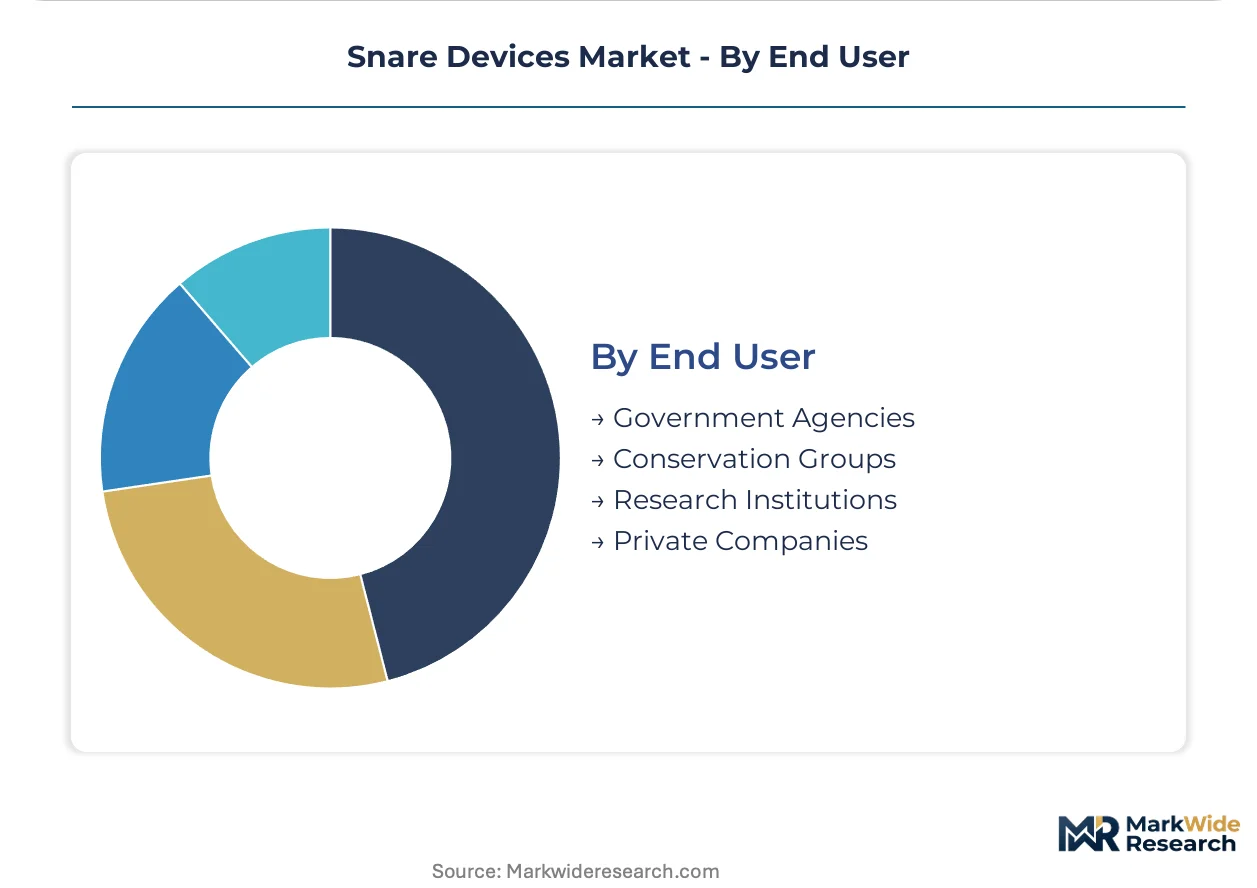
End User:
End user segmentation tracks procurement authority centralization, with government agencies consolidating vendor pools while private companies fragment across regional distributors.
- Government Agencies:Federal and state wildlife management authorities with standardized certification requirements. United States agencies are expanding adoption of humane capture systems, with procurement concentrating through federal land management contracts and state-level conservation programs.
- Conservation Groups:Non-profit organizations operating under endangered species protocols with premium sensitivity to tissue impact.
- Research Institutions:Universities and field stations prioritizing simultaneous sample collection efficiency and biosecurity compliance.
- Private Companies:Commercial pest control operators and agricultural protection services.
Procurement authority centralizes in Government Agencies; Conservation Groups are expanding most quickly through EU Green Deal biodiversity funding channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denver anchors North American snare device procurement through concentrated federal land management contracting infrastructure and proximity to Rocky Mountain wildlife corridors.
United States
Federal land management contracts and state-level conservation programs absorb the majority of domestic volume. EPA guidelines on wildlife interaction protocols are tightening material compliance standards across procurement channels. Colorado and Montana field stations are unbundling equipment supply from integrated capture services, enabling direct manufacturer relationships.
Germany
Veterinary research centers in Munich and Berlin are consolidating vendor relationships around multi-snare systems for simultaneous sample collection efficiency. ECHA REACH compliance requirements govern polymer and coating substance approvals for European distribution. Baden-Württemberg rehabilitation centers are adopting composite alternatives with reduced tissue impact at accelerating pace.
France
EU Green Deal biodiversity restoration targets are recalibrating procurement standards across conservation agencies toward humane capture systems. ANSM oversees device safety frameworks affecting cross-border distribution. The Auvergne-Rhône-Alpes corridor hosts specialized research institutions prioritizing ISO 10993 biocompatibility compliance for tissue-contacting configurations.
Canada
Provincial wildlife management authorities are expanding adoption of humane capture systems through Health Canada-influenced procurement protocols. PMRA guidelines on wildlife interaction materials are tightening compliance timelines for steel and polymer formulations. Alberta and British Columbia field operations are concentrating demand for disposable configurations eliminating cross-contamination risks.
Australia
TGA biocompatibility standards are shaping material selection for snare devices contacting mammalian tissue in research applications. Queensland and New South Wales rehabilitation centers are absorbing composite snare alternatives despite per-unit cost premiums. The country's national wildlife agency mandates on humane capture certification are tightening qualification requirements for imported equipment.
Snare Devices Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification documentation and rapid fulfillment infrastructure. The vendor base stratifies into three tiers: diversified medical device conglomerates with polymer science capabilities, specialized surgical instrument fabricators with veterinary crossover expertise, and regional equipment suppliers serving unbundled government contracts. Dominant competitive moves include R&D partnerships with veterinary research centers and consolidation of supplier relationships around pre-registered substance portfolios for ECHA REACH compliance.
Within the diversified medical device tier, Medtronic plc, Boston Scientific Corporation, and Cook Medical exemplify archetypes leveraging polymer science expertise and regulatory compliance infrastructure. Medtronic occupies a position representing composite material development capabilities, while Boston Scientific anchors the European partnership model with veterinary research centers. Cook Medical sits within the specialized configuration segment, exemplifying differentiation through single-snare formats designed for sensitive capture protocols.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Olympus Corporation |
| Cook Medical |
| CONMED Corporation |
| Medline Industries, Inc. |
| Steris |
| Merit Medical Systems |
| Fujifilm Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
Aircraft-grade steel cable price volatility cascades through snare device manufacturing, compressing margins on heavy-duty steel configurations while amplifying pricing power for polymer alternatives certified under EPA wildlife interaction protocols. Procurement officers at United States federal land management agencies face escalating cost differentials between commodity steel grades and REACH-compliant composite formulations, forcing budget reallocation across disposable and reusable program lines.
Pricing Analysis
Certification-grade pricing anchors snare device valuation, with ISO 10993 biocompatibility compliance and humane capture certification commanding substantial premiums over uncertified commodity alternatives. Price differentiation separates trauma-minimized composite configurations for endangered species protocols from standard steel deployments in pest control applications. Cost compression in heavy-duty steel tiers intensifies because specialty metallurgy supply concentrates among limited producer bases, exposing manufacturers to input cost swings. Government agencies exhibit lowest price sensitivity due to mandate-driven procurement, while private pest control operators absorb greatest margin pressure.
Supply Chain Analysis
Domestic-content mandates in United States federal contracting are reshaping sourcing patterns, compelling manufacturers to qualify alternative metallurgy from North American mills rather than traditional European or Asian specialty steel suppliers. Aircraft-grade steel cable concentrates in United States, Germany, and Japan production facilities, while high-tensile polymer filaments draw from South Korean and Chinese chemical synthesis clusters. Supply chain risk centers on single-source vulnerability for certified steel grades meeting EPA wildlife interaction protocols. Distribution runs through government procurement portals and specialized veterinary equipment distributors serving research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Snare device supply remains constrained by polymer science talent scarcity, with certified composite development capacity propping pricing premiums across rehabilitation and research segments.
For Market Incumbents: To counter emerging composite specialists capturing endangered species protocol share, medical device conglomerates should deepen R&D partnerships with veterinary research centers in Germany and France while consolidating backward integration into pre-registered REACH substance libraries. Capacity addition in United States domestic steel qualification infrastructure protects federal contract positioning against procurement localization mandates. For New Entrants and Emerging Players: Enter via state-level conservation program unbundling in Colorado and Montana, where direct manufacturer relationships are displacing integrated service contractors. The most penetrable segment lies in disposable snare configurations for disease surveillance operations, with biosecurity compliance as the primary go-to-market angle against established reusable-system vendors. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized surgical instrument fabricators with veterinary crossover expertise in European jurisdictions, where ECHA compliance investments have strained mid-tier supplier balance sheets. Long-term viability hinges on dual-market qualification spanning wildlife management and veterinary surgical retrieval. The signal to watch is EPA guideline finalization on wildlife interaction protocols, which will trigger requalification spending waves and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Substance Portfolio Consolidation | ECHA pre-registered libraries eliminate registration cost duplication for European distribution channels. |
| Veterinary Research Center Partnership | R&D alliances with Munich and Berlin institutions accelerate composite snare development timelines. |
| Federal Procurement Portal Direct Access | Unbundled government contracts enable margin capture previously absorbed by integrated service providers. |
| ISO 10993 Biocompatibility Certification | Dual-market qualification opens veterinary surgical retrieval applications alongside wildlife management. |
| Domestic Steel Mill Qualification | United States federal contracting mandates prioritize North American metallurgy sourcing. |
Study Parameters
Trade databases, EPA regulatory filings, and ECHA substance registration records formed the secondary backbone, cross-referenced against primary interviews with wildlife agency procurement officers, veterinary research center directors, polymer science specialists, and biomedical equipment distributors. Bottom-up demand modeling from federal land management contract awards and state conservation program budgets combined with top-down market sizing from medical device regulatory filings to establish volume and value parameters.
Historical trendline analysis across steel cable pricing indices and polymer filament cost curves informed growth trajectory projections over the analysis window. Segmentation modeling incorporated product type, material grade, application protocol, and end-user procurement authority dimensions. CAGRs were derived from weighted average of equipment replacement cycles and unbundled contract expansion rates, with veterinary surgical retrieval crossover demand and EU Green Deal biodiversity funding trajectories as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA guideline implementation or specialty steel supply disruption scenarios. Forecasts reflect documented assumptions regarding certification timeline compression and procurement unbundling velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Smart Syringe Market
Medical Devices
ADA Substitute Market
Medical Devices
Global Liposuction Surgery Devices Market
Medical Devices
Uterine Fibroid Embolization Devices Market
Medical Devices
Global Obstetrics Devices Market
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market
Medical Devices
Global Robotic Nurse Assistant Market
Medical Devices
Spectacle Lens Market
Medical Devices
Esophagoscopes and Gastroscopes Market
Medical Devices
Defibrillator Pads Market
Medical Devices
Non-Invasive Brain Trauma Monitoring Devices Market
Medical Devices
Clear Aligners Market
Medical Devices
Bone Allografts Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
Silastic Implant Market