
 Gastrointestinal Drugs Market | 2026-2036
Gastrointestinal Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Gastrointestinal Drugs Market Intelligence
The FDA's accelerated approval pathways for orphan gastrointestinal indications is rebalancing how pharmaceutical firms allocate clinical development budgets toward smaller patient populations with higher unmet need. Takeda Pharmaceutical anchors its position through deep specialization in inflammatory bowel disease biologics. AbbVie Inc. leverages its immunology infrastructure to sustain competitive presence across Crohn's disease and ulcerative colitis indications. AstraZeneca competes through targeted investment in novel acid-related disorder mechanisms.
Gastrointestinal drugs comprise pharmaceutical agents formulated to modulate digestive system function through mechanisms including acid suppression, motility regulation, anti-inflammatory action, and microbiome modification, with formulations ranging from immediate-release tablets to parenteral biologic preparations requiring cold-chain distribution. These therapeutics serve to treat or manage conditions from benign reflux to life-threatening autoimmune enteropathies in acute, chronic, and maintenance care settings. Proton pump inhibitors occupy the largest volume position within the drug class segmentation, though biologic agents for ulcerative colitis and Crohn's disease capture disproportionate value pools due to pricing power and chronic administration profiles. Oral administration dominates prescription volume across target conditions, while intravenous delivery concentrates in hospital and infusion center settings where biologic therapies require supervised administration.
The FDA maintains stringent bioequivalence requirements for generic proton pump inhibitors, while EMA's MDR framework imposes escalating clinical evidence standards on biologic gastrointestinal therapies seeking European market access. Health Canada's PMRA aligns with FDA pharmacovigilance protocols for post-market surveillance of acid-suppressing agents linked to long-term nutritional deficiencies. Stakeholders must monitor how evolving regulatory divergence across these jurisdictions affects portfolio prioritization and launch sequencing decisions.
Market Dynamics
Biologic patent cliffs and biosimilar entry waves are compressing pricing power across inflammatory bowel disease portfolios while redirecting R&D investment toward novel mechanism targets. Hospital formulary consolidation and specialty pharmacy network dominance are concentrating buyer leverage, forcing manufacturers to restructure access and rebate strategies around integrated delivery system procurement.
Growth Catalysts
- FDA Accelerated Approval:Orphan gastrointestinal indications now qualify for expedited review pathways, reducing clinical development timelines and enabling earlier revenue recognition for sponsors targeting small patient populations with unmet need.
- Japan's Elderly Demographics:PMDA reimbursement incentives for chronic disease management therapies are expanding the addressable patient base for maintenance biologic regimens in ulcerative colitis and Crohn's disease.
- Microbiome Modulation:Fecal microbiota transplantation standardization and live biotherapeutic product pipelines are opening mechanistically distinct therapeutic categories beyond conventional immunosuppression.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for proton pump inhibitors concentrates in Chinese chemical synthesis clusters, exposing formulators to geopolitical disruption and environmental compliance shutdowns.
- EMA MDR Escalation:European medical device regulation reclassification of drug-device combination products is extending approval timelines and inflating clinical evidence requirements for novel delivery systems.
- Oral Small Molecule Substitution:JAK inhibitor tablets for ulcerative colitis are capturing maintenance therapy share from injectable biologics, threatening infusion center revenue models and cold-chain logistics investments.
Strategic Opportunities
- India's Biosimilar Export:CDSCO streamlined approval pathways for reference biologics are positioning domestic manufacturers to supply regulated markets with infliximab and adalimumab alternatives at substantial discounts.
- Digital Therapeutics Integration:Prescription digital therapeutics for irritable bowel syndrome are gaining FDA breakthrough device designation, creating combination therapy bundles with pharmacologic agents.
- Point-of-Care Diagnostics:Fecal calprotectin and lactoferrin rapid tests are enabling treatment escalation decisions in primary care settings, expanding biologic initiation beyond gastroenterology specialist gatekeepers.
Industry Challenges
- Biologics Manufacturing Talent:Cell culture and aseptic fill-finish expertise scarcity is constraining capacity expansion for monoclonal antibody production, particularly for complex glycosylated molecules.
- Cold-Chain Integrity:Temperature excursion monitoring and remediation protocols for parenteral biologics are requiring substantial infrastructure investment across distribution networks, with zero-tolerance specifications for high-value vials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastrointestinal Drugs Market |
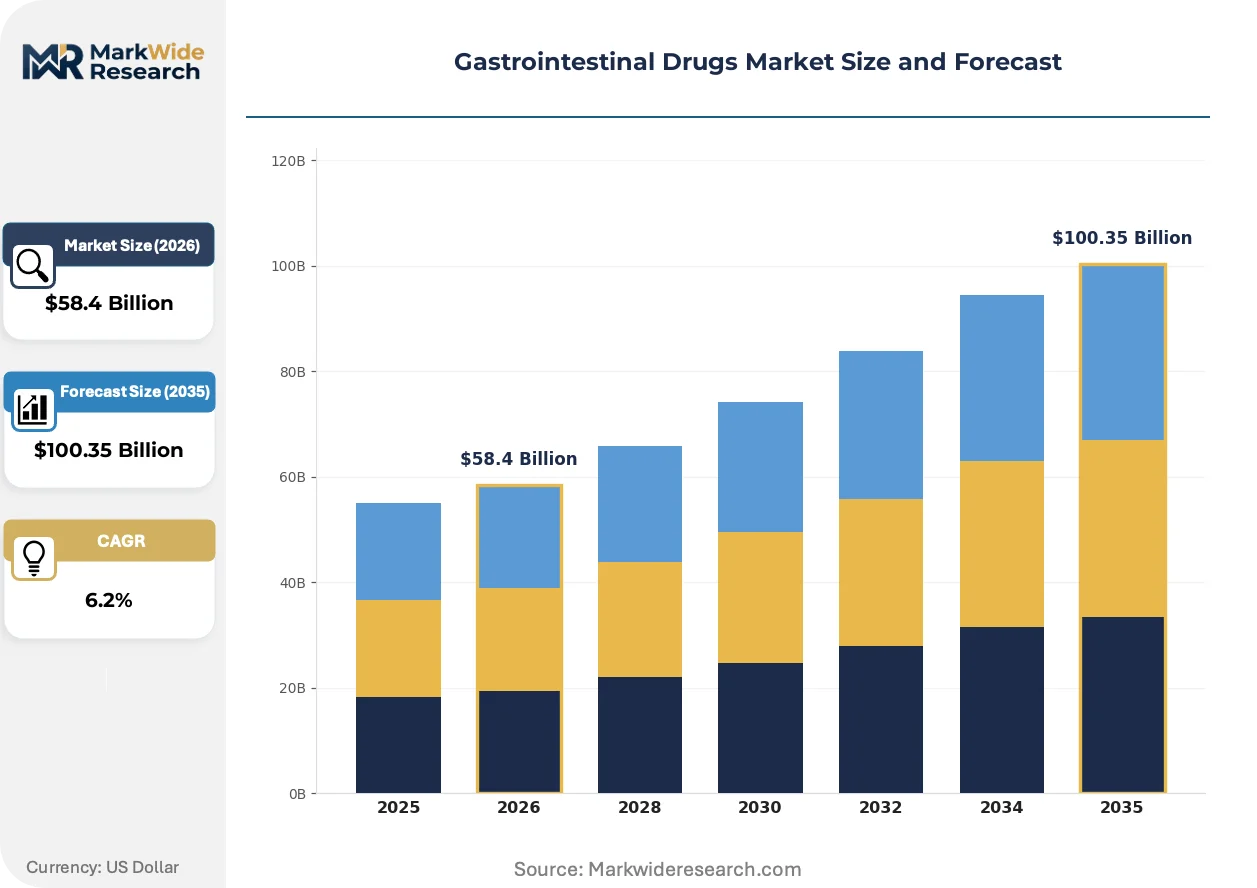
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $100.35 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Antacids, H2-Receptor Antagonists, Proton Pump Inhibitors, Laxatives Target Condition: Gastroesophageal Reflux Disease, Irritable Bowel Syndrome, Ulcerative Colitis, Crohn's Disease Administration Route: Oral, Intravenous, Rectal, Sublingual End User: Hospitals, Clinics, Retail Pharmacies, Homecare |
| Companies Covered | Takeda Pharmaceutical, AbbVie Inc., AstraZeneca, GlaxoSmithKline Plc, Bayer AG, Allergan Plc., Boehringer Ingelheim GmbH, Johnson & Johnson Services Inc., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastrointestinal Drugs Market Strategic Shifts & Innovations
Novel target discovery platforms and real-world evidence generation capabilities are compressing the gap between mechanistic insight and commercial therapeutic availability. Biopharmaceutical firms are restructuring development organizations around precision gastroenterology indications.
Antibody engineering platforms are modularizing construct design for gut-selective immunomodulation. Takeda and AbbVie are advancing Fc-engineered biologics with tissue-restricted activity profiles. This architectural flexibility is modularizing the pipeline, enabling rapid iteration on target-binding domains while retaining validated effector mechanisms.
EMA's MDR framework is elevating clinical evidence standards for biologic gastrointestinal therapies seeking European market access. Sponsors must now generate comparative effectiveness data against established standards rather than placebo-controlled trials. Ulcerative colitis biologics with existing FDA approvals are delaying EU launches to accumulate the required head-to-head datasets.
Integrated delivery systems in the United States are consolidating specialty pharmacy dispensing and prior authorization management under single vendor relationships. Hospital-owned specialty pharmacies are capturing biologic fulfillment from independent channels, compressing manufacturer access to patient adherence data and switching the locus of formulary negotiation from physician practices to system-level pharmacy committees.
Gastrointestinal Drugs Market Segmentation
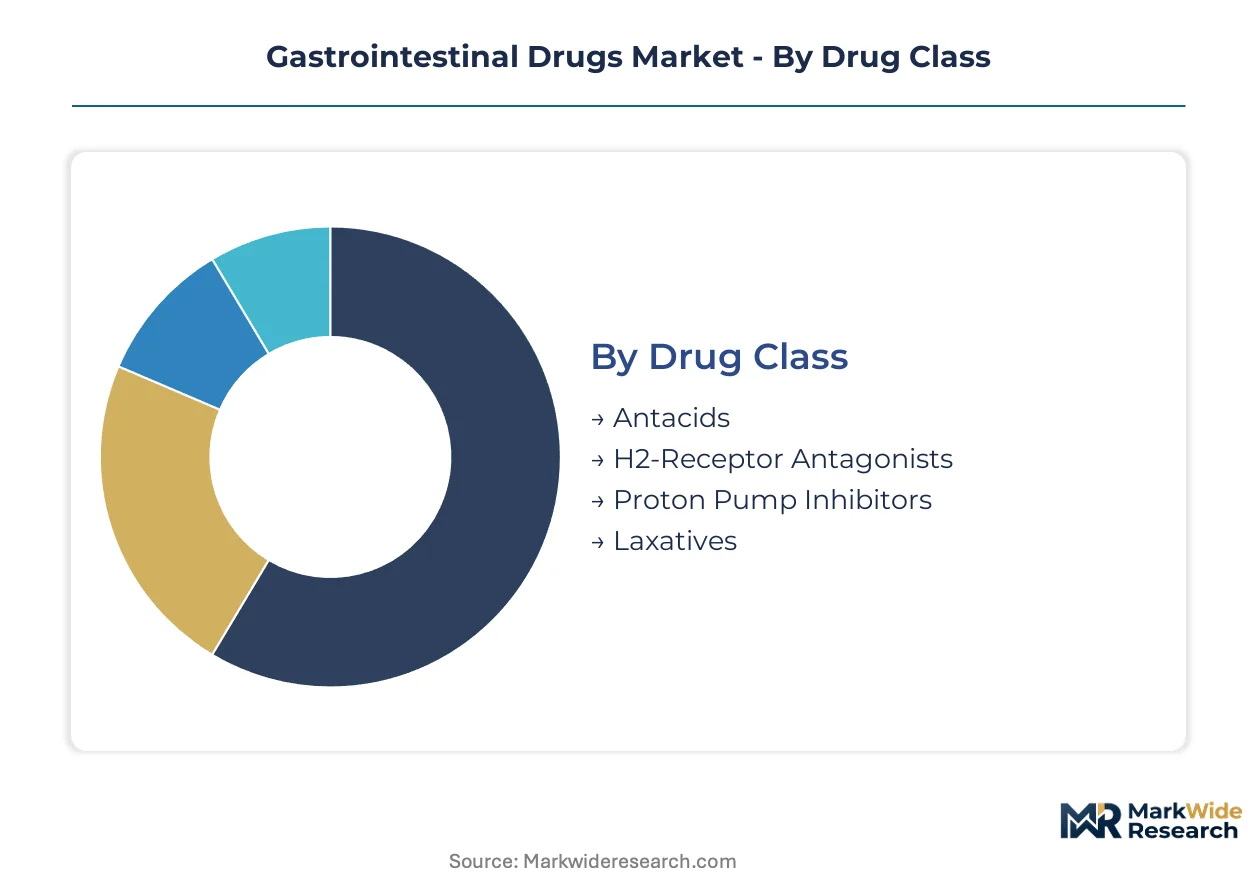
Gastrointestinal drug portfolios require precise segmentation alignment with regulatory pathways and reimbursement structures. Each dimension carries distinct certification burdens that determine commercial viability and launch sequencing across jurisdictions.
Drug Class:
FDA bioequivalence requirements vary sharply across this category, with proton pump inhibitors facing the most stringent generic substitution protocols while laxatives navigate OTC monograph pathways.
- Proton Pump Inhibitors:Omeprazole, esomeprazole, and lansoprazole formulations suppress gastric acid through irreversible H+/K+ ATPase inhibition. Demand concentrates in ambulatory care settings across the United States where step-therapy protocols mandate failure of H2-antagonists before authorization. FDA requires multiple bioequivalence studies for generic entrants due to the complex pharmacokinetics of enteric-coated formulations.
- H2-Receptor Antagonists:Ranitidine withdrawal reshaped this segment toward famotidine and cimetidine dominance. Hospital formularies in Japan favor these agents for stress ulcer prophylaxis in intensive care units where drug-drug interaction profiles prove more manageable than PPI alternatives.
- Antacids:Aluminum and magnesium hydroxide combinations provide immediate symptomatic relief without prescription requirements.
- Laxatives:Bulk-forming, osmotic, and stimulant subclasses serve distinct constipation etiologies with varying onset profiles.
Leading the category by volume: Proton Pump Inhibitors. Expanding most quickly: H2-Receptor Antagonists as ranitidine replacement demand persists.
Target Condition:
Orphan drug designation eligibility and accelerated approval pathways cluster heavily toward autoimmune indications, reshaping R&D allocation toward smaller patient populations with premium pricing tolerance.
- Ulcerative Colitis:Chronic mucosal inflammation limited to the colon drives biologic maintenance therapy demand. Takeda's vedolizumab and AbbVie's adalimumab anchor formulary positions in United States integrated delivery systems where prior authorization complexity favors established agents with streamlined reimbursement protocols.
- Crohn's Disease:Transmural inflammation affecting any gastrointestinal segment requires more aggressive immunosuppression. Fistulizing complications in German and French hospital systems sustain infliximab infusion center volumes despite biosimilar pressure.
- Gastroesophageal Reflux Disease:Erosive and non-erosive subtypes drive the largest prescription volume globally.
- Irritable Bowel Syndrome:IBS-C and IBS-D subtypes demand mechanistically distinct therapeutic approaches with mixed serotonin modulation.
By revenue concentration: Ulcerative Colitis. Steepest expansion trajectory: Crohn's Disease as pediatric indications expand.
Administration Route:
Supply chain infrastructure investments diverge dramatically between ambient-distribution oral solids and cold-chain-dependent parenteral biologics.
- Oral:Immediate-release tablets, enteric-coated formulations, and multiparticulate systems dominate prescription volume. Indian CDSCO streamlined approvals for fixed-dose combinations are accelerating domestic manufacturer entry into regulated export markets.
- Intravenous:Monoclonal antibody infusions require supervised administration in hospital or certified infusion center settings. Temperature excursion protocols mandate continuous monitoring across distribution networks from manufacturing through patient administration.
- Rectal:Suppositories and enemas serve distal colonic disease with topical corticosteroid and mesalamine formulations.
- Sublingual:Rapid absorption bypasses first-pass metabolism for select antiemetic applications.
By prescription volume: Oral. Gaining share fastest: Intravenous as subcutaneous biologic alternatives expand self-administration options.
End User:
Procurement leverage concentrates in institutional channels where formulary consolidation and specialty pharmacy integration reshape manufacturer access strategies.
- Hospitals:Inpatient and outpatient departments capture high-acuity cases requiring parenteral biologics. United States health system specialty pharmacies are consolidating prior authorization management and dispensing under single vendor relationships, compressing independent pharmacy channel share.
- Retail Pharmacies:Community dispensing dominates oral maintenance therapy for GERD and IBS. Japan's elderly population concentration sustains high prescription frequency for chronic acid suppression regimens.
- Clinics:Gastroenterology specialist practices serve as biologic initiation gatekeepers.
- Homecare:Subcutaneous biologic self-administration and enteral nutrition support expand beyond institutional settings.
Dominant by volume: Hospitals. Climbing fastest: Homecare as patient-administered biologic formulations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech corridor anchors North American gastrointestinal drug development, with the Massachusetts cluster housing concentrated inflammatory bowel disease trial infrastructure and specialized infusion center networks.
United States
Specialty pharmacy consolidation and integrated delivery system procurement dominate biologic access. FDA accelerated approval pathways for orphan gastrointestinal indications compress development timelines for sponsors targeting ulcerative colitis and Crohn's disease. The Research Triangle Park corridor in North Carolina sustains contract manufacturing capacity for monoclonal antibody production serving hospital formulary networks.
Germany
Fistulizing Crohn's disease complications sustain infliximab infusion center volumes in university hospital systems. EMA MDR framework reclassification extends approval timelines for novel drug-device combination products. The Rhine-Main biopharma cluster around Frankfurt anchors European clinical trial operations for gut-selective immunomodulation programs.
Japan
PMDA reimbursement incentives for chronic disease management expand maintenance biologic regimens in elderly ulcerative colitis populations. METI industrial policy supports domestic fermentation capacity for biosimilar production. The Kanto region surrounding Tokyo concentrates gastroenterology specialist practices and prior authorization infrastructure.
India
CDSCO streamlined approval pathways for reference biologics position domestic manufacturers to supply regulated export markets. API synthesis clusters in Hyderabad and Ahmedabad concentrate proton pump inhibitor intermediate production. Gujarat's pharmaceutical manufacturing belt expands fill-finish capacity for oral solid dosage forms targeting North American generic substitution demand.
Switzerland
Swissmedic pharmacovigilance protocols align with FDA post-market surveillance standards for acid-suppressing agents. Basel's biopharma corridor anchors antibody engineering platforms for tissue-restricted gastrointestinal biologics. The country's precision manufacturing infrastructure supports aseptic processing for high-value parenteral formulations requiring cold-chain integrity.
Gastrointestinal Drugs Market Key Industry Players
The competitive structure tilts toward diversified pharmaceutical conglomerates with immunology infrastructure. Patent cliffs and biosimilar entry waves compress pricing power across inflammatory bowel disease portfolios. Three archetypes dominate: biologic specialists with deep IBD specialization, diversified immunology players leveraging cross-indication platforms, and acid suppression incumbents defending genericized proton pump inhibitor volumes. M&A activity concentrates on microbiome modulation assets and digital therapeutics capabilities, while capacity expansion focuses on cell culture and aseptic fill-finish infrastructure.
Among the biologic specialist tier, Takeda Pharmaceutical and AbbVie Inc. exemplify platform-driven IBD strategies, with the former anchoring deep specialization in inflammatory bowel disease biologics and the latter leveraging immunology infrastructure across Crohn's disease and ulcerative colitis indications. AstraZeneca occupies a position among mechanism-focused acid-related disorder players, representing targeted investment in novel therapeutic targets beyond conventional suppression pathways.
| Leading Market Players |
|---|
| Takeda Pharmaceutical |
| AbbVie Inc. |
| AstraZeneca |
| GlaxoSmithKline Plc |
| Bayer AG |
| Allergan Plc. |
| Boehringer Ingelheim GmbH |
| Johnson & Johnson Services Inc. |
| Sanofi |
| Others |
Cost & Logistics Intelligence
Hospital formulary consolidation across United States integrated delivery systems is compressing manufacturer rebate margins and forcing supply chain restructuring toward direct specialty pharmacy relationships that bypass independent wholesale channels.
Pricing Analysis
Value-based contracting tied to mucosal healing endpoints anchors biologic pricing for ulcerative colitis therapies. Three-tier pricing structure across originator biologics, biosimilars, and oral small molecules separates premium infusion center products from self-administered alternatives. Price differentiation hinges on FDA breakthrough designation status and cold-chain reliability certification. Cost compression in the biosimilar tier is intensifying because AbbVie and Takeda have accelerated adalimumab and infliximab reference product discounts ahead of patent expiry. Retail pharmacy channels show highest price sensitivity, while hospital specialty pharmacies tolerate premium positioning for formulary exclusivity.
Supply Chain Analysis
India's PLI scheme for active pharmaceutical ingredients is reshaping proton pump inhibitor intermediate sourcing away from sole reliance on Chinese chemical synthesis clusters. API manufacturing draws from Hyderabad and Ahmedabad fermentation capacity, while biologic fill-finish rests on Swiss and German aseptic processing infrastructure. Supply chain risk centers on single-source vulnerability for enteric coating polymers used in delayed-release formulations. Distribution runs through temperature-controlled logistics networks where hospital-owned specialty pharmacies capture fulfillment from independent channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gastrointestinal therapeutics is transitioning from chronic immunosuppression toward microbiome-modulating live biotherapeutics, with fecal microbiota transplantation standardization displacing conventional maintenance biologic regimens in ulcerative colitis.
For Market Incumbents: Acquire microbiome modulation platforms and digital therapeutics capabilities to offset biosimilar pressure on anti-TNF franchises. Takeda and AbbVie must defend vedolizumab and risankizumab positioning through backward integration into cell culture capacity in the Research Triangle Park corridor, securing monoclonal antibody supply against talent scarcity in aseptic fill-finish operations. For New Entrants and Emerging Players: Capture the irritable bowel syndrome digital therapeutics white space where FDA breakthrough device designation creates reimbursement pathways without competing against established biologic formularies. India's CDSCO streamlined biosimilar approvals offer the most penetrable regulatory entry point for adalimumab alternatives targeting North American specialty pharmacy networks through contract manufacturing partnerships. For Investors and Strategic Acquirers: The window for entry favors precision gastroenterology platform companies with gut-selective antibody engineering capabilities over generic proton pump inhibitor manufacturers facing API supply concentration risks. Watch fecal calprotectin point-of-care diagnostic adoption rates as the signal indicating biologic initiation expansion beyond gastroenterology specialist gatekeepers.| Strategic Initiative | Industry Significance |
|---|---|
| Microbiome Platform Acquisition | Live biotherapeutic pipelines diversify beyond immunosuppression mechanisms for ulcerative colitis maintenance. |
| Cold-Chain Infrastructure Investment | Temperature excursion monitoring secures parenteral biologic integrity across United States distribution networks. |
| Digital Therapeutics Integration | Prescription software bundles with pharmacologic agents create differentiated IBS treatment protocols. |
| Biosimilar Manufacturing Scale-Up | Indian CDSCO approvals enable regulated market entry for infliximab alternatives at substantial discounts. |
| Point-of-Care Diagnostic Partnership | Fecal calprotectin rapid tests expand biologic initiation into primary care settings beyond specialist gatekeepers. |
Research Approach
Independent corroboration across FDA accelerated approval filings, EMA MDR submission databases, and United States hospital formulary records underwrites the qualitative findings. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists combined with secondary validation from ClinicalTrials.gov, SEC 10-K disclosures, and GPO contract databases. Bottom-up prescription volume modeling and top-down therapeutic class revenue estimates triangulate market sizing.
Comparable-period anchoring to historical biologic launch trajectories and biosimilar entry patterns structured the projection horizon. The analytical framework segments by drug class, target condition, administration route, and regional regulatory cluster. CAGRs derive from patent expiry schedules, accelerated approval pathway utilization rates, and formulary consolidation velocity across integrated delivery systems. Forecast inputs include PMDA reimbursement incentive changes and CDSCO biosimilar approval timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA orphan indication pathway reforms and EMA MDR evidentiary requirement escalations. Assumptions underlying volume projections reflect current formulary structures and prior authorization complexity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Biliary Tract Cancers (Btcs) Treatment Market
Gastroenterology
Digestive Health Market
Gastroenterology
Gluten Intolerance Treatment Market
Gastroenterology
Gastroretentive Drug Delivery Systems Outsourcing Market
Gastroenterology
Ultrasound Gastroscopes Market
Gastroenterology
Gastroesophageal Reflux Disease Therapeutics Market
Gastroenterology
Inflammatory Bowel Disease Treatment Market
Gastroenterology
Digestive Health Products Market
Gastroenterology
Helicobacter Pylori Infections Treatment Market
Gastroenterology
Polyps Market
Gastroenterology
Peptic Ulcer Market
Gastroenterology
Chronic Liver Diseases Therapeutics Market
Gastroenterology
Crohns Disease Therapeutics Market
Gastroenterology
Gastritis Treatment Market
Gastroenterology
Anal Fissure Treatment Market
Gastroenterology
Diverticular Disease Therapeutics Market