
 United States General Surgical Devices Market | 2026-2036
United States General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States General Surgical Devices Market Analytics
Market Context with Strategic Players
Device-as-a-service models encompassing preventive maintenance and software-defined upgrade paths is rebalancing how hospitals commit capital. Stryker Corporation leverages its service infrastructure to extend customer lifetime value across installed bases. Medtronic anchors its position through intensive R&D allocation toward minimally invasive platforms. Johnson & Johnson differentiates via brand strength in sutures and wound closure, competing for preference in integrated delivery networks.
Technical Definition and Structural Segments
General surgical devices encompass reusable and single-use instruments, drapes, sutures, gloves, and powered equipment designed for tissue manipulation, hemostasis, and wound closure, typically manufactured from medical-grade stainless steel, polymers, or nitinol with tolerances measured in millimeters for precision performance. These tools serve hospitals, ambulatory surgical centers, and specialty clinics performing procedures ranging from routine appendectomy to complex thoracic intervention. Surgical instruments and sutures occupy mature margin pools sustained by high replacement frequency, while robotic surgery and laparoscopic surgery platforms represent the fastest-growing technology segments as facilities convert open procedures to minimally invasive protocols. Electrosurgical devices command premium positioning within the technology hierarchy due to their integration with generator systems and disposable electrode dependence.
Regulatory Framework and Forward Outlook
FDA 510(k) clearance pathways, EPA sterilization emission standards, and OSHA bloodborne pathogen regulations collectively shape product design, manufacturing location decisions, and facility compliance costs across the United States. The Centers for Medicare & Medicaid Services reimbursement schedules further filter which device categories achieve rapid clinical uptake versus prolonged adoption curves. Stakeholders must monitor how FDA's evolving substantial equivalence criteria and anticipated quality system regulation harmonization affect pipeline timelines and competitive positioning.
Market Dynamics
Device-as-a-service contracting is compressing capital cycles for ambulatory surgical centers, forcing manufacturers to reprice hardware around utilization metrics rather than upfront purchase premiums.
Growth Catalysts
- CMS outpatient reimbursement expansion:Medicare payment parity for select procedures performed in ASCs is redirecting case volumes away from inpatient settings and expanding addressable demand for portable surgical equipment.
- Robotic-assisted surgery platforms:Intuitive Surgical's installed base expansion and competitor system launches are converting open abdominal and thoracic procedures to minimally invasive protocols, requiring complementary instrument ecosystems.
- Southeast hospital construction boom:Greenfield medical facility development across Florida, Texas, and Georgia is generating concentrated procurement windows for turnkey surgical suites and associated device packages.
Market Restraints
- Medical-grade stainless steel price volatility:Nickel and chromium input cost swings are compressing margins on reusable instrument portfolios that lack contractual pass-through mechanisms.
- FDA 510(k) substantial equivalence tightening:Enhanced scrutiny of predicate device comparisons is extending clearance timelines for iterative product modifications and delaying revenue recognition.
- Single-use polymer waste regulations:State-level environmental mandates in California and New York are imposing compliance costs on disposable instrument manufacturers without viable material substitutes at scale.
Strategic Opportunities
- Rural hospital outsourcing partnerships:Critical access facilities in the Mountain West and Great Plains are contracting perioperative services to regional health systems, creating bundled device-and-service procurement channels.
- AI-enabled surgical navigation:Machine vision integration with laparoscopic towers is enabling real-time tissue identification and reducing conversion rates to open procedures.
- IRA domestic manufacturing incentives:Clean energy tax credits and domestic content bonuses are subsidizing reshoring of electrosurgical generator production and electrode assembly operations.
Industry Challenges
- Biomedical technician specialization gaps:Robotic system maintenance requires vendor-certified expertise that rural ASCs struggle to recruit and retain, driving reliance on manufacturer service contracts.
- Interoperability with legacy EMR systems:Smart instrument data streams lack standardized APIs, forcing custom integration projects that delay connected device deployments.
- Ethylene oxide sterilization capacity constraints:EPA emission restrictions on EtO facilities are creating regional bottlenecks for single-use device terminal sterilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States General Surgical Devices Market |
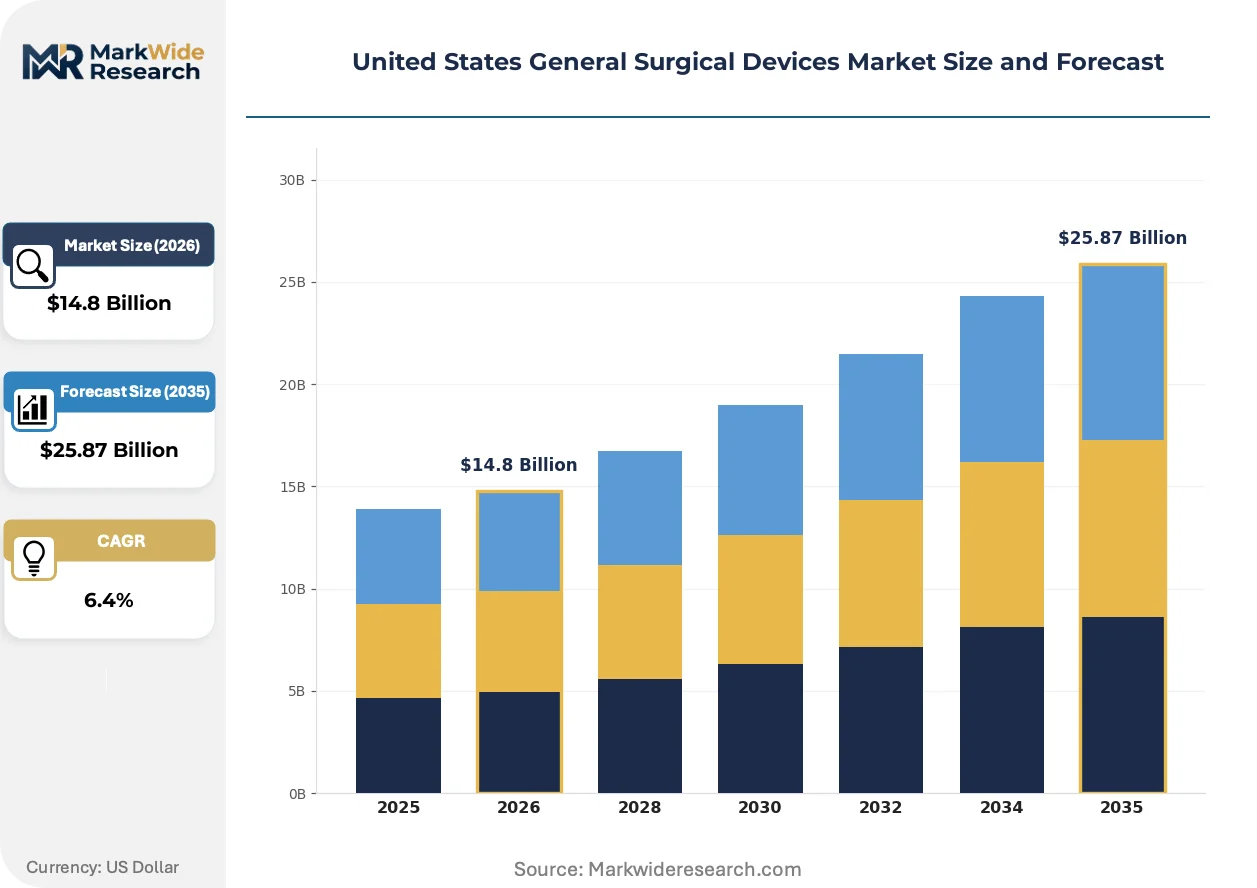
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Surgical Drapes, Sutures, Surgical Gloves Application: General Surgery, Orthopedic Surgery, Cardiothoracic Surgery, Neurosurgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Technology: Robotic Surgery, Laparoscopic Surgery, Electrosurgical Devices, Laser Surgery |
| Companies Covered | Stryker Corporation, Smith & Nephew, Medtronic, Zimmer Biomet Holdings, CONMED Corporation, Johnson & Johnson, B. Braun, Becton, Dickinson and Company, Boston Scientific, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States General Surgical Devices Market Evolving Landscape
Smart instrumentation and software-defined functionality are displacing purely mechanical tools, while regulatory pressure on sterilization emissions is forcing material and process reinvention across the supply base.
Radiofrequency identification (RFID) tagging is integrating with surgical instrument tracking systems to automate inventory reconciliation and usage logging. Health systems in the Midwest are deploying these systems fastest, driven by joint commission audit requirements. Real-time location data is compressing instrument loss rates and enabling predictive replacement scheduling that reduces case delays.
FDA's evolving guidance on cybersecurity in medical devices is mandating software bill of materials disclosure and patch management protocols for connected surgical equipment. Manufacturers must now embed update infrastructure into generator systems and robotic consoles. Electrosurgical device suppliers face the steepest compliance burden given their network connectivity and patient contact duration.
Subscription-based instrument access is displacing capital purchase models among independent ASC chains seeking to preserve liquidity for facility expansion. Third-party financing entities are intermediating these arrangements, assuming residual value risk and handling maintenance coordination. This pattern is most visible in Texas and Florida where ASC roll-up strategies concentrate buying power.
United States General Surgical Devices Market Segmentation
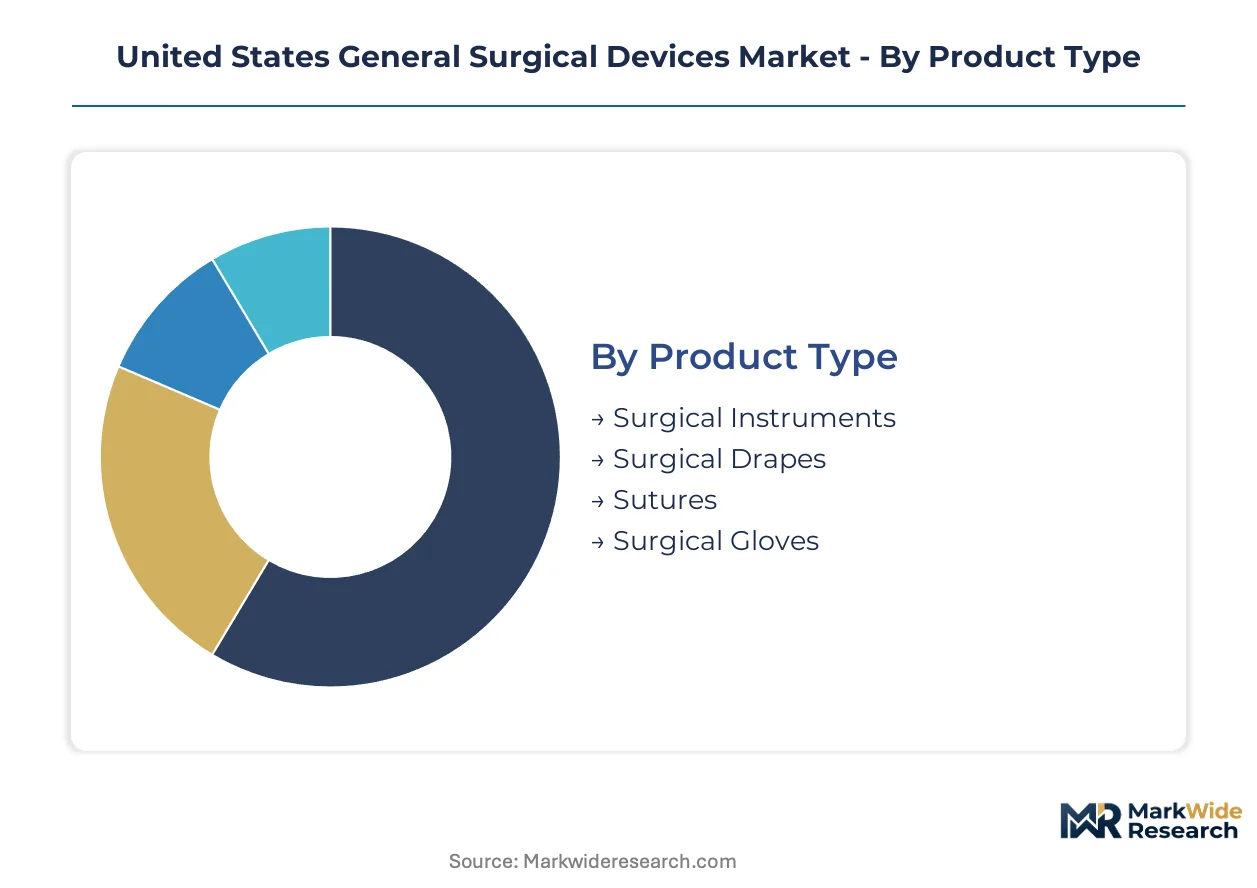
Segmentation in the United States General Surgical Devices Market reveals distinct procurement patterns across facility types and procedure categories. Understanding these divides enables manufacturers to align product portfolios with reimbursement flows and capital cycle timing.
Product Type:
Standalone consumables dominate routine procedure economics, while capital-intensive instruments integrate into broader surgical platforms and service contracts.
- Surgical Instruments:Reusable scalpels, forceps, retractors, and clamps manufactured from medical-grade stainless steel with precision tolerances. Demand concentrates in Southeast hospital construction projects where greenfield facilities require complete instrument sets for turnkey suite activation.
- Sutures:Absorbable and non-absorbable wound closure materials including synthetic polymers and natural collagen variants. Ambulatory surgical centers in Texas and Florida drive procurement volume as outpatient procedure volumes expand under CMS reimbursement parity.
- Surgical Drapes:Sterile barrier fabrics and adhesive incise films preventing surgical site contamination.
- Surgical Gloves:Latex and nitrile examination and sterile gloves with tactile sensitivity specifications for microsurgical procedures.
Volume placements concentrate in sutures; the faster expansion belongs to surgical instruments.
Application:
Procedure complexity determines device specification tiers, with open surgery maintaining volume leadership while minimally invasive protocols capture growth.
- General Surgery:Appendectomy, cholecystectomy, and hernia repair procedures utilizing standard instrument sets and basic electrosurgical units. ASCs in Georgia and North Carolina are expanding general surgery capacity fastest, converting traditionally inpatient cases to outpatient settings.
- Orthopedic Surgery:Joint replacement, fracture fixation, and arthroscopic procedures requiring specialized powered instruments and implantable hardware. Hospital systems in the Mountain West are consolidating orthopedic service lines, creating bundled procurement opportunities for device-and-implant packages.
- Cardiothoracic Surgery:Open-heart and minimally invasive chest procedures demanding high-precision staplers and tissue sealants.
- Neurosurgery:Cranial and spinal interventions utilizing microscopic visualization and navigation-enabled instrument systems.
General surgery captures the widest installed base; neurosurgery shows the steepest expansion trajectory as navigation technology penetrates academic medical centers.
End User:
Capital availability and reimbursement structure create divergent procurement behaviors across facility ownership models.
- Hospitals:Integrated delivery networks with centralized supply chain operations negotiating enterprise-wide contracts spanning multiple surgical service lines. The Southeast hospital construction boom is generating concentrated procurement windows for complete surgical suite packages.
- Ambulatory Surgical Centers:Independent and health system-affiliated outpatient facilities with compressed capital cycles favoring device-as-a-service arrangements. Texas and Florida ASC roll-ups are concentrating buying power and intermediating third-party financing for instrument access subscriptions.
- Specialty Clinics:Dermatology, ophthalmology, and plastic surgery practices performing limited-scope procedures.
- Research Laboratories:Academic and commercial R&D facilities procuring experimental and prototype surgical tools.
Hospitals anchor absolute spending; ASCs are climbing the fastest as outpatient migration accelerates.
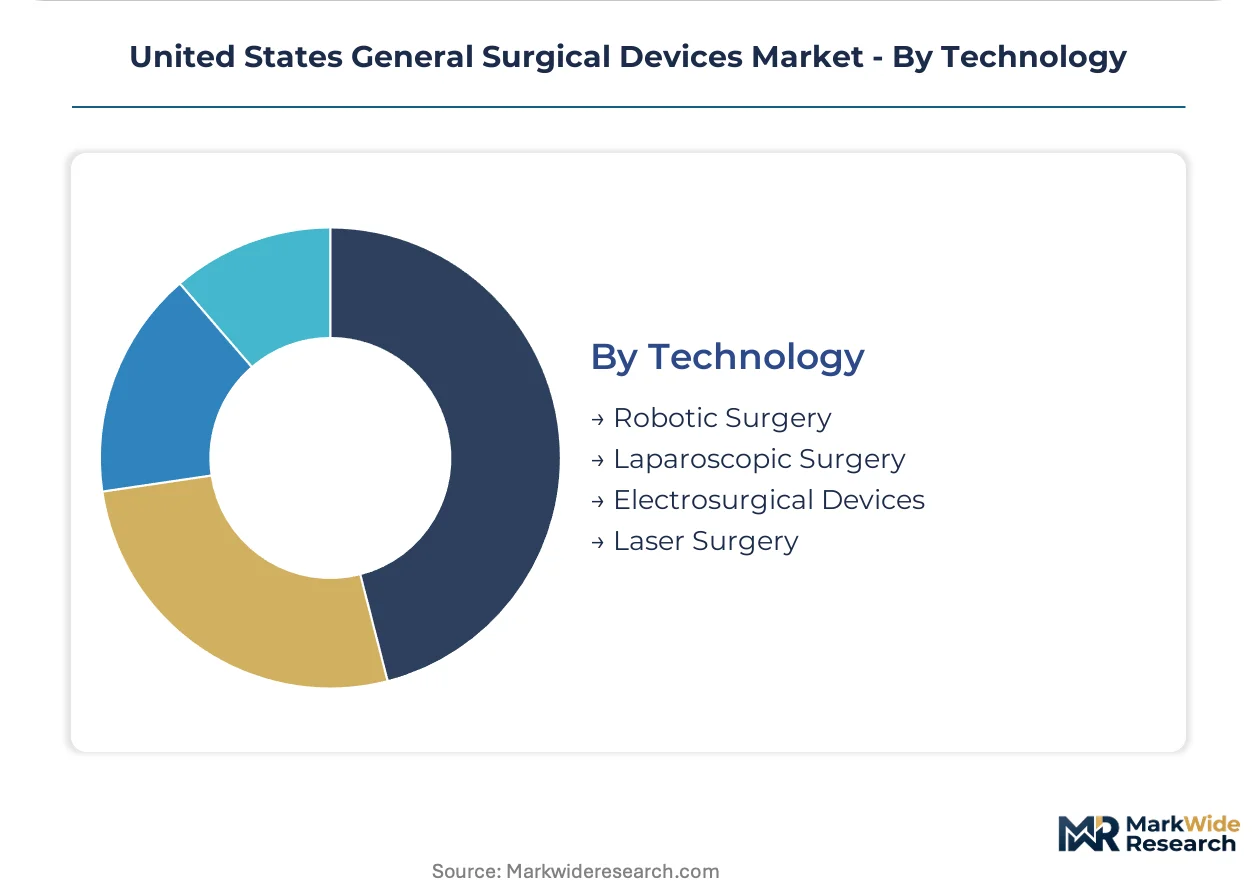
Technology:
Digital integration and software-defined functionality are displacing purely mechanical platforms, reshaping competitive dynamics.
- Robotic Surgery:Computer-assisted platforms enabling precision tissue manipulation through surgeon-controlled manipulator arms. Academic medical centers in California and Massachusetts are expanding robotic program capacity, requiring complementary instrument ecosystems and service infrastructure.
- Electrosurgical Devices:Radiofrequency and ultrasonic energy systems for tissue cutting and coagulation integrated with generator networks. FDA cybersecurity mandates are imposing software bill of materials disclosure requirements on connected generator systems.
- Laparoscopic Surgery:Minimally invasive abdominal procedures utilizing rigid endoscopes and specialized trocar access systems.
- Laser Surgery:Photonic energy platforms for precision tissue ablation in ophthalmic and dermatologic applications.
Electrosurgical devices maintain the broadest installed base; robotic surgery is gaining share fastest as system launches multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production clusters concentrate in the Midwest and Northeast, while consumption growth concentrates in the Southeast and Texas where facility construction outpaces national averages.
Southeast
Florida, Georgia, and North Carolina drive device procurement through greenfield hospital construction and ASC roll-ups. CMS outpatient reimbursement parity accelerates case volume migration from inpatient settings. Atlanta and Charlotte anchor distribution networks serving expanding surgical capacity across the Carolinas and Gulf Coast.
Texas
Independent ASC chains in Dallas-Fort Worth and Houston concentrate buying power through third-party financing arrangements. Device-as-a-service adoption runs ahead of national benchmarks as facilities preserve capital for geographic expansion. The Texas Medical Center complex sustains demand for high-complexity instrument sets and robotic platform accessories.
California
Academic medical centers in Los Angeles and the Bay Area pilot AI-enabled surgical navigation systems before national deployment. State-level single-use polymer waste regulations impose compliance costs on disposable instrument manufacturers. Stanford and UCSF anchor early-adopter clusters for connected device cybersecurity protocols mandated by FDA guidance.
Midwest
Integrated delivery networks in Illinois and Ohio negotiate enterprise-wide contracts spanning multiple surgical service lines. Joint Commission audit requirements drive RFID instrument tracking deployment faster than other regions. Cleveland Clinic and Mayo Clinic supply chain consolidation reshapes vendor access patterns across the Great Lakes corridor.
Northeast Corridor
Legacy hospital infrastructure in New York and Massachusetts sustains replacement demand for electrosurgical generators and laparoscopic towers. EPA ethylene oxide emission restrictions create sterilization bottlenecks for single-use device manufacturers. Boston's medical device cluster anchors R&D partnerships between academic institutions and instrument suppliers.
United States General Surgical Devices Market Competitive Landscape
Top-tier vendors anchor the premium technology tier, while mid-scale specialists and regional distributors occupy price-sensitive segments. Consolidation pressure intensifies as integrated delivery networks reduce approved vendor lists. Three archetypes dominate: diversified conglomerates with service infrastructure, pure-play instrument specialists, and robotics-integrated platform providers. Strategic moves concentrate on M&A for technology access and geographic expansion through ASC-focused distribution partnerships.
Among diversified conglomerates, Stryker Corporation and Medtronic exemplify the service-anchored model, extending customer lifetime value through preventive maintenance contracts and software-defined upgrade paths. Johnson & Johnson occupies a position within the wound closure and suture segment, competing for preference in integrated delivery networks through brand strength. These three represent distinct competitive vectors: hardware-service integration, minimally invasive platform R&D, and consumable brand loyalty.
| Leading Market Players |
|---|
| Stryker Corporation |
| Smith & Nephew |
| Medtronic |
| Zimmer Biomet Holdings |
| CONMED Corporation |
| Johnson & Johnson |
| B. Braun |
| Becton, Dickinson and Company |
| Boston Scientific |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FDA 510(k)-cleared devices and non-cleared alternatives manifests in both pricing stratification and supply chain configuration. Premium tiers command hardware-service bundling through manufacturer-direct relationships, while commodity instrument flows move through distributor networks with compressed margin structures.
Pricing Analysis
Margin tightening in reusable stainless steel instruments reflects nickel and chromium input cost volatility that lacks contractual pass-through protection. Three-tier pricing structure across premium, standard, and economy levels separates robotic platform accessories from basic laparoscopic sets from commodity gloves and drapes. Cost-down pressure on electrosurgical generators accelerates because IRA domestic manufacturing incentives are subsidizing reshoring competitors. Independent ASC chains exhibit highest price sensitivity, while integrated delivery networks anchor least sensitive demand through enterprise contract structures.
Supply Chain Analysis
Reverse logistics for reusable instrument refurbishment and remanufacturing flows concentrate in Midwest manufacturing clusters where biomedical technician specialization supports quality-controlled reprocessing. Geographic supply concentration centers on Germany, China, and Mexico for precision-machined components and polymer molding operations. Raw material dependencies draw from medical-grade stainless steel, nitinol wire, and silicone elastomer feedstocks. Single-source vulnerability in ethylene oxide sterilization capacity creates regional bottlenecks under EPA emission restrictions. Distribution runs through health system GPO contracts, regional specialty distributors, and direct manufacturer relationships to hospital and ASC endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethylene oxide sterilization capacity constraints prop pricing power for terminal-sterilized single-use devices, creating supply-constrained conditions that favor incumbents with captive sterilization infrastructure.
For Market Incumbents: Lock in ASC service contracts before third-party financing intermediaries consolidate instrument access subscriptions. Deepen backward integration into electrosurgical electrode assembly operations to capture IRA domestic content bonuses and defend against reshoring competitors. Prioritize cybersecurity patch management infrastructure for connected generator systems facing FDA software bill of materials mandates. For New Entrants and Emerging Players: Launch via device-as-a-service arrangements targeting rural hospital outsourcing partnerships in the Mountain West and Great Plains where perioperative service bundling creates procurement channel access. White-space concentration sits in AI-enabled surgical navigation integration with legacy laparoscopic towers lacking standardized APIs. The most penetrable segment comprises critical access facilities contracting regional health systems for instrument-and-service packages. For Investors and Strategic Acquirers: Exit pathways concentrate in robotics-integrated platform providers with installed base expansion potential and complementary instrument ecosystem requirements. Long-term viability across the analysis window favors manufacturers with service infrastructure anchoring customer lifetime value. Acquisition target archetype: mid-scale instrument specialists with ASC distribution partnerships in Texas and Florida. Monitor FDA substantial equivalence scrutiny intensity as inflection indicator for clearance timeline risk and revenue recognition delays.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Enterprise-wide contracts with Southeast IDNs secure turnkey surgical suite procurement windows. |
| Software Companion Development | AI-enabled navigation modules reduce conversion rates and differentiate laparoscopic tower offerings. |
| FDA Submission | Premarket notification pathways for iterative modifications face heightened predicate scrutiny. |
| Reimbursement Strategy | CMS outpatient parity alignment accelerates ASC case volume capture for portable equipment. |
| Backward Integration | In-house electrode assembly captures IRA tax credits and insulates against nickel price swings. |
Research Methodology
Multi-period observation of hospital construction permitting, ASC roll-up activity, and FDA 510(k) submission volumes anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and ASC operations directors. Secondary validation drew from CMS Medicare reimbursement schedules, FDA premarket notification databases, hospital procurement records, and EPA sterilization facility emission reports. Bottom-up facility-level demand estimation triangulated against top-down manufacturer revenue segmentation.
Segment-weighting across product type, application, end user, and technology dimensions informed the analytical framework throughout the projection horizon. CAGRs were derived from installed base expansion rates, replacement frequency modeling, and procedure volume migration patterns. Industry-specific forecast inputs included robotic system launch timelines and state-level single-use polymer waste regulation compliance cost trajectories.
The model assumes a particular technology adoption path; alternative pathways for AI-enabled surgical navigation would alter the outlook if interoperability standards emerge faster than projected. Forecasts reflect assumptions regarding CMS reimbursement stability and EPA ethylene oxide emission restriction enforcement. Practitioners should monitor FDA cybersecurity guidance evolution and domestic manufacturing incentive program renewals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Laparoscopic Sutures Market
Surgical Instruments
Cryosurgery Market
Surgical Instruments
Special Purpose Needles Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Global Surgical Booms Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
United Arab Emirates General Surgical Devices Market
Surgical Instruments
Global Microsurgical Instruments Market
Surgical Instruments
Knee Surgical Impactor Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Thoracic Surgery Market
Surgical Instruments
Global Urology Surgical Instruments Market
Surgical Instruments
Global Surgical Instruments Market
Surgical Instruments
Resectoscopes Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Robotic Surgery Market