
 Suture Needles Market | 2026-2036
Suture Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Suture Needles Market Intelligence
REACH is hardening material compliance costs for European manufacturers while simultaneously elevating barriers for new entrants across all geographies. Johnson & Johnson Medical N.V. leverages its sterilization infrastructure to maintain hospital formulary positions in North America. Medtronic anchors its portfolio through proprietary alloy formulations that reduce tissue drag. Futura Surgicare Pvt. Ltd. competes on cost-optimized stainless steel variants for price-sensitive Asian markets.
Suture needles are precision-engineered piercing instruments, typically manufactured from 300-series stainless steel or specialized carbon alloys, with tip geometries ranging from conventional cutting to taper-point and reverse-cutting profiles designed to minimize tissue trauma during wound closure. Their primary commercial purpose centers on enabling reliable apposition of biological tissue across general surgery, orthopedics, cardiovascular, and ophthalmic procedures. Taper point needles dominate soft-tissue applications where penetration resistance remains low, while reverse cutting needles command premium positioning in dermatological and plastic surgery due to reduced suture pull-through. Stainless steel formulations sustain the majority of unit volume, though alloy steel variants are capturing share in microsurgical segments where fatigue resistance and dimensional stability prove critical.
FDA 510(k) clearance pathways, EMA MDR compliance requirements, and ISO 13485 quality management standards collectively govern market access and sustain recurring audit burdens across the supply base. These frameworks elevate documentation intensity for sterile single-use formats while permitting streamlined pathways for certain reusable instrument categories. Stakeholders must monitor evolving biocompatibility testing protocols and sterilization validation requirements as regulators narrow acceptable residual contamination thresholds.
Market Dynamics
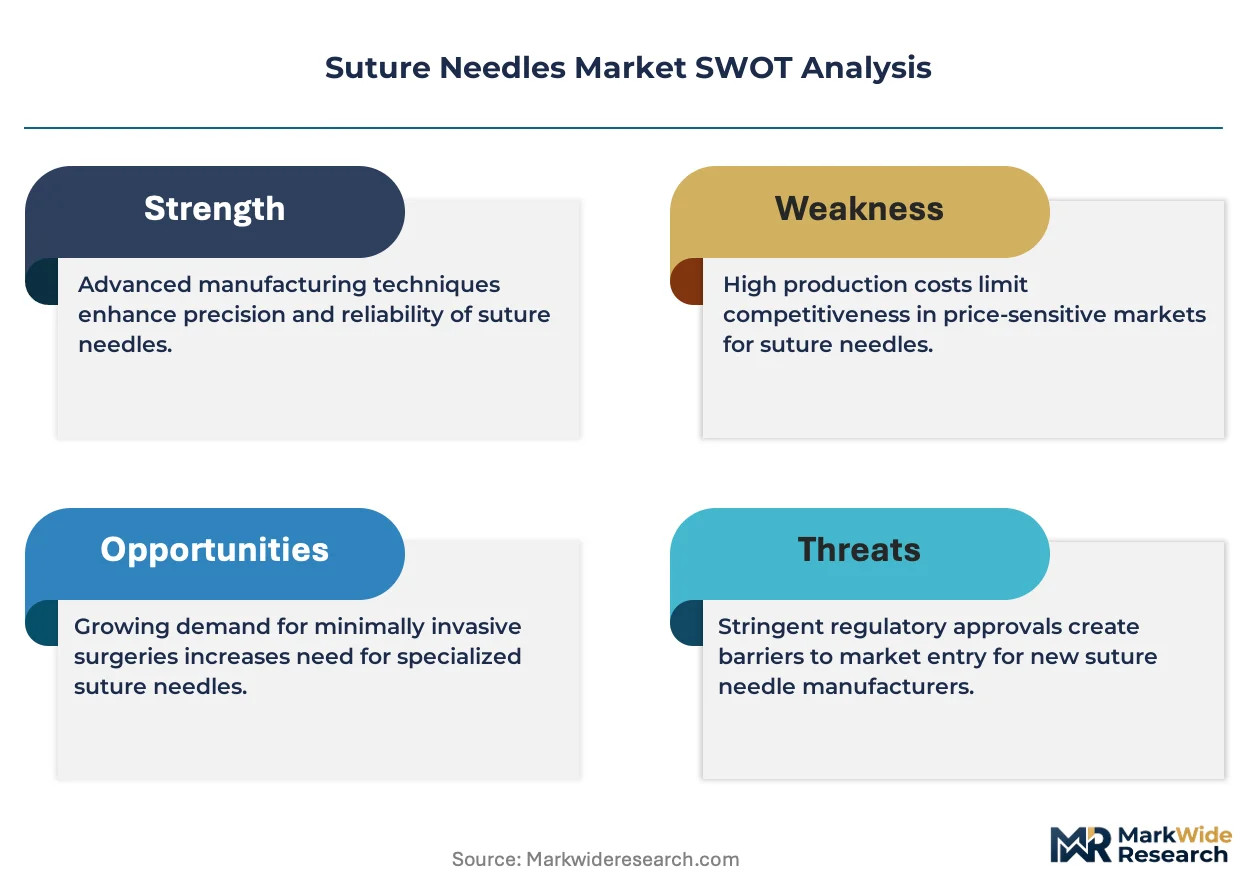
REACH compliance is forcing European manufacturers to reformulate alloy compositions while simultaneously elevating sterilization validation costs across all export markets. This regulatory pressure is compressing margins for stainless steel needle producers and accelerating consolidation among mid-tier suppliers.
Growth Catalysts
- EMA MDR sterilization standards:Tighter residual contamination thresholds are mandating single-use formats across European surgical centers, expanding addressable volume for sterile disposable needles.
- Ambulatory surgical centers:United States outpatient facilities are procuring specialized taper-point and reverse-cutting profiles for same-day discharge procedures.
- Carbon alloy fatigue resistance:Microsurgical segments are adopting proprietary alloy formulations that reduce tissue drag and enable finer gauge needles for ophthalmic applications.
Market Restraints
- Nickel price volatility:300-series stainless steel feedstock costs fluctuate with mining output from Indonesian and Philippine suppliers, compressing margin predictability for commodity needle producers.
- Supply concentration in Solingen:German precision grinding equipment manufacturers control access to automated tip-geometry machinery, creating bottlenecks for capacity expansion.
- Synthetic tissue adhesive substitution:Cyanoacrylate and fibrin sealant formulations are displacing suture closure in superficial laceration repair across emergency departments.
Strategic Opportunities
- Indian PLI scheme for medical devices:Domestic manufacturing incentives are enabling cost-optimized stainless steel variants for price-sensitive Asian surgical markets.
- Robotic-assisted suturing:Laparoscopic and endoscopic platforms are converging with pre-curved needle designs that enable automated tissue apposition in minimally invasive procedures.
- Direct hospital contracting:Manufacturers are bypassing distributor markups by establishing captive supply agreements with integrated delivery networks in the United States.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified quality management system assessors are concentrated in Western Europe and the United States, extending certification timelines for Asian and Latin American facilities by six to twelve months.
- Legacy ERP integration:Sterilization lot tracking requirements are forcing mid-cap manufacturers to replace paper-based batch records with validated electronic systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Suture Needles Market |
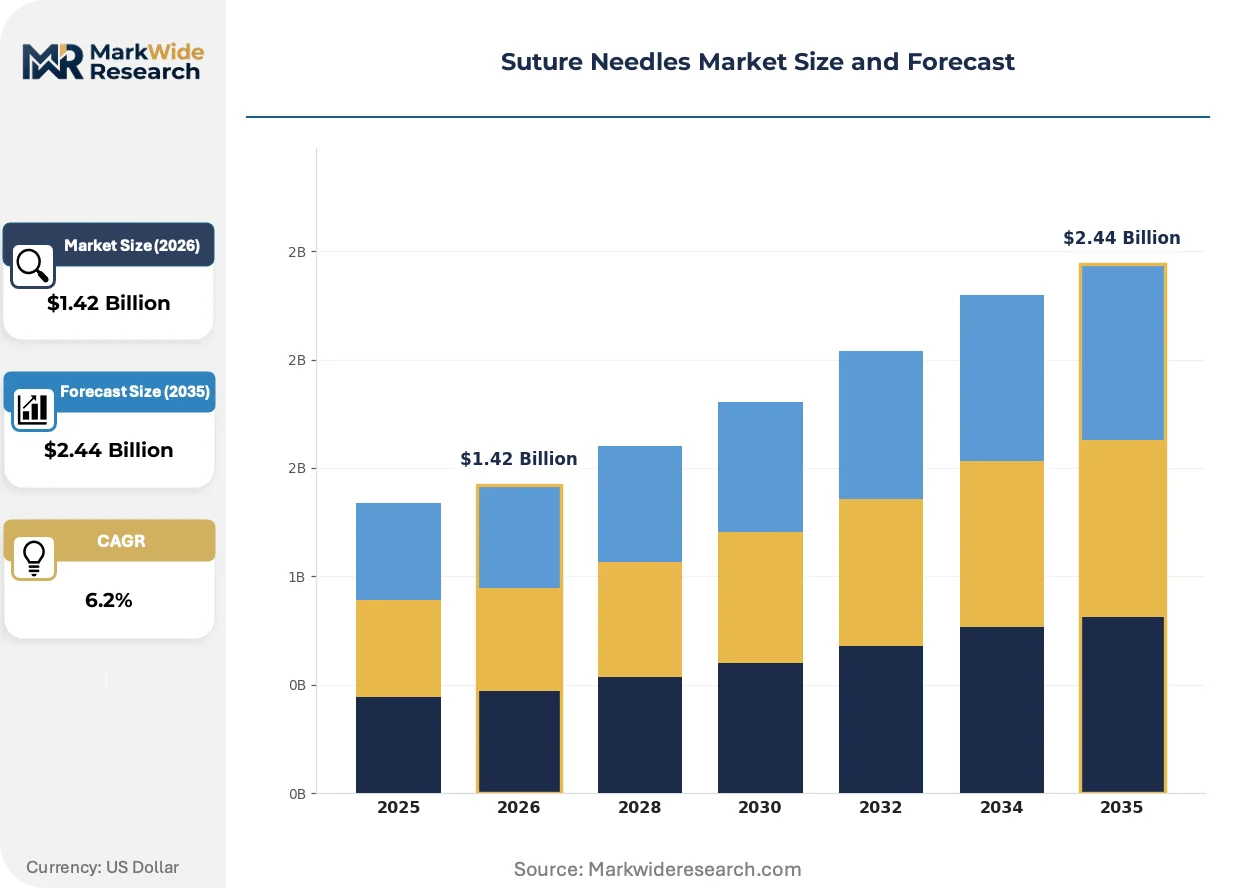
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cutting Needles, Taper Point Needles, Blunt Needles, Reverse Cutting Needles Material: Stainless Steel, Carbon Steel, Alloy Steel, Plastic Form: Single Use, Reusable, Sterile, Non-Sterile End User: Hospitals, Clinics, Surgical Centers, Veterinary Practices |
| Companies Covered | Medtronic, Futura Surgicare Pvt. Ltd., Johnson & Johnson Medical N.V., Aurolab, Natsume Seisakusho Co., Ltd., Alfresa Pharma Corporation, Bear Medic Corporation, Teleflex Incorporated, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Suture Needles Market Strategic Shifts & Innovations
Needle surface engineering and sterilization modality evolution are compressing product development cycles while elevating performance thresholds for tissue penetration and biocompatibility. These shifts are redrawing competitive boundaries between alloy specialists and sterilization service providers.
Nitinol shape-memory alloys are converging with conventional stainless steel manufacturing lines to enable self-retaining curved profiles that maintain preset geometries through soft-tissue manipulation. Cardiovascular and orthopedic surgeons are adopting these formulations for valve repair and ligament reattachment where needle flexibility proves critical. The technology is converging with automated suturing platforms to reduce hand-fatigue and standardize closure consistency across high-volume surgical workflows.
REACH substance restrictions are hardening material compliance costs for European manufacturers while simultaneously elevating barriers for new entrants across all geographies. ECHA candidate list updates are forcing reformulation of nickel-bearing alloys and surface coating chemistries. Sterile single-use needle producers are absorbing recurring audit burdens and biocompatibility testing documentation intensity that reusable instrument categories largely bypass.
Hospital formulary consolidation is compressing vendor lists and privileging suppliers with integrated sterilization infrastructure and multi-product portfolios. Integrated delivery networks are replacing individual surgeon preference cards with standardized procurement contracts that specify alloy grade, tip geometry, and sterile packaging configuration. This concentration is most visible in United States metropolitan markets where health system mergers have reduced independent purchasing authority at individual facility level.
Suture Needles Market Segmentation
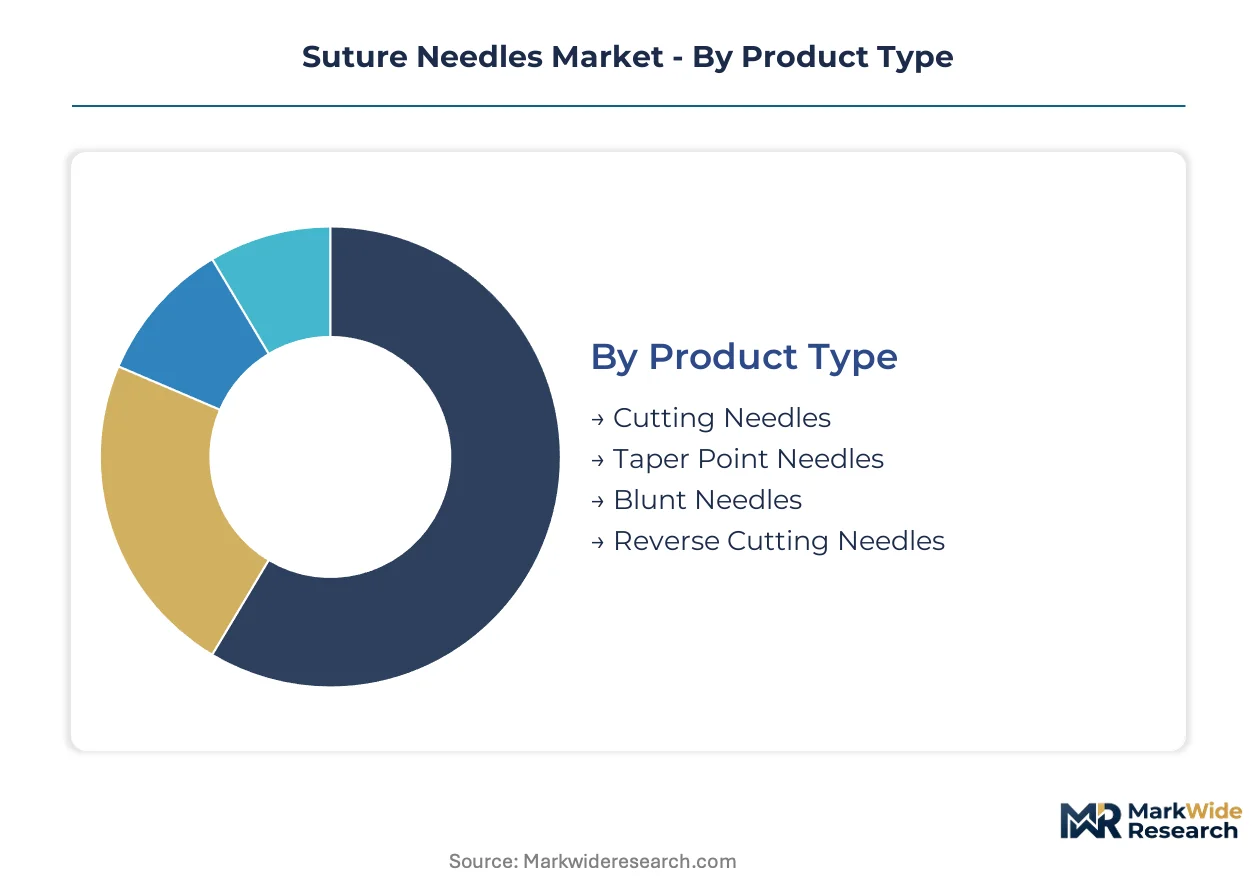
Needle specification diversity reflects divergent clinical requirements across tissue types and surgical settings. Procurement patterns cluster around material compliance capabilities and sterilization infrastructure access rather than unit economics alone.
Product Type:
Manufacturing capacity concentrates among German precision grinding equipment suppliers and Japanese tip-geometry specialists, creating supply bottlenecks for complex profile geometries.
- Taper Point Needles:These feature a rounded body transitioning to a sharp point, designed to spread rather than cut fibrous tissue. Demand concentrates in United States ambulatory surgical centers performing same-day discharge procedures where tissue trauma minimization drives formulary selection.
- Reverse Cutting Needles:Triangular cross-sections with cutting edges on the outer curvature reduce suture pull-through in dense tissue. German and Japanese manufacturers command premium positioning in dermatological and plastic surgery segments where cosmetic outcomes justify higher procurement costs.
- Cutting Needles:Conventional triangular profiles with cutting edges on the inner curvature penetrate resistant tissue planes in general surgery applications.
- Blunt Needles:Rounded tips minimize accidental puncture in friable organ surgery and mass closure techniques.
Taper point configurations absorb the bulk of installed capacity; reverse cutting profiles are expanding most quickly.
Material:
Cost tier differentiation separates commodity stainless steel from proprietary alloy formulations where fatigue resistance commands measurable price premiums.
- Stainless Steel:300-series formulations sustain the majority of unit volume through established supply chains from Indonesian and Philippine nickel feedstock. United States hospital procurement contracts specify this grade for routine closure procedures where cost predictability outweighs performance margins.
- Alloy Steel:Proprietary carbon and chromium blends reduce tissue drag and enable finer gauge needles. Microsurgical segments in Japan and Germany adopt these formulations for ophthalmic and cardiovascular applications where dimensional stability proves critical.
- Carbon Steel:Hardened variants serve price-sensitive Asian markets through Indian PLI scheme-enabled domestic manufacturing.
- Plastic:Polymer formulations address specialized biopsy and radiopaque marking applications.
Stainless steel retains the dominant production footprint; alloy steel variants are climbing the fastest.
Form:
Volume distribution reflects regulatory bifurcation between EMA MDR-mandated single-use formats and reusable categories permitted under streamlined validation pathways.
- Single Use:Pre-sterilized disposable formats eliminate cross-contamination risk and satisfy tightening FDA and EMA residual contamination thresholds. European surgical centers are converting procurement toward this category following EMA MDR implementation.
- Sterile:Gamma and ethylene oxide sterilization modalities command premium positioning in integrated delivery network contracts.
- Reusable:Autoclavable formats persist in veterinary practices and resource-constrained settings where sterilization infrastructure investment is recoverable.
- Non-Sterile:Bulk formats serve institutional sterilization departments with captive processing capacity.
Single use formats capture the steepest expansion trajectory; reusable instruments retain niche volume in veterinary segments.
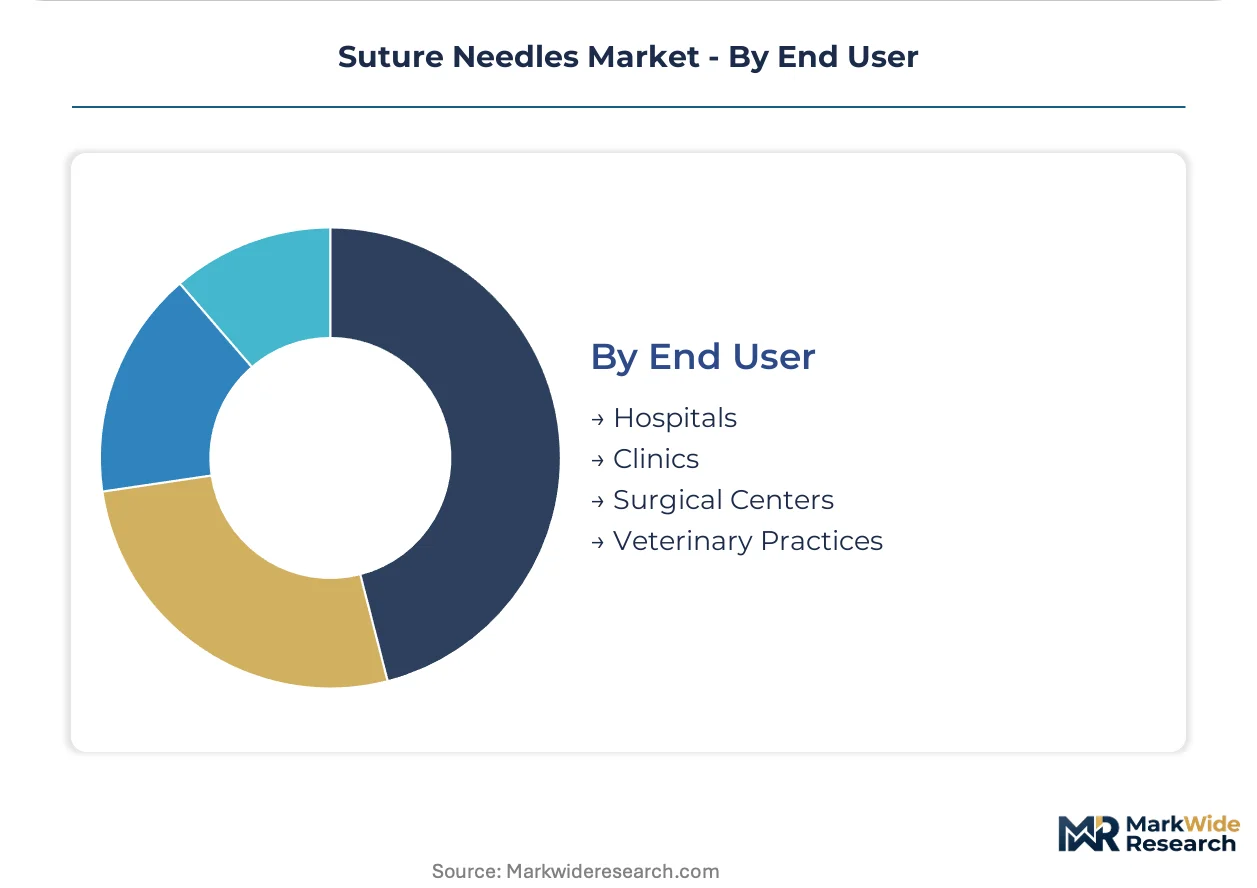
End User:
Customer type segmentation reveals procurement authority concentration among integrated delivery networks versus fragmented purchasing in outpatient settings.
- Hospitals:Formulary consolidation across United States metropolitan health systems privileges suppliers with multi-product portfolios and validated sterilization infrastructure. These facilities specify alloy grade, tip geometry, and packaging configuration through standardized contracts.
- Surgical Centers:United States outpatient facilities procure specialized taper-point and reverse-cutting profiles for high-volume same-day procedures.
- Clinics:Primary care and urgent care settings favor cost-optimized stainless steel variants for superficial laceration repair.
- Veterinary Practices:Price-sensitive demand concentrates in Asian markets with lower regulatory documentation requirements.
Hospitals command the dominant procurement volume; surgical centers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Tamil Nadu and Shenzhen are concentrating precision grinding capacity for medical device exports, with bonded warehousing facilities reducing customs friction for sterile instrument shipments.
United States
Ambulatory surgical centers in Texas and Florida are procuring specialized taper-point profiles for high-volume outpatient procedures. FDA 510(k) clearance pathways govern sterile single-use format approvals, with residual contamination thresholds tightening documentation requirements. Minneapolis and Boston anchor integrated delivery network procurement consolidation, where formulary standardization privileges multi-product suppliers.
Germany
Aging demographics in Bavaria and North Rhine-Westphalia are elevating elective surgery volumes for cardiovascular and orthopedic applications. EMA MDR implementation is mandating single-use formats across European surgical centers, expanding addressable volume for sterile disposable needles. Solingen precision grinding equipment manufacturers control automated tip-geometry machinery access, creating capacity bottlenecks for complex profile production.
Japan
Microsurgical segments in Tokyo and Osaka are adopting proprietary alloy formulations for ophthalmic applications where dimensional stability proves critical. PMDA quality management standards enforce biocompatibility testing protocols that narrow acceptable residual contamination thresholds. Nagoya medical device clusters are converging with nitinol shape-memory alloy manufacturing lines for self-retaining curved profiles.
India
Price-sensitive surgical markets in Maharashtra and Gujarat are absorbing cost-optimized stainless steel variants enabled by PLI scheme domestic manufacturing incentives. CDSCO medical device regulations are elevating documentation intensity for sterile single-use formats while permitting streamlined pathways for certain reusable categories. Bengaluru and Hyderabad are emerging as contract sterilization hubs for export-oriented needle producers.
Suture Needles Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across a tiered market structure where sterilization infrastructure and alloy formulation capabilities determine positioning. The vendor base stratifies between premium-tier suppliers with captive precision grinding capacity and mid-cap competitors dependent on third-party equipment access. Two strategic archetypes dominate: integrated sterilization service providers and alloy specialists with proprietary fatigue-resistant formulations. Competitive moves center on hospital formulary consolidation through multi-product portfolio expansion and direct contracting with integrated delivery networks that bypass distributor markups.
Among diversified medical technology conglomerates, Medtronic and Johnson & Johnson Medical N.V. exemplify the integrated archetype through their sterilization infrastructure and hospital formulary positions. Futura Surgicare Pvt. Ltd. occupies a position within the cost-optimized tier serving price-sensitive Asian markets. Specialists in precision tip geometry include Natsume Seisakusho Co., Ltd., which represents Japanese manufacturing concentration in automated grinding technology. These named entities anchor competitive commentary without implying specific strategic actions or market share claims beyond their evident geographic and structural positioning.
| Leading Market Players |
|---|
| Medtronic |
| Futura Surgicare Pvt. Ltd. |
| Johnson & Johnson Medical N.V. |
| Aurolab |
| Natsume Seisakusho Co., Ltd. |
| Alfresa Pharma Corporation |
| Bear Medic Corporation |
| Teleflex Incorporated |
| Smith & Nephew |
| Others |
Cost & Logistics Intelligence
Nickel feedstock from Indonesian and Philippine mining operations flows through 300-series stainless steel production into three-tier pricing structures across premium, standard, and economy levels, with alloy-grade certification and sterilization validation costs determining tier placement for hospital procurement committees.
Pricing Analysis
Short lead-time premiums command measurable markups from United States ambulatory surgical centers facing same-day discharge scheduling pressures, while spot inventory discounts attract price-sensitive Asian clinics. Three-tier pricing structure across premium, standard, and economy levels separates proprietary alloy formulations from commodity stainless steel and carbon steel variants. Pricing pressure stems from REACH compliance costs elevating European manufacturing expenses. Veterinary practices in Asian markets exhibit highest price sensitivity; integrated delivery networks in United States metropolitan markets demonstrate lowest sensitivity due to formulary standardization.
Supply Chain Analysis
Returns and refurbishment flows remain minimal given single-use format dominance under EMA MDR and FDA sterilization standards, though reusable autoclavable formats persist in veterinary channels with reverse logistics concentrated in Indian domestic manufacturing zones. Manufacturing gravity centers on Germany, Japan, and China for precision grinding equipment and tip-geometry machinery. Raw material flows draw from Indonesian nickel mines, Indian PLI scheme-enabled steel production, and Japanese nitinol alloy specialists. Single-source vulnerability concentrates in Solingen equipment manufacturers controlling automated needle grinding capacity. Distribution runs through integrated delivery network direct contracts and specialized medical device distributors serving ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solingen precision grinding equipment bottlenecks constrain global needle manufacturing capacity, propping pricing power for incumbent suppliers with captive machinery access and sterilization infrastructure.
For Market Incumbents: Hedge against synthetic tissue adhesive substitution by deepening proprietary alloy formulation portfolios and securing long-term nickel supply agreements with Indonesian mining operators. Expand sterilization validation capacity in United States and European facilities to defend hospital formulary positions against mid-tier competitors. Prioritize direct contracting with integrated delivery networks to bypass distributor markups and lock in multi-year procurement commitments. For New Entrants and Emerging Players: CDSCO medical device regulations in India open a window for cost-optimized stainless steel variants targeting price-sensitive Asian surgical markets and veterinary channels with lower documentation requirements. Focus white-space capture on contract sterilization services for export-oriented needle producers in Bengaluru and Hyderabad clusters. Pursue robotic-assisted suturing platform partnerships as the most penetrable application segment for pre-curved needle designs. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European manufacturers facing REACH compliance cost compression but holding precision grinding equipment access and established hospital relationships. Long-term viability hinges on sterilization infrastructure ownership and alloy formulation intellectual property. Monitor ECHA candidate list updates for nickel-bearing alloy restrictions as the critical inflection signal for material substitution investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Single-Use Conversion | Mandatory sterile disposable formats expand addressable volume for compliant European manufacturers. |
| Nitinol Alloy Manufacturing Integration | Self-retaining curved profiles capture cardiovascular and orthopedic surgeon preference in Japan. |
| Direct Hospital Contracting | Integrated delivery network agreements bypass distributor markups and standardize procurement specifications. |
| Indian PLI Scheme Manufacturing | Domestic cost-optimized production enables competitive positioning in price-sensitive Asian markets. |
| Robotic-Assisted Suturing Partnerships | Pre-curved needle designs align with automated tissue apposition platforms in minimally invasive procedures. |
Research Approach
FDA 510(k) clearance databases, EMA MDR submission records, and ISO 13485 certification registries formed the secondary backbone, supplemented by customs trade data tracking nickel feedstock flows from Indonesian and Philippine suppliers. Primary interviews with hospital purchasing committee members, ambulatory surgical center procurement managers, biomedical engineers, and GPO contracts specialists validated demand-side assumptions. Bottom-up volume modeling triangulated against top-down expenditure estimates from integrated delivery network annual reports.
Historical trendline analysis of surgical procedure volumes, alloy material adoption patterns, and sterilization format shifts informed the projection framework across the analysis window. Segmentation dimensions encompassed needle tip geometry profiles, material grade tiers, sterile versus reusable formats, and end-user facility types including hospitals, surgical centers, clinics, and veterinary practices. CAGRs derived from regression analysis of procedure growth rates and per-procedure needle consumption intensities, with nickel price volatility and regulatory compliance cost trajectories as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for nitinol shape-memory alloys or synthetic tissue adhesive substitution would alter the outlook for stainless steel needle demand. Forecasts reflect documented assumptions regarding EMA MDR implementation timelines, REACH substance restriction scopes, and ambulatory surgical center expansion rates. Practitioners should monitor ECHA candidate list updates, Indonesian nickel export policy shifts, and robotic-assisted suturing platform regulatory clearances for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Endoscopic Closure Systems Market
Surgical Instruments
US Integrated Operating Rooms Market
Surgical Instruments
Ultrasonic Tissue Ablation System Market
Surgical Instruments
Homecare Surgical Drains Market
Surgical Instruments
Global Microsurgical Instruments Market
Surgical Instruments
Special Purpose Needles Market
Surgical Instruments
Retractable Needles Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Plastic Wound Retractor Market
Surgical Instruments
Global Surgical Stapler Market
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Handheld Arthroscopic Instruments Market