
 Corneal Transplantation Surgical Instrument Package Market | 2026-2036
Corneal Transplantation Surgical Instrument Package Market Size, Share, and Industry Trends Forecast 2026-2036
Corneal Transplantation Surgical Instrument Package Market Analytics
Academic medical centers is unwinding purchasing concentration from private ambulatory surgical centers as fellowship training programs expand keratoplasty volumes. MORIA leverages its European manufacturing footprint to sustain premium positioning across European teaching hospitals. Alcon Inc. anchors North American distribution through direct sales teams embedded in major ophthalmology departments. Carl Zeiss Meditec AG differentiates via integrated imaging-to-surgical workflow systems that bundle instrument packages with optical coherence tomography platforms.
A corneal transplantation surgical instrument package comprises sterile, single-use or reusable tools—keratomes, speculums, forceps, and cannulas—engineered to precise tolerances for lamellar and penetrating graft procedures. These packages eliminate cross-contamination risk while ensuring geometric compatibility between donor tissue preparation and recipient bed creation. Keratome-based packages dominate current revenue as mechanical microkeratome systems retain cost advantages over femtosecond alternatives in price-sensitive settings. Endothelial keratoplasty applications represent the fastest-expanding segment as DMEK and DSAEK procedures displace full-thickness penetrating keratoplasty for Fuchs' endothelial dystrophy. Optical coherence tomography integration within instrument packages is concentrating margin pools among vendors offering real-time graft alignment verification.
The FDA's Quality System Regulation and ISO 13485 framework govern sterilization validation and traceability for reusable corneal instrument sets, while the EU Medical Device Regulation imposes stricter clinical evidence requirements on Class IIa ophthalmic surgical kits. These standards elevate capital requirements for new entrants and compress margins for distributors lacking in-house regulatory affairs capacity. Stakeholders must monitor evolving reimbursement codes for DMEK procedures, as payer coverage decisions will directly shape which instrument package configurations hospitals prioritize for capital allocation.
Market Dynamics
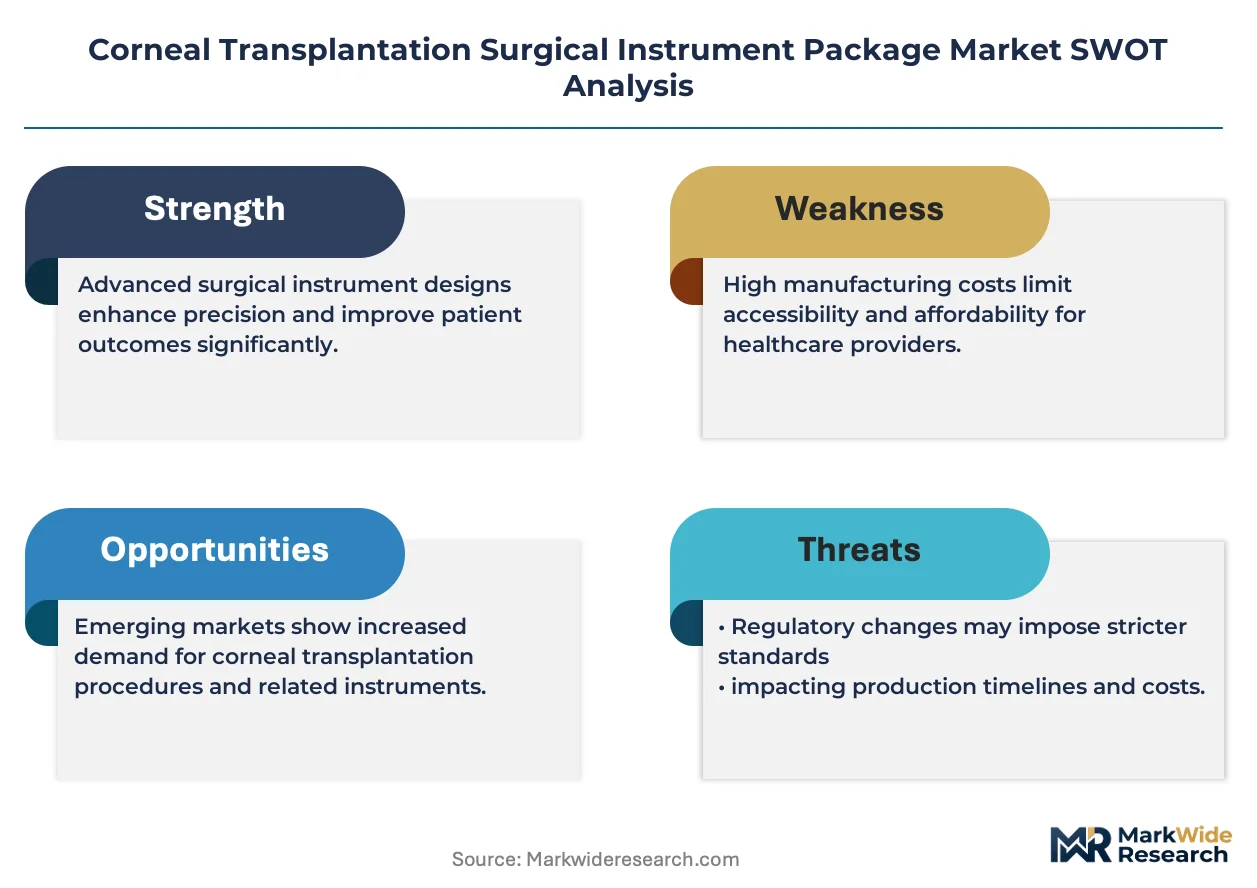
The FDA's updated medical device classification rules for ophthalmic surgical kits are compressing margins for distributors lacking in-house regulatory affairs capacity while elevating capital requirements for new entrants.
Growth Catalysts
- Endothelial keratoplasty technique migration:DMEK and DSAEK procedures are displacing full-thickness penetrating keratoplasty for Fuchs' endothelial dystrophy, expanding instrument package volumes in academic medical centers.
- ISO 13485 framework adoption:Sterilization validation and traceability standards for reusable corneal instrument sets are creating compliance-driven replacement cycles among hospital procurement departments.
- Fellowship training program expansion:Academic medical centers in the United States are unwinding purchasing concentration from private ambulatory surgical centers as keratoplasty volumes rise.
Market Restraints
- EU Medical Device Regulation clinical evidence requirements:Stricter mandates on Class IIa ophthalmic surgical kits are extending time-to-market for new package configurations.
- Femtosecond laser cost premium:Mechanical microkeratome systems retain cost advantages over laser alternatives in price-sensitive settings, limiting upgrade velocity.
- Reusable set sterilization infrastructure:Central sterile processing department capacity constraints in smaller facilities favor single-use disposables despite per-procedure cost premiums.
Strategic Opportunities
- Optical coherence tomography convergence:Real-time graft alignment verification capabilities are concentrating margin pools among vendors bundling instrument packages with imaging platforms.
- Direct sales team embedding:Major ophthalmology departments are consolidating vendor relationships around field-based technical support and procedure-specific training.
- DSAEK reimbursement code expansion:Payer coverage decisions for endothelial keratoplasty procedures will shape which instrument package configurations hospitals prioritize for capital allocation.
Industry Challenges
- Cross-contamination risk mitigation:Geometric compatibility requirements between donor tissue preparation and recipient bed creation demand precise tolerance engineering across keratome, speculum, forceps, and cannula sets.
- Regulatory affairs talent scarcity:Distributors lacking in-house compliance capacity face margin compression under FDA Quality System Regulation and evolving EU MDR frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corneal Transplantation Surgical Instrument Package Market |
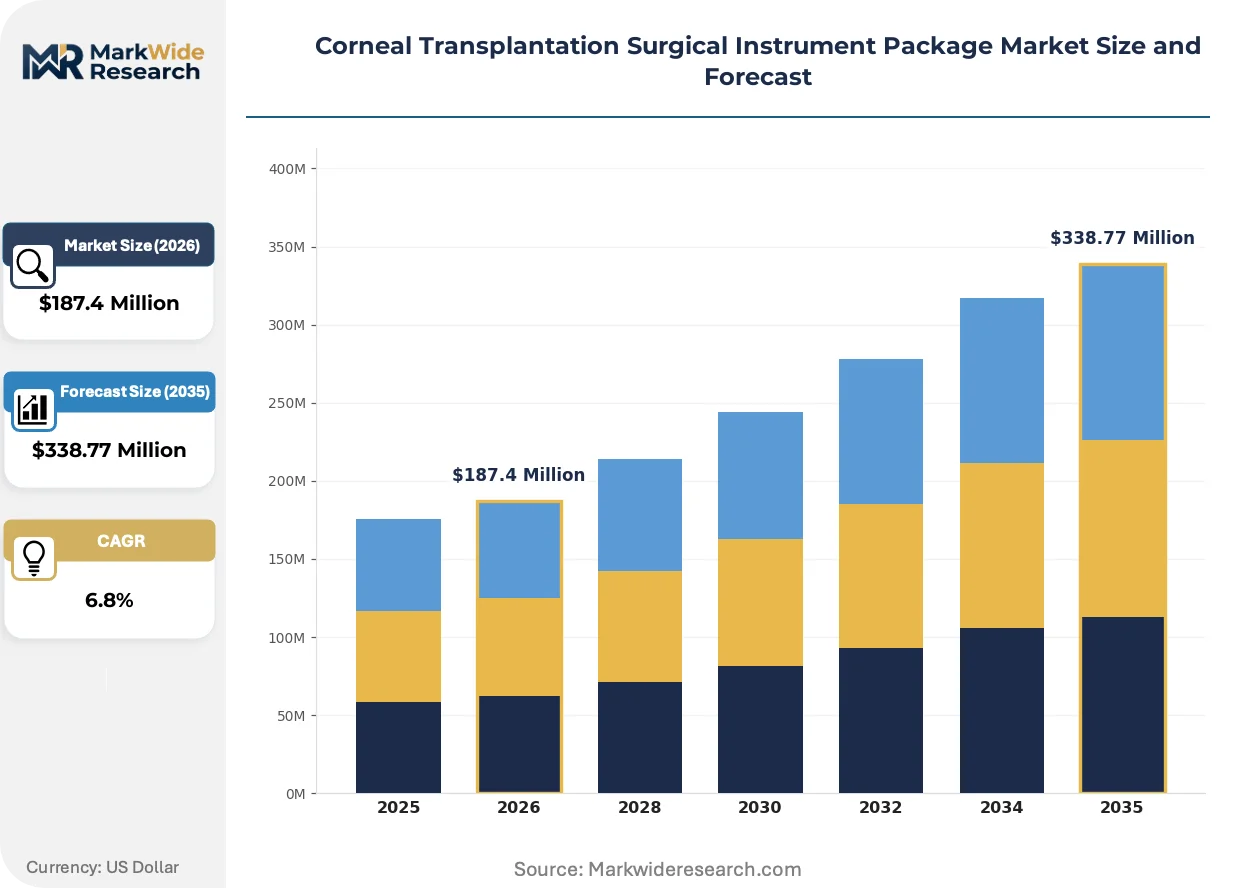
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Keratome, Speculum, Forceps, Cannula Application: Descemet's Stripping Automated Endothelial Keratoplasty, Penetrating Keratoplasty, Endothelial Keratoplasty, DMEK End User: Hospitals, Ambulatory Surgical Centers, Eye Clinics, Research Institutes Technology: Surgical Assistant Systems, Imaging Systems, Optical Coherence Tomography, Biometric Devices |
| Companies Covered | MORIA, OASIS Medical, Rumex, Peregrine, OPHMED, ASICO, Alcon Inc., Carl Zeiss Meditec AG, Ziemer Ophthalmic Systems AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corneal Transplantation Surgical Instrument Package Market Evolving Landscape
Instrument package architecture is fragmenting across sterile single-use and validated reusable pathways as procurement departments weigh total cost of ownership against infection control protocols.
Femtosecond laser-assisted keratoplasty is bifurcating the premium segment from mechanical microkeratome systems. Academic medical centers with fellowship programs are adopting laser platforms for complex lamellar procedures. This technology is compressing margins for standalone instrument package vendors unable to bundle imaging-to-surgical workflow systems.
The EU Medical Device Regulation is imposing stricter clinical evidence requirements on Class IIa ophthalmic surgical kits. Manufacturers must now generate additional safety and performance data for reusable corneal instrument sets. European teaching hospitals are responding by consolidating purchases around vendors with established notified body relationships and MDR technical documentation.
Hospital procurement departments are embedding vendor sales teams within ophthalmology departments to secure procedure-specific training commitments. Major academic medical centers are replacing distributor intermediaries with direct manufacturer relationships that bundle instrument packages with fellowship education credits. This pattern concentrates most visibly in the United States, where keratoplasty volume growth aligns with training program expansion.
Corneal Transplantation Surgical Instrument Package Market Segmentation
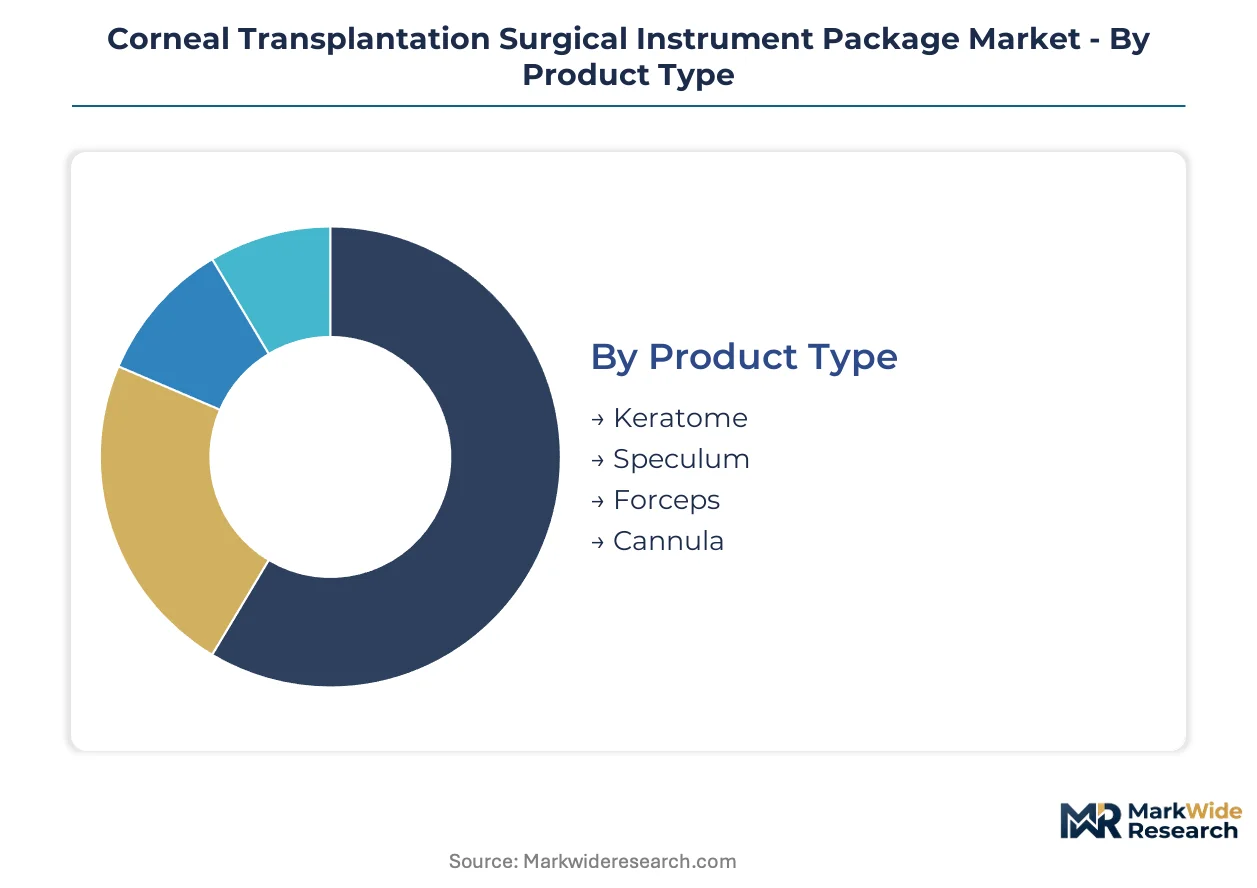
Instrument package configuration varies sharply by surgical technique and facility infrastructure. Procurement departments prioritize bundles that match specific keratoplasty workflows while managing sterilization compliance costs.
Product Type:
Keratome-based packages face intensifying substitution pressure from femtosecond laser systems in premium settings, while reusable speculum and forceps sets confront single-use alternatives in infection-sensitive environments.
- Keratome:Mechanical microkeratome packages retain dominance in price-sensitive markets due to lower capital requirements and established surgeon familiarity. Academic medical centers in the United States are unwinding purchases toward femtosecond-compatible configurations as fellowship programs expand complex lamellar procedure volumes.
- Speculum:Wire and solid blade designs engineered for minimal corneal distortion during graft placement. Demand concentrates in ambulatory surgical centers lacking central sterile processing capacity, driving preference toward single-use disposable sets despite per-procedure cost premiums.
- Forceps:Corneal forceps with platform-specific jaw geometries for donor tissue manipulation and graft insertion.
- Cannula:Irrigation and aspiration cannulas sized for anterior chamber maintenance during endothelial keratoplasty.
Keratome packages anchor the volume base while speculum disposables gain share at the steepest rate.
Application:
Procedure migration toward lamellar techniques is fragmenting package demand across penetrating and endothelial keratoplasty workflows with divergent instrument density requirements.
- Descemet's Stripping Automated Endothelial Keratoplasty:DSAEK instrument packages incorporate donor tissue preparation tools alongside recipient bed creation sets. Hospital procurement departments in the United States are expanding purchases as payer coverage codes solidify reimbursement pathways for this intermediate-complexity procedure.
- Penetrating Keratoplasty:Full-thickness graft packages require trephine systems and comprehensive suturing instrumentation. Volume is concentrating in emerging markets where endothelial keratoplasty training infrastructure remains underdeveloped and mechanical keratome cost advantages persist.
- Endothelial Keratoplasty:Broad category encompassing posterior lamellar procedures with specialized donor insertion devices.
- DMEK:Descemet's Membrane Endothelial Keratoplasty packages feature ultrathin graft manipulation tools and standardized donor preparation scrolls.
Penetrating keratoplasty anchors the volume base while DMEK climbs the fastest as technical proficiency spreads through fellowship networks.
End User:
Facility scale and sterile processing infrastructure determine package economics, with smaller sites favoring disposable configurations that externalize compliance burdens.
- Hospitals:Academic medical centers with fellowship programs drive premium package adoption for training volume. These institutions maintain central sterile processing departments capable of validating reusable instrument sets under FDA Quality System Regulation protocols.
- Ambulatory Surgical Centers:Freestanding ASCs prioritize single-use disposables to eliminate sterilization infrastructure investment. Procurement is shifting toward procedure-specific kits as case volume concentrates in specialized ophthalmology-focused facilities.
- Eye Clinics:Office-based settings with limited surgical volume favor pre-sterilized disposable packages.
- Research Institutes:Preclinical and translational research facilities require instrument packages compatible with experimental graft protocols.
Hospitals anchor the volume base while ambulatory surgical centers expand most quickly as outpatient keratoplasty migration accelerates.
Technology:
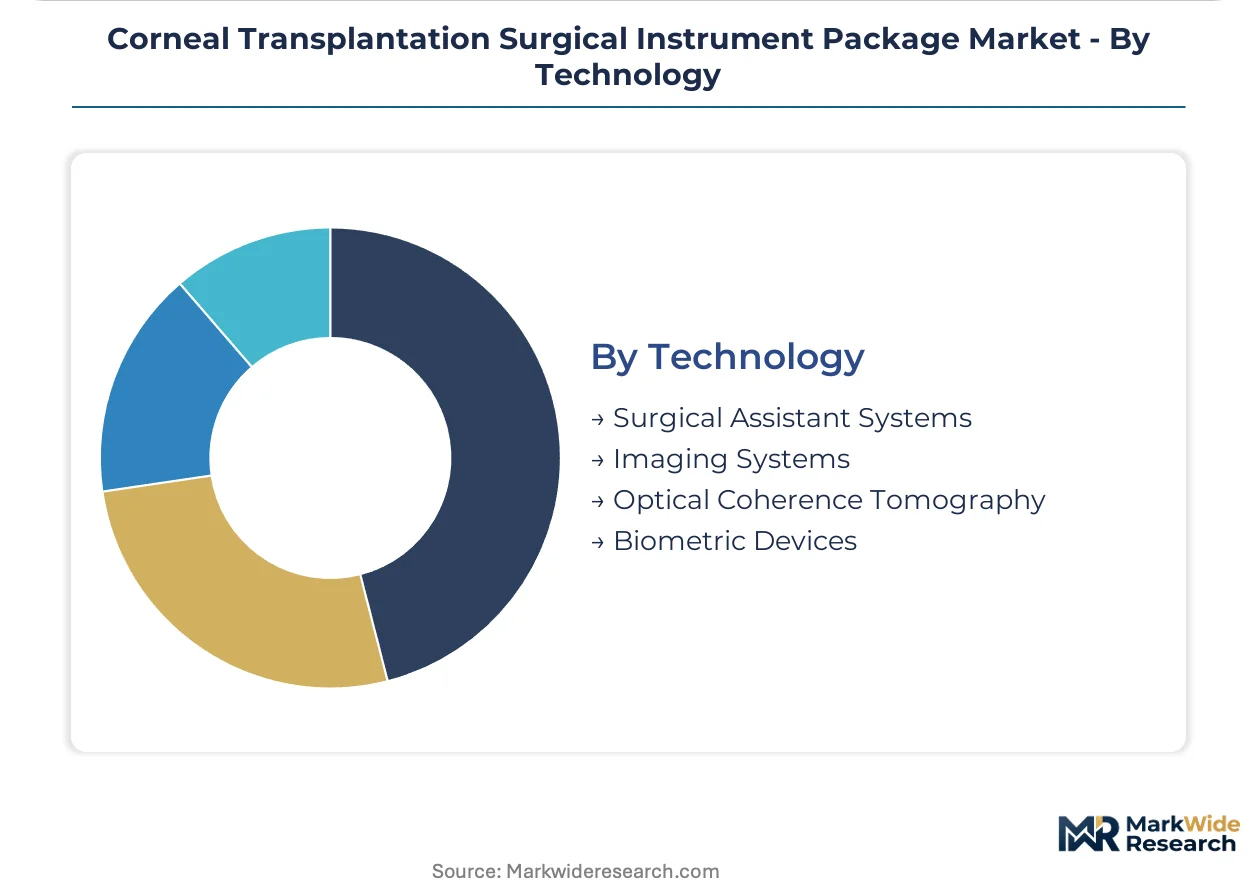
Margin pools are concentrating among vendors bundling imaging-to-surgical workflow systems rather than standalone instrument packages.
- Optical Coherence Tomography:OCT-integrated packages enable real-time graft alignment verification during endothelial keratoplasty. Carl Zeiss Meditec AG and integrated platform vendors are capturing premium positioning through bundled instrument-imaging workflows in European teaching hospitals.
- Surgical Assistant Systems:Robotic and computer-assisted positioning platforms for donor tissue manipulation.
- Imaging Systems:Specular microscopy and pachymetry tools for preoperative graft assessment.
- Biometric Devices:Corneal topography and tomography systems for recipient bed measurement.
Surgical assistant systems anchor the volume base while optical coherence tomography gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision ophthalmic instrument packages to United States academic medical centers, while Swiss and French suppliers serve Middle Eastern hospital procurement departments expanding keratoplasty capacity.
United States
Fellowship training programs at academic medical centers in Boston, New York, and Baltimore are expanding keratoplasty volumes. FDA Quality System Regulation compliance requirements are elevating capital barriers for reusable instrument set vendors. Procurement departments in the Midwest are consolidating purchases around direct manufacturer relationships that bundle instrument packages with education credits.
Germany
European teaching hospitals in Munich and Heidelberg are adopting premium instrument configurations for complex lamellar procedures. EU Medical Device Regulation clinical evidence requirements on Class IIa ophthalmic surgical kits are extending time-to-market for new package configurations. The Baden-Württemberg medical technology cluster anchors precision manufacturing for keratome and speculum systems.
Switzerland
Swissmedic oversight of Class IIa device conformity assessments is concentrating procurement around established notified body relationships. Zurich and Basel-based manufacturers are bundling instrument packages with optical coherence tomography platforms for real-time graft alignment. Swiss teaching hospitals are prioritizing vendors with integrated imaging-to-surgical workflow capabilities.
Japan
PMDA marketing authorization requirements for reusable corneal instrument sets are compressing margins for distributors lacking in-house regulatory affairs capacity. Tokyo and Osaka academic centers are expanding DMEK procedure volumes through fellowship networks. Japanese procurement departments favor validated reusable pathways where central sterile processing infrastructure supports ISO 13485 compliance.
United Arab Emirates
Dubai and Abu Dhabi hospital groups are importing premium instrument packages for medical tourism keratoplasty programs. MOHAP device registration requirements are shaping vendor selection toward suppliers with established Gulf distributor networks. Procurement in the Emirates concentrates on single-use disposable configurations that eliminate sterilization infrastructure investment.
Corneal Transplantation Surgical Instrument Package Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities and direct sales team embedding. The vendor base concentrates around three tiers: integrated imaging-to-surgical platform vendors, standalone instrument package manufacturers, and regional distributors serving price-sensitive facilities. Strategic archetypes include bundling specialists, compliance-heavy European precision fabricators, and scale-driven disposable producers. Competitive moves center on M&A for regulatory affairs talent acquisition and capacity expansion in ISO 13485-certified facilities.
Within the integrated platform tier, Carl Zeiss Meditec AG and Ziemer Ophthalmic Systems AG exemplify vendors capturing premium positioning through bundled instrument-imaging workflows. Among standalone instrument specialists, MORIA represents the European precision manufacturing archetype serving teaching hospitals with reusable keratome systems. Alcon Inc. anchors the North American direct sales model, embedding technical support teams within major ophthalmology departments to secure procedure-specific training commitments.
| Leading Market Players |
|---|
| MORIA |
| OASIS Medical |
| Rumex |
| Peregrine |
| OPHMED |
| ASICO |
| Alcon Inc. |
| Carl Zeiss Meditec AG |
| Ziemer Ophthalmic Systems AG |
| Others |
Value Network & Pricing Analysis
Ninety-day sterilization validation cycles for reusable corneal instrument sets compress distributor working capital and amplify pricing power for ISO 13485-certified manufacturers with captive sterile processing capacity. This lead-time band concentrates margin capture among German and Swiss precision fabricators while forcing price-sensitive hospitals toward single-use disposable alternatives.
Pricing Analysis
Femtosecond laser-compatible instrument packages command three-to-five-fold premiums over mechanical microkeratome configurations, while next-generation OCT-integrated bundles capture additional margin through real-time graft alignment capabilities. Three-tier pricing structure across premium, standard, and economy levels stratifies by sterilization pathway—validated reusable sets, single-use disposables, and hybrid configurations—with ISO 13485 certification tier and fellowship training bundling as primary price differentiation drivers. Cost compression in mechanical keratome tiers is intensifying because academic medical centers are consolidating purchases around direct manufacturer relationships. Ambulatory surgical centers exhibit highest price sensitivity due to per-procedure cost accounting, while teaching hospitals with central sterile processing departments absorb reusable set premiums.
Supply Chain Analysis
Germany and Switzerland anchor precision manufacturing for keratome and speculum systems, while the United States concentrates sterile processing validation and distribution infrastructure. Stainless steel surgical-grade alloys, medical-grade polymers for single-use disposables, and ethylene oxide sterilization equipment constitute critical input dependencies. Single-source vulnerability in European notified body relationships for EU MDR compliance creates bottleneck risk for new package configurations. Distribution runs through direct manufacturer sales teams embedded in major ophthalmology departments, bypassing traditional distributor intermediaries in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corneal transplantation surgical instrument package market sits in early-cycle expansion as DMEK and DSAEK procedures displace full-thickness penetrating keratoplasty through fellowship network diffusion. Endothelial keratoplasty technique migration creates durable tailwinds for specialized instrument configurations.
For Market Incumbents: Compound defensive positioning by acquiring regulatory affairs talent to navigate FDA Quality System Regulation and EU MDR documentation burdens, while expanding ISO 13485-certified sterile processing capacity in Baden-Württemberg and Zurich manufacturing clusters. Femtosecond laser substitution pressure threatens mechanical keratome margins; vertical integration into optical coherence tomography platforms preserves pricing power through bundled imaging-to-surgical workflows.
For New Entrants and Emerging Players: Differentiate on single-use disposable configurations for ambulatory surgical centers lacking central sterile processing infrastructure, where infection control protocols externalize compliance costs. The Middle East medical tourism corridor—specifically Dubai and Abu Dhabi hospital groups—offers the most penetrable geography given MOHAP registration pathways and premium procurement budgets. Target direct-to-facility distribution partnerships with Gulf distributor networks rather than embedded sales team replication.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity arbitrage play because FDA and EU MDR compliance burdens are elevating capital requirements and compressing margins for distributor-dependent business models. Acquisition candidates should demonstrate established notified body relationships and MDR technical documentation capabilities for Class IIa ophthalmic surgical kits. The signal to watch is reimbursement code expansion for DMEK procedures, which would trigger hospital capital allocation shifts toward premium instrument package configurations.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | EU Medical Device Regulation compliance accelerates market access for Class IIa ophthalmic surgical kits in Heidelberg and Munich teaching hospitals. |
| Direct Sales Team Embedding | Field-based technical support within Boston and Baltimore ophthalmology departments secures procedure-specific training commitments and fellowship education credits. |
| OCT Platform Integration | Real-time graft alignment verification bundles concentrate margin pools among vendors with imaging-to-surgical workflow capabilities. |
| Single-Use Disposable Expansion | Ambulatory surgical center procurement prioritizes pre-sterilized configurations that eliminate central sterile processing infrastructure investment. |
| Fellowship Training Partnership | Academic medical center relationships in the United States drive premium package adoption as keratoplasty volumes expand through education networks. |
Research Methodology
Operator-level perspectives from hospital procurement managers, ophthalmology department chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract records, and CMS Medicare reimbursement code updates. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation cross-checked segmentation outputs.
Sensitivity analysis across sterilization pathway adoption rates, femtosecond laser penetration assumptions, and fellowship program expansion trajectories tested forecast robustness over the projection horizon. Segmentation dimensions modeled include product type, application technique, end-user facility scale, and technology integration level, with reimbursement code coverage and regulatory compliance cost inflation as industry-specific forecast inputs. CAGRs derived from procedure volume elasticity to training program expansion and payer coverage decisions.
The analysis sits within stated boundaries; outcomes outside sustained endothelial keratoplasty technique migration or delayed DMEK reimbursement code expansion would require recalibration. Forecasts reflect assumptions regarding sterilization validation capacity, notified body relationship durability, and fellowship network growth trajectories. Recalibration cycles align with material shifts in FDA device classification rules, EU MDR enforcement patterns, and payer coverage determinations for lamellar keratoplasty procedures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
Homecare Surgical Drains Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Dissolvable Sutures Market
Surgical Instruments
Endoscopic Closure Systems Market
Surgical Instruments
United States Minimally Invasive Surgery Market
Surgical Instruments
Laparotomy Sponges Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Biosurgery Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market
Surgical Instruments
United Arab Emirates General Surgical Devices Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Global Electromagnetic Surgical Navigation System Market
Surgical Instruments
Spain General Surgical Devices Market