
 Asia Pacific Surgical Equipment Market | 2026-2036
Asia Pacific Surgical Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Surgical Equipment Market Analysis
Trained surgical robotics specialists are reorganizing capacity planning across the Asia Pacific region. Medtronic PLC leverages its integrated surgical ecosystem to anchor high-volume procedural suites in tertiary hospitals. Stryker Corporation competes through specialized orthopedic navigation platforms calibrated for Asian anatomical variance. Johnson & Johnson sustains broad category coverage across sutures, staplers, and energy devices.
Asia Pacific surgical equipment encompasses instruments, powered devices, and robotic platforms engineered for tissue manipulation, hemostasis, and wound closure with ISO 13485-validated sterility assurance levels. These systems enable precise intervention across cardiac, orthopedic, and neurological procedures in settings ranging from major teaching hospitals to ambulatory surgical centers. Electrosurgical devices and surgical robotics command premium positioning due to capital intensity and software-integrated service models. Handheld instruments occupy stable volume tiers where procurement consolidation favors suppliers with foundry-to-sterile-packaging control.
Japan's PMDA, China's NMPA, and India's CDSCO enforce divergent clinical evidence requirements that fragment registration timelines and reshape market entry sequencing for multinational manufacturers. The EU MDR's extraterritorial influence on reference-country approvals adds compliance layering for devices sourced from European parents. Stakeholders must monitor regulatory reciprocity negotiations between ASEAN member states and major economies to anticipate where first-mover registration advantages will crystallize.
Market Dynamics
Japan's PMDA regulatory harmonization with ASEAN standards is compressing cross-border approval timelines and redrawing competitive entry sequences across the region's surgical device landscape. This structural shift is accelerating the relocation of registration-first strategies toward Singapore and Thailand as reference markets.
Growth Catalysts
- Electrosurgical platform proliferation:Tertiary hospitals in India and South Korea are retrofitting hybrid operating theaters with integrated energy systems that consolidate cutting and coagulation functions into single console architectures.
- PMDA-ASEAN regulatory reciprocity:Japan's pharmaceutical and medical device agency is piloting mutual recognition protocols that reduce duplicate clinical trials for Class III devices seeking simultaneous approval across Tokyo, Singapore, and Bangkok.
- Ambulatory surgical center expansion:Day-procedure volumes in Australia's private clinic networks are climbing as cataract and arthroscopic workflows shift away from inpatient settings, pulling portable instrument demand upward.
Market Restraints
- High-purity stainless steel supply concentration:Foundry capacity for surgical-grade 316L and 17-4 PH alloys clusters in China's Jiangsu and Zhejiang provinces, exposing instrument manufacturers to input cost volatility and export permit delays.
- CDSCO evidence requirements:India's central drugs standard control organization mandates local clinical data for novel robotic platforms, extending registration timelines by eighteen to thirty months versus reference-country pathways.
- Reusable instrument reprocessing liability:Hospital sterilization departments face escalating insurance costs and protocol complexity as prion and viral inactivation standards tighten across Australian and New Zealand health systems.
Strategic Opportunities
- Vietnam's private hospital buildout:Ho Chi Minh City and Hanoi are attracting foreign direct investment into joint-venture surgical centers that specify North American and European equipment procurement standards.
- AI-integrated navigation convergence:Machine learning algorithms are fusing with optical tracking systems to enable real-time anatomical mapping for spine and cranial procedures, creating software-hardware bundled revenue streams.
- Malaysia's medical device hub incentives:The country's investment development authority offers ten-year tax holidays and duty exemptions for manufacturers establishing sterile packaging and final assembly operations in Penang and Johor.
Industry Challenges
- Robotic surgery specialist scarcity:Training programs in Indonesia and the Philippines produce fewer than two hundred console-certified surgeons annually, constraining throughput at installed da Vinci and Versius sites.
- Legacy EMR integration friction:Japanese and South Korean hospitals operate on fragmented electronic medical record architectures that resist seamless data exchange with newer surgical navigation platforms, delaying go-live schedules.
- ISO 13485 certification backlogs:Notified bodies accredited for quality management system audits in the Asia Pacific region carry six-to-nine month waiting lists, slowing market entry for emerging manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Surgical Equipment Market |
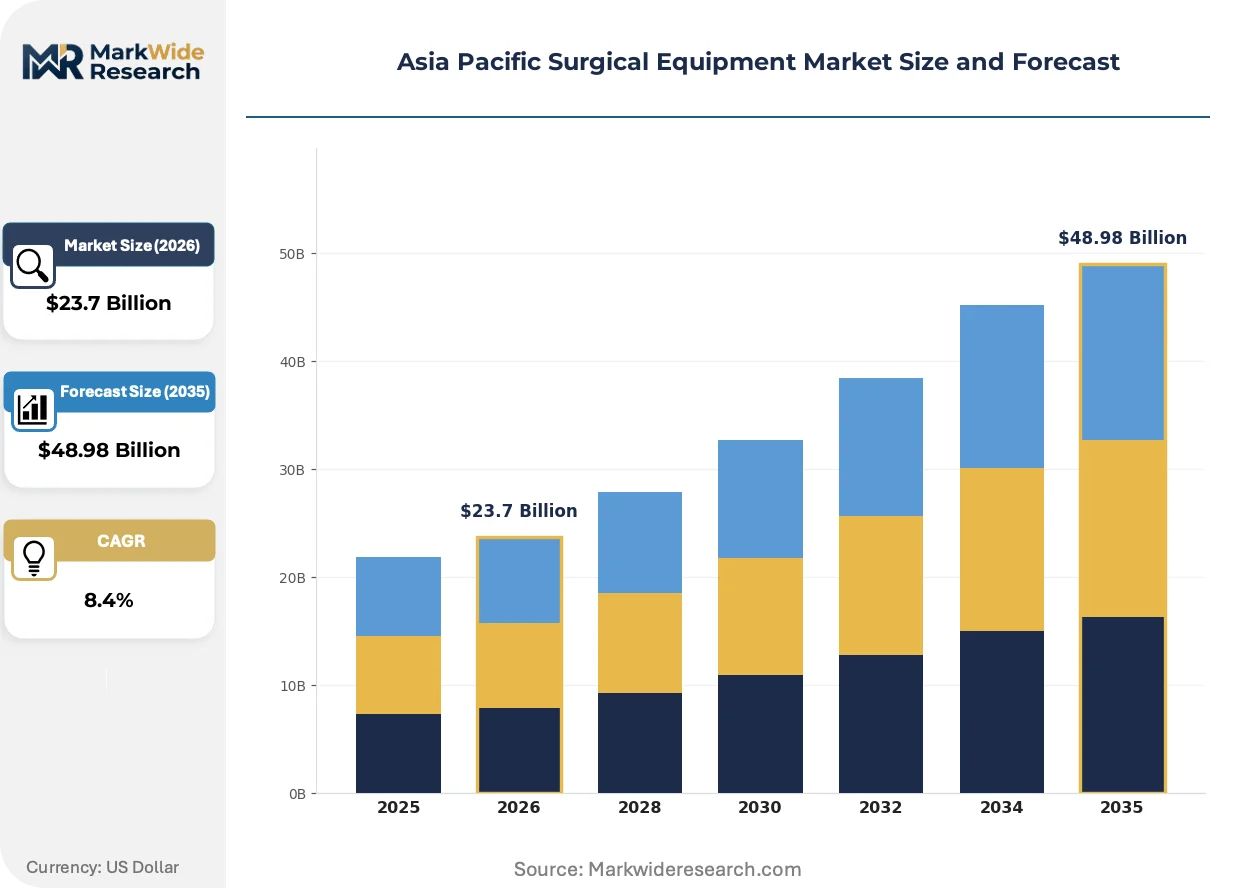
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrosurgical Devices, Surgical Sutures, Handheld Instruments, Surgical Robotics End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Surgery Centers Technology: Minimally Invasive Surgery, Traditional Surgery, Robotic Surgery, Laser Surgery Application: Orthopedic Surgery, Cardiothoracic Surgery, Neurosurgery, General Surgery |
| Companies Covered | B. Braun SE, Boston Scientific Corporation, Medtronic PLC, CONMED Corporation, Zimmer Biomet Holdings Inc, Stryker Corporation, Smith & Nephew PLC, Olympus Corporation, Johnson & Johnson, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Surgical Equipment Market Emerging Trajectories
Digital surgery ecosystems are displacing standalone instrument sales across the Asia Pacific region, with software-integrated platforms capturing preference in high-volume orthopedic and cardiac centers. This shift is compressing traditional procurement cycles and elevating service contract economics.
Single-port robotic access systems are miniaturizing abdominal and thoracic procedure entry points from multi-incision architectures to single umbilical or natural-orifice approaches. Japanese university hospitals in Osaka and Nagoya are piloting these platforms for colorectal and gynecologic workflows. The technology is miniaturizing patient recovery timelines and reducing postoperative complication rates, forcing competitors to accelerate compact arm development programs.
China's NMPA has implemented priority review pathways for domestically manufactured innovative devices, compressing approval timelines from twenty-four months to twelve for qualifying submissions. This regulatory tailwind is redirecting multinational localization strategies toward Suzhou and Shenzhen manufacturing partnerships. Korean and Taiwanese component suppliers are repositioning as primary vendors to capture volume from these accelerated approval channels.
Hospital procurement committees across Thailand and Malaysia are unbundling after-sales service contracts from capital equipment purchases, negotiating separate multi-year maintenance agreements with third-party technical service providers. This behavior is fragmenting vendor revenue streams and elevating spare parts pricing transparency as a competitive battleground. Singapore's integrated hospital networks are pioneering this disaggregation model, with private operators in Bangkok and Kuala Lumpur following within eighteen months.
Asia Pacific Surgical Equipment Market Segmentation
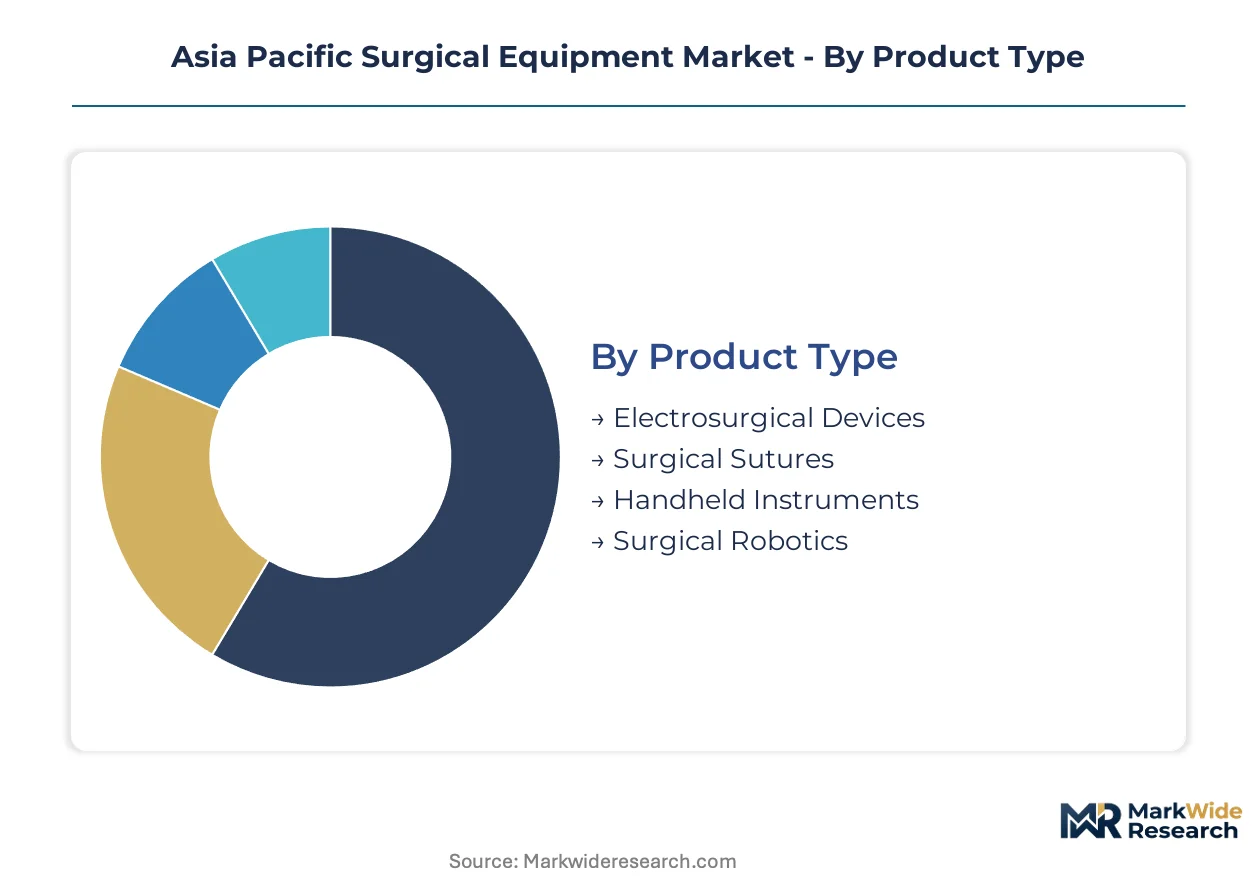
Surgical equipment procurement in Asia Pacific fragments across capital intensity tiers, with electrosurgical platforms and robotic systems commanding multi-year service contracts while handheld instruments flow through consolidated distributor networks. Understanding these segment boundaries clarifies where pricing power concentrates versus where volume throughput drives returns.
Product Type:
Margin pools concentrate in capital equipment segments where software-integrated service models generate recurring revenue streams beyond initial hardware placement.
- Electrosurgical Devices:Generator-and-accessory architectures deliver controlled thermal energy for cutting and coagulation, integrating vessel sealing and impedance feedback algorithms. Tertiary hospitals in South Korea and India are retrofitting hybrid operating theaters with single-console systems that consolidate previously separate electrosurgical and ultrasonic functions.
- Surgical Robotics:Multi-arm platforms with haptic feedback and 3D visualization enable remote manipulation through small incisions. Japan's PMDA accelerated approval pathways are expanding installed bases at university hospitals in Tokyo and Osaka, though console-certified surgeon scarcity constrains throughput utilization.
- Surgical Sutures:Absorbable and non-absorbable closure products with antimicrobial coatings address wound healing protocols across cardiac and orthopedic procedures.
- Handheld Instruments:Forceps, retractors, and scalpels manufactured from surgical-grade 316L stainless steel serve high-volume general surgery workflows in India's metropolitan hospital chains.
Electrosurgical devices hold installed capacity. Surgical robotics is rotating up the share rankings.
End User:
Procurement authority patterns diverge sharply between public hospital systems with tender-driven purchasing and private chains negotiating direct vendor relationships.
- Hospitals:Multi-specialty tertiary centers with catheterization labs and hybrid operating theaters anchor capital equipment demand for integrated surgical platforms across India, Japan, and Australia.
- Ambulatory Surgical Centers:Day-procedure facilities specializing in cataract, arthroscopic, and endoscopic workflows are expanding across Australia's private clinic networks and Thailand's medical tourism corridors.
- Specialty Surgery Centers:Dedicated cardiac, orthopedic, and ophthalmology facilities concentrate procedural volume and equipment specialization in Singapore and South Korea.
- Clinics:Primary care and minor procedure settings in Indonesia and Vietnam source portable electrosurgical units and basic instrument sets through distributor networks.
Hospitals dominate capital allocation. Ambulatory surgical centers are gaining share fastest in day-procedure migration.
Technology:
Adoption velocity varies by reimbursement environment and surgeon training infrastructure across the region's heterogeneous healthcare systems.
- Minimally Invasive Surgery:Laparoscopic and endoscopic techniques through small incisions reduce recovery timelines and complication rates. China's NMPA priority review pathways are accelerating domestic port access device approvals.
- Robotic Surgery:Telemanipulation platforms with tremor filtration and motion scaling enable precise intervention in confined anatomical spaces. Training program bottlenecks in Indonesia and the Philippines constrain expansion despite installed console growth.
- Traditional Surgery:Open procedural approaches persist in emergency settings and resource-constrained environments across rural India and Vietnam where capital equipment penetration remains limited.
- Laser Surgery:Tissue ablation and photocoagulation systems serve ophthalmology and dermatology applications with specialized wavelength delivery systems.
Minimally invasive surgery holds procedural volume leadership. Robotic surgery is climbing the fastest in metropolitan tertiary centers.
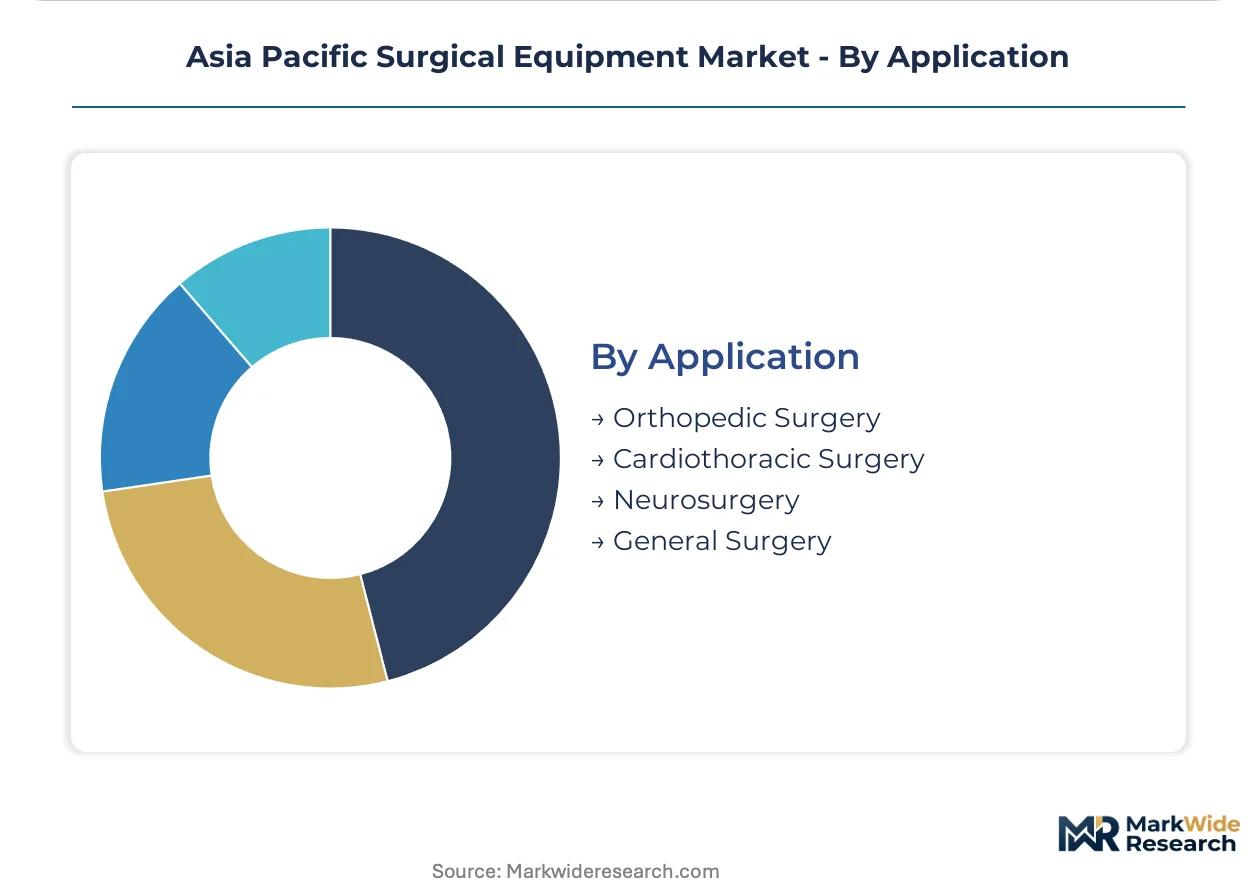
Application:
Procedure reimbursement rates and clinical outcome data availability shape equipment investment priorities across surgical disciplines.
- Orthopedic Surgery:Joint replacement, spine, and sports medicine procedures drive navigation platform and powered instrument demand. Stryker's specialized navigation systems calibrated for Asian anatomical variance capture preference in South Korean and Japanese arthroplasty centers.
- Cardiothoracic Surgery:Coronary artery bypass, valve repair, and lung resection procedures require cardiopulmonary bypass support and precision suturing systems. India's metropolitan hospital chains are building dedicated cardiac surgery units with hybrid operating theater configurations.
- Neurosurgery:Cranial and spinal procedures leverage optical navigation and intraoperative imaging for tumor resection and vascular intervention.
- General Surgery:Appendectomy, cholecystectomy, and hernia repair constitute high-volume workflows sustaining handheld instrument and basic electrosurgical demand.
Orthopedic surgery holds equipment installed base. Cardiothoracic surgery is expanding most quickly in private hospital buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PMDA's regulatory harmonization with ASEAN standards anchors Japan's influence over cross-border device approval timelines across the Asia Pacific surgical equipment landscape.
Japan
University hospitals in Tokyo and Osaka are retrofitting hybrid operating theaters with integrated energy platforms. PMDA accelerated approval pathways for Class III devices compress registration timelines versus historical baselines. The Kansai region around Osaka anchors single-port robotic pilot programs for colorectal workflows.
China
Metropolitan hospital chains in Shanghai and Beijing are building dedicated cardiac surgery units with robotic console installations. NMPA priority review pathways for domestically manufactured innovative devices compress approval timelines from twenty-four months to twelve. Suzhou and Shenzhen manufacturing partnerships are capturing accelerated approval channel volume.
India
Private operators in Delhi, Mumbai, and Bangalore are constructing dedicated robotic surgery centers with da Vinci and Versius platforms. CDSCO mandates local clinical data for novel robotic platforms, extending registration timelines eighteen to thirty months versus reference-country pathways. Maharashtra's hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases.
South Korea
Tertiary centers in Seoul are adopting specialized orthopedic navigation platforms calibrated for Asian anatomical variance. MFDS enforces clinical evidence requirements that align with international standards while maintaining domestic quality benchmarks. The Seoul Capital Area concentrates arthroplasty center density and navigation platform installed base.
Australia
Private clinic networks in Sydney and Melbourne are expanding day-procedure volumes for cataract and arthroscopic workflows. TGA sterilization protocol tightening is escalating insurance costs for hospital sterilization departments. Victoria's ambulatory surgical centers are pulling portable instrument demand upward through distributor networks.
Asia Pacific Surgical Equipment Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational conglomerates controlling capital equipment segments while regional fabricators capture handheld instrument volume. The structure rewards foundry-to-sterile-packaging control and software-integrated service models. Three archetypes dominate: integrated surgical ecosystem providers, specialized navigation platform developers, and broad category coverage manufacturers. Competitive moves concentrate on strategic partnerships for regulatory reciprocity and capacity expansion into ASEAN manufacturing hubs.
Within the integrated ecosystem tier, Medtronic PLC and Stryker Corporation exemplify contrasting strategic positions. Medtronic anchors high-volume procedural suites through service contract bundling, while Stryker occupies the specialized navigation vector with platforms calibrated for anatomical variance. Johnson & Johnson represents the broad category coverage archetype, sustaining presence across sutures, staplers, and energy devices through procurement consolidation relationships.
| Leading Market Players |
|---|
| B. Braun SE |
| Boston Scientific Corporation |
| Medtronic PLC |
| CONMED Corporation |
| Zimmer Biomet Holdings Inc |
| Stryker Corporation |
| Smith & Nephew PLC |
| Olympus Corporation |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Domestic NMPA approvals substituting for EU MDR reference-country pathways are relocating manufacturing partnerships toward Suzhou and Shenzhen while compressing procurement timelines for multinational hospital chains. This geographic shift simultaneously elevates price competition among Korean and Taiwanese component suppliers and tightens margin structures for legacy European-sourced instrument portfolios.
Pricing Analysis
Long-term service contracts bundling capital equipment with multi-year maintenance agreements dominate tertiary hospital procurement in Japan and Australia, though unbundling trends in Singapore and Thailand fragment vendor revenue streams. Price differentiation hinges on ISO 13485 certification tier and after-sales service integration depth. Cost compression in handheld instrument tiers intensifies as Chinese foundry output expands. Public hospital tender committees in India exhibit highest price sensitivity, while private robotic surgery centers in South Korea prioritize platform capability over unit economics.
Supply Chain Analysis
Inventory lead times for surgical-grade 316L and 17-4 PH stainless steel extend when export permit delays emerge from Jiangsu and Zhejiang province foundries. Raw material sourcing draws from Chinese alloy production, German precision machining, and Japanese optical component fabrication. Single-source vulnerability concentrates in electrosurgical generator subassemblies. Distribution runs through consolidated distributor networks for handheld instruments and direct vendor relationships for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific surgical equipment sits in early-cycle expansion as PMDA-ASEAN regulatory reciprocity accelerates cross-border device approvals and redraws competitive entry sequences. Robotic platform penetration remains below twenty percent of addressable procedural volume across Indonesia and Vietnam.
For Market Incumbents: Shield installed base economics by deepening backward integration into sterile packaging operations in Penang and Johor, countering Malaysian hub incentives that attract emerging competitors. Accelerate ISO 13485 certification pre-investment to circumvent notified body backlogs that delay market entry for challengers.
For New Entrants and Emerging Players: Differentiate on AI-integrated navigation convergence for spine and cranial applications, where software-hardware bundling creates defensible revenue streams. Vietnam's private hospital buildout in Ho Chi Minh City and Hanoi represents the most penetrable geography, with joint-venture procurement standards favoring North American and European equipment specifications.
For Investors and Strategic Acquirers: Capital is best deployed toward component suppliers repositioning as primary vendors to NMPA accelerated approval channels, capturing volume from domestic manufacturing partnerships in Suzhou and Shenzhen. Monitor training program throughput in Indonesia and the Philippines as the signal indicating when robotic console utilization rates will inflect upward.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA-ASEAN Regulatory Reciprocity Pursuit | Compresses duplicate clinical trial requirements across Tokyo, Singapore, and Bangkok approval pathways. |
| Domestic NMPA Manufacturing Partnership | Captures twelve-month priority review timelines for innovative devices produced in Suzhou and Shenzhen. |
| Service Contract Unbundling Response | Addresses Singapore hospital procurement committee demands for transparent spare parts pricing. |
| Surgeon Training Program Expansion | Alleviates console-certified specialist scarcity constraining da Vinci and Versius throughput in Southeast Asia. |
| Single-Port Robotic Platform Development | Matches Japanese university hospital pilot programs for colorectal and gynecologic workflows in Osaka and Nagoya. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and regulatory affairs leads at multinational manufacturers, then refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of PMDA submission databases, NMPA priority review disclosures, CDSCO registration records, and hospital procurement tender documents. Bottom-up procedural volume estimates triangulated against top-down equipment shipment data.
Variance decomposition across product type, end user, technology, application, and country regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from modeled equipment replacement cycles, procedural volume trajectories, and reimbursement environment evolution. Forecast inputs incorporated surgeon training pipeline throughput and regulatory reciprocity negotiation status.
Forecasts assume regulatory continuity in PMDA, NMPA, and CDSCO regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
Resectoscopes Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
Neurosurgery Surgical Power Tools Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Europe General Surgical Devices Market
Surgical Instruments
Knotless Tissue Control Devices Market
Surgical Instruments
Global Gauze Swabs Market
Surgical Instruments
Colorectal Procedure Market
Surgical Instruments
Breast Retractors Market
Surgical Instruments
Global Biopsy Needles Market
Surgical Instruments
Global Electromagnetic Surgical Navigation System Market
Surgical Instruments
Middle East and Africa General Surgical Devices Market