
 Vascular Snare Market | 2026-2036
Vascular Snare Market Size, Share, and Industry Trends Forecast 2026-2036
Vascular Snare Market Outlook
The gap between premium single-use snares and reusable commodity alternatives is recalibrating procurement criteria across cath lab networks. Medtronic plc leverages its endovascular portfolio breadth to bundle snare offerings with guiding catheter systems, while Cook Medical anchors its position through deep specialization in interventional radiology workflow integration. Merit Medical Systems, Inc. competes by controlling a direct hospital distribution channel that bypasses third-party logistics markups.
A vascular snare is a looped wire retrieval device, typically constructed from nitinol or stainless steel with a 2–35 mm loop diameter range, designed to encircle and extract foreign bodies, catheter fragments, or dislodged stents from the venous or arterial system. Single use snares command the dominant revenue share due to infection control mandates and elimination of reprocessing liability, whereas electrothermal snare variants represent the fastest-expanding technology segment as operators seek integrated cautery capability for tissue adhesion during retrieval. Manual snares retain volume leadership in emerging markets where capital equipment constraints limit adoption of powered alternatives.
FDA 510(k) premarket notification requirements and EU MDR technical documentation obligations shape product development timelines and clinical evidence thresholds for market authorization. Japan's PMDA enforces QMS ministerial ordinances that add compliance layers for foreign manufacturers seeking reimbursement listing. Stakeholders must monitor evolving nitinol raw material sourcing constraints and cath lab consolidation trends to align manufacturing scale with shifting point-of-care demand patterns.
Market Dynamics
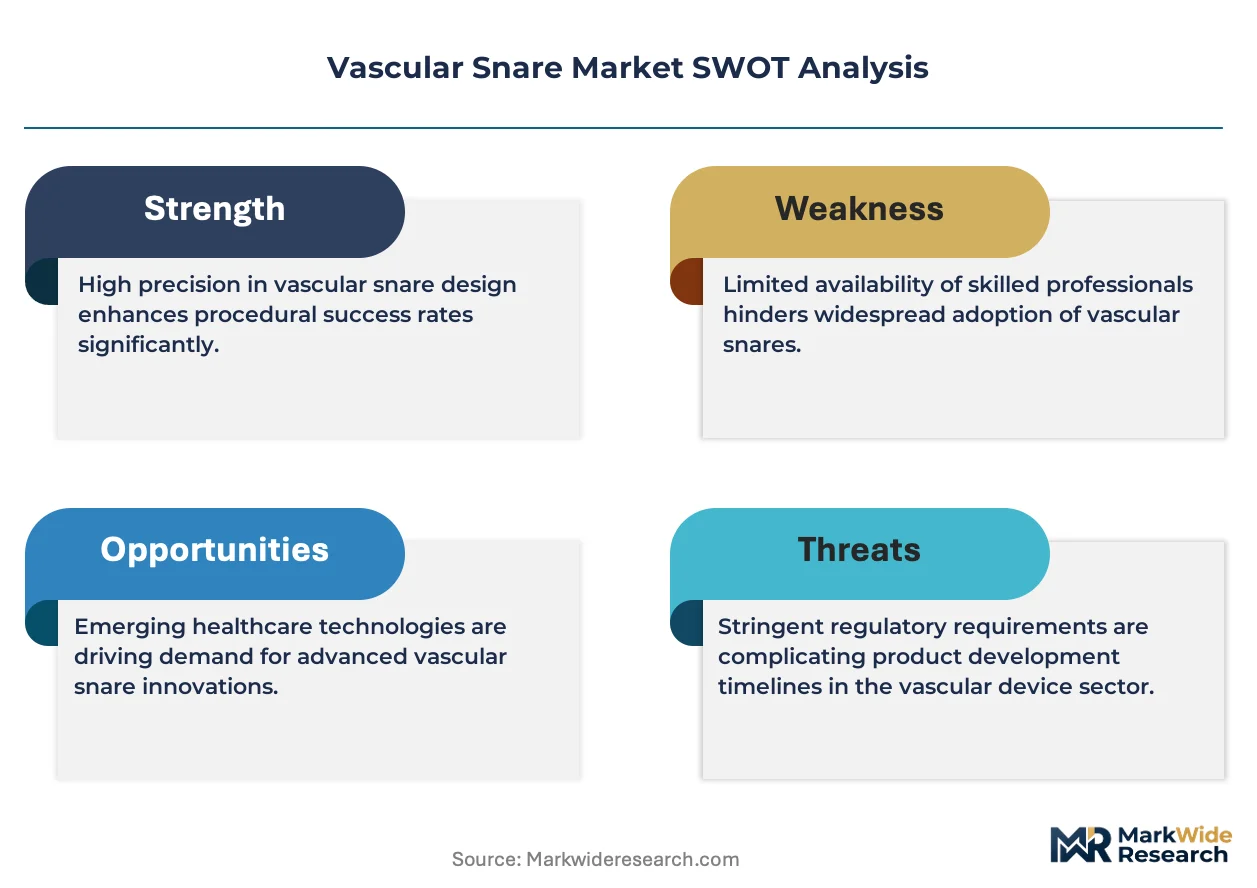
Cath lab consolidation into hospital mega-systems is compressing vendor relationships into multi-year enterprise agreements that privilege bundled device portfolios over standalone snare procurement.
Growth Catalysts
- EU MDR technical documentation mandates:Stricter clinical evidence requirements for nitinol-based devices are accelerating R&D investment in next-generation retrieval systems with enhanced biocompatibility profiles.
- Interventional radiology suite expansion:Hospital systems across Germany and Japan are adding dedicated foreign body retrieval capabilities, creating procedural pull-through for specialized snare configurations.
- Electrothermal integration:Cautery-capable snare variants are capturing preference in complex retrieval cases where tissue adhesion complicates extraction.
Market Restraints
- Nitinol raw material concentration:Superelastic alloy supply chains cluster among limited specialty metal producers, exposing device manufacturers to input volatility and qualification delays.
- Single-use cost structure:Premium disposable snares carry per-procedure costs that strain reimbursement-constrained cath lab budgets in emerging markets.
- Reusable substitute persistence:Stainless steel manual snares retain volume in cost-sensitive settings where reprocessing infrastructure offsets infection control mandates.
Strategic Opportunities
- Japan PMDA QMS pathway optimization:Foreign manufacturers who master ministerial ordinance compliance can secure premium reimbursement positioning ahead of competitors.
- Ambulatory surgical center channel development:Outpatient venous access procedures are migrating from hospital settings, creating demand for compact, procedure-ready snare kits.
- Stent repositioning application expansion:Malfunctioning peripheral vascular stents represent an underaddressed retrieval indication with distinct device performance requirements.
Industry Challenges
- EU MDR notified body capacity constraints:Technical file review backlogs are extending time-to-market for new nitinol loop configurations by 12-18 months.
- Cath lab technician training standardization:Foreign body retrieval proficiency varies across interventional radiology departments, limiting consistent adoption of advanced electrothermal snare techniques.
- Legacy reprocessing infrastructure lock-in:Hospital systems with capital invested in sterilization equipment resist full conversion to single-use protocols despite liability advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vascular Snare Market |
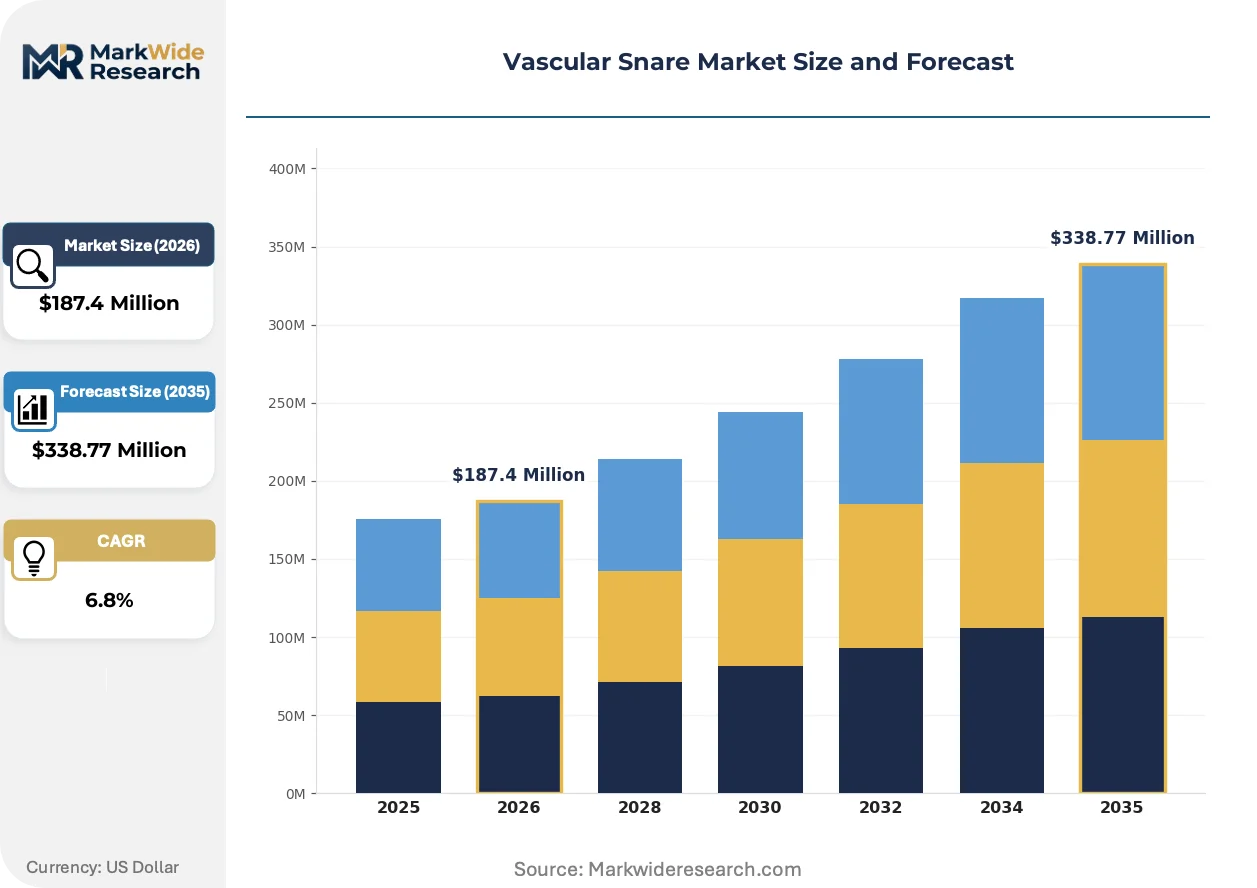
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Use Snare, Multiple Use Snare, Pediatric Snare, Large Snare Application: Cardiac Surgery, Interventional Radiology, Endovascular Procedures, Oncology Procedures End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Centers Technology: Electrothermal Snare, Laser Snare, Pneumatic Snare, Manual Snare |
| Companies Covered | Medtronic plc, Cook Medical, Merit Medical Systems, Inc., Becton, Dickinson and Company, Teleflex Incorporated, Argon Medical Devices, Inc., Boston Scientific Corporation, Terumo Corporation, pfm medical ag, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vascular Snare Market Strategic Shifts
Device convergence with energy delivery systems and procurement centralization into supply chain consortia are rewriting competitive positioning rules for retrieval device manufacturers.
Electrothermal snare technology is overtaking conventional mechanical retrieval in complex cases requiring simultaneous tissue dissection and foreign body capture. Academic medical centers in the United States and university hospitals in Germany are adopting these systems for difficult stent extractions. The technology is overtaking standalone mechanical devices by compressing procedure time and reducing ancillary tool requirements.
FDA 510(k) premarket notification pathways are tightening predicate device equivalence standards for nitinol-based retrieval systems, forcing manufacturers to generate primary clinical performance data rather than relying on historical benchmarks. This regulatory shift extends development timelines but creates differentiation opportunities for sponsors with robust evidence packages. Electrothermal variants face heightened scrutiny due to their combined device-energy classification.
Hospital purchasing consortiums are consolidating snare procurement into multi-category endovascular contracts that bundle retrieval devices with guiding catheters and access sheaths. Integrated delivery networks in the United States and hospital groups in Germany are displacing standalone snare negotiations with enterprise-level agreements. This concentration is most visible in metropolitan health systems where cath lab standardization across multiple facilities creates volume leverage.
Vascular Snare Market Segmentation
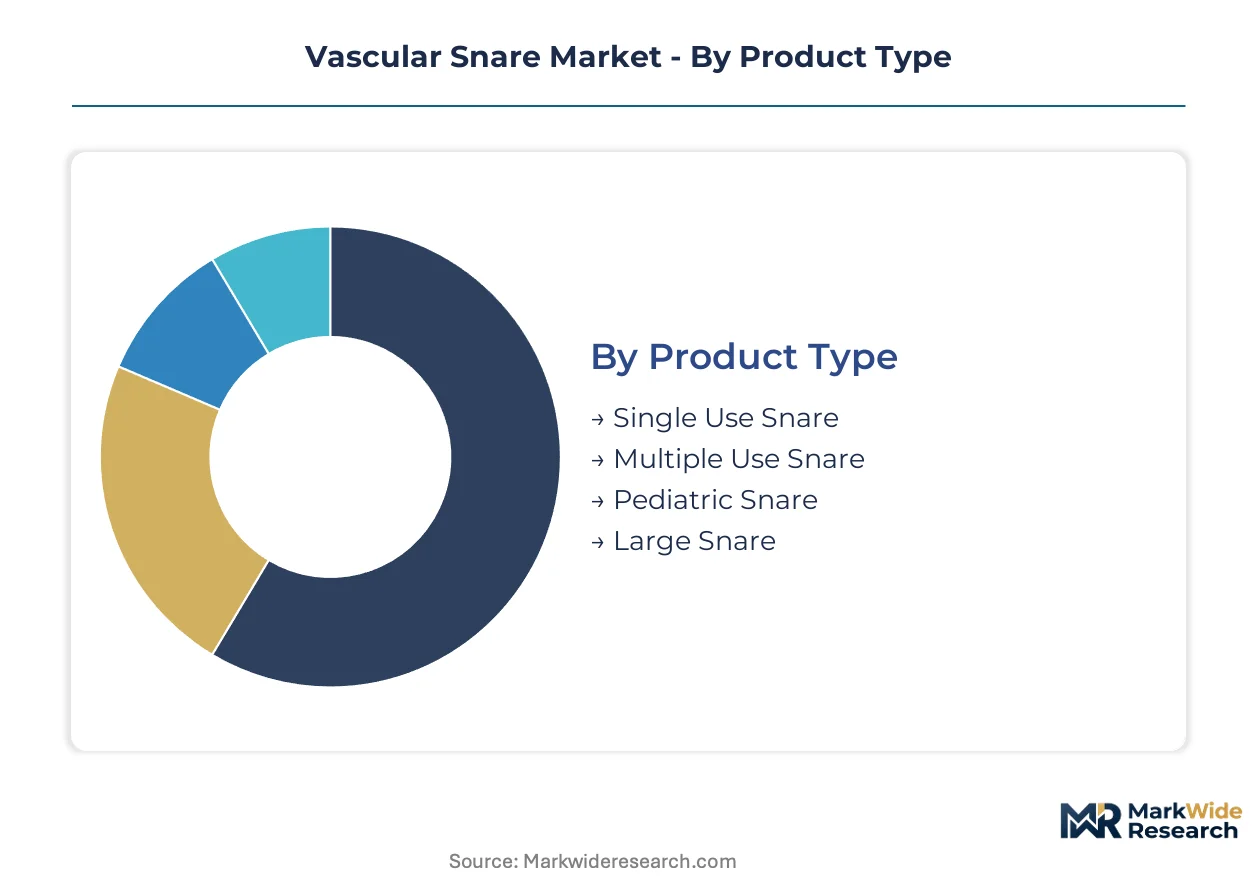
Vascular snare procurement decisions diverge sharply across clinical settings, with infection control mandates, procedural complexity, and capital equipment availability each favoring distinct product configurations. Manufacturers must align portfolio breadth against these heterogeneous demand patterns rather than pursuing uniform market penetration.
Product Type:
Upgrade cycles in cath lab networks are accelerating as hospital mega-systems standardize device protocols across consolidated facilities, displacing legacy reusable inventories.
- Single Use Snare:Nitinol-loop devices packaged for immediate deployment dominate procurement in United States hospital systems where liability exposure and infection control protocols eliminate reprocessing economics. German university hospitals and Japanese tertiary centers absorb premium per-unit costs in exchange for guaranteed sterility and elimination of sterilization queue delays.
- Multiple Use Snare:Stainless steel constructions with validated reprocessing protocols retain footholds in cost-constrained settings where sterilization infrastructure is already capitalized. Demand concentrates in emerging market public hospital networks and select European regional facilities with dedicated central sterile supply departments.
- Pediatric Snare:Reduced loop diameters and enhanced flexibility characteristics address anatomical constraints in neonatal and pediatric interventional suites.
- Large Snare:Extended loop configurations accommodate inferior vena cava filter retrieval and large-vessel foreign body extraction in adult bariatric populations.
Single Use Snare sits at the top of the volume ranking, with Pediatric Snare climbing the fastest as congenital interventional programs expand.
Application:
Procedural volume distribution across clinical specialties determines snare specification requirements, with complexity gradients favoring technology-differentiated offerings.
- Interventional Radiology:Foreign body retrieval and central venous access complication management constitute core demand drivers in dedicated IR suites. United States metropolitan hospital systems and German academic medical centers deploy specialized retrieval teams with preference for electrothermal-capable systems.
- Cardiac Surgery:Intraoperative retrieval of catheter fragments and lead extraction in electrophysiology overlap procedures requires rapid-deployment snare configurations. Japanese cardiovascular centers integrate these devices into hybrid operating room workflows.
- Endovascular Procedures:Stent repositioning and malpositioned device retrieval in peripheral arterial interventions drive demand for torque-responsive snare designs.
- Oncology Procedures:Port catheter and tunneled line fragment retrieval in cancer centers with high venous access device utilization creates specialized workflow requirements.
Interventional Radiology commands the largest procedure base, while Endovascular Procedures are expanding most quickly as peripheral arterial disease interventions proliferate.
End User:
Site-of-care migration is fragmenting purchasing authority, with outpatient facility procurement operating on distinct capital and operational budget cycles.
- Hospitals:Integrated delivery networks in the United States and hospital groups in Germany consolidate snare procurement into enterprise endovascular contracts with multi-year volume commitments. Cath lab standardization across facility networks privileges bundled device portfolios.
- Ambulatory Surgical Centers:Freestanding venous access and dialysis catheter management procedures are migrating to outpatient settings with compact, procedure-ready kit requirements. United States ASC networks seek simplified inventory configurations with minimal sterilization overhead.
- Specialty Clinics:Interventional radiology and vascular surgery specialty practices with procedure-specific focus drive demand for application-optimized snare configurations.
- Rehabilitation Centers:Long-term care facilities with retained central line populations generate episodic retrieval demand through contracted mobile interventional services.
Hospitals retain dominant procurement volume, though Ambulatory Surgical Centers are gaining share fastest as site-of-care shifts accelerate.
Technology:
Capital equipment integration requirements segment technology adoption, with powered systems demanding dedicated generator infrastructure and technician training.
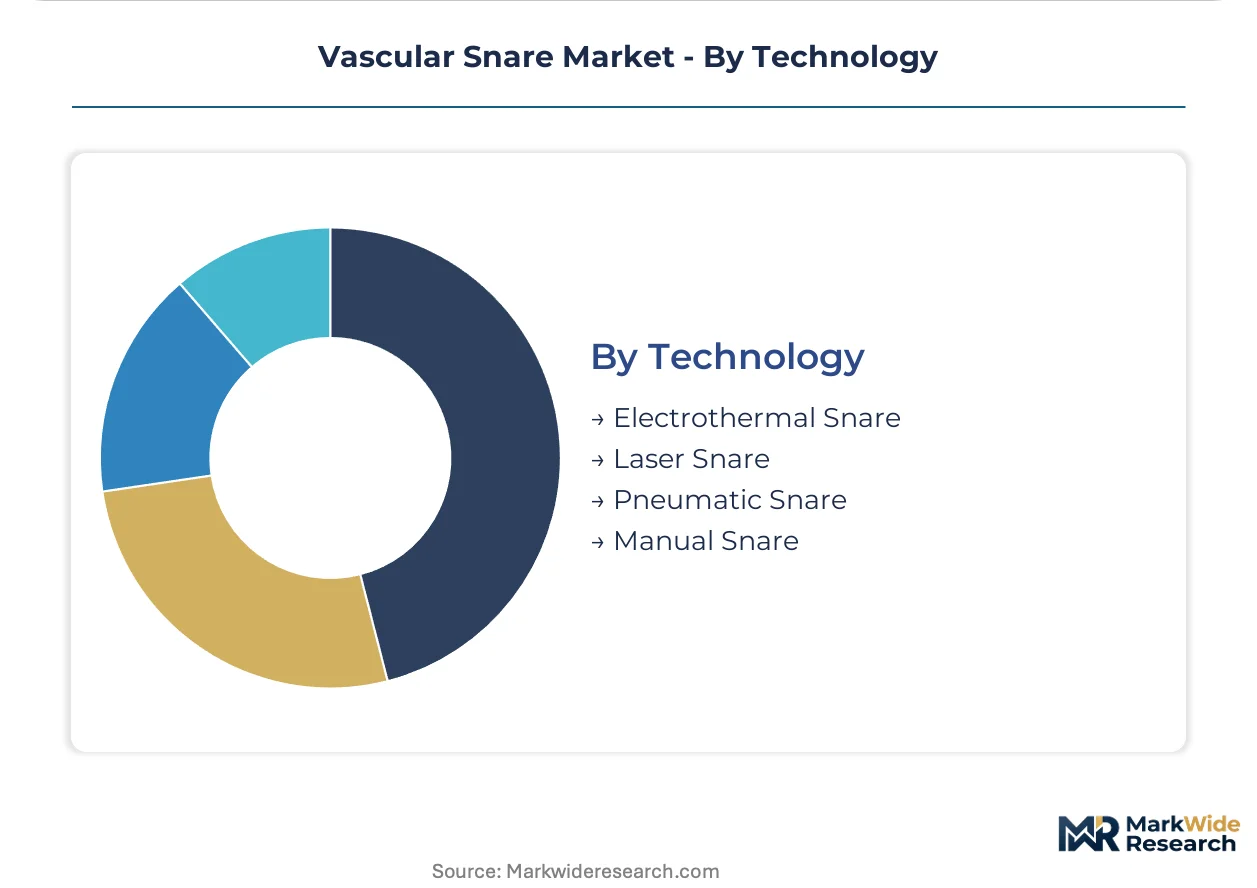
- Electrothermal Snare:Integrated cautery capability enables simultaneous tissue dissection and foreign body capture in complex retrieval cases. United States academic medical centers and German university hospitals adopt these systems for difficult stent extractions where tissue adhesion complicates mechanical retrieval alone.
- Manual Snare:Mechanical loop deployment without energy delivery retains volume leadership in emerging markets where generator capital constraints limit powered alternative adoption. Basic nitinol and stainless steel configurations satisfy standard retrieval indications.
- Laser Snare:Photothermal energy delivery for targeted tissue ablation during retrieval represents a specialized configuration with limited current deployment.
- Pneumatic Snare:Compressed gas actuation mechanisms offer alternative powered deployment with distinct tactile feedback characteristics for select operator preferences.
Manual Snare holds the highest shipment volumes globally, while Electrothermal Snare demonstrates the steepest expansion trajectory as complex case volumes concentrate in advanced centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional cardiologists and radiologists cluster in tertiary medical centers across developed economies, anchoring demand for advanced retrieval systems. Cath lab infrastructure investments and procedural specialization determine regional purchasing patterns. Reimbursement frameworks and regulatory compliance costs fragment market access across jurisdictions.
United States
Integrated delivery networks in metropolitan hospital systems drive enterprise-level snare procurement through bundled endovascular contracts. FDA 510(k) premarket notification pathways enforce predicate device equivalence standards for nitinol-based systems. The Cleveland Clinic and Mayo Clinic anchor specialized retrieval team development in the Midwest corridor.
Germany
University hospitals in Baden-Württemberg and Bavaria expand dedicated interventional radiology suites for foreign body retrieval. EU MDR technical documentation mandates extend time-to-market for new loop configurations through notified body capacity constraints. The Rhine-Main cluster around Frankfurt concentrates cath lab standardization initiatives across hospital groups.
Japan
PMDA QMS ministerial ordinances add compliance layers for foreign manufacturers seeking reimbursement listing in tertiary cardiovascular centers. METI industrial policy supports domestic device manufacturing scale-up. The Kanto region around Tokyo anchors hybrid operating room workflow integration for intraoperative retrieval procedures.
United Kingdom
NHS procurement frameworks consolidate snare purchasing into category management contracts with multi-year volume commitments. MHRA post-Brexit regulatory alignment maintains CE marking recognition while building UKCA capacity. The Oxford-Cambridge-London triangle concentrates academic medical center adoption of electrothermal-capable systems.
India
CDSCO medical device rules enforcement tightens import registration requirements for nitinol retrieval devices in private hospital networks. Central government PLI scheme incentives attract contract manufacturing investment for export-oriented production. The Delhi-NCR corridor anchors cath lab expansion in corporate hospital chains.
Vascular Snare Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the vascular snare market, with integrated medtech conglomerates holding manufacturing scale advantages over specialized retrieval device firms. The vendor base splits between diversified endovascular portfolio owners and single-category specialists. Three archetypes dominate: diversified conglomerates bundling snares with catheter systems, interventional radiology workflow specialists, and direct-distribution channel controllers. Competitive moves concentrate on strategic partnerships for nitinol supply security and geographic licensing arrangements for regulatory pathway acceleration.
Among diversified portfolio owners, Medtronic plc and Boston Scientific Corporation exemplify the conglomerate archetype with endovascular breadth enabling bundled contract positioning. Cook Medical occupies a specialist position rooted in interventional radiology workflow integration. Merit Medical Systems, Inc. represents the direct-channel archetype, bypassing third-party logistics infrastructure to control hospital distribution economics.
| Leading Market Players |
|---|
| Medtronic plc |
| Cook Medical |
| Merit Medical Systems, Inc. |
| Becton, Dickinson and Company |
| Teleflex Incorporated |
| Argon Medical Devices, Inc. |
| Boston Scientific Corporation |
| Terumo Corporation |
| pfm medical ag |
| Others |
Value Chain & Pricing Dynamics
EU MDR technical documentation mandates for nitinol-based devices gate qualified supply access and premium-tier pricing power, as manufacturers absorbing compliance costs pass through validation investments to hospital systems while disqualifying commodity producers from reimbursement-eligible procurement channels.
Pricing Analysis
Bundled enterprise contracts versus standalone snare procurement splits pricing power between integrated delivery networks and specialized manufacturers. Three-tier pricing structure across premium electrothermal, standard single-use nitinol, and economy reusable stainless steel levels reflects FDA 510(k) clearance tier and cath lab standardization depth. Pricing pressure stems from GPO consolidation in United States metropolitan systems. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers show lowest.
Supply Chain Analysis
Freight cost volatility from Asian specialty metal producers to United States and German manufacturing sites compresses margin structures for nitinol-dependent device assemblers. Superelastic alloy supply concentrates in Japan, Germany, and United States specialty foundries. Nitinol wire, loop fabrication equipment, and sterilization packaging constitute critical input dependencies. Single-source vulnerability runs through limited qualified nitinol suppliers. Distribution runs through direct hospital channel controllers and third-party medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vascular snare market represents a late-cycle quality story as cath lab consolidation shifts procurement criteria toward guaranteed sterility and liability elimination, privileging premium single-use specifications over reusable alternatives.
For Market Incumbents: To counter electrothermal snare commoditization, Medtronic plc and Cook Medical should deepen backward integration into nitinol wire supply and secure multi-year enterprise contracts with United States integrated delivery networks before notified body capacity constraints delay competitor EU MDR clearance timelines. For New Entrants and Emerging Players: CDSCO medical device rules enforcement in India opens a window for contract manufacturing positioning serving export markets, with white-space targets in cost-optimized single-use snares for South Asian private hospital networks and compact kit configurations for United States ambulatory surgical center migration. For Investors and Strategic Acquirers: Roll-up economics work for interventional radiology workflow specialists because cath lab standardization across hospital mega-systems creates volume leverage for bundled device portfolios. Five-to-ten year viability hinges on reimbursement pathway security. Acquisition targets should demonstrate PMDA QMS compliance progress. The signal to watch is Japan reimbursement listing velocity for foreign manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Advancement | Notified body capacity constraints extend clearance timelines for nitinol loop configurations by 12-18 months. |
| Japan PMDA QMS Pathway Investment | Ministerial ordinance mastery secures premium reimbursement positioning ahead of competitor market entry. |
| Nitinol Supply Security Partnership | Specialty alloy qualification delays from limited producers threaten manufacturing scale alignment. |
| Ambulatory Surgical Center Channel Development | Site-of-care migration creates demand for compact procedure-ready snare kits with minimal sterilization overhead. |
| Electrothermal Capability Integration | Academic medical center adoption for complex stent extractions compresses procedure time and ancillary tool requirements. |
Study Parameters
Coverage spans United States, Germany, Japan, United Kingdom, and India, with primary inputs from each market cluster combining structured interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, PMDA approval records, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchor value estimates.
Granularity-level modeling distinguishes single-use versus multiple-use snare configurations, electrothermal versus manual technology platforms, interventional radiology versus cardiac surgery versus endovascular application settings, and hospital versus ambulatory surgical center versus specialty clinic end-user channels across the projection horizon. CAGRs derive from segmented procedure volume growth trajectories and per-procedure device utilization rates adjusted for cath lab consolidation patterns and reimbursement framework evolution.
Revisions become necessary when EU MDR notified body capacity constraints extend beyond modeled timelines, nitinol raw material supply disruptions materialize, or cath lab consolidation accelerates beyond enterprise contract coverage assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Smart Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Global Percutaneous Coronary Intervention (PCI) Devices Market
Cardiovascular Devices
Global Arterial Stents Market
Cardiovascular Devices
North America Vascular Stents Market
Cardiovascular Devices
Global Vascular Injury Treatment Market
Cardiovascular Devices
Mitral Valve Disease Market
Cardiovascular Devices
Global Advanced Balloon Catheter Market
Cardiovascular Devices
Atherosclerotic Renovascular Treatment Market
Cardiovascular Devices
Global Nitinol-Based Medical Devices Market
Cardiovascular Devices
Cardiac Cannulas Market
Cardiovascular Devices
Transcatheter Heart Valve Replacement (THVR) Market
Cardiovascular Devices
Spain Cardiovascular Devices Market
Cardiovascular Devices
Global Non-Vascular Stents Market
Cardiovascular Devices
Atherectomy Systems Market
Cardiovascular Devices
Global Cardiac Output Monitoring Devices Market
Cardiovascular Devices
Anticoagulation Market