
 Surgical Clips Market | 2026-2036
Surgical Clips Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Clips Market Intelligence
The ISO 13485 quality management standard is unwinding the market's historical reliance on brand reputation alone, establishing a baseline for entry that elevates the importance of manufacturing precision. Johnson & Johnson leverages its extensive hospital network and distribution channels to maintain a significant footprint. Medtronic specializes in clips designed for integration with robotic-assisted surgery platforms. Meanwhile, B. Braun Melsungen AG competes through its focus on material science and a broad portfolio spanning both metal and polymer-based clip systems.
Surgical clips are specialized medical fasteners used to occlude vessels, ducts, or other tissues during surgical procedures, ensuring hemostasis or marking a specific site. They are typically manufactured from medical-grade materials like titanium or absorbable polymers, designed to be non-ferromagnetic for MRI compatibility. The market's material composition shows Titanium Clips retaining a large share due to their proven efficacy and cost-effectiveness. However, Absorbable Clips represent the fastest-growing segment, driven by clinical demand to eliminate foreign body presence post-operatively, especially in Laparoscopic Surgery applications.
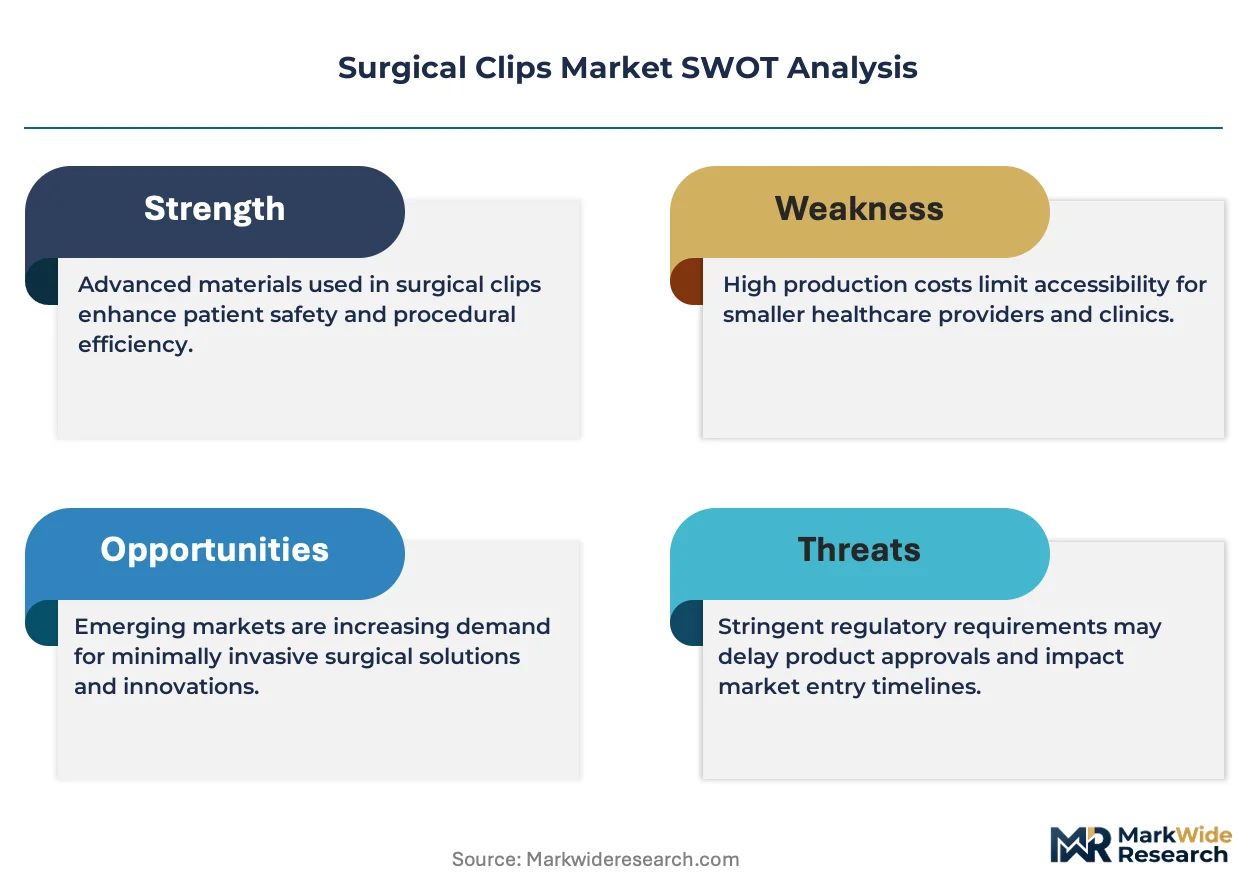
Regulatory oversight is a critical structural element, with bodies like the US FDA, the European Union's MDR framework, and Japan's PMDA setting stringent requirements. These regulations govern material biocompatibility, sterilization processes, and the need for robust clinical data, directly influencing product development timelines and market access. For manufacturers, the strategic imperative is to navigate the complex trade-off between investing in novel bioresorbable polymer research and optimizing production of established metallic clip portfolios.
Market Dynamics
The fundamental dynamic shaping the surgical clips market is the clinical and regulatory pressure to shift from permanent metallic implants to fully bioabsorbable alternatives. This transition creates a deep-seated tension between the proven, cost-effective performance of titanium clips and the higher-cost, reduced long-term-complication profile of advanced polymer clips.
Growth Catalysts
- Minimally Invasive Surgery Volume:The global expansion of laparoscopic and robotic-assisted procedures, particularly in gastrointestinal and cardiothoracic surgery, increases the number of clips required per intervention to achieve hemostasis in complex anatomies.
- Bioabsorbable Material Science:Innovations in polymer chemistry are yielding clips with more predictable absorption times and improved mechanical strength, meeting surgeon demands to eliminate long-term foreign body presence post-operatively.
- Standardization under ISO 13485:Adherence to this quality management standard provides a clear framework for manufacturing and documentation, enabling manufacturers to more efficiently navigate regulatory submissions with bodies like the US FDA and Japan's PMDA.
Market Restraints
- Premium Cost of Absorbable Clips:The significantly higher unit cost of polymer-based absorbable clips compared to their titanium counterparts restricts their widespread adoption, especially in cost-sensitive healthcare systems or for high-volume, routine procedures.
- Stringent Regulatory Scrutiny:The EU's Medical Device Regulation (MDR) mandates extensive clinical evidence for long-term safety and performance, creating substantial barriers to market entry and costly compliance burdens for novel materials.
- Legacy Material Preference:Deeply ingrained surgeon familiarity and trust in the tactile feedback and decades of proven performance of metallic clips can create resistance to adopting newer, polymer-based technologies.
Strategic Opportunities
- Robotic Surgery Integration:There is a distinct opportunity to engineer and market surgical clips specifically designed for the articulation and force feedback limitations of robotic surgery platforms, creating a high-margin sub-segment.
- Penetration in Emerging Markets:As healthcare infrastructure and surgical volumes grow in countries like Brazil and India, there is a large, untapped opportunity for standard, cost-effective titanium clip systems.
- Development of Functional Clips:Research into clips that are either drug-eluting to prevent infection or enhanced with radiopaque markers for superior post-operative imaging visibility offers a path to significant product differentiation.
Industry Challenges
- Biocompatibility and Degradation Testing:Validating the long-term biocompatibility and predictable absorption profile of new polymers requires multi-year clinical trials, posing a significant time and capital investment challenge for manufacturers.
- Sterilization Process Validation:Changes in sterilization regulations, such as restrictions on Ethylene Oxide (EtO), force manufacturers to re-validate processes for both new and existing products, which can disrupt supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Clips Market |
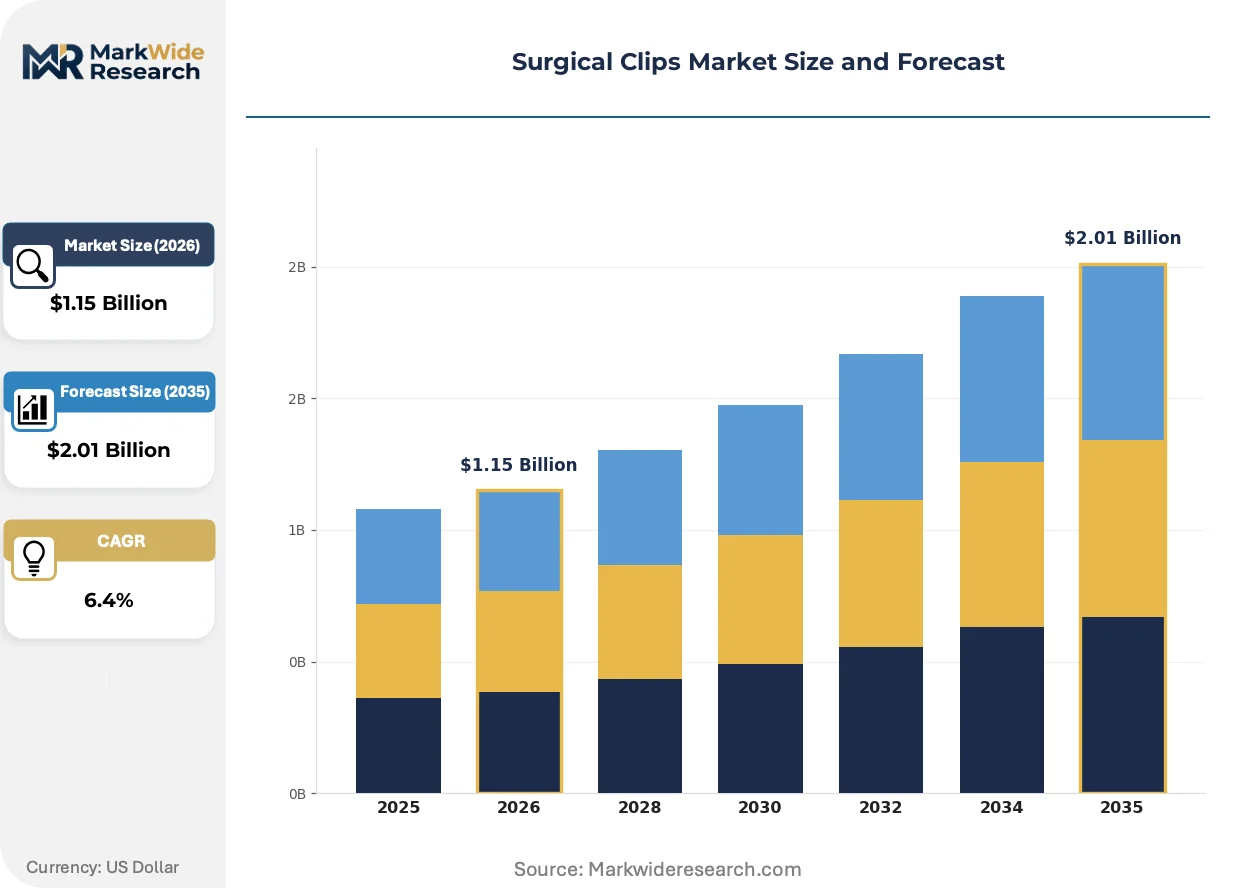
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.01 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Clips, Absorbable Clips, Polymer Clips, Titanium Clips Application: Cardiothoracic Surgery, Gastrointestinal Surgery, Urological Procedures, Neurosurgery, Gynecological Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Academic Research Institutes Deployment: Open Surgery, Laparoscopic Surgery, Robotic-assisted Surgery, Minimally Invasive Surgery |
| Companies Covered | Johnson & Johnson, Boston Scientific Corporation, B. Braun Melsungen AG, Medtronic, Edwards Lifesciences Corporation, Teleflex Incorporated, Grena Limited, Ackermann Medical GmbH & Co., Scanlan International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Clips Market Strategic Shifts & Innovations
The evolution of surgical practice toward greater precision and less invasive patient interventions is the primary force compelling innovation in clip design. This movement is driving a significant re-evaluation of material science, device functionality, and the regulatory evidence required to support new products.
Advanced polymer composites, such as those based on polyglycolide-co-L-lactide (PGLA), provide predictable absorption profiles and robust tensile strength for reliable vessel ligation. These materials see accelerated adoption in specialized fields like pediatric surgery, where minimizing long-term implant burden is a clinical priority. This focus on improved patient outcomes is miniaturizing the physical profile of clips, enabling their application in more delicate surgical sites.
Europe's Medical Device Regulation (MDR) has intensified requirements for clinical evidence and post-market surveillance across all device classes. This forces manufacturers to generate new clinical data even for established titanium clips to maintain market access, increasing the total cost of compliance. Absorbable clips, often in a higher risk class, face the most stringent scrutiny, requiring investment in long-term patient studies to prove safety and efficacy.
Hospital purchasing criteria are evolving to consider the total cost of care rather than just the upfront price of a single device. This behavioral shift moves procurement decisions beyond a simple cost comparison of titanium versus polymer clips, starting to factor in the economic benefit of avoiding potential secondary surgeries. This value-based analysis is most visible in large, integrated healthcare networks in the United States and Germany.
Surgical Clips Market Segmentation
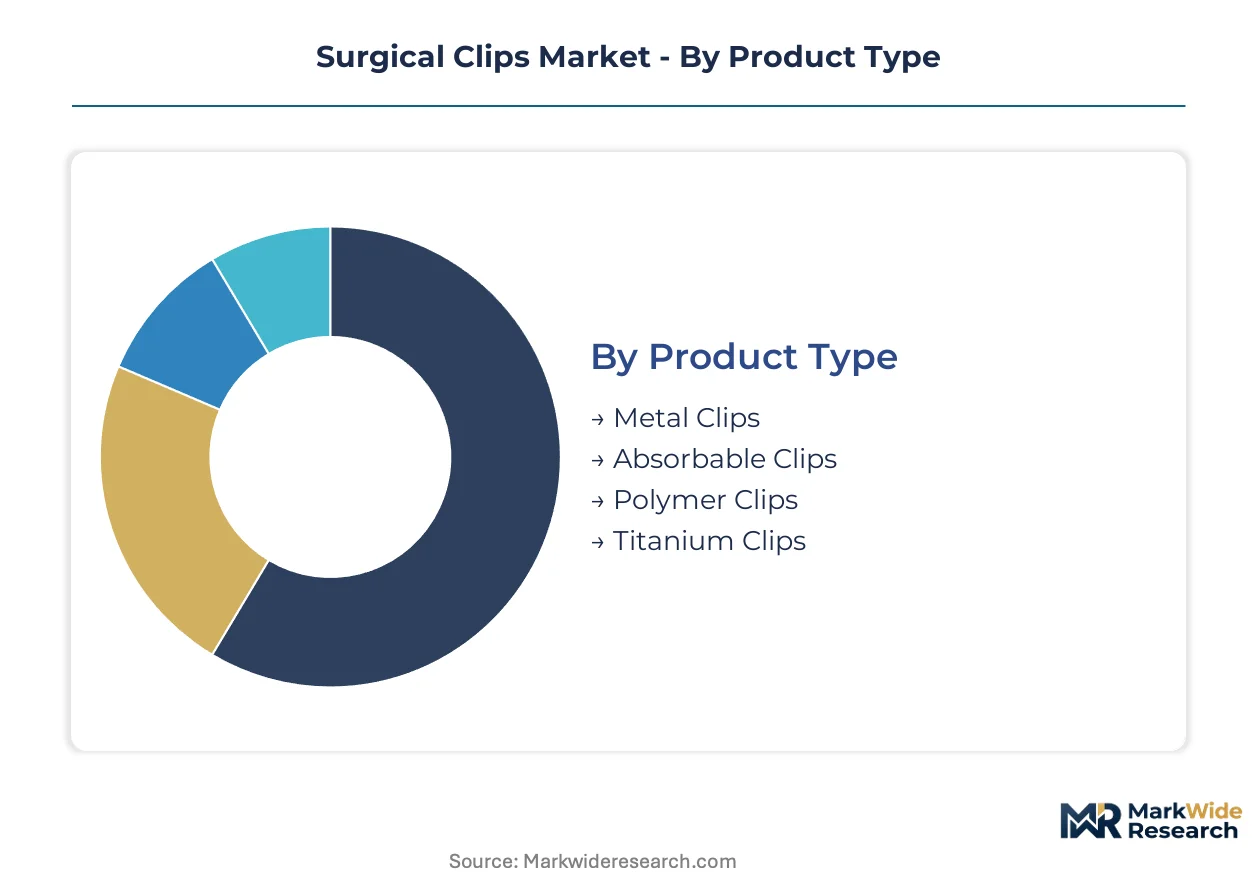
The surgical clips market's segmentation reflects the diverse clinical requirements and technological advancements driving product differentiation. Understanding these distinct segments allows manufacturers to tailor research and development efforts, aligning product features with specific surgical needs and patient outcomes.
Product Type:
The product type segment faces considerable substitution pressure, particularly as advanced polymer-based clips challenge the long-standing dominance of metallic options in various surgical contexts.
- Titanium Clips:These clips are manufactured from medical-grade titanium, offering high tensile strength and proven biocompatibility for vessel occlusion and tissue approximation. Demand concentrates in cost-sensitive healthcare systems and for high-volume, routine procedures across the United States and Germany, where their reliability is well-established.
- Absorbable Clips:Composed of bioresorbable polymers like polyglycolide-co-L-lactide, these clips degrade naturally over time, eliminating foreign body presence post-operatively. Their utilization is expanding most quickly in laparoscopic surgery and pediatric applications where minimizing long-term implant burden is critical.
- Metal Clips:This broad category includes clips made from various medical-grade metals, primarily used for permanent ligation and marking during surgical interventions.
- Polymer Clips:These non-absorbable clips, made from inert polymers, offer MRI compatibility and a lightweight alternative to metallic options in specific surgical scenarios.
Titanium Clips anchors the volume base while Absorbable Clips gains share at the steepest rate.
Application:
Application segments delineate where surgical clips are most frequently deployed, with specific clinical needs dictating material and design preferences.
- Cardiothoracic Surgery:Clips in this segment are engineered for precise vessel and tissue occlusion within the delicate thoracic cavity during procedures like coronary artery bypass grafting. Demand is particularly high in developed healthcare markets with advanced cardiac care infrastructure, such as the United States and Japan.
- Gastrointestinal Surgery:This segment utilizes clips for hemostasis and tissue approximation in procedures involving the digestive tract, including colectomies and gastric resections. The expansion of minimally invasive techniques in gastrointestinal surgery, especially in Europe, drives device innovation.
- Urological Procedures:Surgical clips support various urological interventions, including nephrectomies and prostatectomies, providing secure ligation of vessels and ducts.
- Neurosurgery:Specialized clips are designed for delicate hemostasis and aneurysm clipping within neurological procedures, requiring exceptional precision and minimal artifact.
- Gynecological Surgery:Clips find use in gynecological operations for vessel ligation and tissue management, often within laparoscopic approaches to procedures like hysterectomies.
The cardiothoracic and gastrointestinal surgery segments collectively command substantial market share, reflecting high procedural volumes and critical hemostasis requirements.
End User:
The end user segmentation illustrates the primary healthcare settings where surgical clips are procured and utilized, influencing purchasing patterns and product distribution strategies.
- Hospitals:These large medical institutions represent the largest end-user segment, performing a wide range of complex and routine surgical procedures requiring diverse clip types. Hospitals in the United States and Germany account for significant procurement volumes.
- Ambulatory Surgical Centers:ASCs specialize in outpatient procedures, demanding cost-effective and efficient clip solutions for their high-volume, less complex surgical caseloads. This segment is experiencing rapid expansion dueencing to shifts towards outpatient care models.
- Specialty Clinics:Focused on specific medical disciplines, specialty clinics utilize clips tailored to their narrow procedural scope, often prioritizing specialized designs over broad utility.
- Academic Research Institutes:These institutions employ surgical clips primarily for research, training, and the development of new surgical techniques and device evaluations.
Hospitals remain the dominant procurement channel, while Ambulatory Surgical Centers demonstrate robust growth in device consumption.
Deployment:
Deployment methods highlight the surgical approach dictating clip design, with a pronounced shift towards less invasive techniques influencing innovation and market demand.
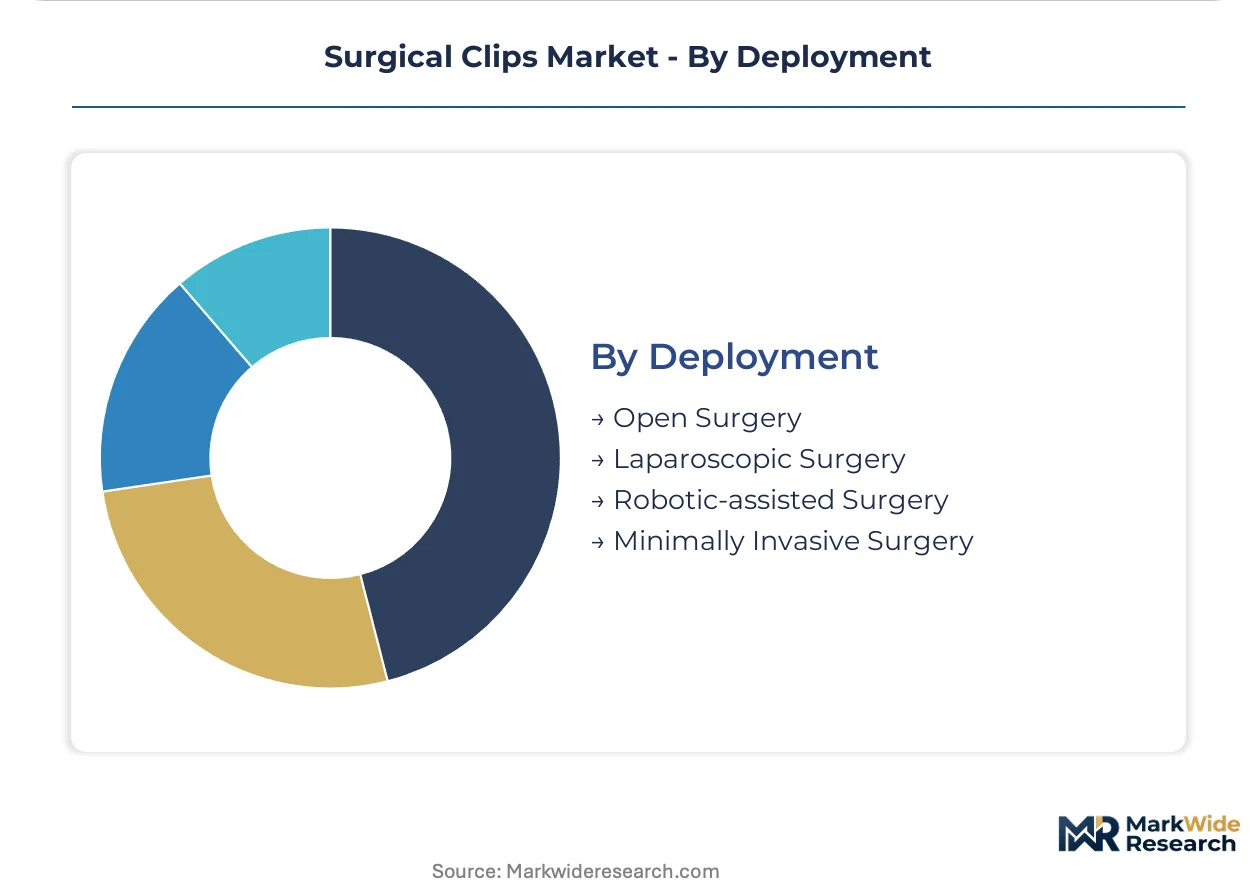
- Laparoscopic Surgery:Clips for laparoscopic procedures are designed for delivery through small incisions, requiring specific applicators and enhanced visibility features for use in confined spaces. This method drives demand for miniaturized and articulating clips, particularly in gastrointestinal applications.
- Robotic-assisted Surgery:These clips are specifically engineered to integrate with robotic platforms, addressing the dexterity and tactile feedback limitations inherent in robotic systems. The United States leads in robotic surgery adoption, creating a focused demand for compatible clip systems.
- Open Surgery:Traditional open surgical procedures utilize clips that are manually applied, often requiring larger sizes and simpler designs for direct access to the surgical site.
- Minimally Invasive Surgery:This broad category encompasses all techniques that minimize incision size, including laparoscopic and robotic-assisted methods, driving demand for smaller, more precise clips.
Laparoscopic Surgery and Robotic-assisted Surgery are the primary drivers of innovation and unit volume expansion within the deployment landscape.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration significantly influences the global surgical clips market, with demand primarily originating from developed healthcare systems. These systems prioritize advanced surgical techniques and high-quality medical devices. Emerging markets also present growth avenues, particularly for established product categories.
United States
Demand for surgical clips in the United States stems from high volumes of minimally invasive procedures and the rapid integration of robotic-assisted surgery platforms. The US FDA's stringent regulatory framework ensures product safety and efficacy for all medical devices. Major medical technology clusters in Boston and California drive innovation in clip design and material science.
Germany
Germany's advanced healthcare infrastructure and emphasis on precision surgery generate substantial demand for both metallic and absorbable surgical clips. The European Union's MDR framework establishes rigorous requirements for market access and post-market surveillance. Medical device manufacturing hubs in Bavaria and Baden-Württemberg contribute significantly to product development and supply.
Japan
Japan exhibits strong demand for surgical clips, particularly in cardiothoracic surgery, due to its advanced cardiac care capabilities and an aging population. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees strict regulatory approval processes for medical instruments. Tokyo and Osaka serve as central points for medical device research, development, and distribution.
India
India represents a substantial opportunity for cost-effective titanium clip systems as its healthcare infrastructure and surgical volumes expand. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices, with initiatives like the PLI scheme encouraging domestic manufacturing. Bengaluru and Mumbai are emerging as key centers for medical device innovation and healthcare delivery.
France
France shows robust demand for surgical clips, driven by the expansion of minimally invasive gastrointestinal surgical techniques across its public and private hospital networks. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) ensures compliance with national and EU medical device regulations. Lyon and Paris host significant clusters for medical research and healthcare technology development.
Surgical Clips Market Key Industry Players
Player mix skews toward large, diversified medical device conglomerates alongside specialized surgical tool manufacturers. The market exhibits a tiered structure, with established leaders maintaining broad portfolios and smaller innovators focusing on niche applications or material science advancements. Strategic partnerships and targeted research and development investments represent dominant competitive moves.
Diversified medical device leaders like Johnson & Johnson leverage their extensive hospital networks and global distribution capabilities to maintain a significant footprint. Medtronic exemplifies the archetype of a company integrating clip technology with advanced surgical platforms, particularly robotic-assisted surgery. Meanwhile, B. Braun Melsungen AG sits within the segment focused on material science expertise, offering a broad portfolio of both metallic and polymer-based clip systems to cater to diverse clinical needs.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Boston Scientific Corporation |
| B. Braun Melsungen AG |
| Medtronic |
| Edwards Lifesciences Corporation |
| Teleflex Incorporated |
| Grena Limited |
| Ackermann Medical GmbH & Co. |
| Scanlan International Inc. |
| Others |
Cost & Logistics Intelligence
Scale economies in titanium clip manufacturing establish a baseline for supply concentration and drive competitive price floors across the surgical clips market. This dynamic influences investment in higher-cost, advanced bioabsorbable alternatives.
Pricing Analysis
Cost-plus contract patterns, often indexed to raw material costs for metallic clips, govern procurement in many healthcare systems. Price differentiation stems from material composition, such as advanced bioresorbable polymers, and the level of regulatory certification required for market access. Pricing softness reflects intense competition for high-volume titanium clips, particularly in cost-sensitive healthcare systems like public hospitals. Specialized clinics adopting novel absorbable clips demonstrate lower price sensitivity.
Supply Chain Analysis
Inventory and lead-time management are critical for surgical clip supply, particularly for sterile-packaged devices with limited shelf lives. Geographic supply concentrates in advanced manufacturing hubs like Germany and the United States, alongside emerging production in India for standard metallic clips. Raw material dependencies include medical-grade titanium and specialized bioresorbable polymers such as polyglycolide-co-L-lactide. Sterilization process validation represents a structural supply chain risk. Distribution runs through established medical device distributors and direct hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical clips market is shaped by a distinct capability scarcity, particularly in the deep material science expertise required for developing next-generation bioabsorbable polymers. This gap creates opportunities for focused innovation.
For Market Incumbents: Compound existing strengths in distribution and hospital relationships to reinforce market share against niche innovators. Invest in advanced manufacturing processes for bioabsorbable clips to counter the threat of specialized material science firms. Leverage ISO 13485 certification to streamline regulatory compliance under frameworks like the EU MDR, ensuring continued market access for established portfolios. Prioritize integration with robotic surgery platforms to maintain relevance in high-growth segments.
For New Entrants and Emerging Players: Anchor in unmet clinical needs within specialized applications, such as pediatric surgery, where minimizing foreign body presence is paramount. Target the integration of clips with robotic-assisted surgery platforms, offering superior articulation and feedback. Focus on developing functional clips, like drug-eluting or radiopaque variants, to create significant product differentiation. A go-to-market angle emphasizing long-term patient outcomes and reduced secondary interventions will resonate with value-based procurement.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firms providing integrated surgical solutions that bundle clips with applicators and training, offering stable cash flows. Long-term viability rests on sustained demand from an aging global population and the ongoing expansion of minimally invasive procedures. Acquisition targets should include specialized material science firms with proprietary polymer technologies or companies excelling in robotic accessory development. The signal to watch is successful regulatory approval of novel bioabsorbable clips with superior mechanical properties.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Advanced Bioabsorbable Polymers | This initiative addresses clinical demand for foreign body elimination and drives product differentiation in specialized surgical fields. |
| Strengthen Robotic Surgery Integration | Optimizing clips for robotic platforms captures growth in high-value, precision-driven surgical segments. |
| Invest in ISO 13485 Compliance | Robust quality management ensures market access and navigates stringent regulatory frameworks like the EU MDR. |
| Expand into Emerging Markets | Targeting countries like India provides volume growth for cost-effective metallic clip systems. |
| Form Hospital System Partnerships | Collaborations with large healthcare networks secure procurement volumes and facilitate clinical adoption of new technologies. |
Research Approach
A spread of perspectives from surgeons, hospital procurement managers, R&D directors, and regulatory affairs specialists converged on the working assumptions for the surgical clips market. This primary data was combined with extensive secondary validation from sources including FDA filings, EU MDR guidance documents, clinical trial registries, and medical device industry association reports. A robust bottom-up and top-down triangulation process ensured data consistency and accuracy.
Segmentation dimensions modeled included product type, application, end user, deployment method, material composition, and regional regulatory clusters across the analysis window. The analytical framework integrated historical market performance with projected growth drivers, such as minimally invasive surgery adoption rates and healthcare expenditure growth. Compound annual growth rates were derived through a comprehensive analysis of these factors, projecting market evolution over the projection horizon.
Material uncertainties — such as unforeseen regulatory changes or major shifts in material science breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions regarding technological advancements and healthcare policy stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
India Surgical Sutures Market
Surgical Instruments
Ultrasonic Tissue Ablation System Market
Surgical Instruments
Huber Needles Market
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
Global Surgical Catheters Market
Surgical Instruments
Laparoscopic Sutures Market
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market
Surgical Instruments
Breast Retractors Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Suture Anchor Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Colorectal Procedure Market
Surgical Instruments
Minimally Invasive Surgical Instruments Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Global Bone Wax Market