
 Skin Excision Market | 2026-2036
Skin Excision Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Excision Market Intelligence
Germany is reconfiguring its outpatient surgical infrastructure to accommodate same-day skin excision procedures. Medtronic leverages its integrated surgical portfolio to supply excision kits across European hospital networks. Ethicon Inc anchors its position through suture and hemostatic agent lines that dominate European procurement channels. KARL STORZ GmbH & Co. KG specializes in endoscopic visualization systems that physicians employ during complex dermal lesion removals.
Skin excision denotes the surgical removal of abnormal or damaged tissue using scalpels, punches, electrocautery, or laser instrumentation, typically performed under local anesthesia with margins ranging from 1 mm to 2 cm depending on lesion pathology. The procedure serves diagnostic confirmation via histopathological analysis and therapeutic elimination of malignant, premalignant, or cosmetically undesirable tissue. Surgical excision kits and hemostatic agents command the largest product revenue pools due to recurrent consumption in high-volume settings. Oncology and dermatology applications are expanding fastest as population screening intensifies and melanoma incidence rises across aging demographics. Laser surgery and electrosurgery technologies are displacing traditional scalpel methods in cosmetic and trauma applications where precision and hemostasis reduce operative time.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape device commercialization timelines and clinical evidence requirements for manufacturers seeking market access. HIPAA privacy frameworks and GDPR data governance rules constrain how excision outcomes and pathology reports traverse digital health platforms in the United States and Europe. Stakeholders must monitor evolving reimbursement thresholds for outpatient versus inpatient excision codes as payers recalibrate site-of-service policies.
Market Dynamics
Ambulatory surgical centers are consolidating outpatient skin lesion removal volumes, compressing procedure site-of-service economics and forcing manufacturers to reconfigure kit specifications for same-day discharge protocols.
Growth Catalysts
- EU MDR Classification Rules:Tightened device classification under EU MDR is accelerating clinical evidence generation for excision kits, creating competitive moats for manufacturers with robust technical documentation.
- Melanoma Screening Intensification:Population-based dermatological screening programs in aging Western demographics are expanding diagnostic excision volumes through earlier lesion detection protocols.
- Laser Hemostasis Technology:Precision thermal coagulation systems are reducing operative time in cosmetic applications, pulling demand from traditional scalpel methods in dermatology clinics.
Market Restraints
- Single-Use Consumable Cost Structure:Electrocautery tips and disposable excision kits face input cost volatility from medical-grade polymer supply chains concentrated in East Asian manufacturing zones.
- Pathology Integration Bottlenecks:Histopathological confirmation requirements create procedural friction, as excised tissue logistics depend on centralized laboratory capacity with fixed throughput ceilings.
- Substitute Modalities:Cryotherapy and topical immunomodulators for superficial lesions present non-surgical alternatives that capture low-acuity cases before excision referral.
Strategic Opportunities
- Teledermatology Triage Convergence:Remote lesion assessment platforms are channeling patients toward in-person excision appointments, creating digital-to-physical care pathway integration.
- India Outpatient Infrastructure:Underpenetrated dermatology clinic networks in tier-2 Indian cities present white space for standardized excision protocol adoption as private healthcare investment accelerates.
- US Site-of-Service Reimbursement Tailwinds:Medicare reimbursement recalibration toward ambulatory surgical centers is incentivizing capital deployment into freestanding excision facilities.
Industry Challenges
- EU MDR Technical Documentation Workloads:Legacy device portfolios require substantial clinical evidence regeneration, straining regulatory affairs capacity across mid-tier manufacturers.
- Dermatopathologist Workforce Constraints:Specialized histopathological interpretation capacity faces geographic maldistribution, creating diagnostic turnaround bottlenecks in rural excision sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Excision Market |
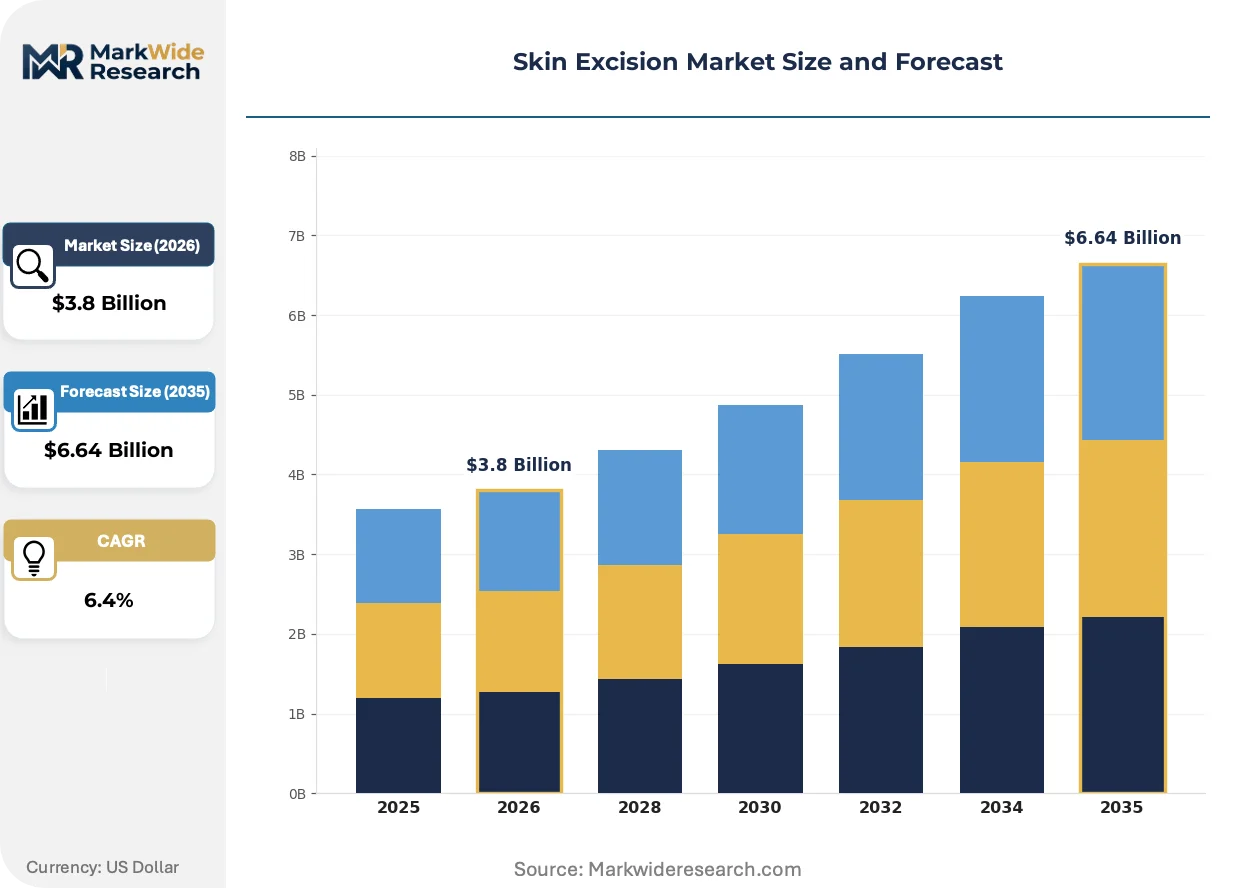
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Excision Kits, Biopsy Punches, Sutures, Hemostatic Agents Application: Oncology, Dermatology, Cosmetic Surgery, Trauma Treatment End User: Hospitals, Outpatient Clinics, Research Laboratories, Ambulatory Surgical Centers Technology: Laser Surgery, Electrosurgery, Cryosurgery, Traditional Surgery |
| Companies Covered | Medtronic, Ethicon Inc, Becton, Dickinson and Company, Integra LifeSciences, Richard Wolf GMBH, KARL STORZ GmbH & Co. KG, Zimmer Biomet, B. Braun SE, Conmed Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Excision Market Strategic Shifts & Innovations
Digital pathology workflows and intraoperative margin assessment tools are compressing the diagnostic-therapeutic loop, redefining real-time decision-making during skin excision procedures.
Confocal laser scanning microscopy is virtualizing traditional frozen section analysis by enabling non-invasive real-time margin assessment during Mohs micrographic surgery. Academic medical centers in Germany and the United States are piloting integrated systems that overlay cellular-level imaging onto surgical navigation displays. This virtualization is collapsing the iterative excision-and-verify cycle from multiple stages toward single-session completion.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up data collection for excision devices, compelling manufacturers to build registry infrastructure. The regulation forces alignment between device performance tracking and patient outcome metrics. High-volume dermatology clinic networks in France and the Netherlands are responding by consolidating purchasing around suppliers with established vigilance systems.
Direct-to-employer contracting for dermatology benefits is bypassing traditional payer intermediaries, concentrating excision volume into narrow clinic networks. Large self-insured employers in Texas and California are steering employees toward designated ambulatory surgical centers through reduced cost-sharing. This channel compression is visible most acutely in metropolitan corridors where employer headquarters density overlaps with specialized dermatology group practices.
Skin Excision Market Segmentation
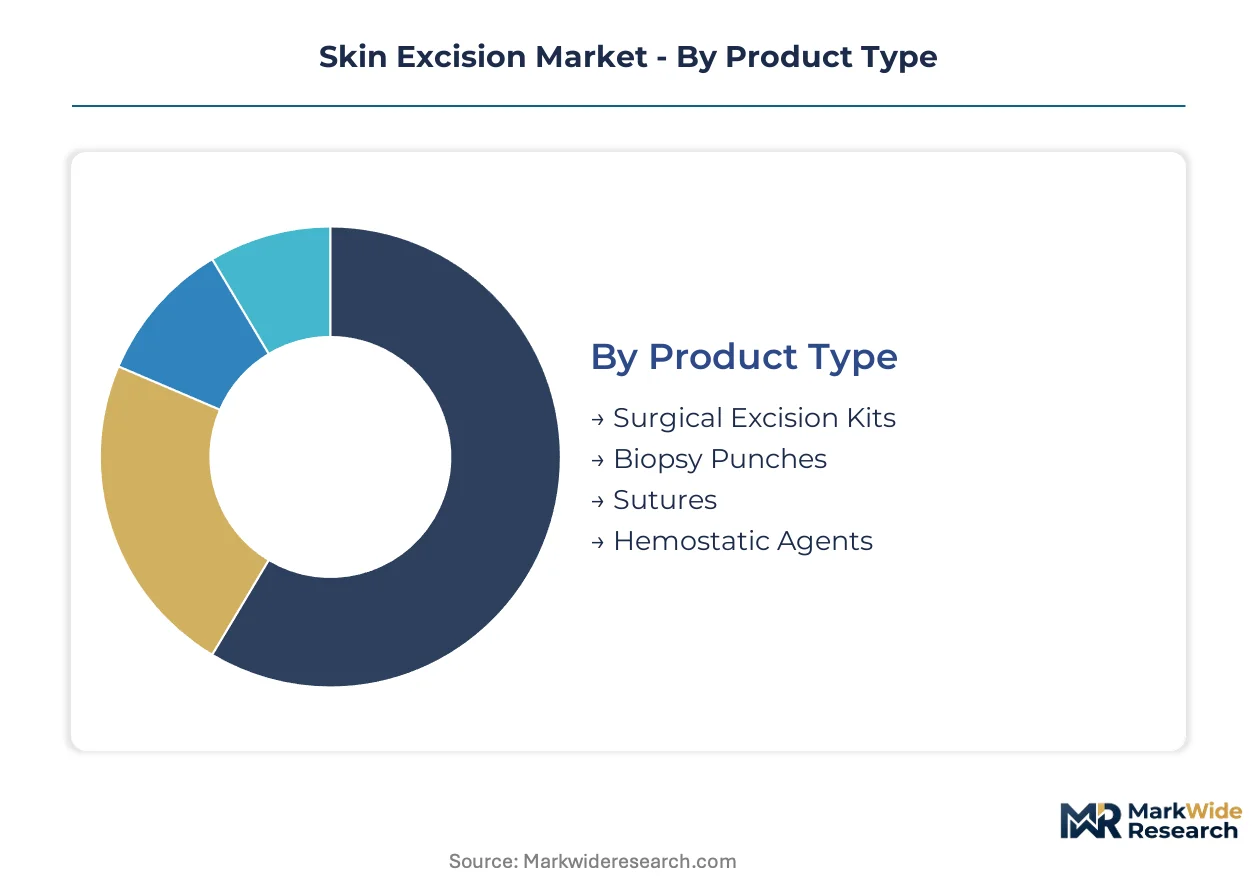
Product configuration, procedural setting, and energy modality collectively determine procurement patterns and margin structures across skin excision workflows. Manufacturers configure portfolio depth around high-velocity consumables while technology transitions reshape capital equipment replacement cycles.
Product Type:
Cost tier differentiation separates premium sterile kits from commodity component sourcing, with procurement committees weighting total procedure economics against unit price.
- Surgical Excision Kits:Pre-configured sterile trays containing scalpels, forceps, and drapes eliminate OR preparation time. Demand concentrates in ambulatory surgical centers across the United States where same-day discharge protocols prioritize workflow efficiency.
- Hemostatic Agents:Topical hemostats and sealants derived from gelatin, collagen, or oxidized cellulose control bleeding in anticoagulated patients. German dermatology clinics under EU MDR tightened device rules are consolidating purchasing around suppliers with established vigilance systems.
- Biopsy Punches:Circular blade instruments for cylindrical tissue sampling.
- Sutures:Absorbable and non-absorbable wound closure materials.
Surgical Excision Kits hold installed capacity. Hemostatic Agents is rotating up the share rankings.
Application:
Clinical indication severity dictates margin capture, with malignant lesion protocols commanding premium pricing versus cosmetic procedures subject to patient out-of-pocket sensitivity.
- Oncology:Melanoma and non-melanoma skin cancer excisions require wide local excision or Mohs micrographic surgery with margin control. Screening intensification in aging Western demographics is expanding diagnostic excision volumes through earlier lesion detection protocols.
- Dermatology:Diagnostic excisions for atypical nevi and inflammatory conditions. Outpatient clinic networks in France and the Netherlands are consolidating purchasing around suppliers with robust technical documentation under EU MDR post-market surveillance requirements.
- Cosmetic Surgery:Elective lesion removal and scar revision procedures.
- Trauma Treatment:Emergency debridement and foreign body removal.
Oncology commands premium positioning. Dermatology is climbing the fastest.
End User:
Site-of-service economics compress reimbursement differently across facility types, with freestanding centers capturing Medicare recalibration benefits versus hospital outpatient departments.
- Ambulatory Surgical Centers:Freestanding facilities optimized for same-day procedures. Medicare reimbursement recalibration in the United States is incentivizing capital deployment into freestanding excision facilities.
- Outpatient Clinics:Dermatology-focused settings with in-house pathology partnerships. Tier-2 Indian cities present white space for standardized excision protocol adoption as private healthcare investment accelerates.
- Hospitals:Academic medical centers and community hospitals with integrated pathology laboratories.
- Research Laboratories:Tissue acquisition for translational studies and clinical trials.
Ambulatory Surgical Centers hold procedure volume leadership. Outpatient Clinics is gaining share fastest.
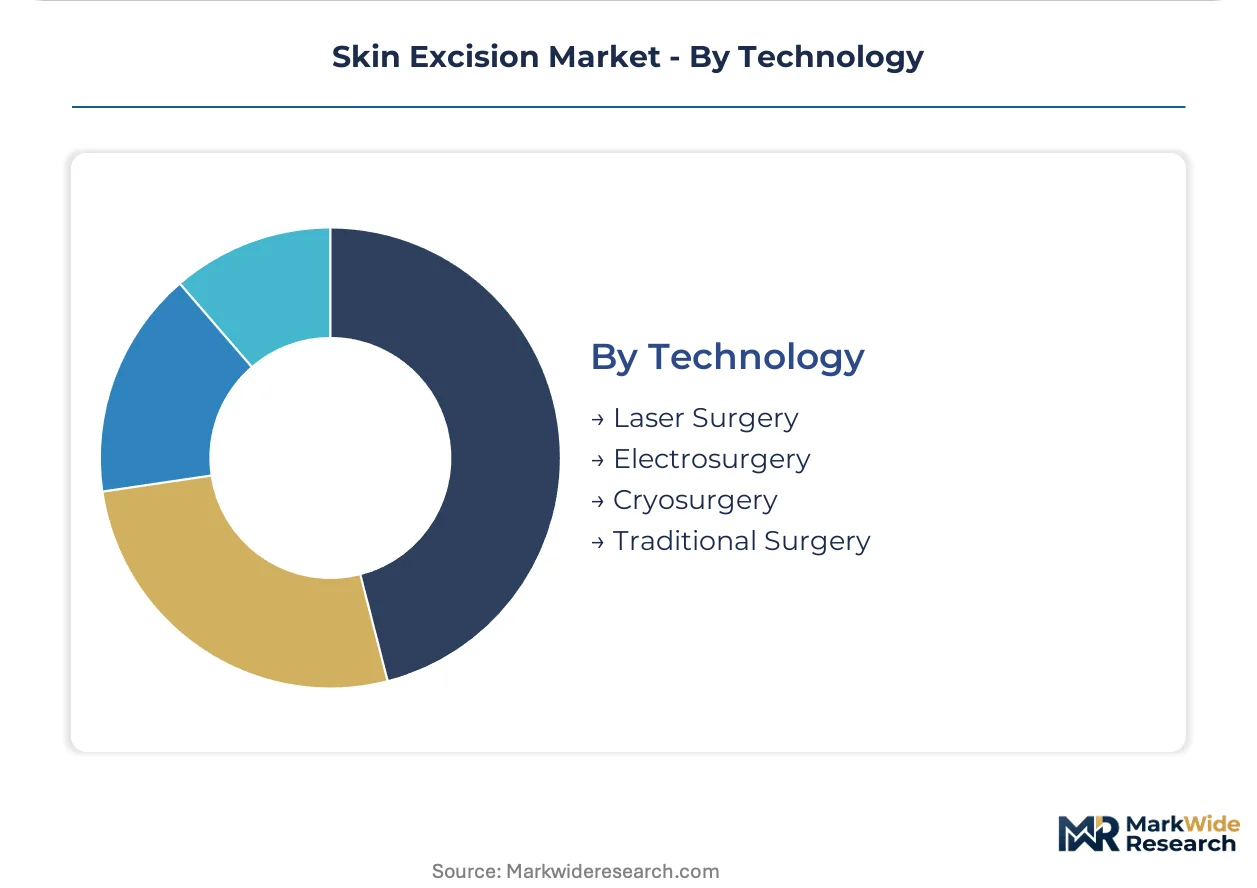
Technology:
Energy modality selection trades precision and hemostasis against capital cost and training requirements, with thermal technologies displacing cold steel in specific applications.
- Laser Surgery:Carbon dioxide and erbium:YAG systems enable precise tissue ablation with minimal thermal damage. Precision thermal coagulation systems are reducing operative time in cosmetic applications, pulling demand from traditional scalpel methods in dermatology clinics.
- Electrosurgery:Radiofrequency and electrocautery devices provide simultaneous cutting and coagulation. Input cost volatility from medical-grade polymer supply chains concentrated in East Asian manufacturing zones pressures disposable tip economics.
- Cryosurgery:Liquid nitrogen destruction of superficial lesions.
- Traditional Surgery:Scalpel-based excision with manual hemostasis.
Electrosurgery holds installed base dominance. Laser Surgery is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters concentrate in Germany and the United States, with regulatory compliance infrastructure shaping regional competitive moats. Asia-Pacific manufacturing zones supply polymer-based consumables to Western kit assemblers. Site-of-service economics diverge sharply across reimbursement regimes.
United States
Ambulatory surgical centers capture Medicare reimbursement recalibration benefits, consolidating outpatient excision volumes into freestanding facilities. FDA 510(k) clearance pathways dictate commercialization timelines for excision kits and energy-based devices. Texas and California metropolitan corridors concentrate employer-direct contracting networks that steer patients toward designated dermatology group practices.
Germany
Dermatology clinics expand minimally invasive protocols under tightened EU MDR device classification rules requiring enhanced clinical evidence. KARL STORZ GmbH & Co. KG anchors endoscopic visualization supply across European hospital networks. Bavaria and Baden-Württemberg host the densest concentrations of outpatient surgical infrastructure reconfigured for same-day discharge protocols.
France
Academic medical centers pilot confocal laser scanning microscopy systems for real-time margin assessment during Mohs micrographic surgery. ANSM post-market surveillance requirements align device performance tracking with patient outcome registries. Paris and Lyon metropolitan areas consolidate purchasing around suppliers with established vigilance systems under EU MDR compliance frameworks.
India
Private healthcare investment accelerates standardized excision protocol adoption across tier-2 city dermatology clinic networks. CDSCO medical device regulations govern import and distribution of surgical excision kits and hemostatic agents. Maharashtra and Karnataka present the most penetrated outpatient infrastructure for lesion removal procedures.
Japan
PMDA regulatory frameworks emphasize clinical evidence standards for laser surgery and electrosurgery devices entering the dermatology market. Aging demographics intensify melanoma screening programs, expanding diagnostic excision volumes through earlier detection protocols. Tokyo and Osaka metropolitan clusters concentrate integrated pathology laboratory capacity for histopathological confirmation workflows.
Skin Excision Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base organizes around three structural tiers: multinational surgical conglomerates with integrated portfolios, mid-scale device manufacturers with regional density, and consumable-focused suppliers with polymer conversion expertise. Competitive positioning depends on EU MDR technical documentation capacity and ambulatory surgical center kit specification relationships. M&A activity targets hemostatic agent lines and laser platform technology; geographic expansion concentrates on Indian outpatient clinic networks and US freestanding surgical facilities.
Within the integrated surgical systems tier, Medtronic leverages its portfolio breadth across European hospital networks, while Ethicon Inc anchors suture and hemostatic positioning through procurement channel dominance in Western markets. KARL STORZ GmbH & Co. KG occupies the visualization specialist archetype, supplying endoscopic systems employed in complex dermal lesion removals. These three entities exemplify divergent strategic foundations: conglomerate scale, consumable recurrence, and precision technology specialization.
| Leading Market Players |
|---|
| Medtronic |
| Ethicon Inc |
| Becton, Dickinson and Company |
| Integra LifeSciences |
| Richard Wolf GMBH |
| KARL STORZ GmbH & Co. KG |
| Zimmer Biomet |
| B. Braun SE |
| Conmed Corporation |
| Others |
Cost & Logistics Intelligence
Underutilized polymer conversion capacity in East Asian manufacturing zones is forcing sterile kit suppliers toward volume-based contract terms while compressing margins on electrocautery consumables. This utilization asymmetry between component manufacturers and Western kit assemblers shapes procurement leverage across ambulatory surgical center networks.
Pricing Analysis
EU MDR dictates the pricing tier structure across surgical excision kits, with enhanced clinical evidence requirements separating premium-certified suppliers from commodity-positioned competitors. Three-tier pricing stratifies across premium CE-marked vigilance systems, standard FDA-cleared configurations, and economy-grade unbranded consumables. Cost compression in the economy tier is intensifying because of polymer feedstock volatility, while hospital purchasing committees exhibit lowest price sensitivity for hemostatic agents in anticoagulated patient protocols.
Supply Chain Analysis
Export control restrictions on medical-grade laser optics limit technology transfer from German precision engineering clusters to emerging manufacturing hubs. Component sourcing draws from China for polymer-based consumables, Germany for endoscopic visualization systems, and the United States for radiofrequency electrosurgery platforms. Single-source vulnerability concentrates in medical-grade gelatin and collagen hemostat precursors. Distribution runs through GPO contracts and direct hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The skin excision market is accelerating through EU MDR regulatory disruption, with clinical evidence requirements creating competitive moats that favor manufacturers with established technical documentation infrastructure.
For Market Incumbents: Insulate installed base relationships by embedding EU MDR vigilance systems into hospital procurement workflows before mid-tier competitors complete legacy portfolio re-certification. Deepen backward integration into medical-grade polymer supply to offset East Asian input cost volatility. Prioritize ambulatory surgical center kit specification partnerships as Medicare site-of-service reimbursement recalibration concentrates volume in freestanding facilities. For New Entrants and Emerging Players: Tier-2 Indian city dermatology networks present the most penetrable white space for standardized excision protocol adoption, given accelerating private healthcare investment and underdeveloped outpatient surgical infrastructure. Target cosmetic laser surgery applications where precision thermal coagulation technology displaces traditional scalpel methods. Pursue teledermatology platform partnerships to channel digital triage toward in-person excision appointments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across hemostatic agent manufacturing as modular biopolymer processing equipment reduces minimum efficient scale. Acquisition candidates with established EU MDR technical documentation and Indian distribution licenses offer viable five-to-ten-year positioning. Monitor CDSCO regulatory harmonization progress as signal for Indian market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Establishes competitive moats against mid-tier manufacturers with legacy device portfolios requiring evidence regeneration. |
| Ambulatory Surgical Center Partnership Development | Captures Medicare reimbursement recalibration benefits as site-of-service economics shift toward freestanding facilities. |
| Confocal Laser Scanning Microscopy Platform Integration | Collapses Mohs micrographic surgery excision-and-verify cycles from multiple stages toward single-session completion. |
| Indian Tier-2 City Clinic Network Expansion | Addresses underpenetrated dermatology infrastructure as private healthcare investment accelerates standardized protocol adoption. |
| Hemostatic Agent Backward Integration | Offsets medical-grade polymer supply chain volatility concentrated in East Asian manufacturing zones. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with dermatology clinic directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation registries, CMS Medicare reimbursement filings, and hospital procurement contract repositories. Bottom-up procedure volume estimates triangulated against top-down device manufacturer revenue positioning.
Forecast inputs considered technology modality transitions, site-of-service reimbursement recalibration, and regulatory compliance timelines across the projection horizon. Segmentation dimensions modeled include product configuration tiers, procedural setting economics, energy modality adoption curves, and geographic regulatory clusters. CAGRs derived from procedure volume trajectories weighted by average selling price evolution and mix-shift assumptions between hospital outpatient departments and ambulatory surgical centers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity deployment by laser platform specialists or accelerated EU MDR enforcement against legacy portfolios would shift outcomes. Material shifts in polymer feedstock trade flows or CDSCO regulatory harmonization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Global Online Dermatology Consultation Market
Dermatology
Acne Scar Treatment Market
Dermatology
Radiation Dermatitis Market
Dermatology
Global Radiodermatitis Market
Dermatology
Darier Disease Drugs Market
Dermatology
Scar Treatment Oils Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market
Dermatology
Australia Skin Treatment Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Global Rosacea Market
Dermatology
Common Warts Market
Dermatology
Dermatological Products Market
Dermatology
Impetigo Treatment Market
Dermatology
Rosacea Treatment Market
Dermatology
Athletes Foot (Tinea Pedis) Treatment Market
Dermatology
Dermabrasion Market