
 Sulfur Fertilizer Market | 2026-2036
Sulfur Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Sulfur Fertilizer Market Intelligence
Aftermarket agronomic advisory revenue is rewriting margin capture across the sulfur fertilizer value chain. Nutrien Ltd. leverages its retail distribution network to bundle soil testing with sulfur prescription services. Yara International ASA anchors premium positioning through digital farming platforms that optimize sulfur application timing. Koch Fertilizer LLC competes on manufacturing scale, with integrated sulfur supply from North American oil and gas refining.
Sulfur fertilizer encompasses sulfur-containing compounds—primarily elemental sulfur, ammonium sulfate, and sulfate-based micronutrient blends—applied to correct soil sulfur deficiency and enhance protein synthesis in plants. Granular formulations dominate volume sales due to mechanical compatibility with existing spreader fleets, while liquid sulfur products are gaining share in fertigation systems where precision delivery reduces leaching losses. Application segmentation shows crops as the mature volume base, whereas horticulture represents the fastest-expanding margin pool as high-value produce commands premium input pricing.
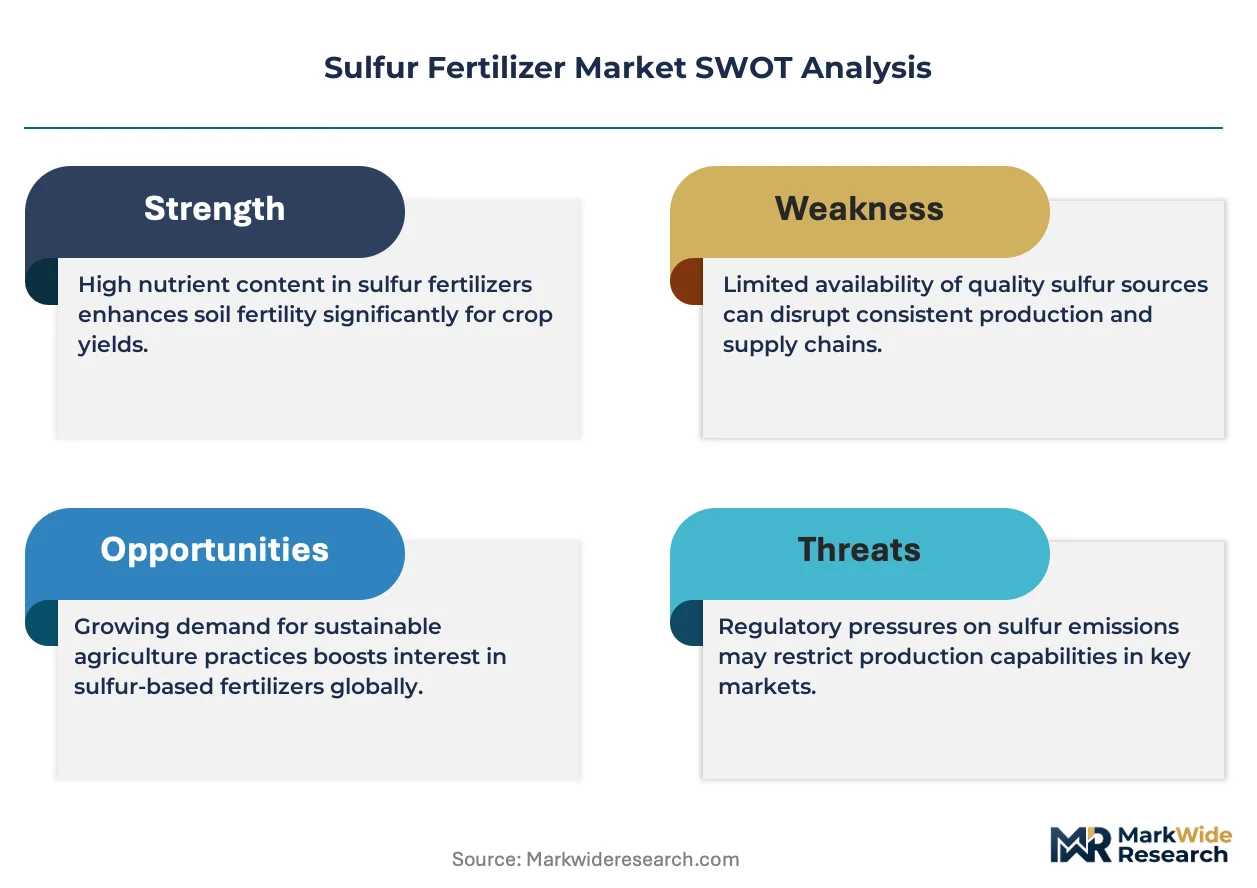
The EPA regulates sulfur compound emissions from phosphate fertilizer production under the Clean Air Act, while the EU Fertilizing Products Regulation mandates CE marking and contaminant limits for marketed products. India's FSSAI and BIS frameworks govern fertilizer quality standards and micronutrient labeling requirements, shaping import specifications and domestic manufacturing compliance. Stakeholders must monitor evolving carbon border mechanisms and nutrient-use-efficiency mandates that will increasingly determine market access and product formulation economics.
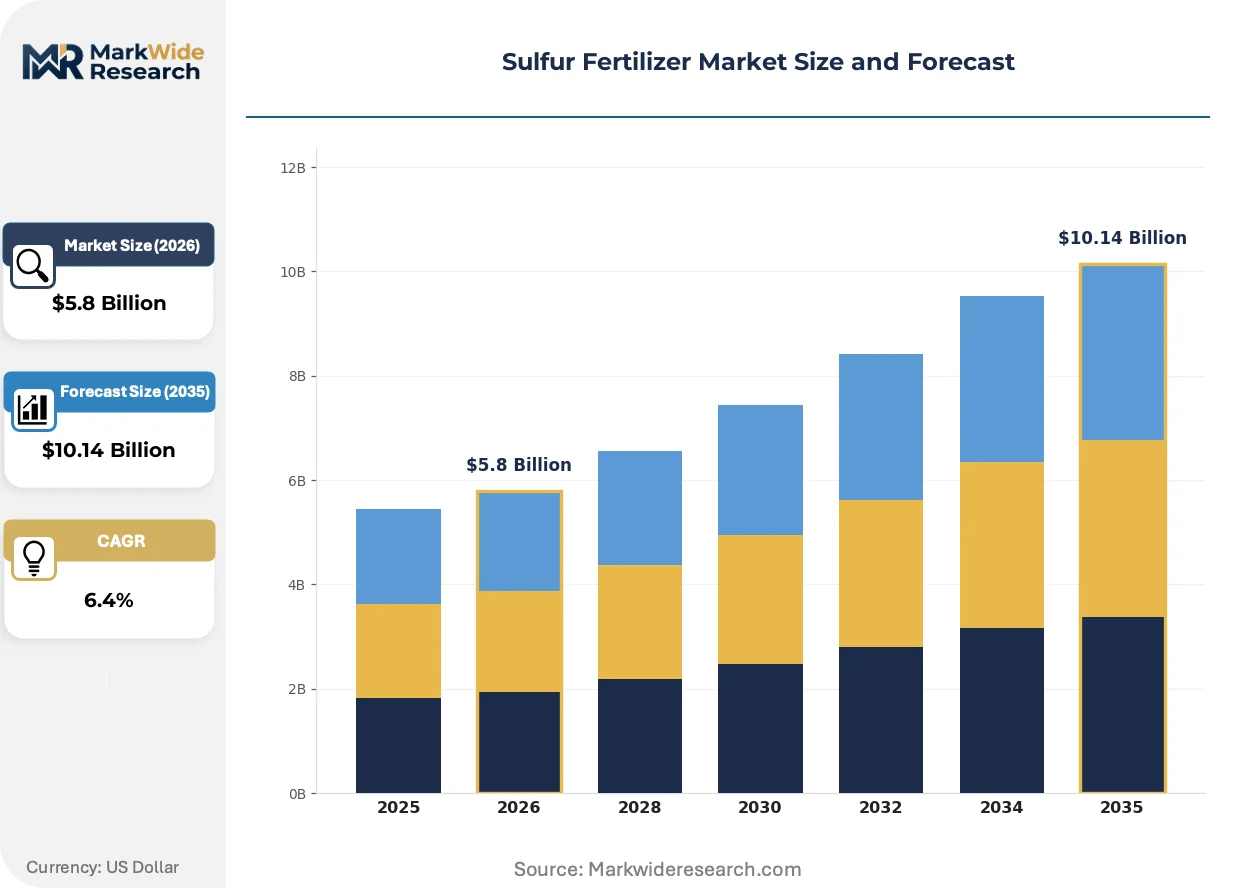
Market Dynamics
The sulfur fertilizer market is undergoing structural recalibration as the EU Fertilizing Products Regulation tightens contaminant thresholds, forcing manufacturers to reformulate products and absorb compliance costs while agronomic advisory services capture expanding margin pools.
Growth Catalysts
- EU Fertilizing Products Regulation:The CE marking mandate and stricter contaminant limits are accelerating product standardization across member states, creating compliance-driven replacement cycles for legacy formulations.
- Oilseed crop expansion:Brazil and Black Sea region farmers are elevating sulfur application rates to support protein synthesis in high-oil cultivars, sustaining volume demand despite commodity price volatility.
- Indo-Gangetic Plain intensification:Sulfur-deficient alluvial soils combined with intensive wheat-rice rotations generate sustained procurement from state-backed distribution networks and private dealers.
Market Restraints
- Refinery sulfur price volatility:Elemental sulfur derived from North American oil and gas processing exposes fertilizer manufacturers to feedstock cost swings that compress blending margins.
- Granular formulation lock-in:Mechanical spreader fleets across major agricultural regions create technical path dependency, slowing liquid sulfur adoption despite fertigation efficiency gains.
- Import specification friction:India's BIS quality standards and FSSAI micronutrient labeling requirements create documentary bottlenecks for cross-border shipments, extending clearance timelines.
Strategic Opportunities
- Horticulture premiumization:High-value produce growers in protected cultivation systems command premium input pricing, opening margin expansion for sulfate-based micronutrient blends.
- Digital farming convergence:Soil testing integration with variable-rate application technology enables prescription sulfur services that differentiate beyond commodity tonnage.
- Carbon border positioning:Early alignment with emerging EU carbon border adjustment mechanisms offers first-mover access for low-emission sulfur production pathways.
Industry Challenges
- Agronomic advisory talent scarcity:Soil science and precision agriculture expertise shortages constrain the scaling of bundled testing-to-prescription service models.
- Legacy equipment integration:Retrofitting existing spreader fleets for liquid sulfur compatibility demands capital outlays that smaller farm operations defer during input price spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulfur Fertilizer Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Powder, Suspension Application: Crops, Horticulture, Pastures, Turf Delivery Mode: Broadcast, Foliar, Fertigation, Seed Treatment End User: Farmers, Distributors, Retailers, Cooperatives |
| Companies Covered | Yara International ASA, Nutrien Ltd., The Mosaic Company, ICL Group Ltd., CF Industries Holdings Inc., K+S AG, EuroChem Group AG, Koch Fertilizer LLC, Shell Sulfur Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulfur Fertilizer Market Strategic Shifts & Innovations
Product formulation and delivery mechanisms are pivoting toward precision agriculture compatibility, while regulatory frameworks restructure competitive access conditions and buyer procurement patterns fragment across service-integrated channels.
Controlled-release sulfur coatings are migrating from research-stage demonstration plots to commercial-scale adoption among Midwestern US corn-soy operations seeking to reduce leaching losses and synchronize nutrient availability with crop uptake windows. Large-scale cooperatives are piloting these formulations to meet watershed nutrient management plans. The technology is compressing traditional volume-based procurement models toward outcome-verified supply agreements.
REACH substance registration requirements and the EU Fertilizing Products Regulation's contaminant thresholds are compelling reformulation of phosphate co-products containing sulfur. Manufacturers serving European markets are investing in purification infrastructure to meet cadmium and heavy metal limits. Specialty fertilizer blends targeting organic cultivation systems face the steepest compliance cost escalation.
Aftermarket agronomic advisory unbundling is fragmenting traditional dealer relationships as Brazilian soybean growers and Indo-Gangetic wheat farmers separately contract soil testing, prescription mapping, and input fulfillment. Digital platforms are intermediating these transactions, eroding bundled distributor margins. This pattern is most pronounced in regions with high smartphone penetration and fragmented landholding structures.
Sulfur Fertilizer Market Segmentation
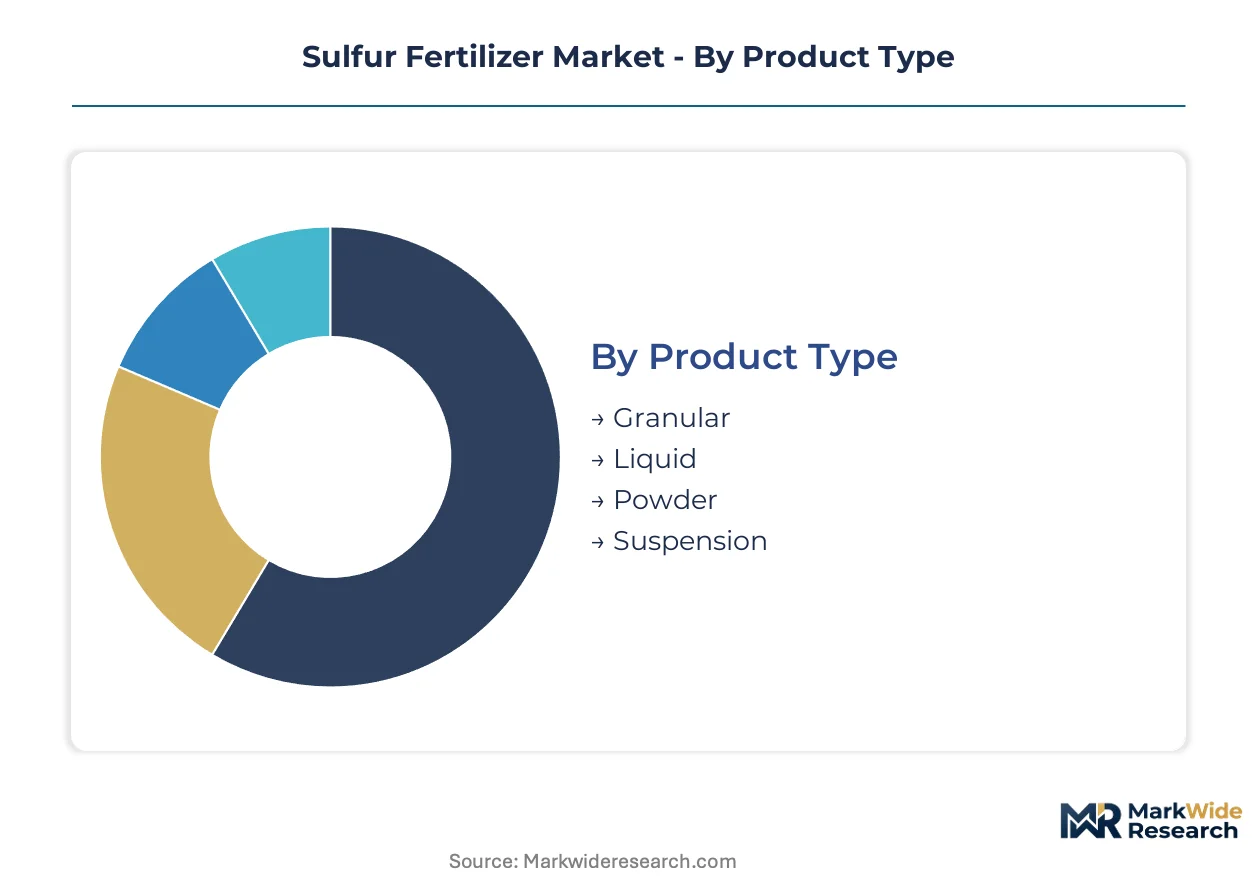
Sulfur fertilizer segmentation reveals divergent margin structures across physical forms and application channels. Product formulation choices lock in equipment compatibility, while delivery mode selection determines precision agriculture integration depth.
Product Type:
Mature mechanical spreading infrastructure dominates volume flows, though liquid systems are capturing precision agriculture expansion.
- Granular:Compressed sulfur prills or pellets engineered for mechanical spreader compatibility dominate procurement volumes across wheat-rice rotations in the Indo-Gangetic Plain. Existing equipment fleets in Brazil and Ukraine create technical path dependency that sustains this segment despite leaching inefficiencies in high-rainfall zones.
- Liquid:Dissolved or emulsified sulfur formulations enable metered injection through fertigation infrastructure, gaining traction in California almond orchards and Spanish greenhouse complexes where water-soluble nutrient delivery synchronizes with drip irrigation schedules.
- Powder:Micronized elemental sulfur serves specialty blending operations and soil amendment compounding in organic certification systems.
- Suspension:Colloidal sulfur dispersions support high-concentration foliar applications in high-value horticulture.
Granular retains volume leadership; liquid holds the steepest expansion curve.
Application:
Commodity crop tonnage anchors revenue stability, while protected cultivation commands premium pricing multiples.
- Crops:Field-scale cereal and oilseed cultivation consumes standardized sulfate formulations, with Brazilian soybean operations and Black Sea wheat belts driving procurement scale.
- Horticulture:Protected cultivation of tomatoes, peppers, and leafy greens in Almeria and the Netherlands commands micronutrient blends with sulfur co-fortification at 3-4x commodity pricing.
- Pastures:Grassland sulfur supplementation supports livestock-forage systems in New Zealand and Ireland.
- Turf:Golf course and sports field maintenance in Florida and the UAE sustains specialized sulfate demand.
Crops anchor procurement tonnage; horticulture captures the widest margin spreads.
Delivery Mode:
Application technology choices segment farmers by capital intensity and precision agriculture adoption stage.
- Broadcast:Surface spreading of granular sulfur dominates smallholder operations across India and Ukraine where equipment retrofit costs deter precision system adoption.
- Foliar:Direct leaf-surface application of liquid or suspension sulfur corrects acute deficiencies in high-value orchards and vineyards.
- Fertigation:Irrigation-integrated nutrient delivery concentrates in Israeli net-house operations and Californian Central Valley nut production.
- Seed Treatment:Coating applications protect emerging oilseed rape and legume seedlings in Canadian prairie provinces.
Broadcast retains equipment-driven dominance; fertigation posts the most rapid adoption velocity.
End User:
Channel structure fragments between state-backed procurement networks and private advisory-integrated retail.
- Farmers:Direct procurement concentrates among large-scale operations in Brazil and Australia seeking volume discounts on elemental sulfur.
- Distributors:Wholesalers buffer inventory across seasonal demand cycles in the US Corn Belt and Argentine Pampas.
- Retailers:Input dealers bundle sulfur with soil testing services in the Indo-Gangetic Plain, capturing advisory margins.
- Cooperatives:Member-owned purchasing bodies aggregate demand across Midwestern US and French cereal regions.
Retailers are gaining channel share fastest; cooperatives retain collective bargaining leverage in mature markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian soybean operations favor granular sulfate broadcasting for mechanical spreader compatibility, while Dutch greenhouse complexes deploy liquid sulfur through precision fertigation infrastructure. This consumption-mix differential separates volume-driven commodity applications from premium horticulture systems.
Brazil
Oilseed expansion across Mato Grosso and Goiás elevates sulfur application rates for protein synthesis in high-yield soybean cultivars. ANVISA oversees agricultural input registration, though fertilizer quality standards fall under MAPA jurisdiction. São Paulo-based cooperatives pilot controlled-release sulfur coatings to meet watershed nutrient management requirements.
India
Intensive wheat-rice rotations across Punjab and Haryana sustain granular sulfur procurement through state-backed distribution networks. BIS quality standards and FSSAI micronutrient labeling requirements shape import specifications and domestic manufacturing compliance. Uttar Pradesh retailers bundle soil testing with sulfur prescription services, capturing advisory margins.
United States
Midwestern corn-soy operations drive elemental sulfur demand through large-scale cooperatives seeking volume discounts. EPA regulates sulfur compound emissions from phosphate fertilizer production under the Clean Air Act. Iowa and Illinois distribution hubs buffer inventory across seasonal demand cycles while integrating digital soil mapping platforms.
Germany
Specialty fertilizer blends targeting organic cultivation systems face steep compliance cost escalation under REACH substance registration and EU Fertilizing Products Regulation thresholds. CE marking mandates accelerate product standardization across member states. North Rhine-Westphalia purification infrastructure investments address cadmium and heavy metal limits in phosphate co-products.
Netherlands
Protected cultivation of tomatoes and peppers in Almeria-style greenhouse clusters commands micronutrient blends with sulfur co-fortification at premium pricing multiples. EU Fertilizing Products Regulation contaminant limits drive reformulation of legacy products. Wageningen-area research partnerships advance variable-rate application technology integration with sulfur prescription services.
Sulfur Fertilizer Market Key Industry Players
Capability concentration sits with specialty blenders possessing agronomic advisory infrastructure; scale advantage sits with integrated manufacturers commanding captive sulfur supply. The market structures around three tiers: global diversified fertilizer conglomerates, regional sulfate specialists, and precision agriculture platform operators. Consolidation pressures favor players combining manufacturing scale with digital farming integration. Dominant competitive moves include backward integration into sulfur refining and strategic partnerships with soil testing laboratories.
Among integrated manufacturing conglomerates, Yara International ASA and Nutrien Ltd. exemplify divergent strategic positioning. Yara anchors premium market presence through digital farming platform investments that optimize sulfur application timing. Nutrien leverages North American retail distribution density to bundle soil testing with prescription services, capturing advisory margins beyond commodity tonnage. Koch Fertilizer LLC occupies a position at the scale-driven end, with integrated sulfur supply derived from oil and gas refining operations.
| Leading Market Players |
|---|
| Yara International ASA |
| Nutrien Ltd. |
| The Mosaic Company |
| ICL Group Ltd. |
| CF Industries Holdings Inc. |
| K+S AG |
| EuroChem Group AG |
| Koch Fertilizer LLC |
| Shell Sulfur Solutions |
| Others |
Cost & Logistics Intelligence
Refinery sulfur price volatility determines both pricing tier spreads and supply chain shape across the sulfur fertilizer value chain. North American oil and gas processing concentration exposes blenders to feedstock cost swings that compress margins in commodity sulfate segments while sustaining premium capture for controlled-release formulations.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated refiners and large-scale cooperatives, insulating volume buyers from spot market swings in elemental sulfur. Price differentiation rests on formulation grade and certification tier, with EU Fertilizing Products Regulation CE marking commanding 15-20% premiums over non-compliant blends. Cost compression in standard ammonium sulfate is intensifying because Brazilian soybean operations are consolidating purchases through cooperative bargaining. Smallholder broadcast applicators in the Indo-Gangetic Plain exhibit the highest price sensitivity, while Dutch greenhouse operators purchasing micronutrient blends show the least.
Supply Chain Analysis
Extended payment terms from Koch Fertilizer LLC and other integrated manufacturers cushion distributor working capital across seasonal demand cycles in the US Corn Belt. Elemental sulfur supply concentrates in the United States, Canada, and Russia, drawing from oil and gas refining byproduct streams. Ammonium sulfate production rests on phosphate fertilizer co-product availability and caprolactam manufacturing outputs. Single-source vulnerability runs through North American refinery sulfur dependency for domestic blenders. Distribution runs through cooperatives and retail dealer networks that buffer inventory across planting seasons.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate substitution pressure from nitrogen stabilizers and enhanced-efficiency fertilizers that reduce sulfur leaching losses in high-rainfall zones.
For Market Incumbents: Build agronomic advisory moats by bundling soil testing with prescription services to lock in farmer relationships beyond commodity tonnage. Backward integration into sulfur refining secures feedstock cost control against refinery price volatility. Expand controlled-release coating capacity in Midwestern US corn-soy regions to meet watershed nutrient management compliance requirements. For New Entrants and Emerging Players: Pursue liquid sulfur formulation partnerships with fertigation equipment manufacturers to bypass granular spreader fleet lock-in. Target California almond orchards and Spanish greenhouse complexes where precision irrigation infrastructure enables metered sulfur injection. Enter through digital farming platform integration that intermediates soil testing-to-prescription transactions. For Investors and Strategic Acquirers: EU Fertilizing Products Regulation cadmium threshold enforcement reshapes the acquisition landscape toward purification-capable blenders. Long-term viability centers on players combining manufacturing scale with digital advisory infrastructure across a multi-year transition window. Acquire specialty sulfate compounders with REACH registration assets and existing CE marking compliance. Watch EU carbon border adjustment mechanism development as the signal for low-emission sulfur production pathway valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Refining | Captive supply from North American oil and gas processing insulates blending margins from feedstock volatility. |
| Controlled-Release Coating Capacity Expansion | Midwestern US watershed nutrient management plans drive commercial adoption beyond research demonstration plots. |
| Digital Farming Platform Partnership | Wageningen-area research collaborations advance variable-rate sulfur application timing optimization. |
| Purification Infrastructure Investment | North Rhine-Westphalia facilities address EU Fertilizing Products Regulation cadmium and heavy metal limits. |
| Agronomic Advisory Service Bundling | Uttar Pradesh retailers capture margins beyond commodity tonnage through soil testing integration. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interviews with fertilizer plant managers, cooperative procurement leads, retail distribution channel partners, and technical agronomy directors. Secondary validation drew from customs and trade data, SEC 10-K filings, EU fertilizer registration databases, and BIS quality standard documentation. Bottom-up volume modeling triangulated against top-down macroeconomic indicators to ensure segment-level consistency.
Calibration against historical volume trajectories and regional production capacity utilization informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product formulation type, application crop category, delivery mode technology, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized growth curves fitted to validated baseline data. Industry-specific forecast inputs incorporated refinery sulfur availability projections and EU Fertilizing Products Regulation compliance cost estimates.
Macroeconomic conditions sit as an overlay; deviation in energy prices, fertilizer input costs, or agricultural commodity returns would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
North America Organic Fertilizers Market
Fertilizers
Asia-Pacific Fertilizers Market
Fertilizers
China Organic Fertilizers Market
Fertilizers
Egypt Fertilizer Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
Global Fertilizers Market
Fertilizers
United States Fertilizers Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Silicon Fertilizer Market
Fertilizers
South America Fertilizers Market
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
Global Specialty Fertilizer Market
Fertilizers
Fertilizer Applicators Market
Fertilizers
Southeast Asia Fertilizer Market
Fertilizers
United States Micronutrient Fertilizer Market