
 India Phosphate Rich Organic Manure (PROM) Market | 2026-2036
India Phosphate Rich Organic Manure (PROM) Market Size, Share, and Industry Trends Forecast 2026-2036
India Phosphate Rich Organic Manure (PROM) Market Insights
Aftermarket soil-testing service revenue is narrowing as integrated PROM suppliers bundle agronomic advisory with product sales. National Fertilizers Limited anchors its position through captive rock-phosphate sourcing from Rajasthan mines. Godrej Agrovet differentiates via specialized liquid PROM formulations for precision drip systems. Coromandel International dominates south Indian distribution through its extensive rural dealer network.
Phosphate Rich Organic Manure is a composted organic fertilizer containing percent-grade citrate-soluble phosphate bound with organic carbon carriers, manufactured through co-composting of low-grade rock phosphate with farm waste or press mud to achieve phosphate availability between six and ten percent on a dry-weight basis. Its primary purpose is to correct phosphate deficiency in alkaline-calcareous soils where conventional DAP fixation renders phosphorus unavailable to crops. Granular PROM leads volume due to mechanical compatibility with existing broadcaster equipment, while liquid formats attract the fastest growth from greenhouse and protected-cultivation adopters seeking fertigation integration. The wholesale channel still captures the dominant margin pool through government-subsidized bulk procurement routed via state agricultural departments.
BIS certification requirements under the Fertilizer Control Order and periodic CEA quality audits shape product standards and market access for PROM manufacturers operating across Indian states. The PLI scheme for advanced biofertilizer manufacturing incentivizes capital investment in automated composting infrastructure. Stakeholders must monitor how state-level organic farming missions recalibrate subsidy eligibility between chemical and organic phosphate sources.
Market Dynamics
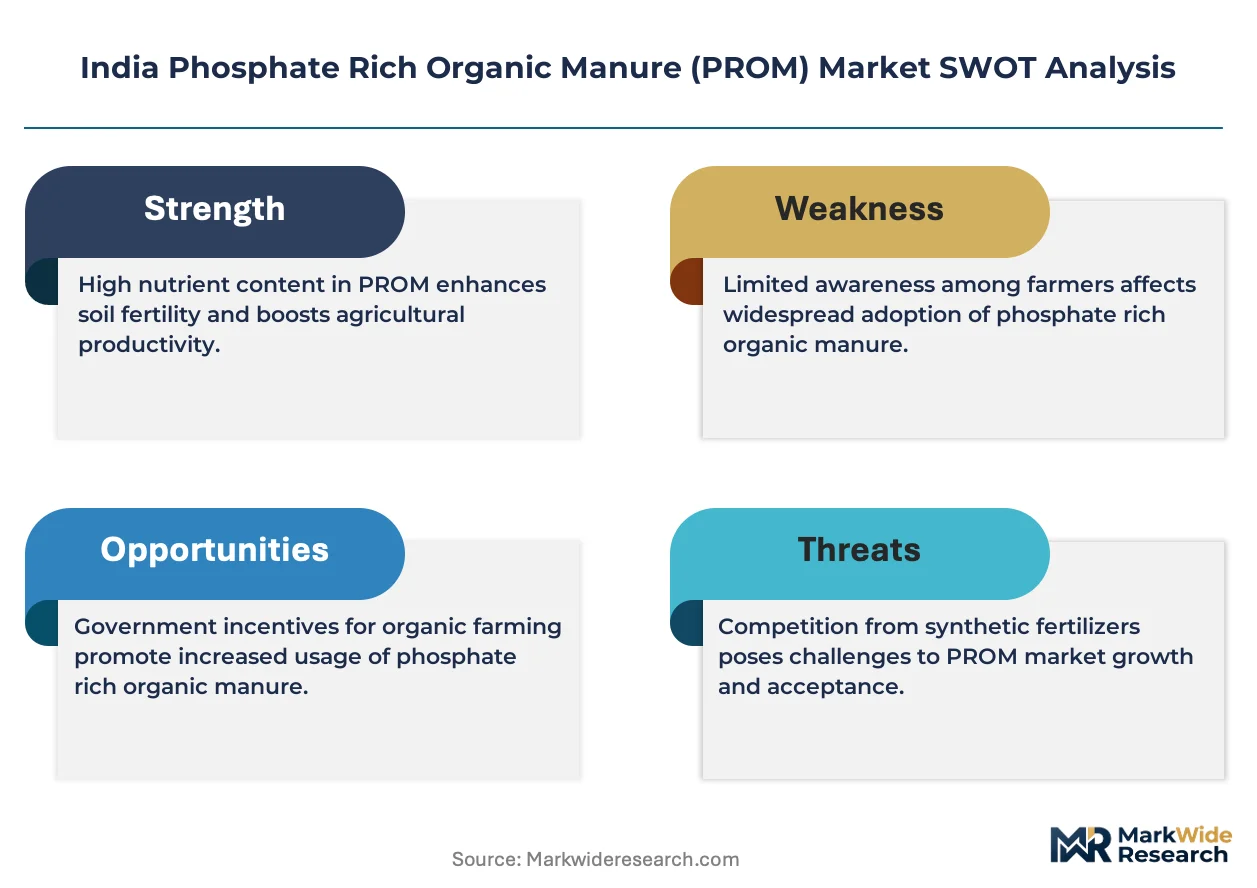
India's Phosphate Rich Organic Manure sector is compressing around regulatory enforcement of the Fertilizer Control Order, which is tightening citrate-soluble phosphate thresholds and disqualifying substandard composted products from state subsidy channels.
Growth Catalysts
- Fertilizer Control Order amendments:The Ministry of Agriculture's tightened chemical-phosphate limits in Punjab and Haryana are forcing conventional DAP users toward certified PROM alternatives.
- Soil phosphate deficiency:Maharashtra's sugarcane belt and Gujarat's horticulture clusters exhibit acute phosphorus fixation in alkaline-calcareous soils, driving farmer conversion to organic phosphate sources.
- PLI scheme for biofertilizers:Capital subsidies for automated composting infrastructure are lowering entry barriers for mechanized PROM manufacturers with captive rock-phosphate linkages.
Market Restraints
- Low-grade rock phosphate supply concentration:Rajasthan's captive mines dominate domestic feedstock, creating geographic supply vulnerability for non-integrated producers in eastern and southern states.
- BIS certification timeline friction:The Bureau of Indian Standards' multi-stage testing protocol for citrate-soluble phosphate content extends product-to-market cycles by six to nine months.
- DAP price volatility spillover:Subsidized diammonium phosphate remains price-competitive in government procurement channels, constraining PROM adoption among cost-sensitive smallholders.
Strategic Opportunities
- Protected cultivation expansion:Greenhouse operators in Karnataka and Telangana are adopting liquid PROM formulations for fertigation integration, opening premium pricing corridors.
- State organic farming missions:Subsidy recalibration toward organic phosphate sources in Maharashtra and Gujarat creates first-mover advantage for certified suppliers.
- Soil-testing service bundling:Integrated PROM suppliers can capture advisory revenue streams that standalone agronomists are losing to product-plus-service models.
Industry Challenges
- Composting microbiology expertise gap:Co-composting of low-grade rock phosphate with farm waste requires specialized microbial inoculation protocols that agronomy graduates rarely possess.
- CEA audit compliance burden:Periodic quality audits by the Controller of Explosives and Agriculture impose documentation overhead that informal composting operations cannot sustain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Phosphate Rich Organic Manure (PROM) Market |
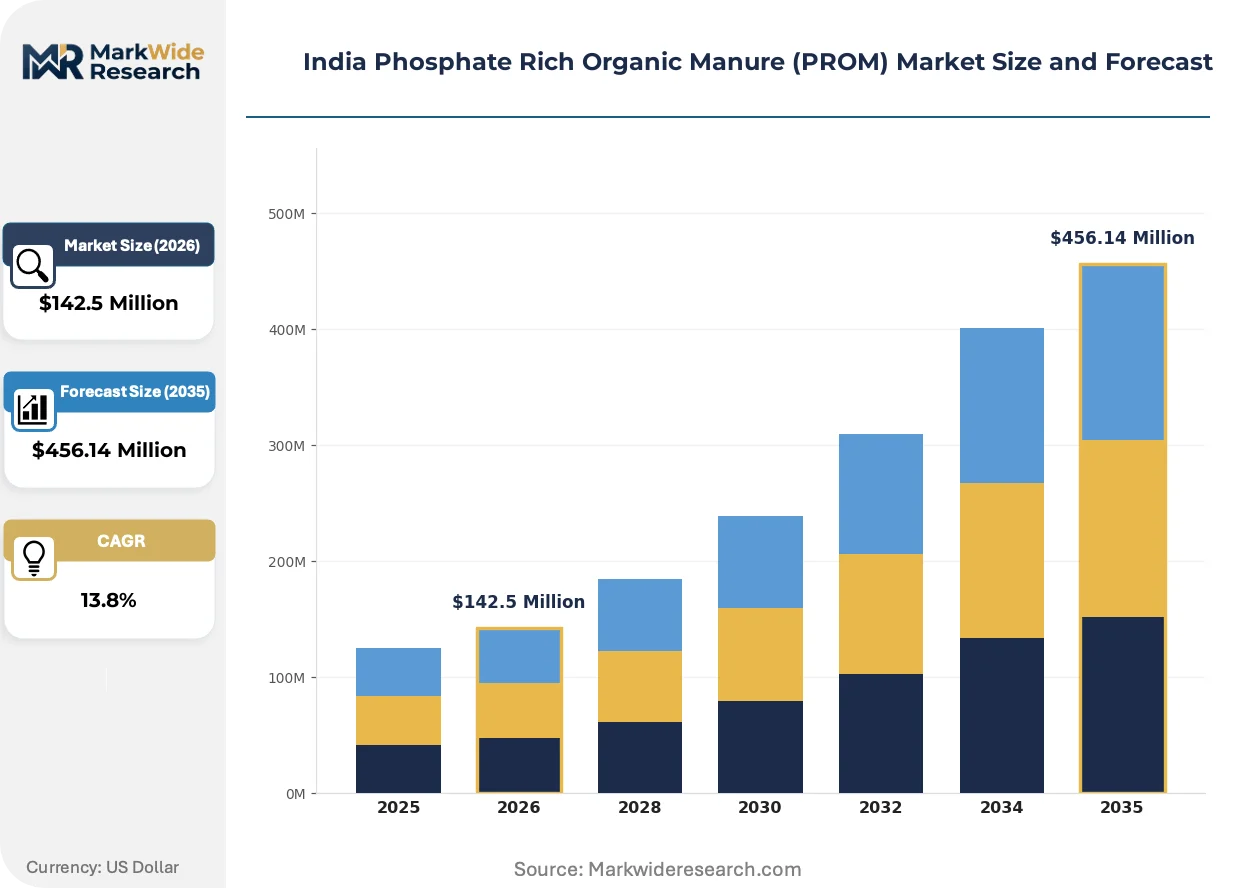
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $456.14 Million |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Powdered, Enriched Application: Crops, Vegetables, Fruits, Turf Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales End User: Agricultural Producers, Gardeners, Landscapers, Organic Farmers |
| Companies Covered | National Fertilizers Limited, Godrej Agrovet Limited, Gujarat State Fertilizers & Chemicals Limited, Nextnode BioScience Pvt. Ltd., Deepak Fertilisers & Petrochemicals Corporation Limited, Chambal Fertilizers and Chemicals Limited, Biogen Fertilizers India Private Limited, Agri India Biotech, Coromandel International Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Phosphate Rich Organic Manure (PROM) Market Trends and Innovations
Product format diversification and regulatory digitization are restructuring how phosphate-bound organic carbon reaches Indian farms, with liquid formulations and precision application technologies gaining operational traction.
Co-composting technology is hybridizing with automated temperature and moisture control systems to standardize citrate-soluble phosphate availability between six and ten percent. Large-scale PROM manufacturers in Rajasthan and Madhya Pradesh are deploying these systems to meet BIS certification thresholds consistently. This convergence is compressing quality variance between batches and disqualifying artisanal composting operations from institutional procurement.
The Fertilizer Control Order's 2024 amendments have introduced mandatory QR-code traceability for subsidized organic fertilizer bags, with state agricultural departments now verifying citrate-soluble phosphate claims through centralized databases. This digitization is shifting competitive advantage toward integrated manufacturers with in-house laboratory infrastructure. Maharashtra's sugarcane cooperatives are responding by demanding batch-specific test certificates before releasing payment.
Farmer buying patterns are fragmenting away from single-channel dependence on state agricultural department bulk procurement. Direct-to-farm dealer networks and cooperative society aggregators are capturing margin pools previously reserved for wholesale distributors. This channel disintermediation is most visible in Gujarat's horticulture clusters, where progressive farmers negotiate liquid PROM supply contracts directly with formulation specialists.
India Phosphate Rich Organic Manure (PROM) Market Segmentation
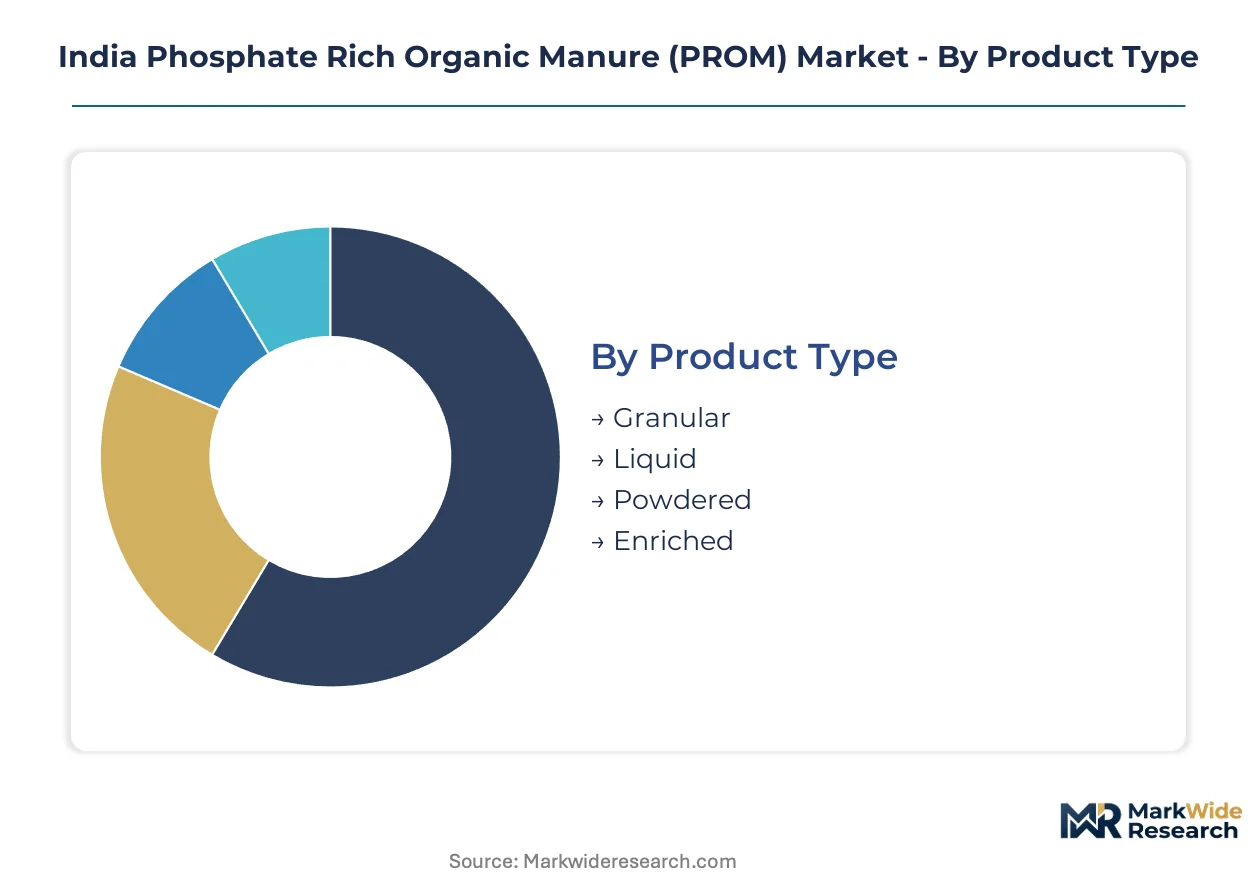
Segmentation in the India PROM market reveals how phosphate delivery formats, crop-specific applications, and procurement channels align with distinct farmer capabilities and soil conditions. Understanding these divides helps suppliers match product specifications to agronomic requirements and subsidy eligibility pathways.
Product Type:
After-sales service intensity varies sharply across physical formats, with liquid formulations demanding technical advisory for fertigation calibration while granular products rely on equipment compatibility support.
- Granular:Spherical or irregular granules containing citrate-soluble phosphate bound to organic carbon carriers, engineered for mechanical spreading compatibility with existing broadcaster equipment. Demand concentrates in Punjab and Haryana where wheat-paddy rotation farmers transitioning from DAP require plug-and-play application methods without irrigation infrastructure investment.
- Liquid:Suspension or solution formulations with phosphate availability optimized for drip and sprinkler fertigation systems. Protected cultivation operators in Karnataka and Telangana are adopting this format fastest, driven by greenhouse automation and precision nutrient delivery requirements.
- Powdered:Fine-ground PROM with enhanced surface area for rapid soil incorporation, typically applied in high-value horticulture where manual broadcasting suffices.
- Enriched:Value-added variants fortified with microbial consortia or secondary nutrients, targeting organic certification premiums in export-oriented production clusters.
By volume, Granular leads. By growth pace, Liquid is expanding most quickly.
Application:
Cost tier stratification separates commodity grain applications from premium horticulture segments where phosphate deficiency correction commands higher per-hectare expenditure.
- Crops:Field crops including wheat, rice, and sugarcane where soil phosphorus fixation in alkaline-calcareous conditions demands repeated organic phosphate amendment. Maharashtra's sugarcane belt represents the dominant demand concentration as cooperatives enforce BIS-certified input procurement.
- Vegetables:Solanaceous and leafy vegetables requiring rapid early-stage phosphorus uptake for root establishment. Gujarat's peri-urban vegetable clusters near Ahmedabad and Surat are converting fastest due to export market organic certification pressure.
- Fruits:Orchard crops including mango, banana, and pomegranate where long-term soil phosphate buildup matters more than immediate availability.
- Turf:Golf courses, sports grounds, and commercial landscaping with aesthetic performance standards driving specialized slow-release formulations.
Crops capture the largest acreage base. Vegetables exhibit the steepest conversion trajectory from chemical to organic phosphate sources.
Distribution Channel:
Margin retention differs substantially across channels, with government wholesale procurement compressing supplier margins while direct sales preserve pricing power through relationship-based advisory bundling.
- Retail:Rural agricultural input shops serving smallholders with bagged quantities and seasonal credit terms. Dealer networks in Tamil Nadu and Andhra Pradesh are consolidating around multi-product agri-input chains.
- Wholesale:State agricultural department bulk procurement under subsidized schemes, still capturing the dominant procurement volume despite channel disintermediation trends.
- E-commerce:Digital platforms aggregating demand from progressive farmers and urban gardeners, growing fastest in tier-2 cities with smartphone penetration.
- Direct Sales:Manufacturer-to-farm contracts for large cooperatives and commercial estates, bypassing distributor margins through volume commitments.
Wholesale moves the largest tonnage. Direct Sales is gaining share fastest as institutional buyers seek traceability assurances.
End User:
Customer maturity separates price-sensitive smallholders from premium-seeking organic operators willing to absorb higher per-unit phosphate costs for certification compliance.
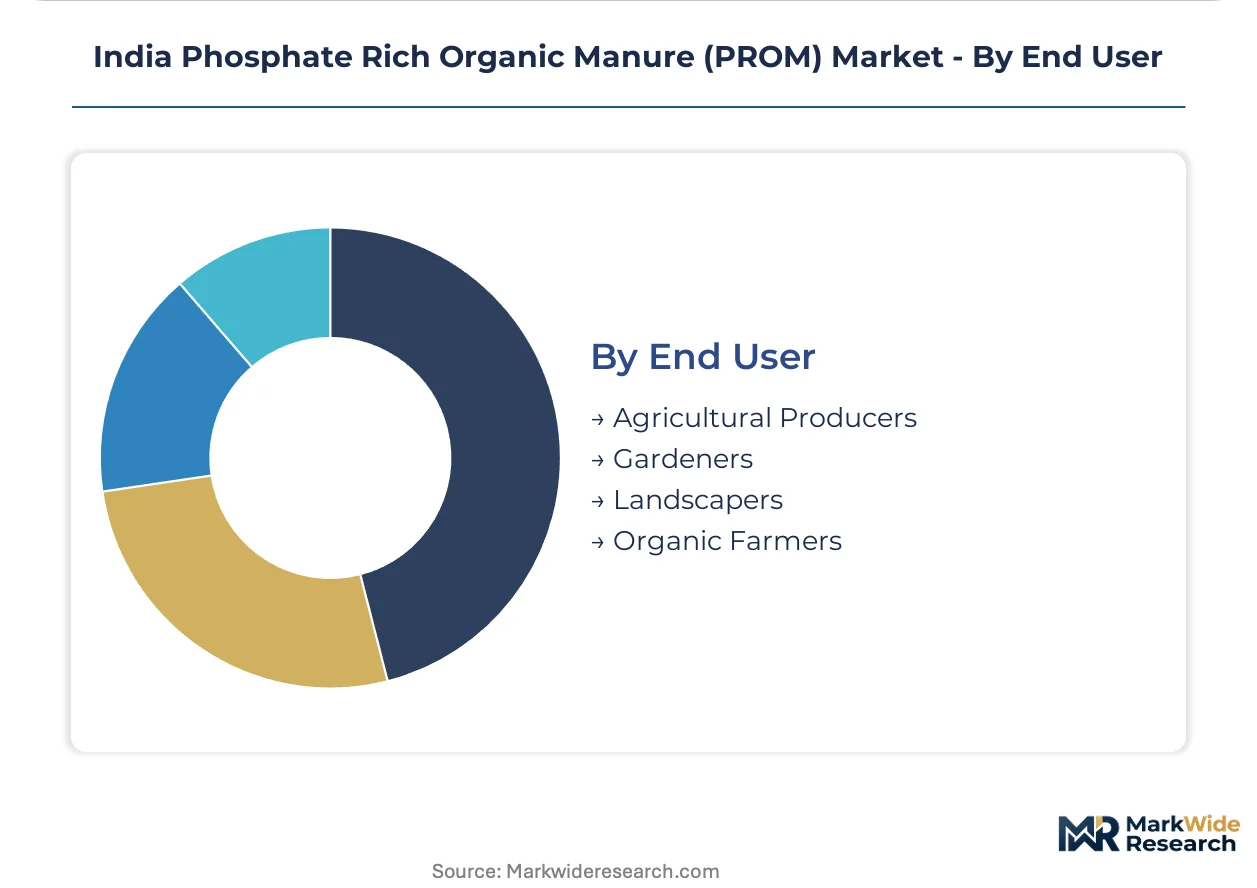
- Agricultural Producers:Commercial farming operations above ten hectares managing phosphate budgets across multiple crop cycles. Punjab's mechanized wheat farmers represent the core conversion demographic as Fertilizer Control Order enforcement tightens.
- Organic Farmers:Certified organic operations prohibited from synthetic phosphate inputs, creating captive demand for citrate-soluble organic alternatives regardless of price premium.
- Gardeners:Urban and peri-urban household cultivators purchasing small-format retail packs for kitchen gardens and terrace farming.
- Landscapers:Commercial turf and ornamental maintenance contractors with specification-driven procurement tied to municipal and corporate contracts.
Agricultural Producers dominate volume absorption. Organic Farmers are climbing the fastest as state mission subsidies expand eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Punjab and Haryana favor granular PROM for mechanical broadcasting compatibility, while Maharashtra and Gujarat growers increasingly specify liquid formulations for fertigation integration. This format divergence shapes supplier product mix and distribution investments across state boundaries.
Punjab
Wheat-paddy rotation farmers dominate PROM absorption here, driven by Fertilizer Control Order enforcement that tightens chemical-phosphate limits. The state's agricultural department routes subsidized procurement through wholesale channels. Ludhiana and Amritsar districts exhibit the steepest conversion curves as cooperatives enforce BIS certification requirements.
Haryana
Mechanized farming operations above ten hectares anchor demand for plug-and-play granular alternatives to DAP. State organic farming missions recalibrate subsidy eligibility toward certified organic phosphate sources. Hisar and Karnal clusters concentrate dealer network consolidation around multi-product agri-input chains.
Maharashtra
Sugarcane cooperatives command the dominant procurement volume, with acute soil phosphorus fixation in alkaline-calcareous soils driving repeated organic amendment. The Fertilizer Control Order's 2024 QR-code traceability mandates reshape payment release protocols. Kolhapur and Solapur belts demand batch-specific test certificates before procurement.
Gujarat
Peri-urban vegetable clusters near Ahmedabad and Surat convert fastest under export market organic certification pressure. Horticulture operators negotiate liquid PROM supply contracts directly with formulation specialists. Anand and Vadodara sub-regions lead channel disintermediation as progressive farmers bypass wholesale distributors.
Karnataka
Protected cultivation operators in greenhouse belts adopt liquid formulations for precision drip integration. PLI scheme capital subsidies lower entry barriers for automated composting infrastructure investments. Bengaluru Rural and Kolar districts concentrate premium pricing corridors for fertigation-compatible products.
India Phosphate Rich Organic Manure (PROM) Market Competitive Landscape
Capability concentration sits with integrated manufacturers possessing captive rock-phosphate linkages; scale advantage sits with state-backed entities with subsidized procurement channel access. The market structures around three tiers: fertilizer majors with mining backward integration, agro-industrial conglomerates with distribution density, and specialized biofertilizer firms with microbial formulation expertise. Dominant competitive moves include automated composting infrastructure deployment and direct-to-farm contract negotiation that bypasses traditional wholesale margins.
Within the integrated manufacturer tier, National Fertilizers Limited anchors positions through Rajasthan mine linkages, while Coromandel International occupies extensive rural dealer network density across southern states. Godrej Agrovet represents the agro-industrial conglomerate archetype with diversified input portfolios. These three exemplify how captive feedstock control, distribution infrastructure, or multi-product bundling create defensible positioning against price-competitive DAP alternatives.
| Leading Market Players |
|---|
| National Fertilizers Limited |
| Godrej Agrovet Limited |
| Gujarat State Fertilizers & Chemicals Limited |
| Nextnode BioScience Pvt. Ltd. |
| Deepak Fertilisers & Petrochemicals Corporation Limited |
| Chambal Fertilizers and Chemicals Limited |
| Biogen Fertilizers India Private Limited |
| Agri India Biotech |
| Coromandel International Limited |
| Others |
Pricing and Supply Chain Analysis
Rajasthan's captive rock-phosphate mines concentrate upstream feedstock control among three integrated manufacturers, compressing margin pools for non-integrated compounders in eastern and southern states who must absorb transport premiums or accept thinner spreads.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement, with state agricultural departments locking annual volumes at fixed citrate-soluble phosphate specifications. Price differentiation hinges on BIS certification tier and bundled agronomic advisory intensity. Cost compression in the wholesale channel is intensifying because subsidized DAP retains price advantage in government schemes. Smallholders in Bihar and Uttar Pradesh exhibit highest price sensitivity, while organic export-oriented cooperatives in Gujarat absorb premium liquid formulations.
Supply Chain Analysis
Export-control regimes on phosphate rock concentrate limit raw material flows from Morocco and Western Sahara, though India's domestic Rajasthan deposits insulate against complete supply disruption. The network draws from low-grade rock phosphate, farm waste press mud, and specialized microbial inoculants. Single-source vulnerability concentrates in Rajasthan's Jhamarkotra mine complex for non-integrated producers. Distribution runs through state agricultural department wholesale channels, with direct-to-farm contracting gaining share among large cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microbial inoculation expertise for co-composting low-grade rock phosphate remains scarce among agronomy graduates, creating a bottleneck that constrains quality-consistent output expansion regardless of capital availability.
For Market Incumbents: Insulate margin pools by deepening captive rock-phosphate linkages through Rajasthan mine lease extensions or backward integration into automated composting infrastructure. Defend against channel disintermediation by embedding soil-testing laboratories within dealer networks to capture advisory revenue streams that standalone agronomists are losing. For New Entrants and Emerging Players: Pursue protected cultivation clusters in Karnataka and Telangana where liquid PROM fertigation demand outpaces specialized formulation supply. The greenhouse operator segment remains penetrable due to incumbent focus on granular bulk volumes. Establish direct technical service teams for drip calibration support rather than competing through wholesale subsidy channels. For Investors and Strategic Acquirers: Capital is best deployed toward integrated manufacturers with demonstrated BIS certification consistency and in-house laboratory infrastructure capable of batch-specific test certificate generation. Long-term viability across the analysis window rests on regulatory digitization readiness, specifically QR-code traceability compliance. Watch state organic farming mission subsidy recalibration timing as the inflection signal for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Rock-Phosphate Mining | Rajasthan mine linkages secure feedstock cost advantage against volatile import parity. |
| Automated Composting Infrastructure Deployment | Temperature and moisture control systems standardize citrate-soluble phosphate availability for BIS compliance. |
| Liquid Formulation Development for Fertigation | Precision drip compatibility opens premium pricing corridors in Karnataka greenhouse belts. |
| Direct-to-Farm Contract Negotiation | Bypassing wholesale distributor margins captures value from traceability-demanding cooperatives. |
| In-House Soil-Testing Laboratory Investment | Batch-specific certification capability satisfies Maharashtra sugarcane cooperative procurement protocols. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with PROM plant managers, state agricultural department procurement officers, sugarcane cooperative input committees, and microbial inoculation specialists; alongside secondary validation through Fertilizer Control Order amendments, BIS certification registries, PLI scheme disbursement records, and Rajasthan mining lease disclosures. Bottom-up volume modeling triangulated against top-down value estimates from wholesale channel procurement data.
Forecast inputs considered product format splits, application crop categories, distribution channel evolution, and end-user conversion trajectories across the projection horizon. CAGRs derived from segment-level growth rate compounding weighted by base-year value shares. Industry-specific inputs included Fertilizer Control Order enforcement timelines, state organic farming mission subsidy allocation patterns, and protected cultivation acreage expansion curves.
Sensitivities concentrate around DAP subsidy parity adjustments and BIS certification timeline compression. Forecasts reflect assumptions on regulatory digitization adoption rates and microbial inoculation technology transfer efficiency. Material shifts in Fertilizer Control Order phosphate availability thresholds or Rajasthan mining output constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
North America Feed Antibiotics Market
Agricultural Chemicals
Field Marking Paint Market
Agricultural Chemicals
Feed Antioxidants Market
Agricultural Chemicals
Auxin Substitutes Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
South America Feed Enzymes Market
Agricultural Chemicals
Global Dinotefuran Market
Agricultural Chemicals
South America Feed Acidifiers Market
Agricultural Chemicals
Stored Grain Insecticides Market
Agricultural Chemicals
Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Europe Feed Antibiotics Market
Agricultural Chemicals
Asia-Pacific Feed Binders Market
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
South America Feed Antioxidants Market
Agricultural Chemicals
Poultry Premix Market