
 United States Fertilizers Market | 2026-2036
United States Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
United States Fertilizers Market Analytics
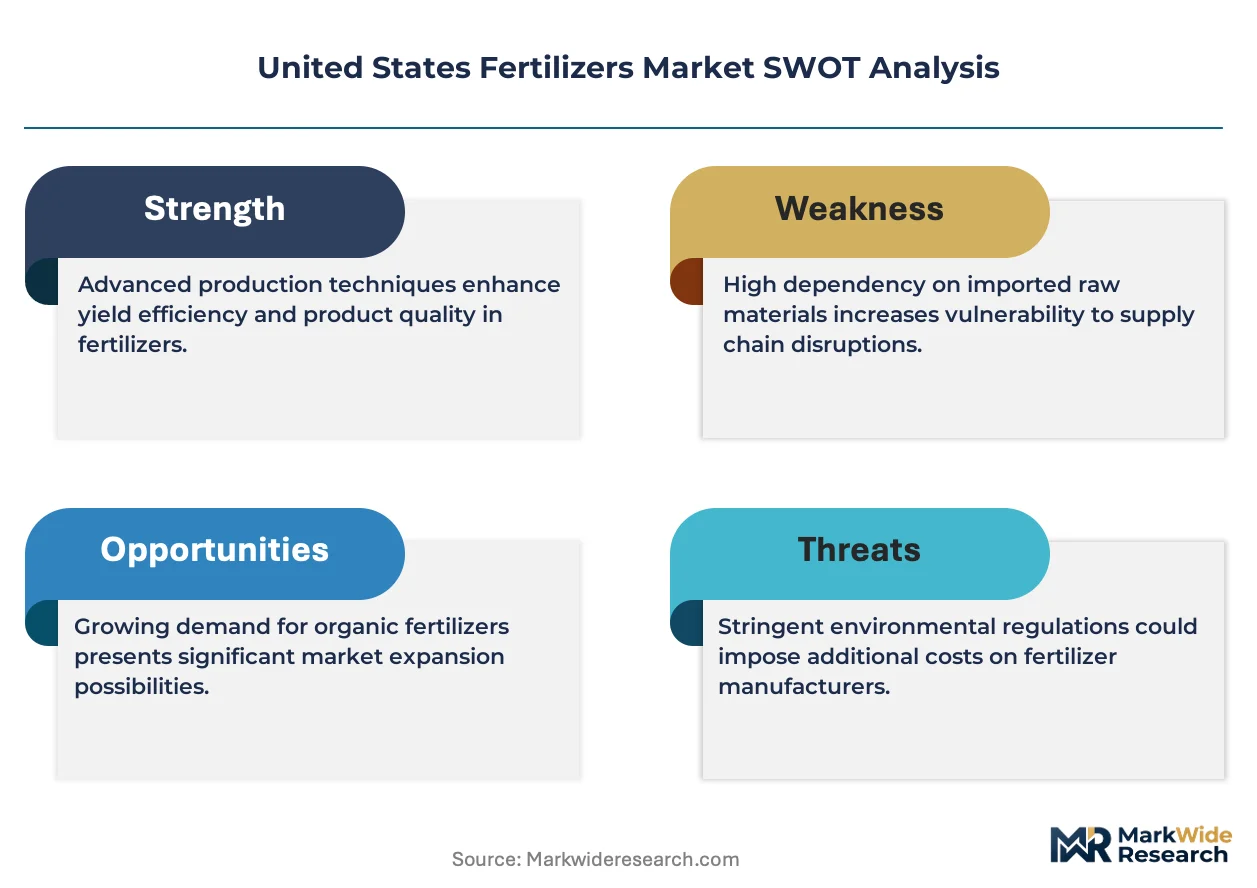
The EPA's revised Waters of the United States rule is decoupling fertilizer demand from volume-based application models, pushing agricultural producers toward variable-rate technologies and enhanced-efficiency formulations. CF Industries Holdings, Inc. leverages its Gulf Coast ammonia network to sustain cost-advantaged nitrogen supply to Midwestern corn growers. Nutrien Ltd. anchors its position through integrated potash mining and retail distribution, while The Mosaic Company dominates phosphatic fertilizer production from Florida phosphate reserves.
Fertilizers encompass nitrogenous, phosphatic, potassic, and compound formulations engineered to deliver essential macronutrients—nitrogen, phosphorus, and potassium—in plant-available forms through granular, liquid, or gaseous application. Manufacturing processes include Haber-Bosch ammonia synthesis, phosphate rock acidulation, and potash solution mining, with formulations specified by N-P-K analysis ratios tailored to soil test recommendations and crop removal rates. Nitrogenous products command the largest revenue share due to corn's intensive demand and urea's transport economics, while compound fertilizers capture margin expansion through customized blends that reduce application passes. The horticultural end-user segment represents the fastest structural growth as controlled-environment agriculture and specialty crop acreage expand.
The USDA's Natural Resources Conservation Service administers cost-share programs for nutrient management planning, while state-level Departments of Agriculture in Iowa and Illinois enforce phosphorus index protocols that restrict fall application timing. The Clean Water Act's total maximum daily load frameworks in Chesapeake Bay and Mississippi River watersheds impose downstream accountability on upstream fertilizer retailers. Stakeholders must monitor evolving state fertilizer use restrictions and precision agriculture subsidy thresholds to align product portfolios with compliance-driven purchasing behavior.
Market Dynamics
Precision agriculture adoption is decoupling fertilizer demand from acreage expansion, forcing suppliers to align product portfolios with variable-rate application technologies and 4R nutrient stewardship protocols across the Corn Belt.
Growth Catalysts
- USDA Environmental Quality Incentives Program:Cost-share funding for nutrient management planning accelerates adoption of soil testing and split nitrogen application among Midwestern corn-soybean operations.
- Controlled-release urea formulations:Polymer-coated products reduce volatilization losses and extend nitrogen availability, satisfying EPA nonpoint source pollution guidelines while cutting application passes.
- Farm consolidation in Iowa and Illinois:Larger operational footprints generate procurement scale that favors bulk liquid nitrogen systems and custom-blended compound fertilizers.
Market Restraints
- Natural gas price volatility:Ammonia synthesis consumes 70-90% of production costs, exposing nitrogen margins to Gulf Coast Henry Hub fluctuations and international LNG arbitrage.
- Phosphate rock import dependence:Florida reserves face depletion pressure while Morocco and Russia control 70% of global mineable ore, concentrating supply risk with geopolitical chokepoints.
- Fall phosphorus application bans:Iowa's Phosphorus Index and Illinois' nutrient loss reduction strategy restrict timing windows, compressing seasonal demand concentration and inventory turns.
Strategic Opportunities
- Nebraska's expanding irrigated corn acreage:Center-pivot systems enable fertigation integration, creating pull for liquid UAN and micronutrient blends in the Platte River Valley.
- Biostimulant-fertilizer convergence:Microbial inoculants paired with starter fertilizers promise yield uplift and carbon credit eligibility under developing soil health protocols.
- Retail channel digitization:Agronomy platforms connecting soil data to prescription fulfillment are capturing input procurement decisions from traditional cooperative relationships.
Industry Challenges
- Certified crop adviser shortage:Nutrient management planning complexity exceeds available agronomic talent, delaying 4R implementation and compliance documentation.
- Legacy equipment retrofit costs:Variable-rate application requires planter and spreader upgrades that strain capital allocation for mid-scale operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Fertilizers Market |
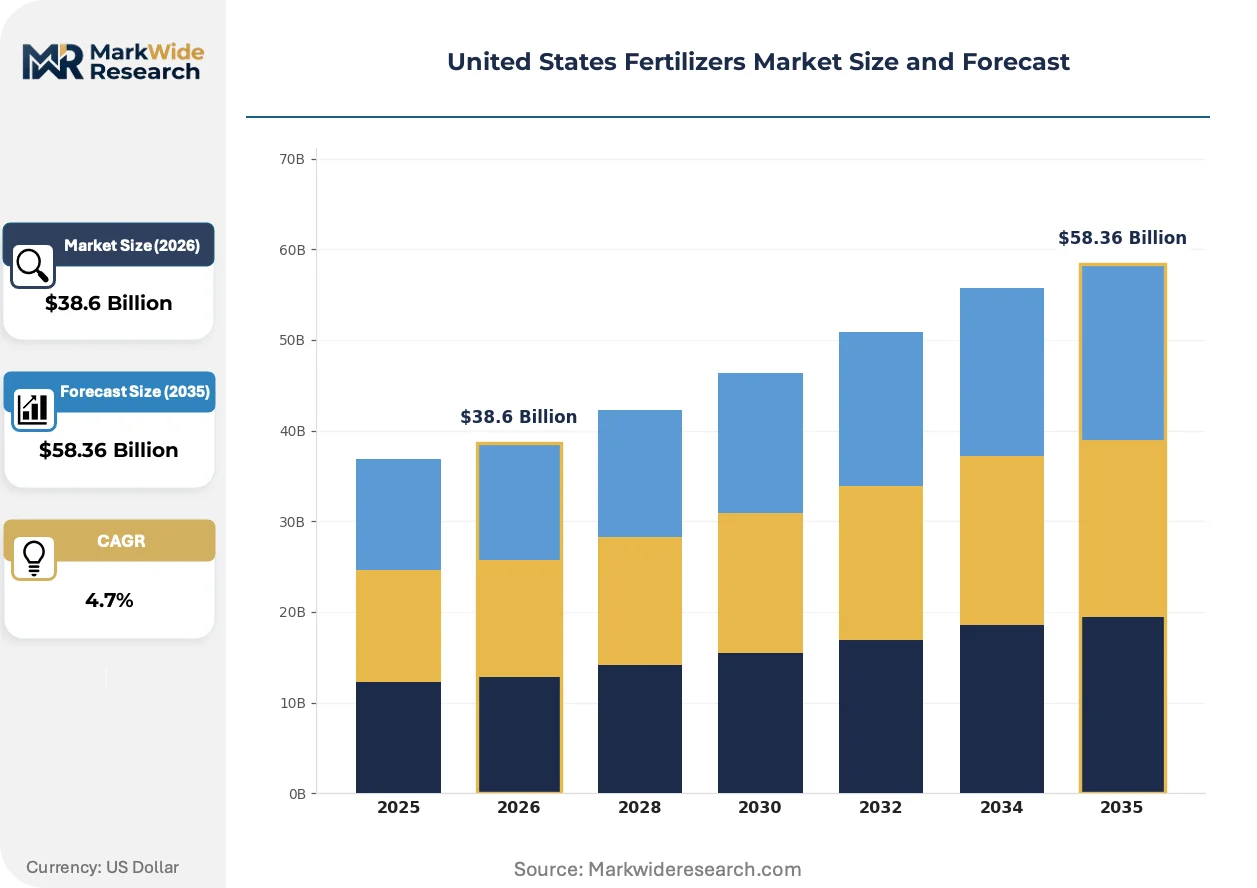
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.36 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogenous, Phosphatic, Potassic, Compound End User: Agricultural Producers, Lawn Care, Horticultural, Turf Management Application: Crops, Gardens, Lawns, Greenhouses Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | CF Industries Holdings, Inc., Nutrien Ltd., The Mosaic Company, The Andersons Inc., Yara International ASA, ICL Group Ltd, Koch Industries Inc., Wilbur-Ellis Company LLC, Helena Agri-Enterprises, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Fertilizers Market Evolving Landscape
Digital agronomy platforms are compressing the information loop between soil sensing, prescription generation, and product fulfillment, reshaping how fertilizer value migrates from commodity tonnage to outcome-based recommendations.
Variable-rate application technology is unifying spatial soil data with real-time equipment control, enabling sub-field nitrogen prescriptions that match input placement to yield potential zones. Corn growers exceeding 2,000 acres are retrofitting planters with pneumatic delivery systems and section control at replacement rates exceeding 15% annually. This capability is compressing the addressable market for uniform-blend products while expanding margin capture for customized fertility programs.
EPA's revised Waters of the United States rule is tightening nutrient runoff accountability across 22 states in the Mississippi River watershed, triggering state-level phosphorus reduction frameworks and fall application moratoria. Fertilizer retailers in Iowa, Illinois, and Minnesota now face downstream liability linkages that elevate documentation requirements for product placement and timing. Enhanced-efficiency formulations capturing nitrogen in root zones are capturing preferential placement in nutrient management plans submitted for USDA cost-share eligibility.
Procurement centralization among farm management companies and investment-backed aggregators is displacing decentralized cooperative purchasing, concentrating annual contract negotiations with fewer decision-makers controlling larger volume blocks. These professionalized buyers demand outcome guarantees and application services bundling that commoditize standalone product supply. The shift is most visible in the I-80 corridor from Des Moines to Chicago, where 10,000-acre-plus operations now direct 40% of regional nitrogen volume through direct manufacturer relationships.
United States Fertilizers Market Segmentation
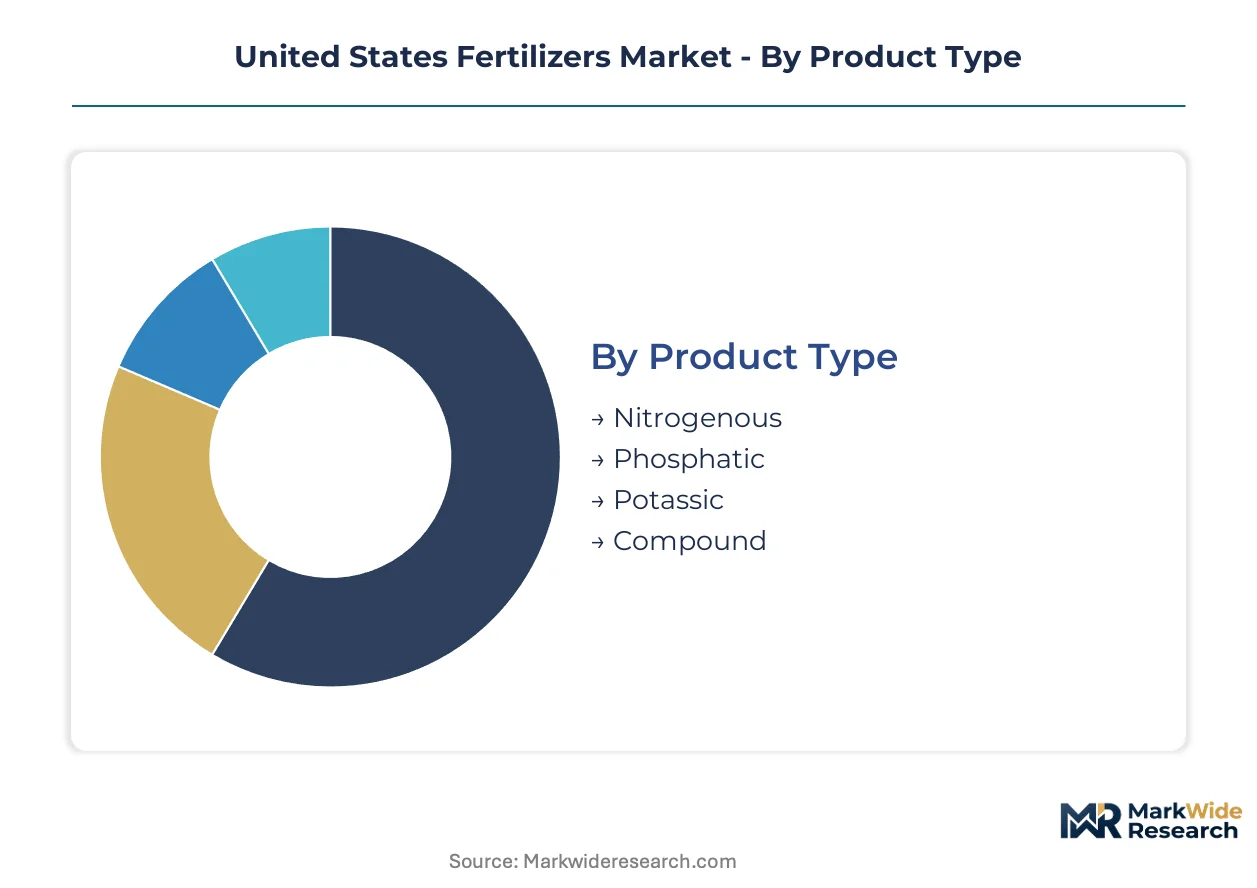
Segmentation in the United States Fertilizers Market reveals how product chemistry, end-use intensity, and channel control interact to determine margin capture. Corn Belt procurement patterns diverge sharply from specialty turf and greenhouse applications, requiring suppliers to align formulation portfolios with distinct agronomic and logistical requirements.
Product Type:
Formulation chemistry dictates manufacturing input costs, transport economics, and application timing flexibility across Midwestern corn-soybean systems and specialty crop zones.
- Nitrogenous:Urea, anhydrous ammonia, and UAN solutions supply corn's primary macronutrient demand through soil injection or surface application. Illinois and Iowa growers favor anhydrous ammonia for pre-plant placement due to cost-per-unit-nitrogen economics and reduced volatilization risk under cooler soil temperatures.
- Phosphatic:Diammonium phosphate and monoammonium phosphate deliver phosphorus in plant-available orthophosphate forms critical for root development and early-season vigor. Florida phosphate reserves anchor domestic production, though Iowa's Phosphorus Index restrictions compress fall application windows and shift demand toward spring starter programs.
- Potassic:Muriate of potash from Saskatchewan solution mining addresses potassium removal rates in high-yield corn systems. Bulk rail delivery to Midwestern terminals supports competitive pricing against imported alternatives.
- Compound:Custom-blended N-P-K formulations reduce application passes and match variable-rate prescriptions to soil test zones. These products gain share among farm management companies consolidating procurement across 5,000-plus-acre footprints.
Nitrogenous formulations lead on scale; compound products lead on momentum.
End User:
Customer scale and agronomic sophistication determine service intensity, pricing power, and loyalty mechanism design across the value chain.
- Agricultural Producers:Corn-soybean operations exceeding 2,000 acres drive 60% of nitrogen volume through direct manufacturer contracts and cooperative purchasing pools. These buyers demand soil testing integration, application services bundling, and compliance documentation for USDA cost-share programs.
- Lawn Care:Professional landscape contractors and municipal turf managers purchase seasonal fertilizer programs with slow-release nitrogen guarantees. Product performance consistency matters more than per-ton pricing in this segment.
- Horticultural:Controlled-environment agriculture and specialty crop producers in California's Central Valley and Florida's winter vegetable belt require micronutrient-fortified formulations and soluble fertigation products. This segment expands most quickly as protected acreage climbs.
- Turf Management:Golf courses and sports field operators specify polymer-coated urea for uniform color response and reduced mowing frequency. Seasonal contract structures lock in supplier relationships ahead of spring demand surges.
Agricultural Producers dominate volume concentration; Horticultural applications show the steepest expansion trajectory.
Application:
Site-specific growing conditions determine formulation selection, timing flexibility, and equipment compatibility requirements.
- Crops:Field corn, soybeans, and wheat account for the majority of fertilizer tonnage, with split nitrogen application and starter phosphorus placement governed by 4R nutrient stewardship protocols. Nebraska's center-pivot irrigated acres enable fertigation integration that pulls liquid UAN through in-season delivery systems.
- Gardens:Home and community gardeners purchase smaller package sizes with organic certification claims and beginner-friendly application instructions. Retail shelf placement and seasonal promotional timing drive purchase decisions.
- Lawns:Residential and commercial turf applications favor weed-and-feed combination products with pre-emergent herbicide pairing. Fall phosphorus restrictions in Chesapeake Bay watershed states limit formulation options and compress marketing windows.
- Greenhouses:Soilless growing media and hydroponic systems require complete soluble fertilizers with balanced micronutrient packages and low electrical conductivity. pH buffering and chelated iron availability separate premium from commodity offerings.
Crop applications anchor revenue scale; greenhouse systems command the highest margin per pound of nutrient delivered.
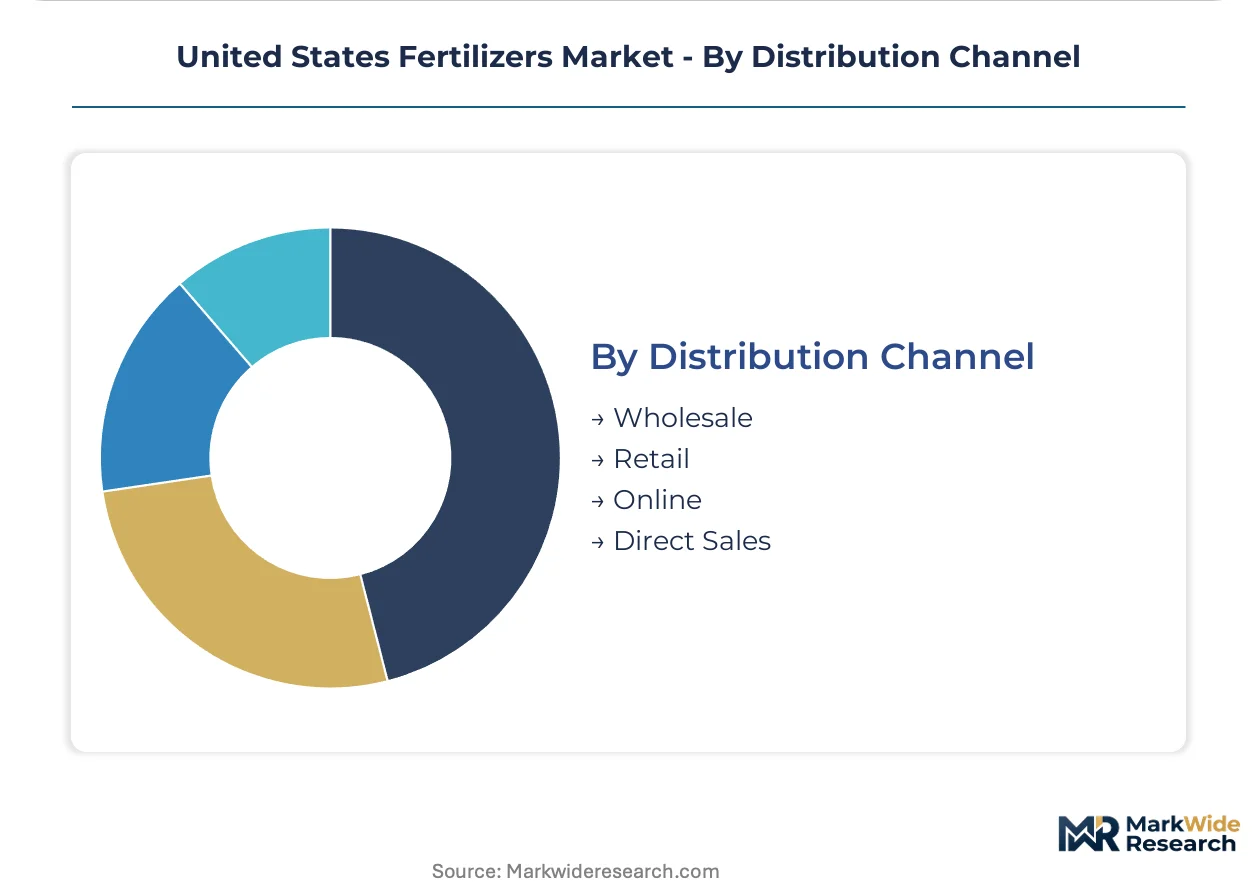
Distribution Channel:
Channel structure determines working capital intensity, customer intimacy depth, and exposure to price transparency pressures.
- Wholesale:Regional distributors aggregate manufacturer volumes for redistribution to independent retail agronomy centers and farm supply cooperatives. Inventory positioning at river terminals and rail hubs enables just-in-time delivery to planting-season demand spikes.
- Retail:Farm supply cooperatives and independent agronomy retailers maintain localized soil testing capabilities, custom application equipment fleets, and certified crop adviser staff. These relationships persist through multi-year input financing arrangements and harvest-price contracts.
- Online:Digital platforms capture hobbyist and small-acreage demand with subscription replenishment models and educational content integration. Price transparency pressures traditional channel markups on commodity formulations.
- Direct Sales:Major manufacturers bypass distribution layers to contract directly with farm management companies and investment-backed aggregators controlling 10,000-plus-acre operations. These agreements bundle product supply with agronomic advisory and application services.
Retail channels retain the deepest customer relationships; direct sales capture the fastest volume migration among professionalized buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Farm consolidation and precision agriculture talent pools concentrate fertilizer procurement decisions across distinct US agricultural zones, with state-level environmental regulations reshaping application timing and formulation preferences.
Illinois
Corn-soybean operations exceeding 5,000 acres dominate nitrogen volume through direct manufacturer contracts and cooperative purchasing pools. The Illinois Nutrient Loss Reduction Strategy enforces phosphorus index protocols that restrict fall application windows. The I-80 corridor from Des Moines to Chicago anchors procurement centralization, where farm management companies control 40% of regional nitrogen volume through bundled agronomic services.
Iowa
Deep, fertile soils support the nation's highest corn yields per acre, driving intensive nitrogen removal rates and split-application programs. Iowa's Phosphorus Index mandates soil testing and setbacks for fall phosphorus placement near waterways. The Des Moines-Ames corridor concentrates retail agronomy centers with certified crop adviser staff and custom application equipment fleets serving consolidated operations.
Nebraska
Center-pivot irrigation across the Platte River Valley enables fertigation integration, pulling liquid UAN through in-season delivery systems. USDA's Environmental Quality Incentives Program cost-shares nutrient management planning for split nitrogen application. The tri-cities region of Grand Island, Kearney, and Hastings anchors bulk liquid terminal infrastructure for just-in-time delivery to irrigated corn acres.
Minnesota
Red River Valley sugar beet and spring wheat rotations demand specialized potassium and micronutrient formulations. The state's buffer strip law and revised Waters of the United States implementation impose downstream liability on fertilizer retailers for nutrient placement documentation. The Minneapolis-St. Paul metro anchors wholesale distribution terminals redirecting Saskatchewan potash rail shipments to Upper Midwest farm supply cooperatives.
Indiana
White River and Wabash River watersheds face Chesapeake Bay and Mississippi River total maximum daily load frameworks, elevating compliance documentation for retailers. The Purdue University agronomy corridor around Lafayette concentrates precision agriculture research and certified crop adviser training programs. Eastern corn belt operations here adopt variable-rate technologies at rates exceeding the national average for mid-scale farms.
United States Fertilizers Market Competitive Landscape
Capital-heavy ammonia producers compete with asset-light retail distributors and agronomy service providers for margin capture across the fertilizer value chain. The market structures around three tiers: integrated nitrogen manufacturers with Gulf Coast production assets, potash miners with Saskatchewan solution operations, and regional retailers with localized soil testing and application equipment. Consolidation accelerates through farm management company procurement centralization and cooperative merger activity. Competitive positioning depends on backward integration into natural gas or phosphate rock, and forward integration into prescription agronomy platforms.
Among integrated nitrogen producers, CF Industries Holdings, Inc. and Koch Industries Inc. anchor cost-advantaged supply positions through Gulf Coast ammonia network access. Nutrien Ltd. and The Mosaic Company exemplify divergent integration models—potash mining and phosphatic fertilizer production respectively—each leveraging captive mineral reserves against raw material volatility. These four entities represent the capital-intensive foundation of domestic fertilizer supply, with their infrastructure positions shaping regional pricing and availability patterns across the Corn Belt.
| Leading Market Players |
|---|
| CF Industries Holdings, Inc. |
| Nutrien Ltd. |
| The Mosaic Company |
| The Andersons Inc. |
| Yara International ASA |
| ICL Group Ltd |
| Koch Industries Inc. |
| Wilbur-Ellis Company LLC |
| Helena Agri-Enterprises |
| Others |
Value Network & Pricing Analysis
Procurement centralization among farm management companies and investment-backed aggregators is compressing supplier margins and forcing nitrogen manufacturers to bundle application services with commodity tonnage. This shift toward outcome-based contracting erodes standalone product pricing power while rewarding backward-integrated players with captive supply networks.
Pricing Analysis
Bundled agronomic services versus unbundled commodity supply defines the pricing architecture across the Corn Belt. Three-tier pricing structure across premium enhanced-efficiency formulations, standard granular products, and economy bulk urea reflects certification tiers for 4R nutrient stewardship compliance and volume scale from 10,000-acre operations. Cost compression in standard nitrogen grades is intensifying because procurement centralization concentrates annual contract negotiations with fewer professionalized buyers. Agricultural producers exceeding 5,000 acres exhibit lowest price sensitivity due to yield-guarantee contracts, while mid-scale operations below 1,000 acres remain most responsive to per-ton differentials.
Supply Chain Analysis
Natural gas feedstock draws from Gulf Coast Henry Hub pricing, Canadian AECO benchmarks, and international LNG arbitrage to determine ammonia production economics. Phosphate rock concentrates in Florida's Bone Valley deposits, Saskatchewan potash solution mines, and Moroccan export terminals controlled by OCP Group. Single-source vulnerability runs through Florida phosphate reserve depletion and concentrated Moroccan-Russian ore control. Distribution runs through river terminal aggregation at St. Louis and Minneapolis, rail shipment to Midwestern farm supply cooperatives, and direct manufacturer pipelines to consolidated operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Gulf Coast ammonia production with access to cheap domestic natural gas and nitrogen import dependence on volatile international LNG markets.
For Market Incumbents: Cement cost-advantaged supply positions by deepening backward integration into natural gas transportation infrastructure and expanding prescription agronomy platform capabilities. The certified crop adviser shortage threatens service bundling margins, making captive agronomic talent acquisition a critical defensive lever. Capacity positioning near Nebraska's Platte River Valley liquid terminals captures irrigated corn acreage expansion. For New Entrants and Emerging Players: EPA's revised Waters of the United States rule in Mississippi River watershed states opens a window for enhanced-efficiency formulation specialists with nitrogen-stabilizer technology and compliance documentation capabilities. White-space targets include biostimulant-fertilizer convergence for carbon credit eligibility and digital agronomy platforms connecting soil data to prescription fulfillment. The horticultural controlled-environment agriculture segment offers lowest incumbent saturation and highest margin per pound of nutrient delivered. For Investors and Strategic Acquirers: Asymmetric upside sits with regional retailers possessing localized soil testing infrastructure and certified crop adviser staff in Iowa and Illinois consolidation corridors. Long-term viability hinges on prescription agronomy service revenue streams displacing commodity tonnage dependency. Watch Nebraska center-pivot irrigated acreage expansion as inflection indicator for liquid UAN demand pull through fertigation integration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Gas Transport | Captive feedstock supply insulates nitrogen margins from Henry Hub volatility and LNG arbitrage. |
| Prescription Agronomy Platform Development | Digital soil-data-to-fulfillment loops capture procurement decisions from traditional cooperative relationships. |
| Enhanced-Efficiency Formulation Expansion | Polymer-coated and stabilized nitrogen products satisfy EPA nonpoint source pollution guidelines for cost-share eligibility. |
| Regional Retail Agronomy Acquisition | Localized certified crop adviser staff and application equipment fleets defend channel control against manufacturer direct sales. |
| Biostimulant-Fertilizer Convergence R&D | Microbial inoculant pairing with starter fertilizers unlocks yield uplift claims and emerging soil health carbon credit protocols. |
Research Methodology
Multiple input streams — executive interviews with nitrogen manufacturer procurement leads, agronomy platform engineers, and farm management company input directors; regulatory filings from EPA and state Departments of Agriculture; and USDA cost-share program disbursement records — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from SEC 10-K disclosures of integrated fertilizer producers, EIA natural gas consumption data, and customs records tracking phosphate rock import flows. Primary fieldwork encompassed retail cooperative managers and certified crop advisers across the I-80 corridor.
Data-stream reconciliation across product type, end-user scale tier, application method, and distribution channel dimensions anchored the analytical framework across the analysis window. CAGRs derived from historical consumption patterns, corn-soybean rotation acreage projections, and nitrogen removal rate intensities. Industry-specific forecast inputs incorporated EPA regulatory implementation timelines and farm consolidation velocity metrics from agricultural census tract data.
Revisions become necessary when natural gas price volatility exceeds modeled bands, Florida phosphate reserve depletion accelerates, or state-level phosphorus application restrictions expand beyond current Mississippi River watershed boundaries. A small set of named triggers — Henry Hub sustained elevation, Moroccan supply disruption, and 4R nutrient stewardship mandate expansion — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
India Fertilizers Market
Fertilizers
Europe Controlled Release Fertilizer Market
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
China Fertilizers Market
Fertilizers
Nitro Compound Fertilizers Market
Fertilizers
Australia Fertilizer Market
Fertilizers
Biochar Fertilizer Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
Fertilizer Bags Market
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
Global NPK Fertilizer Market
Fertilizers
Diammonium Hydrogen Phosphate (DAP) Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Global Fertilizers Market
Fertilizers
Asia-Pacific Specialty Fertilizer Market
Fertilizers
China Micronutrient Fertilizer Market