
 Asia-Pacific Micronutrient Fertilizer Market | 2026-2036
Asia-Pacific Micronutrient Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Micronutrient Fertilizer Market Outlook
Precision chelation technology is rewriting how micronutrient fertilizers achieve bioavailability in alkaline soils common across South Asia. ICL Group Ltd. leverages its Dead Sea bromine expertise to dominate specialty boron formulations for high-value horticulture. Yara International ASA anchors its position through controlled-release coating systems that reduce leaching losses in monsoon agriculture. Coromandel International Limited competes on deep distribution into India's southern state cooperative networks.
Micronutrient fertilizers are inorganic or organic compounds containing essential trace elements—zinc, iron, boron, copper, manganese, molybdenum, chlorine, and nickel—typically applied at concentrations below one kilogram per hectare to correct soil deficiencies and optimize enzymatic functions in plant metabolism. Zinc deficiency affects nearly half of India's arable soils, making zinc fertilizers the largest product category by volume, while boron formulations command premium margins in horticultural crops where flower and fruit abortion risks drive grower willingness to pay. Liquid formulations are gaining fastest in drip-irrigated vegetable systems across Australia's Murray-Darling Basin and China's Shandong Province, though granular products still sustain the bulk of broadcast application in smallholder rice-wheat rotations.
India's Fertilizer Control Order mandates micronutrient content labeling and quality certification through state agricultural departments, while Australia's APVMA regulates product efficacy claims under its agrochemical registration framework. China's Ministry of Agriculture and Rural Affairs has tightened heavy metal contamination limits in micronutrient products, forcing reformulation of several legacy mineral sources. Stakeholders must monitor how India's PLI scheme and China's green agriculture campaigns reshape the competitive cost structure for domestic versus imported micronutrient sources.
Market Dynamics
India's PLI scheme for agrochemical manufacturing is compressing the cost gap between domestic and imported chelated micronutrient sources, forcing regional supply chain reconfiguration across South and Southeast Asia.
Growth Catalysts
- Soil Zinc Deficiency Spread:Nearly half of India's arable land now shows critical zinc depletion, compelling wheat and rice growers across the Indo-Gangetic Plain to adopt corrective micronutrient protocols.
- PLI Scheme Subsidies:India's production-linked incentive framework for agrochemical manufacturing is accelerating capital deployment into domestic chelation facilities and reducing import dependency.
- Precision Farming Cooperatives:Western and southern Indian states are embedding micronutrient dosing into standard crop management through cooperative-led extension services.
Market Restraints
- Dead Sea Bromine Concentration:Specialty boron formulation supply concentrates around ICL Group's Dead Sea extraction operations, creating single-source vulnerability for premium horticulture inputs.
- Heavy Metal Contamination Limits:China's Ministry of Agriculture and Rural Affairs tightened purity standards, forcing costly reformulation of legacy mineral sulfate sources.
- Monsoon Leaching Losses:High rainfall intensity across Bangladesh and Myanmar rice systems degrades micronutrient retention, elevating application frequency and total cost of ownership.
Strategic Opportunities
- Vietnam Horticulture Expansion:Mekong Delta dragon fruit and mango export zones present underpenetrated demand for boron and zinc fertigation systems.
- Drip Irrigation Convergence:Liquid micronutrient integration with Australia's Murray-Darling Basin precision water systems opens premium formulation channels.
- State Cooperative Distribution:India's southern state agricultural department networks offer embedded access to smallholder rice-wheat rotations without traditional retail markup.
Industry Challenges
- Chelate Chemistry Talent Scarcity:Formulation chemists with expertise in EDTA and EDDHA stability under alkaline soil conditions command premium compensation and limited availability.
- APVMA Registration Timelines:Australia's agrochemical efficacy verification process extends 18-24 months for novel micronutrient claims, delaying product launch cycles.
- Legacy System Integration:Smallholder cooperatives lack digital soil testing infrastructure to support precision micronutrient prescription, forcing reliance on blanket recommendation rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Micronutrient Fertilizer Market |
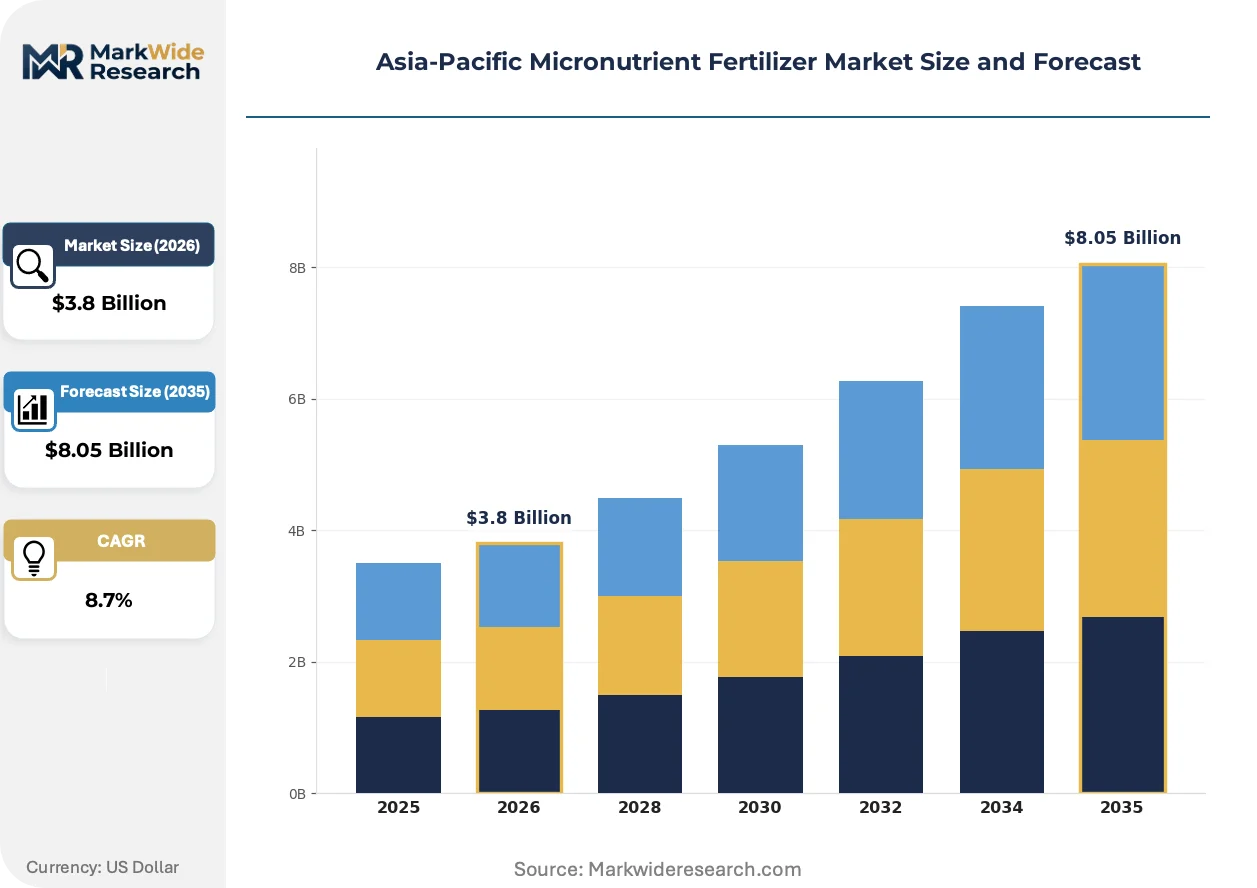
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zinc, Iron, Boron, Copper Application: Agricultural Crops, Horticultural Crops, Turf & Ornamentals, Vegetables Form: Dust, Granules, Liquid, Powder End User: Farmers, Agricultural Cooperatives, Crop Consultants, Research Institutions |
| Companies Covered | Nufarm Limited, ICL Group Ltd., Yara International ASA, Chambal Fertilizers & Chemicals Ltd, Zuari Agro Chemicals Ltd, BASF SE, Nouryon, The Mosaic Company, Coromandel International Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Micronutrient Fertilizer Market Strategic Shifts
Precision delivery mechanisms and regulatory chemistry standards are compressing the viable formulation window for legacy mineral sources across Asia-Pacific agricultural systems.
Controlled-release coating technology is hybridizing conventional granular micronutrients with polymer barrier systems that modulate dissolution across monsoon rainfall patterns. Yara International deploys these systems most aggressively in Bangladesh and eastern India rice rotations. The technology is hybridizing competitive positioning by enabling premium pricing for leaching protection that commodity sulfates cannot match.
China's Ministry of Agriculture and Rural Affairs heavy metal contamination limits are forcing wholesale replacement of mineral sulfate feedstocks with purified oxide and chelate alternatives. Reformulation costs concentrate most severely on legacy zinc and manganese products previously sourced from industrial byproduct streams. Domestic Chinese manufacturers are responding by vertical integration into primary mineral refining.
Cooperative procurement consolidation in India's southern states is displacing independent retailer networks for micronutrient distribution. Precision farming cooperatives in Karnataka and Tamil Nadu now aggregate member demand for direct manufacturer contracting, compressing traditional commission structures. This channel shift is most visible in high-value horticulture zones where volume concentration justifies dedicated logistics investment.
Asia-Pacific Micronutrient Fertilizer Market Segmentation
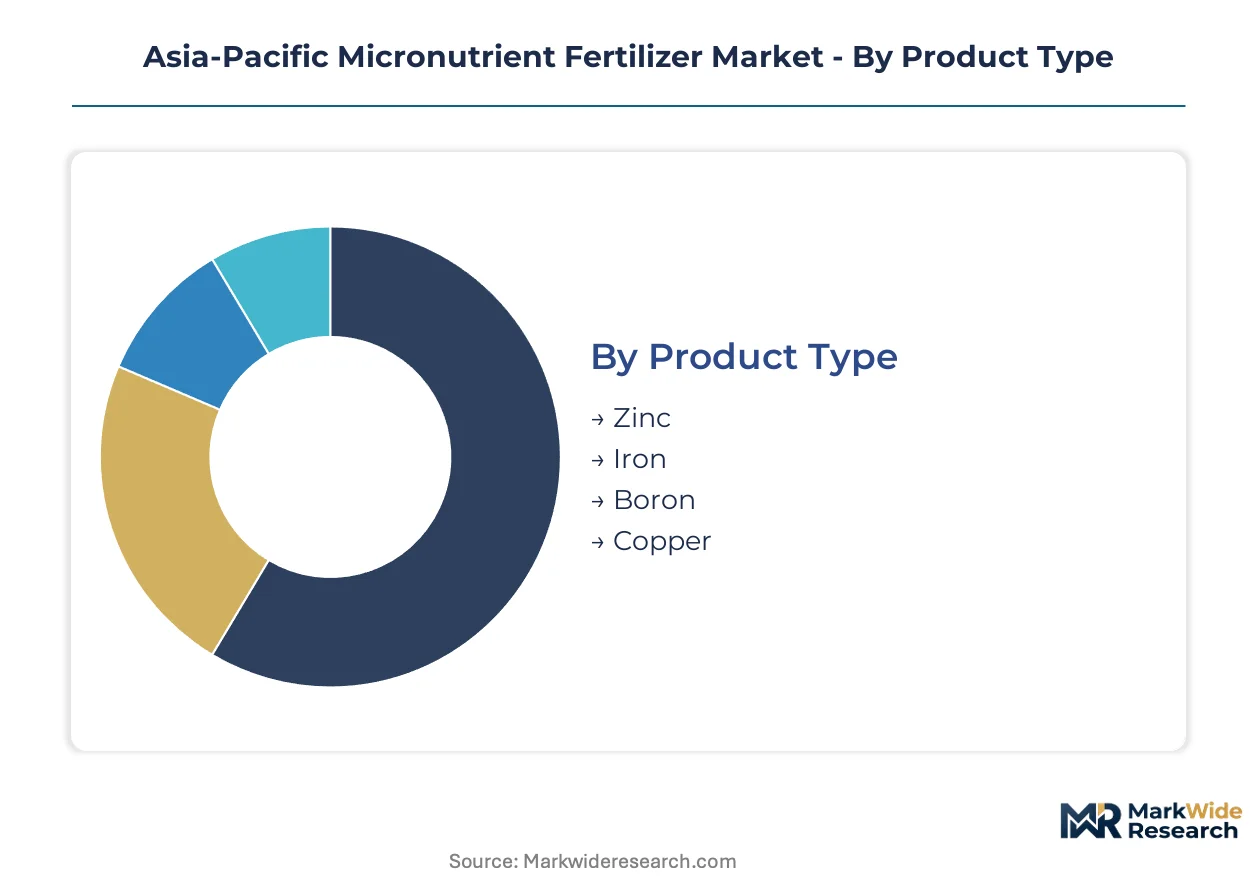
Micronutrient fertilizer demand fragments across crop systems with radically different replenishment cycles—annual vegetables drive rapid inventory turnover while perennial orchards lock in formulation choices for multiple seasons. Understanding these velocity differentials helps suppliers calibrate working capital and technical service deployment across the Asia-Pacific region.
Product Type:
Zinc formulations turn over fastest in the Indo-Gangetic Plain's intensive rice-wheat rotations, while boron products move slowly through high-value horticulture with lower acreage but premium pricing power.
- Zinc:Sulfate and oxide compounds dominate corrective applications for India's depleted alluvial soils. Demand concentrates in Punjab and Haryana wheat systems where PLI-subsidized domestic chelation is displacing imported sources.
- Boron:Soluble borate and complexed formulations command margins three to four times zinc levels in dragon fruit and mango export zones. Vietnam's Mekong Delta expansion is pulling specialty boron volumes faster than any other micronutrient category.
- Iron:EDDHA-chelated sources maintain stability in alkaline paddy soils where ferrous sulfate oxidizes rapidly. Application remains concentrated in southern India's precision farming cooperatives.
- Copper:Sulfate and oxide forms serve defensive protocols in cereal disease management with limited growth trajectory. Usage tracks wheat rust pressure cycles in Pakistan and northern India.
Zinc anchors the volume base while boron gains share at the steepest rate.
Application:
Margin structure inverts between commodity grain rotations and export-oriented horticulture, with the latter absorbing formulation premiums that would collapse demand in food staple systems.
- Agricultural Crops:Rice and wheat dominate tonnage across the Indo-Gangetic Plain with zinc-driven corrective protocols. India's Fertilizer Control Order mandates content labeling that standardizes quality expectations across state agricultural departments.
- Horticultural Crops:Boron and zinc fertigation in Vietnam's dragon fruit belts and Australia's table grape regions commands per-hectare spending multiples above field crops. Flower and fruit abortion risks justify premium chelated sources.
- Turf & Ornamentals:Manganese and iron foliar applications serve golf course and landscape maintenance in Australia's urban corridors. Demand concentrates in Sydney and Melbourne metropolitan procurement.
- Vegetables:Liquid micronutrient integration with drip systems in China's Shandong Province and Australia's Murray-Darling Basin enables precise dosing in high-value tomato and capsicum production.
Agricultural crops sustain the revenue foundation while horticultural applications expand most quickly.
Form:
Physical state determines logistics economics and application equipment compatibility, with liquid formulations requiring specialized handling infrastructure that granular products bypass.
- Liquid:Fully soluble concentrates integrate with fertigation infrastructure in Australia's precision water systems and China's Shandong vegetable belts. Compatibility testing with drip emitters limits supplier qualification.
- Granules:Controlled-release coating systems from Yara International modulate dissolution across Bangladesh monsoon patterns. Broadcasting equipment ubiquity sustains this form's dominance in smallholder rice systems.
- Powder:Fine-ground sulfates serve foliar spray preparation in cooperative mixing stations. Dust exposure and caking resistance constrain formulation stability.
- Dust:Legacy mineral sulfates persist in lowest-cost applications with severe drift and handler exposure limitations. Regulatory pressure is compressing viable use cases.
Granules anchor the volume base while liquid gains share at the steepest rate.
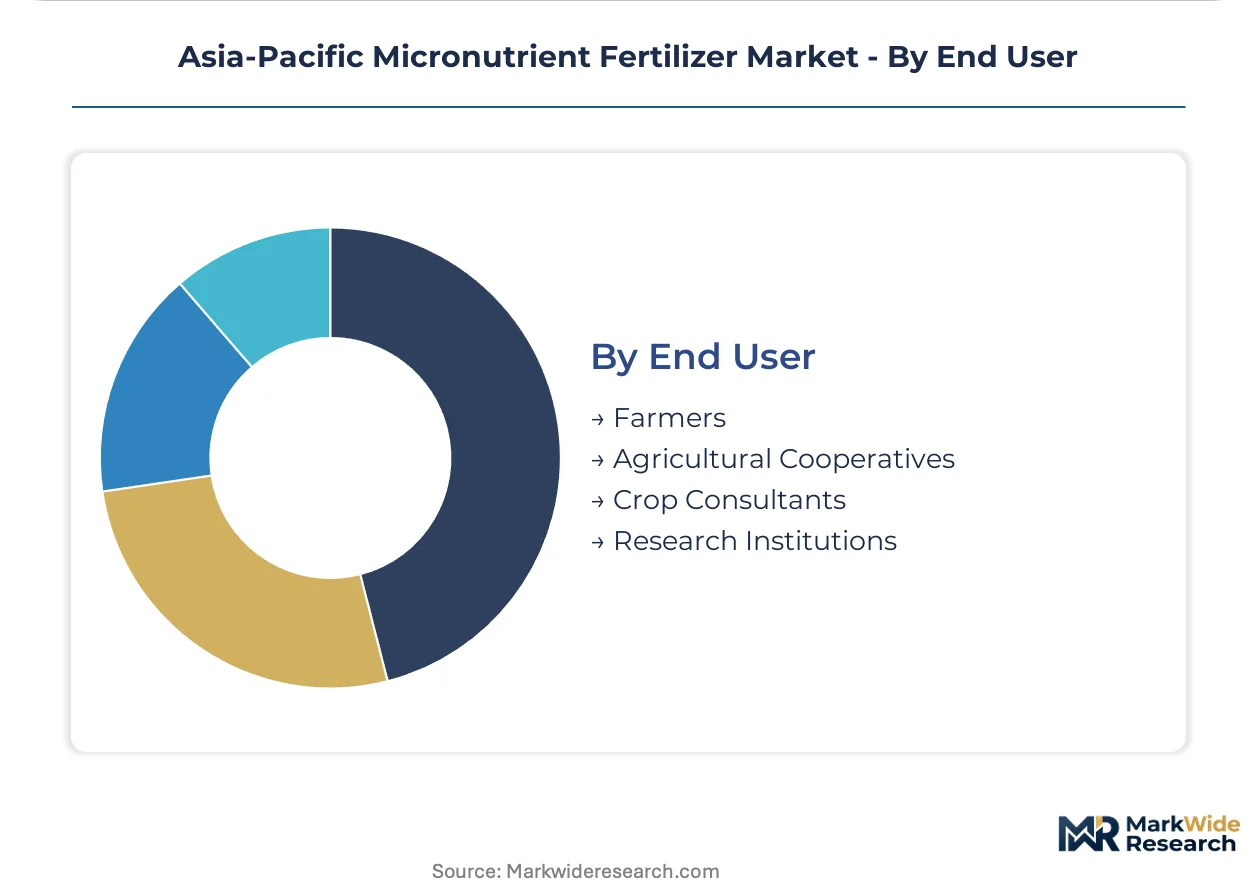
End User:
Procurement authority is shifting from individual farmers toward aggregated entities with technical staff capable of evaluating chelation quality and soil test interpretation.
- Agricultural Cooperatives:Karnataka and Tamil Nadu precision farming groups now aggregate member demand for direct manufacturer contracting. Volume concentration justifies dedicated logistics investment and embedded extension services.
- Farmers:Individual smallholders in India's rice-wheat belt remain price-sensitive purchasers through traditional retailer networks. Digital soil testing penetration is slowly enabling prescription-based purchasing.
- Crop Consultants:Independent agronomists in Australia's high-value horticulture zones specify micronutrient protocols for grower clients. Recommendation authority carries limited procurement control.
- Research Institutions:State agricultural universities and ICAR centers validate efficacy claims and generate extension materials. Regulatory influence exceeds commercial volume.
Farmers anchor the volume base while agricultural cooperatives gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian micronutrient manufacturers export chelated formulations to Vietnam and Bangladesh, capturing demand from rice-intensive deltas where soil zinc depletion drives corrective application protocols.
India
State cooperative networks in Karnataka and Tamil Nadu aggregate smallholder demand for direct manufacturer contracting, bypassing traditional retail markups. The Fertilizer Control Order mandates micronutrient content labeling through state agricultural departments, standardizing quality certification. Punjab and Haryana wheat systems anchor zinc sulfate consumption as PLI-subsidized domestic chelation displaces imported sources.
China
Shandong Province vegetable belts integrate liquid micronutrient concentrates with precision drip irrigation infrastructure. The Ministry of Agriculture and Rural Affairs tightened heavy metal contamination limits, forcing reformulation of legacy mineral sulfate feedstocks. Yangtze River Delta fertilizer manufacturers respond by vertical integration into primary mineral refining to meet purity standards.
Australia
Murray-Darling Basin table grape and tomato operations absorb premium liquid formulations compatible with fertigation emitters. The APVMA regulates micronutrient efficacy claims under agrochemical registration frameworks extending 18-24 months for novel products. Sydney and Melbourne metropolitan corridors concentrate turf and ornamental manganese applications for golf course maintenance.
Vietnam
Mekong Delta dragon fruit and mango export zones pull specialty boron volumes faster than any other micronutrient category. The country's national agricultural regulator monitors heavy metal limits in imported fertilizer formulations. Can Tho and Long An provinces anchor cooperative-led adoption of zinc fertigation systems in intensive horticulture belts.
Bangladesh
Monsoon rice systems degrade micronutrient retention, elevating application frequency and total cost of ownership for smallholders. National fertilizer quality standards align with regional heavy metal protocols. Jessore and Rajshahi districts concentrate Yara International controlled-release coating deployment to modulate dissolution across rainfall patterns.
Asia-Pacific Micronutrient Fertilizer Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent route-to-market strategies. The vendor base clusters around three strategic archetypes: Dead Sea mineral extractors with bromine-derived boron dominance, Scandinavian controlled-release technology licensors, and Indian subcontinent distribution-integrated formulators. Capacity expansion and cooperative procurement consolidation constitute the dominant competitive moves, with state-level aggregation displacing independent retailer networks.
Among Asia-Pacific-based agrochemical formulators, Coromandel International Limited and Zuari Agro Chemicals Ltd occupy positions within the distribution-integrated tier, leveraging southern Indian state cooperative networks for embedded smallholder access. ICL Group Ltd. anchors the specialty mineral extraction archetype through Dead Sea bromine operations. Yara International ASA exemplifies the controlled-release technology vector with monsoon-adapted coating systems. Nufarm Limited and BASF SE represent multinational formulation specialists competing on product registration breadth.
| Leading Market Players |
|---|
| Nufarm Limited |
| ICL Group Ltd. |
| Yara International ASA |
| Chambal Fertilizers & Chemicals Ltd |
| Zuari Agro Chemicals Ltd |
| BASF SE |
| Nouryon |
| The Mosaic Company |
| Coromandel International Limited |
| Others |
Value Chain & Pricing Dynamics
Dead Sea bromine concentration risk determines both the premium spread for specialty boron formulations and the geographic shape of Asia-Pacific micronutrient supply chains. India's PLI scheme for agrochemical manufacturing is compressing domestic-import price differentials while forcing regional feedstock reconfiguration.
Pricing Analysis
Chelated micronutrient formulations command three-to-four-fold premiums over commodity sulfate sources, with EDDHA-stabilized iron and specialty borates anchoring the premium tier against zinc oxide and manganese sulfate economy grades. Price differentiation rests on heavy metal certification tiers mandated by China's Ministry of Agriculture and Rural Affairs and leaching-resistance performance in monsoon conditions. Cost compression in standard-grade zinc sulfate is intensifying because PLI-subsidized Indian domestic production displaces legacy import sources. Smallholder rice-wheat growers in the Indo-Gangetic Plain exhibit highest price sensitivity, while Vietnam's dragon fruit export cooperatives absorb premium chelated boron with minimal elasticity.
Supply Chain Analysis
Tariff exposure between India and ASEAN sourcing corridors dominates supply chain risk calculations for chelated micronutrient distributors. Manufacturing gravity centers on Israel for Dead Sea-derived boron, India for PLI-subsidized zinc chelation facilities, and China for purified oxide feedstocks meeting tightened environmental standards. Formulation chemistry depends on EDTA and EDDHA ligand supplies, primary mineral refining capacity, and polymer coating inputs for controlled-release systems. Single-source vulnerability concentrates around ICL Group's bromine extraction operations. Distribution runs through southern Indian state cooperative networks and Australian APVMA-registered channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat where India's Fertilizer Control Order certification requirements and China's heavy metal limits create structural barriers to formulation substitution.
For Market Incumbents: Insulate market position by securing captive EDDHA ligand supply through backward integration into chelation chemistry, and deepen state cooperative channel control in Karnataka and Tamil Nadu before procurement consolidation completes. Emerging domestic manufacturers threaten margin compression in standard-grade zinc sulfate. Certification investment in China's Ministry of Agriculture and Rural Affairs compliance tiers protects premium positioning. For New Entrants and Emerging Players: Build out technical service capabilities targeting Vietnam's Mekong Delta dragon fruit cooperatives, where boron fertigation penetration remains underdeveloped relative to Indian horticulture belts. Australia's Murray-Darling Basin precision irrigation convergence offers white-space demand for liquid formulation specialists. Direct manufacturer contracting with state agricultural departments bypasses entrenched retailer commission structures. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors distribution-integrated formulators with embedded cooperative access over pure-play technology licensors. Long-term viability hinges on regulatory chemistry capabilities and channel density rather than mineral extraction control. Watch for APVMA registration timeline acceleration as inflection signal for novel product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chelate Chemistry | Captive EDDHA ligand production secures margin protection against specialty chemical volatility. |
| State Cooperative Distribution Partnership | Direct contracting with Karnataka and Tamil Nadu agricultural departments displaces retailer markups. |
| Controlled-Release Coating Scale-Up | Monsoon-adapted polymer barriers command premium pricing in Bangladesh rice systems. |
| Heavy Metal Compliance Certification | China's Ministry of Agriculture and Rural Affairs tiered standards block legacy sulfate competitors. |
| Liquid Formulation Fertigation Integration | Murray-Darling Basin drip system compatibility opens premium channels in Australian horticulture. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, state agricultural department procurement records, and agrochemical registration filings. Interviews with formulation chemists at Indian and Chinese manufacturers, procurement leads at southern Indian farming cooperatives, APVMA regulatory affairs specialists, and technical directors at precision irrigation OEMs informed demand-side validation. Secondary sources include India's Fertilizer Control Order enforcement data, China's Ministry of Agriculture and Rural Affairs contamination limit announcements, and SEC disclosures from listed agrochemical firms. Bottom-up volume modeling triangulates against top-down value estimates across product type, application, and regional segments.
Forecast inputs incorporate chelation technology adoption curves, PLI scheme subsidy phase trajectories, and cooperative procurement consolidation velocity across the projection horizon. Segmentation modeling spans zinc, boron, iron, and manganese product categories; agricultural, horticultural, turf, and vegetable applications; liquid, granular, powder, and dust forms; and farmer, cooperative, consultant, and institutional end users. CAGRs derive from regression against historical penetration rates and scenario-weighted regulatory enforcement intensity. Monsoon variability and drip irrigation infrastructure deployment pace constitute industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by domestic Indian manufacturers or accelerated APVMA registration reform would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
Global Starter Fertilizers Market
Fertilizers
Biological Organic Fertilizers Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Middle East and Africa Micronutrient Fertilizer Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Nitrogen Nutrients Market
Fertilizers
United States Fertilizers Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Europe Micronutrient Fertilizer Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
Nano Fertilizer Market
Fertilizers
China Specialty Fertilizer Market
Fertilizers
Global Phosphatic Fertilizers Market
Fertilizers
Water Soluble NPK Fertilizers Market