
 Silicon Fertilizer Market | 2026-2036
Silicon Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Fertilizer Market Intelligence
ISO 18643 certification for silicon-containing fertilizers is rotating the competitive landscape toward producers with dedicated agronomic testing infrastructure. Agripower Australia leverages its mining-to-farm vertical integration to control raw diatomite quality from quarry to formulation. Denka Company Limited anchors its position through captive production of soluble silicon derivatives for precision agriculture systems. Plant Tuff differentiates by specializing in granular silicon products optimized for bulk blending compatibility with NPK fertilizers.
Silicon fertilizer refers to crop input materials containing plant-available silicon, typically as calcium silicate slags or potassium silicate solutions with SiO₂ concentrations ranging from 10% to 30%, applied to enhance mechanical strength, drought tolerance, and disease resistance in monocots and select dicots. The product type landscape shows liquid silicon formulations capturing margin pools in greenhouse and fertigation systems where rapid uptake is prioritized, while solid silicon retains volume leadership in broadacre grain operations where broadcast application dominates cost structures. Application segmentation reveals specialty crops and turf management as faster-growing channels where silicon's cosmetic quality benefits command price premiums over commodity agriculture.
The EPA regulates silicon fertilizer manufacturing under FIFRA and TSCA provisions that govern inert ingredient classifications and environmental release thresholds, while the USDA Natural Resources Conservation Service influences adoption through cost-share eligibility in conservation programs. India's FCO standards under the Ministry of Agriculture set minimum silicon content and solubility benchmarks that determine market access for domestic and imported products. Stakeholders must monitor evolving residue tolerance dialogues between regulators and food safety bodies to anticipate registration requirements that could reshape formulation strategies and geographic sourcing priorities.
Market Dynamics
REACH compliance in the European Union is tightening impurity thresholds for imported silicon fertilizers, forcing producers to reformulate products and invest in dedicated agronomic testing infrastructure to maintain market access.
Growth Catalysts
- State Agricultural Validation Programs:India's rice-growing belts are expanding silicon fertilizer adoption as state agricultural universities validate lodging resistance benefits and integrate recommendations into extension services.
- Abiotic Stress Intensification:Specialty crop growers in Australia and Brazil are scaling silicon programs to strengthen plant cell walls against drought and heat stress in climate-vulnerable growing regions.
- Conservation Cost-Share Eligibility:The USDA Natural Resources Conservation Service is influencing adoption through cost-share programs that subsidize silicon fertilizer use in soil health and conservation initiatives.
Market Restraints
- Raw Material Concentration Risk:Quality diatomite deposits concentrate in limited quarry regions, creating supply vulnerability for producers dependent on specific mining locations.
- Solubility Standard Friction:India's FCO standards under the Ministry of Agriculture enforce minimum silicon content and solubility benchmarks that exclude lower-grade imported formulations.
- Calcium Silicate Slag Volatility:Steel industry output fluctuations directly affect calcium silicate slag availability and pricing, the dominant solid silicon fertilizer feedstock.
Strategic Opportunities
- Greenhouse Fertigation Expansion:Liquid silicon formulations are capturing margin pools in controlled-environment agriculture where rapid uptake and precision dosing justify premium positioning.
- Bulk Blending Compatibility:Granular silicon products optimized for NPK co-application open volume channels in broadacre grain operations seeking single-pass efficiency.
- ISO 18643 Certification Arbitrage:Producers with dedicated agronomic testing infrastructure can differentiate against commodity suppliers lacking certification-compliant validation capabilities.
Industry Challenges
- Agronomic Expertise Scarcity:Field agronomists trained in silicon tissue testing and deficiency diagnosis remain concentrated in university research stations rather than commercial distribution networks.
- Residue Tolerance Uncertainty:Evolving dialogues between EPA regulators and food safety bodies on silicon residue thresholds create registration timeline risk for new formulation submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Fertilizer Market |
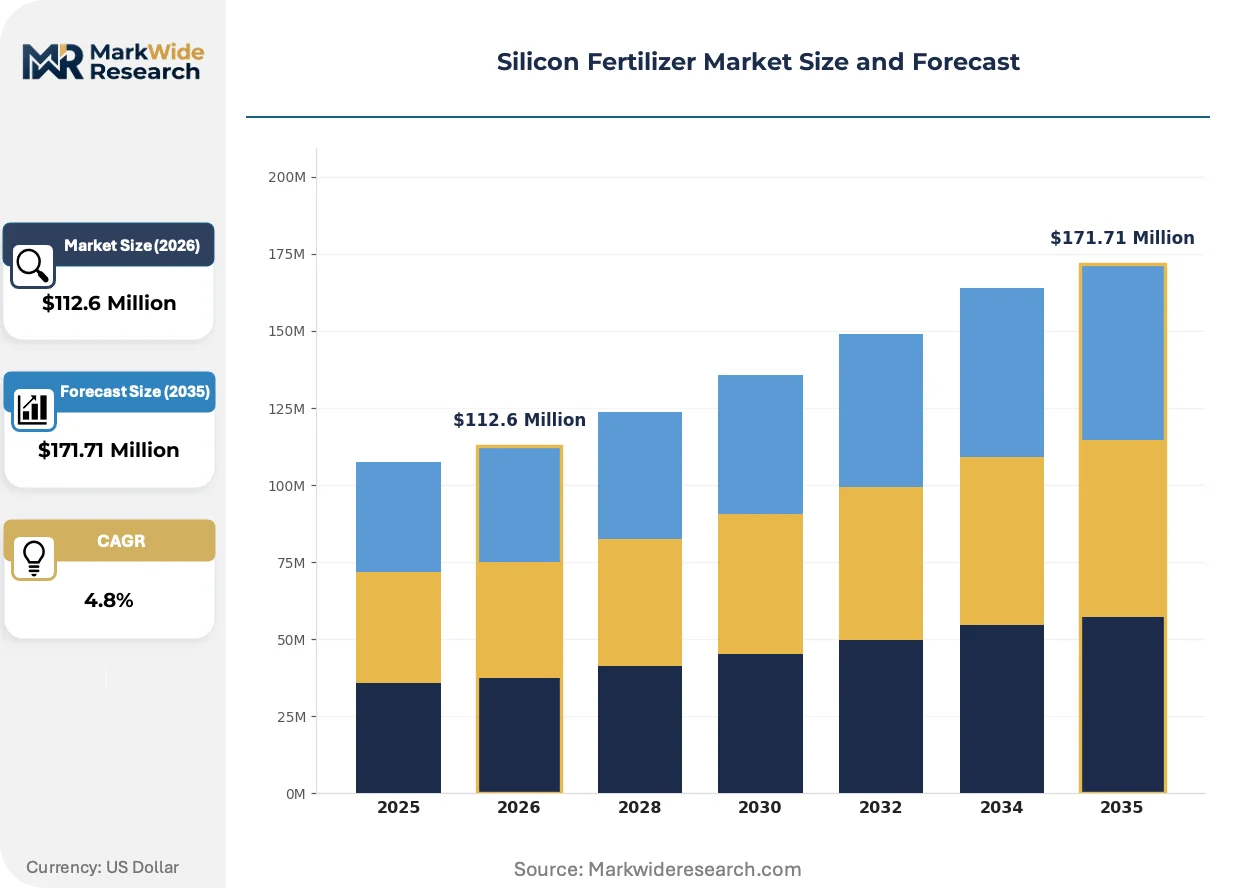
| Market Size in 2026 | $112.6 Million |
| Market Size in 2035 | $171.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Silicon, Soluble Silicon, Solid Silicon, Granular Silicon Application: Agriculture, Horticulture, Turf Management, Specialty Crops Delivery Mode: Foliar Application, Soil Application, Fertigation, Seed Treatment End User: Farmers, Agricultural Cooperatives, Distributors, Retailers |
| Companies Covered | Agripower Australia, MaxSil Pty Ltd, Denka Company Limited, Plant Tuff, PQ Corporation, Redox Pty Ltd, Jaipur Bio Fertilizers, Fertipower Norway AS, Haifa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Fertilizer Market Strategic Shifts & Innovations
Formulation chemistry and application precision are converging to reshape competitive positioning, with soluble derivatives and granular engineering opening distinct channel strategies.
Liquid potassium silicate concentrates with enhanced stability at lower pH are supplanting traditional calcium silicate slags in greenhouse and fertigation systems. Controlled-environment operators in the Netherlands and Spain are adopting these formulations for rapid root-zone availability. This shift is compressing the addressable market for solid silicon in protected agriculture while expanding margin pools for precision-compatible chemistries.
REACH Annex XVII restrictions on heavy metal impurities in fertilizer inputs are tightening entry barriers for commodity silicon suppliers. The European Chemicals Agency is enforcing lower cadmium and lead thresholds that require beneficiation investments or alternative sourcing. Importers without captive quarry relationships or in-house purification capacity are exiting the EU market or reformulating for adjacent geographies.
Cosmetic quality premiums in specialty crops and turf management are reshaping buyer willingness-to-pay for silicon-enhanced outputs. Golf course superintendents in Florida and strawberry growers in California are contracting directly with fertilizer suppliers for guaranteed silicon uptake protocols. This bypasses traditional cooperative and retail distribution layers in high-value crop segments where visual quality drives procurement decisions.
Silicon Fertilizer Market Segmentation
Silicon fertilizer segmentation reflects divergent agronomic requirements across crop systems and delivery infrastructure. Product chemistry, application method, and buyer type each create distinct margin profiles and competitive barriers.
Product Type:
Domestic production of calcium silicate slags dominates supply in steel-producing regions, while soluble and liquid formulations rely heavily on import flows for specialty agriculture.
- Liquid Silicon:Potassium silicate concentrates with SiO₂ concentrations of 20-30% enable rapid root-zone availability in greenhouse systems. Dutch and Spanish controlled-environment operators prioritize these formulations for precision dosing compatibility. Premium positioning in fertigation channels offsets higher logistics costs versus solid alternatives.
- Solid Silicon:Calcium silicate slags from steel industry byproduct streams supply broadacre grain operations through bulk blending networks. Indian rice belts and Australian wheat regions anchor volume demand where broadcast application dominates cost structures. Steel output fluctuations directly constrain feedstock availability.
- Soluble Silicon:Powdered potassium silicate derivatives dissolve for tank-mix flexibility with crop protection chemistries. Specialty crop growers in California and Florida favor soluble formats for split-application programs.
- Granular Silicon:Engineered particle sizes optimize flowability in NPK co-blending equipment. Brazilian soybean operations and US corn belts drive adoption for single-pass efficiency.
Solid silicon commands the established base. The steepest expansion runs through liquid silicon.
Application:
Margin pools concentrate where cosmetic quality premiums justify guaranteed uptake protocols over commodity procurement.
- Specialty Crops:Strawberry growers in California and Florida contract directly with suppliers for silicon-enhanced visual quality. Golf course superintendents specify guaranteed protocols for turf density and stress recovery. Direct supplier relationships bypass cooperative distribution layers.
- Agriculture:Rice cultivation in India's eastern states integrates silicon for lodging resistance validated by state agricultural universities. Wheat and corn operations in Australia and Brazil scale programs for drought tolerance in climate-vulnerable zones.
- Horticulture:Greenhouse vegetable producers in the Netherlands adopt silicon for powdery mildew suppression in high-humidity environments.
- Turf Management:Sports field managers and residential lawn services apply silicon for wear tolerance and color uniformity.
Agriculture maintains volume leadership. Specialty crops are climbing the fastest.
Delivery Mode:
Application infrastructure investment divides segments between precision-capable operations and broadcast-dependent broadacre systems.
- Fertigation:Drip and micro-sprinkler systems in protected agriculture enable precise silicon dosing synchronized with irrigation schedules. Israeli and Spanish greenhouse clusters lead adoption for water-stressed production environments.
- Soil Application:Broadcast spreading of solid silicon dominates Indian rice paddies and Australian dryland wheat. Equipment compatibility with existing fertilizer applicators minimizes adoption friction.
- Foliar Application:Tank-mixed silicon sprays address acute deficiency symptoms in high-value orchards and vineyards. Timing sensitivity limits use to specialized agronomic advisory relationships.
- Seed Treatment:Silicon coating of germinating seeds targets early root establishment in precision vegetable production. Limited commercial scale restricts segment penetration.
Soil application holds the volume base. Fertigation is gaining share fastest.
End User:
Procurement authority concentrates with entities controlling application equipment and agronomic decision rights.
- Farmers:Large-scale operators in Brazil and Australia directly specify silicon programs based on tissue testing and yield response data. Individual farm trials drive adoption in underpenetrated regions.
- Agricultural Cooperatives:Indian and US Midwest cooperatives aggregate member demand for bulk silicon procurement and shared application services. Extension relationships influence product selection.
- Distributors:Regional fertilizer distributors in Europe and North America manage inventory and blending logistics for solid silicon products. REACH compliance investments filter supplier portfolios.
- Retailers:Independent garden centers and farm supply stores serve turf management and small horticulture accounts with packaged liquid and soluble formats.
Farmers anchor direct procurement. Agricultural cooperatives are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's FCO standards and state agricultural university validation programs are accelerating silicon fertilizer adoption in rice-growing belts. Australia's mining-to-farm supply chains and drought resilience priorities concentrate demand in eastern wheat regions. Brazil's soybean expansion and abiotic stress management are scaling silicon programs across the Cerrado.
India
State agricultural universities in West Bengal and Odisha validate silicon's lodging resistance benefits for rice cultivation. The Ministry of Agriculture enforces FCO solubility benchmarks that filter lower-grade imports. Eastern rice belts integrate silicon recommendations into extension services.
Australia
Drought tolerance programs in New South Wales and Queensland wheat regions drive silicon adoption for cell wall strengthening. The country's national agricultural regulator influences input registration timelines for imported formulations. Agripower Australia controls diatomite quality from quarry operations in Queensland through to farm delivery.
Brazil
Soybean growers in Mato Grosso and Goiás scale silicon applications against heat stress in climate-vulnerable Cerrado zones. ANVISA monitors heavy metal thresholds in fertilizer imports. Granular silicon engineering optimizes NPK bulk blending compatibility for single-pass efficiency.
United States
USDA Natural Resources Conservation Service cost-share programs subsidize silicon use in soil health initiatives across the Corn Belt. The EPA regulates manufacturing under FIFRA and TSCA provisions governing inert ingredient classifications. Golf course superintendents in Florida contract directly for guaranteed silicon uptake protocols.
Netherlands
Greenhouse vegetable producers adopt liquid potassium silicate for powdery mildew suppression in high-humidity environments. ECHA enforces REACH Annex XVII heavy metal restrictions that require beneficiation investments. Controlled-environment clusters around Westland prioritize rapid root-zone availability formulations.
Silicon Fertilizer Market Key Industry Players
Player mix skews toward mining-integrated specialists and steel-industry derivative producers. The competitive structure concentrates around entities with captive raw material access and those dependent on external slag sourcing. Two strategic archetypes dominate: quarry-to-farm vertically integrated operators and steel-integrated slag processors. Capacity expansion in soluble silicon derivatives and ISO 18643 certification investments represent the dominant competitive moves.
Within the mining-integrated tier, Agripower Australia exemplifies quarry-to-formulation control over diatomite quality. Denka Company Limited occupies a position among soluble silicon specialists with captive production capabilities. Plant Tuff represents the granular engineering archetype optimized for NPK co-application channels. These three entities anchor distinct competitive vectors based on raw material access and application-format specialization.
| Leading Market Players |
|---|
| Agripower Australia |
| MaxSil Pty Ltd |
| Denka Company Limited |
| Plant Tuff |
| PQ Corporation |
| Redox Pty Ltd |
| Jaipur Bio Fertilizers |
| Fertipower Norway AS |
| Haifa Group |
| Others |
Cost & Logistics Intelligence
Ninety-day inventory cycles for diatomite feedstock concentrate pricing power with quarry-integrated producers, compressing margins for slag-dependent formulators while REACH compliance investments widen spreads between certified and commodity tiers.
Pricing Analysis
Certification level creates the primary spread, with ISO 18643-validated silicon fertilizers commanding premium positioning against untested imports. Three-tier pricing structure separates agronomically tested formulations from standard-grade slags and economy-tier unverified imports. Pricing pressure stems from India's FCO solubility benchmarks, which exclude lower-grade products and force reformulation costs onto marginal suppliers. Agricultural cooperatives in broadacre grain belts exhibit highest price sensitivity, while greenhouse operators in controlled-environment agriculture accept premiums for rapid-uptake liquid formulations.
Supply Chain Analysis
Sixty-to-ninety-day lead times for steel-industry calcium silicate slags tether solid silicon supply to blast furnace output cycles in China, India, and Brazil. Quality diatomite deposits draw from limited quarry regions in Australia and the United States, concentrating upstream control with mining-integrated specialists. Single-source vulnerability runs through steel industry byproduct dependency, where output fluctuations directly constrain feedstock availability. Distribution runs through agricultural cooperatives and regional distributors for solid products, with direct supplier relationships dominating liquid and soluble channels in specialty crop segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon fertilizer adoption is accelerating as state agricultural validation programs and REACH Annex XVII compliance requirements simultaneously expand addressable demand and erect technical barriers to entry.
For Market Incumbents: Secure captive diatomite quarry relationships or long-term slag offtake agreements to defend against raw material concentration risk. Invest in ISO 18643 certification infrastructure to differentiate against commodity importers facing REACH heavy metal threshold tightening. Lock in agricultural cooperative partnerships before university extension programs fully standardize recommendations. For New Entrants and Emerging Players: Technical advisory services for silicon tissue testing and deficiency diagnosis represent a service-layer gap where incumbents under-serve commercial distribution networks. Target India's rice-growing belts where state university validation is converting trial plots to systematic programs, entering through agronomic advisory partnerships rather than commodity pricing. Position through fertigation-compatible liquid formulations for greenhouse clusters in Spain and the Netherlands. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-input consolidation play because regulatory compliance investments favor scaled producers with in-house testing infrastructure over trading-house importers. Focus acquisition screening on mining-integrated mid-caps with quarry-to-formulation control and existing ISO certification. Watch for ECHA enforcement actions on heavy metal thresholds as the signal indicating which commodity suppliers will exit, creating distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diatomite Quarries | Agripower Australia's Queensland mining operations demonstrate quality control from extraction through farm delivery. |
| ISO 18643 Certification Investment | Validated agronomic testing infrastructure differentiates suppliers as REACH tightens impurity thresholds for EU market access. |
| Liquid Formulation Capacity Expansion | Greenhouse operators in Dutch Westland clusters prioritize potassium silicate concentrates for precision fertigation compatibility. |
| State University Partnership Programs | Indian agricultural universities in West Bengal and Odisha convert research validation into extension service recommendations. |
| Granular Engineering for NPK Co-Blending | Brazilian Cerrado soybean operations optimize single-pass efficiency through bulk blending-compatible particle sizing. |
Research Approach
Initial hypotheses were tested against primary input from fertilizer plant managers, agricultural cooperative procurement leads, greenhouse operations directors, and state extension service agronomists and refined through secondary validation against customs trade data, FCO registration filings, SEC 10-K disclosures from diversified chemical producers, and steel industry byproduct flow reports. Bottom-up demand modeling across crop-specific application rates triangulated with top-down supply-side capacity assessments.
Variance in projected outcomes decomposes across product chemistry segments, application method channels, and regional regulatory clusters throughout the forecast period. CAGRs derive from installed base penetration curves for silicon validation programs, steel output correlation models for slag feedstock availability, and greenhouse acreage expansion rates in water-stressed production regions. Modeled inputs include FCO solubility standard enforcement timelines and ECHA heavy metal threshold revision probabilities.
Forecasts assume regulatory continuity in EU REACH enforcement, India's FCO standards, and Brazil's ANVISA fertilizer import monitoring; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Blue-Green Algae Fertilizer Market
Fertilizers
India Organic Fertilizer Market
Fertilizers
Slow Release NPK Fertilizer Market
Fertilizers
China Specialty Fertilizer Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
India Specialty Fertilizer Market
Fertilizers
Organic Fertilizers Market
Fertilizers
Global Urea Market
Fertilizers
Global Specialty Fertilizer Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Russia Fertilizers Market
Fertilizers
Fertilizer Spreader Market
Fertilizers
Global Nitrogen Fertilizers Market
Fertilizers
Enhanced Efficiency Fertilizer Market