
 L-Glufosinate Ammonium Market | 2026-2036
L-Glufosinate Ammonium Market Size, Share, and Industry Trends Forecast 2026-2036
L-Glufosinate Ammonium Market Insights
The capital-intensity divergence between integrated manufacturers and formulation-only suppliers is unwinding competitive stability in the L-glufosinate ammonium sector. Bayer AG leverages its seed-trait pipeline to anchor herbicide demand through stacked-trait licensing. Nufarm sustains cost competitiveness through backward integration into key intermediates. Zhejiang YongNong BioSciences specializes in technical-grade production, occupying a narrow but defensible position in Asian supply chains.
L-glufosinate ammonium is a phosphinic acid herbicide derived from Streptomyces viridochromogenes fermentation, formulated as a water-soluble salt with contact and systemic activity against broadleaf and grass weeds; it inhibits glutamine synthetase, causing rapid ammonia accumulation and plant tissue necrosis. Herbicidal Formulation dominates product-type revenue due to compatibility with major agrochemical tank mixes and established application infrastructure. Agricultural Crops represents the largest application segment, though Turf Management generates disproportionate margin pools through specialized channel pricing and lower volume-price sensitivity.
The EPA regulates L-glufosinate ammonium tolerances and labeling under FIFRA, while the EU's EFSA and REACH frameworks govern residue thresholds and active-substance renewal. China's MEE enforces emission standards on phosphorous intermediate production that constrain technical-grade capacity expansion. Stakeholders must monitor regulatory divergence between jurisdictions on pollinator risk assessments and buffer-zone requirements, as these will determine which formulation types and application rates retain market access.
Market Dynamics
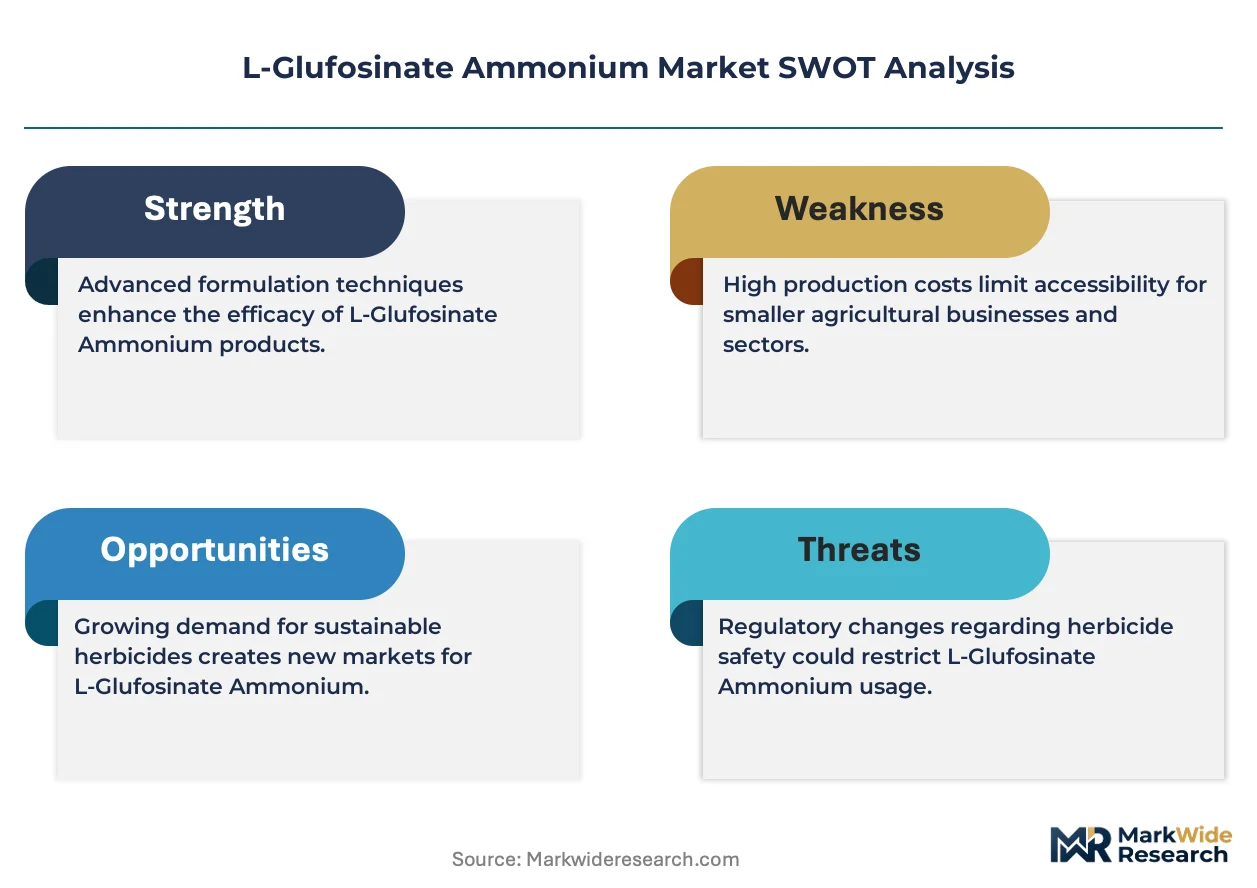
Glyphosate resistance proliferation across soybean and cotton belts is restructuring herbicide procurement patterns, forcing growers toward glufosinate-tolerant trait stacks as the primary defense rotation. Seed-trait licensing agreements now lock in multi-year herbicide commitments ahead of planting cycles.
Growth Catalysts
- EU Farm to Fork residue tightening:The EU Green Deal's pesticide reduction targets accelerate biopesticide registration reviews, creating regulatory preference for glufosinate's favorable toxicological profile relative to older chemistries.
- Brazil Cerrado expansion:New soybean frontiers in Mato Grosso and Goiás exclusively adopt glufosinate-tolerant stacked traits, concentrating demand in genetically modified seed corridors.
- Phosphinic acid fermentation scale-up:Advances in Streptomyces viridochromogenes strain optimization reduce production cycle times and improve yield consistency for technical-grade manufacturing.
Market Restraints
- Phosphorous intermediate supply concentration:Technical-grade capacity expansion faces binding constraints from China's MEE emission standards on phosphorous chemical production.
- Glutamine synthetase inhibitor substitution:Newer herbicidal modes of action in development pipelines threaten long-term positioning of phosphinic acid chemistry.
- REACH active-substance renewal costs:ECHA data requirements for glufosinate re-registration impose multi-million-euro toxicology and ecotoxicology study burdens on formulators.
Strategic Opportunities
- India cotton belt penetration:Maharashtra and Gujarat cotton growers remain underexposed to glufosinate-tolerant traits, presenting first-mover advantage for trait-stack licensing.
- Turf management channel expansion:Golf course and sports field maintenance contracts offer premium pricing with lower volume-price sensitivity than agricultural commodity markets.
- Drone application compatibility:Low-volatility formulation development aligns with emerging aerial spraying regulations in Australia and Brazil.
Industry Challenges
- Formulation chemist scarcity:Expertise in phosphinic acid salt stability and tank-mix compatibility resides with a narrow cohort of agrochemical specialists approaching retirement.
- Seed-trait licensing complexity:Stacked-trait IP portfolios require navigation of multiple patent estates covering both herbicide tolerance and insect resistance genes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | L-Glufosinate Ammonium Market |
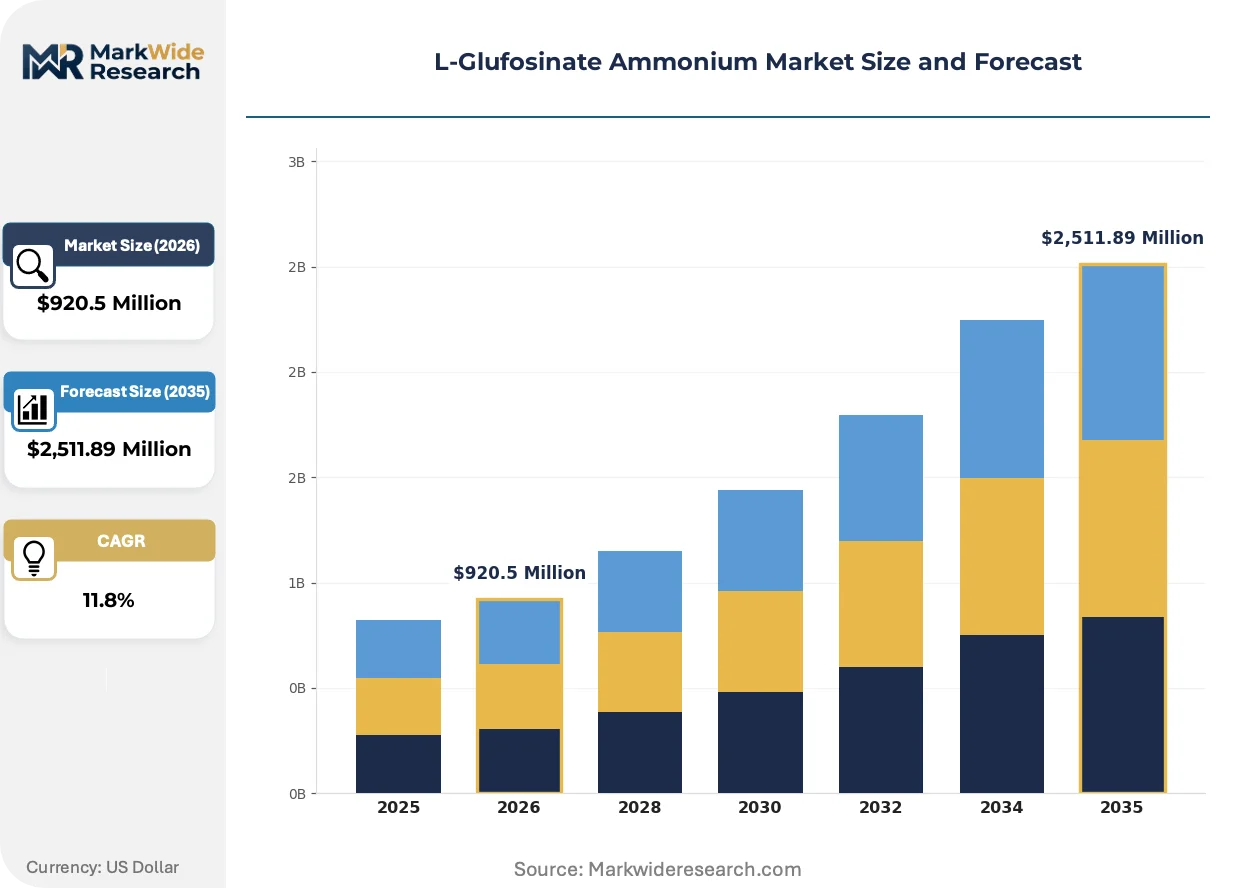
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $2,511.89 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicidal Formulation, Granules, Liquid Concentrate, Water-Soluble Powder Application: Agricultural Crops, Vegetable Production, Industrial Non-Crop, Turf Management End User: Farmers, Agricultural Cooperatives, Research Institutions, Gardening Enterprises Distribution Channel: Direct Sales, Online Retail, Distributors, Specialty Stores |
| Companies Covered | Corteva Agriscience, Nufarm, Bayer AG, Zhejiang YongNong BioSciences, Adama Agricultural Solutions, Syngenta, Lier Chemical, Jiangsu Huangma Agrochemicals, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
L-Glufosinate Ammonium Market Trends and Innovations
Formulation chemistry advances are compressing application rates while expanding crop compatibility, reshaping competitive positioning around technical purity and adjuvant systems rather than raw active ingredient volume.
Micro-encapsulation technology for glufosinate salts is miniaturizing droplet deposition requirements, enabling reduced water volumes per hectare. Brazilian cotton cooperatives are adopting these formulations for aerial application compatibility. The technology is miniaturizing equipment capital requirements for smallholder mechanization programs.
EPA FIFRA buffer-zone calculations now incorporate pollinator risk assessments, mandating expanded setbacks for flowering crops. Formulators must redesign label language and application timing restrictions. Turf management and non-crop vegetation control segments face the most immediate compliance recalibration.
Channel consolidation among agricultural retailers is compressing manufacturer-direct relationships with growers. Input purchasing cooperatives in the US Corn Belt now negotiate consolidated herbicide procurement contracts. This pattern is most visible in Iowa and Illinois, where three distributor groups control majority volume flows.
L-Glufosinate Ammonium Market Segmentation
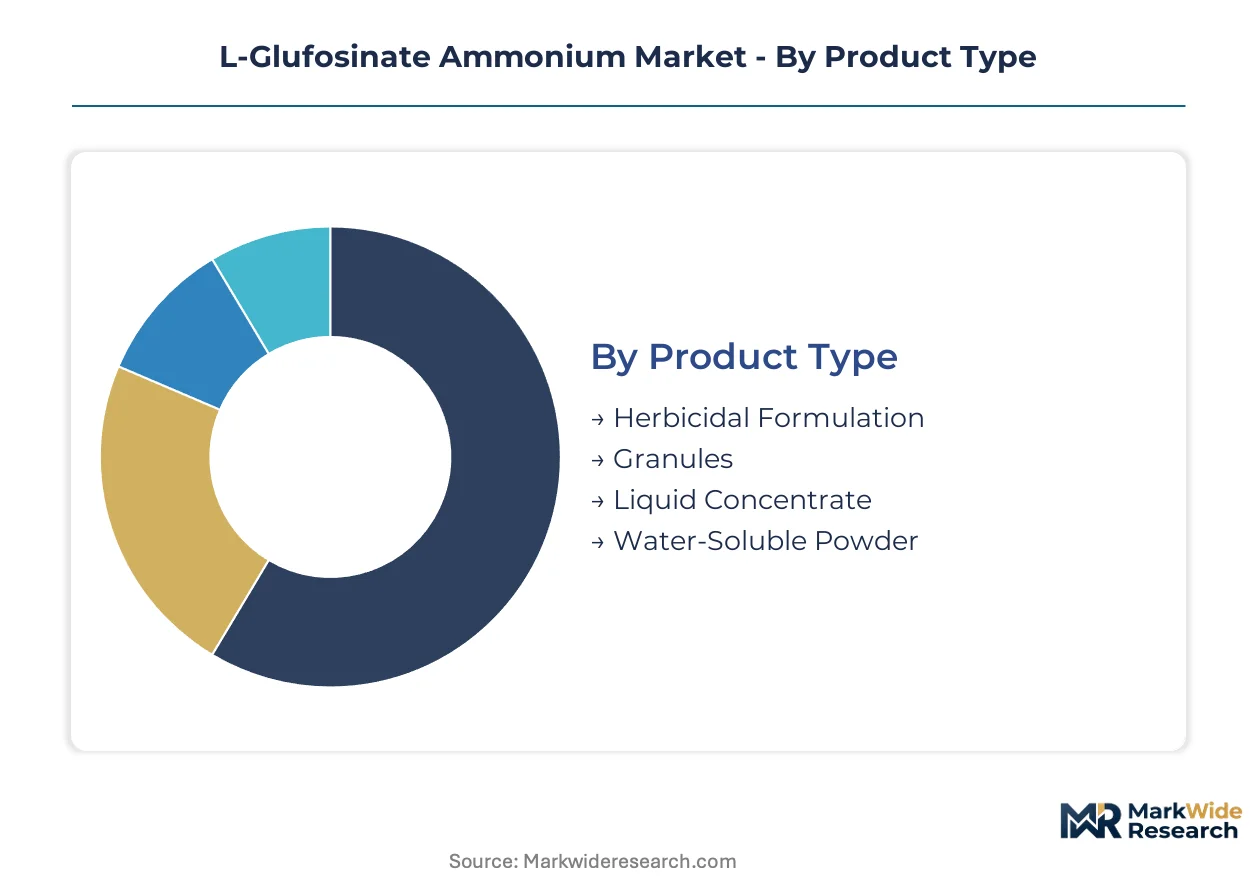
L-glufosinate ammonium demand fragments across formulation types, application settings, and procurement channels that each impose distinct technical specifications and margin structures. Channel economics and regulatory exposure vary sharply between bulk agricultural procurement and specialized turf management contracts.
Product Type:
Herbicidal Formulation and Liquid Concentrate dominate manufacturer-direct channels to large-scale growers, while Granules and Water-Soluble Powder flow through distributor networks serving smaller operations.
- Herbicidal Formulation:Pre-mixed aqueous solutions containing glufosinate ammonium salt with surfactant packages optimized for tank-mix compatibility. Demand concentrates in Brazil's Mato Grosso soybean belt where aerial application infrastructure favors ready-to-use formats. EPA FIFRA labeling requirements for buffer zones drive formulation refinement to reduce drift potential.
- Liquid Concentrate:High-active-content solutions requiring dilution prior to field application, offering freight cost advantages for bulk procurement. Cotton cooperatives in Maharashtra, India favor this format for on-farm mixing flexibility. China's MEE emission standards on phosphorous intermediate production constrain technical-grade supply for concentrate manufacturing.
- Granules:Slow-release matrix formulations for turf and ornamental applications with extended residual activity.
- Water-Soluble Powder:Solid salt formulations reconstituted at point of use, preferred by research institutions and precision agriculture operations.
By volume, Herbicidal Formulation leads. By growth pace, Liquid Concentrate is expanding most quickly in emerging trait-stack corridors.
Application:
Cost tier differentiation separates commodity agricultural applications from premium-priced turf and industrial segments, with regulatory compliance burdens scaling inversely with volume.
- Agricultural Crops:Broadacre soybean, cotton, and canola production representing the volume foundation of glufosinate demand. Brazil's Cerrado expansion zones exclusively adopt glufosinate-tolerant stacked traits, concentrating procurement in genetically modified seed corridors. EU Farm to Fork residue tightening accelerates grower transition from glyphosate to glufosinate rotations.
- Turf Management:Golf course, sports field, and ornamental maintenance applications commanding premium pricing through specialized channel relationships. ECHA REACH active-substance renewal requirements impose disproportionate compliance costs relative to volume. Formulation chemists optimize for low-volatility characteristics to satisfy pollinator risk assessments.
- Vegetable Production:High-value row crops with stringent maximum residue limits driving technical-grade purity requirements.
- Industrial Non-Crop:Railway, utility, and infrastructure vegetation management with extended application windows and lower price sensitivity.
Agricultural Crops anchor volume procurement. Turf Management claims the steepest margin expansion trajectory.
End User:
Customer scale determines procurement modality, with large cooperatives negotiating multi-year supply agreements while smaller operators rely on distributor credit terms.
- Farmers:Individual growers accessing glufosinate through retail cooperatives and input suppliers, with adoption patterns tied to seed-trait licensing availability. Iowa and Illinois Corn Belt purchasing groups now consolidate herbicide procurement through three dominant distributor networks.
- Agricultural Cooperatives:Member-owned entities aggregating volume for manufacturer-direct negotiations, particularly prevalent in Brazilian cotton and soybean production zones. Backward integration into formulation capabilities distinguishes cooperatives with captive supply chains.
- Research Institutions:Universities and extension services evaluating resistance management protocols and application timing optimization.
- Gardening Enterprises:Commercial landscaping and nursery operations with intermittent demand patterns and higher service expectations.
Farmers represent the broadest installed base. Agricultural Cooperatives are gaining share fastest through consolidated procurement leverage.
Distribution Channel:
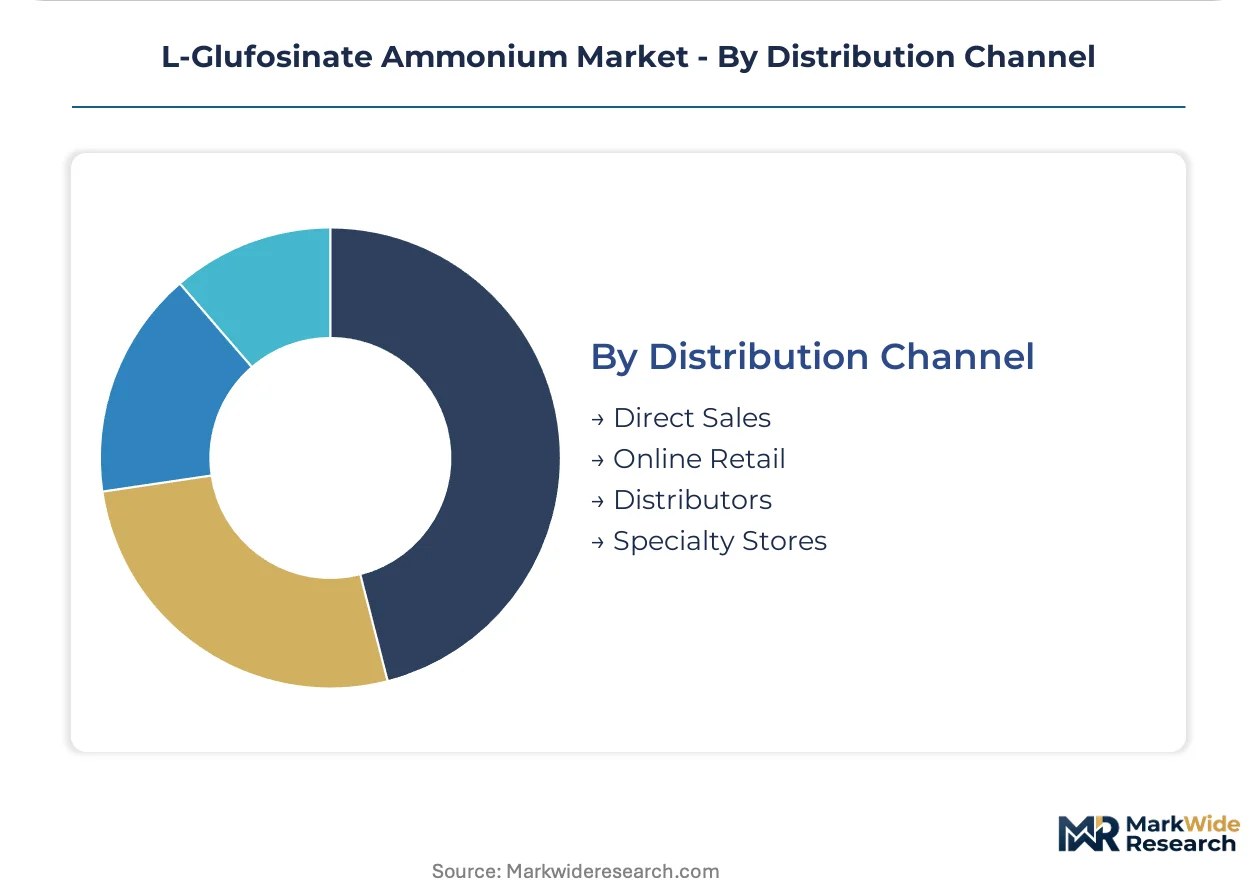
Geographic concentration of demand shapes channel viability, with direct sales economical only in high-volume production clusters while fragmented markets sustain distributor intermediation.
- Distributors:Regional agrochemical wholesalers maintaining inventory positions and credit relationships with grower cooperatives. Channel consolidation in the US Midwest compresses manufacturer access to end users.
- Direct Sales:Manufacturer-to-grower contracts for large-volume accounts with dedicated agronomic support, standard in Brazil's consolidated soybean frontier.
- Online Retail:Emerging platform-based procurement for smaller-scale operations and specialty formulations, constrained by hazardous material shipping regulations.
- Specialty Stores:Turf management and gardening-focused retailers with technical consultation capabilities and premium product positioning.
Distributors still handle the greatest volume throughput. Direct Sales is climbing the fastest as trait-stack licensing locks in supply relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian soybean growers exhibit the lowest price elasticity, locking in multi-year herbicide commitments through seed-trait licensing, while Indian cotton smallholders remain highly price-sensitive and exposed to spot-market volatility.
Brazil
Mato Grosso and Goiás Cerrado expansion zones exclusively adopt glufosinate-tolerant stacked traits, concentrating procurement in genetically modified seed corridors. ANVISA pesticide registration reviews are accelerating under sustainability mandates. São Paulo-based formulators are scaling micro-encapsulation capacity for aerial application compatibility.
United States
Iowa and Illinois Corn Belt purchasing cooperatives consolidate herbicide procurement through three dominant distributor networks, compressing manufacturer-direct access. EPA FIFRA buffer-zone calculations now incorporate pollinator risk assessments, mandating expanded setbacks for flowering crops. Midwestern retailers are redesigning label language and application timing restrictions to satisfy compliance recalibration.
China
Jiangsu and Zhejiang provinces host technical-grade production clusters constrained by MEE emission standards on phosphorous intermediate manufacturing. The country's national environmental regulator enforces binding capacity expansion limits. Nantong chemical parks are optimizing Streptomyces viridochromogenes fermentation yields to offset regulatory headwinds.
India
Maharashtra and Gujarat cotton belts remain underexposed to glufosinate-tolerant traits, presenting first-mover advantage for trait-stack licensing. CDSCO and the Central Insecticides Board govern pesticide registration and residue monitoring. Ahmedabad-based cooperatives are piloting liquid concentrate formats for on-farm mixing flexibility.
Germany
Bavaria and North Rhine-Westphalia anchor EU formulation chemistry expertise, though ECHA REACH active-substance renewal costs impose multi-million-euro toxicology burdens. The EU Green Deal's Farm to Fork pesticide reduction targets accelerate biopesticide registration reviews. Leverkusen-area research clusters are advancing low-volatility adjuvant systems for pollinator-risk mitigation.
L-Glufosinate Ammonium Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence unwinding competitive stability across the sector. Bayer AG leverages seed-trait pipelines to anchor herbicide demand, while Nufarm sustains cost competitiveness through backward integration into key intermediates. Zhejiang YongNong BioSciences occupies a narrow but defensible position in Asian supply chains. Dominant competitive moves include strategic partnerships for trait-stack licensing and capacity expansion in fermentation-based technical-grade manufacturing.
Among integrated agrochemical conglomerates, Bayer AG and Corteva Agriscience exemplify the seed-trait anchoring archetype, locking in multi-year herbicide commitments through stacked-trait licensing agreements ahead of planting cycles. Within the Asian specialist tier, Zhejiang YongNong BioSciences and Lier Chemical represent technical-grade production archetypes, occupying positions in phosphinic acid salt supply chains constrained by environmental emission standards. Nufarm sits within the backward-integrated formulator category, sustaining cost structures through captive intermediate supply.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Nufarm |
| Bayer AG |
| Zhejiang YongNong BioSciences |
| Adama Agricultural Solutions |
| Syngenta |
| Lier Chemical |
| Jiangsu Huangma Agrochemicals |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Multi-year seed-trait licensing agreements lock in herbicide procurement ahead of planting cycles, anchoring price visibility for Brazilian soybean cooperatives while exposing spot-market buyers in India's cotton belt to volatile input costs. China's MEE emission standards on phosphorous intermediate production constrain technical-grade supply expansion, translating regulatory scarcity into sustained premium pricing for fermentation-derived technical purity grades.
Pricing Analysis
After-sales agronomic advisory services drive lifetime value for glufosinate formulators, with Bayer AG and Corteva Agriscience bundling resistance-management protocols into trait-stack licensing fees. Three-tier pricing structure across premium micro-encapsulated formulations, standard aqueous solutions, and economy-grade liquid concentrates reflects technical purity gradients and tank-mix compatibility certification. Cost compression in standard-grade segments is intensifying because Nufarm's backward integration into phosphinic acid intermediates resets baseline manufacturing economics. Agricultural cooperatives in Brazil's Mato Grosso exhibit the lowest price sensitivity, while Indian cotton smallholders in Gujarat face acute spot-market volatility.
Supply Chain Analysis
Jiangsu and Zhejiang province phosphorous chemical parks underwrite global technical-grade capacity, with Nantong fermentation clusters feeding Asian formulation networks. The supply chain draws from Streptomyces viridochromogenes strain banks, phosphorous trichloride intermediates, and surfactant adjuvant packages sourced from German specialty chemical producers. Single-source vulnerability concentrates in China's MEE-regulated intermediate corridor, where emission quota enforcement caps expansion regardless of demand signals. Distribution runs through agricultural retailer cooperatives in the US Corn Belt and manufacturer-direct contracts in Brazil's consolidated soybean frontier.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise has narrowed to a retiring specialist cohort, creating acute capability scarcity for phosphinic acid salt stability optimization and pollinator-risk-compliant adjuvant design. This talent compression rewards organizations that capture institutional knowledge through structured technical apprenticeship programs.
For Market Incumbents: Consolidate backward integration into phosphorous intermediate production to offset China's MEE capacity constraints, while capturing retiring formulation chemists through technical advisory retainers. Seed-trait licensing complexity demands dedicated IP navigation teams to manage stacked-trait patent estates covering both herbicide tolerance and insect resistance genes. For New Entrants and Emerging Players: Lead with drone-application-compatible low-volatility formulations targeting Australia's emerging aerial spraying regulations and Brazil's cotton cooperative mechanization programs. Maharashtra and Gujarat cotton belts offer the most penetrable geography, with first-mover advantage available for trait-stack licensing partnerships with regional seed distributors. For Investors and Strategic Acquirers: Fermentation-based technical-grade specialists with captive Streptomyces strain optimization capabilities represent the priority acquisition archetype, as environmental emission standards permanently constrain synthetic chemistry alternatives. Watch EPA FIFRA pollinator risk assessment outcomes as the critical inflection signal, with expanded buffer-zone mandates favoring micro-encapsulation formulators over commodity aqueous solutions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorous Intermediates | Nufarm's captive supply of key inputs insulates margin structures from China's MEE emission quota volatility. |
| Micro-Encapsulation Capacity Expansion | São Paulo-based formulators align with ANVISA aerial application regulations and Brazilian cotton cooperative mechanization. |
| Seed-Trait Licensing Partnership | Bayer AG's stacked-trait portfolios lock in multi-year herbicide commitments ahead of planting cycles in Mato Grosso. |
| Low-Volatility Formulation Development | Leverkusen research clusters address ECHA REACH pollinator risk assessments for EU turf management market retention. |
| Fermentation Yield Optimization | Nantong chemical parks improve Streptomyces viridochromogenes productivity to offset regulatory headwinds on phosphorous chemistry. |
Research Methodology
Desk research of customs trade data, EPA FIFRA registration filings, and ECHA REACH active-substance renewal documentation preceded structured interviews with formulation R&D directors, agricultural cooperative procurement managers, seed-trait licensing executives, and phosphorous intermediate plant managers. Primary fieldwork across Brazil's Mato Grosso soybean belt, India's Maharashtra cotton regions, and China's Jiangsu chemical parks validated secondary estimates. Bottom-up volume triangulation from trait-stack adoption rates and top-down value reconciliation from manufacturer revenue disclosures anchored the analytical framework.
Variance decomposition across product type, application setting, and regional regulatory cluster shaped the projection methodology. Segmentation dimensions modeled include formulation chemistry grade, crop-specific tolerance trait penetration, and channel procurement modality. CAGRs were derived from compounded annual growth trajectories across the analysis window, with industry-specific inputs incorporating glyphosate resistance spread rates and Farm to Fork residue limit implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained glufosinate-tolerant seed adoption, stable phosphorous intermediate supply, or unchanged pollinator risk assessment frameworks would require recalibration. Practitioners should keep alternative scenarios live as EU pesticide reduction targets and Brazilian Cerrado expansion rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
South Africa Agrochemicals Market
Agrochemicals
Agrochemical Market
Agrochemicals
Malaysia Agrochemicals Market
Agrochemicals
Canada Agrochemicals Market
Agrochemicals
Agrochemical Active Ingredients Market
Agrochemicals
Middle East and Africa Plant Growth Regulators Market
Agrochemicals
North America Agrochemicals Market
Agrochemicals
Australia Agrochemicals Market
Agrochemicals
Mexico Agrochemicals Market
Agrochemicals
Potassium Humate Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
Africa Agrochemicals Market
Agrochemicals
Indonesia Agrochemicals Market
Agrochemicals
India Agrochemicals Market
Agrochemicals
South America Agrochemicals Market
Agrochemicals
Global Buprofezin Market