
 United States Micronutrient Fertilizer Market | 2026-2036
United States Micronutrient Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Micronutrient Fertilizer Market Analytics
The EPA's updated water quality standards for agricultural runoff is shifting demand toward controlled-release micronutrient formulations that reduce leaching losses. The Mosaic Company leverages its phosphate mining integration to anchor domestic sulfur and micronutrient supply chains. Nutrien Ag Solutions, Inc. competes through its retail agronomy network, which sustains direct farmer relationships across the Great Plains and Delta regions. Yara International ASA differentiates via its digital farming platform, which positions the company to capture precision agriculture spending in high-value specialty crop zones.
United States micronutrient fertilizers are inorganic or chelated compounds containing essential trace elements—typically copper, iron, manganese, or zinc—formulated at concentrations between 5% and 15% elemental metal by weight, designed to correct soil deficiencies and optimize plant enzymatic function in commercial agriculture. Liquid formulations lead in revenue intensity due to compatibility with fertigation systems and variable-rate application equipment, while granular products dominate volume through their integration with bulk blended NPK programs. Zinc products command the largest product-type share given widespread deficiency across calcareous Midwestern soils, whereas copper demand accelerates fastest in Pacific Northwest tree fruit and nut orchards where woody perennial requirements outstrip soil availability.
USDA conservation programs and state-level nutrient management regulations in Iowa, Illinois, and Minnesota mandate soil testing before micronutrient application, creating compliance-driven demand for certified analytical services and prescription-grade products. The FDA's Food Safety Modernization Act traceability rules pressure fresh produce growers toward documented micronutrient inputs, tightening supply chain verification requirements. Stakeholders must monitor evolving state fertilizer registration fees and the EPA's pending review of chelating agent environmental fate, as these will determine formulation economics and market access conditions.
Market Dynamics
Precision application technologies are compressing the United States Micronutrient Fertilizer Market's traditional bulk-blending model, as variable-rate equipment and fertigation systems displace uniform broadcasting methods across the Corn Belt and specialty crop zones.
Growth Catalysts
- EPA Water Quality Standards:The EPA's revised agricultural runoff rules are pressuring growers toward controlled-release formulations that minimize leaching losses into watersheds.
- Specialty Crop Sustainability Mandates:California and Florida produce handlers are requiring documented micronutrient programs as a condition of supply contracts with national retailers.
- Soil Deficiency Mapping:Grid-based soil sampling technologies are revealing zinc and manganese gaps across calcareous Midwestern soils that previously went untreated.
Market Restraints
- Sulfur Price Volatility:Domestic sulfur supply ties to phosphate mining concentration, exposing formulation costs to energy sector fluctuations and refinery output decisions.
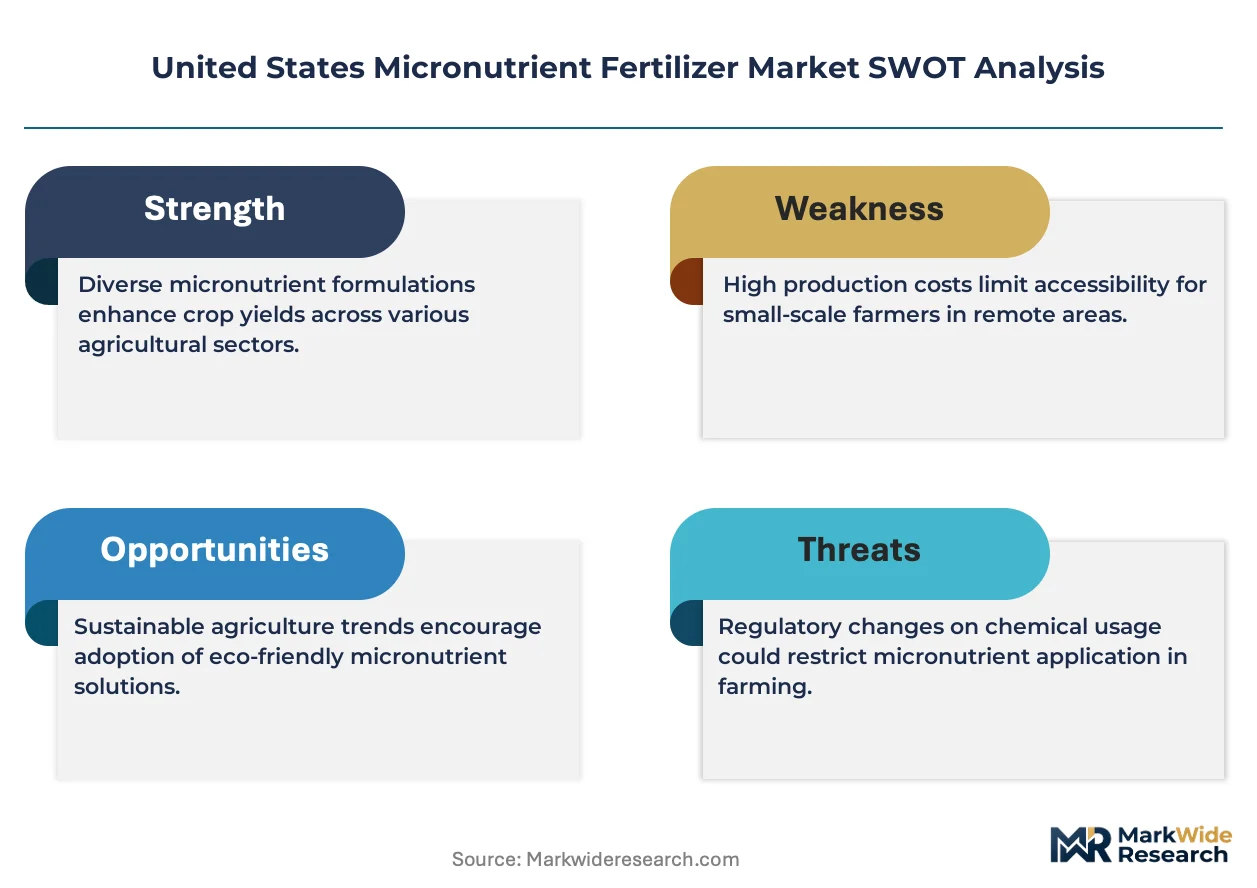
- Chelating Agent Regulatory Review:The EPA's pending environmental fate assessment of EDTA and DTPA chelators threatens reformulation costs and product registration timelines.
- Granular NPK Integration Lock-in:Bulk blending infrastructure at rural cooperatives creates technical friction for liquid micronutrient adoption despite superior agronomic performance.
Strategic Opportunities
- Digital Farming Convergence:Variable-rate application equipment paired with real-time soil sensors enables prescription-grade micronutrient dosing in high-value specialty crop zones.
- State Nutrient Management Incentives:Iowa, Illinois, and Minnesota conservation cost-share programs subsidize certified soil testing and precision application equipment purchases.
- FDA Traceability Alignment:The Food Safety Modernization Act's documentation requirements create premium positioning for verified supply chain micronutrient products in fresh produce channels.
Industry Challenges
- Agronomic Expertise Scarcity:Certified crop advisors with micronutrient prescription training remain concentrated in university extension programs, limiting grower access to site-specific recommendations.
- Equipment Compatibility Friction:Liquid formulation adoption requires retrofitting of existing granular application infrastructure at farm and retail levels, compressing near-term conversion economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Micronutrient Fertilizer Market |
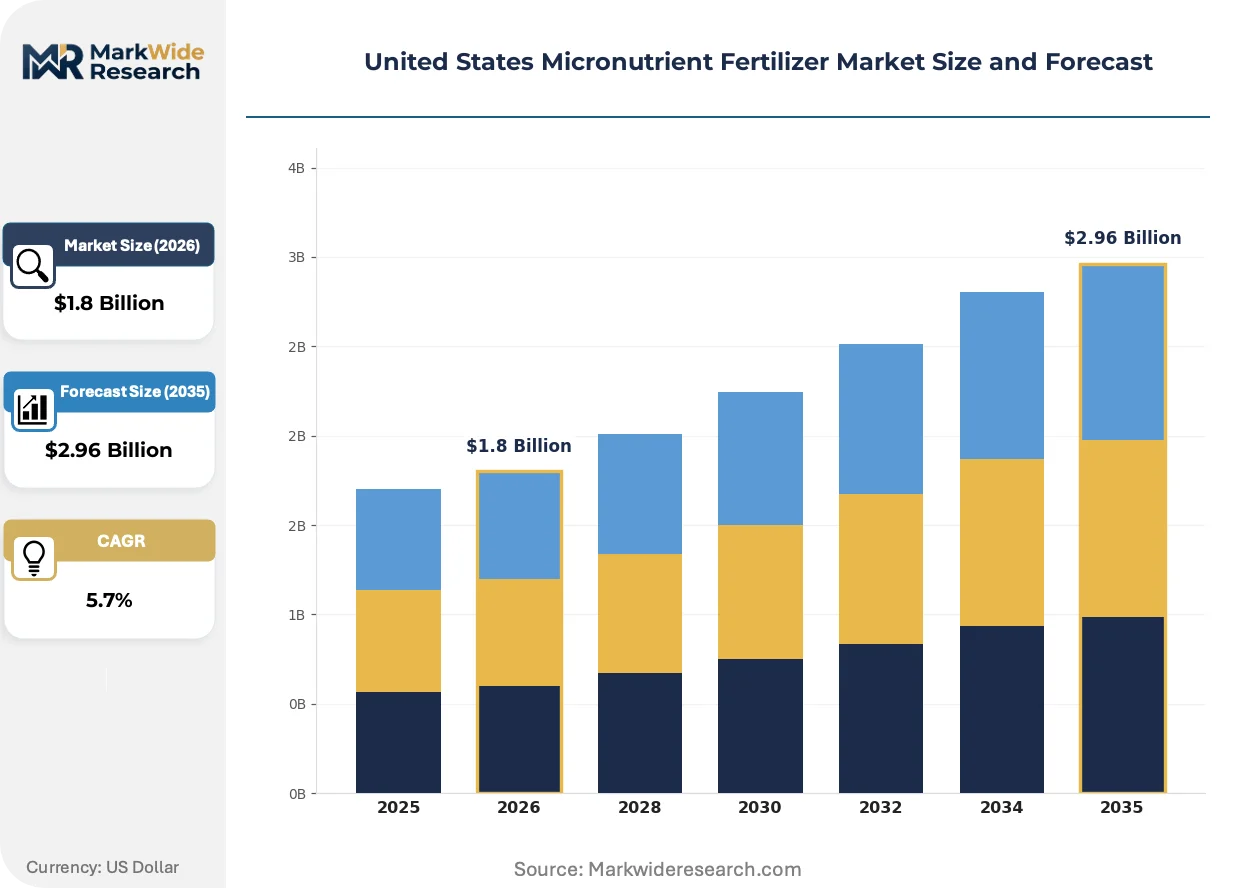
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper, Iron, Manganese, Zinc Application: Agricultural Crops, Horticultural Plants, Turf, Ornamental Plants Distribution Channel: Online Retail, Agrochemical Stores, Direct Sales, Wholesale Form: Granular, Liquid, Powder, Suspension |
| Companies Covered | The Mosaic Company, The Andersons Inc., Sociedad Quimica y Minera de Chile SA, Wilbur-Ellis Company LLC, Yara International ASA, Koch Industries Inc., Nutrien Ag Solutions, Inc., Helena Agri-Enterprises, LLC, Brandt, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Micronutrient Fertilizer Market Evolving Landscape
Controlled-release and chelated formulation technologies are displacing conventional salt-based products, while digital agriculture platforms reshape how micronutrient prescriptions reach farm-level decision-makers across soil types and crop rotations.
Chelated zinc and manganese formulations are consolidating market position in calcareous soil regions where conventional sulfate salts precipitate before root uptake occurs. Specialty crop producers in the Pacific Northwest and California Central Valley are adopting these products at accelerated rates. The technology is consolidating agronomist recommendations around foliar and fertigation delivery methods that bypass soil chemistry limitations entirely.
The EPA's pending review of chelating agent environmental fate is forcing reformulation investments ahead of potential registration restrictions. Manufacturers are accelerating biodegradability testing and exploring natural organic complexing alternatives to synthetic EDTA. Fresh produce growers in Florida and California face the tightest compliance timelines, with several already requiring documented chelator profiles in supplier qualification audits.
Retailer-driven sustainability verification is restructuring procurement relationships in specialty crop supply chains. National produce retailers are unbundling traditional input supplier relationships to require direct micronutrient documentation from farm operators. This pattern concentrates most visibly in California's Salinas Valley and Florida's Immokalee region, where documented micronutrient programs now gate access to premium retail channels.
United States Micronutrient Fertilizer Market Segmentation
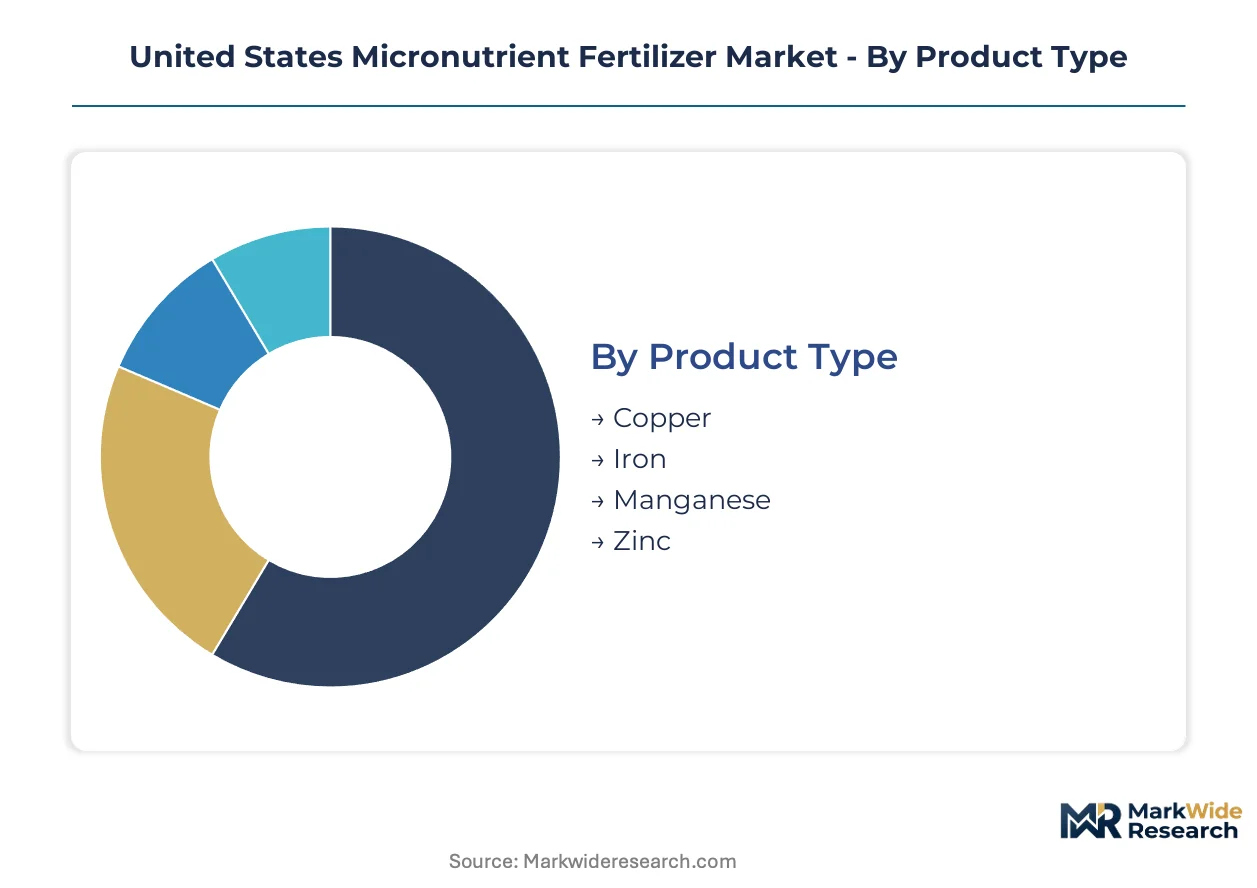
Micronutrient fertilizer purchasing decisions in the United States track closely to soil chemistry constraints, application infrastructure, and crop value intensity. Segmentation reveals how formulation choices diverge between commodity grain operations and high-value specialty producers.
Product Type:
Replacement cycles for micronutrient products accelerate when soil testing reveals cumulative depletion patterns, pushing growers toward chelated upgrades over conventional sulfate salts.
- Zinc:Formulated as zinc sulfate, zinc oxide, or chelated EDTA/Zn complexes at 5-14% elemental concentration. Demand concentrates across the Corn Belt's calcareous soils where pH-induced deficiency limits corn and soybean yields, with Iowa and Illinois extension services mandating pre-plant testing for certified nutrient management plans.
- Manganese:Available as manganese sulfate or chelated formulations targeting enzymatic activation in photosynthesis and nitrogen metabolism. Wisconsin and Minnesota growers drive recurring application in soybean rotations where soil pH above 6.5 triggers severe deficiency symptoms.
- Copper:Essential for lignin synthesis and pollen fertility, formulated as copper sulfate or chelated complexes. Pacific Northwest tree fruit and nut orchards in Washington and Oregon require sustained supplementation where organic matter binds native copper beyond root access.
- Iron:Delivered as ferrous sulfate, ferric chelates, or lignosulfonate complexes to correct chlorosis in high-pH soils. California Central Valley specialty crop producers deploy fertigation-compatible iron chelates for drip-irrigated vegetables and permanent crops.
Zinc sits at the top of the volume ranking, with copper climbing the fastest as Pacific Northwest perennial acreage expands.
Application:
Application segmentation reflects divergent agronomic protocols between broadacre mechanized farming and labor-intensive horticultural systems.
- Agricultural Crops:Corn, soybean, wheat, and cotton operations deploying variable-rate spreaders or aerial application for bulk-blended programs. The Corn Belt's zinc and manganese deficiencies generate recurring demand tied to rotation cycles and yield targets.
- Horticultural Plants:Vegetable, fruit, and nut producers requiring precision dosing through fertigation or foliar systems. California's Salinas Valley and Florida's Immokalee region mandate documented micronutrient programs for retail supply contract qualification.
- Turf:Golf courses, sports fields, and municipal landscapes utilizing liquid formulations for spray tank compatibility. Florida and Arizona lead volume given year-round maintenance cycles and salinity stress management requirements.
- Ornamental Plants:Nursery and greenhouse operations favoring controlled-release formulations for container production. The Pacific Northwest and Northeast concentrate propagation activity where substrate-based growing systems eliminate native soil nutrient access.
Agricultural crops dominate absolute volume, though horticultural plants gain share fastest as specialty crop acreage expands and documentation requirements tighten.
Distribution Channel:
Channel selection tracks to farm scale, technical service requirements, and procurement centralization trends reshaping input purchasing patterns.
- Agrochemical Stores:Independent and cooperative retail locations providing soil testing, prescription blending, and agronomic consultation. Rural Midwestern cooperatives maintain bulk blending infrastructure that locks in granular micronutrient attachment to NPK programs.
- Direct Sales:Manufacturer-to-grower relationships for large-scale operations requiring customized formulation and technical support. California and Florida specialty crop producers above 5,000 acres increasingly bypass retail intermediaries for supply chain verification compliance.
- Wholesale:Volume distribution to retail networks and formulators from domestic production and import terminals. The Mosaic Company's phosphate mining integration anchors sulfur and micronutrient wholesale supply chains through Florida and Louisiana port infrastructure.
- Online Retail:E-commerce platforms serving small-scale producers, hobby farmers, and landscape contractors. Limited penetration in bulk micronutrient markets due to freight economics and technical consultation requirements.
Agrochemical stores capture the largest volume flow, while direct sales expand most quickly as large specialty operations consolidate procurement functions.
Form:
Form selection reflects equipment compatibility constraints, application timing flexibility, and soil chemistry bypass strategies.
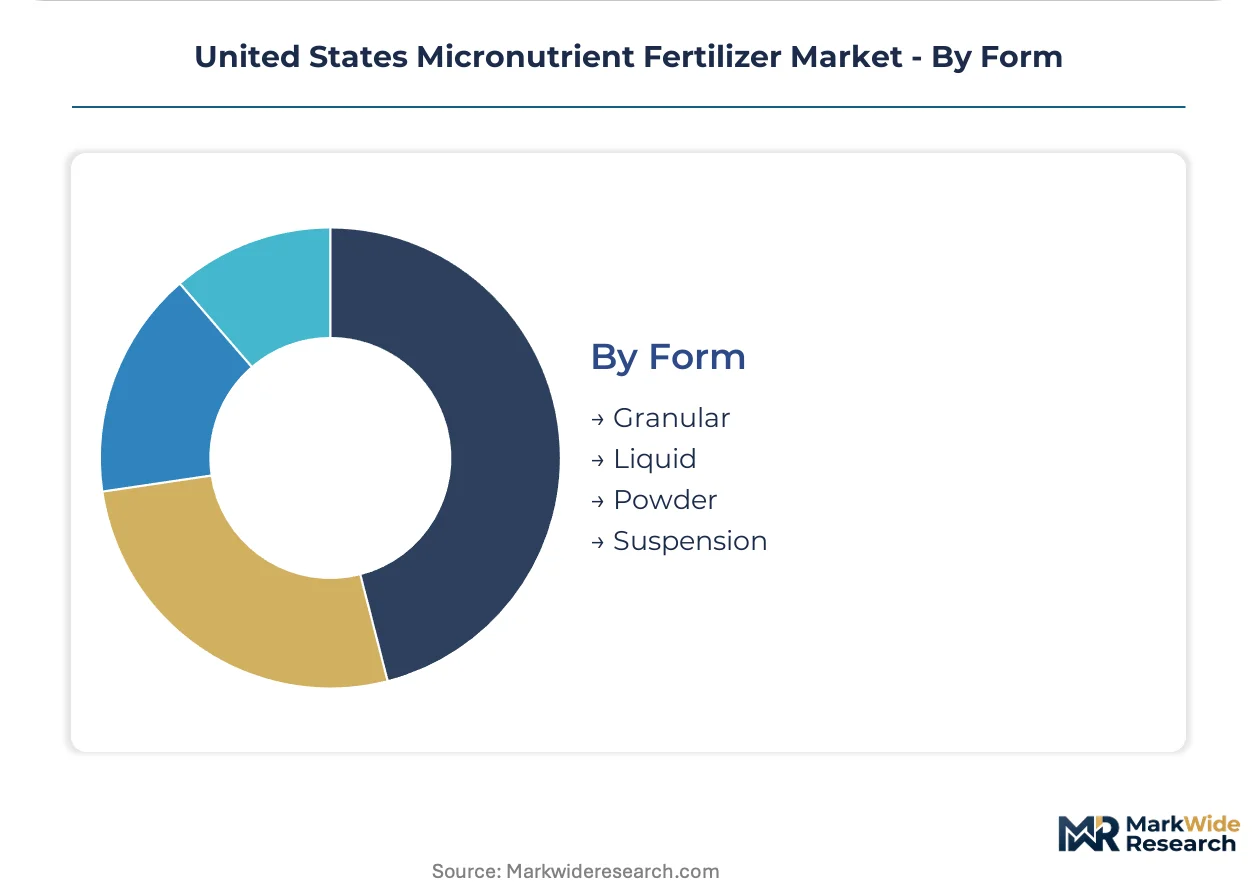
- Liquid:Solution and suspension formulations compatible with fertigation systems, spray tanks, and variable-rate injection equipment. California Central Valley vegetable producers and Florida citrus operations lead adoption for precision timing and uniform distribution.
- Granular:Dry products integrated with bulk NPK blends or applied as standalone broadcast materials. Midwestern corn-soy rotations depend on granular zinc and manganese through cooperative blending infrastructure.
- Powder:Fine crystalline products for dissolution in spray tanks or integration with specialty fertilizer blends. Turf and ornamental segments favor powder iron and manganese for rapid tank mixing and foliar application.
- Suspension:Concentrated liquid formulations with extended stability for high-volume field application. Emerging adoption in Great Plains wheat operations seeking liquid compatibility with existing sprayer fleets.
Granular formulations lead in volume terms, with liquid forms gaining fastest as fertigation infrastructure penetrates specialty crop zones and precision equipment upgrades accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States micronutrient fertilizer industry traces its modern scaling to post-World War II agricultural intensification in the Midwest Corn Belt, where soil testing programs first identified systematic zinc deficiencies in the 1950s and established the foundation for today's precision supplementation protocols.
Midwest Corn Belt
Iowa and Illinois drive volume demand through corn-soy rotations on calcareous soils where zinc and manganese deficiencies recur annually. The USDA Natural Resources Conservation Service cost-shares certified soil testing under nutrient management plans. Cooperative bulk blending infrastructure in Des Moines and Peoria anchors granular micronutrient distribution to NPK programs.
California Central Valley
Specialty vegetable and permanent crop producers deploy fertigation-compatible chelated formulations for drip-irrigated systems. The FDA Food Safety Modernization Act traceability rules pressure Salinas Valley growers toward documented micronutrient inputs. Fresno County operations increasingly bypass retail intermediaries for direct manufacturer relationships exceeding 5,000 acres.
Florida Peninsula
Citrus, sugarcane, and winter vegetable operations sustain year-round micronutrient demand through foliar and soil-applied programs. State water quality regulations for Everglades agricultural areas mandate controlled-release formulations that minimize phosphorus and micronutrient runoff. The Immokalee region concentrates procurement consolidation as national produce retailers require direct farm-level documentation.
Pacific Northwest
Washington and Oregon tree fruit and nut orchards require sustained copper and zinc supplementation where organic matter binds native minerals beyond root access. Washington State University extension programs certify crop advisors in woody perennial micronutrient protocols. The Yakima Valley and Hood River corridor concentrate precision application equipment adoption for variable-rate dosing.
Southeast Atlantic Coast
North Carolina and Georgia row crop and poultry integration operations supplement micronutrients through liquid injection systems compatible with existing sprayer fleets. State nutrient management regulations in the Chesapeake Bay watershed tributaries pressure growers toward documented application rates. The Coastal Plain region accelerates suspension formulation trials for wheat and cotton operations.
United States Micronutrient Fertilizer Market Competitive Landscape
Capital-heavy phosphate mining integrated producers compete with asset-light retail agronomy networks and specialty formulation designers across the United States micronutrient fertilizer market. The vendor base clusters around three strategic archetypes: upstream mining-integrated suppliers controlling sulfur and micronutrient feedstocks, retail-cooperative networks sustaining direct farmer relationships through soil testing and prescription blending, and digital-enabled precision agriculture platforms capturing high-value specialty crop accounts. Dominant competitive moves include backward integration into captive sulfur and micronutrient sourcing, plus geographic expansion through retail agronomy acquisitions in the Great Plains and Delta regions.
Within the mining-integrated tier, The Mosaic Company anchors domestic supply chains through Florida phosphate mining concentration. Among retail-cooperative networks, Nutrien Ag Solutions, Inc. and Helena Agri-Enterprises, LLC occupy positions sustained by direct farmer relationships and technical consultation infrastructure. These three entities exemplify the structural tension between upstream feedstock control and downstream agronomic service delivery that shapes competitive positioning across commodity grain and specialty crop segments.
| Leading Market Players |
|---|
| The Mosaic Company |
| The Andersons Inc. |
| Sociedad Quimica y Minera de Chile SA |
| Wilbur-Ellis Company LLC |
| Yara International ASA |
| Koch Industries Inc. |
| Nutrien Ag Solutions, Inc. |
| Helena Agri-Enterprises, LLC |
| Brandt, Inc. |
| Others |
Value Network & Pricing Analysis
Sulfur feedstock costs anchored to Florida phosphate mining concentration cascade through formulation economics into three-tier pricing structure across premium, standard, and economy levels. EPA pending chelator registration reviews and state nutrient management mandates in Iowa and Minnesota compress margin flexibility for mid-tier suppliers while concentrating pricing power with integrated upstream producers.
Pricing Analysis
Contract-based long-term offtage with volume-scaled discounts dominates procurement relationships between cooperative retailers and mining-integrated suppliers. Price differentiation hinges on chelation certification tier and precision application compatibility, with EDTA-complexed products commanding sustained premiums over sulfate salts. Cost compression in standard-grade formulations is intensifying because sulfur price volatility ties formulation economics to phosphate sector energy exposure. Small-scale specialty crop producers in California's Central Valley exhibit highest price sensitivity, whereas large Corn Belt operations above 10,000 acres leverage volume aggregation for least-cost sourcing.
Supply Chain Analysis
State fertilizer registration requirements and EPA chelating agent environmental fate assessments gate market access before product commercialization. Domestic supply draws from Florida phosphate mining concentration, Louisiana sulfur refinery output, and Canadian potash corridor integration. Raw material dependencies center on elemental sulfur, phosphoric acid feedstocks, and synthetic chelating agents. Single-source vulnerability concentrates in Florida's phosphate mining belt where Hurricane exposure disrupts sulfur and micronutrient feedstock availability. Distribution runs through cooperative bulk blending infrastructure in the Corn Belt and direct manufacturer relationships in California specialty crop zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States micronutrient fertilizer market presents a late-cycle quality story as retailer-driven sustainability verification and FDA traceability mandates shift procurement toward documented, certified formulations. Demand is concentrating in chelated and controlled-release products that command premium positioning through compliance alignment.
For Market Incumbents: Cement phosphate mining integration advantages through captive sulfur sourcing that insulates formulation costs from refinery output volatility. Deepen technical consultation infrastructure in the Corn Belt to defend against digital-enabled precision agriculture platforms capturing high-value specialty crop accounts. Prioritize biodegradability testing investments ahead of EPA chelating agent registration restrictions that threaten EDTA-based product lines. For New Entrants and Emerging Players: Launch via direct-to-grower digital platforms serving California and Florida specialty crop producers above 5,000 acres who bypass retail intermediaries for supply chain verification compliance. Target suspension formulation trials in Great Plains wheat operations where existing sprayer fleet compatibility reduces equipment conversion friction. White-space opportunity concentrates in natural organic complexing alternatives to synthetic chelators facing regulatory headwinds. For Investors and Strategic Acquirers: Consolidation pressure builds where retail agronomy networks lack technical consultation depth to serve precision agriculture adoption in high-value specialty crop zones. Long-term viability favors vertically integrated positions spanning Florida phosphate mining through Midwestern cooperative distribution. Acquisition target archetype: regional formulators with state registration portfolios and certified crop advisor relationships. Signal to watch is EPA chelating agent environmental fate assessment timeline as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Sourcing | Captive phosphate mining integration insulates The Mosaic Company from energy sector feedstock volatility. |
| Digital Farming Platform Deployment | Yara International ASA captures precision agriculture spending through real-time soil sensor integration in California. |
| Controlled-Release Formulation Development | Biodegradable chelator alternatives preempt EPA registration restrictions on EDTA environmental fate. |
| Direct Manufacturer Relationship Expansion | Nutrien Ag Solutions bypasses retail intermediaries for FDA traceability compliance in Florida produce channels. |
| Certified Crop Advisor Training Investment | Helena Agri-Enterprises addresses agronomic expertise scarcity limiting site-specific recommendation access. |
Research Methodology
Bottom-up crop rotation modeling reconciled against top-down mining-integrated supply tracking forms the analytical core of this study. Primary interviews with certified crop advisors, cooperative procurement managers, Florida phosphate mining operations executives, and California specialty crop farm operators combined with secondary validation from USDA NRCS conservation program databases, EPA water quality standard filings, state fertilizer registration records, and SEC 10-K disclosures from publicly traded suppliers. Triangulation between farmer-level application rate surveys and wholesale distribution volume data ensures segmentation integrity across formulation types and regional demand clusters.
Historical trendline analysis of corn-soy rotation micronutrient supplementation rates, specialty crop acreage expansion patterns, and chelated product adoption curves informed projection modeling across the analysis window. Segmentation dimensions span product type, application method, distribution channel, and form factor, with additional modeling of state regulatory compliance tier impacts. CAGRs derived from regression analysis of soil deficiency mapping penetration, precision equipment adoption curves, and retailer sustainability mandate rollout timelines. Industry-specific forecast inputs include EPA chelating agent review schedule assumptions and FDA Food Safety Modernization Act implementation pace.
Several conditions sit outside the modeled scope, including extreme weather disruption to Florida phosphate mining operations, abrupt EPA chelator registration revocation, and trade policy shifts affecting sulfur import economics. Forecasts reflect documented assumptions regarding state nutrient management incentive continuity and precision agriculture equipment cost depreciation curves. A model refresh is warranted upon material change in EPA environmental fate assessment outcomes or federal conservation program funding authorization levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Slow Release NPK Fertilizer Market
Fertilizers
Global Nitrogen Fertilizers Market
Fertilizers
Europe Fertilizers Market
Fertilizers
Potash Market
Fertilizers
Crop Micronutrients Market
Fertilizers
Argentina Fertilizer Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Blue-Green Algae Fertilizer Market
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
Asia-Pacific Specialty Fertilizer Market
Fertilizers
North America Controlled Release Fertilizer Market
Fertilizers
Global Green Fertilizers Market
Fertilizers
Fertilizer Applicators Market
Fertilizers
Vietnam Organic Fertilizer Market
Fertilizers
Africa Fertilizers Market