
 Africa Micronutrient Fertilizer Market | 2026-2036
Africa Micronutrient Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Micronutrient Fertilizer Market Outlook
Nigeria's emerging urea-micronutrient co-production corridor is fragmenting as new domestic blending capacity enters operation. OCP Africa leverages its Moroccan phosphate integration to anchor West African supply chains through coastal import terminals. Kynoch Fertilizer sustains decades of channel dominance in South Africa's high-value horticulture belt. Dangote Fertiliser Limited competes on manufacturing scale at its Lekki complex, while Yara International ASA navigates premium positioning through digital agronomy services bundled with micronutrient prescriptions.
Africa micronutrient fertilizers are formulated compounds containing essential trace elements—iron, zinc, manganese, copper—typically applied at rates below ten kilograms per hectare to correct soil deficiencies that macronutrient fertilizers cannot address. These products function by restoring enzymatic and chlorophyll processes in crops, with chelation technologies using EDTA or lignosulfonate carriers determining nutrient availability in alkaline soils. Zinc and iron product types currently lead volume due to widespread deficiency mapping across Sahelian cereal systems, while copper applications show structural acceleration in East African avocado and macadamia orchards where deficiency-induced dieback threatens export compliance. Foliar application methods command premium positioning relative to soil broadcasting, as precision spraying reduces lock-up in high-pH vertisols common to Ethiopia's highlands.
Kenya's Agriculture and Food Authority enforces fertilizer registration under Crops Act standards, while South Africa's Fertilizer Association of Southern Africa administers voluntary quality certification that increasingly determines supermarket supply chain access. Nigeria's National Agency for Food and Drug Administration and Control now requires micronutrient content labeling on all imported blends, tightening informal market participation. Stakeholders must monitor how harmonized fertilizer regulations under the African Continental Free Trade Area reshape cross-border product registration costs and manufacturing location decisions.
Market Dynamics
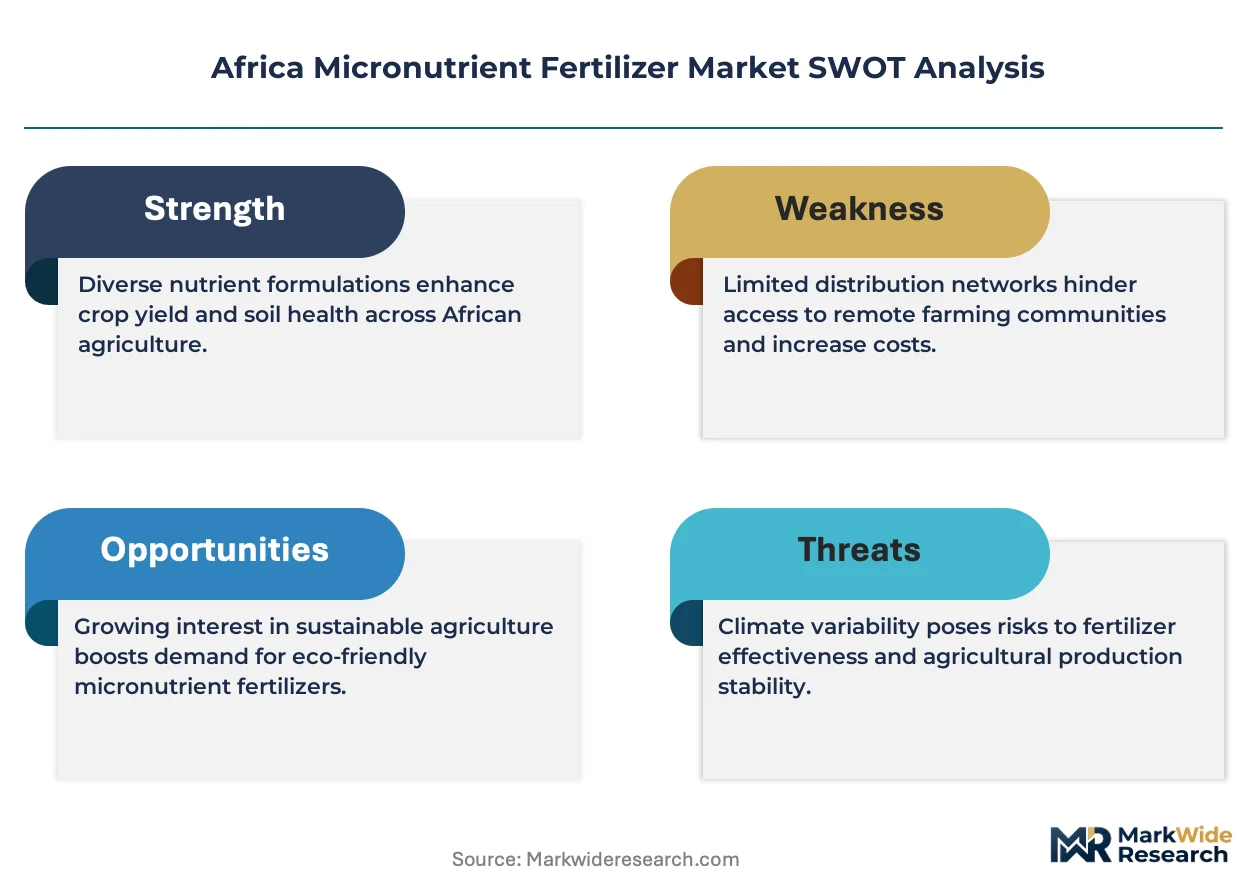
Chelated micronutrient formulations are displacing bulk oxide blends across Africa's commercial farming corridors, driven by alkaline soil chemistry and export crop quality mandates that render unprotected nutrients biologically unavailable.
Growth Catalysts
- Ethiopia's coffee quality premiums:Specialty exporters now require zinc-boron foliar protocols for bean size certification, pulling smallholder cooperatives into certified input networks.
- Kenya's Crops Act enforcement:Mandatory fertilizer registration is filtering counterfeit blends from formal channels, concentrating demand around verified micronutrient suppliers.
- EDTA chelation chemistry:Lignosulfonate carriers are losing ground to EDTA-complexed products in high-pH vertisols, where nutrient lock-up previously capped yield response.
Market Restraints
- Sulfuric acid feedstock volatility:Moroccan phosphate processors dominate sulfuric acid supply to West African blenders, exposing formulation costs to phosphate rock price swings.
- Limited analytical infrastructure:Soil testing laboratory density in Nigeria's northern cereal belt falls below one facility per 50,000 hectares, preventing precision deficiency mapping.
- Organic matter substitution:Compost and green manure applications in Tanzania's highland vegetable zones are partially displacing purchased micronutrient inputs among certified organic exporters.
Strategic Opportunities
- Rwanda's horticulture corridor:Avocado and macadamia plantings in the Eastern Province lack copper sufficiency programs, creating first-mover positioning for deficiency-corrective blends.
- Drone-based foliar application:Precision spraying contractors in Kenya's Rift Valley are reducing labor costs and improving coverage uniformity on tea terraces previously inaccessible to ground rigs.
- AfCFTA harmonized standards:Cross-border fertilizer registration simplification is enabling regional manufacturing location optimization for blenders serving multiple East African markets.
Industry Challenges
- Blender technician scarcity:Formulation chemistry expertise sufficient for chelated product manufacturing concentrates in South Africa and Morocco, constraining new entrant technical capacity.
- Multi-jurisdiction certification timelines:Separate registration requirements in Nigeria, Kenya, and Ghana extend product launch cycles to 18-24 months for pan-African suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Micronutrient Fertilizer Market |
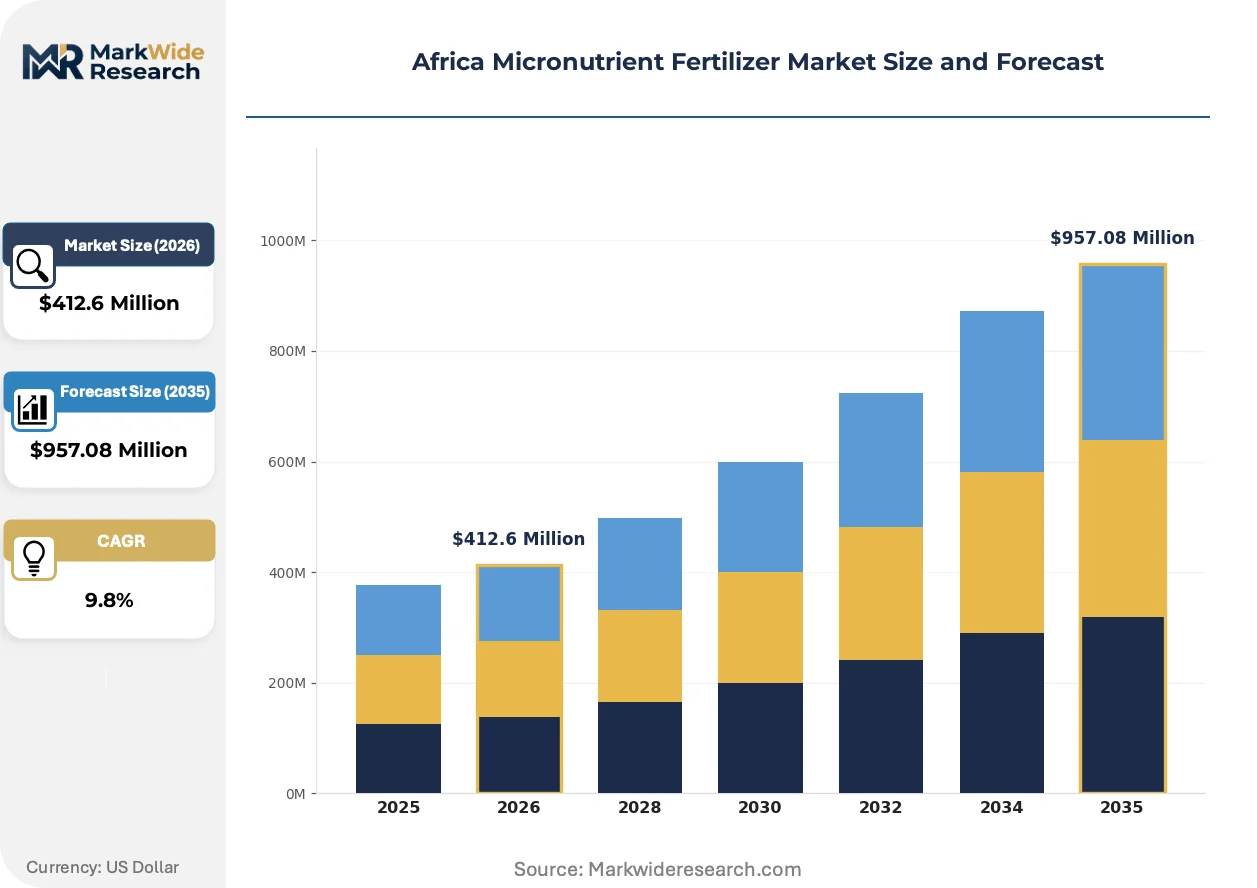
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $957.08 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron, Zinc, Manganese, Copper Application: Soil, Foliar, Hydroponics, Fertigation End User: Agricultural Cooperatives, Farmers, Distributors, Retailers Distribution Channel: Direct Sales, E-commerce, Agronomy Services, Wholesalers |
| Companies Covered | Kynoch Fertilizer, OCP Africa, Yara International ASA, Omnia Fertilizer, K+S Aktiengesellschaft, ICL Group Ltd, Gavilon South Africa (MacroSource, LLC), Dangote Fertiliser Limited, Unikeyterra Chemical, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Micronutrient Fertilizer Market Strategic Shifts
Digital soil mapping and variable-rate application technologies are compressing the information gap between agronomic science and smallholder practice, reshaping how micronutrient prescriptions reach fragmented farm bases.
Nano-encapsulated zinc oxide particles are rendering obsolete conventional bulk zinc sulfate applications in Senegal's groundnut basin. Commercial cooperatives in the Groundnut Basin are piloting nano-formulations at 30% lower application rates. The technology is compressing per-hectare input costs while maintaining tissue concentration targets for export certification.
Kenya's Agriculture and Food Authority is tightening heavy metal contamination thresholds under revised Crops Act schedules. Importers now face batch testing requirements for cadmium and arsenic in blended products. High-value horticulture exporters in Naivasha and Thika are shifting procurement toward certified European-standard products to preempt supermarket chain rejection.
Smallholder buying committees in Nigeria's Kaduna and Kano states are consolidating procurement through aggregator platforms that bypass traditional agro-dealer networks. These digital intermediaries bundle micronutrient blends with credit and extension services. The model is most visible among maize farmers accessing input financing tied to warehouse receipt systems.
Africa Micronutrient Fertilizer Market Segmentation
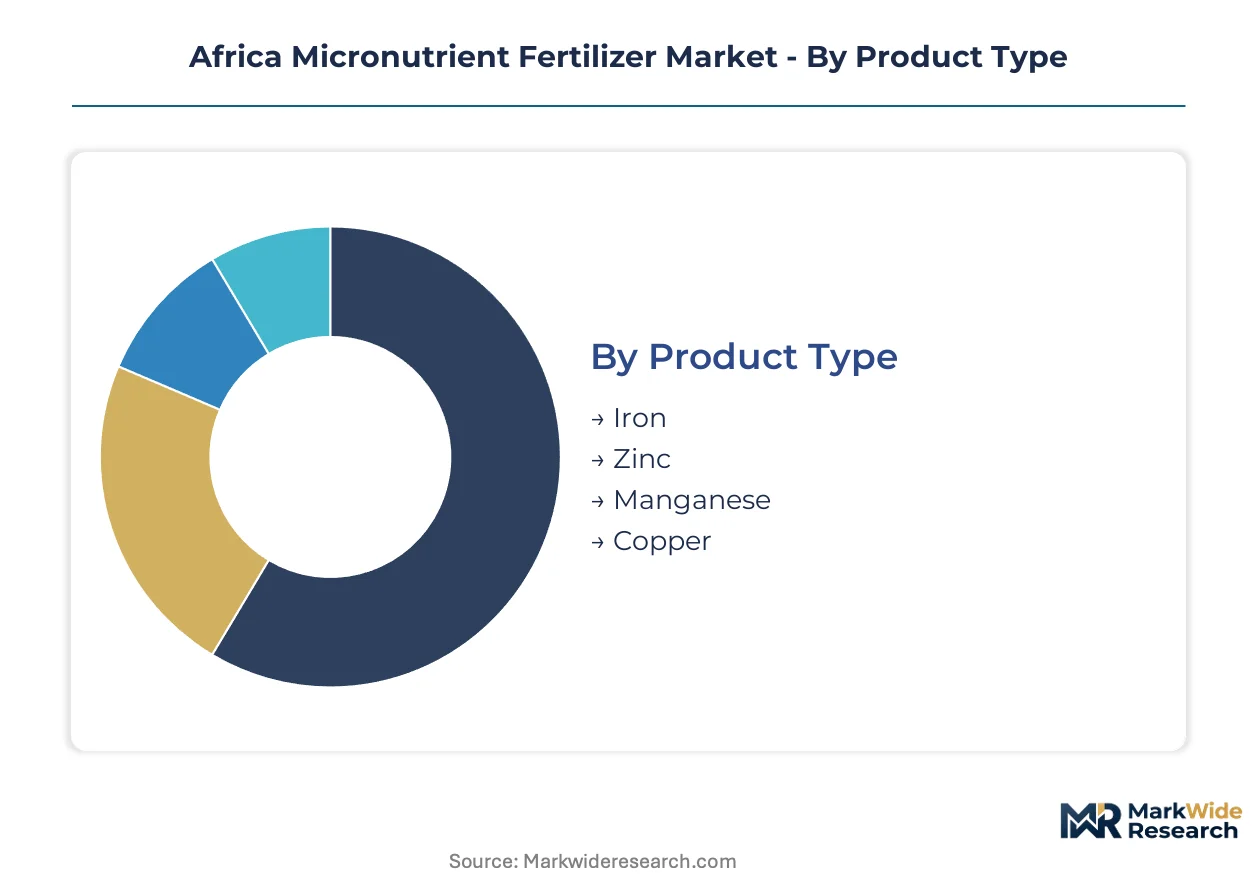
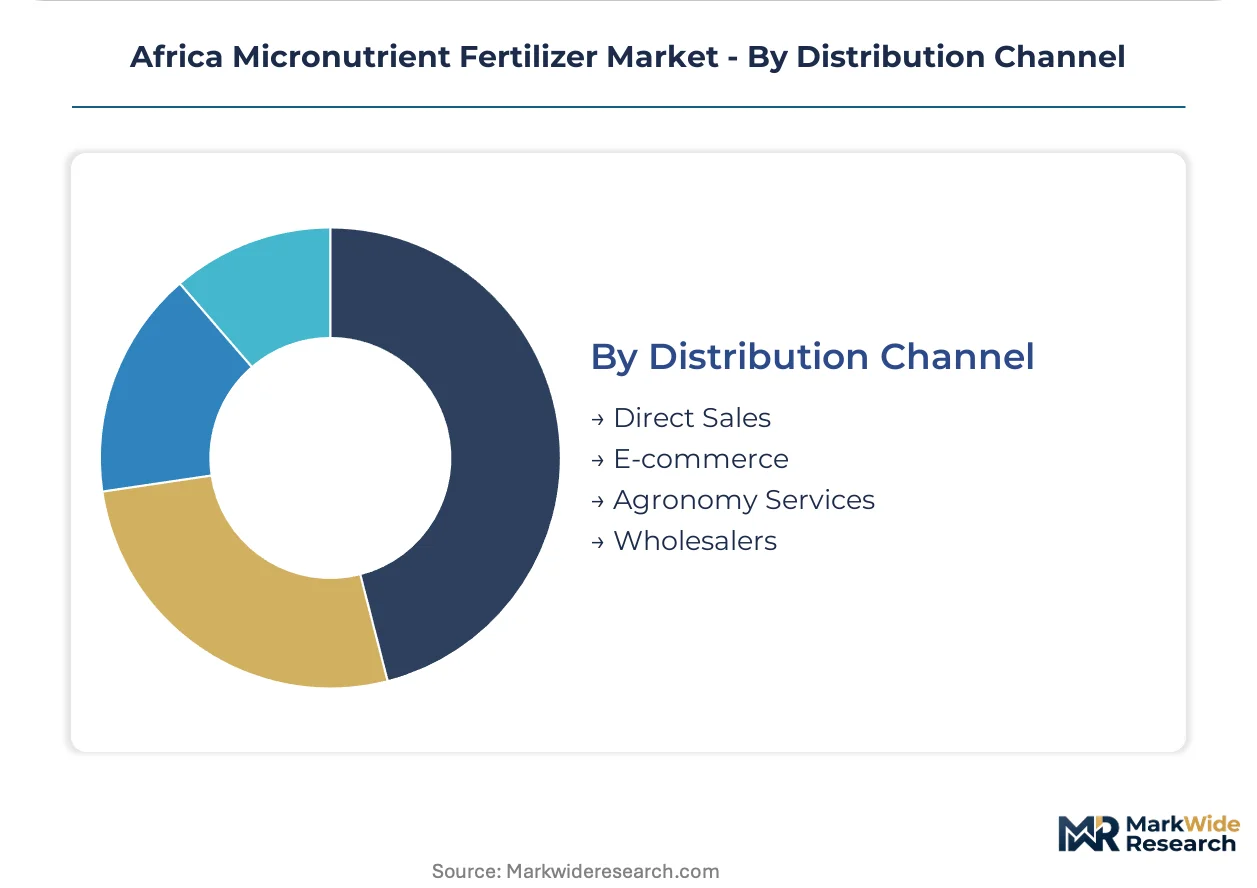
Micronutrient fertilizer demand fragments sharply across application methods and buyer types in Africa. Soil chemistry variations and export crop requirements pull formulations toward distinct technical specifications. Distribution channel evolution is compressing traditional agro-dealer margins while expanding direct manufacturer reach.
Product Type:
The use-case spectrum spans cereal fortification in Nigeria's maize belt through copper deficiency correction in Kenyan avocado orchards.
- Zinc:Sulfate and oxide forms dominate Sahelian cereal applications, with chelated EDTA variants capturing premium positioning in alkaline vertisols where lock-up renders bulk compounds biologically unavailable. Nigeria's northern smallholders now represent the largest incremental buyer segment for certified zinc-boron blends.
- Iron:Ferrous sulfate formulations address chlorosis in Ethiopian highland wheat systems, while lignosulfonate-chelated products serve Tanzanian vegetable exporters facing supermarket chain heavy metal thresholds. Foliar protocols are displacing soil broadcasting where pH exceeds 8.0.
- Manganese:Oxide-based products maintain cost positioning in bulk cereal applications across Ghana's northern region.
- Copper:Sulfate applications accelerate in Rwanda's Eastern Province horticulture corridor, targeting dieback prevention in expanding avocado and macadamia plantings.
The dominant share belongs to zinc, while copper is closing the gap fastest.
Application:
Cost tier separation runs from precision foliar spraying through broadcast soil amendment.
- Foliar:Aerial and ground-based precision spraying commands 40-60% price premiums over soil application, justified by coverage uniformity on Kenya's tea terraces and reduced nutrient lock-up in high-pH Ethiopian highlands. Drone contractors in the Rift Valley are compressing labor costs for previously inaccessible terrain.
- Soil:Broadcasting remains volume-dominant among Nigeria's cereal smallholders purchasing through aggregator platforms, though chelated blends are displacing bulk oxides as deficiency mapping improves.
- Fertigation:Drip-line injection gains traction in South Africa's high-value horticulture belt where water scarcity mandates precision delivery.
- Hydroponics:Controlled-environment vegetable producers in peri-urban Nairobi and Lagos deploy complete micronutrient solutions in recirculating systems.
Foliar application holds the premium positioning, while fertigation is expanding most quickly among commercial operations.
End User:
Customer type determines procurement scale and technical service intensity.
- Farmers:Nigeria's Kaduna and Kano smallholders now access micronutrient blends through digital aggregator platforms bundling credit, extension, and warehouse receipt financing, bypassing traditional agro-dealer networks. Individual plot sizes below two hectares fragment order quantities.
- Agricultural Cooperatives:Kenya's coffee and tea cooperatives consolidate procurement for zinc-boron foliar protocols required by specialty exporters for bean size certification, pulling smallholders into certified input networks.
- Distributors:Pan-African blenders maintain inventory positions in coastal import terminals serving landlocked markets.
- Retailers:Agro-dealer networks in Tanzania's highland vegetable zones face partial displacement from organic matter substitution among certified organic exporters.
Individual farmers command the largest addressable base, while cooperatives are gaining share fastest through export-linked certification requirements.
Distribution Channel:
Supply concentration varies from manufacturer-direct relationships through fragmented wholesale networks.
- Direct Sales:OCP Africa and Yara International ASA anchor West African supply chains through coastal import terminals, with digital agronomy services bundled to secure micronutrient prescriptions. Manufacturing scale at Dangote's Lekki complex supports direct large-account relationships.
- Agronomy Services:Precision spraying contractors in Kenya's Rift Valley combine application equipment with technical recommendations, capturing margin from both product and service.
- Wholesalers:Traditional networks persist in Nigeria's northern cereal belt where infrastructure gaps limit manufacturer reach.
- E-commerce:Input financing platforms in Kaduna and Kano states consolidate smallholder demand through mobile ordering systems.
Direct sales maintain the dominant volume position, while e-commerce is climbing the fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kenya's Agriculture and Food Authority anchors East African regulatory frameworks for micronutrient fertilizer registration. The country's Crops Act enforcement is filtering counterfeit blends from formal channels. National regulators across the continent are tightening content labeling and heavy metal thresholds.
Nigeria
Northern cereal belt smallholders now represent the largest incremental buyer segment for chelated micronutrient blends, particularly zinc-boron formulations for maize. The National Agency for Food and Drug Administration and Control mandates micronutrient content labeling on all imported blends. Kaduna and Kano states host digital aggregator platforms bundling credit, extension, and warehouse receipt financing for input procurement.
Kenya
Specialty coffee exporters require zinc-boron foliar protocols for bean size certification, pulling smallholder cooperatives into certified input networks. The Agriculture and Food Authority enforces fertilizer registration under Crops Act standards with revised heavy metal contamination thresholds. Naivasha and Thika horticulture clusters are shifting procurement toward certified European-standard products to preempt supermarket chain rejection.
South Africa
High-value horticulture belt demand sustains premium positioning for precision fertigation and foliar application systems. The Fertilizer Association of Southern Africa administers voluntary quality certification that increasingly determines supermarket supply chain access. Cape Town and Paarl wine regions drive copper and zinc demand for deficiency correction in export-oriented vineyards.
Ethiopia
Highland wheat systems require ferrous sulfate formulations to address chlorosis in alkaline vertisols exceeding pH 8.0. Federal agricultural extension services promote certified input networks through cooperative consolidation models. The Oromia and Amhara regional states concentrate coffee quality premium programs demanding micronutrient protocols for export certification.
Rwanda
Eastern Province avocado and macadamia plantings lack copper sufficiency programs, creating first-mover positioning for deficiency-corrective blends. Ministry of Agriculture and Animal Resources coordinates regional harmonization under East African Community fertilizer standards. Kigali and Bugesera districts anchor horticulture corridor expansion with drip-line infrastructure supporting precision micronutrient delivery.
Africa Micronutrient Fertilizer Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. Technical formulation expertise for chelated products concentrates in South Africa and Morocco, constraining new entrant capacity across the continent. The vendor base separates into phosphate-integrated multinationals, domestic manufacturing scale players, and precision agronomy service bundlers. Dominant competitive moves include coastal terminal anchoring for West African supply chains and digital platform development for smallholder aggregator access.
Among Morocco-based phosphate integrators, OCP Africa exemplifies coastal supply chain anchoring through import terminal infrastructure. Yara International ASA occupies a position within the precision agronomy service tier, bundling digital recommendations with micronutrient prescriptions. Dangote Fertiliser Limited represents domestic manufacturing scale advantage at its Lekki complex, competing on volume relationships with large agricultural accounts. These three anchors illustrate the structural segmentation between upstream resource control, technical service integration, and national-scale production capacity.
| Leading Market Players |
|---|
| Kynoch Fertilizer |
| OCP Africa |
| Yara International ASA |
| Omnia Fertilizer |
| K+S Aktiengesellschaft |
| ICL Group Ltd |
| Gavilon South Africa (MacroSource, LLC) |
| Dangote Fertiliser Limited |
| Unikeyterra Chemical |
| Others |
Value Chain & Pricing Dynamics
Sulfuric acid feedstock volatility from Moroccan phosphate processors determines both the spread between chelated premium blends and bulk oxide formulations and the geographic clustering of blending capacity around coastal import terminals. This single-source dependency for West African formulators compresses margins on standard-grade products while concentrating pricing power with phosphate-integrated suppliers.
Pricing Analysis
East African markets command 15-25% premiums over West African equivalents for identical EDTA-chelated zinc formulations, reflecting higher inland logistics costs from Mombasa and Dar es Salaam corridors. Three-tier pricing structure across premium chelated, standard sulfate, and economy oxide levels separates export-certified horticulture from cereal smallholders. Cost compression in standard-grade blends is intensifying because Nigerian domestic blending capacity expansion fragments procurement volumes. Agricultural cooperatives in Kenya's coffee belt show least price sensitivity due to export quality mandates, while Nigeria's northern cereal smallholders exhibit highest sensitivity and consolidate through digital aggregator platforms.
Supply Chain Analysis
Tariff exposure between Morocco and Nigeria's northern states dominates supply chain risk as OCP Africa's coastal terminal anchoring faces competition from Dangote's Lekki complex. Manufacturing concentration sits with Morocco, South Africa, and Nigeria as the three supply nodes serving distinct regional corridors. Raw material dependencies on phosphate rock, sulfuric acid, and EDTA chelating agents draw from captive Moroccan phosphate integration and Asian chemical suppliers. Distribution runs through coastal import terminals for landlocked markets, with digital platforms increasingly disintermediating traditional agro-dealer networks in Nigeria's Kaduna and Kano states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic matter substitution in Tanzania's highland vegetable zones and compost adoption among certified organic exporters present a credible substitute threat that incumbent micronutrient suppliers must navigate through differentiation and service bundling.
For Market Incumbents: Build regulatory certification moats around Kenya's Agriculture and Food Authority registration requirements and Nigeria's NAFDAC content labeling mandates. Defend against organic substitution by embedding micronutrient protocols into digital agronomy service bundles that demonstrate yield response superiority. Anchor coastal terminal positions to control sulfuric acid supply chains and limit new entrant feedstock access. For New Entrants and Emerging Players: Rwanda's Eastern Province copper deficiency programs in avocado and macadamia plantings represent the most penetrable entry point for first-mover positioning. Drone-based foliar application contracting in Kenya's Rift Valley tea terraces offers equipment-light service entry with immediate margin capture. Pursue go-to-market partnerships with agricultural cooperatives rather than fragmented individual smallholders to achieve procurement scale. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors technical formulation specialists with chelation chemistry expertise. Long-term viability rests on backward integration into phosphate processing or forward integration into precision application services. Watch for AfCFTA harmonized standards implementation as the inflection signal enabling regional manufacturing location optimization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Processing | OCP Africa's Moroccan phosphate integration anchors West African supply chains against feedstock volatility. |
| Digital Agronomy Platform Development | Yara International's bundled micronutrient prescriptions capture premium positioning through technical service differentiation. |
| Coastal Terminal Capacity Expansion | Import terminal anchoring at Mombasa and Lagos enables efficient landlocked market penetration. |
| Drone Application Service Launch | Precision spraying contractors in Kenya's Rift Valley reduce labor costs for tea terrace coverage. |
| Regulatory Certification Investment | Kenya's Crops Act enforcement filters counterfeit blends and concentrates demand around verified suppliers. |
Study Parameters
The analysis maps chelated formulation chemistry, bulk oxide applications, and precision foliar delivery systems, each validated through agronomists at agricultural cooperatives, procurement managers at pan-African blenders, regulatory affairs officers at national fertilizer authorities, and extension agents at federal agricultural services. Primary interview intelligence combined with secondary validation from customs and trade data, Fertilizer Association of Southern Africa certification records, Agriculture and Food Authority registration filings, and East African Community harmonization protocols. Bottom-up demand modeling from smallholder procurement patterns triangulates against top-down supply capacity assessments at coastal blending facilities.
Assumptions held fixed include current AfCFTA implementation timelines and existing Kenya Crops Act enforcement intensity, while sulfuric acid price trajectories and organic certification adoption rates were varied across sensitivity scenarios. Segmentation dimensions modeled span product type by chelation chemistry, application method by precision tier, end user by procurement scale, and distribution channel by digital penetration. CAGRs derive from regression analysis against historical deficiency mapping expansion and export crop quality mandate adoption. Forecast inputs incorporate Ethiopia's coffee certification program rollout and Nigeria's warehouse receipt system penetration.
Practitioners should monitor Moroccan phosphate processor pricing decisions and AfCFTA harmonization implementation for early signals of margin compression or regulatory simplification. Forecasts reflect assumptions about continued export quality premium expansion and digital platform consolidation among smallholder buyers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Global Potash Fertilizer Market
Fertilizers
Asia-Pacific Specialty Fertilizer Market
Fertilizers
Slow Release NPK Fertilizer Market
Fertilizers
Saudi Arabia Fertilizer Market
Fertilizers
Phosphate Fertilizers Market
Fertilizers
Global Urea Market
Fertilizers
Europe Fertilizers Market
Fertilizers
Fertilizer Tester Market
Fertilizers
North America Controlled Release Fertilizer Market
Fertilizers
Middle East and Africa Specialty Fertilizer Market
Fertilizers
Russia Fertilizers Market
Fertilizers
GCC Organic Fertilizer Market
Fertilizers
India Specialty Fertilizer Market
Fertilizers
Nitrogen Fertilizer Additives Market
Fertilizers
GCC Fertilizer Market
Fertilizers
Chelated Micronutrient Fertilizers Market