
 Global Specialty Fertilizer Market | 2026-2036
Global Specialty Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Fertilizer Market Foresight
Project finance for soil nutrient-as-a-service platforms is tilting competitive dynamics toward asset-light operators. Yara International ASA leverages its integrated ammonia-to-finished-product chain across multiple continents. ICL Group Ltd specializes in premium water-soluble and controlled-release formulations for high-value crop segments. Nutrien Ltd anchors North American distribution through its retail agronomy network and direct farm relationships.
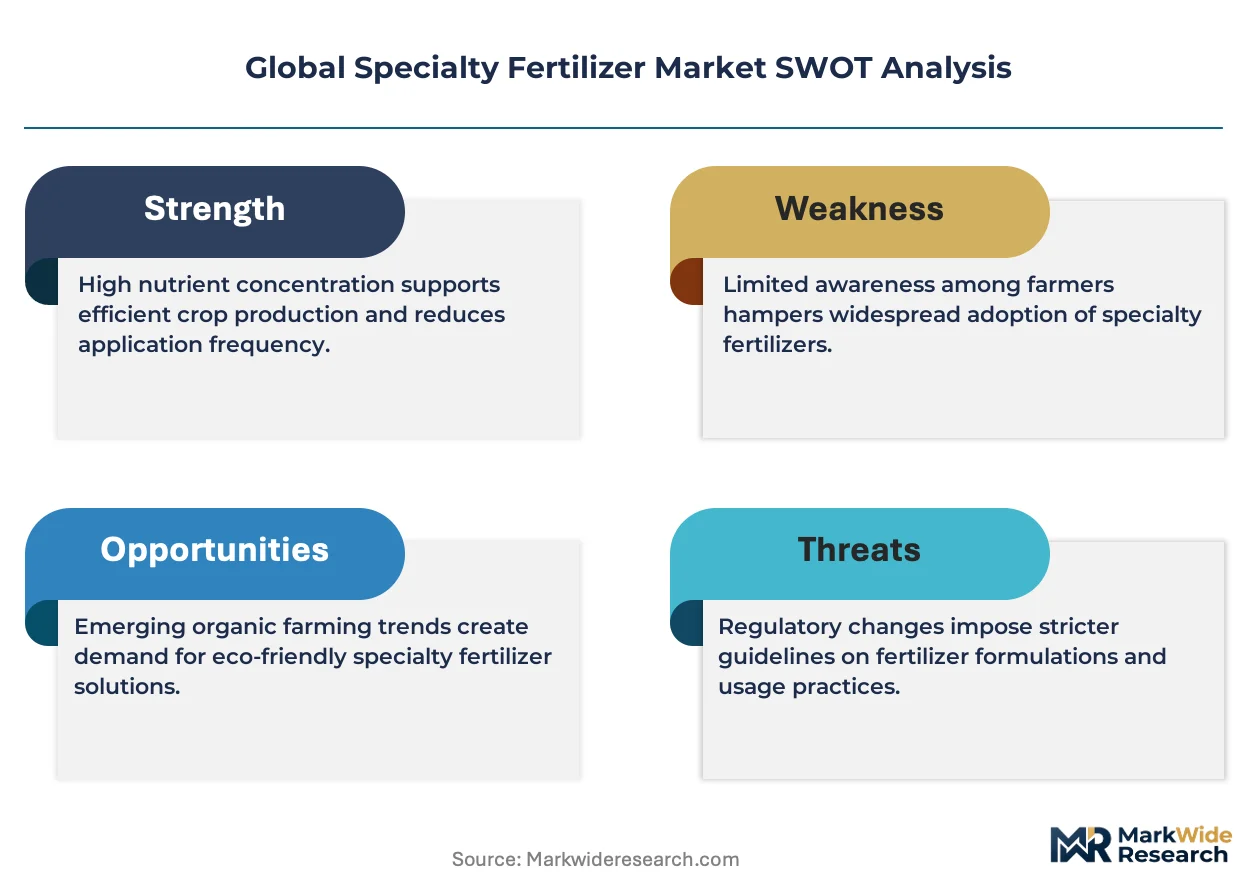
Specialty fertilizers are formulated products delivering targeted nutrient ratios—often including secondary and micronutrients such as sulfur, zinc, or boron—engineered for specific soil conditions, crop growth stages, or application methods like fertigation and foliar spraying. Their primary purpose is to optimize nutrient use efficiency, reduce environmental runoff, and support precision agriculture outcomes where bulk commodity fertilizers underperform. Nitrogen fertilizers and micronutrient fertilizers represent the deepest margin pools, with controlled-release and water-soluble forms commanding premium pricing in fruits and vegetables cultivation. Biofertilizers occupy a nascent but structurally important position as regulatory pressure on synthetic inputs intensifies across major agricultural economies.
The EPA oversees nutrient management and water quality standards affecting fertilizer application rates in the United States, while the EU Fertilizing Products Regulation harmonizes circular-economy nutrient recovery criteria across member states. India's FSSAI and state-level agricultural departments enforce micronutrient fortification mandates in key food crops, directly shaping product formulation requirements. Brazil's MAPA and ANA regulate fertilizer registration and water-use efficiency standards in the Cerrado and Matopiba expansion zones. Stakeholders must monitor how carbon border adjustments and Scope 3 emissions accounting reshape procurement criteria for nitrogen-intensive inputs.
Market Dynamics
Precision agriculture operators in Brazil's Cerrado and India's Punjab are consolidating procurement around controlled-release nitrogen and micronutrient bundles that tie product performance to verified yield outcomes rather than tonnage delivered.
Growth Catalysts
- EU Fertilizing Products Regulation:Circular-economy nutrient recovery mandates are accelerating demand for recovered phosphate and struvite-based formulations across member states.
- Fertigation infrastructure expansion:Drip irrigation penetration in Vietnam's Mekong Delta and Egypt's Nile Delta is pulling water-soluble specialty fertilizer uptake.
- India's FSSAI fortification mandates:Micronutrient enrichment requirements for wheat and rice are creating guaranteed offtake channels for zinc and iron formulations.
Market Restraints
- Ammonia feedstock volatility:Natural gas price swings at Louisiana and Rotterdam hubs compress nitrogen fertilizer margins unpredictably.
- Phosphate rock concentration:Moroccan and Saudi Arabian state-controlled suppliers dominate upstream phosphate concentrate, limiting formulation flexibility.
- REACH registration burdens:Novel biostimulant and microbial additive dossiers face multi-year toxicology timelines that delay EU market entry.
Strategic Opportunities
- Sub-Saharan Africa soil testing gaps:Kenya and Nigeria present white space for bundled soil-nutrient prescription services where extension infrastructure remains thin.
- Carbon credit stacking:Nitrification inhibitor coatings that cut N2O emissions qualify for compliance markets in California and voluntary registries.
- Drone-based foliar application:UAV service providers in Australia's wheat belt are creating last-mile distribution bypassing traditional retail agronomy.
Industry Challenges
- Formulation chemist scarcity:Controlled-release polymer coating expertise concentrates at a handful of European and Israeli research centers, constraining R&D bandwidth.
- Multi-jurisdiction registration parallelism:Brazil's MAPA, India's FCO, and Australia's APVMA operate non-harmonized efficacy trial protocols that duplicate field study costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Fertilizer Market |
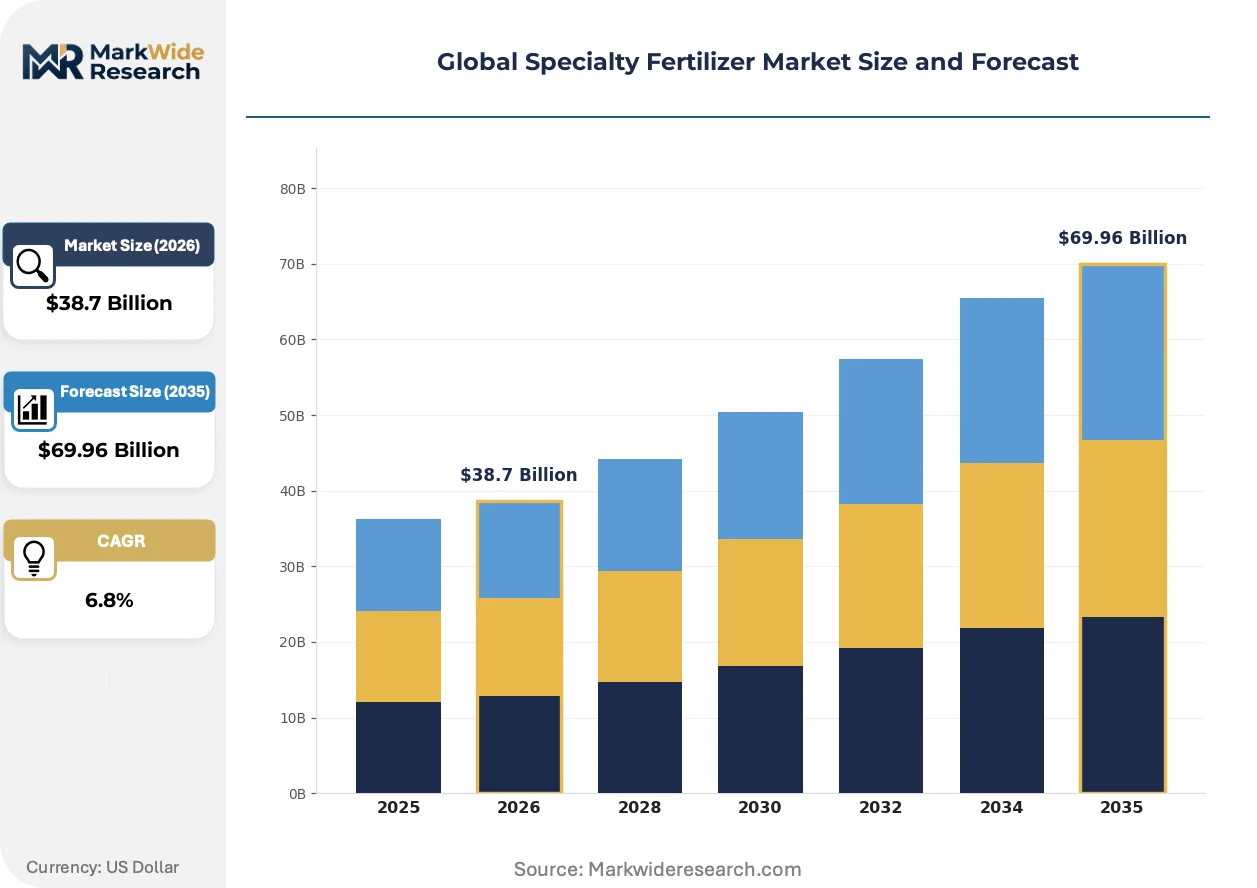
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogen Fertilizers, Phosphatic Fertilizers, Potassic Fertilizers, Micronutrient Fertilizers, Biofertilizers Crop Type: Cereals, Fruits & Vegetables, Oilseeds, Pulses, Plantation Crops Fertilizer Form: Granular, Liquid, Water Soluble, Slow Release, Controlled Release Application Method: Foliar Feeding, Soil Application, Seed Treatment, Drip Fertilization |
| Companies Covered | Yara International ASA, ICL Group Ltd, Nutrien Ltd, The Mosaic Company, CF Industries Holdings, Inc., K+S Aktiengesellschaft, OCP Group, SQM SA, EuroChem Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Fertilizer Market Shifts & Advancements
Biologicals and precision application hardware are converging to displace broadcast synthetic application as the default nutrient delivery paradigm in high-value cropping systems.
Polymer-coated urea with temperature-responsive release kinetics is rendering obsolete conventional split-application nitrogen programs in Chinese greenhouse vegetable operations. Shandong and Hebei province growers are adopting single-dose basal applications that match nitrogen availability to crop phenological stages. This compression of application labor is accelerating farm-scale consolidation as smaller holdings cannot amortize coated product premiums.
EPA's revised Waters of the United States rule and state-level nitrate load reduction targets in Iowa and Minnesota are forcing precision placement investments. Fertilizer retailers are retrofitting spreaders with real-time prescription maps and variable-rate actuators to maintain application permits. The compliance burden falls heaviest on corn-soy operations in the Upper Mississippi Basin where watershed nutrient trading schemes are emerging.
Soil-nutrient-as-a-service contracts are replacing upfront product purchases among Brazilian soybean cooperatives in Mato Grosso. Agronomy providers assume input cost risk and capture upside through yield-linked performance fees. This transfers working capital pressure from capital-constrained growers to distributors with balance sheet depth, reshaping credit relationships across the Cerrado farm credit system.
Global Specialty Fertilizer Market Segmentation
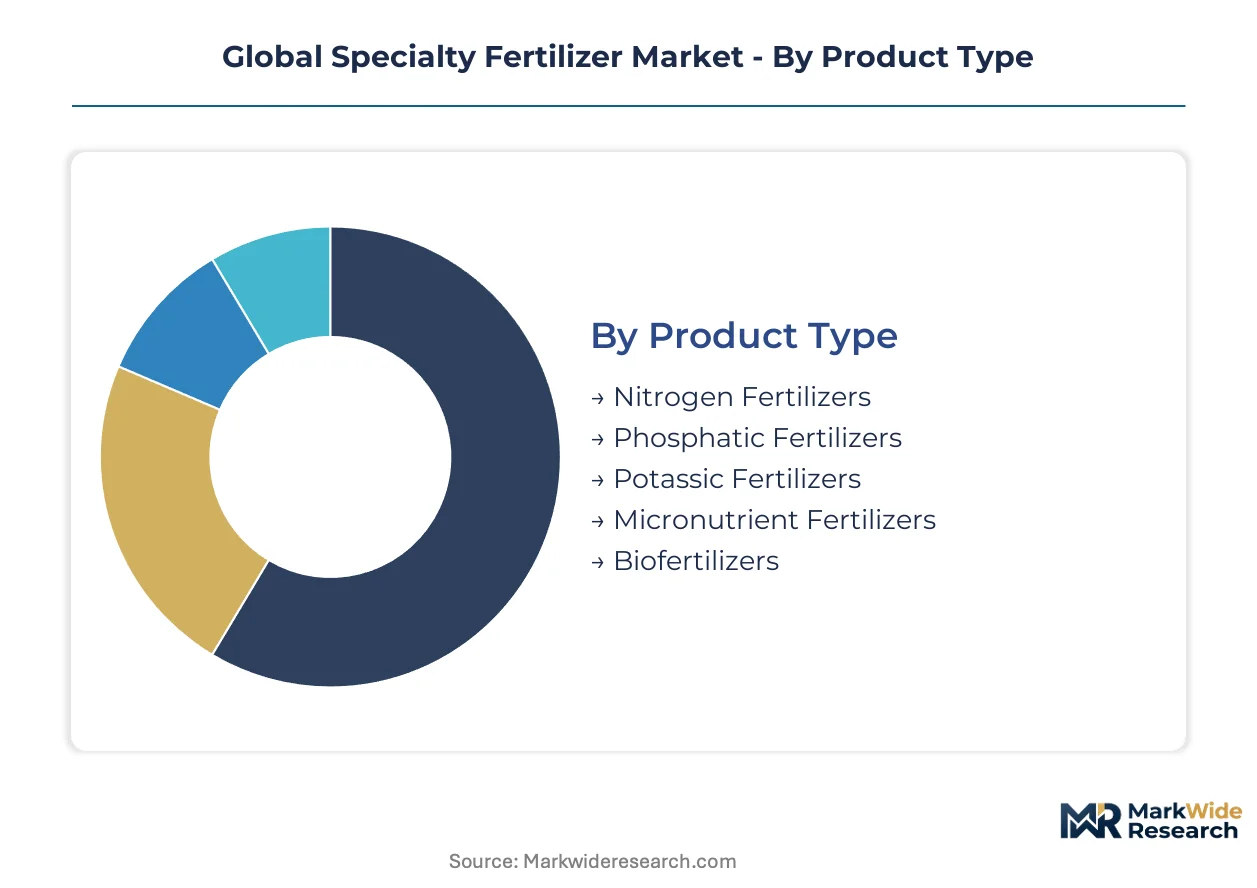
Specialty fertilizer segmentation reveals how formulation chemistry, crop economics, and application infrastructure intersect to create distinct margin profiles. Product type and fertilizer form divisions capture the deepest technology differentiation, while crop type and application method segments expose where precision agriculture investments concentrate procurement decisions.
Product Type:
Cost tier stratification across product categories separates premium micronutrient and controlled-release formulations from commodity nitrogen derivatives.
- Nitrogen Fertilizers:Urea-based and ammonia-derivative formulations dominate tonnage deployed, with polymer-coated variants commanding 40-60% price premiums over prilled urea. Demand concentrates in Brazil's Mato Grosso soybean belt and India's Punjab wheat corridor, where split-application labor costs drive adoption of single-dose controlled-release alternatives.
- Micronutrient Fertilizers:Zinc, boron, and iron chelate formulations address soil deficiency mapping in high-value cropping systems. Fruits and vegetables cultivation in Spain's Almería greenhouses and Turkey's Aegean tomato belt absorbs water-soluble micronutrient bundles tied to fertigation infrastructure.
- Phosphatic Fertilizers:Monoammonium phosphate and diammonium phosphate derivatives serve starter fertilizer applications in North American corn-soy rotations.
- Potassic Fertilizers:Muriate and sulfate of potash formulations support quality parameters in chloride-sensitive crops including tobacco and potatoes.
- Biofertilizers:Nitrogen-fixing rhizobium and phosphate-solubilizing bacterial inoculants occupy nascent positioning as EU Fertilizing Products Regulation tightens synthetic input thresholds.
Nitrogen fertilizers hold installed capacity. Micronutrient fertilizers are rotating up the share rankings.
Crop Type:
Application intensity and nutrient prescription complexity vary dramatically across crop economics, with high-value segments justifying precision formulation premiums.
- Fruits & Vegetables:Greenhouse tomato, pepper, and cucumber operations in the Netherlands, Mexico's Sinaloa valley, and China's Shandong province demand water-soluble NPK blends with micronutrient fortification. Fertigation compatibility and residue compliance for export markets to Germany and the UK drive formulation specifications.
- Cereals:Wheat, rice, and corn absorb the largest absolute tonnage, with India's FSSAI zinc fortification mandates creating guaranteed offtake for specific micronutrient grades. Basmati rice cultivation in Pakistan's Punjab and corn production in Iowa's Corn Belt prioritize nitrogen use efficiency over premium micronutrient packages.
- Oilseeds:Soybean and canola rotations in Brazil's Cerrado and Canada's prairies require sulfur and boron supplementation for oil content optimization.
- Pulses:Lentil and chickpea cultivation in Australia's Victoria and India's Madhya Pradesh leverages biological nitrogen fixation, limiting synthetic nitrogen demand.
- Plantation Crops:Oil palm in Indonesia's Sumatra and rubber in Thailand's southern provinces deploy specialized palm-specific formulations with magnesium and chlorine management.
Cereals hold installed capacity. Fruits and vegetables are climbing the fastest on margin contribution.
Fertilizer Form:
Physical formulation determines application equipment compatibility, nutrient release kinetics, and logistics economics across distribution networks.
- Controlled Release:Polymer-coated urea and sulfur-coated variants with temperature-responsive release kinetics match nitrogen availability to crop phenological stages. Chinese greenhouse operators in Hebei province compress labor costs through single basal applications replacing conventional split programs.
- Water Soluble:Crystalline NPK formulations with complete solubility for drip irrigation systems penetrate Vietnam's Mekong Delta mango orchards and Egypt's Nile Delta strawberry tunnels. Compatibility with EC-controlled fertigation systems determines product selection.
- Granular:Conventional prilled and compacted products remain default for broadcast application in mechanized row-crop systems.
- Liquid:UAN solutions and suspension fertilizers facilitate starter placement and sidedress flexibility in North American corn production.
- Slow Release:Urea-formaldehyde and isobutylidene diurea products with microbial decomposition kinetics serve turf and ornamental segments.
Granular formulations hold installed capacity. Controlled release is gaining share fastest on precision agriculture adoption.
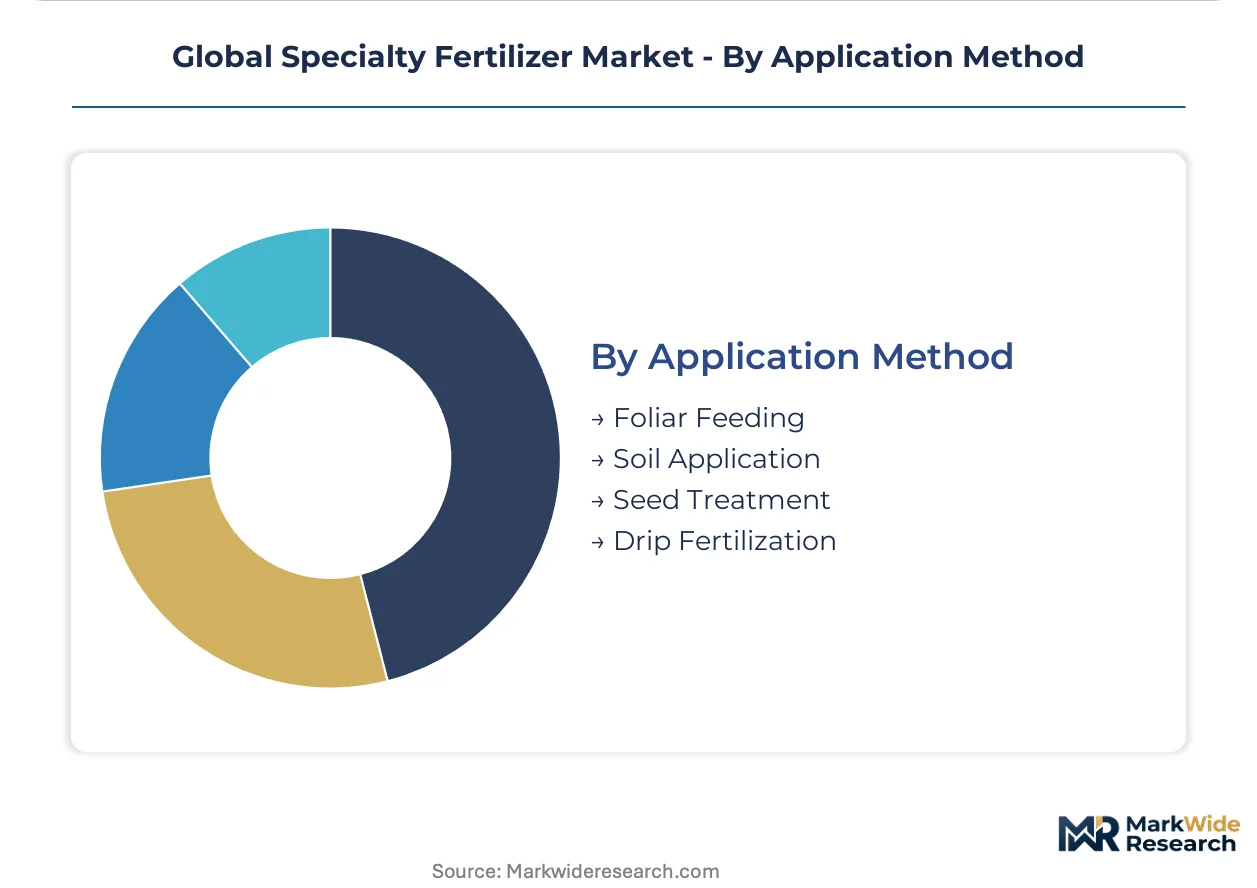
Application Method:
Equipment infrastructure and labor availability shape method selection, with capital-intensive precision systems concentrating in high-value cropping zones.
- Drip Fertilization:Fertigation integration with subsurface drip networks in California's Central Valley almond orchards and Israel's Negev desert vegetable operations demands complete water solubility and injection system compatibility. Filtration requirements and emitter clogging risks drive formulation purity standards.
- Foliar Feeding:UAV-based micronutrient application in Australia's wheat belt bypasses traditional retail agronomy through drone service provider networks. Chelate stability and droplet adhesion properties determine efficacy in variable weather windows.
- Soil Application:Broadcast and banded placement remains standard for broadacre cereals and oilseeds with conventional equipment.
- Seed Treatment:Starter nutrient and biological inoculant coatings on soybean and corn seed concentrate in Brazil's precision planting adoption zones.
Soil application holds installed capacity. Drip fertilization is expanding most quickly on irrigation infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in nitrogen and phosphate concentrates are reshaping procurement geography for specialty fertilizer value chains. Brazil and India remain net importers of high-analysis formulations, while Morocco and Saudi Arabia control upstream phosphate rock exports. Regulatory divergence across the EU, India, and Brazil is fragmenting product registration pathways.
Brazil
Mato Grosso soybean cooperatives are consolidating procurement around controlled-release nitrogen bundles tied to yield outcomes. MAPA registration requirements enforce efficacy trial protocols that delay novel biostimulant market entry. The Cerrado expansion zone around Lucas do Rio Verde absorbs premium micronutrient formulations for intensive corn-soy rotations.
United States
EPA Waters of the United States compliance is forcing precision placement investments across Iowa and Minnesota corn-soy operations. State-level nitrate load reduction targets in the Upper Mississippi Basin drive variable-rate spreader retrofits. The Central Valley almond belt in California demands water-soluble formulations compatible with subsurface drip networks.
India
FSSAI zinc fortification mandates for wheat and rice create guaranteed offtake channels for micronutrient grades. State agricultural departments in Punjab enforce application rate monitoring through soil health card schemes. Basmati rice cultivation clusters in Haryana prioritize nitrogen use efficiency over premium micronutrient packages.
China
Shandong and Hebei province greenhouse operators are adopting polymer-coated urea with temperature-responsive release kinetics. NMPA-equivalent provincial standards regulate microbial additive registration for biofertilizer categories. The Yangtze River Delta vegetable belt compresses labor costs through single-dose basal applications replacing split programs.
Germany
EU Fertilizing Products Regulation circular-economy mandates accelerate demand for recovered phosphate and struvite-based formulations. ECHA REACH registration burdens face multi-year toxicology timelines for novel biostimulant dossiers. The Lower Rhine agricultural corridor tests nutrient recovery from municipal wastewater streams for compliant fertilizer production.
Global Specialty Fertilizer Market Competitive Landscape
On the supply side, the industry is consolidating around integrated ammonia-to-finished-product chains and specialized formulation expertise. Tiered competitive positioning separates scale-driven nitrogen producers from premium micronutrient and controlled-release specialists. Three archetypes dominate: integrated upstream operators with captive raw material access, regional formulation specialists with agronomy service integration, and biological input innovators navigating regulatory complexity. Capacity expansion in polymer coating technology and strategic partnerships for biologicals licensing represent the dominant competitive moves.
Among integrated upstream operators, Yara International ASA exemplifies the ammonia-to-finished-product archetype with multi-continent manufacturing footprints. ICL Group Ltd occupies a position within the premium formulation tier, specializing in water-soluble and controlled-release technologies. Nutrien Ltd anchors the retail agronomy integration archetype through direct farm relationships and distribution network control.
| Leading Market Players |
|---|
| Yara International ASA |
| ICL Group Ltd |
| Nutrien Ltd |
| The Mosaic Company |
| CF Industries Holdings, Inc. |
| K+S Aktiengesellschaft |
| OCP Group |
| SQM SA |
| EuroChem Group |
| Others |
Supply & Pricing Matrix
Undercapacity in European polymer coating facilities drives supplier allocation discipline and amplifies premium pricing power for controlled-release formulations. Ammonia feedstock volatility at Louisiana and Rotterdam hubs compresses nitrogen fertilizer margins unpredictably, forcing buyers to absorb cost pass-throughs or switch to lower-analysis alternatives.
Pricing Analysis
Precision agriculture operators anchor pricing stratification across premium, standard, and economy tiers. Polymer-coated urea commands substantial markups over prilled urea based on certification grade and volume scale, while micronutrient bundles tied to verified yield outcomes resist commoditization. Cost compression in commodity nitrogen derivatives is intensifying because natural gas price swings erode producer margins. Smallholder cooperatives in India's Punjab exhibit highest price sensitivity, whereas Brazilian soybean operations in Mato Grosso prioritize performance guarantees over unit economics.
Supply Chain Analysis
Export-control regimes on phosphate rock concentrate limit formulation flexibility for non-integrated blenders. Moroccan and Saudi Arabian state-controlled suppliers dominate upstream phosphate concentrate, while natural gas availability in Trinidad and Egypt shapes nitrogen derivative economics. Single-source vulnerability concentrates in Moroccan phosphate rock exports. Distribution runs through regional formulation specialists with agronomy service integration and direct farm relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soil-nutrient-as-a-service platforms are reconfiguring the market around outcome-based contracting and interoperability between prescription algorithms and application hardware.
For Market Incumbents: Insulate polymer coating technology positions through captive R&D partnerships with Israeli and European research centers. Secure backward integration into ammonia production or long-term offtake agreements with Trinidad and Egyptian gas-based producers to offset feedstock volatility. Biological input innovators threaten formulation margins as EU Fertilizing Products Regulation tightens synthetic thresholds. For New Entrants and Emerging Players: Pursue bundled soil-nutrient prescription services in Kenya and Nigeria where extension infrastructure remains thin. Drone-based foliar application in Australia's wheat belt offers the most penetrable last-mile distribution bypass. Partner with UAV service providers to circumvent traditional retail agronomy relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across biofertilizer manufacturing as modular fermentation platforms reduce scale thresholds. Target regional formulation specialists with agronomy service integration and direct farm relationships in Brazil's Cerrado. Watch for nitrification inhibitor coating adoption in California compliance markets as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Production | Captive supply of natural gas-derived feedstock insulates margin compression at Louisiana and Rotterdam hubs. |
| Polymer Coating Capacity Expansion | Temperature-responsive release kinetics expertise concentrates in European and Israeli research centers. |
| Biological Input Licensing Agreement | Nitrogen-fixing rhizobium and phosphate-solubilizing bacterial inoculants navigate EU Fertilizing Products Regulation complexity. |
| Soil-Nutrient-as-a-Service Platform Launch | Yield-linked performance fees transfer working capital pressure from capital-constrained growers to distributors. |
| Drone-Based Foliar Application Partnership | UAV service providers in Australia's wheat belt bypass traditional retail agronomy distribution. |
Research Methodology
A standing panel of formulation chemists, procurement leads at Brazilian soybean cooperatives, distribution channel partners, and technical R&D directors at controlled-release specialists provided ongoing calibration. Primary interviews combined with secondary validation from customs and trade data, FAO fertilizer consumption statistics, SEC 10-K filings, and EU Fertilizing Products Regulation compliance databases. Bottom-up and top-down triangulation cross-checked regional production capacity against import dependency ratios.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, crop type, fertilizer form, and application method. CAGRs derived from fitted growth curves adjusted for regulatory inflection points and infrastructure investment cycles. Forecast inputs incorporated ammonia feedstock price trajectories and drip irrigation penetration rates in Vietnam's Mekong Delta and Egypt's Nile Delta.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing at Henry Hub and TTF, or phosphate rock export quotas from Moroccan state-controlled suppliers, would shift the trajectory. Material shifts in EU carbon border adjustment implementation timelines or Scope 3 emissions accounting standards for nitrogen-intensive inputs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
Calcium Ammonium Nitrate Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Global NPK Fertilizer Market
Fertilizers
United States Fertilizers Market
Fertilizers
Urea Fertilizers Market
Fertilizers
Phosphate Fertilizers Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Global Green Fertilizers Market
Fertilizers
France Fertilizer Market
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
Sulfur Fertilizer Market