
 Southeast Asia Fertilizer Market | 2026-2036
Southeast Asia Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Fertilizer Market Analytics
Indonesian state-backed producers is pivoting toward integrated urea-ammonia complexes to secure feedstock access. PT Pupuk Indonesia (Persero) leverages its sprawling archipelagic distribution network to sustain supply continuity across remote growing regions. Yara International ASA anchors its Southeast Asia presence through precision agriculture advisory services bundled with premium compound formulations. Southern Fertilizer JSC competes on phosphate-based specialty blends tailored to Mekong Delta rice systems.
Southeast Asia fertilizer encompasses nitrogenous, phosphatic, and potassic nutrient delivery systems formulated with specified N-P-K ratios, typically manufactured via Haber-Bosch ammonia synthesis or phosphate rock acidulation for soil amendment and crop yield optimization. Granular fertilizers dominate volume flows into large-scale plantation agriculture where mechanical spreading equipment requires uniform particle size distribution. Liquid fertilizers represent the fastest-growing product type among drip-irrigated vegetable operations in Vietnam and Thailand where fertigation systems permit precise nutrient dosing. Organic fertilizers command premium positioning in export-oriented fresh produce supply chains serving Japanese and South Korean supermarket procurement standards.
Indonesia's Ministry of Agriculture and the Thai Department of Agriculture enforce fertilizer registration and quality certification protocols that determine market access for imported products. Vietnam's CEA-aligned standards and Malaysia's Department of Agriculture labeling rules further fragment compliance requirements across national boundaries. Stakeholders must monitor evolving biofertilizer registration pathways as several ASEAN member states develop domestic microbial inoculant industries.
Market Dynamics
Indonesian oil palm plantation operators are consolidating hectarage under certified sustainable sourcing mandates, concentrating procurement volumes among fewer buyers with stricter supplier qualification protocols. This buyer-side concentration is compressing margins for traders while rewarding integrated producers with captive ammonia capacity.
Growth Catalysts
- EU Deforestation Regulation (EUDR) compliance:Plantation groups across Indonesia and Malaysia are expanding certified sustainable hectarage, driving demand for traceable fertilizer inputs that meet supply chain audit requirements.
- Mekong Delta intensification:Vietnamese rice operators are adopting multi-cropping cycles with higher nutrient replacement rates, lifting compound fertilizer application per hectare above traditional single-crop baselines.
- Controlled-release coating technology:Polymer-coated urea formulations reduce nitrogen volatilization losses in tropical high-rainfall zones, improving nutrient use efficiency for plantation managers facing labor constraints.
Market Restraints
- Natural gas feedstock volatility:Ammonia synthesis costs fluctuate with LNG import prices, exposing Indonesian and Malaysian urea producers to margin compression when global energy markets spike.
- Phosphate rock import dependence:Southeast Asian blenders rely on Moroccan and Jordanian phosphate concentrate, creating supply concentration risk at the upstream raw material layer.
- Soil acidification trade-offs: Repeated ammonium sulfate application in Indonesian peat soils accelerates pH decline, requiring lime amendments that raise total input costs for plantation operators.
Strategic Opportunities
- Myanmar agricultural reconstruction:Post-conflict rehabilitation of central dry zone farming systems will require substantial phosphate and potassic inputs as irrigation infrastructure restores.
- Biofertilizer registration pathway convergence:Several ASEAN member states are developing harmonized microbial inoculant approval frameworks, reducing cross-border product registration duplication costs.
- Drone-based variable-rate application:Integration of multispectral crop sensing with granular spreader drones enables precision nutrient placement in Indonesian smallholder cooperatives previously unreachable by mechanized spreading.
Industry Challenges
- Agronomic advisory capacity gaps:Plantation groups struggle to recruit soil scientists capable of interpreting tissue test data and prescribing site-specific nutrient blends across heterogeneous tropical soils.
- Multi-jurisdictional label compliance:Fertilizer registrants must maintain separate packaging and documentation for Indonesia's Ministry of Agriculture, Vietnam's CEA-aligned standards, and Malaysia's Department of Agriculture requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Fertilizer Market |
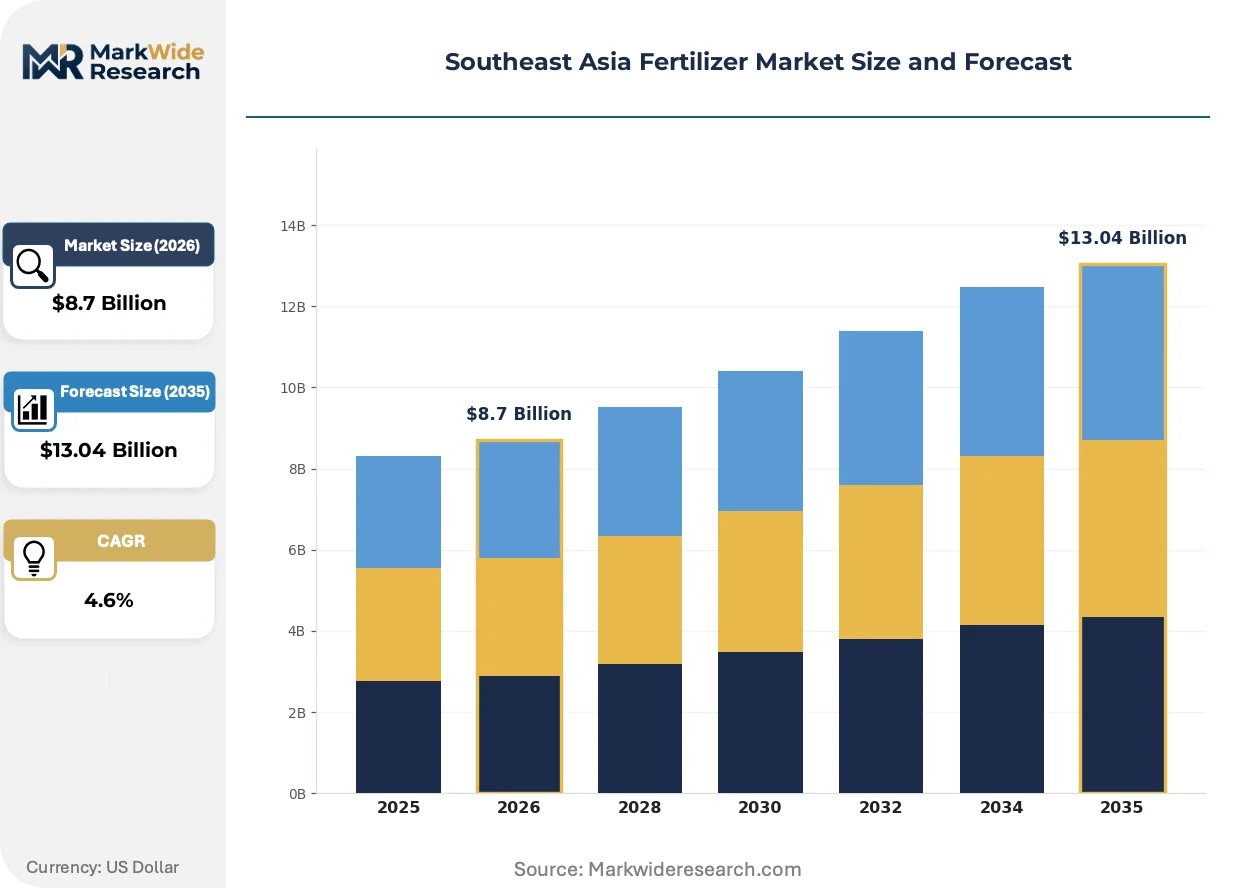
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Fertilizers, Granular Fertilizers, Slow-Release Fertilizers, Organic Fertilizers Application: Crops, Turf, Ornamental Plants, Gardens Distribution Channel: Wholesale, Retail, E-commerce, Direct Sales Customer Type: Agricultural Producers, Homeowners, Landscapers, Commercial Growers |
| Companies Covered | Mitsui & Co., Ltd. (Thai Central Chemical PCL), Nutrien Ltd., PT Pupuk Indonesia (Persero), Southern Fertilizer JSC, Ninh Binh Phosphate Fertilizer JSC, Yara International ASA, Song Gianh Corporation, Maaden, PT Petrokimia Gresik, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Fertilizer Market Evolving Landscape
Digital soil mapping and variable-rate application technologies are compressing the gap between agronomic theory and field-level execution across Southeast Asian plantation agriculture. These tools are enabling precise nutrient stewardship that aligns with tightening export market sustainability protocols.
Water-soluble fertilizer formulations is overtaking conventional granular products in Vietnamese greenhouse vegetable operations. These crystalline or liquid concentrates dissolve completely for drip fertigation systems, eliminating clogging risks in emitter networks. High-value tomato and pepper growers in Lam Dong province are adopting these inputs fastest, compressing working capital cycles through reduced inventory volumes and just-in-time mixing.
Indonesia's Ministry of Agriculture has tightened heavy metal contamination limits for phosphate-based fertilizers, mirroring stricter EU fertilizer product regulation benchmarks. This regulatory convergence is forcing importers to source from lower-cadmium phosphate rock deposits or invest in beneficiation washing capacity. Compound blenders serving certified palm oil supply chains are absorbing the highest compliance costs as traceability documentation requirements expand upstream.
Fresh produce exporters to Japanese and South Korean supermarket chains are mandating organic fertilizer documentation in procurement contracts. This certification-driven preference shift is displacing conventional compound purchases among Vietnamese dragon fruit and Thai mango packhouses supplying premium retail channels. The behavioral change is most visible in export-oriented growing districts where farm-gate prices justify input cost premiums for soil amendment traceability.
Southeast Asia Fertilizer Market Segmentation
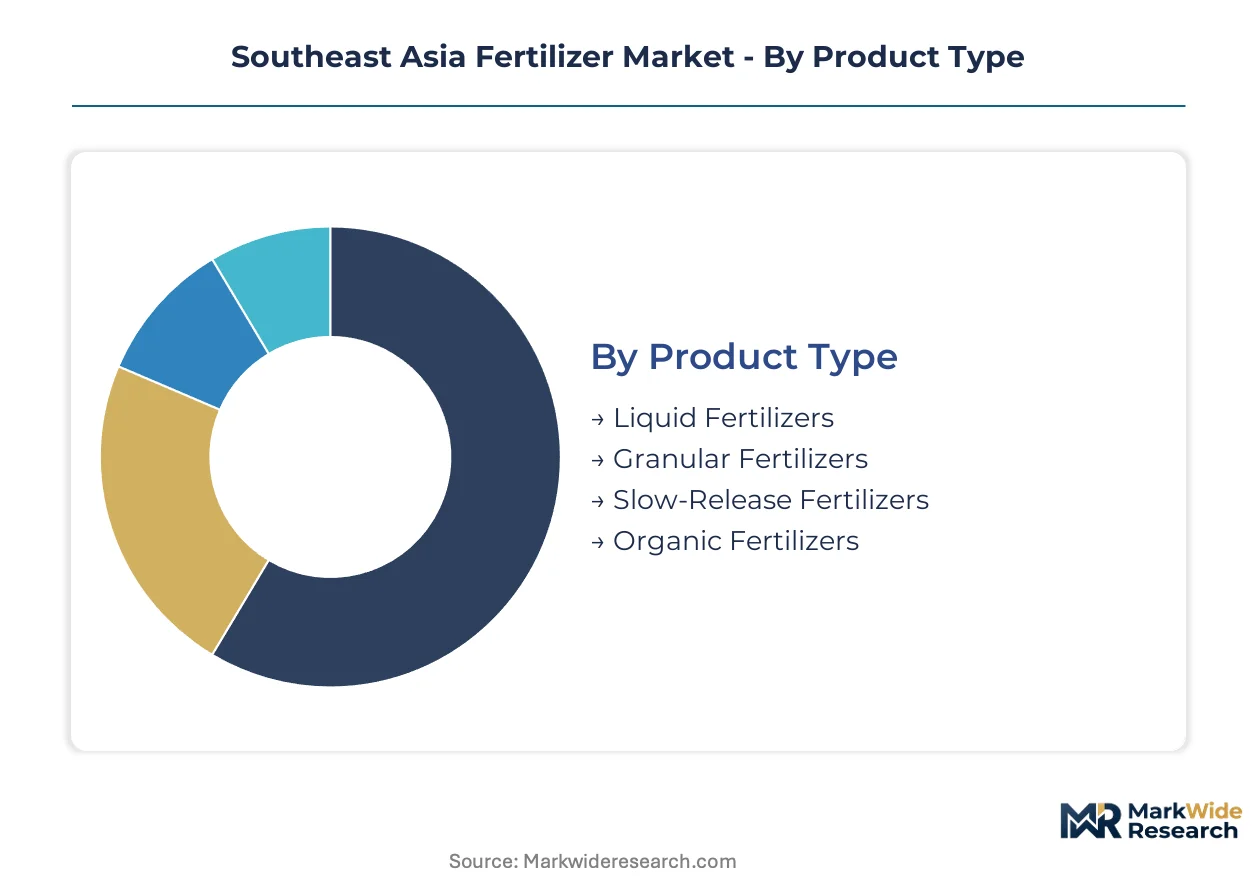
Fertilizer segmentation in Southeast Asia reflects divergent agronomic requirements across plantation scale, crop value tiers, and irrigation infrastructure maturity. Distinct nutrient delivery formats, application methods, and procurement channels shape competitive positioning for suppliers serving Indonesian oil palm conglomerates versus Vietnamese smallholder cooperatives.
Product Type:
Standardization dominates commodity nitrogen and phosphate compounds, while specialty coatings and organic certifications command formulation premiums across certification-sensitive supply chains.
- Granular Fertilizers:Uniform particle size distribution enables mechanical spreading across Indonesian and Malaysian oil palm plantations. Demand concentrates in Sumatra and Kalimantan belts where plantation operators require bulk volume flows compatible with aerial and ground-based application equipment.
- Liquid Fertilizers:Completely water-soluble concentrates dissolve for drip fertigation without emitter clogging. Vietnamese greenhouse vegetable operations in Lam Dong province adopt these formulations fastest as multi-cropping intensification demands precise nutrient dosing through automated irrigation systems.
- Slow-Release Fertilizers:Polymer-coated urea reduces nitrogen volatilization in tropical high-rainfall zones. Plantation managers facing labor constraints favor these formulations for extended nutrient availability.
- Organic Fertilizers:Composted and microbial-based soil amendments command premium positioning in export-oriented fresh produce supply chains serving Japanese and South Korean supermarket procurement standards.
Leading the category by volume: Granular Fertilizers. Expanding most quickly: Liquid Fertilizers.
Application:
Crop value tiers determine input cost absorption capacity, with export commodities tolerating premium formulations while subsistence crops remain price-sensitive.
- Crops:Rice, oil palm, and rubber plantations absorb the majority of compound fertilizer volumes across the region. Indonesian sustainable certification mandates drive traceable input documentation for palm oil supply chains.
- Turf:Golf course and sports field maintenance in Thailand and Malaysia generates steady demand for homogeneous granular blends with controlled release characteristics.
- Ornamental Plants:Nursery operations in Vietnam and Thailand serving export markets require micronutrient-complete formulations for flowering species.
- Gardens:Urban consumer segments in Jakarta, Bangkok, and Ho Chi Minh City purchase small-format packaged fertilizers for balcony and rooftop cultivation.
Volume concentration: Crops. Steepest expansion trajectory: Gardens as urban agriculture participation rises.
Distribution Channel:
Channel selection correlates with customer scale, with plantation groups bypassing intermediaries while smallholders depend on local retail networks.
- Wholesale:Bulk procurement by plantation conglomerates and agricultural cooperatives moves through archipelagic distribution networks. PT Pupuk Indonesia leverages captive logistics to sustain supply continuity across remote Indonesian growing regions.
- Retail:Provincial agrochemical dealers serve Vietnamese Mekong Delta rice operators and Thai smallholder vegetable growers with immediate availability and credit terms.
- E-commerce:Platform-based ordering gains traction among urban gardeners and commercial greenhouse operators seeking technical specification transparency.
- Direct Sales:Integrated producers with advisory capabilities bundle precision agriculture services with compound formulations for large-scale customers.
Dominant by throughput: Wholesale. Gaining share fastest: Direct Sales as advisory bundling deepens customer relationships.
Customer Type:
Procurement sophistication varies sharply across the customer base, from soil-test-driven nutrient prescriptions to undifferentiated commodity purchases.
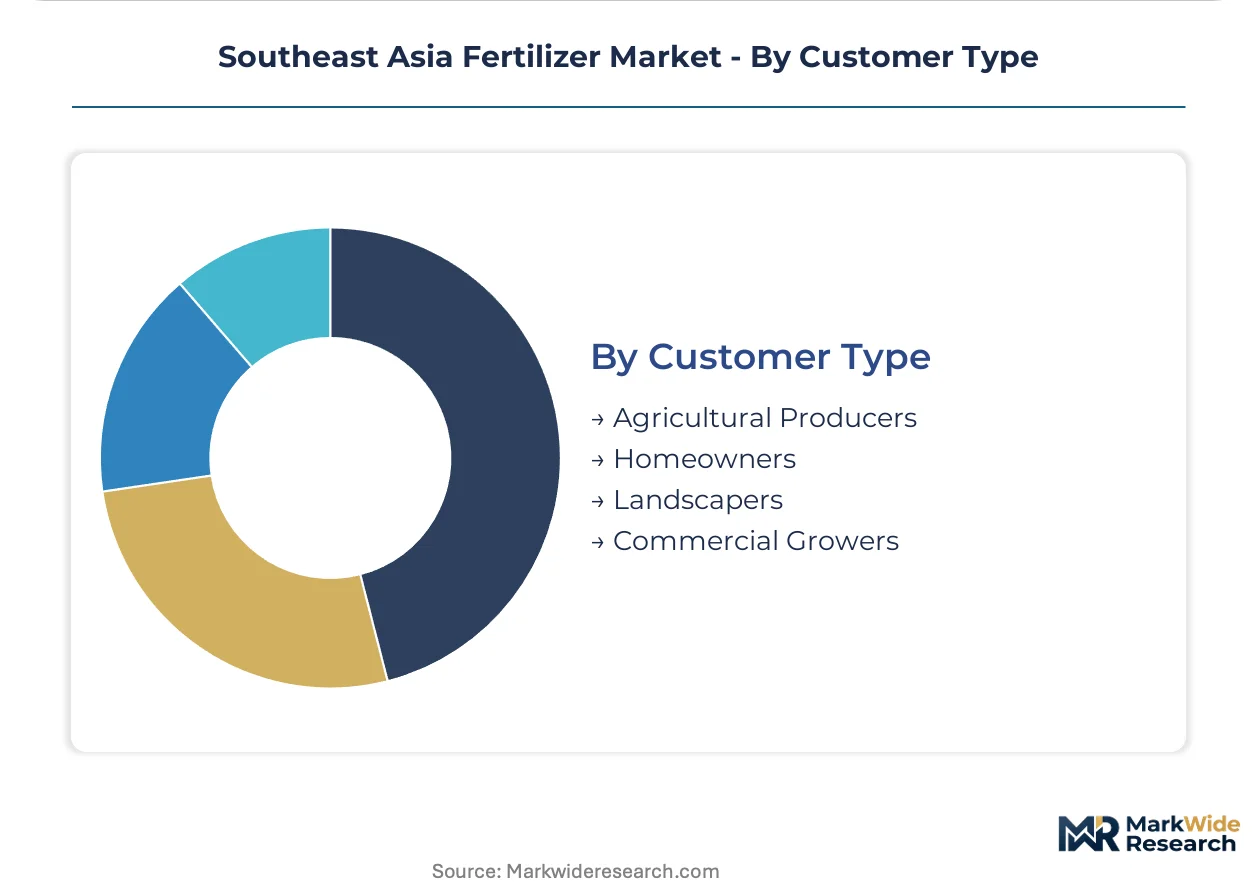
- Agricultural Producers:Plantation groups and cooperative associations represent the core volume buyers. Indonesian certified sustainable sourcing mandates concentrate procurement among fewer buyers with stricter supplier qualification protocols.
- Commercial Growers:Export-oriented dragon fruit and mango packhouses in Vietnam and Thailand mandate organic fertilizer documentation for Japanese and South Korean retail contracts.
- Landscapers:Municipal and private sector maintenance contractors in Malaysian urban centers require consistent product quality for contract compliance.
- Homeowners:Discrete packaged goods purchases for residential gardens represent marginal volume but higher per-kilogram margins.
Volume leadership: Agricultural Producers. Climbing the fastest: Commercial Growers as export certification requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural gas fields in Indonesia's Natuna and Malaysia's Sarawak basins anchor ammonia production capacity across the region. Plantation agriculture concentrates procurement volumes in Sumatra, Kalimantan, and Peninsular Malaysia corridors. National regulators enforce divergent registration protocols that fragment cross-border product flows.
Indonesia
Oil palm plantations in Sumatra and Kalimantan drive granular fertilizer absorption for certified sustainable supply chains. The Ministry of Agriculture enforces heavy metal contamination limits for phosphate-based imports, mirroring EU fertilizer product regulation benchmarks. PT Pupuk Indonesia leverages archipelagic distribution networks to sustain supply continuity across remote growing regions.
Vietnam
Mekong Delta rice operators adopt multi-cropping cycles with elevated nutrient replacement rates. The Ministry of Agriculture and Rural Development tightened micronutrient labeling requirements for imported blends, forcing reformulation of standard compounds. Lam Dong province greenhouse vegetable growers lead adoption of water-soluble concentrates for drip fertigation systems.
Malaysia
Peninsular plantation belts and Sabah oil palm estates absorb bulk nitrogen and phosphate volumes under Roundtable on Sustainable Palm Oil protocols. The Department of Agriculture labeling rules require separate packaging documentation from Indonesian and Vietnamese standards. Johor and Pahang state plantation corridors concentrate mechanized spreading equipment deployment.
Thailand
Central plains rice systems and northeastern cassava operations generate steady compound fertilizer demand. The Department of Agriculture enforces registration and quality certification protocols determining market access for imported products. Bangkok-based distributors serve provincial agrochemical dealers supplying smallholder vegetable growers with immediate availability and credit terms.
Philippines
Luzon rice terraces and Mindanao banana plantations absorb imported urea and complete fertilizer blends. The Fertilizer and Pesticide Authority regulates product registration with biofertilizer pathway development ongoing. Davao region packinghouses serving Japanese export markets mandate organic fertilizer documentation in procurement contracts.
Southeast Asia Fertilizer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty coating and organic certification segments. State-backed integrated producers with captive ammonia capacity compete against international traders supplying blended compounds. Three archetypes dominate: archipelagic distributors with logistics networks, precision agriculture advisors bundling services, and phosphate specialists serving Mekong Delta rice systems. Competitive moves concentrate on backward integration into natural gas feedstocks and geographic expansion through advisory-led direct sales channels.
Among Southeast Asian state-linked producers, PT Pupuk Indonesia (Persero) and PT Petrokimia Gresik represent integrated manufacturing archetypes with domestic distribution control. Yara International ASA anchors the precision agriculture advisory tier, bundling site-specific nutrient recommendations with compound formulations. Southern Fertilizer JSC exemplifies the specialty blender archetype, occupying a position tailored to Vietnamese rice system requirements. Mitsui & Co., Ltd. through Thai Central Chemical PCL sits within the regional trading and formulation segment, connecting Japanese technical standards with plantation procurement offices.
| Leading Market Players |
|---|
| Mitsui & Co., Ltd. (Thai Central Chemical PCL) |
| Nutrien Ltd. |
| PT Pupuk Indonesia (Persero) |
| Southern Fertilizer JSC |
| Ninh Binh Phosphate Fertilizer JSC |
| Yara International ASA |
| Song Gianh Corporation |
| Maaden |
| PT Petrokimia Gresik |
| Others |
Value Network & Pricing Analysis
Natural gas feedstock costs cascade through ammonia synthesis economics to stratify pricing across integrated producers and import-dependent blenders. LNG import price volatility in Indonesia and Malaysia compresses margins for non-integrated compounders while rewarding state-backed producers with captive Natuna and Sarawak basin supply.
Pricing Analysis
Advisory service bundling separates precision agriculture tiers from commodity spot transactions. Three-tier pricing structure across premium compound formulations, standard granular blends, and economy urea commodities reflects certification grade and after-sales technical support inclusion. Pricing pressure stems from buyer-side consolidation among Indonesian certified sustainable plantation groups demanding traceability documentation. Smallholder cooperatives in Vietnam's Mekong Delta exhibit highest price sensitivity, while export-oriented dragon fruit packhouses absorb premium organic fertilizer premiums for Japanese retail contract compliance.
Supply Chain Analysis
Single-source vulnerability sits with Moroccan and Jordanian phosphate rock concentrate feeding Southeast Asian blenders. Upstream ammonia production anchors in Indonesia's Natuna fields and Malaysia's Sarawak basins, while downstream distribution runs through archipelagic logistics networks and provincial agrochemical dealer channels. Raw material dependence on LNG imports, phosphate concentrate, and potash from Belarus and Russia creates commodity price volatility exposure. Plantation procurement offices in Sumatra and Kalimantan bypass intermediaries through direct offtake contracts, compressing trader margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EU Deforestation Regulation compliance costs and certified sustainable sourcing mandates force sub-scale traders and undifferentiated blenders toward exit or acquisition.
For Market Incumbents: Deepen backward integration into natural gas feedstocks or phosphate beneficiation capacity to defend margin position against LNG price spikes. Secure archipelagic distribution control through logistics network expansion into remote Indonesian growing regions. Threat: emerging biofertilizer entrants with microbial inoculant registration pathway advantages. Lever: certification investment for Roundtable on Sustainable Palm Oil traceability documentation. For New Entrants and Emerging Players: Drone-based variable-rate application technology offers a technology-first wedge into Indonesian smallholder cooperatives previously unreachable by mechanized spreading. Target Myanmar's central dry zone agricultural reconstruction as the most penetrable geography post-conflict. White-space: biofertilizer registration pathway convergence across ASEAN member states reducing cross-border duplication costs. Go-to-market: precision agriculture advisory bundling with hardware-enabled nutrient placement services. For Investors and Strategic Acquirers: Harmonized microbial inoculant approval framework development across ASEAN member states is the leading indicator that biofertilizer segment viability is crossing threshold. Long-term viability favors vertically integrated producers with captive ammonia capacity and archipelagic logistics control over pure-play traders. Acquisition target archetype: specialty phosphate blenders with Mekong Delta rice system formulation expertise and Vietnamese regulatory registration assets. Signal to watch: Indonesian Ministry of Agriculture heavy metal contamination limit enforcement accelerating import source switching.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Gas Feedstocks | Captive Natuna and Sarawak basin supply secures ammonia synthesis cost position against LNG import volatility. |
| Precision Agriculture Advisory Bundling | Yara International ASA's site-specific nutrient recommendation services deepen plantation customer relationships beyond commodity transactions. |
| Biofertilizer Registration Pathway Investment | ASEAN harmonized microbial inoculant frameworks reduce cross-border product approval duplication costs for emerging entrants. |
| Archipelagic Distribution Network Expansion | PT Pupuk Indonesia's remote growing region supply continuity sustains volume concentration in Sumatra and Kalimantan belts. |
| Controlled-Release Coating Technology Scale-Up | Polymer-coated urea formulations address nitrogen volatilization losses in tropical high-rainfall plantation zones. |
Research Methodology
Multi-period observation of plantation procurement volumes, import registration filings, and certified sustainable hectarage expansion anchored the trend analysis, supplemented by interviews with Indonesian state-backed producer procurement directors, Vietnamese Ministry of Agriculture regulatory affairs leads, Malaysian plantation group sustainability officers, Thai agrochemical dealer network managers, and Filipino fertilizer importer logistics coordinators. Secondary validation drew from ASEAN customs trade databases, Fertilizer and Pesticide Authority registration records, Roundtable on Sustainable Palm Oil certification disclosures, and EU Deforestation Regulation compliance documentation. Bottom-up volume triangulation across product type, application, and distribution channel segments converged with top-down macroeconomic anchoring.
Segment-weighting approaches applied differential growth assumptions across nitrogenous, phosphatic, and potassic product categories, with granular, liquid, slow-release, and organic format splits modeled throughout the forecast period. Application segmentation weighted rice, oil palm, and rubber plantation demand against emerging greenhouse vegetable and urban garden growth trajectories. Distribution channel dynamics incorporated wholesale plantation offtake, retail smallholder penetration, and direct sales advisory bundling trajectories. CAGRs derived from historical volume elasticity to plantation hectarage expansion, multi-cropping intensification rates, and regulatory-driven formulation shifts. Industry-specific inputs included LNG import price correlation coefficients and phosphate rock beneficiation cost curves.
Several conditions sit outside the modeled scope, including geopolitical disruption to Moroccan phosphate concentrate supply, abrupt ASEAN regulatory divergence on biofertilizer pathways, and unforeseen climate impacts on Indonesian peat soil acidity management protocols. Forecasts reflect documented assumptions about plantation certification mandate enforcement timelines and Myanmar agricultural reconstruction pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
Global Complex Fertilizers Market
Fertilizers
Vietnam Fertilizers Market
Fertilizers
Blue-Green Algae Fertilizer Market
Fertilizers
Indonesia Fertilizer Market
Fertilizers
Mineral Fertilizers Market
Fertilizers
Middle East and Africa Micronutrient Fertilizer Market
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
Asia-Pacific Specialty Fertilizer Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
China Controlled Release Fertilizer Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
EMEA Secondary Macronutrients Market
Fertilizers
Global Water Soluble Fertilizer Market
Fertilizers
China Fertilizers Market