
 China Organic Fertilizers Market | 2026-2036
China Organic Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
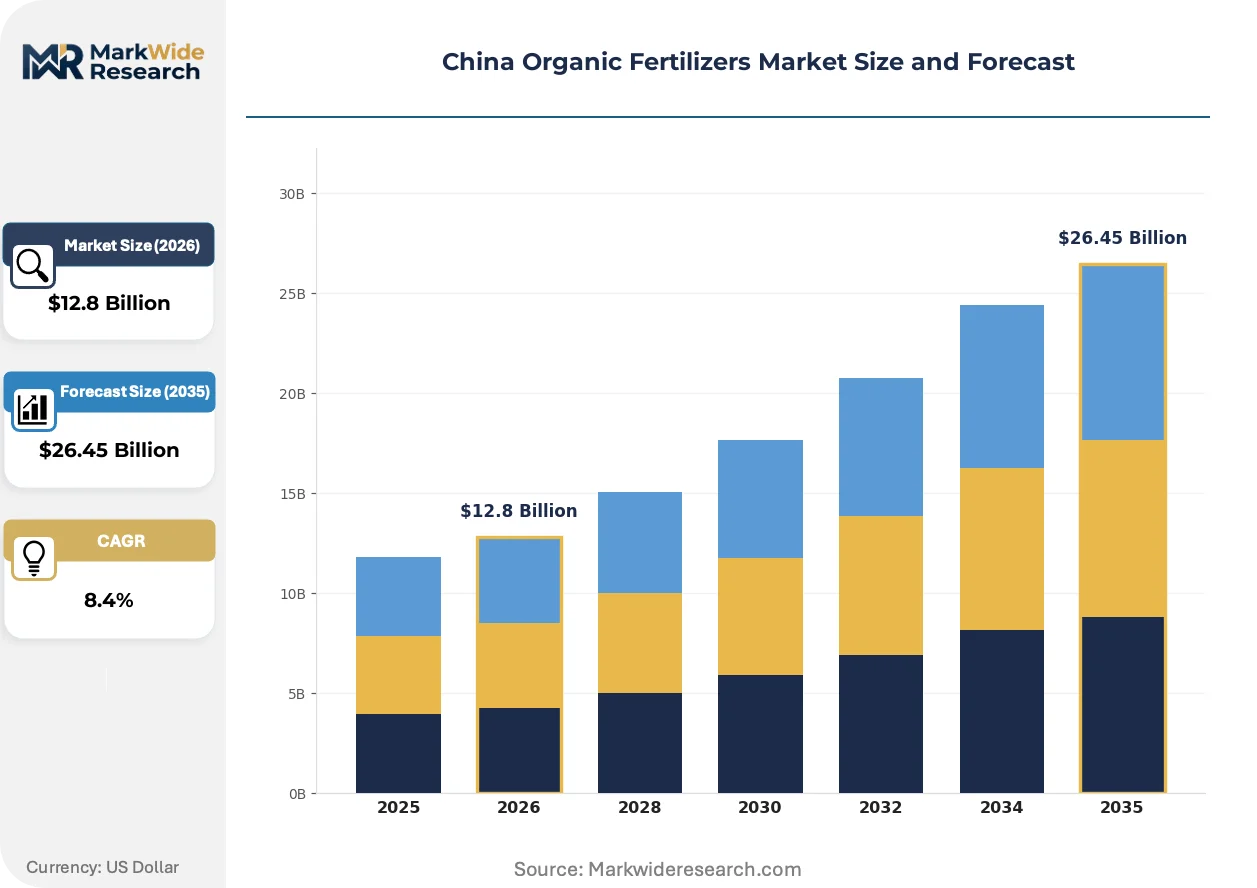
China Organic Fertilizers Market Outlook
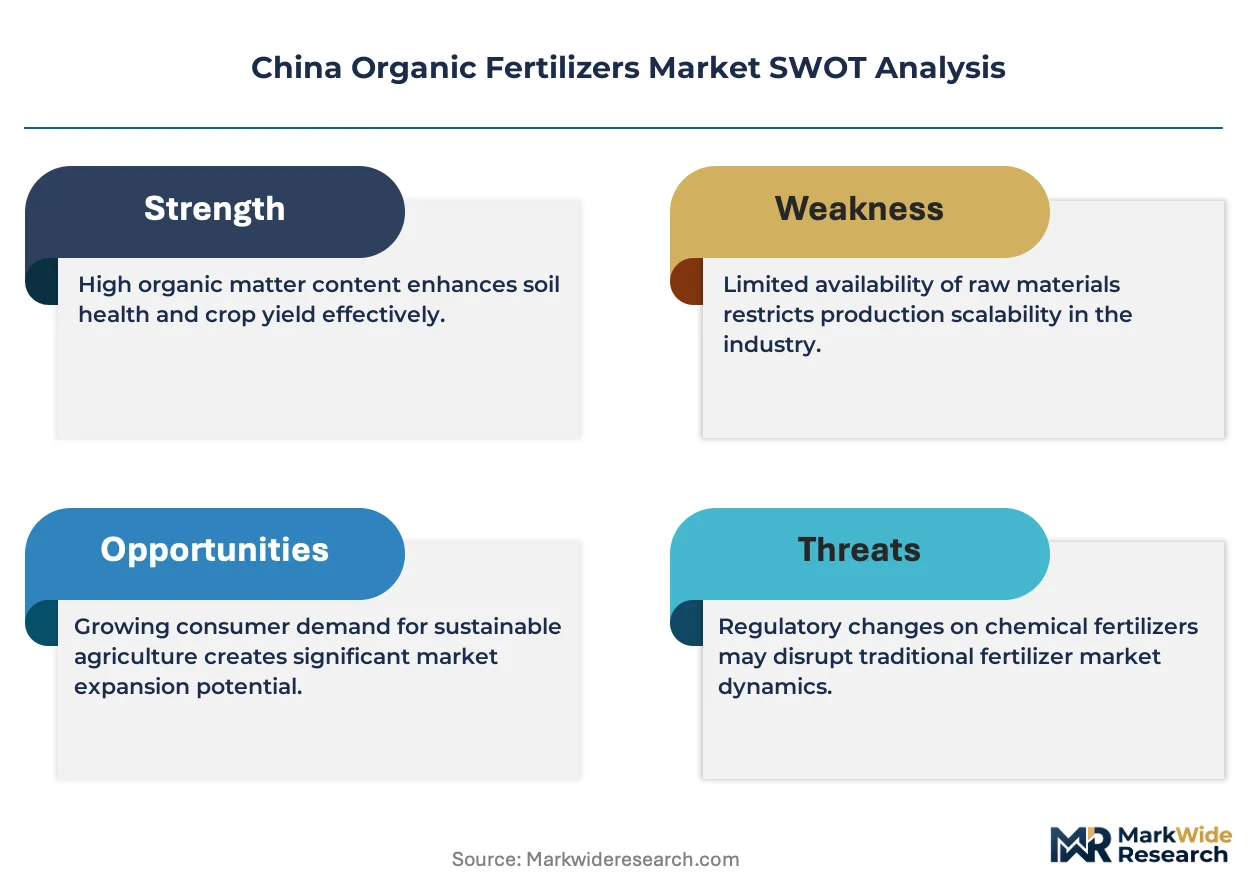
GB 20287-2006 microbial fertilizer standard is rotating competitive access in China's organic fertilizer sector, raising barriers for uncertified producers. Shandong Nongda Fertilizer Sci & Tech Co Ltd leverages its Shandong base to dominate regional compost supply chains. Genliduo Bio-tech Corporation Ltd anchors its position through specialized bio-fermentation technology. Rizhao Organic competes on seaweed-derived formulations for coastal horticulture zones.
Organic fertilizers encompass carbon-based soil amendments derived from plant, animal, or microbial biomass, typically containing humic acids, beneficial microorganisms, and macro or micronutrients in concentrations governed by China's NY 525-2012 organic fertilizer standard. These inputs restore soil organic matter, enhance microbial activity, and reduce chemical runoff in intensive cropping systems. Compost holds the largest volume share among product types due to mature supply infrastructure and lower per-ton production costs. Seaweed extracts command premium positioning in horticulture applications where trace element bioavailability drives grower willingness to pay. Biochar remains nascent but attracts R&D investment from producers targeting carbon-sequestering soil amendment claims in high-value fruit and vegetable sectors.
China's Ministry of Agriculture and Rural Affairs enforces NY 525-2012 quality thresholds while the Ministry of Ecology and Environment monitors runoff impacts under soil pollution prevention mandates. SAMR oversees labeling compliance and cracks down on fraudulent organic claims that distort buyer trust. China's dual carbon goals are channeling subsidy flows toward verifiable carbon-reducing fertilization practices. Stakeholders must track evolving provincial subsidy qualification criteria and certification reciprocity with importing jurisdictions to sustain market access.
Market Dynamics
China's dual carbon goals are restructuring organic fertilizer procurement, redirecting subsidy flows toward verifiable carbon-sequestering amendments and tightening compliance thresholds under GB 20287-2006 microbial standards. This regulatory pivot favors producers with certified bio-fermentation capabilities while marginalizing uncertified regional compounders.
Growth Catalysts
- NY 525-2012 standard enforcement:Mandatory organic matter thresholds in intensive vegetable zones are phasing out low-grade compost, creating pull for certified microbial formulations in Shandong greenhouses.
- Yangtze River Delta horticulture concentration:High-value strawberry and blueberry cultivation clusters support 40-60% price premiums for seaweed-derived trace element formulations versus conventional compost.
- Export-grade certification demand:Shandong vegetable growers pursuing EU and Japanese organic import qualifications are substituting chemical inputs with documented organic amendment chains.
Market Restraints
- Animal manure supply volatility:Hog farming cycle fluctuations in Henan and Sichuan provinces create raw material cost swings of 25-35% for compost-based producers without captive livestock partnerships.
- Technical limitation in biochar carbon verification:Absence of standardized soil carbon quantification protocols blocks premium pricing claims for pyrolyzed biomass amendments in fruit orchards.
- SAMR labeling enforcement gaps:Fraudulent organic claims from uncertified compounders distort buyer trust and compress legitimate premium pricing in county-level distribution channels.
Strategic Opportunities
- Guangdong Province underpenetration:Subtropical fruit cultivation in the Pearl River Delta currently sources 70% chemical inputs, presenting conversion potential for acid-tolerant microbial formulations.
- Carbon credit stacking:MEE soil pollution prevention mandates align with voluntary carbon registry protocols, enabling dual revenue streams for verifiable carbon-sequestering amendment producers.
- E-commerce direct-to-farm channels:Alibaba's rural Taobao network and Pinduoduo agricultural verticals are disintermediating county-level distributors for branded organic input suppliers.
Industry Challenges
- Microbiologist talent scarcity:Formulation chemists with strain isolation expertise command 3-4x agricultural sector salaries, constraining R&D expansion for mid-tier producers.
- GB 20287-2006 compliance timeline compression:Strain viability testing requirements extend product registration cycles to 18-24 months, freezing pipeline commercialization for reformulated lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Organic Fertilizers Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compost, Manure, Seaweed, Biochar Application: Agriculture, Horticulture, Landscaping, Gardening Distribution Channel: Direct Sales, Retail, E-commerce, Wholesale Customer Type: Farmers, Agricultural Cooperatives, Garden Centers, Distributors |
| Companies Covered | Shandong Nongda Fertilizer Sci & Tech Co Ltd, Genliduo Bio-tech Corporation Ltd, Rizhao Organic, Biolchim SPA, Hebei Woze Wufeng Biological Technology Co Ltd, Binzhou Jingyang Biological Fertilizer Co Ltd, Seawin Biotech, Shanxi Haozhida Biotechnology Co Ltd, Qingdao Future Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Organic Fertilizers Market Strategic Shifts
Biological soil amendment technologies are converging with digital agriculture platforms, enabling precision application of microbial inoculants based on real-time soil sensor data. This integration is compressing the traditional agronomist-led recommendation model.
Solid-state fermentation of agricultural residues is supplanting liquid submerged culture for bacillus-based formulations, reducing energy inputs by 60% while maintaining spore counts. Large-scale vegetable cooperatives in Shandong and Hebei are adopting this platform within 24-month equipment payback windows. The technology is enabling distributed production models that bypass centralized bioreactor infrastructure investments.
MEE soil pollution prevention mandates are tightening heavy metal thresholds in organic amendments, forcing compost producers to implement source-segregated collection from certified livestock operations. Industrial consequence includes vertical consolidation between fertilizer compounders and controlled-environment hog farming enterprises. Coastal seaweed extract processors face accelerated heavy metal testing protocols, advantaging deep-water kelp sourcing over nearshore harvesting.
Certification-driven procurement is fragmenting traditional distributor relationships as export-oriented growers demand batch-level traceability documentation. County-level supply cooperatives in the Yangtze River Delta are replacing generic compost with branded microbial products carrying GB 20287-2006 and EU organic dual certification. This shift concentrates purchasing authority with technical managers rather than legacy procurement officers in Shandong and Jiangsu greenhouse clusters.
China Organic Fertilizers Market Segmentation
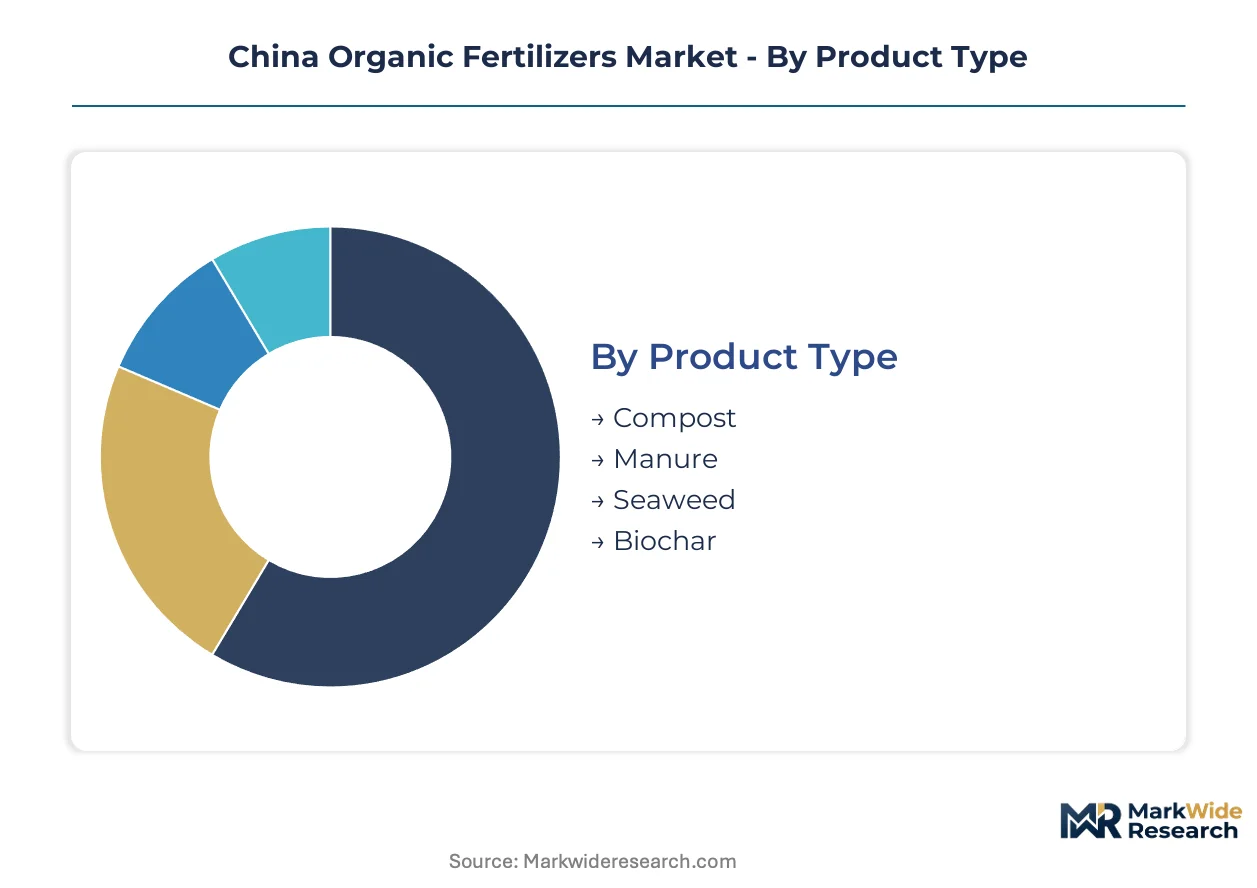
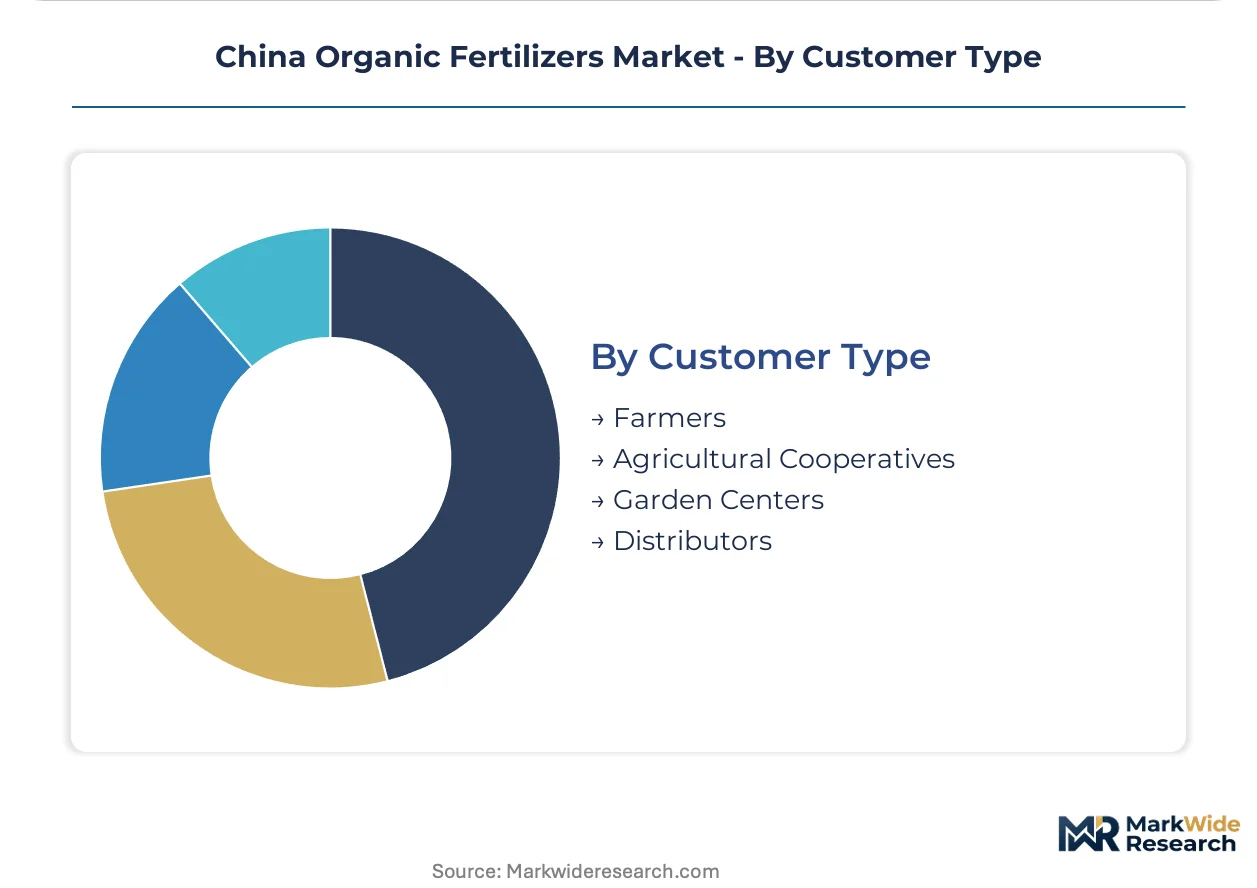
China's organic fertilizer segmentation reflects divergent channel economics across coastal export zones and inland commodity basins. Product certification tiers and application intensity create distinct margin architectures that reshape procurement authority within buyer organizations.
Product Type:
Channel mix varies sharply by product maturity: compost and manure flow primarily through wholesale distributors serving county-level cooperatives, while seaweed extracts and biochar bypass intermediaries via direct technical sales to greenhouse operators.
- Compost:Decomposed organic matter from agricultural residues and livestock waste meeting NY 525-2012 organic matter thresholds. Demand concentrates in Shandong greenhouse clusters where export-certification requirements mandate documented amendment chains for EU-bound vegetable shipments.
- Manure:Animal waste processed through aerobic fermentation or anaerobic digestion. Supply cost volatility from hog farming cycles in Henan and Sichuan creates 25-35% price swings for producers without captive livestock partnerships.
- Seaweed:Marine biomass extracts rich in cytokinins and trace elements. Coastal horticulture zones in Fujian and Zhejiang absorb premium formulations for high-value strawberry and blueberry cultivation.
- Biochar:Pyrolyzed biomass soil amendments with carbon sequestration claims. Fruit orchards in Yunnan and Xinjiang pilot applications pending standardized soil carbon quantification protocols.
Compost dominates installed base. Seaweed is where expansion concentrates.
Application:
Cost tier stratification separates commodity field crops from premium horticulture: agriculture applications tolerate lower-grade compost while horticulture commands certified microbial formulations at 40-60% price premiums.
- Agriculture:Broadacre cereal and oilseed production utilizing bulk compost for soil organic matter restoration. Hebei and Henan grain belts prioritize per-ton cost minimization over certification documentation.
- Horticulture:Intensive fruit and vegetable cultivation requiring trace-element bioavailability and strain-specific microbial inoculants. Yangtze River Delta strawberry cooperatives drive formulation customization.
- Landscaping:Municipal and commercial green space maintenance with standardized compost applications. Provincial urban greening budgets in Jiangsu and Guangdong specify bulk procurement contracts.
- Gardening:Consumer-scale packaged products for residential use. Alibaba rural Taobao channels disintermediate traditional garden center distribution in tier-3 and tier-4 cities.
Agriculture holds volume leadership. Horticulture generates margin concentration.
Distribution Channel:
Customer type dictates channel selection: large agricultural cooperatives leverage direct sales for technical consultation while smallholders remain embedded in wholesale networks.
- Direct Sales:Manufacturer-to-grower relationships with embedded agronomist support. Shandong vegetable export cooperatives require batch-level traceability documentation that only direct channels reliably provide.
- Retail:Agricultural supply stores and garden centers serving dispersed smallholders. County-level distributors in Anhui and Hubei face margin compression from SAMR labeling enforcement gaps.
- E-commerce:Platform-based procurement via Pinduoduo agricultural verticals and Alibaba rural networks. Branded organic input suppliers bypass legacy distributor relationships through direct-to-farm channels.
- Wholesale:Volume aggregation through provincial supply cooperatives. Traditional procurement officers in Jiangsu greenhouse clusters cede authority to technical managers demanding certified microbial products.
Wholesale retains volume dominance. E-commerce is climbing the fastest.
Customer Type:
Volume scale and technical sophistication segment procurement behavior: agricultural cooperatives consolidate purchasing power while individual farmers remain price-sensitive and certification-agnostic.
- Farmers:Individual smallholders operating under 5 hectares with minimal organic certification exposure. Henan and Sichuan commodity producers prioritize per-mu cost over amendment quality documentation.
- Agricultural Cooperatives:Consolidated purchasing entities representing 50-200 member households. Shandong and Jiangsu export-oriented cooperatives demand dual GB 20287-2006 and EU organic certification.
- Garden Centers:Retail intermediaries serving urban consumer gardening demand. Tier-1 city outlets in Shanghai and Beijing curate premium seaweed extract portfolios for affluent hobbyists.
- Distributors:County and provincial-level supply chain intermediaries. Legacy relationships fragment as certification-driven procurement concentrates authority with technical managers.
Agricultural cooperatives anchor revenue concentration. Garden centers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented vegetable cooperatives concentrate purchasing power in Shandong and Jiangsu provinces, where dual GB 20287-2006 and EU organic certification requirements reshape procurement authority toward technical managers.
Shandong Peninsula
Greenhouse vegetable clusters in Weifang and Qingdao drive demand for documented organic amendment chains as growers pursue Japanese and EU export qualifications. Provincial agricultural bureaus enforce NY 525-2012 organic matter thresholds through intensive inspection regimes. Shandong Nongda Fertilizer Sci & Tech Co Ltd anchors regional compost supply chains from its Weifang base.
Yangtze River Delta
Strawberry and blueberry cooperatives in Jiangsu and Zhejiang absorb 40-60% price premiums for seaweed-derived trace element formulations. SAMR labeling enforcement gaps in county-level channels compress legitimate premium pricing for certified suppliers. Suzhou and Nantong greenhouse clusters are replacing generic compost with dual-certified microbial products carrying batch-level traceability documentation.
Pearl River Delta
Subtropical fruit cultivation in Guangdong currently sources 70% chemical inputs, presenting conversion potential for acid-tolerant microbial formulations. Provincial subsidy flows under China's dual carbon goals channel toward verifiable carbon-sequestering amendments. Foshan and Huizhou lychee orchards pilot biochar applications pending standardized soil carbon quantification protocols.
Sichuan-Chongqing
Hog farming cycle fluctuations in Sichuan create 25-35% raw material cost swings for compost-based producers without captive livestock partnerships. MEE soil pollution prevention mandates tighten heavy metal thresholds in organic amendments sourced from livestock operations. Chengdu平原 vegetable belts are consolidating procurement through agricultural cooperatives representing 50-200 member households.
Beijing-Tianjin-Hebei
Municipal landscaping budgets in Beijing and Tianjin specify bulk compost procurement contracts for urban greening maintenance. Provincial environmental regulators monitor runoff impacts under soil pollution prevention mandates. Langfang and Baoding distribution hubs face margin compression from e-commerce disintermediation via Alibaba rural Taobao channels.
China Organic Fertilizers Market Competitive Environment
Player mix skews toward regional compounders with captive raw material access and specialized bio-fermentation specialists. Market structure fragments across hundreds of county-level producers, though certification barriers under GB 20287-2006 are concentrating share among registered microbial formulation suppliers. Three archetypes dominate: Shandong-based compost integrators with livestock partnerships, coastal seaweed extract processors, and biotech-originated solid-state fermentation specialists. Competitive moves center on backward integration into controlled-environment livestock operations and strain licensing partnerships with agricultural universities.
Within the regional compounder tier, Shandong Nongda Fertilizer Sci & Tech Co Ltd and Hebei Woze Wufeng Biological Technology Co Ltd exemplify producers leveraging geographic proximity to intensive livestock zones. Among bio-fermentation specialists, Genliduo Bio-tech Corporation Ltd occupies a position representing the technology-intensive archetype. Coastal formulation capabilities anchor Rizhao Organic and Seawin Biotech within the marine-derived input segment. Shanxi Haozhida Biotechnology Co Ltd and Binzhou Jingyang Biological Fertilizer Co Ltd sit within the provincial-market-focused tier serving county-level cooperatives. Qingdao Future Group represents the diversified regional player archetype spanning multiple product categories.
| Leading Market Players |
|---|
| Shandong Nongda Fertilizer Sci & Tech Co Ltd |
| Genliduo Bio-tech Corporation Ltd |
| Rizhao Organic |
| Biolchim SPA |
| Hebei Woze Wufeng Biological Technology Co Ltd |
| Binzhou Jingyang Biological Fertilizer Co Ltd |
| Seawin Biotech |
| Shanxi Haozhida Biotechnology Co Ltd |
| Qingdao Future Group |
| Others |
Value Chain & Pricing Dynamics
China's GB 20287-2006 microbial fertilizer standard gates supply qualification and price differentiation simultaneously, forcing producers to absorb certification costs while enabling certified suppliers to command 40-60% premiums in Yangtze River Delta horticulture zones. This regulatory pivot compresses margins for uncertified compounders even as it creates pricing power for registered microbial formulation suppliers serving export-oriented vegetable cooperatives.
Pricing Analysis
Cost-plus contracts with hog manure indexation dominate raw material procurement for compost-based producers, exposing margin volatility to 25-35% price swings from livestock cycle fluctuations in Henan and Sichuan. Pricing stratifies across premium, standard, and economy tiers based on certification grade and batch-level traceability documentation. Cost compression in economy-grade compost is intensifying because SAMR labeling enforcement gaps allow fraudulent organic claims to distort buyer trust. Individual smallholders in inland grain belts exhibit highest price sensitivity, while export-oriented cooperatives in Shandong demonstrate lowest sensitivity due to certification compliance requirements.
Supply Chain Analysis
China anchors global organic fertilizer production through concentrated compost manufacturing in Shandong and Hebei provinces, coastal seaweed extraction in Fujian and Zhejiang, and emerging biochar pyrolysis in Yunnan and Xinjiang. Supply chains draw from livestock waste streams, agricultural residues, and deep-water kelp harvesting as primary inputs. Single-source vulnerability runs through hog farming partnerships, where producers without captive livestock operations face raw material disruption from provincial animal husbandry cycle downturns. Distribution runs through county-level agricultural supply cooperatives, though Alibaba rural Taobao and Pinduoduo agricultural verticals are accelerating disintermediation for branded suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's organic fertilizer market sits at a platform-economics inflection, where e-commerce direct-to-farm channels and digital soil sensor integration are reshaping procurement authority and technical recommendation flows.
For Market Incumbents: Shield market position through backward integration into controlled-environment livestock operations in Henan and Sichuan, securing captive manure supply against 25-35% cost volatility. Invest in GB 20287-2006 strain registration pipelines to defend against emerging bio-fermentation specialists with university licensing partnerships. Channel control through embedded agronomist relationships remains critical as technical managers displace legacy procurement officers in cooperative purchasing decisions. For New Entrants and Emerging Players: Differentiate on acid-tolerant microbial formulations targeting Guangdong's Pearl River Delta subtropical fruit sector, where 70% chemical input dependency creates conversion headroom. Penetrate via carbon credit stacking models that align MEE soil pollution mandates with voluntary registry protocols, enabling dual revenue streams absent from incumbent compost suppliers. E-commerce direct-to-farm channels offer lowest customer acquisition friction for branded organic input suppliers bypassing county-level distributor fragmentation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across solid-state fermentation equipment platforms, compressing 24-month payback windows and enabling distributed production models without centralized bioreactor infrastructure. Acquisition targets should display captive livestock partnerships or deep-water kelp sourcing contracts that insulate raw material exposure. The signal to watch is provincial subsidy qualification criteria evolution under China's dual carbon goals, which will determine revenue eligibility for carbon-sequestering amendment producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Livestock Operations | Captive manure supply from Henan hog farming partnerships eliminates 25-35% raw material cost volatility. |
| GB 20287-2006 Strain Registration Investment | 18-24 month product registration cycles freeze pipeline commercialization for uncertified competitors. |
| E-Commerce Direct-to-Farm Channel Buildout | Alibaba rural Taobao and Pinduoduo agricultural verticals disintermediate county-level distributor margin compression. |
| Solid-State Fermentation Technology Adoption | 60% energy reduction versus liquid submerged culture enables distributed production without centralized infrastructure. |
| Carbon Credit Stacking Protocol Development | MEE soil pollution prevention mandate alignment with voluntary registries creates dual revenue streams for verified amendments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with agricultural cooperative technical managers, provincial supply chain distributors, compost plant operations directors, seaweed extraction processors, and SAMR regulatory compliance officers. Secondary validation drew from China customs trade data, Ministry of Agriculture and Rural Affairs subsidy disbursement records, GB standards documentation, provincial environmental bureau filings, and agricultural university strain research publications. Bottom-up volume modeling across product type, application, and customer segments was cross-checked against top-down market sizing from production capacity assessments and channel throughput estimates.
Across the analysis window, value projections incorporate segmentation by product maturity tier, certification grade, and regional horticulture intensity, with CAGRs derived from historical input substitution elasticities and policy-driven adoption curve modeling. Forecast inputs include provincial dual carbon subsidy allocation trajectories, GB 20287-2006 compliance timeline compression effects, and e-commerce penetration rates in tier-3 and tier-4 agricultural counties.
The analysis sits within stated boundaries; outcomes outside sustained subsidy flows, stable hog farming cycle conditions, or accelerated SAMR enforcement would require recalibration. Forecasts reflect documented assumptions regarding strain viability testing duration and heavy metal threshold tightening under MEE mandates. Recalibration cycles align with material shifts in provincial subsidy qualification criteria and certification reciprocity negotiations with EU and Japanese organic import jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Vietnam Biofertilizer Market
Fertilizers
Sulfur Fertilizer Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
China Specialty Fertilizer Market
Fertilizers
Humate Fertilizer Market
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
India Specialty Fertilizer Market
Fertilizers
Global Starter Fertilizers Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Italy Water Soluble Fertilizer Market
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
Nitrogen Nutrients Market
Fertilizers
Russia Fertilizers Market
Fertilizers
United States Controlled Release Fertilizer Market