
 Egypt Fertilizer Market | 2026-2036
Egypt Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Fertilizer Market Insights
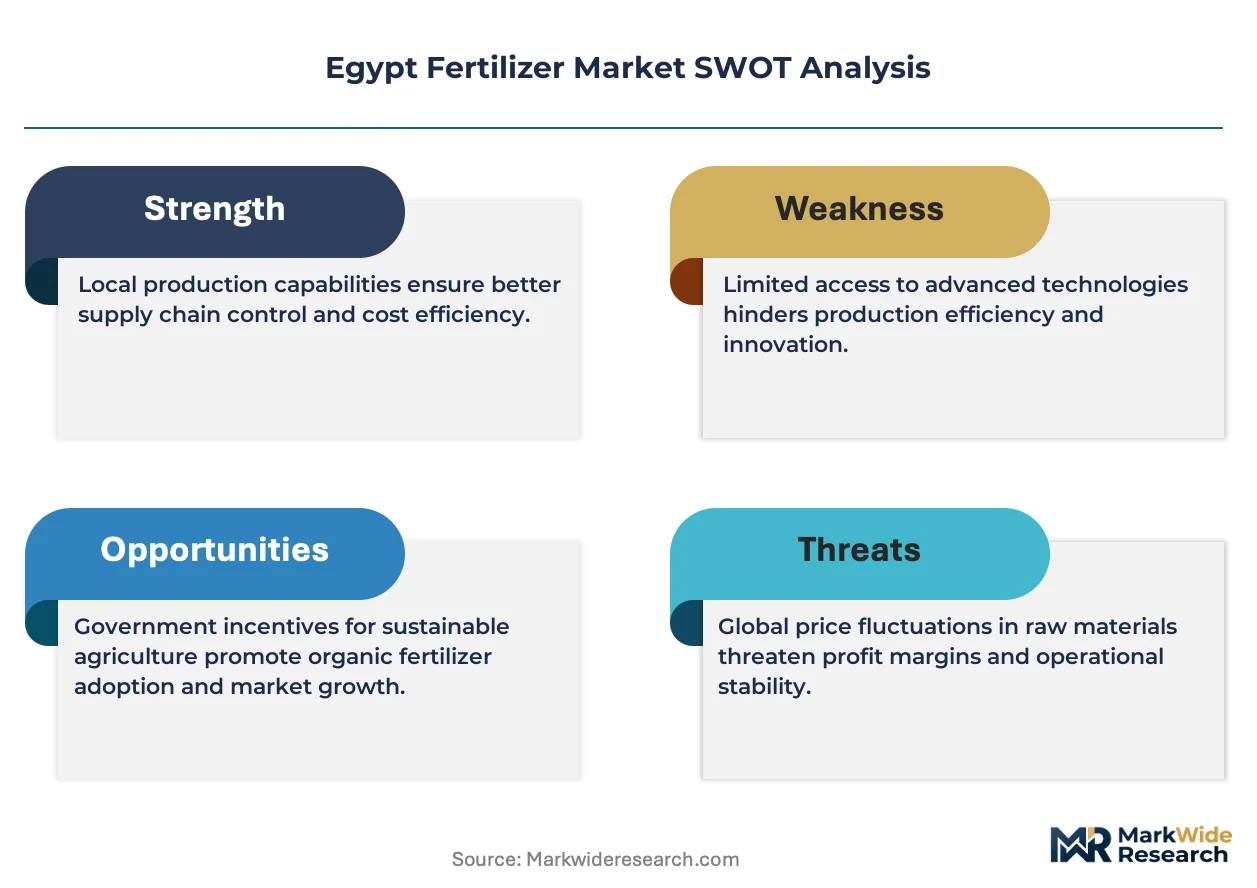
ISO 9001 quality management certification is reorganizing competitive access among Egyptian fertilizer producers. MOPCO leverages its integrated ammonia-urea complex on the Damietta corridor to sustain feedstock cost advantages. Abu Qir Fertilizers and Chemicals Industries Company anchors Mediterranean export capacity through its Alexandria terminal infrastructure. AlexFert differentiates via specialized compound formulations tailored to Delta clay-loam soils.
Egyptian fertilizer comprises nitrogen, phosphorus, and potassium compounds manufactured through Haber-Bosch ammonia synthesis, phosphate rock acidulation, and potash blending, with formulations calibrated to N-P-K ratios matching specific crop nutrient uptake curves. Urea dominates volume throughput due to Egypt's abundant natural gas feedstock and established ammonia infrastructure, while DAP commands premium positioning in phosphate-deficient Western Desert reclamation zones. Direct sales channels to large agriculture producers capture the deepest margin pools, though cooperatives retain structural importance in smallholder-dominated Upper Egypt governorates.
Egypt's Ministry of Agriculture and Land Reclamation governs fertilizer registration and import licensing, while the Egyptian General Authority for Standardization and Quality enforces product composition labeling under mandatory national standards. Subsidy allocation shifts under the government's smart-card distribution system reshape purchasing patterns across customer segments. Stakeholders must monitor water policy convergence with fertilizer application norms as Egypt implements precision agriculture pilots tied to Nile water conservation targets.
Market Dynamics
Egypt's fertilizer market restructuring centers on the Ministry of Agriculture and Land Reclamation's smart-card subsidy reallocation, which is compressing traditional cooperative purchasing channels while elevating direct-to-farm digital distribution platforms.
Growth Catalysts
- Nile Water Conservation Mandates:Precision agriculture pilots tied to reduced irrigation quotas are accelerating controlled-release fertilizer uptake among Delta wheat growers.
- Western Desert Reclamation:State-led land expansion programs are generating phosphate-intensive demand in previously uncultivated governorates.
- Natural Gas Feedstock Abundance:Egypt's East Mediterranean gas infrastructure sustures cost-competitive ammonia-urea production relative to import-dependent regional peers.
Market Restraints
- Input Cost Volatility:International sulfur and phosphate rock price swings compress margin predictability for compound fertilizer blenders.
- Supply Concentration Risk:Damietta corridor pipeline disruptions would immediately constrain nitrogen availability across Sharqia and Dakahlia governorates.
- Regulatory Friction:Egyptian General Authority for Standardization and Quality registration timelines delay product launches by 8-14 months.
Strategic Opportunities
- Upper Egypt Smallholder Penetration:Minya and Sohag governorates remain underserved by specialized micronutrient formulations calibrated to calcareous soils.
- Regulatory Tailwind:ISO 9001 certification requirements are creating first-mover advantage windows for quality-invested domestic producers.
- Channel Innovation:Mobile-enabled aggregator platforms are bypassing cooperative intermediaries to capture margin pools in direct farm relationships.
Industry Challenges
- Agronomic Expertise Gap:Soil testing and prescription agriculture capabilities remain concentrated in Cairo-based consultancies, limiting localized advisory reach.
- Legacy System Integration:Cooperative inventory management systems resist real-time subsidy reconciliation with central government databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Fertilizer Market |
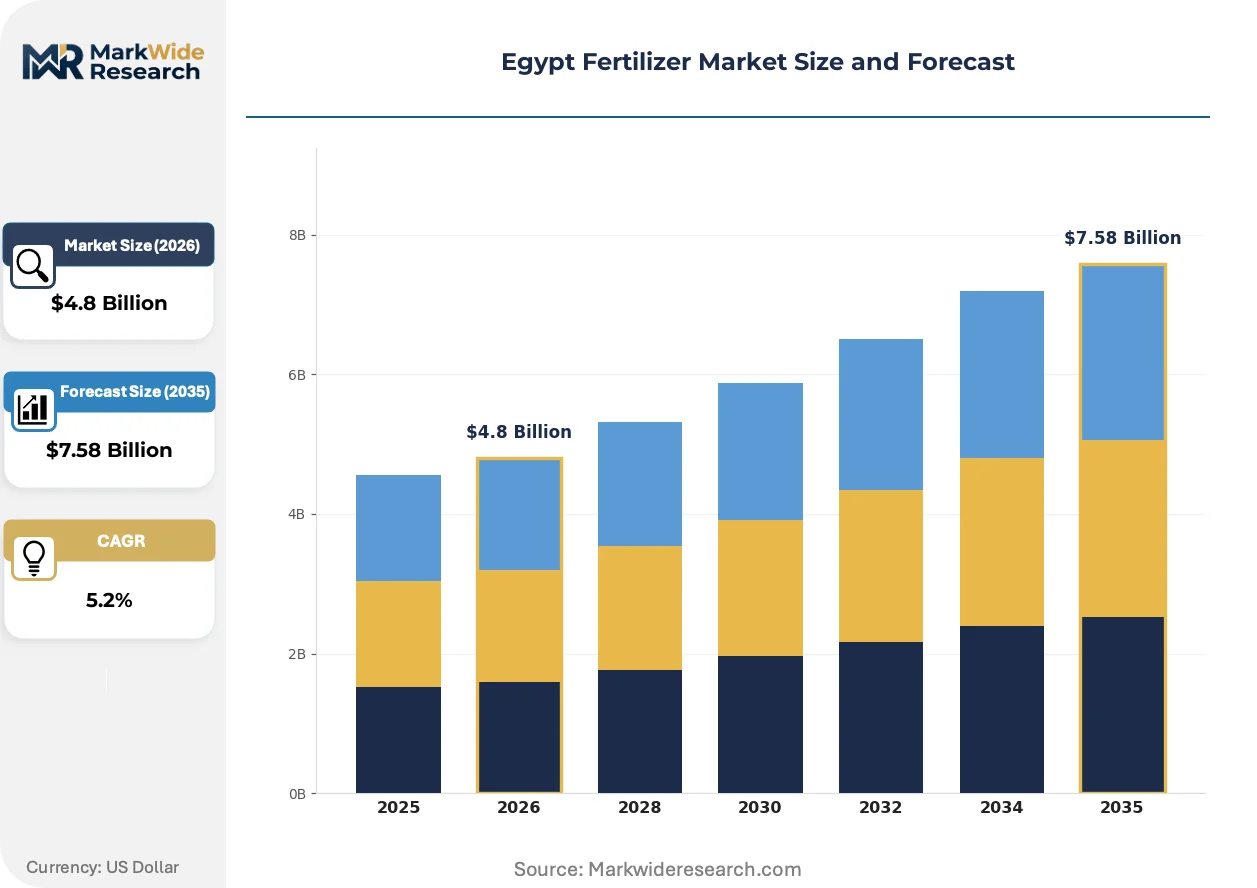
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, Ammonium Nitrate, DAP, Potash Application: Cereals, Fruits, Vegetables, Cash Crops Distribution Channel: Direct Sales, Retailers, Cooperatives, E-commerce Customer Type: Agriculture Producers, Resellers, Commercial Growers, Horticulturists |
| Companies Covered | Elmehwar Group, Evergrow, Misr Fertilizers Production Company (MOPCO), Herbseic, Heliopolis Company for Chemical Industries, Misr Phosphate, Alexandria Fertilizers Company (AlexFert), Egyptian Financial and Industrial, Abu Qir Fertilizers and Chemicals Industries Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Fertilizer Market Trends and Innovations
Digital distribution infrastructure and precision application technologies are compressing traditional value chain layers while elevating data-driven nutrient management as the core competitive differentiator.
Controlled-release polymer coatings for urea granules are fragmenting application frequency norms across Egypt's intensive vegetable production zones. Large-scale tomato and potato operations in Kafr El Sheikh Governorate are adopting these formulations to align with restricted irrigation windows. The technology is fragmenting seasonal purchasing patterns that historically concentrated orders around subsidy release dates.
Egypt's smart-card subsidy system is mandating biometric verification for fertilizer purchases, forcing cooperative networks to deploy point-of-sale infrastructure by Ministry of Agriculture and Land Reclamation deadlines. Smallholder enrollment gaps in Beheira and Gharbia governorates are delaying full system activation. Compound blenders with integrated digital fulfillment capabilities are capturing displaced volume from cash-flow constrained intermediaries.
Soil health monitoring services are unbundling from product sales, with agritech providers selling subscription-based nutrient prescription platforms independent of fertilizer supply contracts. Commercial farming enterprises in the Delta are contracting specialized advisory firms to optimize N-P-K ratios against real-time salinity and moisture data. This service separation is most advanced in Qalyubia Governorate's greenhouse vegetable clusters.
Egypt Fertilizer Market Segmentation
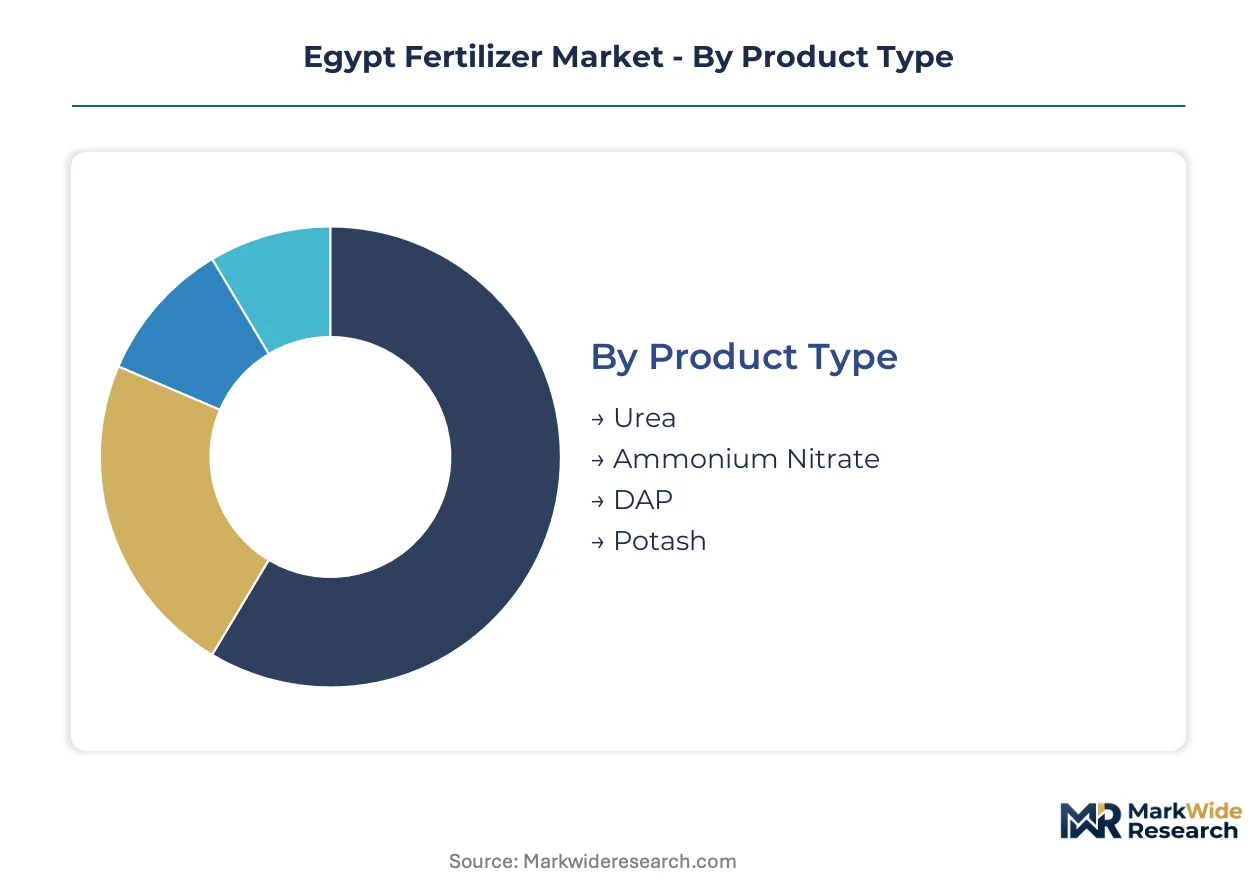
Segmentation reveals how subsidy flows, soil heterogeneity, and farm-scale disparities fragment Egypt's fertilizer demand into distinct commercial battlegrounds. Channel strategy and product formulation decisions must align with these structural fault lines to capture margin pools.
Product Type:
Channel access varies sharply by product chemistry—urea and ammonium nitrate flow predominantly through subsidized cooperative networks, while DAP and potash concentrate in direct sales to commercial operators.
- Urea:Nitrogen-rich granular formulation synthesized via Haber-Bosch ammonia processing using Egyptian natural gas feedstock. Demand concentrates in Sharqia Governorate's intensive wheat corridors, where government subsidy allocations sustain volume throughput despite international price volatility.
- DAP:Diammonium phosphate compound delivering concentrated phosphorus and nitrogen in 18-46-0 N-P-K ratio. Western Desert reclamation zones in Matrouh and New Valley governorates drive uptake, as virgin soils demand heavy phosphate amendment for initial cultivation cycles.
- Ammonium Nitrate:High-nitrogen compound favored for rapid vegetative growth stages in vegetable production. Kafr El Sheikh greenhouse clusters purchase through direct sales channels bypassing cooperative intermediaries.
- Potash:Potassium chloride or sulfate formulations correcting soil deficiencies in long-cultivated Delta lands. AlexFert and import-dependent blenders serve horticulturist demand in Qalyubia and Gharbia through specialized distribution partnerships.
Urea dominates installed base. DAP is where expansion concentrates.
Application:
Cost tier differentiation separates commodity grain applications from premium horticultural segments, with pricing power inversely correlated with crop perishability and farmer scale.
- Cereals:Wheat and maize cultivation across Nile Delta governorates consumes the largest fertilizer volumes, with nitrogen-heavy protocols calibrated to Ministry of Agriculture yield targets. Smart-card subsidy eligibility constrains product choice and purchasing timing for smallholders.
- Vegetables:Tomato, potato, and onion operations in Kafr El Sheikh and Beheira command specialized micronutrient blends and controlled-release formulations. Large commercial growers negotiate direct supply contracts with compound blenders, escaping cooperative markups.
- Fruits:Citrus orchards in Qalyubia and grape cultivation in Minya require potassium-intensive nutrition programs. Soil testing adoption rates lag cereal zones, creating advisory service opportunities for agritech providers.
- Cash Crops:Cotton in Gharbia and sugar beet in Dakahlia follow crop rotation schedules with distinct fertilizer windows. Export-oriented producers invest in ISO 9001-certified inputs to satisfy European buyer traceability requirements.
Cereals anchor volume throughput. Vegetables are climbing the fastest.
Distribution Channel:
Customer type determines channel economics—large agriculture producers extract steepest discounts through direct relationships, while smallholders remain captive to cooperative infrastructure despite digital alternatives emerging.
- Direct Sales:Manufacturer-to-farm contracts serving commercial growers above 500 feddan scale. MOPCO and Abu Qir Fertilizers deploy dedicated sales teams to Delta vegetable enterprises and Western Desert reclamation contractors.
- Cooperatives:Government-subsidized intermediaries handling smallholder aggregation in Upper Egypt governorates. Smart-card biometric verification mandates are forcing infrastructure upgrades that strain working capital.
- Retailers:Independent agricultural supply shops in secondary towns bridging cooperative gaps. Inventory financing constraints limit product breadth to fast-moving urea and standard compounds.
- E-commerce:Mobile-enabled platforms piloting aggregator models in Beheira and Gharbia. Fulfillment logistics and farmer digital literacy gaps constrain scaling beyond trial phases.
Cooperatives retain structural dominance in smallholder zones. Direct sales are gaining share fastest.
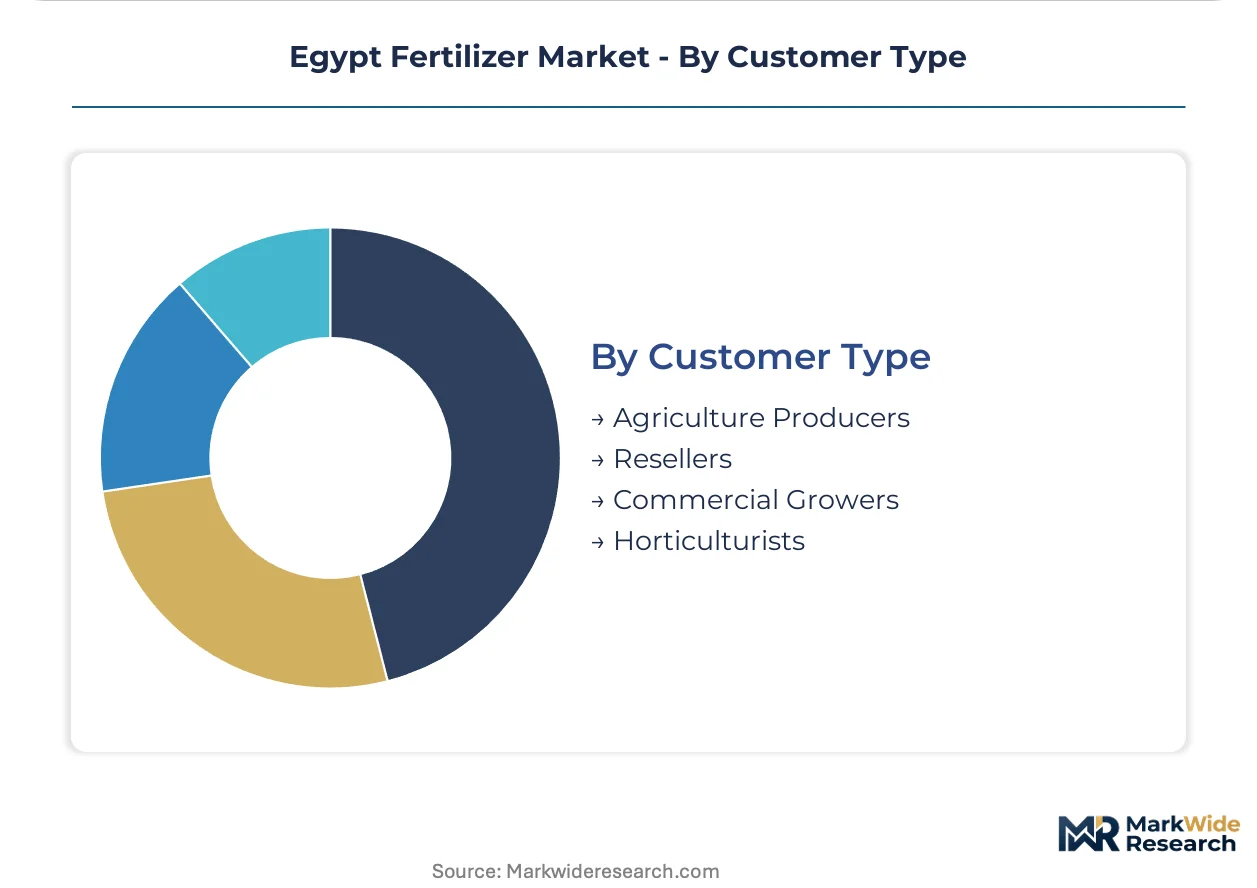
Customer Type:
Volume concentration and margin capture diverge across farmer scale categories, with procurement sophistication correlating to landholding size and export market exposure.
- Agriculture Producers:Smallholder operators below 10 feddan dependent on subsidized cooperative channels and standardized formulations. Minya and Sohag governorates exhibit lowest penetration of specialized micronutrient products.
- Commercial Growers:Mid-scale enterprises 50-500 feddan accessing direct sales for core nitrogen needs while retaining cooperative relationships for subsidized volumes. Precision agriculture adoption is concentrating in this segment.
- Horticulturists:Protected cultivation specialists in Qalyubia and Kafr El Sheikh demanding premium compound blends and subscription advisory services. Soil health monitoring unbundling from product sales is most advanced here.
- Resellers:Independent traders arbitraging price differentials between subsidized and commercial channels. Regulatory scrutiny under smart-card reconciliation is compressing this segment's viability.
Agriculture Producers dominate installed base. Horticulturists represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial growers above 500 feddan dominate procurement in the Nile Delta, while smallholders in Upper Egypt remain tethered to cooperative channels. The Ministry of Agriculture and Land Reclamation's smart-card system is compressing regional purchasing disparities.
Sharqia Governorate
Intensive wheat corridors consume the highest nitrogen volumes nationwide. The smart-card subsidy reallocation mandates biometric verification at cooperative points of sale. MOPCO's Damietta corridor infrastructure feeds direct-to-farm contracts with large-scale operators in Zagazig and Belbeis.
Kafr El Sheikh Governorate
Greenhouse tomato and potato operations drive controlled-release fertilizer uptake. Precision agriculture pilots tied to Nile water conservation targets are accelerating polymer-coated urea adoption. Commercial vegetable clusters in Desouk and Fuwah negotiate supply contracts bypassing cooperative intermediaries.
Beheira Governorate
Smallholder enrollment gaps in the smart-card system are delaying full digital distribution activation. The Egyptian General Authority for Standardization and Quality enforces mandatory labeling compliance for imported compound blends. Mobile-enabled aggregator platforms are piloting direct fulfillment in Damanhour and Rashid.
Minya Governorate
Calcareous soils in this Upper Egypt zone remain underserved by specialized micronutrient formulations. Subsidy flows through cooperative networks dominate smallholder access below 10 feddan scale. AlexFert and import-dependent blenders are expanding retail presence in Mallawi and Samalut.
Matrouh Governorate
Western Desert reclamation zones generate phosphate-intensive demand for initial cultivation cycles. State-led land expansion programs under the Ministry of Agriculture and Land Reclamation prioritize DAP amendment protocols. New Valley extension corridors are replicating Matrouh's input-intensive development pattern.
Egypt Fertilizer Market Competitive Landscape
Player mix skews toward integrated ammonia-urea producers with captive natural gas access. Market structure concentrates around three Damietta-Alexandria corridor complexes serving domestic volume and Mediterranean export positions. Strategic archetypes include feedstock-integrated nitrogen specialists, phosphate rock acidulators, and compound blenders with advisory service attachments. Capacity expansion and ISO 9001 certification acquisition are the dominant competitive moves reshaping access to government procurement channels.
Within the integrated producer tier, Misr Fertilizers Production Company (MOPCO) and Abu Qir Fertilizers and Chemicals Industries Company exemplify feedstock-advantaged positioning through their coastal ammonia-urea complexes. Alexandria Fertilizers Company (AlexFert) occupies a specialization niche in compound formulations calibrated to Delta soil profiles. These three Egyptian joint-stock companies represent distinct strategic postures: MOPCO anchors scale-driven nitrogen supply, Abu Qir commands export terminal infrastructure, and AlexFert targets premium horticultural segments with tailored nutrient blends.
| Leading Market Players |
|---|
| Elmehwar Group |
| Evergrow |
| Misr Fertilizers Production Company (MOPCO) |
| Herbseic |
| Heliopolis Company for Chemical Industries |
| Misr Phosphate |
| Alexandria Fertilizers Company (AlexFert) |
| Egyptian Financial and Industrial |
| Abu Qir Fertilizers and Chemicals Industries Company |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day inventory cycles at Alexandria terminal infrastructure compress working capital for compound blenders while amplifying MOPCO's and Abu Qir's pricing power through feedstock-integrated ammonia-urea complexes. Egyptian General Authority for Standardization and Quality registration delays extend this lead-time exposure, forcing smaller blenders to absorb carrying costs that integrated producers avoid.
Pricing Analysis
Cost-plus contracts indexed to Platts Middle East sulfur and phosphate rock benchmarks dominate compound fertilizer procurement, insulating blenders from raw material volatility while capping margin expansion. Three-tier pricing structure across ISO 9001-certified premium, standard-grade, and economy formulations separates MOPCO's direct sales contracts from cooperative-subsidized volumes. Pricing pressure stems from smart-card subsidy reallocation compressing intermediary markups in Beheira and Gharbia. Smallholders below 10 feddan exhibit highest price sensitivity through cooperative channels, while horticulturists in Qalyubia demonstrate lowest sensitivity due to yield-linked ROI calculations.
Supply Chain Analysis
Egypt and Morocco anchor phosphate rock acidulation capacity, while Russia and Belarus historically fed potash blending operations before trade flow disruptions. Egyptian natural gas from East Mediterranean fields feeds Haber-Bosch ammonia synthesis, with sulfur drawn from domestic oil refining and phosphate rock from Red Sea mining concessions. Single-source vulnerability concentrates in Damietta corridor pipeline infrastructure serving Sharqia and Dakahlia governorates. Distribution runs through cooperative networks for smallholders and direct manufacturer contracts for commercial growers above 500 feddan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's fertilizer market fragments along soil heterogeneity and farm-scale fault lines, with precision agriculture pilots and smart-card digitization creating specialized service niches that incumbent producers underexploit.
For Market Incumbents: Secure ISO 9001 certification ahead of Ministry of Agriculture and Land Reclamation procurement preference shifts, and lock in long-term natural gas offtake agreements before feedstock cost volatility erodes ammonia-urea margins. Mobile-enabled aggregator platforms threaten cooperative channel control in Beheira and Gharbia, making direct-to-farm digital infrastructure the critical defensive lever. For New Entrants and Emerging Players: Soil health monitoring subscription gaps in Minya and Sohag governorates offer white-space entry points where AlexFert and MOPCO lack localized advisory presence. Calcareous soil micronutrient formulations remain underserved in Upper Egypt smallholder zones. A precision agriculture bundling strategy—combining soil testing with controlled-release product recommendations—bypasses capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: Long-term, this sits as a feedstock-advantaged infrastructure play because Egyptian natural gas access and Mediterranean export terminal positioning create durable moats against import-dependent regional competitors. Acquisition targets should display compound blending capabilities with advisory service attachments and smart-card system integration. Watch for smart-card enrollment completion rates in Beheira and Gharbia as the inflection signal for cooperative channel displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Production | MOPCO's Damietta corridor complex demonstrates how captive natural gas feedstock eliminates sulfur price exposure for nitrogen fertilizers. |
| ISO 9001 Certification Acquisition | Egyptian General Authority for Standardization and Quality registration timelines create first-mover windows for quality-invested domestic producers. |
| Mobile-Enabled Aggregator Platform Launch | Biometric verification mandates under smart-card subsidy reallocation force cooperative infrastructure upgrades that digital platforms bypass. |
| Controlled-Release Formulation Development | Kafr El Sheikh greenhouse operators adopt polymer-coated urea to align with Nile water conservation irrigation windows. |
| Soil Health Monitoring Service Unbundling | Qalyubia horticulturists contract specialized advisory firms independent of fertilizer supply contracts, separating nutrient prescription from product sales. |
Research Methodology
Initial hypotheses were tested against primary input from agritech platform operators, cooperative procurement managers, and compound blender technical directors and refined through secondary validation against customs trade data, Ministry of Agriculture and Land Reclamation subsidy allocation records, and Egyptian General Authority for Standardization and Quality registration filings. Bottom-up volume estimates from governorate-level consumption patterns were triangulated with top-down capacity assessments of Damietta-Alexandria corridor production complexes.
Variance decomposition across product type, application, distribution channel, and customer type segments structured the analytical framework throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers including natural gas pricing trajectories and Western Desert reclamation program cadence. Smart-card subsidy reallocation velocity and precision agriculture pilot expansion rates served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in Egyptian fertilizer registration and import licensing regimes; material policy shifts in subsidy allocation mechanisms or water conservation mandates would require re-modeling. Recalibration cycles align with material shifts in Nile water quota enforcement and smart-card system enrollment completion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Europe Specialty Fertilizer Market
Fertilizers
GCC Organic Fertilizer Market
Fertilizers
Compound Fertilizer Market
Fertilizers
Argentina Fertilizer Market
Fertilizers
Vietnam Organic Fertilizer Market
Fertilizers
South America Fertilizers Market
Fertilizers
North America Fertilizers Market
Fertilizers
Global Nitrogenous Fertilizer Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Nitrogen Nutrients Market
Fertilizers
France Fertilizer Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
Global Urea Market
Fertilizers
Global Micronutrient Fertilizer Market
Fertilizers
Brazil Fertilizers Market