
 Corn Co-Products Market | 2026-2036
Corn Co-Products Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Co-Products Market Outlook
Direct sales channels between ethanol producers and compound feed manufacturers is narrowing as large-scale buyers consolidate procurement. Archer Daniels Midland leverages its origination network to secure long-term supply contracts with Midwestern ethanol plants. Cargill sustains geographic dominance through integrated grain handling and co-product processing infrastructure across Iowa and Illinois. Ingredion Incorporated differentiates via specialty corn oil and modified starch derivatives for food processing customers.
Corn co-products comprise the residual streams generated during dry-grind ethanol production and wet milling of corn, including distillers dried grains with solubles containing approximately 30% protein and 10% fat, corn oil extracted from stillage, and corn gluten meal with protein concentrations exceeding 60%. These materials primarily serve as feed ingredients, fermentation substrates, and industrial raw materials. DDGS anchors volume flows in the product type category due to its entrenched role in ruminant and swine nutrition, while corn oil captures expanding interest from biodiesel refiners seeking lower-carbon feedstock alternatives. Within end use industry segmentation, animal feed occupies the largest demand pool though biofuels represents the fastest structural growth vector as renewable diesel capacity expands.
The US EPA administers Renewable Fuel Standard volume obligations that directly determine ethanol plant operating rates and co-product output volumes. FDA feed ingredient regulations and USDA grading standards shape product specifications and interstate commerce eligibility for corn gluten meal and DDGS. State-level environmental permits in Iowa, Nebraska, and Illinois govern wastewater and air emissions from wet milling facilities. Stakeholders must monitor biofuel policy trajectory and protein substitution economics to calibrate co-product processing investments.
Market Dynamics
The US EPA's Renewable Fuel Standard mandates are compressing ethanol plant margins and forcing co-product processors to extract maximum value from every bushel processed, reshaping investment priorities across the Midwest corn belt.
Growth Catalysts
- Renewable Fuel Standard obligations:The US EPA's volume mandates sustain ethanol plant operating rates and lock in DDGS output flows for animal feed processors seeking protein alternatives.
- Protein deficit in soybean meal markets:Livestock producers in Iowa and Nebraska are expanding DDGS inclusion rates as South American soybean supply faces recurring climate disruptions.
- Renewable diesel capacity buildout:Biodiesel refiners across Illinois and Indiana are securing long-term corn oil offtake contracts to meet low-carbon fuel standards.
Market Restraints
- Natural gas price volatility:Wet milling facilities in the US Midwest face margin compression when Henry Hub spikes above normalized baselines, forcing output curtailments.
- Supply concentration in Iowa-Illinois corridor:Over half of dry-grind capacity sits within a 300-mile radius, creating regional logistics bottlenecks during peak harvest.
- DDGS moisture sensitivity:Distillers grains spoilage limits export shelf life to 30-45 days, constraining ocean freight economics to Asian buyers.
Strategic Opportunities
- Underpenetrated Brazilian feed market:Brazilian beef and poultry integrators remain below optimal DDGS inclusion rates, presenting volume expansion potential for US exporters.
- Modified starch derivatives:Food manufacturers seeking clean-label thickeners are accelerating demand for specialty corn starches with tailored viscosity profiles.
- Carbon capture tax credits:The US Inflation Reduction Act's 45Q incentives are driving ethanol plants to install CO2 capture systems, monetizing fermentation emissions.
Industry Challenges
- Skilled maintenance technician scarcity:Wet mill operators in Nebraska and Kansas struggle to staff high-voltage electrical and centrifuge specialist roles.
- FSMA compliance timelines:FDA's Food Safety Modernization Act preventive controls require extensive documentation upgrades for DDGS exporters.
- Legacy DCS integration:Decades-old distributed control systems at established plants resist seamless connection to modern yield optimization software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Co-Products Market |
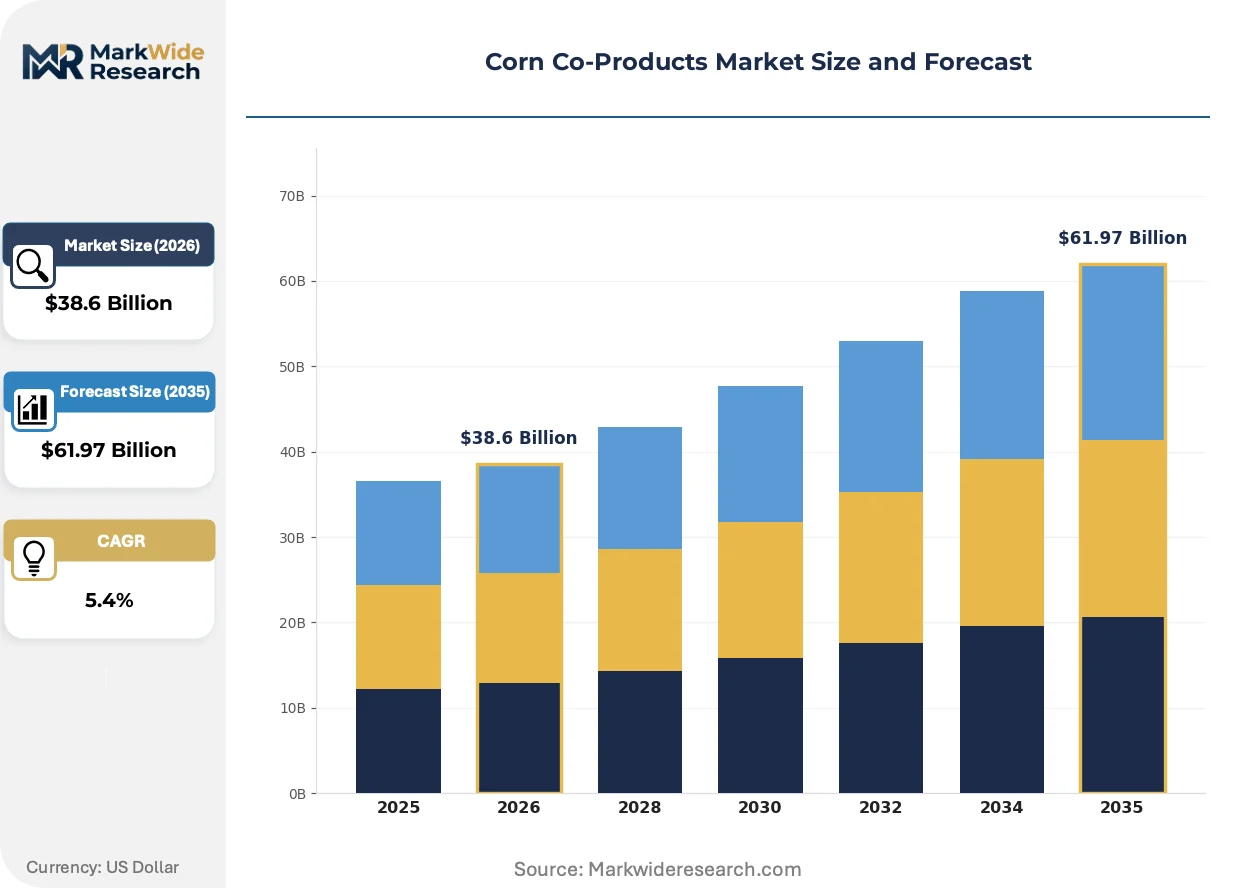
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $61.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DDGS, Corn Oil, Corn Sweeteners, Corn Gluten Meal End Use Industry: Animal Feed, Food & Beverage, Biofuels, Pharmaceutical Distribution Channel: Direct Sales, Wholesalers, Retail, E-Commerce Application: Fermentation, Nutraceuticals, Food Processing, Industrial |
| Companies Covered | Archer Daniels Midland, Bunge North America, Consolidated Grain and Barge, Gavilon Grain, Grain Processing Corporation, Roquette America, Cargill, Ingredion Incorporated, Sayaji Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Co-Products Market Strategic Shifts
Fractionation technologies and process intensification methods are reconfiguring how corn kernel components get separated and valorized, moving beyond traditional dry-grind and wet mill paradigms toward higher-margin product slates.
Membrane filtration systems for stillage processing are rendering obsolete energy-intensive evaporation stages that previously concentrated solubles for DDGS production. Ethanol plants in South Dakota and Minnesota are adopting ceramic and polymeric membranes at commercial scale. This shift cuts natural gas consumption by half while enabling higher-protein DDGS fractions that command feed ingredient premiums.
The US EPA's pending eRIN pathway under the Renewable Fuel Standard is restructuring how biogas and renewable electricity get credited toward compliance obligations. Ethanol producers with anaerobic digesters or solar installations gain new revenue streams from registering eRINs. This regulatory mechanism most directly benefits integrated plants in Iowa with existing biogas capture infrastructure.
Compound feed manufacturers are consolidating procurement through direct origination platforms that bypass traditional broker channels. Large swine and dairy operations in Wisconsin and Ohio now contract directly with named ethanol plants for quarterly DDGS volumes. This disintermediation concentrates buying power among the top dozen feed integrators while squeezing regional distributors.
Corn Co-Products Market Segmentation
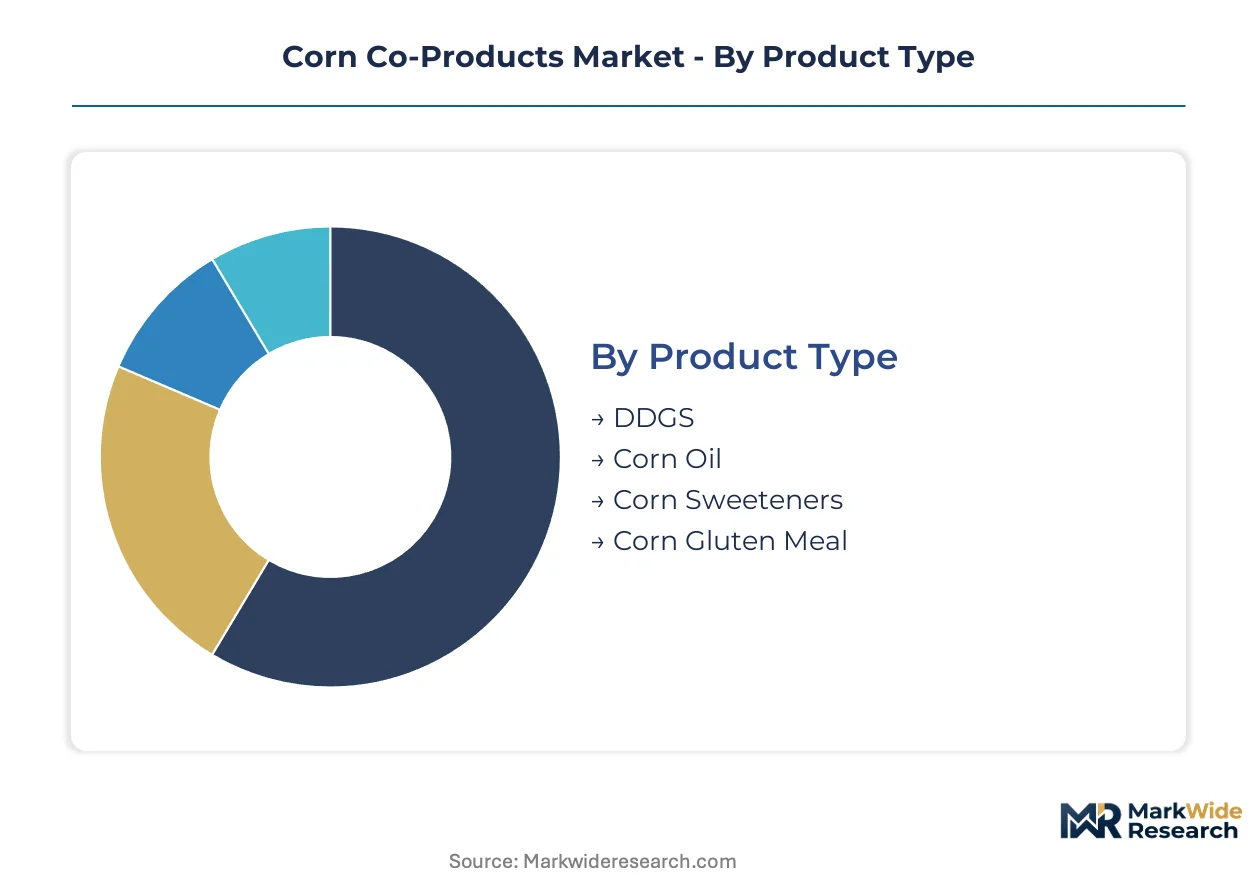
Corn co-products derive value from how kernel fractions separate during processing. Distinct product specifications, end-use requirements, and channel economics create four segmentation dimensions that determine pricing power and volume allocation across the value chain.
Product Type:
Volume concentration across product tiers reflects protein content, oil extraction efficiency, and downstream substitution economics in feed and fuel markets.
- DDGS:Distillers dried grains with solubles carry approximately 30% protein and 10% fat, making them the dominant protein supplement for ruminant and swine operations in Iowa and Nebraska. Livestock integrators facing South American soybean supply disruptions are locking in multi-year procurement contracts with Midwest ethanol plants.
- Corn Oil:Extracted from thin stillage streams, this feedstock serves biodiesel refiners across Illinois and Indiana seeking low-carbon alternatives to soybean oil. Renewable diesel capacity buildout is accelerating long-term offtake negotiations for refined corn oil fractions.
- Corn Sweeteners:High-fructose and dextrose syrups from wet milling supply beverage manufacturers and confectionery processors with standardized sugar replacement.
- Corn Gluten Meal:Protein concentrations exceeding 60% position this fraction for premium aquaculture and pet food formulations requiring concentrated amino acid profiles.
DDGS commands the established base. The steepest expansion runs through corn oil as renewable diesel producers scale procurement.
End Use Industry:
Application diversity spans nutritional inputs, fermentation substrates, and industrial feedstocks with diverging specification requirements and margin profiles.
- Animal Feed:Compound feed manufacturers in Wisconsin and Ohio contract directly with named ethanol plants for quarterly DDGS volumes, bypassing traditional broker channels. Protein inclusion rates are climbing as soybean meal markets face recurring climate-driven supply constraints.
- Food & Beverage:Modified starch derivatives and corn sweeteners serve clean-label thickener demand from food manufacturers seeking tailored viscosity profiles without synthetic additives.
- Biofuels:Corn oil fractions supply biodiesel and renewable diesel refiners meeting state-level low-carbon fuel standards.
- Pharmaceutical:Highly refined corn starches and specialty extracts provide excipient and fermentation substrate applications with stringent purity requirements.
Animal feed absorbs the majority of volume throughput. Biofuels is climbing the fastest as renewable diesel capacity multiplies corn oil demand.
Distribution Channel:
Channel structure reflects shipment scale, buyer consolidation, and the logistics economics of perishable, moisture-sensitive co-products.
- Direct Sales:Large-scale swine and dairy operations negotiate quarterly contracts directly with ethanol producers, concentrating buying power among the top dozen feed integrators.
- Wholesalers:Regional distributors manage smaller lot aggregation for mid-size livestock operations lacking storage infrastructure for bulk DDGS delivery.
- Retail:Bagged corn gluten meal and specialty starches reach hobby farmers and small feed blenders through agricultural supply stores.
- E-Commerce:Digital platforms facilitate spot purchases for specialty corn derivatives and sample quantities for formulation testing.
Direct sales anchors volume flows for major processors. E-commerce is gaining share fastest among specialty ingredient buyers seeking formulation flexibility.
Application:
Functional use cases separate commodity feed inputs from higher-margin fermentation and nutraceutical applications requiring refined processing.
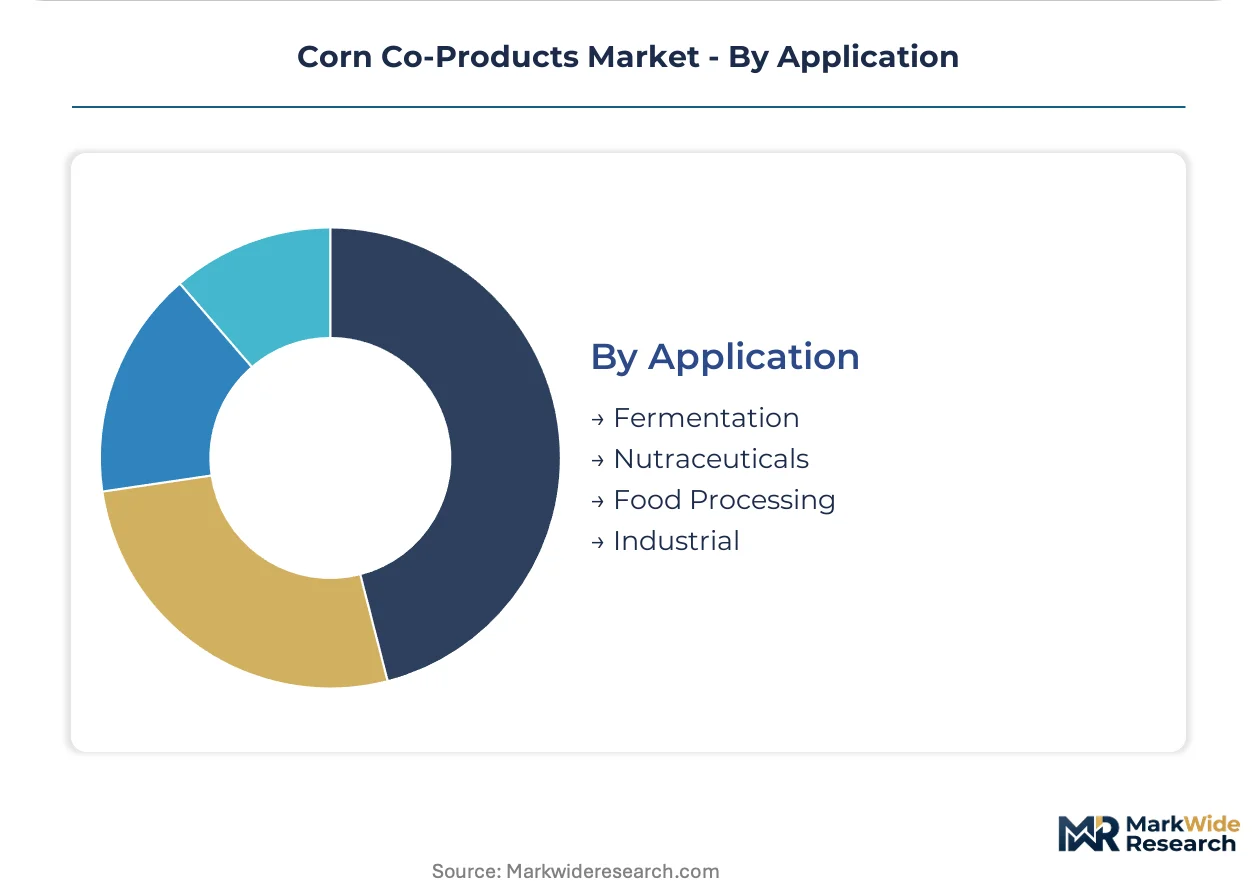
- Fermentation:Corn steep liquor and refined dextrose serve as microbial growth media for industrial enzyme and pharmaceutical production.
- Nutraceuticals:Zein protein and corn fiber oil fractions target dietary supplement manufacturers with plant-derived ingredient positioning.
- Food Processing:Native and modified starches provide texturizing and binding functions across bakery, snack, and prepared food categories.
- Industrial:Corn-derived polyols and biodegradable polymers supply packaging and coating applications with renewable content requirements.
Food processing holds the incumbent position. Nutraceuticals is expanding most quickly as wellness-oriented consumers drive plant-protein ingredient demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern ethanol plants command pricing leverage over coastal buyers due to freight-cost advantages, while Brazilian feed mills absorb surplus DDGS volumes when Asian logistics falter. This geographic asymmetry structures contract negotiations and capacity investment decisions across producing regions.
United States
Iowa and Illinois ethanol facilities process over half of national corn grind, supplying DDGS to Nebraska and Wisconsin livestock integrators. The US EPA's Renewable Fuel Standard volume mandates sustain plant operating rates and lock in co-product output flows. Wet mill clusters in Decatur and Cedar Rapids concentrate modified starch and corn oil production for food and biodiesel customers.
Brazil
Beef and poultry integrators in São Paulo and Paraná states remain below optimal DDGS inclusion rates, creating import demand for US exporters. ANVISA feed ingredient regulations govern import documentation and quality certification requirements. Santos port infrastructure handles bulk grain flows, though moisture sensitivity constrains DDGS shelf life to short-haul routes.
China
Domestic ethanol producers in Jilin and Henan provinces supply corn gluten meal to aquaculture operations in Guangdong and Fujian. NMPA and MIIT standards regulate food-grade starch derivatives and industrial fermentation substrates. Yangtze River Delta processors import specialty corn fractions for pharmaceutical excipient applications.
Germany
Modified starch specialists in North Rhine-Westphalia serve clean-label food manufacturers across the EU seeking tailored viscosity profiles. REACH compliance and EFSA novel food regulations shape product development timelines for new corn-derived ingredients. Hamburg and Rotterdam port complexes handle transshipment of US-origin DDGS to Dutch and Danish compound feed mills.
India
Gujarat and Maharashtra corn processors supply dextrose and liquid glucose to pharmaceutical fermentation operations in Hyderabad and Bangalore. FSSAI and BIS standards govern food-grade starch specifications and industrial alcohol production. Sayaji Industries and regional wet mill operators compete for maize supply with growing poultry feed demand.
Corn Co-Products Market Competitive Environment
Vertically integrated agribusinesses and specialty ingredient specialists split the market between commodity-scale DDGS flows and higher-margin fractionated products. The structure concentrates upstream origination and downstream formulation capabilities among a dozen dominant processors. Three archetypes predominate: grain-trading houses with captive ethanol assets, standalone wet mill operators, and regional dry-grind specialists. Competitive moves center on long-term supply contract consolidation and membrane filtration technology licensing for stillage processing.
Within the integrated agribusiness tier, Archer Daniels Midland and Cargill exemplify origination-to-formulation control across the US corn belt. Ingredion Incorporated occupies a position among specialty starch and corn oil derivatives producers serving food and pharmaceutical customers. Bunge North America anchors the oilseed-processing crossover segment, while Roquette America and Grain Processing Corporation represent the wet mill specialist archetype with European and North American manufacturing footprints.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Bunge North America |
| Consolidated Grain and Barge |
| Gavilon Grain |
| Grain Processing Corporation |
| Roquette America |
| Cargill |
| Ingredion Incorporated |
| Sayaji Industries Limited |
| Others |
Value Chain & Pricing Dynamics
Iowa-Illinois ethanol corridor capacity concentration grants wet mill and dry-grind operators substantial leverage over coastal compound feed manufacturers and biodiesel refiners, compressing delivered cost spreads and locking in contract premiums for named-plant origination. Natural gas price volatility and moisture-sensitive logistics reshape margin allocation between processors and distributors across the value chain.
Pricing Analysis
The customization-premium spread between standard DDGS and higher-protein membrane-filtered fractions runs wide as livestock integrators in Wisconsin and Ohio pay contract premiums for tailored amino acid profiles. Three-tier pricing structure across premium, standard, and economy levels tracks protein certification tiers and named-plant traceability rather than generic commodity grades. Pricing pressure stems from Henry Hub volatility forcing wet mill output curtailments during spike periods. Mid-size dairy operations without direct origination platforms exhibit highest price sensitivity, while renewable diesel refiners securing long-term corn oil offtake show lowest elasticity due to low-carbon fuel standard compliance requirements.
Supply Chain Analysis
Contract-manufacturing concentration at Archer Daniels Midland Decatur and Cargill Cedar Rapids facilities anchors North American modified starch and corn oil derivative output. Geographic supply concentrates in the United States, Brazil, and China, with US Midwest dry-grind capacity processing over half of national corn grind. Raw material flows draw from Iowa-Illinois corn origination networks, natural gas inputs for thermal processing, and ceramic membrane components for stillage fractionation. Single-source vulnerability around Iowa-Illinois corridor logistics creates regional bottlenecks during peak harvest. Distribution runs through direct sales channels consolidating procurement among top dozen feed integrators, bypassing traditional broker intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corn co-products markets track ethanol plant operating rates and biofuel policy cycles, with Renewable Fuel Standard volume mandates and renewable diesel capacity buildouts driving the current recovery phase across the Midwest corn belt.
For Market Incumbents: Harden long-term supply contract positions with Nebraska and Wisconsin livestock integrators before membrane filtration technology licensing spreads to regional competitors. Deepen backward integration into Iowa and Illinois grain origination networks to secure bushel supply against South American climate disruptions. Prioritize EPA eRIN pathway registration for integrated plants with existing biogas capture infrastructure, converting fermentation emissions into compliance revenue streams. For New Entrants and Emerging Players: Establish a beachhead in Brazilian beef and poultry integrator markets where DDGS inclusion rates remain below optimal levels and ANVISA feed ingredient regulations create documentation barriers for smaller US exporters. Target specialty corn oil fractions for renewable diesel refiners in Illinois and Indiana seeking lower-carbon feedstock alternatives to soybean oil. Lead with direct origination platform partnerships that bypass traditional broker channels and aggregate mid-size livestock operations lacking storage infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a biofuel-linked agricultural processing play because Renewable Fuel Standard obligations and renewable diesel capacity expansion structurally elevate corn oil demand above historical feed ingredient baselines. Acquisition target archetype: regional dry-grind specialists with membrane filtration retrofit potential and captive ethanol assets in Iowa-Nebraska corridor. Watch EPA biofuel volume mandate trajectory and South American soybean supply disruptions as inflection indicators for DDGS pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | Ceramic and polymeric stillage processing cuts natural gas consumption by half while enabling premium protein fractions. |
| Long-term Supply Agreement | Direct origination contracts with Wisconsin and Ohio swine integrators lock in quarterly DDGS volumes bypassing broker channels. |
| Backward Integration | Captive Iowa and Illinois grain handling infrastructure secures origination control against South American supply disruptions. |
| Green Certification Program | EPA eRIN registration monetizes fermentation emissions for integrated plants with anaerobic digester infrastructure. |
| Joint Venture | Brazilian feed market partnerships navigate ANVISA documentation requirements while expanding DDGS inclusion rates. |
Study Parameters
Cross-validation between ethanol plant operations data and compound feed manufacturer procurement patterns anchors the qualitative findings across this study. Primary interviews with ethanol plant managers, livestock nutritionists at integrated feed operations, biodiesel refinery procurement leads, and wet mill technical directors combined with secondary validation from EPA Renewable Fuel Standard filings, USDA grain crush reports, and EIA biofuel production statistics. Bottom-up plant capacity assessments and top-down end-use demand aggregation triangulate volume estimates across the analysis window.
Calibration against historical ethanol operating rates and DDGS price spreads at Chicago and California delivery points refined the projection framework. Segmentation dimensions modeled include product type, end-use industry, distribution channel, and application, with geographic production hub clustering across Iowa-Illinois-Nebraska corridor versus coastal demand centers. CAGRs derive from bushel processing volume trajectories, co-product yield coefficients, and protein substitution elasticity in ruminant and swine feed formulations.
Stress conditions across natural gas price volatility, South American soybean supply disruption severity, and EPA biofuel mandate revision scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding membrane filtration adoption rates and renewable diesel capacity commissioning timelines. Quarterly review of ethanol plant operating rates, DDGS export logistics economics, and biofuel policy trajectory is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Sudan Alfalfa Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
United Arab Emirates Poultry Meat Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Netherlands Floriculture Market
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
South America Cashew Market
Agriculture and Agri Products
Europe Poultry Feed Market
Agriculture and Agri Products
Global Animal Feed Dietary Fibers Market
Agriculture and Agri Products
Tissue Cultured Date Palm Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
Cameroon Agriculture Market
Agriculture and Agri Products
Honeysuckle Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Animal Feed Ingredients Market
Agriculture and Agri Products
Argentina Agriculture Market